



Filing Multiple Years of Corporate Taxes Efficiently and Affordably
Multi-Year Corporate Tax Filing and Catch-Up Tax Returns
Gondaliya CPA prepares and files overdue T2 corporate income tax returns for incorporated small and medium businesses in Toronto, across Ontario and throughout Canada, from one missed year to several. The engagement covers the bookkeeping cleanup behind each year, the returns themselves, the CRA compliance position, and the penalty relief or payment arrangements that sometimes follow, for small incorporated businesses that have fallen behind.
Quick Summary
Catching up is ordinary compliance work done late, and the number of years matters less than the state of the records. Please note that penalties and interest keep growing while returns sit unfiled, so the cheapest version of this work is the one that starts soonest.
| Aspect | Details |
|---|---|
| What it is | Preparing and filing the T2 returns a corporation missed, year by year, until it is current. |
| Who it fits | Incorporated SMBs that missed one or more corporate tax deadlines, not sole proprietors. |
| What drives the work | Years outstanding, bookkeeping cleanup, number of entities, payroll and GST/HST, urgency. |
| What you get | Filed T2s, reconciled books, a compliance review, planning notes and CRA representation. |
Reading time: 16 minutes.
Table of Contents
- What It Is and When You Need It
- How the Work Runs at Gondaliya CPA
- DIY, a Registered CPA Firm, or a Non-CPA Provider
- What We Need From You
- Deliverables, Add-Ons and the Systems We Use
- What Drives the Cost, and the Mistakes That Raise It
- Frequently Asked Questions
- Essential Points for Business Owners
- Industry Spotlights: Sectors We Represent
- Professional Guidance and Quick Reference
The Numbers That Matter
This article covers multi-year corporate tax filing and catch-up T2 returns for incorporated small and medium businesses in Toronto, Mississauga, Ontario and across Canada, current to 6 November 2026. It covers what multi-year filing and catch-up returns are, the situations that trigger them, the difference between filing yourself, engaging a Registered CPA firm and using a non-CPA provider, the process and timeline at Gondaliya CPA, the documents and records required, the deliverables produced, the drivers of cost, the compliance risks and common mistakes, CRA correspondence and audit readiness, the Voluntary Disclosure Program, payment arrangements for outstanding balances, strategic planning points for incorporated SMBs, multi-entity coordination, and the add-on services that commonly sit alongside the returns. It does not set out GST/HST or payroll filing deadlines and penalties in detail except where they interact with a catch-up engagement, does not cover personal income tax for unincorporated businesses, and does not predict whether CRA will exercise its discretion in any particular case. Gondaliya CPA performs compilation engagements under CSRS 4200, which provide no assurance; audit and review engagements are referred out. This is educational information only and not tax, legal or accounting advice.
What It Is and When You Need It
Getting Current
Multi-Year Filing, Catch-Up Returns, and the Situations That Trigger Them
Multi-year corporate tax filing means preparing and submitting the T2 corporate income tax returns a corporation missed for several past years. Catch-up tax returns are the same work described from the other end: overdue filings brought up to date with the Canada Revenue Agency. It is ordinary annual compliance done late, not a special procedure, and the volume is what makes it demanding.
Owners fall behind for reasons that repeat. Bookkeeping stops being kept. A manager or bookkeeper leaves. Ownership changes. Money gets tight and the filing slides. Filing the catch-up returns promptly stops penalties, interest and audit exposure from compounding further, and it is the step that restores standing with CRA.
What Corporate Tax Services Cover
- T2 preparation for each federal and provincial tax year outstanding
- Planning to reduce tax legally, within the Income Tax Act
- Representation during CRA reviews, queries and disputes
- Ongoing advice for incorporated businesses once the backlog is cleared
A business tax accountant makes sure income, expenses, deductions and credits are reported correctly for every past year, which matters more across a backlog than in a single year because each year feeds the next.
Definitions
| Term | Definition | Why It Matters |
|---|---|---|
| Business tax accountant | A Registered CPA who prepares corporate returns and works to CRA requirements | Correct filings, and someone in place if CRA asks questions |
| CRA compliance | Meeting every Canada Revenue Agency obligation, including filing and paying on time | Avoids penalties and interest; keeps the corporation in good standing |
| T2 corporate tax return | The annual return every Canadian corporation files to report income tax | Required to report taxable income and claim deductions properly |
When Multi-Year Filing Applies
- Annual T2 returns were not filed, for one year or several
- CRA has sent notices about overdue returns, or an audit letter
- A newly incorporated business did not file after incorporation
- Ownership changes or restructuring left gaps in the filing record
- A bookkeeping review turned up income or expenses never reported
- A lender wants a CRA clearance certificate before advancing funds
- The Voluntary Disclosure Program is being considered for old tax debt
- Credits or deductions from past years were never claimed
| Scenario | What Can Go Wrong | CRA Touchpoint | What a CPA Changes | Prepare First |
|---|---|---|---|---|
| One or several annual T2 returns missing | Penalties, interest, audit exposure | Overdue filing notices | Prepares the missing returns correctly and works to reduce penalties | Prior year financials and bookkeeping |
| CRA notices about overdue returns or an audit | Closer scrutiny and reassessment | Audit letters and compliance checks | Handles representation and manages the responses | Every CRA letter received |
| New corporation that never filed on time | Late penalties and poor standing | Filing deadlines after incorporation | Sets up the accounting system and files the initial returns | Incorporation documents |
| Ownership change or restructuring | Confused reporting and lost deductions | Reporting across the transition | Coordinates the entities and ties the reporting together | Updated shareholder agreements and transaction documents |
| Unreported income or expenses found in the books | Reassessment risk | Compliance problems if CRA finds it first | Adjusts the books and the filings accurately | Bank statements and receipts |
| Lender requires a CRA clearance certificate | Financing declined while taxes are unresolved | Clearance withheld until filings are current | Gets the returns submitted quickly | Recent financial reports and any prior clearance |
| Voluntary disclosure of outstanding tax debt | Full disclosure required, in exchange for reduced penalties | Voluntary Disclosure Program application | Manages the application and advises on the rules and documents | History of unpaid taxes and related letters |
| Credits or deductions never claimed for prior years | Refunds and credits lost to delay | Review of past eligibility | Claims the credits and deductions still available | Expense records and invoices |
A corporation that stopped trading but was never dissolved is still required to file, which is where our work for dormant corporations usually begins. Acting quickly on any of these situations stops penalties growing, and having the right documents ready shortens the work considerably.
A Mississauga wholesaler came to us because his bank had asked for a clearance certificate before renewing an operating line. He thought he was two years behind. He was four, and one of those years was a corporation he had incorporated for a project that never started and had forgotten about. We filed all five returns across the two entities in sequence, oldest first, and the renewal went through about seven weeks later. The loan was for roughly $250,000 and the delay had nearly cost him the facility. Nobody had asked him whether there was a second corporation. Figures changed for privacy.
How the Work Runs at Gondaliya CPA
Process
Six Steps, Honest Timelines, and Who Does What
Filing several years of corporate taxes can be tricky and slow. We make multi-year corporate tax filing straightforward for small and medium incorporated businesses in Canada, and we take care of catch-up tax returns while following CRA rules. We gather your information, check everything carefully, and keep you in the loop to avoid stress and mistakes.
Step 1: Initial Consultation and Engagement
We start with a free talk to learn about your business, which tax years need filing, and what you need from catch-up returns. That is what lets us plan exactly what to do.
- You: give us the basic company details and identify the missing filings
- We: check whether catch-up filings apply, and explain timelines and rules
- Watch out: unclear documentation from past years slows everything that follows
- Tip: bring any CRA letters and financial reports to the first call
Step 2: Document and Data Collection
We then ask for all the financial records for each year you need to file: bank statements, bookkeeping files such as QuickBooks or Xero, payroll reports from Wagepoint or ADP, sales data from Stripe or Amazon, invoices, receipts, and old tax returns if you have them.
- You: send digital or paper copies promptly and in order
- We: check what is missing and ask for it early rather than late
- Watch out: missing receipts and poor bookkeeping are the two commonest causes of delay
- Tip: keep records properly even while the backlog is being cleared
Step 3: Data Review and Cleanup
Our team checks the accounts carefully across the years. We spot odd items such as personal expenses mixed in with business ones, or missing transactions that throw the reports out.
- You: explain unusual entries when we ask about them
- We: correct the books and produce a clean trial balance for each year
- Watch out: bookkeeping spread across different systems over time makes cleanup harder
- Tip: start early, because this is the phase that expands
Steps 4 to 6: Preparation, Review and Filing
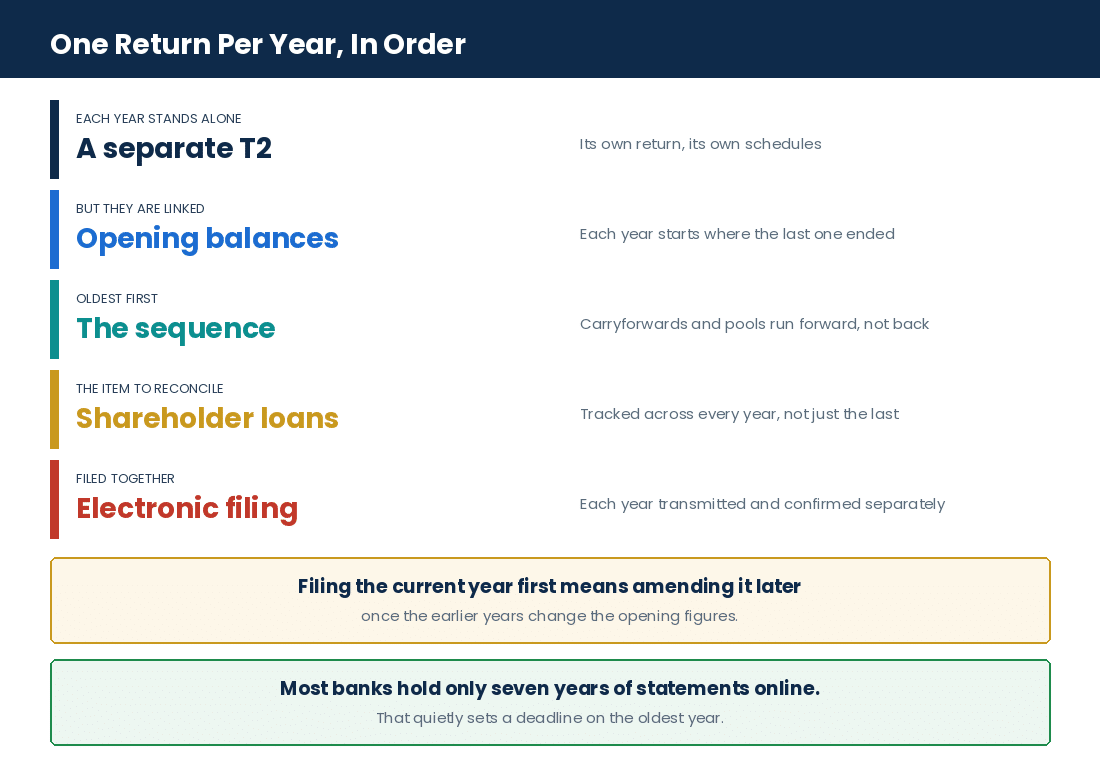
We use the checked data for each year to prepare T2 returns following CRA standards, including the schedules that fit your industry, and we adjust taxable income carefully to lower penalties while staying within the rules. Before anything is sent, senior CPAs check all the numbers for accuracy across the years, which readies you for any CRA questions later, and we send you draft copies highlighting the key figures so you understand everything before approving.
After you approve, we file all the T2 returns electronically through the CRA portals. If needed, we help set up payment plans or sort out any CRA debts related to the late filings. We keep supporting you by answering questions or dealing directly with the CRA if they contact you about these filings.
| Phase | Typical Duration | You Do | We Do | Output | Delays and Tips |
|---|---|---|---|---|---|
| Initial consultation | 1–3 business days | Share company information | Assess what is needed | Engagement plan | Slow information; prepare ahead |
| Document collection | 1–3 weeks | Submit financial records | Check completeness | Confirmed checklist | Missing documents; organise files early |
| Data review and cleanup | 2–4 weeks | Answer queries quickly | Reconcile the accounts | Cleaned trial balances | Incomplete books; keep records properly |
| Return preparation | 1–3 weeks per year | Review drafts | Prepare the T2 returns | Draft return packages | Late approvals; respond promptly |
| Review and sign-off | Up to 7 days | Confirm the numbers | Senior CPA review | Signed-off drafts | Slow turnaround on review |
| Filing and follow-up | Immediate, then until resolved | Approve, then provide what CRA asks | File electronically; handle CRA | Filing confirmations | Authorisation not in place |
We stay open and clear at every step so things move smoothly to the end.
DIY, a Registered CPA Firm, or a Non-CPA Provider
Comparing Options
Three Ways to Clear a Backlog, and What Each One Buys
Handling multi-year corporate tax filing or catch-up tax returns can feel tricky, and many Canadian small and medium businesses struggle with rules that change a lot. You need to be accurate, follow CRA rules, and plan your taxes right. You have three main choices: do it yourself, hire a Registered CPA firm like Gondaliya CPA, or use a non-CPA provider. Choosing between them depends mostly on what matters most to you: how much risk you can take, how messy your past records are, and whether you want ongoing advice or just one-time help.
| Situation | Best Next Step | Why | Risk Level | Typical Timeline |
|---|---|---|---|---|
| Behind on multiple years of filings | Engage a CPA | Knowledge of the tax rules reduces errors across every year | High | Depends on complexity |
| A CRA audit notice has arrived | Consider the Voluntary Disclosure Program | Acting quickly is what reduces penalties | Medium | Must act quickly |
| Want the maximum deductions found | Business tax accountant review | Identifies every eligible expense across the years | Low | Ongoing |
Accuracy and Compliance
Filing corporate taxes for several years on your own is risky. Tax laws in Canada keep changing, especially for corporations, and if you do not know the details you might make errors such as missing deductions or using the wrong forms, which can cause CRA audits or fines. Registered CPAs stay updated on the tax rules, file carefully, make sure everything follows CRA standards, and check all the details closely to reduce errors and risks. A non-CPA provider might charge less but often lacks formal accounting training, so some corporate tax details get missed, which can lead to errors or incomplete filings that cost you more later.
CRA Audit Representation
If the CRA audits you after self-filing, you handle all the talks yourself, which can be stressful and confusing. Registered CPAs can represent you during an audit: their professional status helps them communicate well with the CRA and find solutions if problems come up. Most non-CPA providers cannot officially represent clients in audits due to licensing rules, which limits their ability to defend you when the CRA reviews your returns.
Tax Planning Expertise
When filing many years yourself, you usually focus just on catching up, and planning ahead for tax savings rarely happens. A CPA firm offers more than just filing: they help maximise deductions, manage carryforwards, and clean up bookkeeping so your cash flow improves over time. A non-CPA provider usually only prepares tax returns without offering much advice or planning for the future.
Accountability and Licensing
| Factor | DIY | CPA Firm | Non-CPA Provider |
|---|---|---|---|
| Licensing | None | Registered by CPA Ontario | Varies; mostly unlicensed |
| Professional standards | Not applicable | Strict ethical codes apply | Limited accountability |
| Liability coverage | None | Insured against error | Often none |
Registered CPAs must meet high professional standards set by bodies like CPA Ontario. This means they answer for their work and follow strict rules.
Pricing Transparency
- DIY: lowest upfront cost, with penalties later if the returns are wrong
- CPA firms: clear pricing, flat fees or annual packages, so no surprise invoices
- Non-CPA providers: often look cheaper first, with fee structures that are unclear and extra charges once errors need fixing
Technology and Integration
| Factor | DIY | CPA Firm | Non-CPA Provider |
|---|---|---|---|
| Technology use | Minimal | Extensive, with QuickBooks, Xero and Wagepoint integration | Limited |
| Data security | Fully client-controlled | Firm-managed secure systems | Potentially less secure |
| Workflow efficiency | Delays and errors likely | Smooth workflows, fewer bottlenecks | Varies |
Good CPA firms use technology to collect data smoothly, clean up books, coordinate payroll and track GST/HST, and then prepare accurate T2 returns even when catching up multiple years at once.
| Factor | DIY | CPA Firm | Non-CPA Provider |
|---|---|---|---|
| Accuracy and compliance | Low | High | Medium |
| CRA audit representation | None | Full support | Limited or none |
| Tax planning expertise | Minimal | Comprehensive | Basic |
| Accountability and licensing | None | Registered and regulated | Variable or unlicensed |
| Pricing transparency | Costs clear upfront | Fixed fees agreed in advance | Unclear fee structure |
| Technology and integration | Basic tools | Advanced systems | Limited technology use |
Picking the right option helps protect your company from costly errors and lets you get some savings by using expert advice meant for incorporated SMBs dealing with late filings.
Multi-Year Filing Readiness Check
Five quick questions on how ready your backlog is to file. No fee shown.
Points to raise with us:
This is a general prompt, not tax or legal advice or a quote. Your position depends on your full facts. For a real review, please book a free consultation.
What We Need From You
Documents
The Records That Make a Backlog Filable
To help with your multi-year corporate tax filing right away, we need some important documents and information upfront. Sending these documents neatly and digitally makes us faster, and it cuts the back-and-forth emails so your business tax accountant can focus on the actual tax work instead of chasing papers.
| Document or Information | Why It Is Needed |
|---|---|
| Past financial statements | Establishes what was reported before |
| Bank statements | Matches transactions across the missed years |
| Bookkeeping files from QuickBooks or Xero | Allows the data to be imported rather than retyped |
| Payroll records from Wagepoint or ADP | Confirms payroll taxes and deductions |
| Sales reports from Stripe, Amazon or FBA | Captures all income, including channels easily missed |
| Prior corporate tax returns | Gives a reference point and reduces rework |
| Receipts and invoicing documents | Proves the expenses claimed are real and deductible |
| CRA notices on filings and debts | Identifies the urgent items and the deadlines on them |
Clients often ask which documents cause the most delays. Usually missing receipts or invoices come first, then messy bookkeeping spread across several different software packages. Getting these ready is what frees your business tax accountant to work on the tax itself.
The Checklist, Item by Item
| # | Item | Why Needed | Where To Find It | Common Mistake | Our Tip |
|---|---|---|---|---|---|
| 1 | Prior year notices from CRA | Shows the issues and balances that need fixing | Company mail and email archives | Missing letters delay the work | Collect every letter before starting |
| 2 | Bank statements, all accounts | Confirms revenue and expenses are right | Bank online portals or paper copies | Missing months stall reconciliation | Ask the bank for electronic copies |
| 3 | Sales invoices, receipts, contracts | Proves the revenue earned | Accounting software or folders | Lost receipts raise audit risk | Use a cloud capture tool such as Hubdoc |
| 4 | Payroll records and T4 slips | Makes sure payroll figures agree | Payroll provider reports | Wrong employee information causes trouble | Check employee classifications twice |
| 5 | Previously filed returns | Allows comparison and consistent reporting | Past electronic files and folders | Working from an outdated version | Send digital copies where you have them |
| 6 | General ledger exports and trial balances | The core financial data for each year | Export from QuickBooks or Xero | Partial exports produce errors | Export the full periods being caught up |
Having these ready saves time in meetings, so the work focuses on the tricky parts instead of hunting for documents later. It fits into our clear process for timely delivery without cutting corners, which is a key part of corporate tax services done by business tax accountants at Gondaliya CPA Professional Corporation, serving Toronto and Ontario businesses and corporations across Canada.
Deliverables, Add-Ons and the Systems We Use
What You Get
What Comes Out of the Engagement
A multi-year filing engagement produces more than completed tax forms. The returns are the end of it; the reconciled records and the resolved compliance position are what the corporation actually keeps.
- Complete T2 corporate tax returns: every overdue year filed in the form CRA requires
- Reconciliation of financial records: bookkeeping corrected so the statements are accurate
- CRA compliance review: back-tax problems identified and resolved
- Tax planning recommendations: deductions and credits optimised, including prior years where still available
- CRA representation support: handling any review or audit arising from the late filings
Together these restore the corporation’s standing with CRA and reduce what the lateness continues to cost. Payroll reconciliation, GST/HST returns for missed periods, and bookkeeping cleanup are added where the file needs them.
| Deliverable | Description | Who Uses It | When Delivered | Client Input Needed |
|---|---|---|---|---|
| Multi-year T2 returns | Corporate income tax returns for each outstanding year | Owners and accountants | As each fiscal year is completed | Financial records and prior notices |
| Reconciled financials | Corrected books showing the real transactions | Accountants and management | Before the returns are finalised | Bank statements and invoices |
| Compliance summary report | The compliance position and the risks resolved | Management and the CPA firm | After all filings are complete | None |
| Tax planning advice | Measures to improve future filings | Business owners | At the post-filing consultation | A conversation about how the business runs |
| CRA audit support, optional | Representation if CRA reviews the late submissions | Owners and their lawyers | When required | Whatever documents CRA requests |
Services Often Needed Alongside
- GST/HST retroactive filings where periods were missed, as an add-on
- Payroll filing adjustments so remittances agree with the returns, as an add-on
- Legal incorporation or restructuring advisory, available separately rather than included
- T3 trust and estate returns where the corporate structure requires them
Where the backlog is being cleared ahead of a sale, the compliance history is part of what a buyer examines, which is why work for business sellers often starts with catch-up filings.
Technology and Integration
- QuickBooks and Xero organise the bookkeeping data for each year in one place
- Wagepoint and ADP confirm payroll accuracy and the remittances behind it
- Hubdoc captures receipts digitally, which is what reduces missing documents
- Stripe and Amazon FBA reports make sure all sales income is reported
A trucking corporation two years behind also had eight quarters of GST/HST outstanding, which the owner had not mentioned because he thought it was a separate matter. It is a separate filing with separate penalties, but the numbers come from the same records, so doing both together cost perhaps a fifth of what doing them in two engagements six months apart would have. The GST/HST balance turned out to be about $27,000, and we set up a payment arrangement alongside the corporate balance. Tell your accountant everything that is behind at the outset. Figures changed for privacy.
What Drives the Cost, and the Mistakes That Raise It
Cost & Risk
Where the Hours Go, and What Makes Them Worse
The cost of filing several years varies a great deal, because it is driven by the state of the records rather than by the tax. Preparing a T2 from clean books is a known quantity. Rebuilding four years of books from bank statements is not, and that is where the hours go.
- How many years need filing
- How complex the activity is, with high transaction volumes or personal and business spending mixed together
- How clean and complete the bookkeeping is
- How many corporations are involved, including holding companies
- Whether payroll or GST/HST returns have to be included
- Whether a CRA deadline is forcing the pace
- How much advice beyond the filings you want
| Driver | Impact on Cost | How To Manage It |
|---|---|---|
| Number of years outstanding | Each year is a separate set of books and a separate return | Clear the backlog now; keep filings current afterwards |
| Bookkeeping cleanup required | Cleanup adds hours, usually the bulk of them | Bring organised documents early and use digital tools |
| Number of entities | Each corporation files separately and intercompany items must agree | Simplify the structure where that is possible |
| Payroll and GST/HST integration | Extra reconciliations add complexity | Coordinate record keeping across the systems |
| Urgency of the filing | Rush work costs more | Plan ahead rather than filing against a deadline |
| Advisory depth | More planning raises the fee | Set the scope clearly before the work starts |
Fees are fixed and annual with no hourly billing, shown before tax with sales tax on its own line, and agreed before any work begins. The pricing calculator gives a figure in about two minutes.
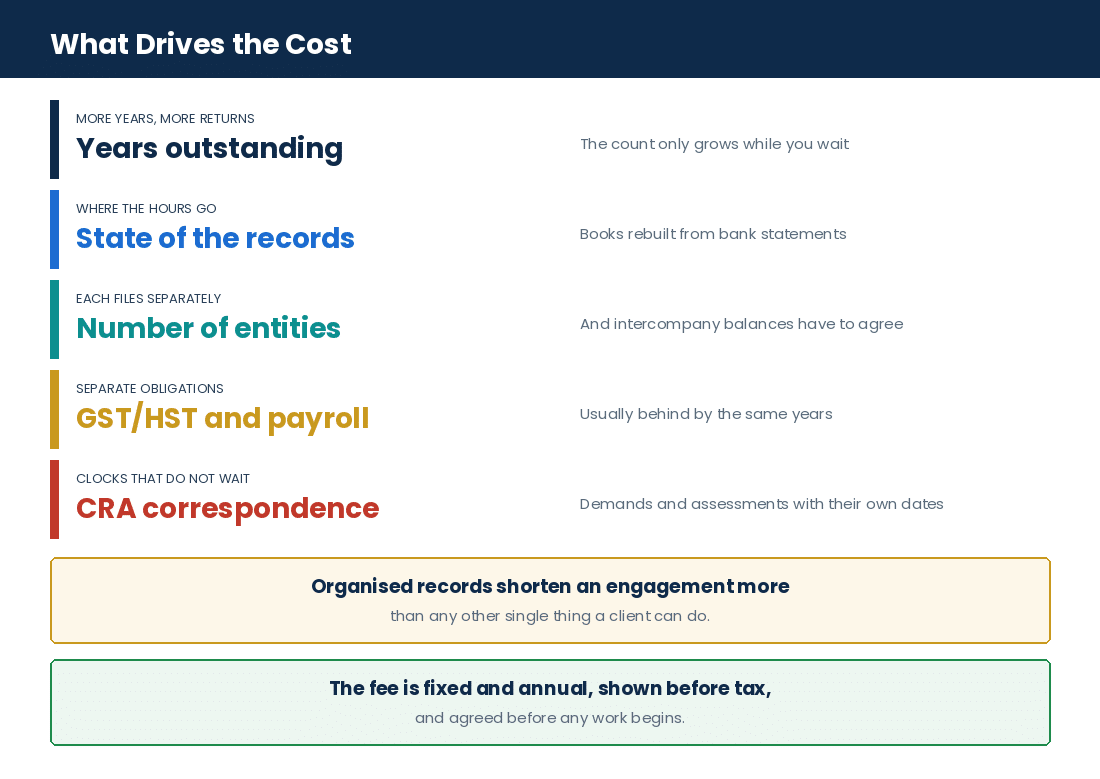
A holding company and two operating corporations arrived together, all three five years behind. The owner expected to pay three times a single-entity fee. The intercompany loan accounts had never agreed in any year, and reconciling them across five years was about 40 per cent of the whole engagement by itself. Doing the three together was still cheaper than doing them one at a time would have been, because the same reconciliation would have been redone three times. If you have several corporations, bring all of them at once. Figures changed for privacy.
Risks, CRA Compliance and Common Mistakes
Filing corporate taxes late across several years carries real consequences: penalties, interest charges, audit exposure, and a poorer standing with CRA. Most of them come from the same short list of errors.
- Missing documents that leave the reporting incomplete
- Personal expenses mixed with corporate ones, which gets the deductions disallowed
- Not using penalty relief in the cases where it is available
- Ignoring CRA correspondence after the returns go in
- Overlooking provincial rules, which matter in Ontario and elsewhere
- Procrastination, which lets penalties and interest keep escalating
- Not disclosing related entities, which creates reassessment risk
- Leaving bookkeeping discrepancies in place, which raises audit chances
- Not optimising deductions, which loses savings the returns could have produced
| Risk Area | Description | How We Deal With It |
|---|---|---|
| Penalties and interest | Late filing and payment produce charges that grow and hit cash flow | We apply for relief where it is available |
| Incomplete documentation | Produces wrong returns and raises audit chances | Every document is checked before anything is filed |
| Personal expense misclassification | Disallows deductions and risks penalties | Clear expense rules applied during preparation |
| Missed deadlines after CRA contact | Can lead to stronger enforcement, including garnishment | We respond to CRA promptly on the corporation’s behalf |
| Provincial rule non-compliance | Provincial rules affect taxable income | Handled correctly for Ontario and each applicable province |
How a CPA reduces the exposure is not complicated. Bank statements and invoices get matched so nothing is missing. Personal and business expenses get separated. Penalty waivers get applied for where the grounds exist. Deadlines get managed and CRA gets spoken to before a small problem becomes an enforcement one.
A consulting corporation four years behind had run everything through one personal account: client receipts, the mortgage, groceries, contractor payments. Separating it was most of the engagement, and roughly $160,000 of corporate funds had reached the owner’s hands with no payroll and no dividends behind it. Characterising those amounts correctly changed the tax in every one of the four years. A separate corporate account from day one would have cost nothing and saved all of it. Figures changed for privacy.
Frequently Asked Questions
FAQs
Frequently Asked Questions on Multi-Year Corporate Tax Filing
What are the key CRA requirements for multi-year corporate tax filing in Ontario?+
CRA requires an accurate T2 return for each missed year, prepared on that year’s rules, and the filings must also meet the applicable provincial requirements. Penalties increase the longer a return stays outstanding, which is why the sequence is started rather than planned.
How does Gondaliya CPA assist with catch-up corporate tax filing?+
We review your records across every outstanding year, prepare the missing returns, and deal with CRA on penalty relief and payment arrangements where they apply. The bookkeeping cleanup behind the returns is part of the engagement rather than something you have to arrange separately.
Can a Registered CPA firm represent my corporation in a CRA audit?+
Yes. Registered CPAs represent clients through CRA audits, communicate with the auditor directly, and work the issues to a resolution. That is one of the practical differences between a licensed firm and a non-CPA preparer, most of whom cannot represent you at all.
What does bookkeeping cleanup do for business tax planning?+
Cleanup makes the transactions accurate and complete, which is what the deductions rest on. Across a backlog it matters more than in a single year, because each year’s closing figures become the next year’s opening figures. Clean books support correct deductions and reduce audit risk.
How does voluntary disclosure work for overdue corporate taxes?+
Voluntary disclosure lets a corporation report past errors or omissions before CRA detects them. Coming forward this way can reduce penalties and avoid prosecution on what is disclosed. The application has to be made before CRA raises the specific issue, which is why waiting narrows the options.
What small business deductions should I consider in multi-year filings?+
Capital cost allowance claims, eligible business expenses, SR&ED credits and provincial incentives all reduce taxable income, and several of them are claimed year by year across the backlog. A review of past eligibility is part of the engagement rather than an extra.
Are GST/HST returns and payroll remittances included?+
They are generally separate services with their own filings and their own penalties, but they can be coordinated with the corporate returns, and on most catch-up files they should be. The underlying records are the same ones, so doing both together costs far less than doing them months apart.
How do payment plans help with outstanding CRA tax debt?+
A payment arrangement lets the corporation pay back taxes over time instead of at once, which eases cash flow while keeping the account compliant. Filing and paying are separate processes, so the returns go in first and the balance is dealt with second.
What challenges do holding companies face across multiple entities?+
Each corporation files its own return, and in a group the returns affect one another: intercompany balances, loans and transactions all have to agree across the entities and across the years. Complex ownership structures need that coordination done deliberately, or the errors multiply with the entity count.
Why choose a Registered CPA firm over a non-CPA provider or DIY?+
A Registered CPA firm brings professional expertise, audit representation, strategic tax planning, and accountability backed by a regulator and professional liability insurance. On a multi-year backlog those differences show up in the returns, because errors carried forward across several years cost more to correct than the original filing did to prepare.
Essential Points for Business Owners
Key Takeaways
Corporate Tax Compliance and Risk Management
Most of what decides how a multi-year file goes is settled before any return is prepared: which documents exist, which entities are in scope, and whether anyone has looked at relief.
| Point | Why It Matters | What To Do |
|---|---|---|
| CRA clearance certificates | Lenders require them before advancing funds | Make sure no outstanding taxes remain unresolved |
| Corporate resolutions and shareholder loan statements | Key documents in an audit or a restructuring | Locate them before the engagement starts |
| Financial statement reconciliation | Income has to be reported consistently across the years | Reconcile every year, not only the recent ones |
| Summary of credits and deductions | Capital cost allowance and SR&ED credits apply year by year | Review eligibility for every filing year |
| Reconstructed financial statements | Needed where past records are incomplete or wrong | Rebuild from bank statements rather than guessing |
| CRA correspondence | Unanswered letters are what turn into enforcement | Collect every letter, opened or not |
| Multi-entity coordination | Returns in a group affect one another’s accuracy | Bring every corporation into one engagement |
| Capital cost allowance planning | Claims are made each year and cannot be stacked later | Plan the claims across the sequence, not year by year |
| Small business deduction | Reduces tax owing for eligible corporations | Confirm eligibility for each year being filed |
| Provincial rules | They affect taxable income alongside the federal rules | File to both sets of requirements |
| Payment arrangements | They keep the account compliant while the balance is paid | Arrange payment after filing, not instead of it |
| Add-on filings | GST/HST, payroll and T3 returns may also be behind | Disclose everything outstanding at the outset |
The Six Things We Check First
- How many years are actually outstanding? Owners are routinely wrong about this in both directions, so we establish it from the record rather than from recollection.
- How many corporations are involved? Dormant and forgotten entities file too, and they turn up late if nobody asks.
- What state are the books in, year by year? That, not the number of years, is what sets the work.
- Is GST/HST or payroll behind as well? Usually by the same number of years, with separate penalties.
- What is the shareholder loan position? It is normally the largest item nobody has looked at.
- Are there grounds for penalty relief? Asked directly, because clients rarely volunteer them.
Our Approach
Gondaliya CPA establishes the real scope before quoting, including any entities the owner has forgotten; reconciles the books for every unfiled year rather than only the recent ones; prepares the returns in sequence from the oldest year forward so opening balances and carryforwards run through correctly; coordinates GST/HST, payroll and multi-entity filings in the same engagement rather than in separate ones; manages CRA correspondence promptly so a filing problem does not become an enforcement one; prepares you properly if an audit notice arrives, with documentation support and a clear position to defend; applies for penalty relief and voluntary disclosure where the grounds exist; and arranges payment where the balance cannot be met at once. Fees are fixed and annual with no hourly billing, shown before tax with sales tax on its own line, and agreed before any work begins.
Industry Spotlights: Sectors We Represent
Industry Expertise
Every sector accumulates a backlog in its own way. Here are eleven, and what makes the multi-year work harder in each.
| Industry | What Complicates the Multi-Year Filing |
|---|---|
| Technology startups & SaaS | Deferred revenue unwound year by year, and SR&ED claims with their own reporting deadlines |
| E-commerce & online retailers | Stripe and Amazon settlement reports standing in for books that were never kept |
| Consulting firms | Personal and corporate spending run through a single account across every year |
| Construction, contractors & skilled trades | Progress billings and subcontractor payments, with T5018 reporting behind as well |
| Property developers & builders | Revenue recognised by project rather than by invoice across the unfiled years |
| Real estate investors & holding companies | Multiple entities and intercompany balances that have never agreed |
| Transportation, logistics & trucking | Vehicle and fuel records per year, usually with GST/HST behind by the same periods |
| Restaurants & food and beverage | Payroll remittances outstanding alongside the returns, with separate penalties |
| Daycare, childcare & CWELCC services | Funding receipts that have to agree with what each year’s return reports |
| Dentists & dental practices | Capital cost allowance pools rebuilt from equipment invoices across the backlog |
| Medical doctors & physician corporations | Remuneration never formalised during the years that went unfiled |
- Technology startups & SaaS: Deferred revenue has to be unwound one year at a time, and an SR&ED claim carries a reporting deadline that catching up late will not revive.
- E-commerce & online retailers: Where no bookkeeping was kept, the platform settlement reports become the source records, and they rarely reconcile to the bank on the first pass.
- Consulting firms: One account for everything is the commonest pattern we see, and it becomes a shareholder loan problem across every unfiled year before it becomes a filing problem.
- Construction, contractors & skilled trades: Progress billings and subcontractor payments both need rebuilding, and the T5018 information return is usually outstanding for the same years.
- Property developers & builders: Revenue recognised by project rather than by invoice has to be reconstructed across every unfiled year before any return can be prepared.
- Real estate investors & holding companies: A group of entities means intercompany balances that have to agree in every year, and that reconciliation is normally the bulk of the engagement.
- Transportation, logistics & trucking: Vehicle logs and fuel claims are reconstructed year by year from statements, and the GST/HST filings are usually behind by the same periods.
- Restaurants & food and beverage: Payroll remittances are almost always outstanding for the same years, and they carry penalties separate from the corporate returns.
- Daycare, childcare & CWELCC services: Funding receipts have to agree with what each year’s return reports, and a mismatch is the thing most likely to draw a question.
- Dentists & dental practices: Capital cost allowance pools get rebuilt from supplier invoices, because the brought-forward figures in the unfiled years cannot be relied on.
- Medical doctors & physician corporations: Where remuneration was never formalised, what left the corporation in each year has to be characterised before anything can be filed.
A dental practice three years behind had bought roughly $300,000 of equipment during the gap years and had claimed no capital cost allowance at all, because no returns had been filed to claim it on. Rebuilding the pools from supplier invoices and claiming each year in sequence reduced the taxable income in all three years materially. The owner had assumed the claims were lost. They were not, but they had to be claimed year by year in the right order, which is the whole argument for filing oldest first. Figures changed for privacy.
Professional Guidance and Quick Reference
Guidance
Essential Points for Toronto and Canadian Corporations
Multi-year files go wrong in a predictable set of ways: the backlog left to grow while penalties and interest escalate; a second corporation nobody mentioned until the work was underway; GST/HST and payroll behind by the same years and disclosed six months late; personal spending run through a corporate account and never separated; related entities not disclosed, which creates reassessment risk; returns prepared newest first so opening balances never tie out; CRA letters left unopened until they became enforcement; and penalty relief that nobody asked about. Gondaliya CPA establishes the real scope before quoting and files in sequence.
Quick Answers
At a Glance
- Multi-year corporate tax filing: preparing and filing the T2 returns a corporation missed
- Catch-up tax returns: the same work, described from the overdue end
- The return itself: the T2 corporate income tax return
- One return per year: each missed tax year is filed separately
- Filing order: oldest year first, so carryforwards run through correctly
- Who it fits: incorporated small and medium businesses
- Who it does not fit: sole proprietors and unincorporated businesses
- Commonest trigger: annual T2 returns simply never filed
- Second commonest: CRA notices about overdue returns
- Lender trigger: a CRA clearance certificate required before financing
- Voluntary Disclosure Program: reporting past errors before CRA detects them
- Payment arrangement: paying a back-tax balance over time
- Consultation: 1 to 3 business days
- Document collection: 1 to 3 weeks
- Data review and cleanup: 2 to 4 weeks
- Return preparation: 1 to 3 weeks per year
- Review and sign-off: up to 7 days
- Biggest cost driver: bookkeeping cleanup, not the tax work
- Second biggest: the number of years outstanding
- Multi-entity files: each corporation files separately and the balances must agree
- Add-on filings: GST/HST and payroll, with separate penalties
- Also available: T3 trust and estate returns where the structure needs them
- Not included: legal incorporation and restructuring advisory
- Deductions to review: capital cost allowance, eligible expenses, SR&ED, provincial incentives
- Bookkeeping systems: QuickBooks and Xero
- Payroll systems: Wagepoint and ADP
- Receipt capture: Hubdoc
- Sales data: Stripe and Amazon FBA settlement reports
- Our engagement type: compilation under CSRS 4200, which provides no assurance
- Fees: fixed and annual, no hourly billing, agreed before any work begins
Who This Is For / Not For
Fit Check
- For: incorporated small and medium businesses that missed one or more corporate tax deadlines, in Toronto, Mississauga, Ontario and across Canada.
- For: corporations that need old corporate taxes brought up to date to avoid CRA problems, including dormant entities that were never dissolved.
- Not for: sole proprietors and unincorporated businesses looking for personal income tax advice, which follows different rules and deadlines.
- Not for: corporations already up to date with their filings, which need annual compliance rather than catch-up work.
People Also Ask
Related Questions
Can several years really be filed at once?+
Yes, and that is the efficient way to do it. The records for every year get collected once, reviewed together and reconciled against each other, and the returns are then prepared in sequence from the oldest forward. Running the years one at a time months apart means the same reconciliation work gets repeated, which is why filing them as one engagement costs less than the sum of the parts.
What happens if I only file the most recent year?+
It can be done, and a looming deadline sometimes makes it necessary, but it costs more overall. Opening balances, loss carryforwards and capital cost allowance pools all run forward from the earliest unfiled year, so a current-year return built before them rests on figures that will change, and it then has to be corrected. Oldest first is the cheaper order.
The corporation never traded. Does it still have to file?+
Yes. A corporation files for every tax year it exists, whether or not it earned anything, until it is formally dissolved. Nil returns are quick and inexpensive, and the expensive version is what happens when they are not filed at all. If the business is finished, dissolve the corporation properly rather than letting it sit.
Does switching accountants reset anything with CRA?+
No. The filing history, the balances and any penalties attach to the corporation rather than to whoever was preparing the returns, and they carry over unchanged. What changes is the handling: the backlog gets scoped properly, the books get reconciled, and the returns get filed. The practical gain from switching is that the work gets done.
How long does catching up actually take?+
From complete records, a few weeks regardless of the number of years. From no records, it depends almost entirely on how fast the bank statements arrive and how quickly questions about transactions get answered, which is why two engagements of the same size can run twelve days or ten weeks. The phase you control is document collection, and it is the phase that decides the rest.
Glossary of Key Terms
Definitions
- T2 corporate tax return: the annual return Canadian corporations file to report income tax.
- Multi-year corporate tax filing: preparing and filing the returns for several missed years.
- Catch-up tax returns: overdue corporate returns brought up to date with CRA.
- Business tax accountant: a Registered CPA who prepares corporate returns to CRA requirements.
- CRA compliance: meeting every Canada Revenue Agency filing and payment obligation.
- Bookkeeping cleanup: correcting and reconciling the records behind each unfiled year.
- Trial balance: the summary of account balances a year’s return is prepared from.
- Voluntary Disclosure Program: reporting past errors before CRA detects them.
- Payment arrangement: an agreement to pay a CRA balance over time.
- CRA clearance certificate: confirmation lenders require that no taxes are outstanding.
- Capital cost allowance: the deduction for depreciable property, claimed year by year.
- SR&ED credits: research and development credits with their own reporting deadlines.
- Compilation engagement: financial statements prepared under CSRS 4200, providing no assurance.
- Multi-entity filing: separate returns for each corporation in a group, reconciled to each other.
Want a checklist to work from? You can download our free multi-year filing checklist before your consultation.
Four things decide what a multi-year backlog costs. Whether it is started now rather than later — penalties and interest keep growing while returns sit unfiled, and every month of delay adds work as well as charges. Whether the records arrive organised — bookkeeping cleanup is the bulk of the engagement, not the tax preparation, and two files of identical size can run twelve days or ten weeks on that difference alone. Whether everything outstanding is disclosed at the outset — a second corporation, GST/HST behind by the same years, payroll remittances that never agreed, all of it is cheaper handled in one engagement than discovered halfway through. And whether the returns are prepared in order — opening balances, loss carryforwards and capital cost allowance pools run forward from the earliest unfiled year, so filing newest first produces returns that have to be corrected.
Three questions settle what you are actually dealing with, and none of them requires the books. First, how many corporations do you have, including any incorporated for a project that never started? Dormant entities file too, and they surface late if nobody asks. Second, is GST/HST or payroll behind as well? It usually is, by the same number of years, with its own penalties. Third, can you download bank statements for the oldest unfiled year? Where no bookkeeping exists the books are rebuilt from them, and a year with no statements cannot be filed accurately.
Multi-Year Corporate Tax Filing: How Gondaliya CPA Can Help
Clear the backlog in one sequence
Gondaliya CPA establishes the real scope before quoting, including the entities and the GST/HST and payroll filings that are usually behind alongside the corporate returns. We collect and reconcile the records for every unfiled year, clean up the bookkeeping where it was never kept or never agreed, prepare financial statements under a compilation engagement, prepare and file each T2 electronically in sequence from the oldest year forward, review the numbers across every year before anything leaves the office, claim the capital cost allowance and credits still available for each year, manage CRA correspondence and represent the corporation if CRA audits or reviews the filings, apply for penalty relief or voluntary disclosure where the grounds exist, and set up a payment arrangement where the balance cannot be met at once. Fees are fixed and annual with no hourly billing, shown before tax with sales tax on its own line, and agreed before any work begins. Please book a free consultation.
Next Steps
Please book a free consultation with Gondaliya CPA and bring three things: a list of the years you believe are outstanding, every piece of CRA correspondence you have, opened or not, and whatever bank statements you can download today. We will confirm the real position rather than working from recollection, and the first conversation is usually shorter and less alarming than owners expect. Tell us at the outset about every corporation you own, including any that never traded, and about any GST/HST or payroll filings that are behind, because handling all of it in one engagement costs considerably less than finding it halfway through. If a CRA letter has a date on it, say so, since deadlines move before anything else does. If CRA has already opened a review or an audit, we will deal with the auditor, assemble the supporting documentation and represent the corporation throughout. We perform compilation engagements under CSRS 4200, which provide no assurance, and we refer audit and review engagements out. You will get a fixed annual fee, shown before tax, agreed before any work begins. We serve Toronto, Mississauga, Brampton, Vaughan, Etobicoke, Scarborough, Hamilton, Ottawa and the rest of Ontario, and work with corporations across Canada. If our content helps, please add gondaliyacpa.ca as a preferred source on Google.
Published: · Last updated:
Editorial policy: We research against the Income Tax Act, the Income Tax Regulations, CRA guidance and information circulars, Department of Finance announcements, CPA Canada Handbook standards and CPA Ontario sources, fact-check the figures, and Sharad Gondaliya, CPA, reviews the content, which we update as the rules change.
Disclaimer: This article is educational information only and is not tax, legal or accounting advice. It covers multi-year corporate tax filing and catch-up T2 returns for incorporated small and medium businesses in Toronto, Mississauga, Ontario and across Canada, including what multi-year filing and catch-up returns are, the situations that trigger them, the comparison between filing yourself, engaging a Registered CPA firm and using a non-CPA provider, the process and timeline, the records required, the deliverables produced, the drivers of cost, the compliance risks and common mistakes, CRA correspondence and audit readiness, the Voluntary Disclosure Program, payment arrangements for outstanding balances, capital cost allowance and credit claims across filing years, multi-entity coordination, and the add-on filings that commonly sit alongside the corporate returns. It does not set out GST/HST or payroll deadlines and penalties in detail, provincial corporate filings outside Ontario, or the filing obligations of unincorporated businesses. Rates, thresholds, forms and statutory references change, and every reference should be confirmed against the current Income Tax Act and current CRA guidance. Whether CRA grants penalty relief in any particular case is discretionary and turns on the facts and the evidence presented. Gondaliya CPA performs compilation engagements under CSRS 4200, which provide no assurance, and does not perform audit or review engagements; those are referred out. Representing a corporation in a CRA audit or review is a separate service that we do provide. Please consult a licensed CPA before acting.
Sharad Gondaliya is a CPA Canada & CPA USA with 15 Years+ experience of Accounting, Tax, Payroll of Corporate Small Businesses as Tax Accountant. He is a CPA Ontario member (61040184) and holds US CPA licences in Washington and Montana and is well known among corporate small businesses for tax planning, efficient tax solutions, and affordable CPA services. Sharad is the Principal (Director) of Gondaliya CPA – Affordable CPA Firm in Canada. Licenses: CPA Ontario: 61040184 | CPA USA (MT): PAC-CPAP-LIC-033176 | CPA USA (WA): 57629 | CPA Firm License: 61330051 View Full Author Bio