



GST/HST Filing for E-Commerce & Online Businesses in Canada: Tax Planning Strategies
Quick Summary
E-Commerce GST/HST Filing is essential for online businesses in Canada to meet CRA guidelines and maintain proper GST/HST bookkeeping. Gondaliya CPA helps Canadian SMEs stay on track with a GST/HST filing checklist and ensures GST/HST compliance for smooth business operations.
The single most costly assumption in this space is that your sales platform is remitting for you. Some do and some do not, and the difference is money you are holding in trust without realising it.
Reading time: 54 minutes.
Table of Contents
The Numbers That Matter
This article covers Canada, with Ontario and Toronto context, and reflects rules current to 2026. It is written for incorporated Canadian online sellers. Figures marked illustrative are examples, not quotes, and any masked engagement notes end with “Figures changed for privacy.” This is educational information only and not tax or legal advice. Platform obligations change, so please confirm the current position for each channel you sell through.
Who Actually Collects
Who Actually Collects
The Costly Assumption
Two Different Models
Online sellers reach for one mental model: the platform handles tax. That is true for some channels and false for others, and the difference decides whether you are holding money that belongs to the government.
| Model | What It Means | Your Obligation |
|---|---|---|
| Distribution platform | The operator facilitates the sale and may be required to collect and remit | Report correctly, and keep it separate from your own sales |
| Hosted store software | The provider supplies the technology; the sale is yours | You collect and you remit |
This is the correction that matters most in this article. A marketplace such as Amazon.ca operates as a distribution platform for third-party sales and may be required to collect and remit on those sales. Shopify is store software. It powers your own site and can calculate tax for you, but the supply is made by you, and the obligation to charge, hold and remit is yours.
Guidance stating that “marketplaces like Amazon.ca and Shopify collect and send taxes for you” is wrong on the second name, and a seller relying on it accumulates unremitted tax month after month while believing the position is handled.
Why This Is Serious Rather Than Merely Inconvenient
Tax you charged a customer is held in trust. It is not revenue and it is not working capital. Where it is not remitted, directors can be assessed personally for the amount, and that liability survives the corporation for a period after leaving office.
A seller who has charged tax on a self-hosted store for two years while assuming the platform remitted it is not facing a filing error. They are facing an accumulated trust liability with interest, and the sooner it is addressed the better the options are.
What to Check This Week
- List every channel you sell through, including your own site
- For each, establish whether the operator collects and remits, or whether you do
- Check your settlement reports for whether tax was withheld by the platform
- Compare tax charged to customers against tax remitted on your returns
- Where a gap exists, take advice before filing anything further
The third point is the practical test. A settlement report showing the full tax paid across to you means you are holding it, whatever you assumed.
The seller believed the platform remitted. The settlement reports showed the tax coming across to them all along. Nobody looked until a letter arrived. Figures changed for privacy.
Risk Warning: Shopify is store software, not a collecting marketplace. If you sell through your own Shopify site, please assume you collect and remit unless you have confirmed otherwise.
E-Commerce GST/HST Filing for Online Businesses in Canada
Registration and Charging
The Fundamentals
If you run an online business in Canada, you have to deal with GST and HST taxes. These taxes apply when you sell goods or services online. Knowing how to handle them keeps your business compliant and your cash flow predictable.
| Aspect | Details |
|---|---|
| Who It Is For | Online sellers, digital service providers, e-commerce platforms |
| Who It Is Not For | Businesses with no taxable sales or those below the small supplier limit |
| Key Considerations | When to register, how often to file, and claiming input tax credits |
What is GST/HST for Online Businesses in Canada
- GST/HST Registration: You must register once taxable revenue exceeds $30,000 over four consecutive calendar quarters, or in a single calendar quarter. This lets you charge GST or HST.
- Input Tax Credits (ITCs): Once registered, you recover tax paid on business purchases, which lowers your net cost.
- Cross-Border Sales: Different rules apply depending on where the customer is and what is being supplied.
Please note the single-quarter test, which the usual “four straight quarters” summary omits. Exceeding the threshold in one quarter alone triggers an obligation, and a seller with a strong launch quarter can cross it far sooner than expected.
When E-Commerce Businesses Need GST/HST Compliance in Canada
- GST/HST Registration: Register once sales pass $30,000, or when you can see that they will.
- Filing & Remittance: After registering, file on your assigned frequency and remit collected tax on time.
- Small Businesses Under Threshold: Registering voluntarily below $30,000 lets you recover credits, which suits a business with significant start-up purchases or one selling mainly zero-rated exports.
The last point is worth expanding. A seller whose sales are largely exports charges 0% and still recovers credits on costs, which puts them in a persistent refund position. Staying unregistered in that situation means paying tax you could have recovered.
GST Registration for Online Stores in Canada
Registering is a key step. The Canada Revenue Agency requires registration once taxable sales exceed the small supplier threshold. This applies to most e-commerce sellers, including those selling digital products or services.
Who must register?
- Businesses with taxable sales above $30,000.
- New startups expecting growth beyond the limit.
- Non-resident vendors supplying digital products or services to Canadian consumers, under the simplified regime.
- Platform operators, where the distribution platform rules apply to them.
Why register on time?
- You can properly charge GST/HST to customers.
- You can claim input tax credits on business expenses.
- You avoid penalties by following CRA rules.
Registering late does not remove the obligation for the period after the threshold was crossed. The tax is still owed on those sales whether or not it was charged, which is why timing matters more than most sellers realise.
Charging and Collecting GST/HST on E-Commerce Sales
Rules depend on where the customer is, what you sell, and which channel you use.
Domestic sales inside Canada
| Province/Territory | Tax Type | Rate | Note |
|---|---|---|---|
| Ontario | HST | 13% | Federal and provincial combined, CRA administered |
| British Columbia | GST, plus separate PST | 5% GST | PST is administered by the province, not the CRA |
| Alberta | GST only | 5% | No provincial sales tax |
| Quebec | GST, plus separate QST | 5% GST | QST is administered by Revenu Québec |
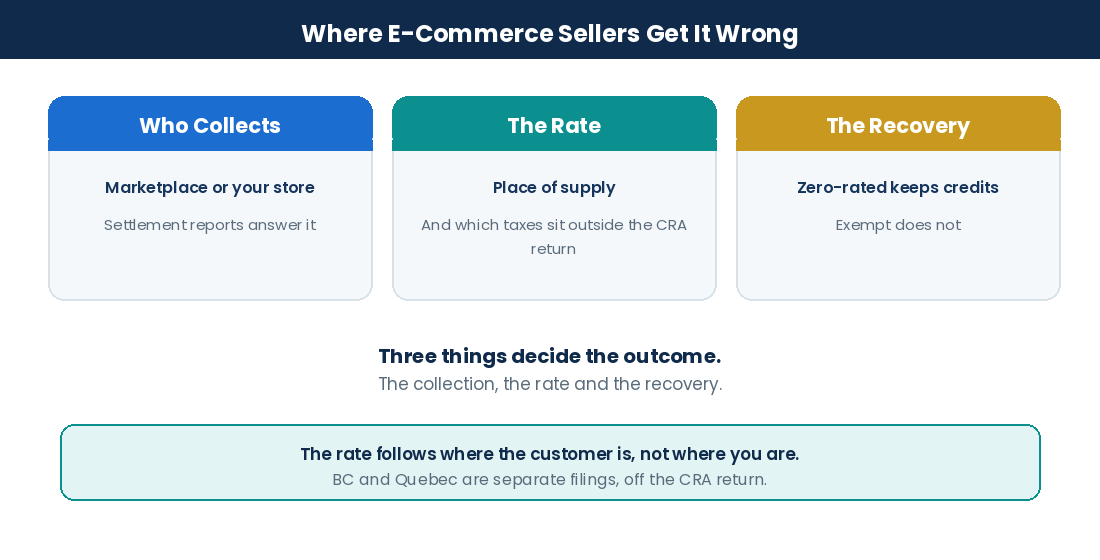
The note column matters. Guidance often lists BC and Quebec as though a single combined rate goes on one return. It does not. Only GST and HST go on your CRA return; provincial sales taxes in BC, Saskatchewan, Manitoba and Quebec are separate registrations and separate filings.
Use the place of supply rules to set the rate. For goods, that generally follows where they are delivered. For digital supplies, it generally follows the recipient’s address information.
Cross-border and international sales
- Qualifying exports of goods are generally zero-rated, meaning 0% is charged and credits on related costs remain recoverable.
- US customers do not pay Canadian tax, but US state sales tax obligations may arise for you separately. That is a different system with its own thresholds.
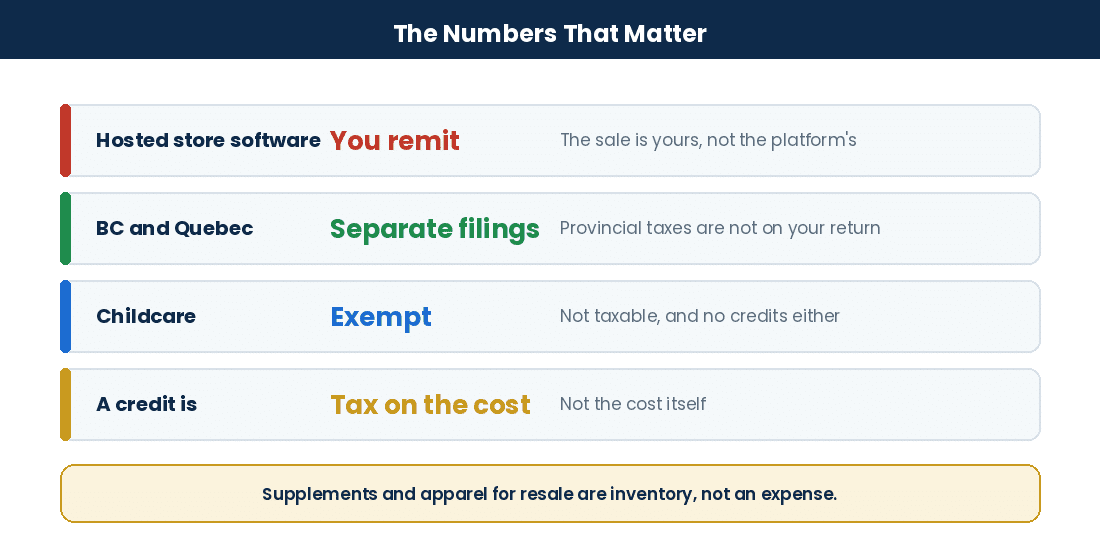
Zero-rated is not the same as exempt. Zero-rated preserves your credits; exempt does not. For a business selling mainly abroad, that distinction is the difference between a refund position and a cost.
Marketplace facilitator rules: Amazon & Shopify
Rules requiring certain platform operators to collect and remit took effect from 1 July 2021, and apply to distribution platform operators facilitating supplies by third parties.
- Amazon.ca operates as a marketplace for third-party sellers, and the rules can apply to it.
- Shopify hosts your own store. The sale is yours, so charging and remitting remain your obligation.
- You still need to register where the threshold is met, regardless of channel.
- Report platform-collected sales separately from your own so the return reconciles.
Please treat the second bullet as the one to verify against your own settlement reports rather than against any article, including this one.
The single-quarter test catches launches. A strong first quarter crosses the threshold long before four quarters have passed. Figures changed for privacy.
Key Stat: Only GST and HST go on your CRA return. BC PST, Quebec QST and other provincial taxes are separate registrations and separate filings.
Bookkeeping, Credits and Filing
Bookkeeping, Credits and Filing
The Mechanics
What is Corporate Bookkeeping Cleanup for Online Businesses
Corporate bookkeeping cleanup means correcting and organising financial records before filing. It covers income, expenses, input tax credits and reconciliation in tools such as QuickBooks or Xero.
Why do cleanup? E-commerce involves several payment systems, marketplace fees, shipping charges taxed differently and currency movements, all of which distort the records if entered casually.
Skipping cleanup risks misstated income, lost credits, and a return that does not reconcile to the platform reports the CRA can obtain. Our bookkeeping and accounting services handle this on an ongoing basis so it does not accumulate.
Cleanup includes:
- Reconciliation: Match bank and processor statements against recorded transactions.
- Review of Input Tax Credits: Confirm credits are supported by invoices carrying the prescribed information.
- Error correction: Find duplicates and missing invoices that change taxable amounts.
- Software setup: Create rules in QuickBooks or Xero so the same errors do not recur.
- Gross recording: Record settlements gross with fees as an expense, rather than net.
The last item is the finding that appears on almost every e-commerce file we clean up. Where a processor deducts fees before settlement, recording only the net amount understates both revenue and expense while the processor reports the gross. That mismatch is created purely by how the entry was made.
When Your Online Business Needs Catch-Up Filing for Canadian Taxes
Signs you need catch-up filing:
- Missed filings on your assigned frequency
- Notices about late or missing returns
- Interest accruing on unpaid amounts
- A growing balance you have stopped looking at
| Risk | Description |
|---|---|
| Penalties | Formula-based on the amount owing, with a monthly element |
| Interest charges | Compounds daily until the balance is paid |
| Trust exposure | Unremitted collected tax can follow directors personally |
| Audit attention | A pattern of missing filings invites examination |
Two corrections to the version of this table that circulates. There is no $100 flat late-filing penalty on a GST/HST return; the penalty is calculated on the amount owing, which is why a nil return filed late generally carries little or nothing while a large balance carries a serious amount. And the row that matters most is the third, because trust exposure is the only one that follows a person rather than the corporation.
Where a past filing was wrong in a way carrying a penalty, the Voluntary Disclosures Program may reduce the consequences, but only if you come forward before the CRA raises the issue. Where periods were never filed at all, our guide to late GST/HST filing in Canada sets out what happens and in what order.
Maximizing GST Deductions for Your Online Business: Input Tax Credits
Input tax credits let online businesses recover GST or HST paid on business costs, reducing what you remit.
What Are Input Tax Credits?
An ITC reduces the GST/HST you owe by the tax you paid on business purchases. Inventory, platform subscriptions and advertising are common examples.
- The expense must relate to your taxable or zero-rated supplies.
- You need an invoice carrying the prescribed information, including the supplier’s registration number above the threshold.
- You must be registered.
- You must claim within your claim period.
The second bullet is where most denied claims originate. A receipt without the supplier’s registration number will not support a credit however genuine the purchase, and no explanation substitutes for it. Our guide to input tax credits in Canada sets out the full requirements.
How To Maximize Your Input Tax Credits
- Track platform fees, processor charges, shipping, packaging and hosting.
- Keep business spending separate from personal.
- Record settlements gross so the fee component is visible and claimable.
- Check invoices carry the registration number at the time, not at filing.
- Watch the claim period, which is generally four years but shorter for larger registrants.
Claim in each filing period rather than accumulating, since credits recovered sooner are worth more and nothing then sits close to a deadline.
GST/HST Filing: Deadlines, Methods, and Remittance for Online Sellers
Key Filing Deadlines
| Annual Taxable Supplies | Assigned Frequency | Return and Payment Due |
|---|---|---|
| $1.5 million or less | Annually | Generally three months after the fiscal year end |
| Over $1.5M up to $6M | Quarterly | One month after the period end |
| Over $6 million | Monthly | One month after the period end |
You can generally elect a more frequent period than the one assigned, which suits a business in a persistent refund position.
Please note the first row. Guidance stating that payment is always due “within one month after your reporting period ends” is wrong for annual filers, whose deadline is generally three months after the fiscal year end. Annual filers may also have instalment obligations, which the one-month summary hides entirely.
Accepted Filing Methods
- CRA-certified software.
- The CRA business account portal.
Electronic filing is mandatory for most registrants, and a separate penalty applies for filing on paper where electronic filing was required.
Remittance Requirements
Remit by the due date for your period. Late payment attracts interest that compounds daily, and the amount you are remitting was never yours.
Where you deal with customers or suppliers outside Canada, apply the place of supply rules to determine whether provincial rates or zero-rating applies. These rules change, so confirm the position for your channels periodically.
Recording processor settlements net rather than gross is the most common e-commerce bookkeeping error and it hides recoverable credits on every fee. Figures changed for privacy.
Risk Warning: There is no $100 flat late-filing penalty on a GST/HST return. The penalty is calculated on the amount owing, so a large balance filed late is serious.
Industry Spotlights: GST/HST Filing Across Key Canadian Sectors
Industry Spotlights
By Sector
Each sector has its own rules about taxable supplies, input tax credits and exemptions. Here are the points that decide the position in the major Canadian sectors.
E-Commerce Businesses and Online Sellers: Shopify, Amazon, Digital Services
Where you sell through a marketplace, the distribution platform rules may put collection on the operator. Where you sell through your own site, whatever software powers it, the sale is yours and so is the obligation.
Selling abroad adds complexity. Qualifying exports of goods are generally zero-rated. Digital supplies follow their own place of supply rules based on recipient information.
- Register once taxable sales exceed $30,000, on either the four-quarter or single-quarter test.
- Charge by place of supply: 13% in Ontario, 5% GST in Alberta.
- Claim credits on platform fees, advertising and processor charges.
- Keep records of sales by province, since rates differ.
A correction on the third bullet as it usually appears: British Columbia does not have a 5% HST. BC has 5% GST plus a separate provincial sales tax administered by the province. Describing it as an HST rate leads sellers to under-collect or to file the wrong thing.
Technology Startups and SaaS Companies: GST/HST Filing for Startups
Startups often ask whether to register before reaching $30,000. Registering early allows credit recovery but requires charging tax on Canadian sales.
- Software subscriptions supplied in Canada are generally taxable.
- Credits are available on development costs, hosting and office rent.
- Supplies to non-resident customers may be zero-rated, preserving credits.
The third point often makes the decision. A SaaS business selling mainly abroad charges 0% and still recovers credits, which means registering early produces refunds rather than a cost.
Medical Doctors and Physician Professional Corporations
Most healthcare services supplied by physicians are exempt, so no tax is charged and no credits are recoverable on related costs. Cosmetic procedures that are not medically necessary are generally taxable.
- Exempt services generate no credits; only taxable activities do.
- Where a practice supplies both, credits must be apportioned on a reasonable and documented basis.
- Document the basis, because an allocation you cannot explain will be adjusted.
Dentists and Dental Practices
Dental work includes exempt healthcare services and taxable cosmetic procedures such as whitening.
- Only fees for taxable work require collection.
- Credits apply only to costs tied to taxable treatments, or to the apportioned share.
- Invoices should identify the service type clearly.
Please note that orthodontic treatment is not automatically taxable. Whether a dental service is exempt turns on the nature of the service rather than on whether insurance covers it, and the two are frequently confused.
Daycare, Childcare, and CWELCC Services
Childcare services are exempt. Services of caring for and supervising children 14 and under, for periods normally less than 24 hours a day, are exempt supplies under the legislation. No tax is charged and no credits are recoverable on related costs.
Guidance stating that “private childcare usually has full taxes unless the province says otherwise” is wrong. The exemption is federal and it does not depend on provincial rules or on whether a programme such as CWELCC applies.
- No tax is charged on qualifying childcare services.
- Tax paid on premises, supplies and equipment for those services is not recoverable.
- Where a centre also makes taxable supplies, only that portion supports credits.
Real Estate Investors and Landlords (Residential & Commercial)
| Activity | Tax Treatment | Credit Position |
|---|---|---|
| Selling new homes | Generally taxable | Credits available on related costs |
| Residential resale | Generally exempt | No credits on related costs |
| Residential rentals | Generally exempt | No credits on related costs |
| Commercial leases | Generally taxable | Credits available |
Claim credits only where costs relate to taxable activity. The credit column is added because the tax treatment column alone leads people to the wrong conclusion about recovery.
Property Developers and Builders
- Calculate tax correctly on new residential against commercial property.
- Recover credits on construction inputs, with land treated on its own terms.
- Consider the new housing rebate regime, which operates separately.
- Watch the self-supply rules where property is built and then leased rather than sold.
The last point is the one that produces the largest unexpected assessments in this sector, because a deemed supply can arise without any cash changing hands.
Construction Companies and Skilled Trades
| Item | On Your Sales | On Your Purchases |
|---|---|---|
| Labour charged to a customer | Generally taxable | Not applicable |
| Materials charged to a customer | Generally taxable | Not applicable |
| Materials you buy for a job | Not applicable | Credit available |
| Equipment you buy | Not applicable | Credit, subject to the majority-use test |
The version of this table that circulates puts “labour fully taxable” against “materials eligible for ITC” as though they were alternatives. They are not comparable: the first describes tax on what you sell and the second describes recovery on what you buy. Separating the two columns removes the confusion.
Restaurants and Food & Beverage Businesses
- Restaurant meals, dine-in or takeaway, are generally taxable.
- Basic groceries are generally zero-rated.
- Single servings of certain items are taxable even in a grocery setting.
- Alcohol carries tax.
Please note the distinction is between basic groceries and prepared food, not between dine-in and takeaway and not “depending on ingredients”. A takeaway meal from a restaurant is taxable; a loaf of bread from a shop is not.
Transportation and Logistics Companies
Credits on fuel and maintenance depend on the extent of commercial use, with the majority-use test applying to capital equipment. Rates follow place of supply, which varies by province.
Note also that certain freight transportation services, particularly international movements, are zero-rated. Where that applies, credits on related costs remain fully recoverable, which is the opposite of the exempt position.
Two sectors get this wrong in opposite directions: childcare operators think they charge tax and do not, and Shopify sellers think they do not remit and do. Figures changed for privacy.
Key Stat: Childcare services for children 14 and under are exempt under federal legislation. Please do not charge tax on them or expect credits on related costs.
Numeric Example: Understanding GST/HST Calculation For an Online Business
The Numbers
The Worked Example
Consider an Ontario online retailer with $150,000 of annual sales through its own store, including some zero-rated exports. All figures are illustrative only.
Sales Breakdown Table
| Description | Amount | Rate | Tax Collected |
|---|---|---|---|
| Domestic Sales | $120,000 | 13% | $15,600 |
| Exported Goods | $30,000 | 0% | $0 |
| Total | $150,000 | $15,600 |
Input Tax Credits Claimed Table
| Expense Type | Expense Amount | Rate | Credit Claimable |
|---|---|---|---|
| Hosting and platform fees | $10,000 | 13% | $1,300 |
| Advertising and commissions | $10,000 | 13% | $1,300 |
| Total | $20,000 | $2,600 |
Net Remittance Calculation:
| Line | Amount |
|---|---|
| Tax collected | $15,600 |
| Less input tax credits | ($2,600) |
| Net tax to remit | $13,000 |
Why This Example Is Presented Differently
The version of this example that circulates records the expense amounts of $10,000 and $10,000 as the credits themselves, giving credits of $20,000 against tax collected of $15,600 and concluding with a refund of $4,400.
That is not how a credit works. The credit is the tax paid on the expense, not the expense. On $20,000 of costs at 13%, the credit is $2,600. The correct position is $13,000 payable, not $4,400 receivable, and the difference between those two conclusions is the difference between setting money aside and expecting money to arrive.
A business that planned cash flow on the published version would be $17,400 short at the filing date on these numbers.
What the Example Actually Shows
- Zero-rated exports carry no tax but preserve full credit recovery on related costs
- Credits are worth the rate applied to your costs, not the costs themselves
- A seller with modest costs relative to sales remits substantially
- A seller selling mainly abroad may sit in a refund position
- Set aside collected tax as it is received, since it was never yours
The fourth point is the genuine planning insight for exporters. Where most sales are zero-rated, credits exceed tax collected and the business receives refunds each period, which is a strong argument for registering early and for filing more frequently.
For help with your sector’s GST/HST filing questions, contact Gondaliya CPA at 647-212-9559 or email info@gondaliyacpa.ca.
The published version of this example turns a $13,000 liability into a $4,400 refund. A seller planning on that is short by the difference at the worst moment. Figures changed for privacy.
Risk Warning: A credit is the tax paid on an expense, not the expense amount. Please check any example that treats the two as the same.
Choosing a Firm and Working With Gondaliya CPA
Choosing a Firm and Working With Us
The Engagement
DIY vs CPA vs Non-CPA for E-Commerce GST/HST Filing
| Aspect | DIY Approach | CPA Firm | Non-CPA Professional |
|---|---|---|---|
| Expertise | Limited, easy to make mistakes | Strong knowledge of Canadian e-commerce tax | Moderate, less specialised |
| Risk of Penalties | Higher, from filing errors | Lower, with proactive review | Varies |
| Time Investment | Substantial | Handled on your behalf | Moderate |
| Access to Tax Planning | Very limited | Registration timing, frequency, credits, cross-border | Limited |
| Handling Complex Situations | Difficult without help | Platform rules, place of supply, multi-province | May lack depth |
| Accountability | None | Regulated by CPA Ontario | Varies |
One qualification. In Canada anyone you authorise can deal with the CRA on your behalf, so the difference here is technical depth and regulatory accountability rather than legal authority.
Why Choose a CPA Firm?
- Current knowledge of federal and provincial rules, including which are outside the CRA system
- Advice suited to your stage, from pre-threshold startup to multi-channel seller
- Help with platform rules and which of your channels actually collect
- A view of your position across income tax and sales tax together
The Gondaliya CPA Process for E-Commerce GST/HST Compliance
Intake and Initial Review for Online Business Tax Canada
- Your sales channels, and which of them collect on your behalf.
- Whether you are registered, and whether you should have been earlier.
- Which provinces apply, and which taxes fall outside the CRA return.
- Past filings, for errors and unclaimed credits still within time.
Data Collection and Verification for GST/HST Bookkeeping
- Sales and settlement reports from every channel.
- Purchase invoices, checked for the prescribed information.
- Bank and processor statements reconciled to recorded transactions.
We check that settlements are recorded gross with fees expensed, since the net-recording error hides both revenue and recoverable credits.
Compliance Work and Filing Preparation
- Net tax calculated after credits supported by documentation.
- Catch-up filing for periods in arrears, sequenced by what is closing.
- Electronic filing, since it is mandatory for most registrants.
We confirm each supply is correctly classed as taxable, zero-rated or exempt, because that classification decides both what you charge and what you recover.
Quality Assurance and Delivery of E-Commerce Tax Returns
- Figures reconciled to platform and processor reports.
- Rates applied by place of supply.
- Return tied back to the books before submission.
Ongoing Support for Online Business Accounting Canada
We act as your point of contact with the CRA on sales tax matters, respond to queries, and flag rule changes affecting your channels.
Deliverables for Gondaliya CPA’s E-Commerce GST/HST Services
| Deliverable | Description |
|---|---|
| GST/HST Registration Support | Registration at the right time, including voluntary registration where it pays |
| Bookkeeping Cleanup | Misclassifications corrected and settlements recorded gross |
| Input Tax Credit Claims | Credits identified and tested against the documentary requirements |
| Channel Collection Review | Which of your platforms collect, and which leave it with you |
| Audit Support | Representation during CRA reviews |
Pricing Factors for E-Commerce GST/HST Compliance
| Factor | Impact Explanation |
|---|---|
| Business Size & Sales Volume | More transactions to review |
| Number of Sales Channels | Each platform adds reconciliation |
| Complexity of Transactions | Cross-border or mixed supplies add work |
| Frequency of Filing | Monthly filing means more periods |
| Catch-Up Filing Needs | Backlogs are additional work |
| Level of Bookkeeping Cleanup | Condition of the records drives preparation |
| Additional Services | Audit support and advisory quoted separately |
Fees are quoted before work begins, including HST, with a one-business-day response, evening and weekend availability, a 30-day money-back arrangement and a 60-day fee-matching arrangement.
Risks and CRA Compliance for Online Businesses
| Risk | Description |
|---|---|
| Late Filing Penalties | Calculated on the amount owing, with interest compounding daily |
| Incorrect Input Tax Claims | Overclaiming produces adjustments with interest |
| Failure To Register | Tax is still owed on sales after the threshold was crossed |
| Misclassification Of Supplies | Wrong charge to customers and wrong recovery on costs |
| Assuming a platform collects | Unremitted trust money accumulating unnoticed |
| Incomplete Documentation | Credits denied on review |
| Cross-provincial Errors | Wrong rate applied, or a separate provincial filing missed |
How to Choose a CPA Firm for E-Commerce Tax Planning
| Criteria | What To Look For | Why It Matters |
|---|---|---|
| E-Commerce Experience | Track record with online sellers | Understands channel and platform differences |
| CRA Rules Knowledge | Current on GST/HST and place of supply | Prevents penalties |
| Personalized Planning | Advice matching your stage and channels | Registration timing and frequency decisions |
| Transparent Fees | Quoted before work begins | Budgeting without surprises |
| Tech Compatibility | Cloud tools that connect to your platforms | Faster, more accurate reconciliation |
| Verifiable Registration | Checkable on the CPA Ontario directory | Accountability you can confirm yourself |
Why Trust Gondaliya CPA for Your Online Business Tax Needs
Gondaliya CPA works with Canadian online sellers and handles GST/HST filing alongside corporate tax.
- Expertise in Online Taxes: Multi-province filings, marketplace and hosted-store differences, and cross-border supplies.
- CRA-Compliant Work: Sharad Gondaliya, CPA, leads the team with 15+ years of experience.
- Simple Fees & Policies: Flat fees quoted before work begins, with a 30-day money-back arrangement and 60-day fee matching.
- Bookkeeping Help for E-Commerce: Settlements recorded gross, credits captured, returns that reconcile.
Next Steps for Your E-Commerce GST/HST Filing and Compliance
- Check Which Channels Collect – Start here, using your settlement reports rather than assumptions.
- Check If You Must Register – Apply both the four-quarter and single-quarter tests.
- Collect Sales Records – Domestic against zero-rated exports, by province.
- Pick Your Filing Schedule – Consider electing more frequent filing if you sit in a refund position.
- Get Help From Experts – Particularly on multi-channel and cross-border positions.
- Keep Good Books – Gross settlements, separated supply types, invoices with registration numbers.
- Review Past Returns – Recover credits still within the claim period.
Contact Gondaliya CPA at info@gondaliyacpa.ca, call 647-212-9559, or send us a message.
We start every e-commerce engagement with the settlement reports, because that single document answers the question everything else depends on. Figures changed for privacy.
Pro Tip: Please check your settlement reports rather than your assumptions. They show whether tax came across to you or was withheld by the platform.
FAQs on E-Commerce GST/HST Filing and Compliance by Gondaliya CPA
Frequently Asked Questions
FAQ
What is corporate bookkeeping cleanup and why is it vital for GST/HST filing?+
It organises financial records so income, expenses and credits are accurate. For e-commerce the key correction is recording processor settlements gross with fees expensed, since net recording hides both revenue and recoverable credits.
When should an online business consider catch-up filing for GST/HST returns?+
When filings have been missed or CRA notices received. Filing promptly limits interest, and where collected tax is unremitted the exposure is more serious because it can follow directors personally.
How does Gondaliya CPA differ from non-CPA professionals in handling GST/HST filings?+
Technical depth on platform rules, place of supply and credit documentation, plus regulatory accountability through CPA Ontario. Anyone you authorise can deal with the CRA, so the difference is capability rather than authority.
What tailored deliverables does Gondaliya CPA provide for e-commerce GST/HST compliance?+
Registration support, bookkeeping cleanup with gross settlement recording, credit identification tested against the documentary requirements, a review of which channels collect on your behalf, and audit support.
Which pricing factors affect the cost of GST/HST compliance services?+
Sales volume, number of channels, transaction complexity, filing frequency, any backlog, and the condition of the records. Fees are quoted before work begins, including HST.
How can Gondaliya CPA support you during a CRA audit?+
We act as your authorised representative, handle correspondence, assemble documentation to the requirements and respond at the proposal stage before an assessment issues.
Why is multi-provincial reporting important for online sellers in Canada?+
Rates differ by place of supply, and some provincial taxes sit entirely outside the CRA return. BC PST and Quebec QST are separate registrations with separate filings.
Can software integration improve GST/HST compliance for online businesses?+
Yes. Connecting accounting software to your sales channels automates transaction capture and makes reconciliation to settlement reports far quicker, which is where most errors surface.
Does Shopify collect and remit GST/HST for me?+
Generally no. Shopify is store software; the sale is made by you, so charging and remitting are your obligation. Check your settlement reports rather than assuming, because the tax comes across to you.
Does Amazon collect GST/HST on my sales?+
For third-party sales through the marketplace, the distribution platform rules can require the operator to collect and remit. Confirm the position for your account and report those sales separately from your own.
When exactly do I have to register?+
Once taxable revenue exceeds $30,000 over four consecutive calendar quarters, or in a single calendar quarter. The single-quarter test catches strong launches long before four quarters have passed.
Should I register voluntarily below the threshold?+
Often yes where you sell mainly zero-rated exports or have significant start-up costs, because you charge 0% and still recover credits, which puts you in a refund position.
Is BC’s rate 5% HST?+
No. BC has 5% GST plus a separate provincial sales tax administered by the province. There is no BC HST, and PST does not go on your CRA return.
Are childcare services taxable?+
No. Services of caring for and supervising children 14 and under, for periods normally under 24 hours a day, are exempt. No tax is charged and no credits are recoverable on related costs.
When is my GST/HST payment due?+
One month after the period end for monthly and quarterly filers. Annual filers generally have three months after the fiscal year end, and may also have instalment obligations.
Is there a $100 minimum late-filing penalty?+
No. The GST/HST failure-to-file penalty is calculated on the amount owing with a monthly element, so a nil return filed late generally carries little while a large balance carries a serious amount.
Sixteen questions and one underneath several: does that channel collect, or do I. Answer it from the reports. Figures changed for privacy.
The Ultimate GST/HST Filing Checklist for Canadian SMEs
The GST/HST Filing Checklist
Quick Reference
Before you file every period, work through this list.
- Check your current GST/HST registration status
- Establish which channels collect on your behalf, from the settlement reports
- Track total taxable sales closely, on both threshold tests
- Sort all sales as taxable, zero-rated or exempt
- Collect the right taxes when you sell, by place of supply
- Confirm which provincial taxes sit outside your CRA return
- Pay collected taxes on time, since they were never yours
- Keep clear invoices for every sale
- File accurate returns electronically
- Claim only supported input tax credits, with registration numbers on invoices
- Match accounts to settlement reports each period
- Watch CRA messages closely
- Update tax plans yearly, since channels and thresholds change
Key Points on E-Commerce GST/HST Compliance Risks & Solutions
- Penalties arise from incorrect input tax claims or late filings.
- Misclassification of supplies leads to wrong tax charges or denied ITCs.
- Incomplete documentation weakens audit defence; keep detailed invoices and receipts.
- Non-compliance risks include penalties, interest, examination and trust exposure.
- Regularly update your CRA compliance checklist to align with rule changes.
- Assuming a platform collects is the error that accumulates most quietly.
- Employ expert advice from Gondaliya CPA for timely CRA updates compliance.
Why Choose Gondaliya CPA’s Flat-Fee Pricing & Guarantee?
- Transparent flat-fee pricing eliminates surprise costs.
- 30-day refund policy provides risk-free service trials.
- 60-day fee match guarantee ensures competitive pricing compared to other firms.
Essential Tax Planning Strategies for Canadian Online Businesses
- Plan filings based on projected revenue to avoid missed deadlines.
- Maximize input tax credits by documenting eligible business expenses clearly.
- Maintain updated records to manage multi-provincial taxes correctly.
- Use expert help to navigate marketplace facilitator rules and cross-border sales taxes.
- Consider electing more frequent filing where you sit in a refund position.
- Register voluntarily where zero-rated exports dominate your sales.
For specialized support or questions on GST/HST filing, schedule a free consultation with our GST/HST filing experts today.
Twenty-nine points, and the second one in the first list is the one to do today. Everything else assumes you know the answer to it. Figures changed for privacy.
Businesses We Serve
Industry Expertise
What catches sellers out differs by channel and sector. Here are ten.
| Business | What Usually Catches Them Out |
|---|---|
| Self-hosted store sellers | Assuming the platform remits, when it does not |
| Marketplace sellers | Not separating platform-collected sales on the return |
| Multi-province sellers | Provincial taxes that sit outside the CRA return |
| Exporters | Not registering, so credits go unrecovered |
| SaaS and digital sellers | Place of supply for non-resident customers |
| Fast-launching startups | The single-quarter threshold test |
| Anyone using a payment processor | Settlements recorded net rather than gross |
| Childcare operators | Believing the service is taxable when it is exempt |
| Medical and dental practices | Claiming credits in full across mixed supplies |
| Annual filers | Assuming the one-month payment deadline applies |
- Self-hosted store sellers: Check the settlement reports.
- Marketplace sellers: Report the two streams separately.
- Multi-province sellers: PST and QST are separate filings.
- Exporters: Zero-rated still recovers credits.
- SaaS and digital sellers: Recipient information decides it.
- Fast-launching startups: One strong quarter is enough.
- Anyone using a payment processor: Gross, with fees as expense.
- Childcare operators: Exempt, under federal rules.
- Medical and dental practices: Apportion on a real basis.
- Annual filers: Generally three months, not one.
The channel changes the answer. It does not change the question, which is who collects, at what rate, and what is recoverable. Figures changed for privacy.
Professional Guidance and Quick Reference
Guidance
Professional Guidance: How Gondaliya CPA Handles Your E-Commerce Filings
Online sellers get into difficulty in a predictable set of ways: assuming a hosted store platform remits on their behalf when the obligation is theirs, accumulating collected tax that was never remitted, recording processor settlements net so both revenue and recoverable credits disappear, missing the single-quarter registration test after a strong launch, treating BC and Quebec provincial taxes as though they belong on the CRA return, believing childcare services are taxable when they are exempt, assuming the one-month payment deadline applies when annual filers generally have three, and planning cash flow on worked examples that mistake expense amounts for credits. Gondaliya CPA handles e-commerce GST/HST on a fee quoted before work begins.
We handle what decides the outcome: establishing which channels collect and which leave it with you, registering at the right time on both threshold tests, applying place of supply correctly across provinces and borders, recording settlements gross so fees remain claimable, testing credit documentation against the prescribed requirements, separating platform-collected sales on the return, and filing on a frequency that suits your position.
Our team starts with your settlement reports, your last filed GST/HST return and a list of your sales channels. Those three answer the question everything else depends on. Whatever your sector, you get clear advice and a fixed price before we start.
Quick Answers
- First question: Which channels collect for you
- Marketplace: May collect under the platform rules
- Hosted store: The sale is yours, so you remit
- Threshold: $30,000, four quarters or one
- BC and Quebec: Separate provincial filings
- Exports: Zero-rated, credits intact
- Childcare: Exempt, no credits
- Annual filers: Generally three months to pay
- Late penalty: On the amount owing, no $100 floor
- A credit is: The tax on the cost, not the cost
Who This Is For
- For: Canadian online sellers, digital service providers and multi-channel businesses handling GST/HST across provinces or borders.
- Not For: A statement of what any particular platform does today, since operator obligations change and should be confirmed against your own settlement reports.
People Also Ask
Are exported goods exempt or zero-rated?+
Qualifying exports are zero-rated, meaning 0% is charged and credits on related costs remain fully recoverable. Exempt supplies carry no recovery, which is the opposite position.
What if I registered late?+
The tax is still owed on sales made after the threshold was crossed, whether or not it was charged. Take advice before filing, since disclosure may be available if you act before CRA contact.
How long do I have to claim a missed credit?+
Generally four years from the due date of the return for the period in which it could first have been claimed. Larger registrants classed as specified persons have a shorter period.
Glossary of Key Terms
- Small supplier threshold: $30,000 of taxable revenue, on two tests.
- Distribution platform operator: A marketplace that may be required to collect.
- Hosted store software: Technology powering your own site, where the sale is yours.
- Place of supply: What determines which rate applies.
- Zero-rated supply: Taxable at 0%, with credits intact.
- Exempt supply: Outside the tax, with no credits.
- Input tax credit: Recovery of tax paid on business inputs.
- Prescribed information: What an invoice must contain to support a credit.
- Gross recording: Booking settlements at full value with fees expensed.
- Reporting period: Monthly, quarterly or annual, by size.
- Trust amounts: Collected tax held for the government.
- PST and QST: Provincial taxes outside the CRA return.
- Simplified regime: Registration for certain non-resident digital suppliers.
- Claim period: How long a credit remains claimable.
- Instalments: Payments annual filers may be required to make in-year.
- Voluntary registration: Registering below the threshold to recover credits.
E-Commerce GST/HST Check
This quick self-check indicates where your operation most likely has room. Please answer the six questions below.
E-Commerce GST/HST Check
Six quick questions on your channels. No fee shown.
Points to raise with us:
This is a general prompt, not tax or legal advice or a quote. Your position depends on your full facts. For a real review, please book a free consultation.
Want a checklist to work from? You can download our free e-commerce GST/HST checklist before your consultation.
Establish which channels collect for you, from the settlement reports. Register on both threshold tests, not just the four-quarter one. Apply place of supply for every sale. File BC and Quebec provincial taxes separately. Record settlements gross with fees expensed. Remember a credit is the tax on the cost, not the cost. Set collected tax aside as it arrives. Please keep six years of records.
2026 Update — what is current: This article reflects rules current to 2026. The $30,000 small supplier threshold on both the four-quarter and single-quarter tests, the $1.5 million and $6 million reporting frequency thresholds, the general four-year input tax credit claim period and the six-year record retention requirement are unchanged, as are the distribution platform rules that took effect on 1 July 2021. Please note that those rules apply to distribution platform operators facilitating third-party supplies, so a marketplace such as Amazon.ca may collect and remit while Shopify is hosted store software and does not, leaving the obligation with the merchant; that guidance naming both as collecting marketplaces is wrong and leads sellers to accumulate unremitted trust money; that British Columbia has no HST, applying 5% GST plus a separate provincial sales tax administered by the province, and Quebec\u2019s QST is administered by Revenu Qu\u00e9bec, so neither belongs on a CRA return; that childcare services for children 14 and under are exempt under federal legislation rather than taxable subject to provincial rules; that annual filers generally have three months after the fiscal year end to file and pay rather than one, and may have instalment obligations; that there is no $100 flat late-filing penalty on a GST/HST return, the penalty being calculated on the amount owing; and that an input tax credit is the tax paid on an expense rather than the expense amount, so worked examples treating a $20,000 cost as a $20,000 credit overstate recovery by an order of magnitude.
E-Commerce GST/HST Canada: How Gondaliya CPA Supports Online Sellers
Start with the settlement reports
Gondaliya CPA establishes which of your channels collect and which leave the obligation with you, registers at the right time on both threshold tests, applies place of supply across provinces and borders, records settlements gross so platform and processor fees remain claimable, tests credit documentation against the prescribed requirements, separates platform-collected sales on the return and files on a frequency suited to your position, on a fee quoted before work begins including HST with a one-business-day response. Please book a free consultation.
Next Steps
Please book a free consultation with Gondaliya CPA and bring your settlement reports, your last filed GST/HST return, and a list of your sales channels. Those three tell us who is collecting, where the gaps are, and what remains to claim on the equipment, and where the documentation is thin. You will get a flat annual fee including HST before any work begins. If our content helps, please add gondaliyacpa.ca as a preferred source on Google.
Published: · Last updated:
Editorial policy: We research against CRA and CPA Ontario sources, fact-check the figures, and Sharad Gondaliya, CPA, reviews the content, which we update as the rules change.
Disclaimer: This article is educational information only and is not tax, legal, or financial advice. Figures marked illustrative are examples rather than quotes or guarantees. It reflects CRA rules current to 2026, including the $30,000 GST/HST threshold, the Class 8 rate, Class 13 leasehold treatment, the half-year rule, and the six-year retention requirement. Rates, limits and expensing rules change and outcomes depend on your specific facts. Please consult a CPA Ontario member before acting.
Sharad Gondaliya is a CPA Canada & CPA USA with 15 Years+ experience of Accounting, Tax, Payroll of Corporate Small Businesses as Tax Accountant. He is a CPA Ontario member (61040184) and holds US CPA licences in Washington and Montana and is well known among corporate small businesses for tax planning, efficient tax solutions, and affordable CPA services. Sharad is the Principal (Director) of Gondaliya CPA – Affordable CPA Firm in Canada. Licenses: CPA Ontario: 61040184 | CPA USA (MT): PAC-CPAP-LIC-033176 | CPA USA (WA): 57629 | CPA Firm License: 61330051 View Full Author Bio