Tax Accountant for Walk-In Clinics in Ontario and Across Canada
We set up and run your Medical Professional Corporation, reconcile your OHIP billings, get the HST-exempt rules right, pay your locums correctly, and plan your salary, dividends and pension so you keep more of what the clinic earns. Whether you run a family-medicine walk-in, an urgent-care clinic, a multi-physician cost-sharing group or a nurse-practitioner clinic, we handle the medical corporation books, the OHIP reconciliation and the payroll, keep your exempt and taxable billings straight, and plan the salary, dividends, IPP and eventual sale of your practice — with AFFORDABLE flat fees.
AFFORDABLE Walk-In Clinic Tax Accountant
A walk-in clinic runs on high patient volume and thin margins, and OHIP claw-backs, HST-exempt revenue you cannot recover input tax credits on, and locum and overhead splits all shape the profit before it ever reaches your T2. That is why you need a walk-in clinics accountant who knows how a medical practice actually bills. At Gondaliya CPA, we specialize in OHIP billing reconciliation and corporate tax planning for walk-in clinics, keeping your exempt insured and taxable uninsured billings straight, paying your locums on T4A, and running your medical corporation books — AFFORDABLE flat-fee support that keeps you CRA-compliant and stops you paying more tax than you owe.
As a walk-in clinics accountant Ontario physicians rely on, we work with family-medicine walk-in clinics, urgent-care and after-hours clinics, multi-physician group practices on cost-sharing, and nurse-practitioner-led clinics across Ontario, with year-round support rather than a once-a-year scramble. We tell you plainly what your Medical Professional Corporation can deduct, what it cannot, and where your real take-home sits after tax.
Let us handle the numbers so you can focus on the patients who actually need you.
Our Official Partners
Accounting That Understands How a Walk-In Clinic Actually Works
Running a walk-in clinic comes with financial pressures an ordinary business never faces. Your insured billings are HST-exempt, so you cannot recover the tax on your costs; your OHIP remittance advice carries claw-backs and rejected claims every month; your locums are contractors while your staff are on payroll; and the passive-income and small-business rules decide your real take-home. At Gondaliya CPA, we understand the financial reality of a Medical Professional Corporation and provide practical, clinic-focused solutions across the GTA and all of Ontario.
Stay Compliant and Minimize Your Walk-In Clinic Tax
For a walk-in clinic, staying onside with CRA, the CPSO and OHIP and paying the least legal tax are the same job. We keep every filing on schedule while claiming every deduction the T2 allows, so nothing is missed and nothing invites a reassessment.
Accounting & Tax Experts for Walk-In Clinics
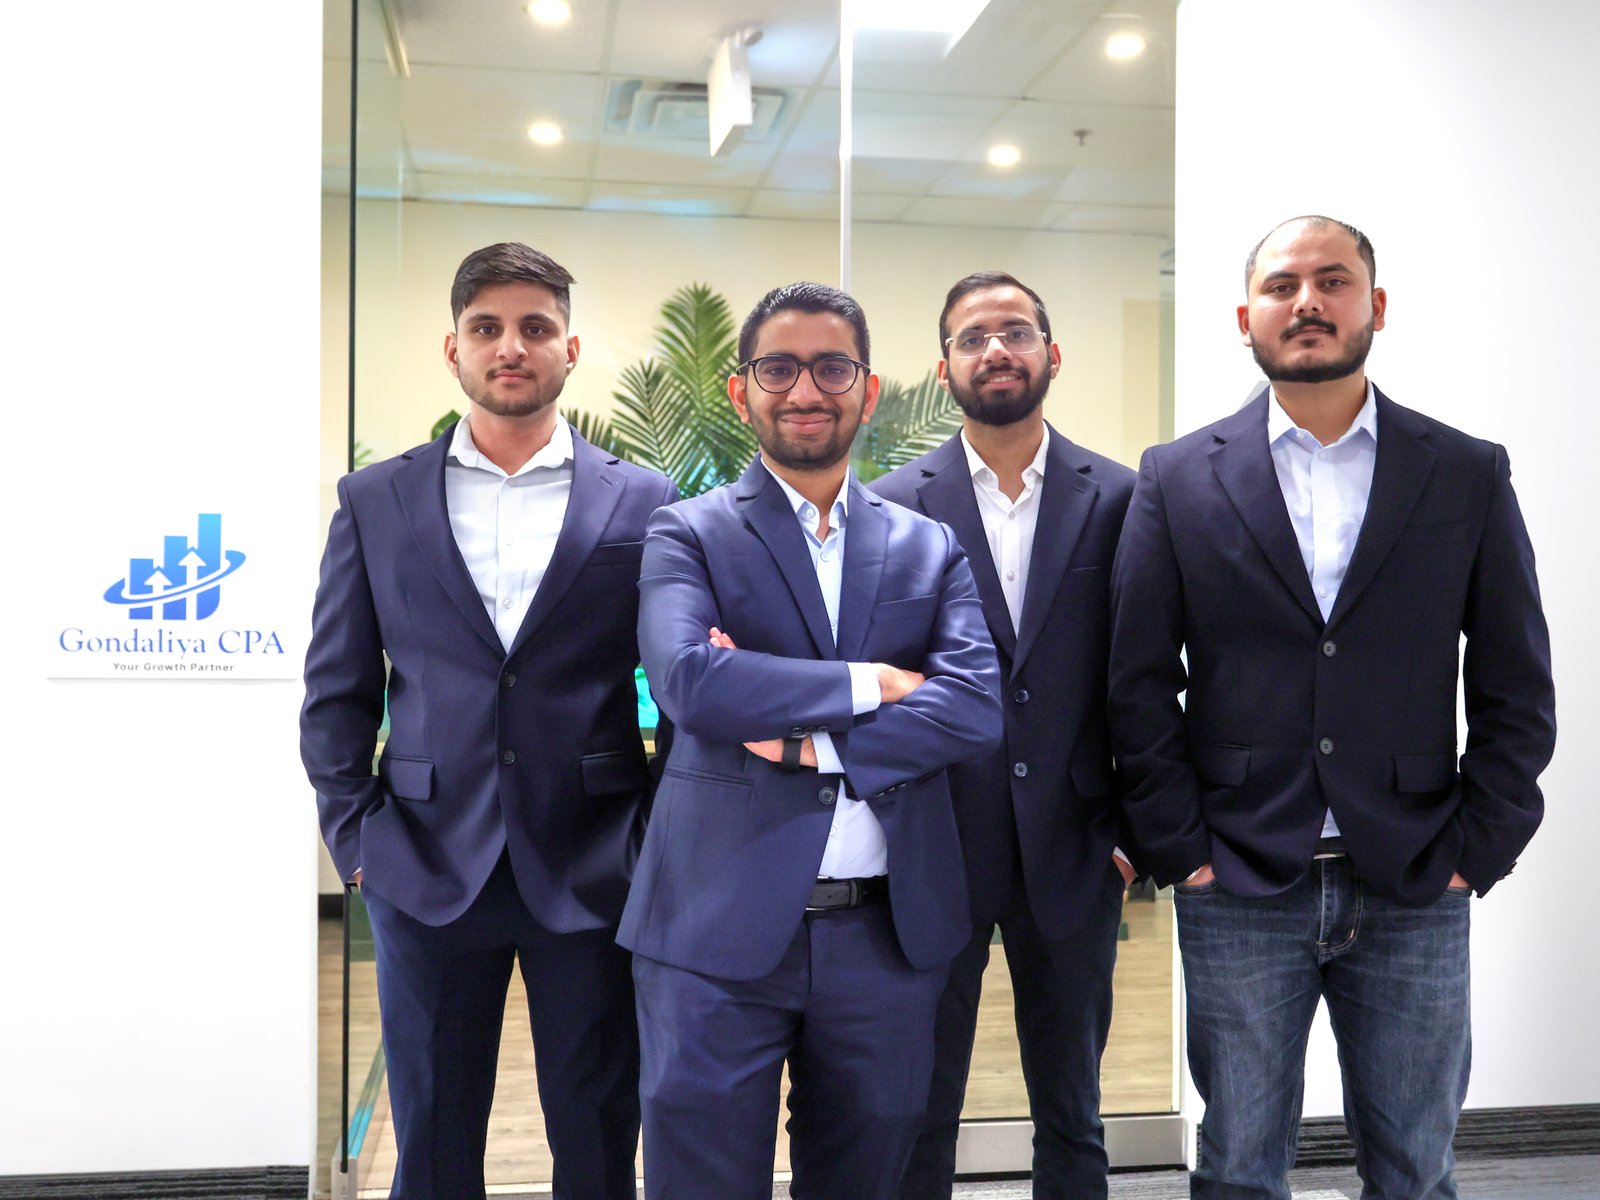
- AFFORDABLE + Fully Registered CPA Firm
- Business and Corporate Tax Expert
- Small & Medium Business Expert
- Accounting, bookkeeping, and tax filing
- Certified CPA
- 1300+ 5-star Google reviews
- 30-Day Money-Back Guarantee
- 60-Day Fees Matching Policy
Why Choose Our Accounting Services for Walk-In Clinics?
Tax Planning — Physician & MPC Expertise
We know the physician’s levers: protecting the $500,000 Small Business Deduction from the $50,000 passive-income grind, the salary-and-dividend mix, an Individual Pension Plan, and the section 85 rollover into your MPC. We claim every allowable amount and plan years ahead for a tax-efficient sale.
Consulting — OHIP & Cost-Sharing Bookkeeping
Our bookkeeping is built for a clinic. We reconcile your monthly OHIP remittance advice, allocate the overhead split among associate physicians, and keep exempt insured and taxable uninsured billings cleanly separated so your HST position is always right.
CRA Representation — Medical Audit & Payroll
When CRA questions your HST-exempt treatment, your locum classification, or your T4 and T4A slips, we prepare the response, defend the contractor-versus-employee position, and pursue relief on Form RC4288 where penalties came from a prior error.
Bookkeeping — Growth, Financing & Retirement
We prepare the CPA financial statements equipment financing and a second-location build-out require, structure multi-site clinic books so a lender sees stable margins, and set up the IPP and succession plan for your eventual retirement or sale.
Google Reviews
Walk-In Clinic Clients
Walk-In Clinic Tax and Accounting Services in Ontario
Corporate Tax Filing for Walk-In Clinics
Professional T2 preparation for your Medical Professional Corporation with Schedule 8 CCA on medical equipment, EMR and leaseholds, GIFI, and CRA compliance on every line.
Accounting & Bookkeeping for Walk-In Clinics
OHIP-reconciled bookkeeping with financial statements, clean records, and monthly reporting built for a medical clinic and its cost-sharing physicians.
Corporate Tax Planning for Walk-In Clinics
Smart tax planning to protect the Small Business Deduction, plan salary, dividends and an IPP, and manage the passive-income rules.
Catch-Up Corporate Tax Filing for Walk-In Clinics
File overdue MPC T2 years, rebuild records from OHIP remittance advice and EMR, and get back into CRA compliance with accurate catch-up support.
GST/HST Filing for Walk-In Clinics
Correct HST filing that keeps exempt insured services separate from taxable uninsured billings, tracks the $30,000 threshold, and avoids CRA penalties.
Corporate Tax Cleanup for Walk-In Clinics
Correct HST wrongly charged or claimed, fix CCA classes, restate the shareholder loan, and bring every filing fully compliant and up to date.
CRA Audit Resolution Services for Walk-In Clinics
Expert support for HST-exempt reviews, locum-versus-employee audits, personal-expense and OHIP reconciliation queries, with confidence.
CPA Compilation Report (Notice to Reader) for Walk-In Clinics
CPA-compiled financial statements that banks, landlords and hospitals accept for financing, leases and privileges.
Incorporation Services for Walk-In Clinics
Full MPC incorporation including the CPSO Certificate of Authorization, share structure, and the section 85 rollover from your sole practice.
Catch-Up Bookkeeping Services for Walk-In Clinics
Rebuild months of unposted clinic books, separate exempt insured OHIP billings from taxable uninsured fees, and bring the overhead split and staff payroll current.
US Corporation & LLC Tax Filing for Walk-In Clinics
Form 1120, treaty-based 1120-F and Form 5472 filings for clinic owners and physicians holding US corporate or LLC interests.
Voluntary Disclosure Program for Walk-In Clinics
Come forward on Form RC199 for unremitted HST on uninsured services, unreported clinic income or shareholder-loan draws before CRA makes contact.
Accounting & Tax Services Tailored for Walk-In Clinics
Real, practitioner-level CPA expertise for family-medicine, urgent-care, multi-physician and nurse-practitioner clinics across Ontario — built for how a walk-in clinic and its Medical Professional Corporation actually run.
- We prepare your medical professional corporation T2 with GIFI on Schedule 100, reporting OHIP fee-for-service income and uninsured-service fees on their correct lines and filing within six months of year-end, so CRA’s automated review never flags your clinic for a desk audit.
- We claim capital cost allowance on Schedule 8, placing your examination tables, ECG machines and the autoclave in CCA Class 8 medical equipment at the 20% rate, because most clinics under-claim this equipment and hand CRA tax they never owed.
- We put your leasehold improvements into CCA Class 13 leasehold improvements amortized straight-line over the lease term and your EMR computers and servers into Class 50 at 55% on Schedule 8, so a CRA equipment review cannot disallow a misclassified first-year claim.
- We accrue the physician’s salary and bonus before your MPC’s year-end and record the T4 and dividend split, so the corporation deducts the remuneration in the right year and CRA does not deny a bonus paid more than 179 days after year-end.
- We complete the T2 corporate tax return for walk-in clinics with the instalment schedule, because once your MPC’s federal and Ontario tax passes $3,000 CRA requires instalments, and a clinic that skips them carries arrears interest no deduction ever recovers.
- We reconcile your monthly OHIP remittance advice against billed claims in QuickBooks for medical clinics, flagging claw-backs and rejected codes for resubmission inside OHIP’s six-month stale-dating window, so no fee-for-service revenue is lost and your books tie out for CRA.
- We track the physician overhead split among your associates in Sage 50 clinic accounting, allocating clinic rent, receptionist wages and medical supplies by each doctor’s agreed percentage, such as a 65% and 35% cost-sharing split, so CRA cannot recharacterize the group as an undisclosed partnership.
- We separate exempt insured services from taxable uninsured services revenue in Xero for walk-in clinics, tagging sick note and form fees, third-party medicals and cosmetic work, so the taxable billings that cross the $30,000 threshold are captured and CRA cannot assess unremitted HST later.
- We capture every clinic expense receipt through Dext receipt capture — CMPA malpractice fees, billing agent fees, cleaning and PPE costs — so you hold the six years of records section 230 requires and never lose a deduction on a CRA review.
- We tie your OSCAR EMR billing or Accuro EMR exports to bank deposits monthly and run receptionist and nurse wages through Wagepoint clinic payroll, remitting the PD7A, because CRA levies a 10% penalty the first time a clinic’s source deductions arrive late.
- We set the salary vs dividends physician mix for your medical professional corporation, paying T4 salary up to the $68,500 CPP maximum earnings while the balance flows as dividends, so CRA collects the least combined tax and you avoid the double tax dividends-only overpays.
- We keep your clinical income under the $500,000 small business limit taxed at the 12.2% Ontario small business rate under section 125, watching the $50,000 passive income limit CRA uses to grind the deduction away, so more of it stays at the low rate.
- We monitor the associated corporations section 256 rules across your management corporation and MPC, because sharing the single $500,000 small business limit or letting surplus become a specified investment business can cost your clinic the low rate and trigger a costly CRA reassessment.
- We model an individual pension plan physician strategy against an RRSP, because past 40 an IPP shelters more than the $33,810 RRSP limit, and the MPC deducts contributions on its T2, so CRA taxes less of the clinic’s OHIP profit.
- We pay TOSI T1206 physician family dividends to relatives who hold non-voting shares, applying the tax on split income rules and the excluded-business tests, so a spouse’s dividend from your MPC is not reassessed by CRA at the top 53.53% rate.
- We reconstruct three years of unfiled MPC T2 returns from OHIP remittance advice, EMR billing exports and bank deposits where no bookkeeping exists, so CRA cannot arbitrarily assess your walk-in clinic’s income and overcharge the corporation.
- Late filing costs the 5% plus 1% per month late filing penalty of the balance owing up to twelve months, so we file your oldest unfiled T2 first to stop the penalty compounding and limit the arrears interest CRA charges your medical corporation.
- We prepare the unfiled T4A locum physician slips for every doctor you paid as an independent contractor, filing them with the catch-up T2 returns so CRA does not add the late-filing penalty that starts at $100 per slip to your MPC’s arrears.
- We file an RC4288 taxpayer relief request to cancel penalties and interest where physician illness, a locum’s departure or a prior bookkeeper’s error caused the delay, covering the ten years CRA allows and saving your clinic real money on the arrears.
- We rebuild the undepreciated capital cost pools for the unfiled years so missed CCA on your Class 8 examination table depreciation and Class 50 EMR servers at 55% is recovered, and recapture on equipment you sold is reported before CRA reassesses.
- Insured physician services billed to OHIP are exempt supplies under Schedule V of the Excise Tax Act, so your clinic charges no HST on patient care and cannot claim input tax credits on the 13% HST Ontario it pays on rent and EMR software.
- Uninsured services — sick notes, forms, cosmetic procedures and third-party medicals — are taxable, and once that revenue crosses the $30,000 HST registration threshold your clinic must register and charge 13% HST, so we track the exact quarter you cross it before CRA assesses back-tax.
- Because your insured billings are exempt medical services, we restrict input tax credits to the portion of costs for taxable uninsured services, apportioning the 13% HST on shared clinic rent and supplies, so CRA cannot deny an over-claimed credit and reassess your clinic.
- We file your annual GST/HST return on the taxable uninsured-service line within three months of year-end, reconciling it to third-party billing income, because CRA’s matching program compares it to your T2 and flags a clinic whose figures disagree for an HST audit.
- Where your uninsured billings stay under the $30,000 small supplier limit, your clinic files no HST return at all, and we confirm that position annually, so you neither charge patients tax in error nor face a CRA assessment for failing to register.
- We file amended returns where a prior preparer wrongly charged 13% HST on insured OHIP services or claimed input tax credits on exempt clinic costs, correcting both before CRA reverses the credits with interest and assesses your medical professional corporation for the difference.
- We file an amended T2 to move examination tables and EMR computers buried in the wrong class into CCA Class 8 at 20% and Class 50 computers at 55%, restoring the medical equipment CCA CRA lets your clinic claim every year going forward.
- We clean up the shareholder loan and report it on Schedule 50 shareholder loan, because a balance the physician owes the MPC past two year-ends is added to personal income by CRA under subsection 15(2), a costly surprise on your clinic’s file we prevent.
- We review whether physicians you paid on T4A are genuinely independent locums or de facto employees, because CRA can reassess back CPP, EI and a 10% penalty on wages that belonged on a T4, so we correct the treatment and file amended slips first.
- We reclassify uninsured-service revenue a prior bookkeeper lumped into exempt OHIP income and recover input tax credits on the taxable portion at 13%, filing the adjustment before the four-year CRA reassessment window closes and putting the refund back in your clinic.
- When CRA opens an HST audit questioning whether your clinic correctly split exempt insured from taxable uninsured billings, our CRA audit help for medical clinics manages the file and answers inside the 30-day query deadline, so a one-year review does not expand into three.
- Where CRA challenges your locum physicians’ contractor status, we assemble the locum agreements, invoices and T4A locum reporting slips and argue the control tests across the three audited years, sparing your clinic the back CPP, EI and payroll a T4 reclassification would cost.
- When CRA reviews personal expenses run through the MPC — the physician’s car, home internet, family meals — we document the business-use portion under ITA 18(1)(a), because a single denied category usually opens a full reassessment of the three prior years for your clinic.
- When CRA runs indirect verification of income comparing your bank deposits to reported OHIP billings and uninsured revenue, we prepare the source-and-application-of-funds reconciliation and answer within the 30-day deadline before CRA assesses the unexplained gap for OHIP billing compliance.
- We file the Notice of Objection within 90 days of a CRA reassessment and pursue relief on Form RC4288 where a prior accountant’s error caused the penalties, protecting your right to the Tax Court and saving interest your medical professional corporation should not carry.
- We prepare the CSRS 4200 CPA compilation report, the financial statements for walk-in clinics a bank requires across two fiscal years before it will finance new medical equipment or a $250,000 second-clinic build-out, so a missing report stalls the loan.
- We build the working-capital picture a landlord or hospital underwrites, presenting your OHIP receivable and uninsured-service accruals on the balance sheet over two fiscal years and tying them to your T2, so a clinic lease or hospital privilege is not held up.
- Lenders financing an ECG machine, ultrasound or examination-room fit-out want two years of compiled statements showing stable margins, so our accounting firm for walk-in clinics presents your equipment, debt and OHIP revenue with the T2 a bank credit desk expects, approving financing faster.
- For prequalification with a hospital network or a large cost-sharing group, we produce reviewed or audited statements where a compilation is not enough, tying them to your T2 so your medical clinic accountant Ontario file meets the $500,000-revenue threshold a governance or credit committee sets.
- The CSRS 4200 report from your CPA for walk-in clinics discloses that no audit or review was performed and sets the basis of accounting, delivered within 30 days so a conditional financing approval on new medical equipment is not lost to an expired deadline.
- We answer should I incorporate my walk-in clinic by forming your Medical Professional Corporation under the Regulated Health Professions Act, so CRA taxes retained OHIP profit on the T2 at the 12.2% small-business rate instead of your personal 53.53% rate.
- We obtain your certificate of authorization CPSO, the document the College of Physicians and Surgeons of Ontario requires before your MPC can bill OHIP, structuring voting shares with the physician and non-voting shares for family, and renewing it annually.
- We complete the section 85 rollover on Form T2057, transferring your diagnostic equipment, EMR system and patient-list goodwill from your sole practice into the new MPC, so 100% of the capital gain and recapture a straight sale would trigger is deferred for CRA.
- We open the corporation’s CRA Business Number, the GST/HST account for the 13% on uninsured services and the payroll account for receptionists and nurses, and close your old sole-practice accounts, so your clinic never remits the same OHIP revenue twice and avoids a CRA penalty.
- We set the opening balance sheet, minute book, share classes and first fiscal year-end 53 weeks out, so dividends can later be split within TOSI, your MPC is ready for sale under the $1.25M lifetime capital gains exemption, and the first T2 is deferred.
- We rebuild months of unposted clinic bookkeeping from your OHIP remittance advice and EMR billing reports, separating exempt insured physician services from taxable uninsured billings such as sick notes, forms, third-party medicals and cosmetic work.
- We repair the input tax credit apportionment a prior bookkeeper got wrong, restricting credits to the share of clinic rent, medical supplies and EMR software that supports your taxable uninsured services rather than your exempt OHIP billings.
- We reconcile the physician overhead share across every associate and locum covering your extended hours, reallocating rent, receptionist wages and medical supplies to each doctor’s agreed cost-sharing percentage so the rebuilt books match the signed agreements.
- We catch up payroll for receptionists, nurses and administrative staff, rebuilding the PD7A source deduction remittances month by month and reissuing T4 slips, alongside the T4A slips for locum physicians paid during the unbookkept period.
- We then close each back year and file the outstanding T2 returns, and where late-filing penalties and interest on the arrears exceed $5,000 we quantify the exposure before requesting relief on Form RC4288 for your clinic.
- We prepare Form 1120 where a clinic physician or the medical professional corporation holds a US C corporation, reporting its income separately from your Ontario OHIP and uninsured billings so the two filing systems never contaminate each other.
- We file the protective Form 1120-F treaty-based return under the Canada-US treaty where your clinic corporation has US activity but no permanent establishment there, disclosing the position on Form 8833 so the IRS cannot deny treaty relief later.
- We complete Form 5472 for every reportable transaction between the US entity and its Canadian clinic owner, including management charges and loans, because a missed 5472 carries a $25,000 penalty for each form in each year.
- We resolve the hybrid mismatch that arises when a physician holds a US LLC that Canada treats as a corporation, coordinating the foreign tax credit so the same locum or consulting income is not taxed twice.
- We handle the cross-border filings for physicians working shifts at your walk-in clinic who remain US citizens or green card holders, covering Form 1040, FBAR and Form 8938 alongside their Canadian returns.
- We prepare your Form RC199 voluntary disclosure for the clinic, assembling the OHIP remittance advice, EMR billing reports and uninsured-service invoices that support the years being corrected before CRA opens any enquiry into your medical professional corporation.
- We test the application against the five acceptance conditions CRA applies: it must be voluntary, complete, involve a penalty or interest, cover information over a year past due, and include payment of the estimated tax owing.
- We disclose unremitted HST on the taxable uninsured side, where sick note fees, forms, third-party medicals and cosmetic work crossed the $30,000 threshold and the clinic kept billing patients without registering or filing a return.
- We report unreported clinic income and the shareholder loan draws a physician took from the medical professional corporation, correcting the Schedule 50 balance before subsection 15(2) adds those withdrawals to personal income on reassessment.
- We assess whether your clinic qualifies for the general track, which cancels penalties and grants partial interest relief, or the limited track where the conduct was more serious, and we advise you before any submission is made.
Walk-In Clinic Tax & OHIP Check
Six quick questions on your OHIP reconciliation, HST split, locum pay and physician tax. No fee shown.
1. Are you reconciling your OHIP remittance advice every month?
2. Are you splitting exempt insured from taxable uninsured billings?
3. Are you paying your locum physicians on T4A?
4. Are you protecting the $500,000 Small Business Deduction from passive income?
5. Is your clinic incorporated as a Medical Professional Corporation?
6. Do you have an Individual Pension Plan set up?
Free CPA Consultation for Walk-In Clinics
Case Studies: Walk-In Clinic Accounting & Tax
Toronto Walk-In Clinic (MPC) — HST-Exempt Cleanup & Tax Optimized
The problem: A Toronto family-medicine walk-in clinic running through a Medical Professional Corporation had a prior preparer charging 13% HST on some insured OHIP visits and claiming input tax credits on rent and EMR software against exempt revenue — both wrong under Schedule V of the Excise Tax Act — while examination tables and EMR servers sat in the wrong CCA classes, so the MPC overpaid tax and was exposed to an HST reassessment with no salary-and-dividend plan.
What we did: We removed HST from insured services, reversed the improper credits, restricted input tax credits to the taxable uninsured portion, rebuilt Schedule 8 to move equipment into Class 8 at 20% and EMR into Class 50 at 55%, filed an amended T2, and set a salary-and-dividend mix using the $500,000 small business deduction.
The result:
- Saved $27,300 in corporate tax in the first corrected year
- Removed a live HST reassessment exposure on exempt billings
- Recovered $9,400 of previously unclaimed CCA on equipment
Mississauga Multi-Physician Clinic — OHIP Reconciliation, Locum/T4A & Payroll Fixed
The problem: A Mississauga multi-physician cost-sharing clinic never reconciled its monthly OHIP remittance advice, so claw-backs and rejected claims went unrecovered; it paid locum physicians by e-transfer with no T4A slips for three years, ran receptionists and nurses off a spreadsheet with no PD7A remittances, and split overhead among four associates with no documentation — each a live CRA exposure.
What we did: We rebuilt the books in Sage 50, set up a monthly OHIP reconciliation workflow in QuickBooks Online, filed the outstanding T4A slips for the locums, moved staff onto Wagepoint payroll with proper PD7A remittances, documented the cost-sharing overhead split, and filed an RC4288 relief request on the late-slip penalties.
The result:
- All late T4A penalties cancelled under Form RC4288
- Recovered rejected OHIP claims inside the six-month window
- Reduced bookkeeping and payroll time by 9 hours per week
Ottawa Urgent-Care Clinic — Passive-Income Grind, IPP & Retirement Plan
The problem: An Ottawa urgent-care clinic earning well above what its physician owner drew had let surplus cash accumulate into passive investments, and the investment income was pushing past the $50,000 passive-income limit and grinding down the $500,000 small business deduction, so more of the clinic’s active income was taxed at the general rate. The owner, past 45, had only modest RRSP room and no retirement structure.
What we did: We purified the MPC of the passive assets, modelled an Individual Pension Plan against the RRSP, established the IPP so the corporation deducted the contributions, and restructured the salary needed to support it, protecting the 12.2% small-business rate on active income.
The result:
- Saved $31,800 in tax by restoring the small business deduction
- Sheltered far more than the RRSP limit through the IPP
- Built a funded retirement plan for the physician owner
Our clear, efficient process ensures every step is transparent, building trust and long-term client relationships.
Kickoff (Document Request)
Collect prior MPC T2 returns, OHIP remittance advice, locum agreements, your equipment and lease list, payroll, and bank statements.
First 30 Days (Cleanup & Setup)
Set up QuickBooks Online, Sage 50 or Xero, build the OHIP reconciliation workflow, split exempt and taxable billings, classify CCA, and configure T4A tracking.
Monthly Close
Monthly OHIP reconciliation, receipt capture, exempt-versus-taxable tracking, payroll, and locum payment logging.
Quarterly Planning Review
Salary and dividend mix, passive-income monitoring, IPP, and HST on uninsured services.
Year-End Close & MPC T2 Filing
Trial balance, financial statements, T2 with GIFI, T4A filing, and CRA preparation.
Get Your Walk-In Clinic Taxes Done Right Today
AFFORDABLE Pricing for Walk-In Clinics
We believe in clear, upfront pricing so you know exactly what to expect. All fees include HST.
- Tax Preparation (Corporation) — From $400
- Tax Return Filing (Corporation) — From $400
- Tax Compliance Audit — FREE CRA audit support for our clients
- Tax Strategy — FREE for our clients
- Accounting Base Plan — From $100 per month
- Bookkeeping Management — Free for our Accounting clients
- Financial Reporting — Free for our Accounting clients
- Business Formation — Flat $35
- Incorporation Process — Flat $35
- Entity Setup Assistance — Flat $35
- Full-Service Payroll — From $125 per month
Payment is by Interac e-Transfer to info@gondaliyacpa.ca only. Security question: Not Applicable, as auto-deposit is enabled.
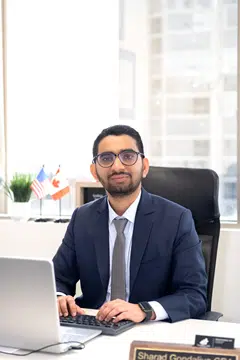
Meet Your Lead Walk-In Clinic Accountant
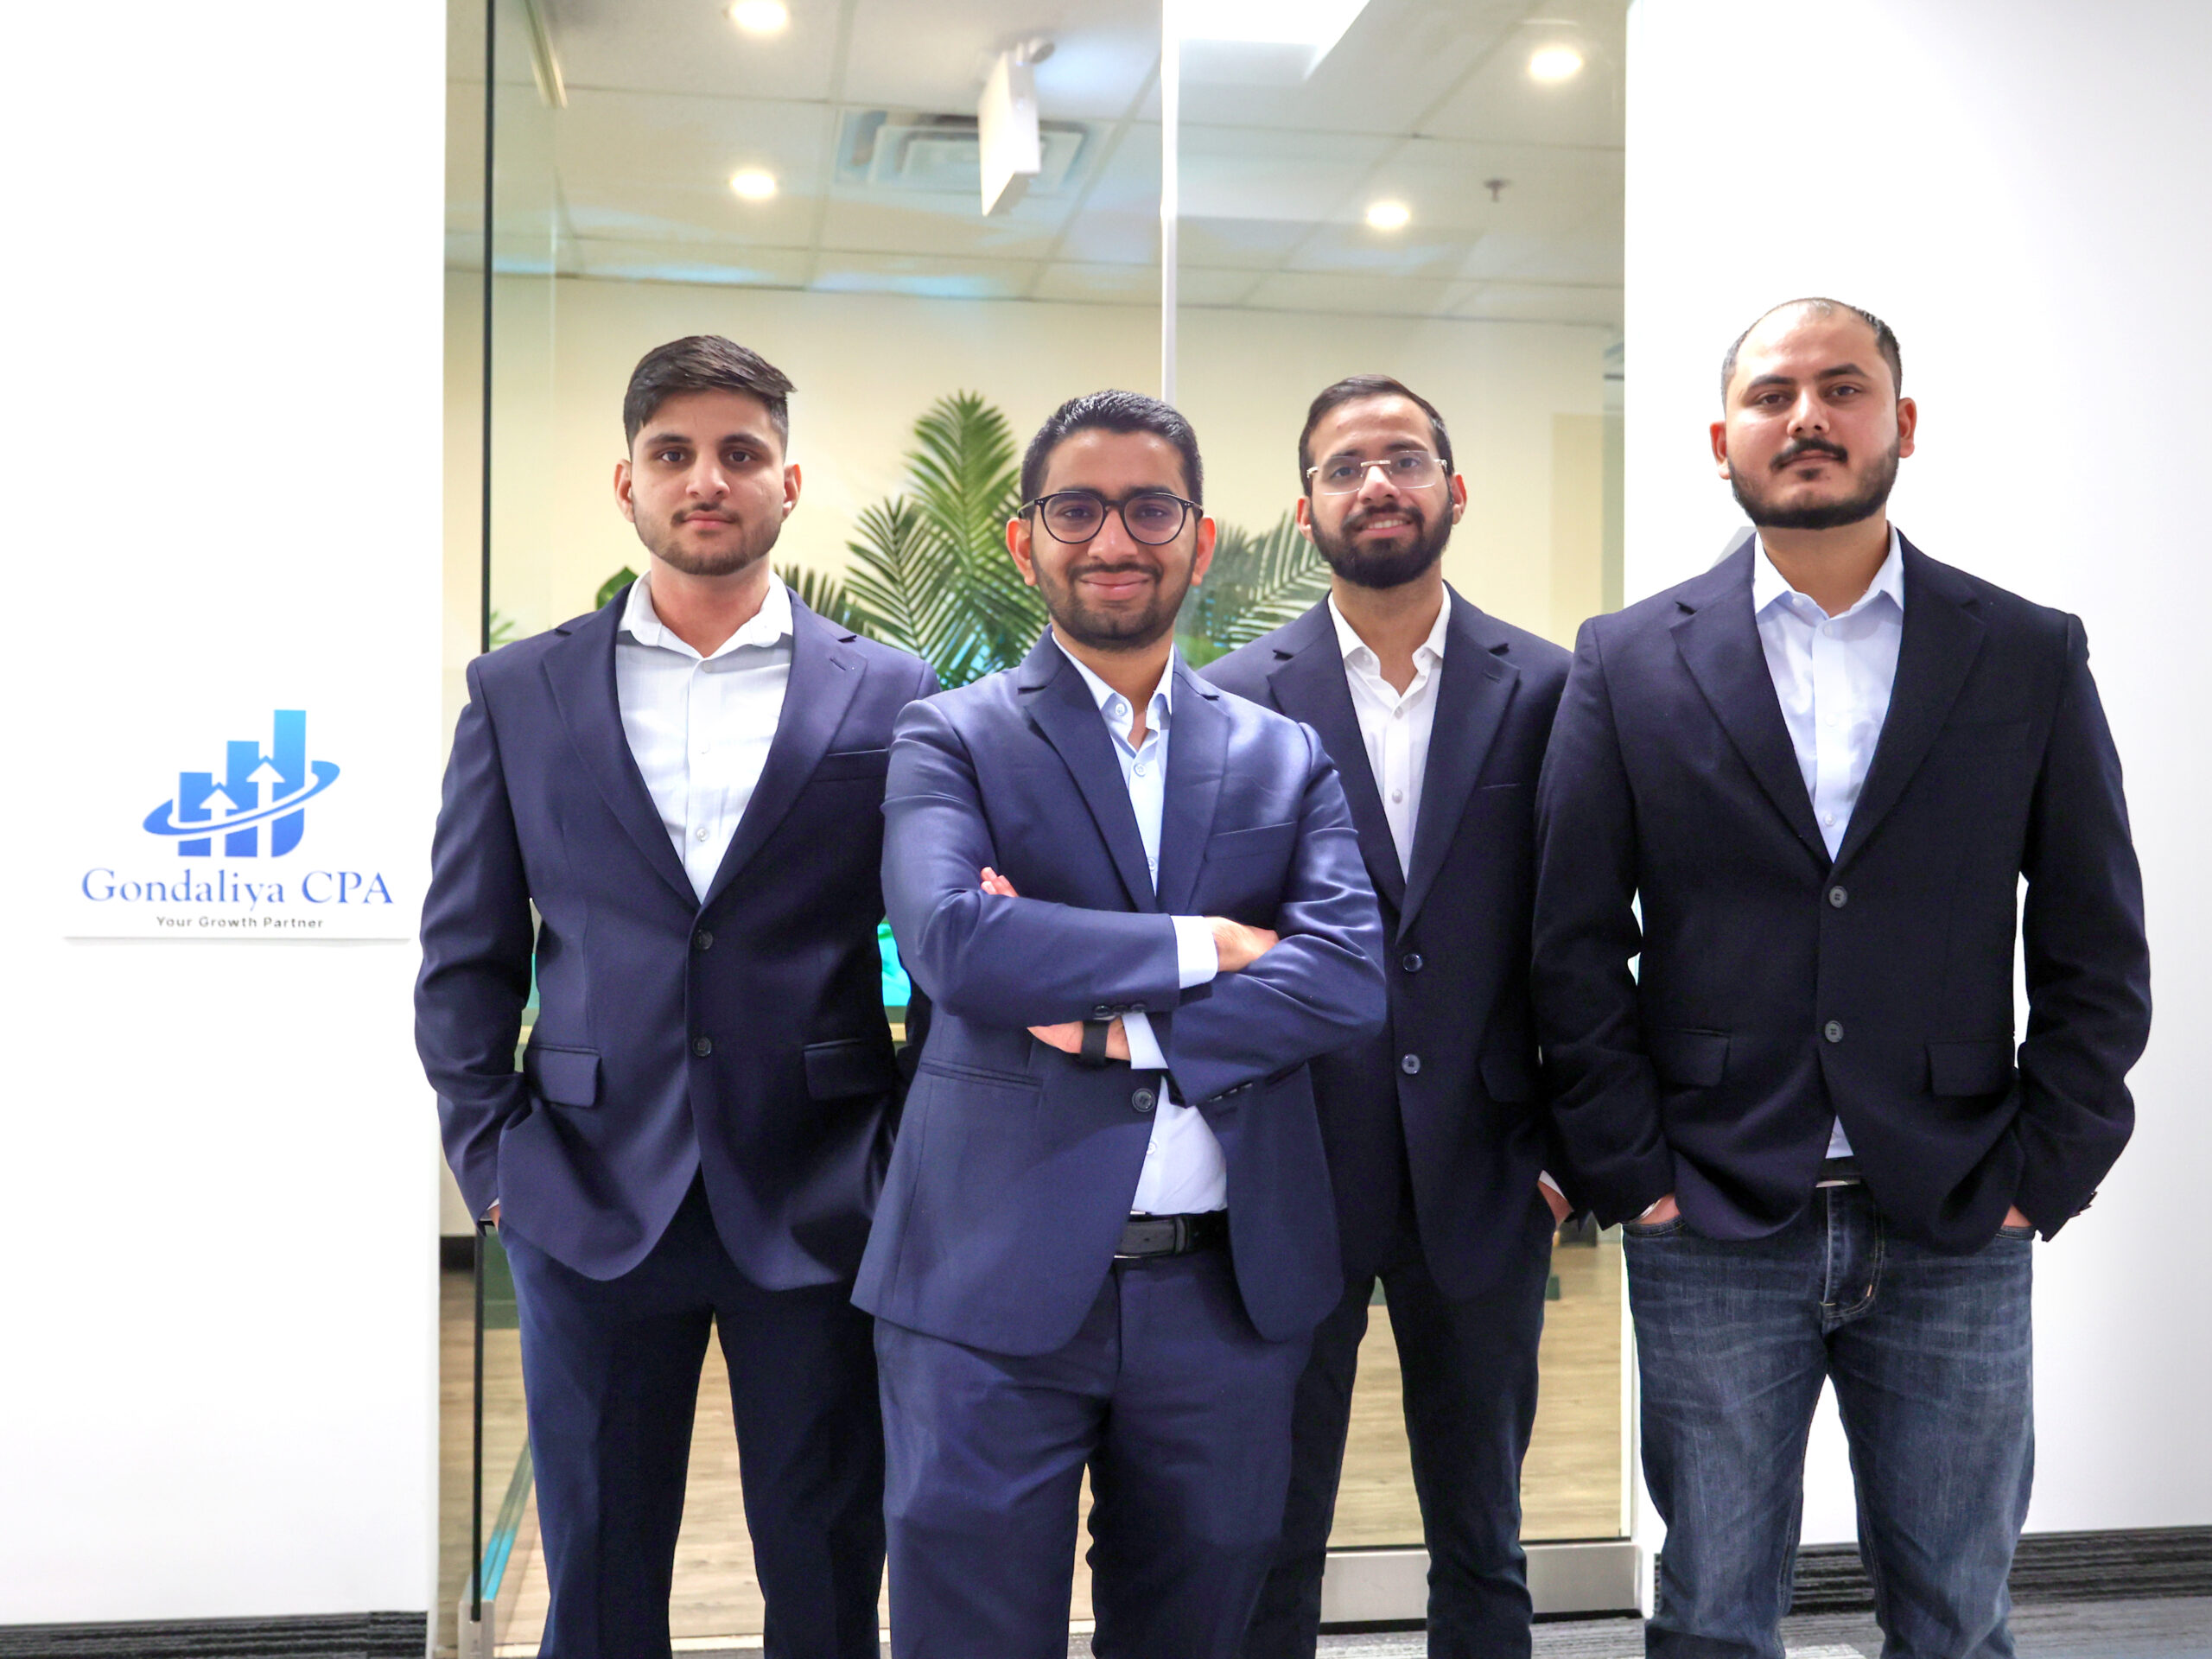
Meet your lead walk-in clinic accountant. As your medical corporation and physician tax adviser, you deal with the same two people every year.
What Our Clients Say
1300+ five-star reviews from walk-in clinics, physicians and small-business owners across Ontario and Canada.
Serving Walk-In Clinics Across Ontario
Our CPA team provides specialized accounting and tax solutions for walk-in clinics and their physicians throughout Ontario. We understand how a Medical Professional Corporation actually operates, what CRA, the CPSO and OHIP look at on a clinic file, and how to keep the exempt billings, the reconciliation and the physician tax planning in order.
Toronto (ON)
55 Queen St E Ste 1205, Toronto, ON M5C 1R6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Mississauga (ON)
2100 Camilla Rd #716, Mississauga, ON L5A 2J8
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Brampton (ON)
4 Starhill Crescent, Brampton, ON L6R 2P9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Scarborough (ON)
24 Clementine Square, Scarborough, ON M1G 2V7, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Vaughan (ON)
19 Cabinet Crescent, Woodbridge, ON L4L 6H9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Oshawa (ON)
210 Durham St, Oshawa, ON L1J 5R3, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Ottawa (ON)
2090 Neepawa Ave a314, Ottawa, ON K2A 3L6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Etobicoke (ON)
60 Stevenson Rd #1601, Etobicoke, ON M9V 2B4, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Hamilton (ON)
70 Starling Dr, Hamilton, ON L9A 0C5, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Guelph (ON)
1155 Gordon St, Guelph, ON N1L 1S8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Windsor (ON)
4387 Guppy Ct, Windsor, ON N9G 2N8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
North York (ON)
150 Graydon Hall Dr #912, North York, ON M3A 3B2, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Walk-In Clinic Accounting & Tax FAQs
Related Industries We Serve
Accountant for Incorporated Businesses
- T2 corporate tax filing and planning
- Salary versus dividend optimization
- Financial statements and bookkeeping
Accounting for Small Businesses
- Corporate tax planning for small businesses
- Business tax filing and financial statements
- Payroll and bookkeeping services
Accountant for Sole Proprietors
- T2125 and personal tax filing
- GST/HST and self-employed CPP
- Bookkeeping and incorporation timing
Accountant for Family-Owned Businesses
- Family dividend and TOSI planning
- Succession and estate transition
- Corporate tax filing and bookkeeping
Walk-In Clinic Accounting & Tax Done Right.
MPC T2 filing, Class 8 medical-equipment and Class 50 EMR CCA, OHIP reconciliation, exempt-versus-taxable HST, T4A locum slips, payroll, passive-income planning and IPPs under one roof. AFFORDABLE flat fees, no hourly billing. Licensed CPA Ontario. 1300+ five-star reviews. 30-Day Money-Back Guarantee.