



Tax Accountant for Family Doctors in Ontario and Across Canada
We set up and run your Medical Professional Corporation, reconcile your FHO capitation and OHIP billings, get the HST-exempt rules right, deduct your CMPA, CME and licensing, and plan your salary, dividends and pension so you keep more of what you earn. Whether you are a rostered FHO family doctor, a solo fee-for-service physician, part of a group family practice, or a locum, we handle the medical corporation books, the capitation and OHIP reconciliation and the payroll, keep your exempt and taxable billings straight, and plan the salary, dividends, IPP and eventual sale of your practice — with AFFORDABLE flat fees.
AFFORDABLE Family Doctor Tax Accountant
A family doctor is not paid like an ordinary business owner, and that is where the accounting starts. Most family physicians work inside a Family Health Organization, Group or Network and are paid capitation per rostered patient plus shadow billing, comprehensive care premiums and access bonuses, with fee-for-service, on-call stipends, hospital privilege income and teaching income layered on top, so the capitation statement and OHIP remittance have to be reconciled to the books — and your insured billings are HST-exempt, so you cannot recover input tax credits on your costs. That is why you need a family physician accountant Ontario doctors rely on. At Gondaliya CPA, we specialize in OHIP and capitation reconciliation and medical corporation tax planning for family doctors, keeping your exempt insured and taxable uninsured billings straight, paying your locums on T4A, and running your Medical Professional Corporation books — AFFORDABLE flat-fee support that keeps you CRA-compliant and stops you paying more tax than you owe.
As a family doctors accountant Ontario physicians trust, we work with rostered FHO and FHG capitation family doctors, solo fee-for-service physicians, group family practices on cost-sharing, and locum family doctors across Ontario, with year-round support rather than a once-a-year scramble. We tell you plainly what your Medical Professional Corporation can deduct, what it cannot, and where your real take-home sits after tax.
Let us handle the numbers so you can focus on the patients who actually need you.
Our Official Partners
Accounting That Understands How a Family Practice Actually Works
Running a family practice comes with financial pressures an ordinary business never faces. Your FHO capitation, comprehensive care premiums and shadow billing must be reconciled to the OHIP remittance; your insured billings are HST-exempt, so you cannot recover the tax on your costs; your locums are contractors while your staff are on payroll; and the Medical Professional Corporation, the passive-income rules and salary-versus-dividend decide your real take-home. At Gondaliya CPA, we understand the financial reality of a family physician and provide practical, primary-care-focused solutions across the GTA and all of Ontario.
Stay Compliant and Minimize Your Family Doctor Tax
For a family doctor, staying onside with CRA, the CPSO and OHIP and paying the least legal tax are the same job. We keep every filing on schedule while claiming every deduction the T2 allows, so nothing is missed and nothing invites a reassessment.
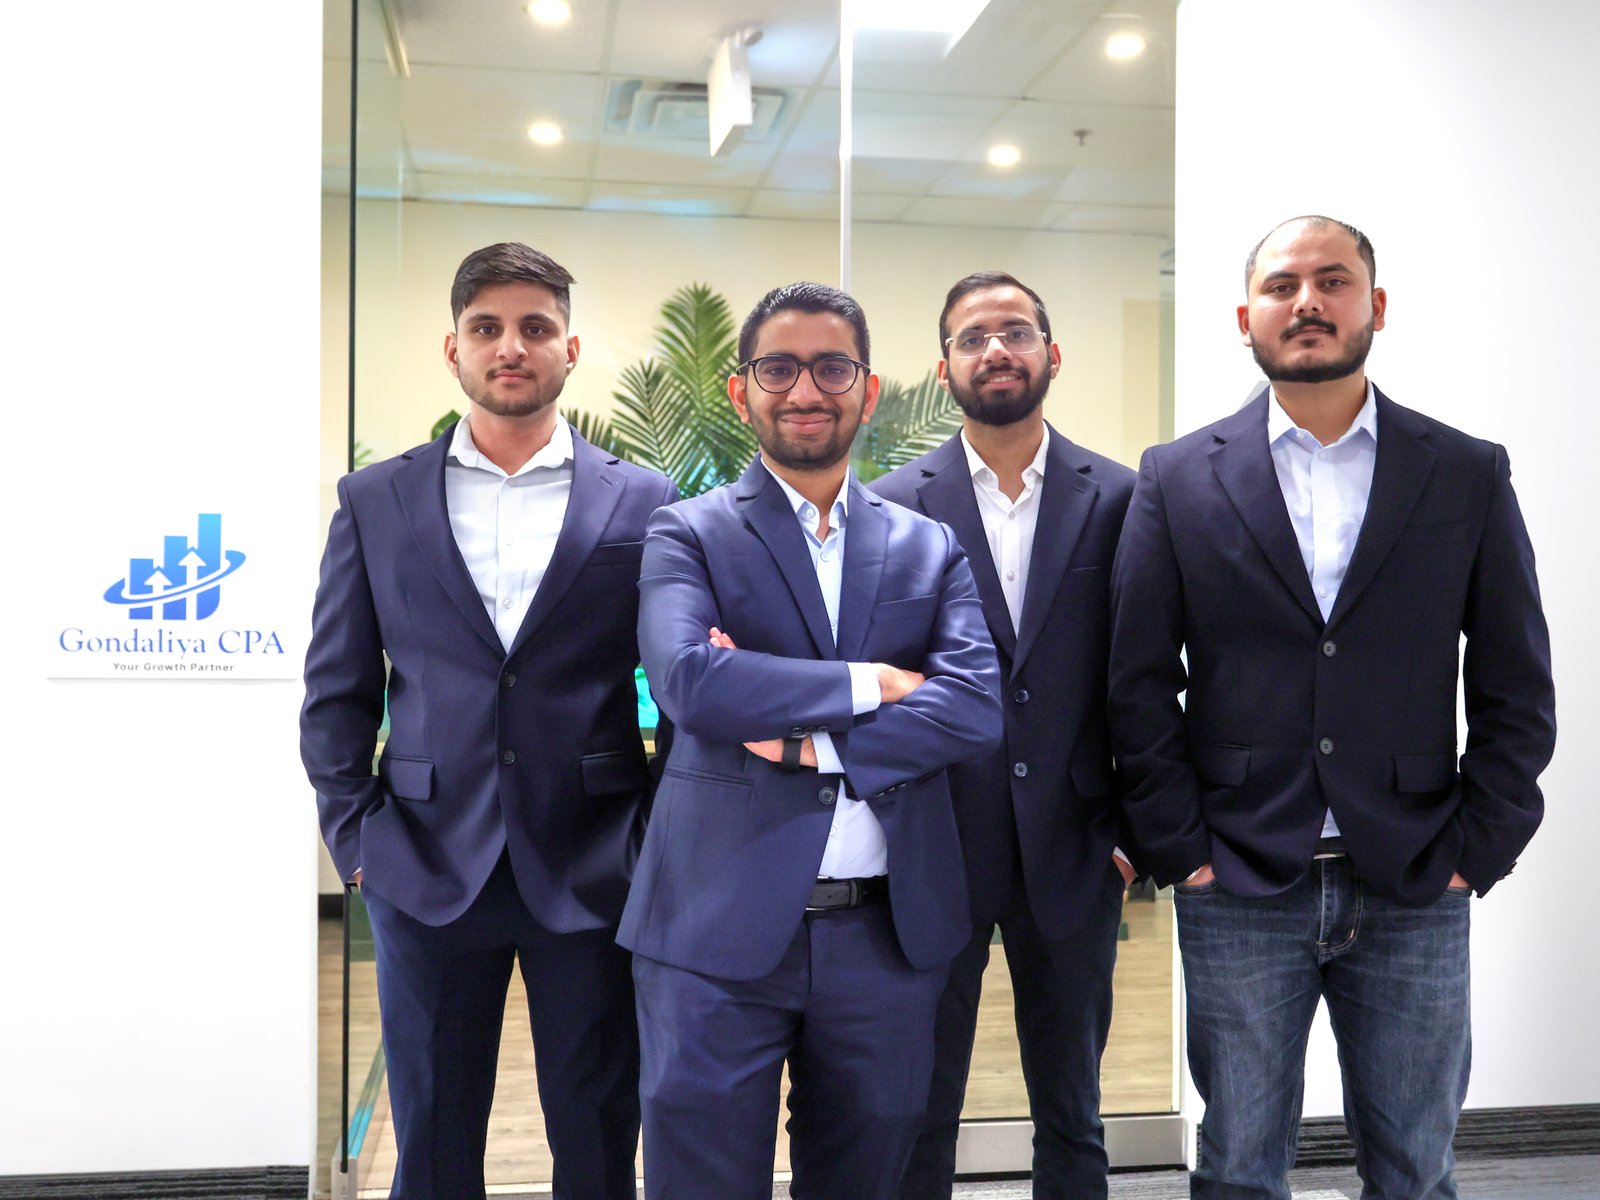
Accounting & Tax Experts for Family Doctors
- AFFORDABLE + Fully Registered CPA Firm
- Business and Corporate Tax Expert
- Small & Medium Business Expert
- Accounting, bookkeeping, and tax filing
- Certified CPA
- 1300+ 5-star Google reviews
- 30-Day Money-Back Guarantee
- 60-Day Fees Matching Policy
Why Choose Our Accounting Services for Family Doctors?
Tax Planning — Physician & MPC Expertise
We know the physician’s levers: protecting the $500,000 Small Business Deduction from the $50,000 passive-income grind, the salary-and-dividend mix, an Individual Pension Plan, and the section 85 rollover into your MPC. We claim every allowable amount and plan years ahead for a tax-efficient sale.
Consulting — Capitation & OHIP Bookkeeping
Our bookkeeping is built for a family practice. We reconcile your capitation statement and shadow billing against the monthly OHIP remittance, book the comprehensive care premiums and access bonuses, and keep exempt insured and taxable uninsured billings cleanly separated so your HST position is always right.
CRA Representation — Medical Audit & Payroll
When CRA questions your HST-exempt treatment, your locum classification, or your T4 and T4A slips, we prepare the response, defend the contractor-versus-employee position, and pursue relief on Form RC4288 where penalties came from a prior error.
Bookkeeping — Growth, Retirement & Structure
We build the CPA financial statements a mortgage or lender requires, set up the Individual Pension Plan and family non-voting shares that FHO income alone cannot fund, and structure your succession plan for your eventual retirement or the sale of your practice.
Google Reviews
Family Doctor Clients
Family Doctor Tax and Accounting Services in Ontario
Corporate Tax Filing for Family Doctors
Professional T2 preparation for your Medical Professional Corporation with Schedule 8 CCA on medical equipment, EMR and leaseholds, capitation and premium income, GIFI, and CRA compliance.
Accounting & Bookkeeping for Family Doctors
Capitation and OHIP-reconciled bookkeeping with financial statements, clean records, and monthly reporting built for a family practice and its cost-sharing physicians.
Corporate Tax Planning for Family Doctors
Smart tax planning to protect the Small Business Deduction, plan salary, dividends and an IPP, and manage the passive-income rules.
Catch-Up Corporate Tax Filing for Family Doctors
File overdue MPC T2 or T2125 years, rebuild records from your capitation statement and OHIP remittance, and get back into CRA compliance.
GST/HST Filing for Family Doctors
Correct HST filing that keeps exempt insured services separate from taxable uninsured forms, tracks the $30,000 threshold, and avoids CRA penalties.
Corporate Tax Cleanup for Family Doctors
Correct HST wrongly charged or claimed, fix CCA classes, restate the shareholder loan, reclassify locums, and bring every filing fully compliant.
CRA Audit Resolution Services for Family Doctors
Expert support for HST-exempt reviews, locum-versus-employee audits, personal-expense and capitation reconciliation queries, with confidence.
CPA Compilation Report (Notice to Reader) for Family Doctors
CPA-compiled financial statements that banks and mortgage lenders accept for financing and lending requirements.
Incorporation Services for Family Doctors
Full MPC incorporation including the CPSO Certificate of Authorization, share structure, and the section 85 rollover from your unincorporated practice.
Catch-Up Bookkeeping Services for Family Doctors
Rebuild months of unposted OHIP remittance advice, capitation statements and uninsured-service fees, restore the exempt-versus-taxable split, and hand your family practice audit-ready books.
US Corporation & LLC Tax Filing for Family Doctors
Form 1120 and treaty-based 1120-F returns, Form 5472 disclosure and foreign tax credit relief for physicians with US locum shifts or a cross-border LLC.
Voluntary Disclosure Program for Family Doctors
Form RC199 applications covering unfiled years, unreported uninsured billings and unremitted HST, seeking penalty and partial interest relief before CRA makes contact.
Accounting & Tax Services Tailored for Family Doctors
Real, practitioner-level CPA expertise for rostered FHO, solo fee-for-service, group family practice and locum family doctors across Ontario — built for how a family practice and its Medical Professional Corporation actually run.
- We prepare your T2 medical professional corporation return with GIFI on Schedule 100, reporting FHO capitation payments, comprehensive care premiums and OHIP fee-for-service income on their correct lines within six months of year-end, so CRA never flags your family practice for a desk audit.
- We claim capital cost allowance on Schedule 8, placing your examination-room table, spirometer and vaccine fridge in CCA Class 8 medical equipment at the 20% rate, because most family doctors under-claim this equipment and hand CRA tax they never owed.
- We put your examination room leaseholds into CCA Class 13 leasehold amortized straight-line over the lease term and your EMR software and servers into Class 50 at 55% on Schedule 8, so a CRA equipment review cannot disallow a misclassified first-year claim.
- We accrue the physician’s salary and bonus before your MPC’s year-end and record the T4 and the salary vs dividend family physician split, so CRA does not deny a bonus paid more than 179 days after your family practice’s year-end.
- We complete the T2 corporate tax return for family doctors with the instalment schedule, because once your MPC’s combined federal and Ontario tax passes $3,000 CRA requires instalments, and a practice that skips them carries arrears interest no deduction ever recovers.
- We reconcile your monthly capitation statement and shadow billing OHIP records against the remittance advice in QuickBooks Online, flagging clawed-back and rejected codes for resubmission inside OHIP’s six-month stale-dating window, so no access bonus income is lost and your books tie out for CRA.
- We allocate the cost-sharing overhead among your group family practice associates in Sage 50 medical accounting, splitting receptionist wages, nurse and staff wages and clinic rent by each doctor’s agreed 60% and 40% split, so CRA cannot recharacterize the group as a partnership.
- We separate exempt insured services from taxable revenue in Xero for physicians, tagging sick note and form fees and third-party medicals, so the billings that cross the $30,000 threshold are captured and CRA cannot assess unremitted HST on your family practice later.
- We capture every practice receipt through Dext receipt capture — CMPA malpractice dues, CME course costs and CPSO and OMA licensing — so you hold the six years of records section 230 requires and never lose a deduction on a CRA review.
- We tie your OSCAR EMR billing, Accuro or TELUS Health exports to bank deposits monthly and run receptionist and nurse wages through Wagepoint payroll, remitting the PD7A, because CRA levies a 10% penalty the first time source deductions arrive late.
- We set the salary vs dividends for family doctors mix, paying T4 salary up to the $68,500 CPP maximum earnings while the balance flows as dividends, so CRA collects the least combined tax on your FHO capitation and premium income.
- We keep your active practice income under the $500,000 small business limit taxed at 12.2% under section 125 small business deduction, watching the $50,000 passive income limit CRA uses to grind the deduction away, so more capitation income stays at the low rate.
- We monitor the associated corporations section 256 rules across any management corporation and your MPC, because sharing the single $500,000 limit or drifting into a specified investment business can cost your family practice the low rate and trigger a CRA reassessment.
- We model an individual pension plan physician strategy against an RRSP, because past 40 an IPP shelters more than the $33,810 RRSP limit, and the MPC deducts contributions on its T2, so CRA taxes less of your FHO capitation profit.
- We pay TOSI T1206 physician family dividends to relatives who hold non-voting shares, applying the tax on split income rules and the excluded-business tests, so a spouse’s dividend from your medical corporation is not reassessed by CRA at the top 53.53% rate.
- We reconstruct three years of unfiled MPC T2, or a T2125 unincorporated physician return where you never incorporated, from your capitation statements, OHIP remittance advice and EMR exports, so CRA cannot arbitrarily assess your family practice’s income and overcharge you.
- Late filing costs the 5% plus 1% per month late filing penalty of the balance owing up to twelve months, so we file your oldest unfiled T2 first to stop the penalty compounding and limit the arrears interest CRA charges your medical corporation.
- We prepare the unfiled T4A locum physician slips for every locum you paid as an independent contractor, filing them with the catch-up T2 returns so CRA does not add the penalty that starts at $100 per slip to your practice’s arrears.
- We file an RC4288 taxpayer relief request to cancel penalties and interest where physician illness, a locum’s departure or a prior bookkeeper’s error delayed your medical corporation compliance, covering the ten years CRA allows and saving your family practice real money.
- We rebuild the undepreciated capital cost pools for the unfiled years so missed medical equipment CCA at 20% and Class 50 EMR at 55% is recovered, and recapture on equipment you sold is reported before CRA reassesses your MPC.
- Insured OHIP and FHO capitation services are GST/HST exempt medical services under Schedule V of the Excise Tax Act, so your practice charges no HST on patient care and claims no input tax credits on the 13% HST Ontario it pays on rent.
- Uninsured services — sick notes, forms, insurance medicals and uninsured patients — are taxable, and once that revenue crosses the $30,000 HST registration threshold your practice must register and charge 13% HST, so we track the exact quarter you cross it before CRA assesses back-tax.
- Because your insured billings are exempt, we restrict input tax credits to the portion of costs for taxable uninsured work, apportioning the 13% HST on your office overhead share of rent, so CRA cannot deny an over-claimed credit and reassess your family practice.
- We file your annual GST/HST return within three months of year-end, reconciling the taxable line to your form and sick-note fee income, because CRA’s matching program compares it to your T2 and flags a practice whose figures disagree for an HST audit.
- Where your uninsured billings stay under the $30,000 small supplier limit, your practice files no HST return at all, and we confirm that physician services HST exempt position annually, so you neither charge patients tax in error nor face a CRA assessment.
- We file amended returns where a prior preparer wrongly charged 13% HST Ontario on insured OHIP or FHO capitation services or claimed input tax credits on exempt costs, correcting both before CRA reverses the credits with interest and reassesses your medical professional corporation.
- We file an amended T2 filing for family doctors to move examination tables and EMR computers from the wrong class into CCA Class 8 at 20% and Class 50 at 55%, restoring the medical equipment CCA CRA lets your practice claim every year.
- We clean up the shareholder loan and report it on Schedule 50 shareholder loan, because a balance the physician owes the MPC beyond the 24-month limit is added to personal income by CRA under the subsection 15(2) shareholder loan rule, a costly surprise we prevent.
- We review whether physicians you paid on T4A are genuine locums or de facto employees, so our locum accounting for family doctors files amended slips before CRA reassesses back CPP, EI and a 10% penalty on wages that belonged on a T4.
- We reclassify uninsured service fees a prior bookkeeper lumped into exempt OHIP income and recover input tax credits on the taxable portion at 13%, filing the adjustment before the four-year CRA reassessment window closes and putting the refund back in your family practice.
- When CRA opens an HST audit questioning whether your practice correctly split exempt insured from taxable uninsured billings, our CRA audit family physician team manages the file and answers inside the 30-day query deadline, so a one-year review does not expand into three.
- Where CRA challenges your locum’s contractor status, our accountant for locum family doctors assembles the locum agreements, invoices and T4A slips and argues the control tests across the three audited years, sparing your practice the back CPP, EI and payroll a T4 reclassification would cost.
- When CRA reviews personal expenses run through the MPC — the physician’s car, home internet, family meals — we document the business-use portion under ITA 18(1)(a) business expenses, because a single denied category usually opens a full reassessment of the three prior years.
- When CRA runs indirect verification of income comparing your bank deposits to reported OHIP billing family doctor revenue and capitation, we prepare the source-and-application-of-funds reconciliation and answer within the 30-day deadline before CRA assesses the unexplained gap.
- We file the Notice of Objection within 90 days of a CRA reassessment and pursue relief on Form RC4288 where a prior accountant left your OHIP and capitation reconciliation wrong, protecting your right to the Tax Court and saving interest your MPC should not carry.
- We prepare the CSRS 4200 CPA compilation report, the financial statements for family doctors a bank requires across two fiscal years and tied to your T2, before it will finance a $300,000 practice fit-out or new medical equipment, so a missing report stalls the loan.
- We build the working-capital picture a mortgage lender underwrites, presenting your OHIP and capitation receivable and uninsured-service accruals on the balance sheet over two fiscal years and tying them to your T2, so our accounting firm for family doctors keeps your financing on schedule.
- Lenders financing a home or an equipment purchase want two years of compiled statements showing stable income, so your CPA for family doctors presents your capitation, premium and fee-for-service revenue with the T2 a bank credit desk expects, so the loan is not stalled.
- For prequalification with a hospital or a large cost-sharing group, our family doctors accountant Ontario team produces reviewed statements presenting your capitation and premium revenue tied to your T2, so a weak file does not stall the $500,000-revenue prequalification a credit committee requires.
- The CSRS 4200 report from your chartered professional accountant for family doctors discloses that no audit or review was performed, sets the basis of accounting and ties to your T2, delivered within 30 days so financing approval on new medical equipment is not lost.
- We handle your medical professional corporation setup under the Regulated Health Professions Act, so CRA taxes retained OHIP and capitation profit on the T2 at the 12.2% small-business rate instead of your personal 53.53% rate.
- We obtain the certificate of authorization CPSO that the College of Physicians and Surgeons of Ontario requires before your MPC can bill OHIP capitation, structuring 100% of voting shares with the physician and non-voting shares for family, so a lapsed certificate cannot halt your billing.
- We complete the section 85 rollover physician election on Form T2057, transferring your medical equipment, EMR system and patient-list goodwill from your unincorporated practice into the new MPC, so 100% of the capital gain and recapture a straight sale would trigger is deferred.
- Our incorporation for family physicians opens the corporation’s CRA Business Number, the GST/HST account for the 13% on uninsured services and the payroll account for your receptionist and nurse, and closes your old sole-practice accounts, so your practice avoids a duplicate-remittance CRA penalty.
- We set the balance sheet, minute book, share classes and first fiscal year-end 53 weeks out, so dividends can later be split within TOSI, your MPC is ready for sale under the $1.25M lifetime capital gains exemption, and the first T2 defers CRA’s balance-due date.
- We rebuild every unposted month from your OHIP remittance advice, monthly capitation statement and EMR form-fee log, so each dollar of insured billing and third-party medical revenue lands in the correct period before your catch-up books close.
- Our catch-up work re-tags the backlog into exempt insured billings and taxable uninsured work such as sick notes and insurance medicals, pinpointing the month that stream passed the $30,000 small-supplier threshold and input tax credits had to be apportioned.
- We untangle the overhead-sharing pool your association agreement runs through, splitting reception salaries, clinic rent and EMR licences by the agreed percentage, so recovery cheques from the other physicians stop inflating what looks like practice revenue.
- We rebuild arrears payroll for your receptionist, nurse and medical office assistant, matching each PD7A remittance to the source deductions actually withheld, then issuing the outstanding T4 slips so CRA can close the payroll account arrears.
- With a reconstructed ledger in hand we file the back-year T2 returns for your Medical Professional Corporation, resetting shareholder-loan balances and retained earnings so the opening figures of your next filing year finally tie.
- Where you hold shares in a US C corporation from a cross-border clinic venture, we prepare the Form 1120 return with its state filings and reconcile that American result back to your Canadian reporting.
- If your practice corporation earns fee income in the United States without a permanent establishment there, we file a protective treaty-based Form 1120-F return claiming Article V and Article VII relief and keep the position fully documented.
- A US corporation or single-member LLC you own must disclose reportable transactions with you on Form 5472, which we prepare on schedule because a single missed filing carries a $25,000 penalty for the year.
- A US LLC is opaque to CRA yet transparent to the IRS, so we document that hybrid mismatch and structure the foreign tax credit claim on Form T2209 or corporate Schedule 21 to stop the same medical income being taxed twice.
- For a family physician holding a US medical licence and taking locum shifts across the border, we count substantial-presence days, allocate the locum fee between the two countries and coordinate both filings so neither authority is short-paid.
- We assemble the Form RC199 application for your practice, listing each unfiled year, the corrected income figures and the supporting OHIP and banking records, and submit it before any CRA enforcement contact removes the option entirely.
- A disclosure only holds where all five acceptance conditions are met: it is voluntary, it is complete, a penalty applies or could apply, the information is at least one year overdue, and estimated tax owing accompanies it.
- Where your sick-note, form and insurance-medical fees passed the $30,000 registration threshold years ago and no return was ever filed, we quantify the unremitted 13% HST on that taxable stream and disclose it with the apportioned credits.
- We disclose unreported third-party medical income together with personal draws left in the shareholder loan account past the subsection 15(2) repayment window, restating them as salary or dividends so the correction is complete rather than partial.
- We press for the general program track, which carries penalty relief and partial interest relief, and tell you plainly when a pattern of repeated non-filing points instead to the limited track, where only gross-negligence penalty relief is available.
Family Doctor Tax & Incorporation Check
Six quick questions on your capitation and OHIP reconciliation, HST split, locum pay and physician tax. No fee shown.
1. Are you reconciling your FHO capitation statement and OHIP remittance every month?
2. Are you incorporated as a Medical Professional Corporation?
3. Are you splitting exempt insured from taxable uninsured billings?
4. Are you paying your locums on T4A?
5. Do you have an Individual Pension Plan set up?
6. Are you protecting the $500,000 Small Business Deduction from passive income?
Free CPA Consultation for Family Doctors
Case Studies: Family Doctor Accounting & Tax
Toronto FHO Family Doctor — Incorporation, IPP & Capitation/OHIP Reconciliation
The problem: A Toronto rostered FHO family doctor was still unincorporated, filing professional income on a T2125 and paying personal tax up to 53.53% on capitation, comprehensive care premiums and shadow billing that were never reconciled to the OHIP remittance, so clawed-back and rejected codes went unrecovered. Surplus cash was piling up with no retirement structure and no plan to defer tax on income well above what the doctor drew.
What we did: We incorporated a Medical Professional Corporation with a CPSO Certificate of Authorization, rolled the practice in on a section 85 election, built a monthly capitation and OHIP reconciliation workflow in QuickBooks Online, set a salary-and-dividend mix using the $500,000 small business deduction at 12.2%, and established an Individual Pension Plan the MPC deducts.
The result:
- Saved $34,600 in tax in the first incorporated year
- Recovered rejected OHIP codes inside the six-month window
- Built a funded IPP the FHO income alone could not
Mississauga Group Family Practice — Cost-Sharing, HST-Exempt Cleanup & Locum T4A Fixed
The problem: A Mississauga group family practice on cost-sharing had a prior preparer charging 13% HST on insured visits and claiming input tax credits on rent against exempt revenue — both wrong under Schedule V — split overhead among four associates with no documentation, paid locums by e-transfer with no T4A slips for three years, and ran receptionist and nurse wages off a spreadsheet with no PD7A remittances.
What we did: We removed HST from insured services, reversed the improper credits, restricted input tax credits to the taxable uninsured portion, rebuilt the cost-sharing overhead split in Sage 50, filed the outstanding T4A locum slips, moved staff onto Wagepoint payroll with proper PD7A remittances, and filed an RC4288 relief request on the late-slip penalties.
The result:
- All late T4A penalties cancelled under Form RC4288
- Removed a live HST reassessment exposure on exempt billings
- Reduced bookkeeping and payroll time by 8 hours per week
Ottawa Family Physician — Passive-Income Grind & Family Non-Voting Shares
The problem: An Ottawa family physician earning well above what she drew had let surplus cash accumulate into passive investments inside her MPC, and the investment income was pushing past the $50,000 passive-income limit and grinding down the $500,000 small business deduction, so more of her active capitation and premium income was taxed at the general rate. No family shares were in place to split dividends.
What we did: We purified the MPC of the passive assets, issued non-voting shares to her spouse within the TOSI rules on Form T1206, modelled dividends against her salary, and restored the full 12.2% small-business rate on active income while documenting the excluded-business tests.
The result:
- Saved $29,700 in tax by restoring the small business deduction
- Added a compliant family dividend within the TOSI rules
- Protected the low rate on capitation and premium income
Our clear, efficient process ensures every step is transparent, building trust and long-term client relationships.
Kickoff (Document Request)
Collect prior MPC T2 or T2125, OHIP remittance and capitation statements, locum agreements, your equipment and lease list, payroll, and bank statements.
First 30 Days (Cleanup & Setup)
Set up QuickBooks Online, Sage 50 or Xero, build the capitation and OHIP reconciliation workflow, split exempt and taxable billings, classify CCA, and configure T4A tracking.
Monthly Close
Monthly capitation and OHIP reconciliation, receipt capture, exempt-versus-taxable tracking, payroll, and locum payment logging.
Quarterly Planning Review
Salary and dividend mix, passive-income monitoring, IPP, and HST on uninsured services.
Year-End Close & MPC T2 Filing
Trial balance, financial statements, T2 with GIFI (or T2125), T4A filing, and CRA preparation.
Get Your Family Doctor Taxes Done Right Today
Affordable Pricing for Family Doctors
We believe in clear, upfront pricing so you know exactly what to expect. All fees include HST.
- Tax Preparation (Corporation) — From $400
- Tax Return Filing (Corporation) — From $400
- Tax Compliance Audit — FREE CRA audit support for our clients
- Tax Strategy — FREE for our clients
- Accounting Base Plan — From $100 per month
- Bookkeeping Management — Free for our Accounting clients
- Financial Reporting — Free for our Accounting clients
- Business Formation — Flat $35
- Incorporation Process — Flat $35
- Entity Setup Assistance — Flat $35
- Full-Service Payroll — From $125 per month
Payment is by Interac e-Transfer to info@gondaliyacpa.ca only. Security question: Not Applicable, as auto-deposit is enabled.
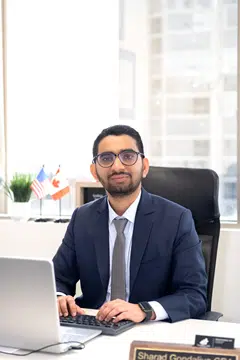
Meet Your Lead Family Doctor Accountant
Meet your lead family doctor accountant. As your medical corporation and physician tax adviser, you deal with the same two people every year.
What Our Clients Say
1300+ five-star reviews from physicians and small-business owners across Ontario and Canada.
Serving Family Doctors Across Ontario
Our CPA team provides specialized accounting and tax solutions for family physicians throughout Ontario. We understand how an FHO, FHG or FHN family practice actually operates, what CRA looks at on a medical corporation return, and how to reconcile your capitation and OHIP billings to the books.
Toronto (ON)
55 Queen St E Ste 1205, Toronto, ON M5C 1R6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Mississauga (ON)
5373 Bullrush Dr, Mississauga, ON, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Brampton (ON)
4 Starhill Crescent, Brampton, ON L6R 2P9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Scarborough (ON)
24 Clementine Square, Scarborough, ON M1G 2V7, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Vaughan (ON)
19 Cabinet Crescent, Woodbridge, ON L4L 6H9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Oshawa (ON)
210 Durham St, Oshawa, ON L1J 5R3, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Ottawa (ON)
2090 Neepawa Ave a314, Ottawa, ON K2A 3L6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Etobicoke (ON)
60 Stevenson Rd #1601, Etobicoke, ON M9V 2B4, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Hamilton (ON)
70 Starling Dr, Hamilton, ON L9A 0C5, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Guelph (ON)
1155 Gordon St, Guelph, ON N1L 1S8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Windsor (ON)
4387 Guppy Ct, Windsor, ON N9G 2N8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
North York (ON)
150 Graydon Hall Dr #912, North York, ON M3A 3B2, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Family Doctor Accounting & Tax FAQs
Related Industries We Serve
Accountant for Walk-In Clinics
- Medical corporation T2 filing and OHIP reconciliation
- HST-exempt billing and locum T4A pay
- Physician tax planning and payroll
Accountant for Incorporated Businesses
- T2 corporate tax filing and planning
- Salary versus dividend optimization
- Financial statements and bookkeeping
Accountant for Numbered Companies
- Numbered company T2 filing and GIFI
- Holding company and investment income
- Incorporation and entity setup
Accounting for Small Businesses
- Corporate tax planning for small businesses
- Business tax filing and financial statements
- Payroll and bookkeeping services
Family Doctor Accounting & Tax Done Right.
MPC T2 filing, Class 8 medical-equipment and Class 50 EMR CCA, FHO capitation and OHIP reconciliation, exempt-versus-taxable HST, T4A locum slips, payroll, passive-income planning and IPPs under one roof. AFFORDABLE flat fees, no hourly billing. Licensed CPA Ontario. 1300+ five-star reviews. 30-Day Money-Back Guarantee.