



Tax Accountant for Boxing Gyms in Ontario and Across Canada
A boxing gym is usually two businesses sharing one address. On one side sit memberships, class packs, day passes, group classes and private coaching — ordinary taxable revenue for a for-profit corporation filing a T2. On the other sits the competitive room: an amateur club funded by dues and often organized as a non-profit that cannot pay its founder a dividend, and a professional side where purses, management percentages and corner fees move to and through individuals rather than across the front counter. Add fight nights, where the gate, the sponsorship, the sanctioning cost and the venue bill all belong to one date, and a contact-sport insurance load an ordinary fitness floor never carries. We take those streams apart in your books, report each on the right line and the right slip, and keep the whole corporation on one filing calendar — with AFFORDABLE flat fees.
AFFORDABLE Boxing Gym Tax Accountant
Most boxing gyms in Ontario are not one business. There is the commercial side — memberships, class packs, day passes, group sessions and private coaching — which is plain taxable service revenue earned by a for-profit corporation that files a T2. Then there is the competitive side: an amateur club living on dues, frequently set up as a non-profit that can never pay its founder a dividend, and a professional stream where purses, management percentages and corner fees are paid to individuals rather than banked as membership income. Three or four times a year a fight card lands on top of both, generating a gate, sponsorship money, a sanctioning cost and a venue bill that all belong to a single date. The trouble is that almost every owner runs all of it through one bank account and one set of books.
That is the problem we solve. At Gondaliya CPA we take the streams apart, give the amateur programme, the commercial floor, the coaching income and each fight night their own place in the ledger, and then report each one the way CRA expects to see it — the T2 and GIFI for the corporation, 13% HST on the taxable supplies, T4 payroll with WSIB for the staff you employ, and the correct slips for the amounts that leave the business as purse, corner or management money. Where a club is genuinely organized for non-profit purposes we say so plainly, and we set out what that structure costs you as well as what it gives you.
Flat fees, year-round contact, and a clear answer on which of your two businesses is actually making money.
Our Official Partners
Accounting That Understands How a Boxing Gym Actually Works
The money in a boxing gym does not arrive from one place or on one schedule. Membership and coaching fees come in monthly, day passes and class packs come in upfront, an amateur programme runs on dues that may sit inside a completely different legal structure, purses and corner fees go out to individuals on fight weekends, and every so often a single Saturday produces a gate, a sponsorship cheque and a stack of costs that all belong to that one date. We build the books around that reality instead of forcing a fitness-studio template over it.
Stay Compliant and Minimize Your Boxing Gym Tax
Compliance and tax saving are the same piece of work for a boxing gym. Filings go in on time, revenue is recognized when it is earned, every capital dollar lands in the class it belongs to, and the amounts that leave the business as purse or corner money are documented before anyone asks about them.
Accounting & Tax Experts for Boxing Gyms
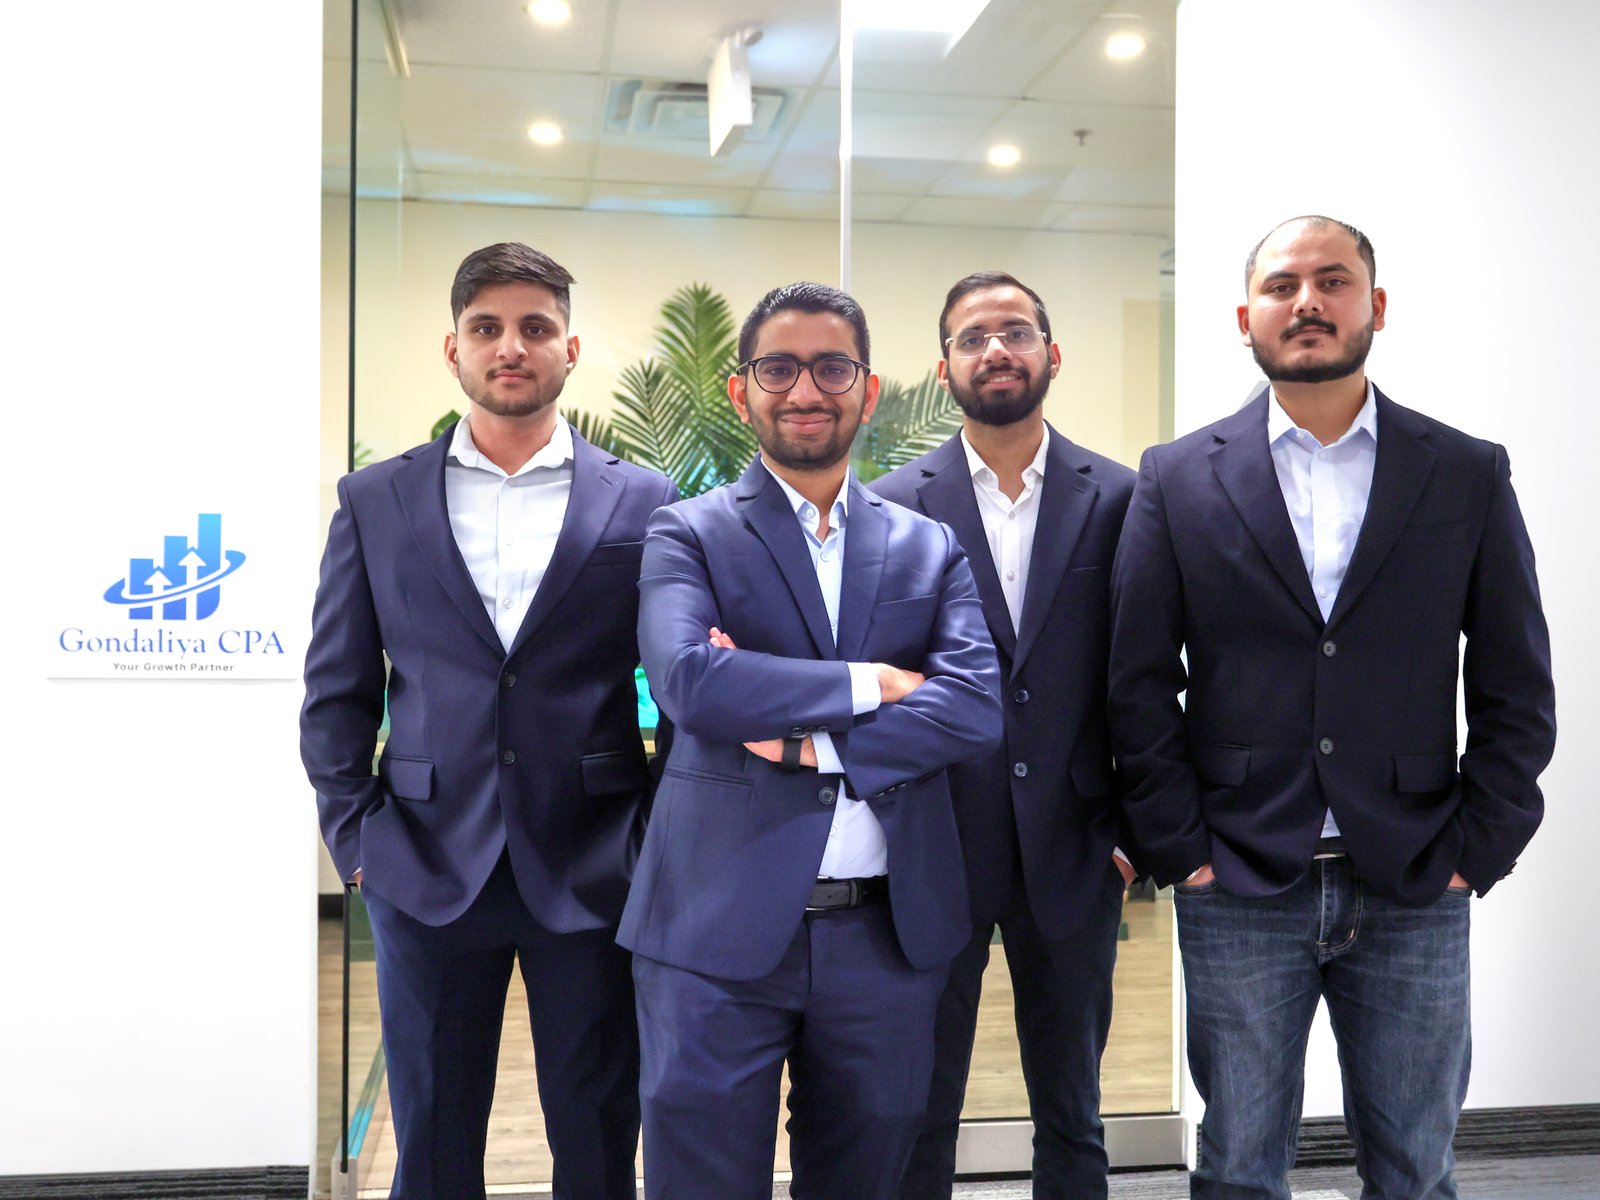
- AFFORDABLE + Registered CPA Firm
- Business and Corporate Tax Expert
- Small & Medium Business Expert
- Accounting, bookkeeping, and tax filing
- CPA (Chartered Professional Accountant)
- 1450+ 5-star Google reviews
- 30-Day Money-Back Guarantee
- 60-Day Fees Matching Policy
Why Choose Our Accounting Services for Boxing Gyms?
Structure — Amateur Club vs For-Profit Gym
We settle the question everything else depends on: whether you are a for-profit corporation, a club organized exclusively for non-profit purposes under ITA 149(1)(l), or both under one roof, and what each choice costs you.
Bookkeeping — Packs, Coaching and Event Nights
Class packs and day-pass books stay unearned until they are used, coaching income is tracked separately from dues, and each fight card gets its own department so the gate, sponsorship, sanctioning and venue costs land on one date.
CRA Representation — Cash, HST and Worker Status
Door cash, HST on the commercial floor, coach classification and transfers between a club and a commercial gym are the four things auditors open with. We assemble the documents and answer them.
Payroll, Slips and Incorporation
Coaching payroll with WSIB, T4 slips reconciled to the PD7A, the right slips behind purse and corner payments, and the section 85 rollover on Form T2057 when it is time to incorporate.
Google Reviews
Boxing Gym Clients
Boxing Gym Tax and Accounting Services in Ontario
Corporate Tax Filing (T2) for Boxing Gyms
T2 preparation with GIFI, Schedule 8 capital cost allowance on the ring, bags and build-out, and unused packs carried as a liability rather than profit.
Bookkeeping & Accounting for Boxing Gyms
A ledger that keeps the commercial floor, the amateur programme, coaching income and each fight night in their own departments instead of one revenue account.
Payroll Services for Boxing Gyms
Coaching and front-desk payroll with WSIB from the first hire, PD7A remittances, T4 slips, and clean employee-versus-contractor reasoning behind every coach.
GST/HST Filing for Boxing Gyms
AFFORDABLE 13% HST filing on memberships, day passes, coaching and gear, with the input tax credits on rent and equipment recovered in full.
Tax Planning for Boxing Gyms
Structure first, then the salary and dividend mix, the small business deduction, purchase timing and an eventual sale of the for-profit company.
Corporate Catch-Up Filing for Boxing Gyms
Overdue T2 and HST years filed in sequence, unfiled T1044 returns for an incorporated club, and taxpayer relief pursued where penalties came from error.
CRA Audit Resolution for Boxing Gyms
Door-cash reviews, HST assessments, coach classification and questions about money moving between a club and a commercial gym, answered with documents.
CPA Financial Statements (Notice to Reader) for Boxing Gyms
CPA-compiled statements a landlord or an equipment lender will accept, showing earned revenue and the unused pack balance separately.
Incorporation Services for Boxing Gyms
NUANS, articles, share structure and the section 85 rollover of your ring, equipment, member list and goodwill into the new corporation.
Catch-Up Bookkeeping Services for Boxing Gyms
Months or years of books rebuilt from membership software exports, processor settlements, door sheets and the fight-night paperwork in your office.
US Corporation & LLC Tax Filing for Boxing Gyms
Form 1120 or 1120-F and Form 5472 for a US entity behind a promotion, a cross-border camp or a licensing deal, coordinated with your Canadian T2.
Voluntary Disclosure Program for Boxing Gyms
Unreported door cash or HST collected on memberships but never remitted, regularized on a disclosure before CRA makes contact.
Accounting & Tax Services Tailored for Boxing Gyms
Practitioner-level CPA work for commercial boxing gyms, registered amateur clubs, white-collar and fitness-boxing programmes and professional stables across Ontario — built around the amateur, professional and commercial split that defines the business.
- We prepare your T2 with GIFI on Schedule 125 and Schedule 100 so membership dues, day passes, private coaching, gate receipts and gear sales each land on their own line instead of reaching CRA as one undifferentiated sales figure.
- Your ring, platform, bag racks, heavy bags and conditioning equipment go in CCA Class 8 at 20 percent on Schedule 8, a pool most clubs under-claim because the fit-out and the fighting equipment arrived on the same invoice.
- Sprung sub-floor, mirrors, change rooms and the shell work that turns a warehouse unit into a boxing gym are Class 13 leasehold improvements over the lease term; on one club we reclassified a $74,000 build-out out of expenses.
- Front-desk terminals, the round timer and your office computers belong in Class 50, which writes off faster than the equipment pool, so hardware you replace every few years is not stranded in a slow-moving Class 8 balance.
- We file within six months of your fiscal year-end and settle any balance within three months, holding roughly 11.2 percent (from July 1, 2026) combined Ontario tax on the first $500,000 of active income rather than losing margin to arrears interest.
- We give the commercial floor and the competitive programme separate departments inside one ledger, so membership income, coaching income, purse-related payments and fight-night activity stop arriving as a single monthly deposit nobody can take apart later.
- Day-pass books, class packs and prepaid coaching blocks are unearned until the sessions are used, and we release them on redemption, applying ITA 12(1)(a) with the reserve in ITA 20(1)(m) for what you have not yet delivered.
- Each fight night gets its own department and its own date: gate receipts, programme and sponsorship money in, sanctioning, venue hire, medical cover and officials out, so the card’s real margin is visible instead of smeared across the month.
- Cash taken at the door for open-gym sessions and sparring nights is logged daily and tied to the deposit, because an unsupported cash line is the first thing an auditor pulls on a walk-in business.
- Departmental reporting shows what each room actually contributes; one club discovered its Saturday amateur programme was absorbing $18,000 a year in coach hours, contact-sport insurance and travel that the membership side had been quietly funding.
- We run head coach, assistant coach and front-desk payroll with income tax, CPP and EI remitted on the PD7A schedule CRA assigns you, so a missed remittance never grows into a penalty reaching 10 percent; one club saved roughly $4,200.
- Coaches sit right on the employee-versus-contractor line, and we weigh control over training times, who supplies the equipment, how integrated the coach is with your programme and who carries the financial risk before you choose a treatment.
- WSIB coverage begins with your first hire, and we register the club, settle the rate group and reconcile premiums to actual coaching wages; Ontario employer health tax then applies once annual payroll passes the $1,000,000 exemption.
- Free unlimited training given to a coach or their family is a taxable benefit that belongs on the T4, and the slips and T4 Summary due the last day of February must agree with your PD7A remittances.
- Purses, corner fees and management percentages are not membership revenue and are not wages; where your gym or a promoter pays them they are commonly reported on a T4A, and the file has to show who, when and for what.
- At a for-profit boxing gym, memberships, class packs, day passes, private coaching and glove and wrap sales are all taxable at 13 percent in Ontario. There is no exempt line to hide behind.
- The exemption people ask about is narrow: only public-sector or non-profit recreational instruction can be exempt, and a for-profit boxing gym is not one of those, so we settle your structure before a single class is coded exempt.
- Registration is required once taxable revenue passes $30,000 over four consecutive calendar quarters, and memberships plus day passes plus coaching plus gear cross that line sooner than most owners expect, so we watch the quarter you actually cross it.
- Input tax credits are real cash back: the 13 percent on rent, ring and bag purchases, gear bought for resale, utilities, cleaning and marketing all reduce what you remit, and one club recovered $10,400 of missed credits.
- Where a year of dues is paid upfront, the tax is remitted when the amount becomes payable rather than when the training happens, so we reconcile every HST return to your deferred revenue schedule and to the T2 before filing.
- The first planning question is not salary or dividends, it is which business you are running: a for-profit corporation you own and can sell, an amateur club under ITA 149(1)(l), or both under one roof.
- An organization operated exclusively for non-profit purposes cannot make income payable to, or otherwise available for the personal benefit of, any member or proprietor, which rules out dividends, the small business deduction and the capital gains exemption.
- Where you run both, we keep them genuinely separate — separate bank accounts, separate books, a written basis for shared rent and coach time — because a club that quietly funds an owner’s commercial side is what CRA looks at hardest.
- On the for-profit side we set the salary and dividend mix against what you actually draw, since roughly 11.2 percent on the first $500,000 of active income only helps if surplus stays in the company instead of passing through at 53.53 percent.
- We time ring replacement, bag and rack purchases and the next stage of the build-out against projected income, and we review the contact-sport and sparring liability cover you carry; one club moved roughly $9,600 of tax across two fiscal years.
- Overdue T2 returns are filed in sequence, oldest first, because each year’s closing deferred dues, retained earnings and capital cost allowance pools become the next year’s opening balances, and a catch-up filed out of order never reconciles.
- Missing HST returns are rebuilt from the same membership, day-pass, coaching and gear records, so the revenue on your corporate return and the revenue on your HST filings agree for every period we put in.
- Incorporation does not remove the T2 obligation from a non-profit club, and the T1044 information return is its own separate filing, triggered by passive income above $10,000, total assets over $200,000 at the previous period end, or a prior-year T1044 requirement.
- Purse, corner and management payments made during the unfiled years are traced and reported on the slips they belonged on, because a catch-up that files the T2 and leaves those amounts undocumented just defers the problem.
- Where penalties and interest came from a genuine error rather than a decision, we apply for taxpayer relief on Form RC4288; one club had arrears reduced by roughly $6,800 and left with a fixed close calendar.
- The first thing an auditor tests on a boxing gym is whether money collected at the counter matches money reported, so we produce the daily door log, the processor settlements and the deposit trail rather than an estimate.
- Where the club and the commercial gym share a landlord, a coach and a bank account, we set out the allocation basis in writing with supporting records, because an unexplained transfer between the two turns a review into an assessment.
- Purse and corner payments draw questions because they leave the business as money paid to individuals, and we answer with the fight-night file: who was paid, for what, on what date and against which slip.
- Coach classification reviews are common, and we present the working arrangement as it really operates against CRA’s control, tools, integration and financial-risk factors instead of leaning on a contract that simply calls someone self-employed.
- If a reassessment lands and it is wrong, we object within the deadline and take the file forward; where the penalties trace back to a bookkeeping mistake we ask for relief, and one Ontario club had roughly $5,900 cancelled.
- We prepare compiled statements that show a boxing gym as it is: earned membership and coaching revenue on the income statement, and the unused balance of packs, day-pass books and prepaid blocks sitting as a liability.
- A landlord signing a ten-year industrial lease and a lender financing a ring, a rack of bags and a build-out both want statements prepared by a CPA firm, and a compilation is usually the level they accept.
- Fight-night activity is presented as its own line rather than buried in sales, so a reader can see how much of the year’s revenue came from events that may not repeat on the same scale.
- Gloves, wraps and apparel held for resale are valued at the lower of cost and net realizable value, so slow stock is written down rather than carried at full cost on a balance sheet a lender reads closely.
- The statements tie directly to the T2 and GIFI schedules we file, so a club showing $420,000 of revenue with $70,000 of unused packs is understood the same way by your bank and by CRA.
- The structure decision comes first. A for-profit corporation can pay you dividends and be sold; an organization operated exclusively for non-profit purposes can do neither, and switching later is not a filing you can simply make.
- Incorporation itself covers the NUANS name search, the articles, the minute book and a share structure planned around who might hold shares later — a spouse, a training partner or an eventual purchaser of the business.
- Moving an existing unincorporated gym across is done on a section 85 rollover filed on Form T2057, so your ring, bags, member list and goodwill transfer without a capital gain arising on the way in.
- The break-even comes before the paperwork. If the gym nets $145,000 and you draw $75,000, the $70,000 left behind is what a corporation lets you hold near 11.2 percent rather than a personal rate reaching 53.53 percent.
- A qualifying for-profit gym’s shares can attract the $1.275M Lifetime Capital Gains Exemption under ITA 110.6 on a sale, so we keep the share register and the balance sheet in shape years before a buyer appears.
- We rebuild months or years of missing books from what already exists: your membership software exports, card-processor settlements, bank and credit-card statements, the door sheets in the desk drawer and the fight-night paperwork in a folder.
- Rebuilding totals is not the job. The unused pack and day-pass balances have to be reconstructed period by period, because a catch-up that treats every cleared deposit as revenue produces a T2 that is wrong in both directions.
- Door cash for open-gym and sparring nights is rebuilt from the daily sheets and matched to deposits, so the cash line in the restated books is supported rather than plugged, which is exactly what an auditor opens with.
- The cleanup often funds itself. One club had never claimed input tax credits on rent, equipment or resale gear, and amending three rebuilt years put $13,700 back into the corporation.
- You get back a working file, not a box: a chart of accounts built for a boxing gym, departments for memberships, coaching, events and retail, and a monthly close either you or we can run.
- Ontario gym owners pick up US filing obligations more often than they expect: a US entity formed for a promotion, a cross-border training camp, a licensing arrangement or an online coaching brand sold to American subscribers.
- We prepare Form 1120 or 1120-F and the Form 5472 a foreign-owned US corporation must file, on time, because the penalty for a missing information return is assessed per form regardless of how small the entity is.
- The classification mismatch is the real risk: an entity that is transparent for American purposes may be treated as a corporation here, and owners usually discover this after the structure is already in place.
- Where US tax has genuinely been paid on camp, promotion or licensing income, we claim the foreign tax credit on the Canadian T2 so the same dollars are not taxed twice on both sides of the border.
- A gym here ran American training camps through a dormant Delaware LLC and had never filed for it; we brought those returns current, aligned them with the Canadian T2 and closed roughly $7,500 of exposure.
- The Voluntary Disclosures Program is for gyms that fell behind and want it fixed before CRA calls: door cash never reported, HST charged on memberships but never remitted, or T2 years that were simply never filed.
- Three conditions decide whether a disclosure is accepted: CRA must not have contacted you about the matter, the submission must be complete rather than partial, and the information must be at least one year past due.
- The accounting is done before the application, not after: the missing years are rebuilt, unused pack balances restated and purse and corner payments documented, so the disclosure is complete on the day it goes in.
- The submission goes in on Form RC199 with schedules and a plain account of what went wrong and when, because a disclosure that reads as vague is the one CRA returns asking for more.
- One club disclosed four years of HST collected on memberships and day passes but never remitted; the tax was still payable, roughly $14,800 of penalties was cancelled, and the file closed without an audit.
Boxing Gym Tax & Revenue Split Check
Six quick questions on your structure, your deferred packs, HST, purse and corner reporting, fight-night accounting and whether it is time to incorporate. No fee shown.
1. Do you know whether your operation is a for-profit corporation, a non-profit club, or both under one roof?
2. Are class packs and day-pass books carried as deferred revenue until the sessions are actually used?
3. Are you charging 13% HST on memberships, day passes, private coaching and gear sales?
4. Are purses, corner fees and management percentages reported on slips where your gym pays them?
5. Does each fight card have its own department for gate, sponsorship, sanctioning and venue costs?
6. Is your boxing gym incorporated?
Free CPA Consultation for Boxing Gyms
Case Studies: Boxing Gym Accounting & Tax
Scarborough Boxing Club and Gym — Two Businesses, One Bank Account
The problem: A Scarborough operator ran a registered amateur programme and a commercial fitness-boxing floor out of the same unit, the same bank account and one accounting file. Amateur dues, memberships, day passes, private coaching fees and the occasional purse payment all posted to a single revenue account. The commercial side looked barely profitable, the club looked as though it was funding an owner draw, and no defensible HST position existed for either.
What we did: We split the operation into two ledgers with their own bank accounts, wrote an allocation basis for shared rent, utilities and coach hours, restated three years, confirmed that memberships, day passes and coaching on the for-profit side carry 13% HST, and tested the club against the non-profit requirements before anything else was filed.
The result:
- Three years restated into two clean, separate sets of books
- $7,900 of input tax credits recovered on the commercial side
- Club funds no longer flowing to the owner’s for-profit gym
Hamilton Boxing Gym — Purse and Corner Payments Brought Current
The problem: A Hamilton gym had paid fighter purses and corner fees on fight weekends for four years, partly in cash from the till and partly by transfer, and coded all of it to a single event expense line. No slips were ever issued, no record showed who had received what, and the amounts sat in the accounts as an unsupported deduction the owner could not explain to anybody who asked.
What we did: We rebuilt the payment history from bank records, transfer logs and the surviving event paperwork, identified each recipient, amount and date against the card it belonged to, separated purse and corner money from both wages and membership revenue, prepared and filed the outstanding slips for four years, and put a ringside payment sheet in place so that every future card now documents itself on the night.
The result:
- Four years of purse and corner payments identified and reported
- $21,000 moved off an unsupported expense line onto proper slips
- Relief request filed; roughly $5,400 of penalties cancelled
Windsor Boxing Gym — Fight-Card Accounting Built From Scratch
The problem: A Windsor gym promoted three club shows a year. Ticket money, gate takings, sponsorship cheques, sanctioning costs, venue hire, medical cover, officials and purses were posted to whichever account was nearest, in whichever month the money happened to move. The owner could not say whether a single card had made money, and sponsorship was being invoiced with no HST charged on it at all.
What we did: We built a department for each event, dated to the card itself, with gate, ticket and sponsorship revenue in and sanctioning, venue, medical and officials costs out. Ticket sales are now held as deferred revenue until the night is fought, sponsorship is invoiced as a taxable supply at 13% HST, and purse and corner payments are captured on a ringside sheet.
The result:
- Every card now closes with its own reportable margin
- Sponsorship invoiced correctly as a taxable supply
- Ticket money deferred until the night is actually fought
Our clear, efficient process ensures every step is transparent, building trust and long-term client relationships.
Kickoff (Document Request)
Prior T2 returns, incorporation or club documents, membership and pack reports, coaching agreements, fight-card paperwork, insurance policies, payroll and WSIB records, and bank statements.
First 30 Days (Structure and Setup)
Settle the for-profit and non-profit question, set up the ledger with departments for the floor, the amateur programme, coaching and events, and configure payroll, WSIB and capital cost allowance pools.
Monthly Close
Reconciliations, door-cash tie-out, pack and day-pass redemption entries, 13% HST on the commercial floor, and slips prepared for purse, corner and management payments.
Quarterly Planning Review
Salary and dividend mix, structure check, fight-card results by event, equipment and build-out purchase timing, insurance review and the incorporation break-even.
Year-End Close and T2 Filing
Trial balance, statements carrying unused packs as a liability, T2 with GIFI, T1044 where an incorporated club meets the tests, and CRA preparation.
Get Your Boxing Gym Taxes Done Right Today
Affordable Pricing for Boxing Gyms
We believe in clear, upfront pricing so you know exactly what to expect. All fees include HST.
- Tax Preparation (Corporation) — From $400
- Tax Return Filing (Corporation) — From $400
- Tax Compliance Audit — FREE CRA audit support for our clients
- Tax Strategy — FREE for our clients
- Accounting Base Plan — From $100 per month
- Bookkeeping Management — Free for our Accounting clients
- Financial Reporting — Free for our Accounting clients
- Business Formation — Flat $35
- Incorporation Process — Flat $35
- Entity Setup Assistance — Flat $35
- Full-Service Payroll — From $125 per month
Payment is by Interac e-Transfer to info@gondaliyacpa.ca only. Security question: Not Applicable, as auto-deposit is enabled.
Read our Pricing Transparency Promise — full and final flat fees, HST included, shown in 2 minutes.
Meet Your Lead Boxing Gym Accountant
Meet your lead boxing gym accountant. The same two people handle your structure, your books and your corporate return every year.


What Our Clients Say
1450+ five-star reviews from boxing gym, club and fitness-business owners across Ontario and Canada.
Serving Boxing Gyms Across Ontario
Our CPA team works with commercial boxing gyms, registered amateur clubs and professional stables throughout Ontario. We know how membership dues, day passes, coaching fees, purse money and fight-night takings actually move through a club, which of those streams CRA questions first, and how to keep the amateur and for-profit sides of one operation properly apart.
Toronto (ON)
55 Queen St E Ste 1205, Toronto, ON M5C 1R6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Mississauga (ON)
2100 Camilla Rd #716, Mississauga, ON L5A 2J8
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Brampton (ON)
4 Starhill Crescent, Brampton, ON L6R 2P9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Scarborough (ON)
24 Clementine Square, Scarborough, ON M1G 2V7, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Vaughan (ON)
19 Cabinet Crescent, Woodbridge, ON L4L 6H9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Oshawa (ON)
210 Durham St, Oshawa, ON L1J 5R3, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Ottawa (ON)
2090 Neepawa Ave a314, Ottawa, ON K2A 3L6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Etobicoke (ON)
60 Stevenson Rd #1601, Etobicoke, ON M9V 2B4, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Hamilton (ON)
70 Starling Dr, Hamilton, ON L9A 0C5, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Guelph (ON)
1155 Gordon St, Guelph, ON N1L 1S8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Windsor (ON)
4387 Guppy Ct, Windsor, ON N9G 2N8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
North York (ON)
150 Graydon Hall Dr #912, North York, ON M3A 3B2, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Boxing Gym Accounting & Tax FAQs
Related Industries We Serve
Martial Arts Schools
- For-profit corporation and non-profit club structures
- Dues, contracts and unearned revenue timing
- Payroll, HST and CRA representation
Gyms
- Membership and class-pass revenue recognition
- Equipment and build-out capital cost allowance
- T2 filing, HST and staff payroll
Personal Trainers & Fitness Businesses
- Tax planning for coaches and instructors
- Employee-versus-contractor and HST support
- Bookkeeping and incorporation advice
Incorporated Businesses
- T2 corporate tax filing and planning
- Salary-versus-dividend and SBD strategy
- Financial statements and CRA compliance
Boxing Gym Accounting & Tax Done Right.
The amateur, professional and commercial split settled properly. T2 filing and GIFI, 13% HST on the commercial floor, deferred packs and day passes, purse and corner payments on the right slips, fight-night departments, coaching payroll with WSIB and the incorporation decision, all under one roof. AFFORDABLE flat fees, no hourly billing. Registered CPA Ontario. 1450+ five-star reviews. 30-Day Money-Back Guarantee.