



Currency Exchange Business Year-End Tax Checklist in Canada
Currency exchange business tax checklist Canada: year-end tax filing, bookkeeping, and CRA compliance tips by Gondaliya CPA
Managing your currency exchange business tax checklist Canada requires careful attention to year-end tax filing, accurate bookkeeping, and strict CRA compliance. Gondaliya CPA helps ensure proper income reporting, transaction records maintenance, and GST/HST filings to keep your foreign exchange operations aligned with the Income Tax Act and Excise Tax Act.
Quick Answer
Separate revenue from volume. Count cash by each currency. Revalue foreign balances at the closing rate. Treat gains as income, not capital. Record client funds as a liability. Reconcile everything before the books close.
Reading time: 52 minutes.
Table of Contents
- The Three Numbers, and the Form That Does Not Exist
- Steps 1 to 4: Revenue, Cash, Revaluation and Character
- Functional Currency and Its Impact on Tax Reporting
- Reporting Foreign Currency Transactions to the CRA
- Tax Implications, GST/HST and Payroll
- Record-Keeping, Costs and Foreign Holdings
- Frequently Asked Questions
- Steps 5 to 14 and Key Points
- Businesses We Serve
- Professional Guidance and Quick Reference
The Numbers That Matter
This article covers Canada, with Ontario and Toronto context, and reflects rules current to 2026. It is written for incorporated Canadian currency exchange businesses, money services businesses and multi-branch bureaus. Figures marked illustrative are examples, not quotes, and any masked engagement notes end with “Figures changed for privacy.” This is educational information only and not tax or legal advice. Provincial rules differ, so please confirm the position where you operate.
The Three Numbers, and the Form That Does Not Exist
The Three Numbers, and the Form That Does Not Exist
The Corrections
What This Trade Reports Differently
| Number | What It Is Not | What It Is |
|---|---|---|
| Revenue | The volume exchanged | The spread and fees you earned |
| Cash on hand | A fixed historical figure | Revalued at the closing rate, on income account |
| Client funds | Revenue when received | A liability until settled |
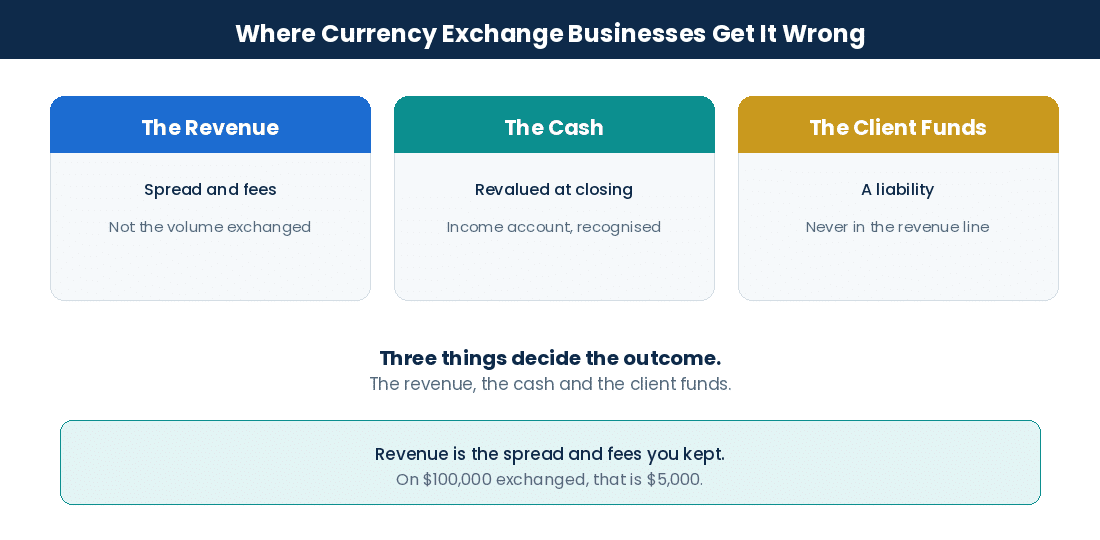
Get these three right and the rest of the year-end is ordinary bookkeeping. Get the first one wrong and your reported revenue is out by a factor of twenty.
The Functional Currency Election, Corrected
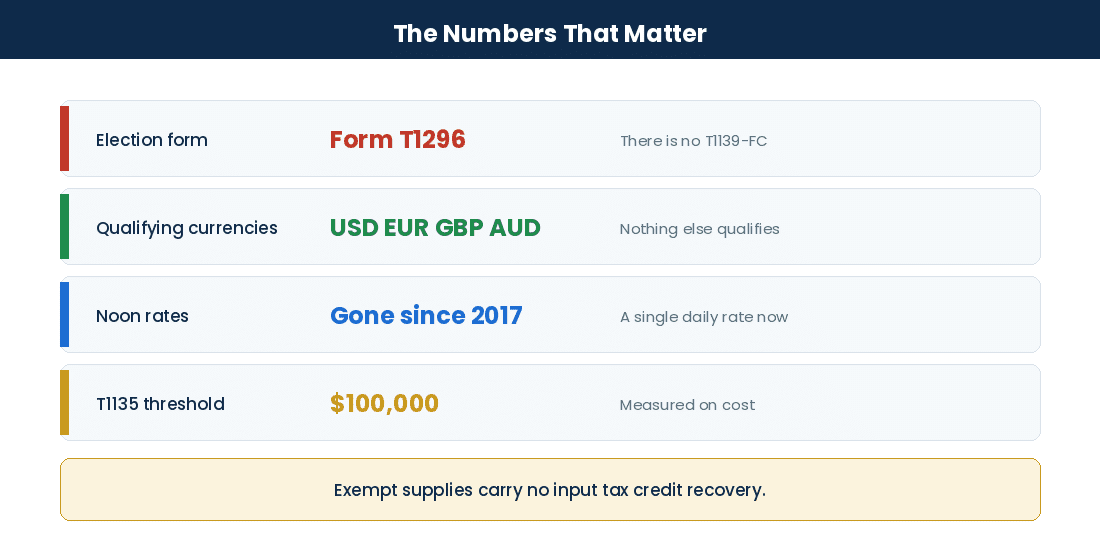
Guidance on this topic names Form T1139-FC as the functional currency election. There is no such form. The election is made on Form T1296.
| Point | What Circulates | The Rule |
|---|---|---|
| The form | T1139-FC | T1296 |
| Frequency | Filed every tax year | Filed once, and it continues until revoked |
| Deadline | With the T2 | On or before the first day of the first year it applies to |
| Which currencies | Any currency you mostly trade in | A qualifying currency: USD, EUR, GBP or AUD |
| How the T2 is filed | Converted to CAD on Schedule 100 | Filed in the functional currency |
The last two rows matter most. A bureau dealing mainly in, say, Indian rupees or Philippine pesos cannot elect that currency, however much of its volume it represents. And the point of the election is that you report in the functional currency, so describing it as converting everything to CAD on Schedule 100 describes the opposite of what the election does.
The deadline is unforgiving. It falls on or before the first day of the year, which means the decision is made before the year starts rather than when the return is prepared.
One More Correction Worth Front-Loading
The Bank of Canada discontinued noon rates in 2017. It now publishes a single daily exchange rate each business day, in the afternoon. Guidance referring to “Bank of Canada noon rates published quarterly by CRA” is describing a rate series that no longer exists and a publication frequency that never did.
The functional currency election is the one that cannot be fixed later. Miss the first day of the year and you wait a full year to elect. Figures changed for privacy.
Risk Warning: Please confirm your main trading currency is USD, EUR, GBP or AUD before planning around a functional currency election. Nothing else qualifies.
Currency Exchange Business Tax Checklist for Year-End Filing in Canada
Steps 1 to 4: Revenue, Cash, Revaluation and Character
The Checklist
Key Numbers at a Glance
| Task | Deadline | Consequence of Skipping |
|---|---|---|
| Revenue separation | Before fiscal year-end | Income materially misstated |
| Cash count | Fiscal year-end | Financial statements will be wrong |
| Balance revaluation | Fiscal year-end | Assets valued incorrectly |
| Gain characterization | When filing T2 | Reassessment risk on the return |
| Client funds separation | Fiscal year-end | Liabilities reported as revenue |
Who This Is For / Not For
- For: Incorporated currency exchange shops, money services businesses and multi-branch bureaus.
- Not For: Unincorporated or individual operators, whose home premises, vehicle and instalment treatment differ.
One thing that applies to every reader regardless of structure: a business dealing in foreign exchange in Canada is generally a money services business and must be registered with FINTRAC, with its own record-keeping and reporting obligations. Those are separate from anything in this article and are not satisfied by filing your taxes correctly.
When Does a Currency Exchange Year-End Start?
Your fiscal year-end is the one chosen when the corporation filed its first return. It is often December 31 but need not be. Two dates follow from it and they are not the same date.
| Obligation | Deadline |
|---|---|
| T2 corporate return | Six months after fiscal year end |
| Corporate tax payment | Three months for an eligible CCPC, two for others |
| T4 and T4A slips | Last day of February |
| Record retention | Six years from the end of the taxation year |
The payment row is earlier than the filing row and is the one most businesses miss. Filing on time with the balance unpaid still accrues interest from the payment date.
Step 1: How Do You Separate Revenue From Volume?
Taxable revenue is the spread and fees you earn, not the gross amount exchanged. This is the single most consequential line on the return.
Illustrative example. You exchange $100,000 of foreign currency and earn $5,000 in spread and fees. Revenue is $5,000. Reporting $100,000 overstates revenue twentyfold, and it also distorts every ratio a reviewer looks at.
- Record the gross amounts moved as a statistic, not as revenue
- Capture the spread on each transaction at the posted rate
- Record service fees and commissions separately from spread
- Reconcile the total to the transaction system monthly
Step 2: How Do You Count Cash by Currency at Year-End?
Count tills at every branch and the vault, by currency and by denomination, on count sheets that are signed and dated.
- One sheet per branch, per currency
- Denomination breakdown, not just a total
- Signed by the counter and a second person
- Reconciled to the till float and the system balance
- Any difference investigated and documented before the books close
Pro Tip: Please count immediately before closing the books, not a week either side. A count that does not tie to the year-end date supports nothing.
Step 3: How Do You Revalue Balances at the Closing Rate?
Revalue foreign currency holdings using the Bank of Canada’s published closing rate for the year-end date, and keep the source for each rate used.
Illustrative example. Holding €10,000 at a rate of 1.45 CAD per euro, the carrying value is $14,500 CAD.
Save a copy of the rate table with the working papers. A revaluation without its rate source is an assertion rather than a calculation.
Step 4: Are Your Gains on Income or Capital Account?
For a dealer, foreign currency is the stock in trade. Gains and losses fall on income account under section 9, taxed as ordinary business income.
| Situation | Account |
|---|---|
| Spread earned on a customer exchange | Income |
| Revaluation of trading currency at year end | Income |
| Converting held currency back at a better rate | Income |
| Loss on counterfeit notes or shortage | Income, if documented |
A correction on unrealized amounts. Guidance on this topic states both that year-end revaluation produces unrealized gains and that unrealized changes do not affect tax until realized. Those two statements contradict each other. For a dealer holding currency as trading property, the year-end revaluation is recognised on income account. The “not until realized” idea belongs to capital-account holdings, which is not what a bureau’s till float is.
Document the basis on which each gain was characterized and keep it with the T2 working papers.
Reporting volume as revenue is the error we see most on a first engagement, and it is usually years deep by the time anyone notices. Figures changed for privacy.
Key Stat: On $100,000 exchanged at a $5,000 spread, revenue is $5,000. The other $95,000 never belonged to you.
Understanding Functional Currency and Its Impact on Tax Reporting
Functional Currency and Its Impact on Tax Reporting
The Election
Definition and Eligibility Criteria for Functional Currency Reporting
Functional currency reporting lets a corporation compute and report its Canadian tax results in a currency other than the Canadian dollar. The rules sit in section 261 of the Income Tax Act.
| Condition | Requirement |
|---|---|
| Residency | The corporation must be resident in Canada throughout the year |
| Currency | A qualifying currency only: USD, EUR, GBP or AUD |
| Primary use | The currency must be the primary currency in which the corporation maintains its records for financial reporting |
| Excluded entities | Investment corporations, mortgage investment corporations and mutual fund corporations cannot elect |
| Timing | Election on or before the first day of the first taxation year it applies to |
Illustrative example. An Ontario bureau with several branches transacts mostly in US dollars and keeps its records in USD. It can elect USD as its functional currency. A bureau whose volume is mainly in a non-qualifying currency cannot elect that currency at all, no matter how dominant it is in the business.
Keep evidence supporting the primary-use test with the election. The test looks at the records the corporation actually maintains, not at transaction volume alone.
Filing Elections for Functional Currency Use in Corporate Returns
The election is filed on Form T1296, once, on or before the first day of the first taxation year it is to apply to. It is not filed annually and it is not filed with the T2.
- Once elected, it continues until revoked
- Revocation has its own timing rule and cannot be done casually mid-stream
- The T2 and its schedules are then prepared in the functional currency
- Amounts payable to the Receiver General are still paid in Canadian dollars
- Transitional rules apply in the first year, converting opening balances
The last two points are where the practical work sits. Reporting happens in the functional currency; paying happens in Canadian dollars. Those are different operations and mixing them up produces instalment amounts that do not match the liability.
Instalment Payments and Balance-Due Procedures When Using a Functional Currency
Instalments and the final balance are remitted in Canadian dollars, converted at the relevant rate. Corporate instalments follow the corporation’s own fiscal year rather than fixed calendar dates.
| Item | Position |
|---|---|
| Instalment frequency | Monthly by default; quarterly only where the corporation qualifies |
| Instalment currency | Canadian dollars |
| Balance due | Three months for an eligible CCPC, two for others |
| Interest on shortfalls | Compounds daily until paid |
Please note that instalment requirements are in section 157 and interest in section 161. Guidance citing section 161 as the source of the payment deadline is naming the interest provision rather than the payment rule.
Illustrative example. An Etobicoke online foreign exchange firm keeps its ledgers in GBP under a valid election. It computes its tax in GBP and converts the instalment amounts to Canadian dollars at the appropriate rate before each due date. Figures changed for privacy.
Software such as QuickBooks or Xero can carry multi-currency ledgers, which helps keep the functional currency records and the CAD remittances reconciled. Our bookkeeping and accounting services set this up so the two do not drift apart through the year.
When Not to Elect
- Where the business genuinely operates in Canadian dollars and merely trades foreign currency
- Where volume is spread across many currencies with no single dominant one
- Where the dominant currency is not one of the four qualifying currencies
- Where the transitional work in year one outweighs the ongoing simplification
Most single-location bureaus fall into the first category. Trading in a currency is not the same as operating in it, and the election is about the second.
Bureaus ask about the functional currency election far more often than they qualify for it. Trading in a currency is not operating in it. Figures changed for privacy.
Risk Warning: The election is due on or before the first day of the year it applies to. It cannot be made retroactively when the return is prepared.
Reporting Foreign Currency Transactions and Income to the CRA
Reporting Foreign Currency Transactions to the CRA
Conversion
Absent a functional currency election, every foreign amount is converted to Canadian dollars before it reaches the return. Income, expenses, gains and losses all follow the same discipline.
Converting Foreign Income and Expenses to Canadian Dollars
- Fee and commission income
- Spread earned on exchanges
- Bank charges and correspondent account fees
- Security and transport costs incurred abroad
- Realized and unrealized foreign exchange gains and losses
Use the rate in effect on the transaction date where the transaction is identifiable. An average rate over a period is acceptable where the amounts are frequent and the average is reasonable, provided the approach is applied consistently.
Illustrative examples. A USD fee paid on 15 March converts at that day’s rate. Rent paid in euros each month, where the payment date varies, can use the month’s average rate if that method is used every month.
Methods for Applying Exchange Rates
| Method | When It Fits |
|---|---|
| Spot rate on the transaction date | Identifiable, material transactions |
| Average rate over a period | Frequent small amounts, where the average is representative |
| Specific identification | Where a contractual rate was actually used |
| A consistent alternative source | Where an official rate is unavailable, documented and applied throughout |
Illustrative example. You receive €10,000 on 5 June. At that day’s rate of 1.45, you report $14,500. You do not apply a quarterly average that shifts the amount into a different pattern than the receipt.
Sources for Reliable Exchange Rates
The Bank of Canada publishes a single exchange rate for each business day. Please note it discontinued noon rates in 2017, so any process still referring to a noon rate is referring to something that is no longer published.
- Bank of Canada daily rates, which are the default and the most defensible
- A major bank’s published rate, where documented and used consistently
- Your own confirmed wire transfer rate, for reconciling a specific settlement
Save the rate tables with the working papers each period. Screenshots are acceptable; recollection is not.
Consistency Requirements in Exchange Rate Usage Across Tax Filings
Pick a method, write it down, and apply it. Switching between spot and average without reason produces revenue and expense that do not match in timing, and it is visible in the numbers.
- Document the source, the timing and the rounding convention
- Apply the same approach to each class of transaction each year
- If the method changes, record why and when
- Retain the supporting rate data for six years from the end of the taxation year
Please note that section 230 is the books and records provision. It is what requires you to keep the rate evidence; it is not a rule about which rate to use.
A Note on the Citations in Circulation
Several bulletin and guide references that circulate on this topic point somewhere real but incorrect, so please check before relying on the surrounding advice.
| Cited As | What It Actually Is |
|---|---|
| IT-490R, foreign currency translation | IT-490R deals with barter transactions |
| RC4065, foreign exchange gains and losses | RC4065 is the medical expenses guide |
| Schedule II, currency conversion | Schedule II sets capital cost allowance classes |
| RC4080, capital gains and losses | RC4080 concerns GST/HST for freight carriers |
| IT-110R, foreign currency | IT-110R deals with gifts and official donation receipts |
A wrong citation is worse than none. It survives review because it looks specific, and nobody opens the bulletin to check. Figures changed for privacy.
Risk Warning: Mixing rate methods between periods misstates taxable income and invites reassessment. Please set the method once and document it.
For help handling foreign currency conversion in line with CRA expectations, contact Gondaliya CPA at info@gondaliyacpa.ca or call 647-212-9559.
Tax Implications of Currency Exchange Transactions for Businesses
Tax Implications, GST/HST and Payroll
The Treatment
When Currency Exchange Activities Create Taxable Events
- A customer exchange that generates spread income
- A commission or service fee charged
- Converting held currency back at a better rate than it was acquired
- The year-end revaluation of trading currency
Moving money between currencies for a customer, in itself, is not revenue. What you keep is revenue. The distinction is the whole of Step 1, and it is why client funds must sit outside the revenue accounts entirely.
Treatment of Currency Gains and Losses on Income and Capital Accounts
For an incorporated currency exchange business, foreign currency is inventory rather than investment. Gains and losses are on income account under section 9, not capital.
- Realized gains arise on converting back at a better rate than acquisition
- Revaluation at the year-end closing rate is recognised, because the currency is trading property
- Losses from theft, counterfeits or till shortages are deductible where documented as incurred in the business
- An incident log with dates, amounts and the response is what makes those losses stick
Note that section 39(2), which deals with capital-account foreign exchange and carries a $200 threshold, applies to individuals and is not the provision governing a dealer’s trading results.
GST/HST Considerations for Currency Exchange Businesses
The exchange of currency is a financial service, and financial services are generally exempt. The definition sits in subsection 123(1) of the Excise Tax Act; the exemption itself sits in Schedule V, Part VII. Guidance citing 123(1) as the source of the exemption is naming the definitions provision.
| Supply | Usual Treatment |
|---|---|
| Currency exchange spread and fees | Exempt financial service |
| Money transfer and remittance fees | Generally exempt as a financial service |
| Cheque cashing | Depends on the arrangement; confirm before assuming |
| Retail sales, phone cards, courier services | Taxable |
| Rent of space to a third party | Taxable |
The consequence runs one way and it is expensive. Exempt supplies carry no input tax credit recovery. A bureau whose activity is wholly exempt recovers nothing on rent, security systems, counting machines or professional fees.
Where you have both exempt and taxable supplies, credits must be apportioned on a fair and reasonable basis, applied consistently, and documented. Please note the registration test as well: the $30,000 threshold is measured on taxable supplies, and it applies over four consecutive calendar quarters or in a single calendar quarter. Our GST/HST filing service covers the apportionment and the return.
Payroll and Financial Statement Reporting in Foreign Currency Context
Payroll obligations do not change because the business handles foreign currency. Employment income is reported in Canadian dollars, converted at the rate applying on the payment date, with income tax, CPP and EI withheld and remitted on your assigned schedule.
- A regular remitter pays by the 15th of the following month
- The deadline tightens as average monthly withholding grows
- T4 and T4A slips are due the last day of February
- Withheld amounts are held in trust, with director liability attaching
Financial statements are prepared under ASPE, with a compilation engagement under CSRS 4200 where one is needed for a lender. Disclose the effect of exchange rate movements where material. Please note that “Notice to Reader” is a retired term and “Canadian GAAP” is no longer the applicable framework name.
Small Business Deduction and Multi-Branch Structures
The small business deduction applies to the first $500,000 of active business income of a Canadian-controlled private corporation. Two things grind it, and neither is the level of active income:
- Taxable capital employed in Canada, measured across the associated group
- Passive investment income above a threshold
- Association, which shares one limit across corporations under common control
Operators running branches through separate corporations are usually associated, so the $500,000 is shared rather than multiplied. Our corporate tax planning service reviews the group position annually. Ontario’s small business rate moves to 2.2% from 1 July 2026, giving a combined 11.2% with the 9% federal rate.
The exempt-supply consequence is the one that surprises owners. No tax charged sounds like good news until the credits on a build-out disappear. Figures changed for privacy.
Key Stat: Exempt supplies carry no input tax credit recovery. For a bureau fitting out a branch, that is usually the largest single number at stake.
Record-Keeping and Documentation for Currency Exchange Businesses
Record-Keeping, Costs and Foreign Holdings
The Evidence
Essential Documentation for Transaction Records and Bookkeeping
- Date, currencies, amounts, posted rate, spread and fee for every transaction
- Customer identification where the money services rules require it
- Daily cash counts by currency, with till float reconciliation
- Bank and correspondent account statements and reconciliations
- A separate ledger for money held on behalf of clients
- System reports supporting the totals in the accounts
Illustrative example. A Toronto bureau records each USD to CAD sale at the posted rate, capturing the spread and fee as revenue and the gross as a statistic, then posts to QuickBooks or Xero daily. Figures changed for privacy.
Required Retention Periods for Tax and Financial Records
| Document Type | Minimum Retention |
|---|---|
| Corporate tax returns and working papers | Six years from the end of the taxation year |
| Transaction records and count sheets | Six years from the end of the taxation year |
| Payroll registers and T4/T4A slips | Six years from the end of the taxation year |
| GST/HST returns and apportionment workings | Six years from the end of the taxation year |
| Exchange rate sources | Six years from the end of the taxation year |
Six years runs from the end of the taxation year the records relate to, not from the filing date. On a late-filed year that distinction shortens the period you might have assumed. Electronic storage is fine provided the records stay readable for the whole period; a system migration that strands three years of reports is a retention failure even though the data existed once.
Separately, money services businesses have their own record retention and reporting obligations under the FINTRAC regime. Those run alongside the tax rules rather than instead of them.
Maintaining Accurate Records for Audit Preparedness and CRA Compliance
- File the T2 on time with GIFI schedules that agree to the statements
- Reconcile bank and correspondent accounts monthly, not annually
- Keep client funds in a separate liability account, never in revenue
- Issue T4 and T4A slips before the deadline
- Check reported revenue against the GST/HST returns before filing
- Investigate and document every unexplained difference while it is fresh
Reviews usually start with a mismatch rather than a suspicion. Revenue that does not agree between the T2 and the sales tax returns, or a year-end with no count sheets behind it, are the two that surface most often in this trade.
Tracking Currency Exchange Costs and Their Impact on Tax Returns
| Asset or Cost | Treatment | Rate |
|---|---|---|
| Counting and sorting machines | Class 8 | 20% declining balance |
| Security systems, safes, screens | Class 8 | 20% declining balance |
| Computers and systems software | Class 50 | 55% declining balance |
| Application software | Class 12 | 100% |
| Leasehold improvements | Class 13 | Over the lease term |
| Armoured transport fees | Current expense | Deducted as incurred |
| Insurance, rent, utilities | Current expense | Deducted as incurred |
Two clarifications on the table as it usually circulates. Leasehold improvements are Class 13, written off over the lease term including renewal options within limits, rather than a class that “varies”. And computers are Class 50 at 55%, not Class 8.
On 2026. Bill C-15 received Royal Assent on 26 March 2026, reinstating the accelerated investment incentive for most depreciable property acquired after 2024 and available for use before 2030. Where it applies, an enhanced first-year deduction replaces the ordinary half-year rule. The claim year is set by when an asset becomes available for use, and the claim is a maximum rather than an obligation.
Cross-Border Workers and Foreign Income Earned in USD
Amounts paid to workers abroad, or earned abroad by a Canadian resident, are converted to Canadian dollars and reported. Keep the amounts and the rates used, and apply the same conversion discipline as everywhere else.
Please note that whether a cross-border worker is an employee or a contractor is decided on the facts, not on the currency they are paid in or the country they sit in.
Reporting Foreign Investment Income and Withholding Taxes
Report foreign investment income gross, before withholding, and claim a foreign tax credit for the tax withheld. Keep the withholding evidence, since the credit depends on it.
Foreign investment income also feeds the passive income calculation that can grind the small business deduction, so the two are connected on a corporate return.
Filing Obligations for Specified Foreign Property (Form T1135)
A corporation files Form T1135 where the total cost of specified foreign property exceeded CAD $100,000 at any time in the year. The threshold is measured on cost, not on market value.
- Foreign bank accounts, including correspondent accounts
- Shares of non-resident corporations
- Debt owed by non-residents
- Interests in foreign trusts
The requirement is in section 233.3. The late-filing penalty is $25 per day, minimum $100, to a maximum of $2,500 per year, with higher penalties where the failure is knowing or grossly negligent. Guidance citing subsection 237.3(7) is naming the reportable transactions rules, which is a different regime.
Correspondent accounts are the line that catches bureaus. They are foreign bank accounts, and their cost counts toward the threshold.
Proceeds from Sales of Foreign Real Estate
Where a corporation disposes of foreign real property, the proceeds are converted at the rate on the disposition date and reported on the corporate return. Whether the result is a capital gain or business income depends on the purpose for which the property was held.
Please note that Form T776 does not apply to a corporation. It is the statement of real estate rentals used on a personal return. A corporation reports rental results within its own T2 and GIFI schedules.
Correspondent accounts are the T1135 trigger nobody expects. The threshold is cost, and the balance sits offshore all year. Figures changed for privacy.
Risk Warning: Please check your correspondent account balances against the $100,000 cost threshold before assuming no T1135 is due.
Frequently Asked Questions on Currency Exchange Business Tax in Canada
Frequently Asked Questions
FAQ
What is the T2 corporate tax filing deadline for currency exchange businesses?+
Six months after your fiscal year end. Payment is due earlier, at three months for an eligible CCPC and two months for others, and interest runs from the payment date.
How long must I keep my currency exchange business records?+
Six years from the end of the taxation year the records relate to, measured from the year end rather than the filing date.
Which Capital Cost Allowance classes apply to currency exchange assets?+
Counting machines and security systems sit in Class 8 at 20%. Computers and systems software are Class 50 at 55%, application software is Class 12, and leasehold improvements are Class 13 over the lease term.
When are GST/HST remittance payments due for currency exchange businesses?+
Monthly and quarterly filers file one month after the period end; annual filers generally have three months. Most currency exchange revenue is exempt, so the question is usually about your taxable side.
What is the deadline for filing payroll slips?+
T4 and T4A slips are due by the last day of February for the preceding calendar year.
What is the shareholder loan repayment window?+
One year after the end of the corporation’s taxation year in which the loan was made. A series of loans and repayments can defeat the exception, and where the amount is included it falls in the year the loan was made.
What penalties apply for late T2 filing?+
5% of the unpaid tax plus 1% for each complete month, to a maximum of twelve. A higher rate applies where there is a demand and a recent history. Interest compounds daily.
Where should I source foreign currency revaluation rates?+
The Bank of Canada daily rate for the year-end date. Note that noon rates were discontinued in 2017, so a single daily rate is what is published now.
Is my revenue the amount exchanged or the spread?+
The spread and fees. On $100,000 exchanged at a $5,000 spread, revenue is $5,000. The gross is a volume statistic, not income.
Are my currency gains income or capital?+
Income, for a dealer. Foreign currency is your stock in trade, so gains and losses fall under section 9 as ordinary business income.
Is the year-end revaluation taxable before I convert?+
For a dealer holding currency as trading property, yes. The revaluation is recognised on income account. The wait-until-realized idea belongs to capital-account holdings.
Which form is the functional currency election?+
Form T1296, filed once on or before the first day of the first taxation year it applies to. There is no Form T1139-FC.
Can I elect any currency as my functional currency?+
No. Only a qualifying currency: US dollars, euros, British pounds or Australian dollars.
Do I charge GST/HST on exchange spreads?+
Generally no. The exchange of currency is a financial service and financial services are generally exempt. The consequence is that you recover no input tax credits on the related costs.
How do I treat money held for customers?+
As a liability, in its own account, never as revenue. It is not your money and it does not belong in the revenue line at any point.
Do I need to file a T1135?+
If the total cost of your specified foreign property exceeded CAD $100,000 at any time in the year, yes. Correspondent accounts held abroad count toward that threshold.
Sixteen questions, and the first one about revenue accounts for more corrected tax than the other fifteen combined. Figures changed for privacy.
Businesses We Serve
Businesses We Serve
Industries
Money services and cash-handling businesses share the same year-end issues. Here are ten and the usual finding.
| Business | The Issue That Usually Appears |
|---|---|
| Currency exchange bureaus | Volume reported as revenue instead of spread |
| Multi-branch exchange chains | No branch-level count sheets at the year end |
| Money transfer and remittance agents | Client funds sitting in the revenue accounts |
| Online foreign exchange platforms | Rate method switching between periods |
| Cheque cashing operators | Exempt and taxable supplies never separated |
| Businesses holding correspondent accounts | T1135 threshold crossed without a filing |
| Bureaus inside retail locations | Shared costs with no apportionment basis |
| Importers and exporters | Foreign exchange gains buried in cost of goods |
| Owner-managed corporations | Shareholder loan balances left past the window |
| Anyone buying equipment | Post-2024 purchases on the plain half-year rule |
- Currency exchange bureaus: Report what you kept.
- Multi-branch exchange chains: One signed sheet per branch.
- Money transfer and remittance agents: A liability, not income.
- Online foreign exchange platforms: Set the method once.
- Cheque cashing operators: Separate the two streams.
- Businesses holding correspondent accounts: Measure cost, not balance.
- Bureaus inside retail locations: Document the apportionment.
- Importers and exporters: Give foreign exchange its own line.
- Owner-managed corporations: Clear it inside the window.
- Anyone buying equipment: Check the 2026 incentive.
The business changes. The first question does not: is the revenue line the spread, or is it the volume. Figures changed for privacy.
Steps 5 to 14 and Key Points
Steps 5 to 14 and Key Points
Quick Reference
Step 5: How do you reconcile bank and correspondent accounts?
Match statements to ledger entries monthly, including every correspondent account. Investigate differences while they are fresh, since a stale reconciling item is rarely explained a year later.
Step 6: How do you treat funds held for customers?
As a liability in a separate account, never as income. Keep client money out of the operating float so the two balances can each be proved independently.
Step 7: How do you reconcile the transaction system to the books?
Compare system totals to the ledger every month, by currency. Volume, spread and fee should each tie, not just the net.
Step 8: How do you handle shortages, theft, or counterfeits?
Log the incident with date, amount, branch and response. Documented losses are deductible as incurred in the business; undocumented ones are a hole in the count.
Step 9: How do you sort GST/HST for the year?
Separate exempt financial services from taxable supplies, apportion input tax credits on a fair and reasonable basis, and keep the workings that support the split.
Step 10: How do you finalise payroll and slips?
Confirm wages, benefits and deductions, reconcile withheld amounts to what was remitted, and issue T4 and T4A slips by the last day of February.
Step 11: Which operating expenses need a final review?
Armoured transport, rent, utilities, insurance, security monitoring and licensing. Check each for amounts that belong in a different period or a capital class.
Step 12: How do you update the capital asset register?
Record additions, disposals and the date each asset became available for use. That date sets the claim year, not the invoice date.
Step 13: How do you clear shareholder and personal items?
Code personal spending to the shareholder loan account as it happens, and deal with any loan balance inside the one-year window after the year in which it was made.
Step 14: What financial statements get prepared at year-end, and what gets filed?
A balance sheet, income statement and supporting schedules under ASPE, with a CSRS 4200 compilation where a third party needs one. The T2 is filed within six months of the year end, with payment earlier.
Key Points on Currency Exchange Business Tax Compliance
- Late filings attract penalties that compound; file on time even when the balance cannot be paid in full.
- Use Bank of Canada daily rates consistently and keep the source with the working papers.
- Treat customer funds strictly as liabilities, in their own account.
- Reconcile transactions and correspondent accounts monthly rather than at year end.
- Document theft, shortage and counterfeit incidents immediately.
- Apportion input tax credits only across the taxable portion of your activity.
- Issue payroll slips by the last day of February.
- Keep the capital asset register current, with availability-for-use dates.
- Keep personal and shareholder transactions out of the operating accounts.
- Check the T1135 threshold against the cost of correspondent accounts and other foreign property.
Corrections Worth Carrying
- Revenue is the spread and fees, never the volume exchanged.
- The functional currency election is Form T1296, not T1139-FC.
- It is filed once, before the first day of the year, not annually with the T2.
- Only USD, EUR, GBP and AUD qualify as functional currencies.
- Under the election the T2 is filed in the functional currency, not converted to CAD.
- Bank of Canada noon rates were discontinued in 2017.
- A dealer’s year-end revaluation is recognised on income account.
- Financial services are exempt under Schedule V Part VII; 123(1) is the definition.
- Exempt supplies carry no input tax credit recovery.
- T1135 sits in section 233.3; 237.3 is the reportable transactions regime.
- Form T776 is a personal return form and does not apply to a corporation.
- Leasehold improvements are Class 13, and computers are Class 50.
You can also download our free currency exchange year-end checklist.
For tailored support with your currency exchange business tax checklist in Canada, contact Gondaliya CPA at info@gondaliyacpa.ca, call 647-212-9559, or book a free consultation. Where records are behind, our catch-up bookkeeping services rebuild them first, and our corporate tax cleanup service handles the filings.
Twelve corrections, and eleven of them are citations or forms that look specific enough that nobody checks them. Figures changed for privacy.
Professional Guidance and Quick Reference
Professional Guidance and Quick Reference
Guidance
Quick Answers: Key Numbers & Concepts at a Glance
At a Glance
| Question | Answer |
|---|---|
| Revenue on $100,000 exchanged at a $5,000 spread | $5,000 |
| Functional currency election form | Form T1296, filed once |
| Election deadline | On or before the first day of the year |
| Qualifying currencies | USD, EUR, GBP, AUD |
| Bank of Canada noon rate | Discontinued in 2017 |
| Dealer revaluation at year end | Income account, recognised |
| Financial services exemption | Schedule V, Part VII |
| Input tax credits on exempt supplies | None |
| T1135 threshold | $100,000, measured on cost |
| T2 filing / payment | Six months / two or three months |
| Record retention | Six years from the end of the taxation year |
| Counting machines / leaseholds | Class 8 at 20% / Class 13 over the lease |
Who This Is For / Not For
Fit Check
- For: Incorporated Canadian currency exchange businesses, money services businesses and multi-branch bureaus, including operators with correspondent accounts abroad.
- Not For: Unincorporated or individual operators, whose home premises and instalment treatment differ, and it is not a guide to FINTRAC obligations, which run separately.
People Also Ask
Quick Answers
Do I report the volume I exchanged as revenue?+
No. Revenue is the spread and fees you keep. Reporting volume overstates revenue by the whole amount that passed through.
Does the Bank of Canada still publish a noon rate?+
No. Noon rates were discontinued in 2017 and a single daily rate is published each business day.
Is a currency exchange business a money services business?+
Generally yes, which brings FINTRAC registration and its own record-keeping obligations, separate from anything in the Income Tax Act.
Glossary of Key Terms
Plain-English Definitions
- Spread: The margin between the buy and sell rate, which is revenue.
- Volume: The gross amount exchanged, a statistic rather than revenue.
- Revaluation: Restating foreign balances at the closing rate at year end.
- Income account: Where a dealer’s foreign exchange gains and losses fall.
- Functional currency: A qualifying currency a corporation may elect to report in.
- Form T1296: The functional currency election, filed once before the year begins.
- Qualifying currency: US dollars, euros, British pounds or Australian dollars.
- Client funds: Money held for customers, recorded as a liability.
- Correspondent account: An account with a foreign bank, counting toward the T1135 threshold.
- Exempt supply: A supply carrying no tax and no credit recovery.
- Apportionment: Splitting recoverable tax between exempt and taxable activity.
- Form T1135: The return for specified foreign property costing over $100,000.
- Available for use: When an asset becomes eligible for capital cost allowance.
- Class 8: Counting machines and security systems, at 20%.
- Class 13: Leasehold improvements, written off over the lease term.
- Trust amounts: Collected sales tax and payroll source deductions.
This quick self-check indicates whether your year-end is ready. Please answer the five questions below.
Year-End Readiness Check
Five quick questions on your bureau. No fee shown.
Points to raise with us:
This is a general prompt, not tax or legal advice or a quote. Your position depends on your full facts. For a real review, please book a free consultation.
A currency exchange year-end turns on three numbers that behave differently from an ordinary business. Revenue is the spread and fees, never the volume that passed through. Foreign cash is revalued at the Bank of Canada closing rate and, because it is trading property, that revaluation is recognised on income account rather than deferred until conversion. Client money is a liability from the moment it arrives. Around those, confirm the functional currency position on Form T1296 before the year begins rather than when the return is prepared, apportion input tax credits against a largely exempt revenue base, and measure the T1135 threshold on the cost of foreign property including correspondent accounts.
2026 Update — what is current: This article reflects rules current to 2026. The six-month T2 filing deadline, the two and three month payment deadlines, the last day of February for T4 and T4A slips, the six-year retention period measured from the end of the taxation year, the $30,000 GST/HST small supplier threshold on both tests, the $100,000 T1135 cost threshold and the Class 8, 12, 13 and 50 rates are unchanged. Bill C-15 received Royal Assent on 26 March 2026, reinstating the accelerated investment incentive for depreciable property acquired after 2024 and available for use before 2030, and Ontario\u2019s small business rate moves to 2.2% from 1 July 2026. Please note that the functional currency election is made on Form T1296, once, on or before the first day of the first taxation year it applies to, and is limited to the qualifying currencies USD, EUR, GBP and AUD, with the return then filed in that currency rather than converted to Canadian dollars; that there is no Form T1139-FC; that the Bank of Canada discontinued noon rates in 2017 and now publishes a single daily rate; that a dealer\u2019s year-end revaluation of trading currency is recognised on income account; that the exemption for financial services sits in Schedule V, Part VII of the Excise Tax Act while subsection 123(1) contains the definition; that T1135 is required by section 233.3 rather than section 237.3; and that Form T776 is a personal return form that does not apply to a corporation.
Currency Exchange Year-End: How Gondaliya CPA Supports You
Running a bureau and want the year-end done properly?
We separate spread from volume, revalue foreign balances at the closing rate with the source kept, hold client funds as a liability, apportion input tax credits across your exempt and taxable supplies, and check the T1135 position — on a flat annual fee stated before the work starts, including HST.
Next Steps
Please book a free consultation with Gondaliya CPA and bring your last filed corporate return, your year-end count sheets, and a month of transaction system reports showing volume against spread. Those three tell us within minutes whether the revenue line is right. You will get a flat fee stated before any work begins, including HST. You can also send us a message if you would rather start in writing.
Published: · Last updated:
Editorial policy: Statutory references are to the Income Tax Act and Excise Tax Act as they stood on the publication date. Rates, thresholds and forms change, so please confirm the current position before acting.
Disclaimer: This article is educational information only and is not tax, legal, or financial advice. Outcomes depend on your full facts, and money services businesses have separate obligations under the FINTRAC regime. Please speak with a CPA before acting.

Sharad Gondaliya is a CPA Canada & CPA USA with 15 Years+ experience of Accounting, Tax, Payroll of Corporate Small Businesses as Tax Accountant. He is fully certified CPA Ontario and CPA USA and is well known among corporate small businesses for tax planning, efficient tax solutions, and affordable CPA services. Sharad is the Principal (Director) of Gondaliya CPA – Affordable CPA Firm in Canada. Licenses: CPA Ontario: 61040184 | CPA USA (MT): PAC-CPAP-LIC-033176 | CPA USA (WA): 57629 | CPA Firm License: 61330051 View Full Author Bio