



Tax Accountant for Tour Operators in Ontario and Across Canada
A tour operator is the principal on everything it sells: you contract the coach, block the rooms, retain the guides and commit to the entrance costs long before a seat is sold, you invoice under your own name, and the loss is yours if a departure runs half empty. That is why the whole price you charge is revenue and the supplier bills behind it are cost of sales. We build costing that reports the margin on each departure, hold deposits in deferred revenue until the trip actually runs, carry money already sent to suppliers as a prepaid asset rather than an expense, and keep the timing on a deposit aligned with ETA subsection 168(9), under which the tax is collected when the deposit is applied against the invoice rather than on the day the client books. Whether you run escorted coach touring, multi-day guided trips, inbound receptive programmes or custom group departures, we handle the departures, the costs and the compliance — with AFFORDABLE flat fees.
AFFORDABLE Tour Operator Tax Accountant
Everything on this page follows from one fact: a tour operator is the principal, not an agent. You design the itinerary, sign for the coach, hold the rooms, engage the guides and take on the entrance costs while the departure is still a line on a brochure, then sell it under your own name and absorb the shortfall when it under-fills. So the whole price a client pays belongs on the revenue line and every supplier invoice behind that trip belongs in cost of sales. An agency is the mirror image of this: it arranges somebody else’s product and its revenue is the fee it is paid for arranging. From that split comes the one figure operators most often cannot produce, which is gross margin by departure, and without it twelve profitable trips will happily conceal three that lost money. The second difficulty is timing. Deposits arrive months early, prepayments to suppliers leave months early, and the bank balance sitting between them flatters a season nobody has operated yet. At Gondaliya CPA we fix the revenue and cost-of-sales split first, build the departure costing on top of it, and let the rest of the file fall into place behind those two.
As a tour operator accountant, we look after escorted coach touring companies, multi-day guided trip operators, inbound receptive operators and custom group departure businesses throughout Ontario, with support running all year instead of one panicked month. You get to see what each departure earned after its own costs, which deposits have become income and which have not, and how much capacity you are already committed to.
Leave the ledger with us and spend your own hours on the itineraries, the suppliers and next season.
Our Official Partners
Accounting That Understands How a Tour Operator Actually Works
Packaging and selling your own product carries pressures a reseller never meets. You are committed to suppliers before anybody has paid you, the money that arrives first belongs to trips that have not run, the money that leaves first buys capacity you may not fill, and the people leading your groups are seasonal in a way CRA regularly disputes. Gondaliya CPA works inside that reality every week and gives operators across Ontario answers built for it.
Stay Compliant and Minimize Your Tour Operator Tax
For a tour operating business, paying the least tax the law allows and keeping every obligation current are the same piece of work. We hold the deadlines and claim every deduction your departures genuinely support, so nothing is missed and nothing on the file invites a closer look.
Accounting & Tax Experts for Tour Operators
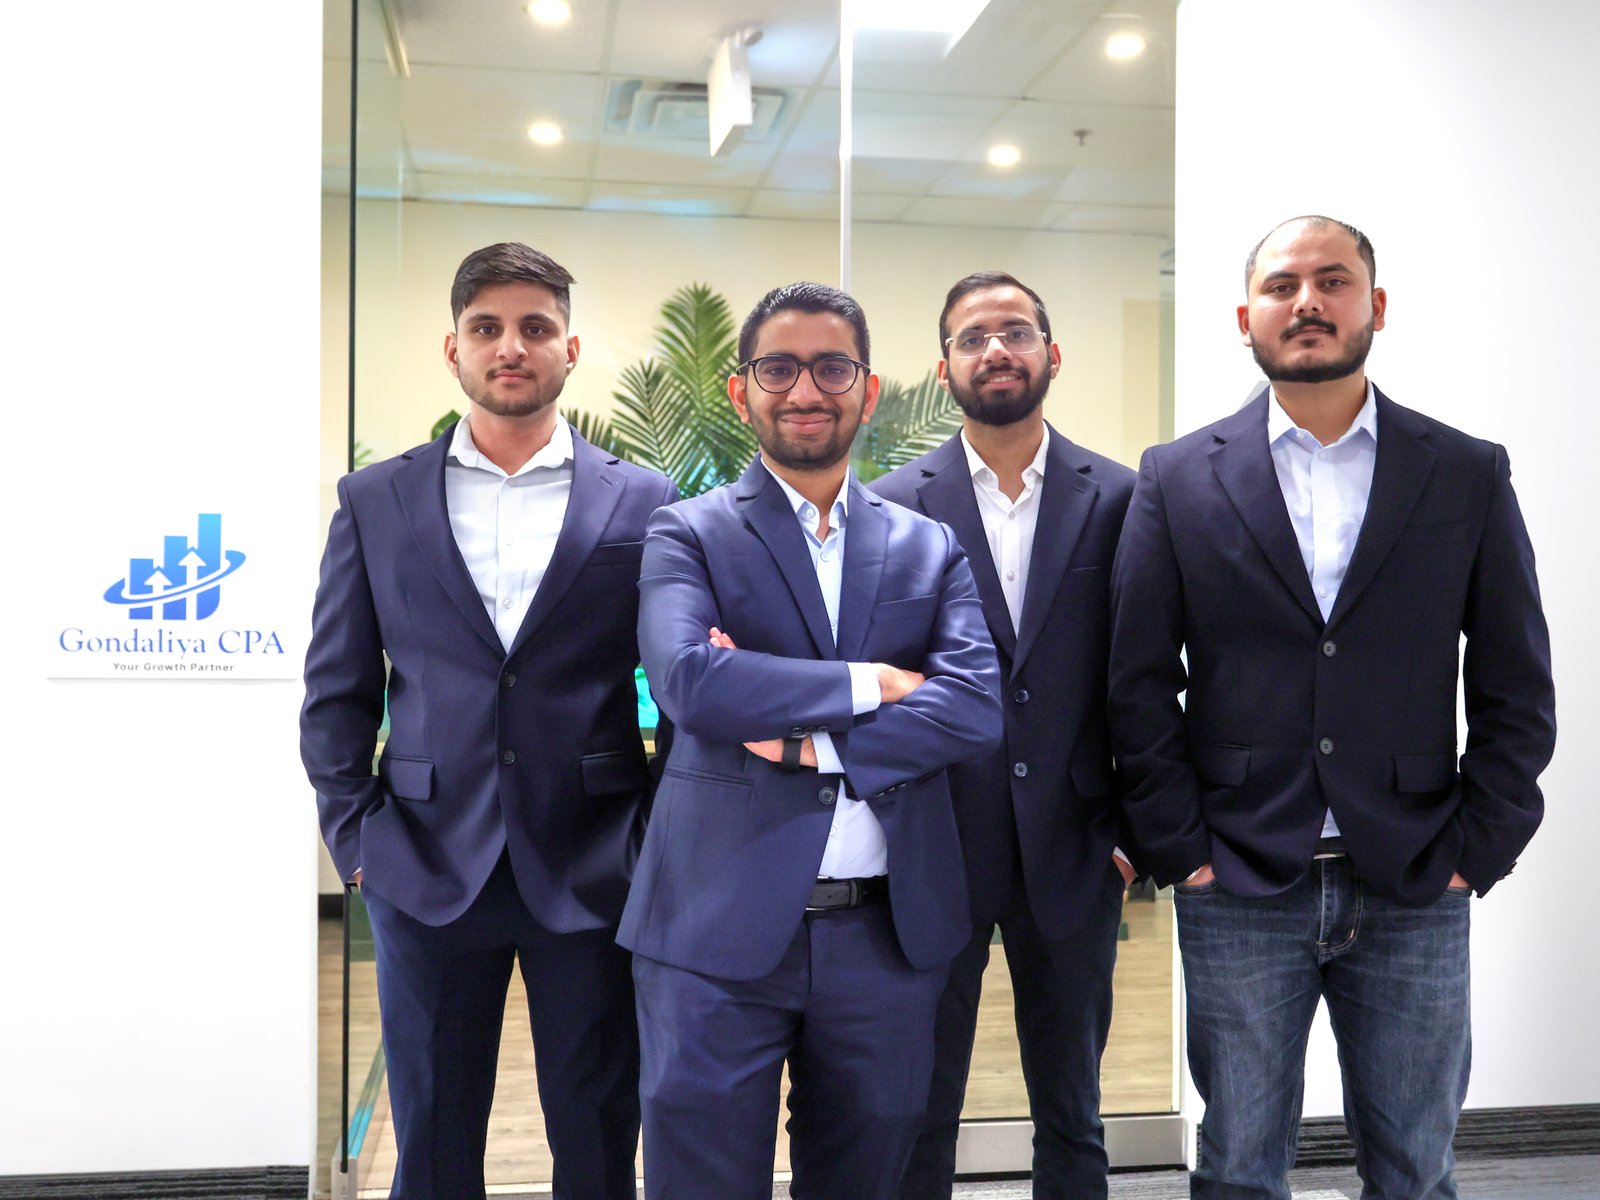
- AFFORDABLE + Fully Registered CPA Firm
- Business and Corporate Tax Expert
- Small & Medium Business Expert
- Accounting, bookkeeping, and tax filing
- Certified CPA
- 1300+ 5-star Google reviews
- 30-Day Money-Back Guarantee
- 60-Day Fees Matching Policy
Why Choose Our Accounting Services for Tour Operators?
Tax Planning — Revenue, Cost of Sales & Margin
We know the trade: the full price charged on the revenue line, supplier bills in cost of sales, deposits deferred to the departure. We protect the $500,000 Small Business Deduction.
Consulting — Costing Trip by Trip
Our bookkeeping reports what each departure charged, what it consumed and what it kept, so you can see which trips carried the season and which quietly drained it.
CRA Representation — Revenue Timing & Worker Status
When a reviewer questions when you recognised a departure or how you treated your guides, we draft the reply, assemble the support, and seek penalty relief on Form RC4288 where an earlier error caused it.
Bookkeeping — Cash Against Commitments
We keep deposits for unrun trips visible against the prepayments and capacity you are already committed to, produce the statements your lender reads, and plan the exit years out.
Google Reviews
Tour Operator Clients
Tour Operator Tax and Accounting Services in Ontario
Corporate Tax Filing (T2) for Tour Operators
Professional T2 preparation with the full price charged on the revenue line, supplier costs in cost of sales, deposits deferred to departure, and CRA compliance throughout.
Bookkeeping & Accounting for Tour Operators
Departure-by-departure costing with margin reported per trip, deferred revenue and supplier prepayments reconciled monthly, and statements built from clean records.
Payroll Services for Tour Operators
Guide and seasonal staff payroll with WSIB coverage, PD7A remittances, T4 and T4A slips filed on schedule, and worker status documented before CRA asks.
GST/HST Filing for Tour Operators
AFFORDABLE HST filing on your own supplies, with deposits timed under ETA subsection 168(9), place of supply settled per booking, and every input tax credit recovered.
Tax Planning for Tour Operators
Smart planning on the fiscal year end, the salary and dividend mix, the Small Business Deduction, and the share structure that supports an eventual sale.
Corporate Catch-Up Filing for Tour Operators
File overdue T2 and HST years, rebuild the departure history and the deferred revenue behind it, and return to CRA compliance with accurate catch-up support.
CRA Audit Resolution for Tour Operators
Confident handling of revenue-timing questions, guide classification challenges and credit-recovery reviews, from the opening CRA letter through to reassessment and objection.
CPA Financial Statements (Notice to Reader) for Tour Operators
CPA-compiled statements lenders accept, showing a real gross margin with deferred revenue and supplier prepayments stated on their own lines.
Incorporation Services for Tour Operators
Complete incorporation with the NUANS search, articles, minute book and share classes, plus a section 85 transfer of your itineraries, goodwill and equipment into the new company.
Catch-Up Bookkeeping Services for Tour Operators
Months or years of client payments, supplier invoices, refunds and card settlements rebuilt and reconciled, so your departure margins are finally visible.
US Corporation & LLC Tax Filing for Tour Operators
Filing on both sides where your departures operate in the United States, or where a shareholder is American or lives outside Canada, including withholding duties and Form T1135 disclosure.
Voluntary Disclosure Program for Tour Operators
Come forward on unfiled slips, misstated revenue or expensed prepayments before CRA calls, cancelling penalties through a Voluntary Disclosures Program application.
Accounting & Tax Services Tailored for Tour Operators
Real, practitioner-level CPA expertise for escorted coach touring companies, multi-day guided trip operators, inbound receptive operators and custom group departure businesses across Ontario — built for a business that commits to suppliers long before a seat is sold.
- We prepare your T2 with GIFI on Schedule 100 and Schedule 125, reporting the full price you charged for each departure as revenue and the supplier invoices behind it as cost of sales, because you sold as principal.
- We carry deposits taken for departures that have not yet run as deferred revenue rather than sales, so the return reflects the seasons you actually operated instead of the ones you had merely sold by year end.
- We reclassify supplier prepayments outstanding at year end into prepaid assets, since money already sent to a coach company or a lodge for a trip that has not taken place is not yet a deduction.
- Capital cost allowance goes on Schedule 8, with furniture and office equipment pooled in Class 8 at 20%, computers in Class 50 at 55%, and money spent improving a rented office written off in Class 13 across its term.
- We keep taxable income inside the $500,000 small business limit where planning allows, because every dollar spilling past that limit leaves the roughly 12.2% Ontario combined rate for the general corporate rate.
- We open a costing file for every departure and post the coach charter, the rooms, the guides, the entrance costs and the meals against it, so each trip reports its own margin rather than vanishing into a seasonal total.
- We hold the whole price a client pays in deferred revenue and release it to sales on the day the departure actually operates, which is the single change that makes a monthly income statement worth reading.
- We reconcile the supplier prepayment account monthly against confirmations, because an operator who has wired forty or fifty thousand dollars ahead of a season needs that figure to be an asset it can prove.
- We schedule committed capacity by departure, so rooms and seats you are already contracted for show up as an exposure well ahead of the release deadline instead of living only in the owner’s memory.
- Supplier bills, card receipts and expense documents run through Dext into a close we perform every month, which preserves the six-year record CRA requires and stops credits on your overheads quietly going unclaimed.
- We test your guides, drivers and seasonal staff against the factors that genuinely decide worker status: who controls the work, who supplies the tools, whether the person can profit or lose, and how deeply they are integrated.
- Employees go on payroll and receive a T4; guides who are truly running their own businesses receive a T4A instead, so each payment you claimed as a deduction is reported in the form CRA expects to match.
- Wagepoint runs the pay cycle, withholds income tax, CPP and EI, and gets the remittance to CRA under the PD7A on schedule, which matters because late source deductions carry a graduated penalty rising to 10%.
- WSIB coverage is opened before your first hire rather than afterwards, since an account nobody registered surfaces at the worst moment and the arrears reach back to the date the obligation first arose.
- February ends with your T4 slips and T4 Summary lodged and agreed against what actually went across to CRA during the year, while Ontario payroll is measured all along against the $1,000,000 Employer Health Tax exemption.
- Your own services are taxable supplies at 13% in Ontario, so we bill, collect and report what you charge, and we recover the input tax credits on the operating costs the business carries for itself.
- When taxable revenue looks set to cross $30,000 across four consecutive calendar quarters, we get you registered, since arriving late at that door erases none of the tax already due on what you supplied.
- Where a departure operates outside Ontario, the place of supply has to be settled booking by booking rather than assumed from your office address, and we build that determination into the monthly close.
- Under ETA subsection 168(9) the tax on a deposit is collected when the deposit is applied against the invoice, not on the day the client books, and we configure your system so the timing follows that rule.
- Every period’s GST34 goes in and is agreed back to the ledger behind it, because a filing nobody can trace to the accounting records is the first thing a reviewer will want walked through line by line.
- The split between salary and dividends is reviewed annually against a roughly 12.2% Ontario combined rate on the first $500,000 of active income and a 53.53% personal ceiling, so nothing leaves the company unplanned.
- We look hard at where your fiscal year end sits, because one chosen in the middle of the selling season leaves a balance sheet stuffed with deposits and prepayments that tells a lender very little of use.
- Long before anyone discusses a price, we shape the shares so a future sale can use the $1.25 million lifetime capital gains exemption, which is not something that can be arranged in the month of a transaction.
- Before you incorporate we model whether it pays, since the deferral only has value once the business earns more than the household takes out, and plenty of small operators have not reached that point.
- Purchases of equipment and office assets are timed against your year end so the deduction falls in the year it is worth most, rather than in whichever year the supplier happened to send the invoice.
- We file every overdue T2 year, because a corporation with nothing on file is assessed arbitrarily on whatever CRA can see, and what CRA can see here is deposit money for trips that had not yet run.
- We rebuild each historic year from departure records rather than from the bank, separating the price charged from the supplier costs consumed, which is the only route to a margin figure you can defend.
- We reconstruct deferred revenue and supplier prepayments at every past year end, so the catch-up balance sheets show what was genuinely owed forward and what was genuinely still an asset of the company.
- Missed HST periods are brought up to date on the supplies you made, and credits you funded during those unreported years are pulled back in, since nobody could claim them while the returns sat unlodged.
- Where a real reason sits behind the delay, Form RC4288 is used to seek cancellation of penalties and some interest, and a monthly discipline then goes in so the years ahead never slide again.
- We handle revenue recognition reviews, which on an operator file nearly always open with a reviewer setting bank deposits beside reported sales and asking why the two figures sit so far apart.
- We prepare the schedule that answers it: deposits held for trips not yet run, prepayments still sitting with suppliers, and the price and cost of each departure that did operate, every line supported by documents.
- Assessments aimed at your guides and seasonal staff are met with the worker-status analysis already sitting on file, since debating control, tools and risk once an assessment has landed is a much weaker position.
- On credit-recovery reviews we hand across the underlying bills together with your suppliers’ registration numbers, so an amount you were plainly entitled to claim is not struck out merely because the paperwork looked thin.
- From the opening letter to the reassessment notice we speak to CRA on your behalf, and where the figures are wrong the objection is lodged within the ninety day window so nothing lapses by default.
- We prepare Notice to Reader statements where revenue is what actually departed and cost of sales is what those departures consumed, so the gross margin line is the real operating result of the season.
- Deferred revenue is stated as a liability of its own, because a reader who cannot see how much cash belongs to trips still waiting to leave will badly misjudge the working capital in front of them.
- Supplier prepayments appear as an asset instead of being buried in expenses, which is what lets a lender understand why cash left the business months ahead of the revenue that money was spent to earn.
- Material committed capacity is disclosed, so a reader sees what the company is contracted for beyond the year end rather than learning about it halfway through a financing conversation.
- The statements go out with the T2 and a GIFI that agrees to them, which is the bundle anyone underwriting you, leasing to you or weighing up a purchase of the business will open before anything else.
- Incorporation is handled end to end: the NUANS search, the articles, the minute book, the share structure, federal or Ontario, and registration of the new company for its HST and payroll accounts.
- The share structure is built with room for a later freeze and for the $1.25 million lifetime capital gains exemption, instead of the single common class a rushed online filing tends to leave behind.
- A section 85 election, filed on Form T2057, carries itineraries, goodwill, vehicles and equipment across at cost, which is what keeps incorporation day from manufacturing a taxable gain out of assets you already owned.
- Where the numbers do not support it we say so plainly, because until the business earns more than the household withdraws, the yearly cost of a corporation quietly eats whatever deferral it was meant to create.
- The opening balance sheet is built correctly on day one, with deferred revenue and supplier prepayments in accounts of their own, so the new company does not inherit the mess most operators arrive carrying.
- Years of client payments, supplier bills, refunds and card settlements are pieced back together and agreed to the bank, giving the file a beginning that will hold up when somebody senior starts asking questions.
- We rebuild the departure ledger trip by trip, setting what each one charged against what it consumed, which is how an operator learns that three trips a season were losing several thousand dollars apiece.
- Deposits for future trips come out of the sales account, because an income statement counting next summer’s money as this year’s revenue has been telling the owner a comfortable story for years.
- We recover input tax credits on operating costs from the unfiled periods, which for an operator carrying an office, reservation systems and marketing spend is routinely several thousand dollars left unclaimed.
- You get back a clean trial balance, a reconciled bank, a reconciled prepayment account and books the next twelve months can be built on, plus a monthly routine so nothing slides again.
- Where your departures run in the United States, or a US entity exists to hold contracts with American suppliers, we review what that side requires and reconcile it against the revenue and costs recorded in Canada.
- Dividends paid to a shareholder resident outside Canada attract Part XIII withholding at 25% before any treaty relief, and we work out the figure, remit it on time, and issue the NR4 slip and summary.
- Owners holding specified foreign property over the $100,000 threshold need Form T1135, and we prepare it, because the penalty here follows the missed disclosure rather than any tax that might have been payable.
- A shareholder who is a United States citizen brings personal filing duties into the picture wherever the operator trades, and we run the Canadian and American returns side by side rather than months apart.
- Where income is reported in both countries we line the figures up so the foreign tax credit is genuinely obtained, since one dollar of profit taxed twice is money the operator simply never gets back.
- We bring a corporation forward where deposits for trips that had not departed were reported as sales, because the corrected numbers usually reduce the tax owing while the wrong returns still carry penalties.
- We disclose guides and seasonal staff paid across several years with no slips issued, since the per-slip exposure and the worker status question both sit behind that single line in the ledger.
- We disclose seasons where supplier prepayments were expensed on payment while the departure fell in the following year, which quietly shifted profit between years and left two returns that will not stand up.
- The application goes in on Form RC199 with a full rebuild behind it from departure records, supplier invoices and bank data, so the figures CRA receives are ones you can defend under questioning.
- Before filing we confirm the three conditions that make a disclosure valid: it comes ahead of any CRA contact, it is complete, and the year in question is at least one year past due.
Tour Operator Departure & Tax Check
Six quick questions on your departure costing, your revenue and cost of sales split, your deposit timing, your supplier prepayments, place of supply and whether it is time to incorporate. No fee shown.
1. Do you cost each departure on its own with the coach, rooms, guides and entrance costs loaded against it?
2. Is the full price you charge recorded as revenue with the supplier bills in cost of sales?
3. Are deposits held in deferred revenue until the departure actually runs?
4. Are supplier prepayments carried as assets rather than expensed the month they are paid?
5. Is the place of supply settled booking by booking when a departure runs outside Ontario?
6. Is your tour operating business incorporated?
Free CPA Consultation for Tour Operators
Case Studies: Tour Operator Accounting & Tax
Barrie Escorted Coach Operator — A Year That Had Not Happened Yet
The problem: A Barrie escorted coach operator banked every deposit straight into sales. The latest return showed $2,640,000 of revenue, but roughly $780,000 of it was money taken for departures scheduled into the following spring, and the supplier prepayments for those same trips had been written off the month the transfers went out. Tax had been paid on a season not yet operated.
What we did: We rebuilt three years from departure records, released revenue on the date each trip ran, moved unrun deposits into deferred revenue, restored outstanding prepayments as assets, and refiled the open years.
The result:
- $780,000 of deposits moved out of the year banked
- Supplier prepayments restored as assets, not expenses
- Open years refiled and tax on unearned revenue recovered
London Guided Trip Operator — The Departures Nobody Costed
The problem: A London operator running multi-day guided trips reported one margin for the whole season and had never costed a single departure. Revenue climbed each year while the bank balance did not. The owner assumed the long summer itineraries carried the business. Loading the coach charters, rooms, guides, entrance costs and meals against each trip individually showed four departures a year losing money, and they were the four priced highest.
What we did: We built per-departure costing in the accounting file, reported gross margin trip by trip, kept fixed office overhead out of it, and handed the owner those numbers before the next brochure was set.
The result:
- Four loss-making departures found, worth $96,000 a year
- Gross margin now reported trip by trip, not by season
- Costing ready before the next season was committed
Niagara Falls Receptive Operator — When a Departure Unwinds
The problem: A Niagara Falls inbound receptive operator cancelled two group programmes that missed their minimum numbers. Deposits had been taken, suppliers paid ahead, and further capacity was already contracted. All three unwound a quarter after the one that recorded them. The bookkeeper reversed deposits against sales, left prepayments in expenses, and committed capacity had never been recorded anywhere, so two quarters were wrong in opposite directions.
What we did: We wrote a cancellation routine that unwinds all three together, dated to the period the cancellation was decided, with supplier correspondence attached to every prepayment recovered or written off.
The result:
- One routine unwinds deposits, prepayments and commitments
- Cancellations recorded in the period they were decided
- Committed capacity tracked on a schedule, not in memory
Our clear, efficient process ensures every step is transparent, building trust and long-term client relationships.
Kickoff (Document Request)
Collect prior T2 returns, the departure and reservation records, supplier contracts and confirmations, deposit and refund files, bank and card statements, guide agreements, payroll records, the office lease and your licensing paperwork.
First 30 Days (Cleanup & Setup)
Set up QuickBooks Online or Xero against your reservation records, restate revenue and cost of sales by departure, build the deferred revenue and prepayment accounts, and document worker status for every guide.
Monthly Close
Revenue released on departures that ran, cost of sales matched to each trip, deferred revenue and supplier prepayments reconciled, GST34 with place of supply settled per booking, and payroll, PD7A and slip reconciliation.
Quarterly Planning Review
Salary and dividend mix, the small business limit, gross margin by departure against the season ahead, committed capacity versus deposits in hand, and cash flow measured against what is already contracted.
Year-End Close & T2 Filing
Trial balance, financial statements with deferred revenue and prepayments stated properly, cancellations settled in the right period, T2 with GIFI, and CRA preparation.
Get Your Tour Operator Taxes Done Right Today
Affordable Pricing for Tour Operators
We believe in clear, upfront pricing so you know exactly what to expect. All fees include HST.
- Tax Preparation (Corporation) — From $400
- Tax Return Filing (Corporation) — From $400
- Tax Compliance Audit — FREE CRA audit support for our clients
- Tax Strategy — FREE for our clients
- Accounting Base Plan — From $100 per month
- Bookkeeping Management — Free for our Accounting clients
- Financial Reporting — Free for our Accounting clients
- Business Formation — Flat $35
- Incorporation Process — Flat $35
- Entity Setup Assistance — Flat $35
- Full-Service Payroll — From $125 per month
Payment is by Interac e-Transfer to info@gondaliyacpa.ca only. Security question: Not Applicable, as auto-deposit is enabled.
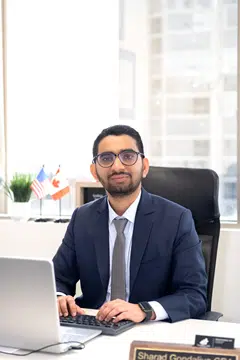
Meet Your Lead Tour Operator Accountant
Meet your lead tour operator accountant. The same two people look after your departure costing and your corporate return, season after season.
What Our Clients Say
1300+ five-star reviews left by owners of tour, hospitality and small service businesses right across Ontario and Canada.
Serving Tour Operators Across Ontario
Our CPA team delivers specialised accounting and tax work for tour operating businesses right across Ontario. We understand why a departure has to be costed on its own, why a deposit is not yet income, why money sent ahead to a supplier is an asset, and what CRA reads first when it opens an operator file.
Toronto (ON)
55 Queen St E Ste 1205, Toronto, ON M5C 1R6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Mississauga (ON)
2100 Camilla Rd #716, Mississauga, ON L5A 2J8
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Brampton (ON)
4 Starhill Crescent, Brampton, ON L6R 2P9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Scarborough (ON)
24 Clementine Square, Scarborough, ON M1G 2V7, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Vaughan (ON)
19 Cabinet Crescent, Woodbridge, ON L4L 6H9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Oshawa (ON)
210 Durham St, Oshawa, ON L1J 5R3, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Ottawa (ON)
2090 Neepawa Ave a314, Ottawa, ON K2A 3L6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Etobicoke (ON)
60 Stevenson Rd #1601, Etobicoke, ON M9V 2B4, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Hamilton (ON)
70 Starling Dr, Hamilton, ON L9A 0C5, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Guelph (ON)
1155 Gordon St, Guelph, ON N1L 1S8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Windsor (ON)
4387 Guppy Ct, Windsor, ON N9G 2N8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
North York (ON)
150 Graydon Hall Dr #912, North York, ON M3A 3B2, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Tour Operator Accounting & Tax FAQs
Related Industries We Serve
Accountant for Travel Agencies
- Earned revenue rather than gross bookings
- Independent agents and worker status
- Corporate tax filing and statements
Accountant for Adventure Tourism Businesses
- Seasonal revenue and deferred deposits
- Equipment pools and capital cost allowance
- Corporate tax planning and payroll
Accounting and Tax Services for Small Businesses
- Bookkeeping, HST and year-end filing
- Owner salary and dividend planning
- Notice to Reader financial statements
Accountant for Incorporated Businesses
- T2 filing and GIFI schedules
- Small business limit and share structure
- Corporate tax planning and bookkeeping
Tour Operator Accounting & Tax Done Right.
T2 filing with the full price you charged on the revenue line and the supplier invoices behind each departure in cost of sales, because you sell as principal. Gross margin reported trip by trip instead of once a season. Deposits held in deferred revenue until the departure runs, with the tax timed to ETA subsection 168(9). Supplier prepayments carried as assets until the trip takes place, committed capacity on a schedule you can see, and a cancellation routine that unwinds all three in the right period. AFFORDABLE flat fees, no hourly billing. Licensed CPA Ontario. 1300+ five-star reviews. 30-Day Money-Back Guarantee.