



Tax Accountant for Recycling Companies in Ontario and Across Canada
We put inventory at the centre of the file, because a recycling company buys material, holds it and sells it, and the spread between the two prices is where the year is won or lost. We carry what sits on your floor at the lower of its cost and its net realizable value under ITA 10(1), take the reduction in the year the grade actually fell and file the price evidence that supports it, build the inbound trail of weight, grade, price and payee that ITA 230 expects to find behind six years of purchases, cost freight to the mill against the shipment it moved, and pool the yard properly with haul trucks and trailers in Class 10 at 30%, scale systems and computers in Class 50 at 55% and small tools in Class 12 at 100%. Whether you run a ferrous and nonferrous yard, a plastics or fibre processor, an electronics recovery operation or a mixed-material facility, we handle the inventory, the tickets and the T2 — with AFFORDABLE flat fees.
AFFORDABLE Recycling Company Tax Accountant
A recycling company looks like a service business and is in fact a trading business. Nobody pays you to take material away. You buy it at the scale, by weight and by grade, often from people you will never see again; you hold it, you sort and process it, and weeks later you sell it to a mill, a smelter or a broker at whatever the market is paying that day. The money is the spread, and between the purchase and the settlement that spread is exposed to a commodity market nobody in the yard controls. So inventory is the centre of the file, and inventory here behaves unlike inventory anywhere else: it arrives in mixed loads, it is measured by weight and grade rather than by unit, it changes value while it sits on the floor, and the only proof that any of it happened is a ticket your own scale house printed. At Gondaliya CPA we specialize in inventory valuation, inbound purchase records and equipment pools for recycling companies. The work is AFFORDABLE and flat-fee, it keeps the corporation onside with CRA, and it stops you handing over tax the return never actually owed.
As a recycling accountant, we act for ferrous and nonferrous yards, plastics and fibre processors, electronics recovery operations and mixed-material facilities across Ontario. We stay on the file all twelve months, which is the opposite of the annual scramble most yards are used to. We tell you what the material on your floor is worth on the last day of the year, whether the paperwork behind your cost of sales would survive a second look, and which grades still earn once freight comes out of them.
You run the yard and read the market. We will keep the ledger, the pools and the return straight behind you.
Our Official Partners
Accounting That Understands How a Recycling Company Actually Works
A yard carries financial pressure a service company never meets. You pay for material before anyone knows what it will fetch, you finance a floor of inventory that revalues itself while you sleep, you settle with a mill weeks after the truck left, and the whole inbound side of your ledger is built from documents your own scale house produced. That is the ground we work on, and what we give yards across Ontario is built for it.
Stay Compliant and Minimize Your Recycling Company Tax
For a recycling company, filing on time and paying the least tax the law allows are one piece of work. We keep each return on the calendar and claim every inventory, freight, payroll and equipment dollar the T2 properly allows, so the filing is complete and nothing inside it invites a second look.
Accounting & Tax Experts for Recycling Companies
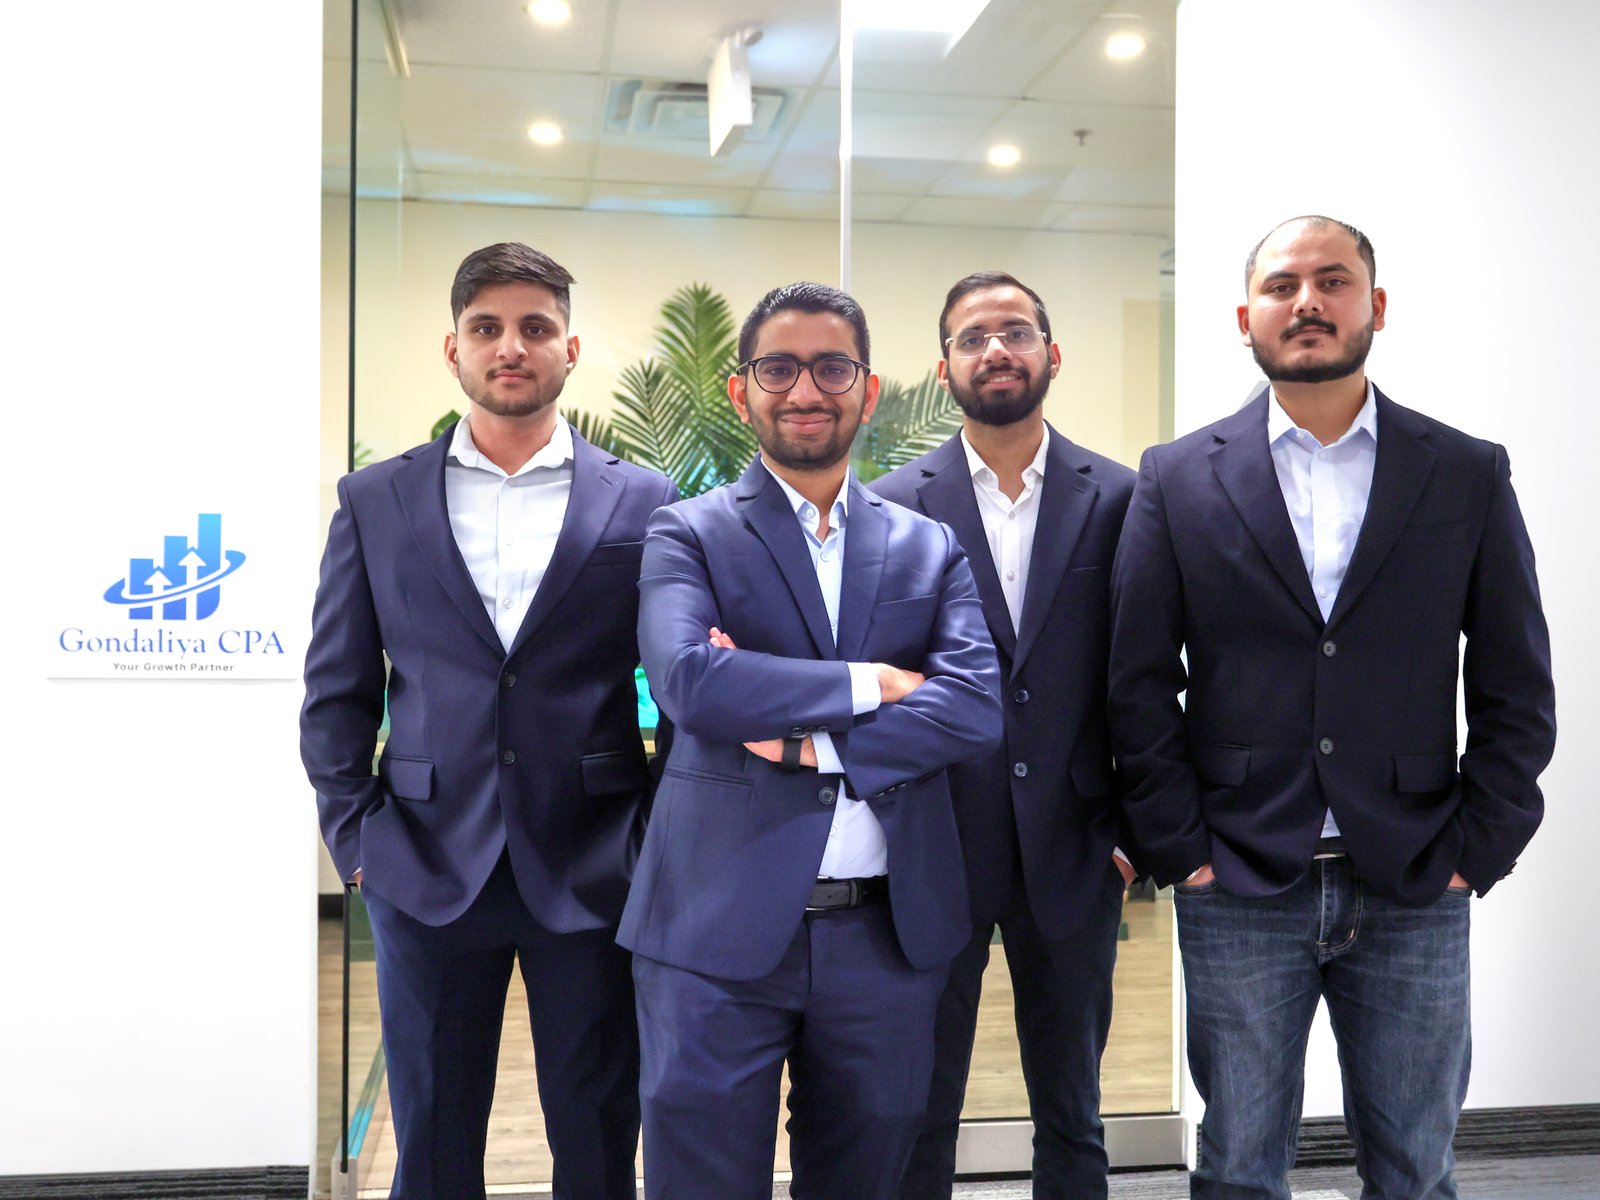
- AFFORDABLE + Registered CPA Firm
- Business and Corporate Tax Expert
- Small & Medium Business Expert
- Accounting, bookkeeping, and tax filing
- CPA (Chartered Professional Accountant)
- 1300+ 5-star Google reviews
- 30-Day Money-Back Guarantee
- 60-Day Fees Matching Policy
Why Choose Our Accounting Services for Recycling Companies?
Tax Planning — Inventory, Pools & Timing
We work the trade: ITA 10(1) on the floor, the reduction taken in the right year, processing machinery pooled on a determination of its use, and the $500,000 Small Business Deduction protected.
Consulting — Margin by Grade
Our bookkeeping costs each commodity family after purchase price, processing and haulage, so you can see which material earns and which is going out the gate at a loss.
CRA Representation — Records & Inventory
When CRA tests your inbound documentation or your year-end valuation, we build the response and apply for relief under Form RC4288 where penalties trace back to somebody else’s mistake.
Bookkeeping — Cash, Settlements & Exit
We forecast the cash that has to leave the yard weeks before a mill settles, produce statements a lender will underwrite, and set up the exit long before you want it.
Google Reviews
Recycling Clients
Recycling Company Tax and Accounting Services in Ontario
Corporate Tax Filing (T2) for Recycling Companies
Professional T2 preparation with the floor valued under ITA 10(1), the yard pooled by capital class on Schedule 8, freight costed to the shipment, and CRA compliance on every line.
Bookkeeping & Accounting for Recycling Companies
Inbound tickets, mill settlements and grade-level margin posted month by month, with inventory that ties back to the scale and statements built from records that actually reconcile.
Payroll Services for Recycling Companies
Payroll for the yard and the sorting line, WSIB opened before anybody starts, source deductions carried on the PD7A, and the T4 and T4A slips out the door each February.
GST/HST Filing for Recycling Companies
AFFORDABLE HST filing on taxable sales of recovered material, with inbound treatment determined per supplier type and every input tax credit on equipment and freight recovered.
Tax Planning for Recycling Companies
Planning around the year-end valuation, the timing of processing equipment purchases, the Small Business Deduction and the eventual sale of your shares.
Corporate Catch-Up Filing for Recycling Companies
Overdue T2 and HST years filed, the inventory and inbound records behind them rebuilt, and your corporation returned to good standing with CRA.
CRA Audit Resolution for Recycling Companies
Support when CRA tests your inbound documentation, your inventory valuation or your capital pools, answered properly from the opening letter onward.
CPA Financial Statements (Notice to Reader) for Recycling Companies
CPA-compiled statements a lender accepts, carrying the material on your floor at a value the grade-by-grade schedule behind it can support.
Incorporation Services for Recycling Companies
Incorporation end to end: NUANS, articles and share structure, plus a section 85 rollover moving the yard, the rolling stock and the material on hand across.
Catch-Up Bookkeeping Services for Recycling Companies
Months or years of tickets, settlement sheets, cash payouts and equipment invoices rebuilt and reconciled, so your inventory and your pools are finally accurate.
US Corporation & LLC Tax Filing for Recycling Companies
Cross-border filing where material moves to American consumers or an owner or shareholder is non-resident, covering withholding and T1135 reporting.
Voluntary Disclosure Program for Recycling Companies
Come forward on unrecorded purchases, an unfiled year or HST never remitted before CRA makes contact, so the penalties are cancelled under a Voluntary Disclosures Program application.
Accounting & Tax Services Tailored for Recycling Companies
Practitioner-level CPA work for ferrous and nonferrous yards, plastics and fibre processors, electronics recovery operations and mixed-material facilities across Ontario, built for a business whose balance sheet is mostly material it has bought and not yet sold.
- Your T2 is prepared with GIFI, and we split material purchases, processing wages, outbound freight and sales by commodity family across Schedule 100 and Schedule 125 so the return reads as the trading business it is.
- Material still on the floor at year end is inventory, and ITA 10(1) requires it to be carried at the lower of its cost and its net realizable value, grade by grade rather than as one blended pile.
- Where a grade lost value before your year end, the reduction belongs in that year and is supported by the price evidence at that date; on one file that single entry moved $41,000 of tax into a later year.
- Capital cost allowance runs on Schedule 8 with haul trucks and trailers in Class 10 at 30%, yard equipment and furnishings in Class 8 at 20%, scale systems and computers in Class 50 at 55%, and small tools in Class 12 at 100%.
- When a baler, a loader or a trailer leaves the yard, ITA 13(1) recapture arises to the extent proceeds run past undepreciated capital cost, and a terminal loss is available where the pool closes out below its balance.
- Every inbound load is posted from its own ticket, carrying gross, tare and net weight, the grade assigned, the unit price and the person paid, so cost of sales is built from documents rather than from a weekly bank total.
- Outbound settlements from mills and brokers are matched to the shipment that earned them, including grade and moisture adjustments, because the price agreed on the purchase order is rarely the amount that lands in the account.
- We run a margin report by commodity family after purchase cost, processing wages and haulage, which is the only view that exposes a grade shipping at a loss; one review found $27,000 a year going out that way.
- Freight to the mill or the broker is coded against the shipment it moved rather than parked in overhead, because on lower-value grades haulage is frequently what separates a load that earns from one that does not.
- Purchase tickets, equipment invoices and freight bills go through Dext and are reconciled every month, so the six-year trail under ITA 230 exists in fact and no input tax credit quietly expires unclaimed.
- Whether a sorter, a loader operator or a driver is an employee or in business on their own account is settled on the facts — control, tools, risk of loss and chance of profit — and we record the conclusion before CRA asks.
- T4 slips go to the crew on payroll and T4A slips to those who are genuinely independent, so what you deducted is reported the way CRA expects rather than resting inside an unsupported subcontract total.
- Wagepoint runs the payroll, income tax, CPP and EI come off each cycle, and the PD7A remittance reaches CRA by the fifteenth of the month after; the graduated penalty for paying late tops out at 10%, which on $14,000 is $1,400.
- We register WSIB coverage before the first hire, because a yard running a baler, a shear, a loader and moving trucks is not a place to find out afterwards that the corporation was never covered at all.
- Your T4 slips and the T4 Summary are filed on or before the last day of February, tied to the remittances that were actually made, and we track Ontario remuneration against the $1,000,000 Employer Health Tax exemption before it is crossed.
- Sales of recovered and processed material are taxable supplies carrying 13% HST in Ontario, and the $30,000 small-supplier limit is measured across four consecutive calendar quarters, so a yard that grows mid-year registers then rather than at its next year end.
- Because your output is fully taxable, input tax credits come back in full on processing equipment, rolling stock, freight, yard rent, fuel and repairs, which on a yard replacing a baler is a large recovery in one period.
- Whether HST applies to an inbound purchase, and what you must hold to claim an input tax credit on it, depends on the status of the person selling to you, so we determine and document the treatment supplier type by supplier type.
- A deposit held against a container or roll-off placement only becomes consideration when you apply it, and ETA subsection 168(9) puts the tax at that point rather than at the moment the money was taken.
- We agree the HST reported each period to the sales figures on Schedule 125 before filing, because a yard whose two sets of numbers disagree is easy for CRA matching to pull; one check headed off a $19,300 adjustment.
- We time processing equipment purchases against your fiscal year end, weighing the rate a machine will attract once its use has been determined against the cash a purchase consumes while the market is soft.
- Each year we set how much the owners take as salary and how much as dividends, drawing enough T4 to keep RRSP room growing while the rest comes out as dividends, so combined tax sits nearer 12.2% than 53.53%.
- Active income is held under the $500,000 Small Business Deduction limit, with the associated-corporation rules watched where the same family owns the land beneath the yard; one restructuring preserved $38,000 of the deduction.
- Because the year-end valuation moves taxable income further than any other single entry, we model it in November instead of discovering it in March, and reset instalments onto the figure the ledger will actually produce.
- Two clear years before a sale we start shaping the shares against the ITA 110.6 tests, so the $1.25M Lifetime Capital Gains Exemption is available and the surplus that would fail the asset test has already gone.
- We rebuild sales, purchases and closing inventory for each unfiled year out of bank records, mill settlements and whatever tickets survived, which restores the six-year record base ITA 230 assumes is already there.
- An unfiled T2 draws 5% of the tax owing at the outset and another 1% for each month it remains outstanding, to a ceiling of twelve, so the earliest year is the one we clear first.
- Closing inventory is the hinge of any catch-up: value it wrong in one year and the error walks forward into every year after it, so each year-end figure is set on the price evidence that existed at that date.
- We rebuild the capital pools across the missing years and place each machine on a determination of how it was used, recovering deduction understated in every year it ran; one rebuild restored $58,200 of capital cost allowance.
- Filed on Form RC199 before CRA makes contact, a Voluntary Disclosures Program application removes the penalties outright and carries relief of roughly half the interest on the oldest years, usually the larger number.
- When CRA tests the inbound side, we produce the ticket file load by load, weight in, grade, price, payment and payee, because that trail is what stands behind both your cost of sales and your closing inventory.
- ITA 152(7) provides that CRA is not bound by the information supplied in a return and may assess otherwise than in accordance with it; where that has happened, displacing the assessment falls to the taxpayer, and we build that case.
- When a year-end reduction in carrying value is questioned, we show the grade, the quantity, the cost and the price evidence at the valuation date, so the entry is defended on what was documented and not on hindsight.
- Where a machine’s pool is challenged, we set out how it was actually used across the year, because the classification of processing equipment is a determination on the facts rather than a label asserted on a schedule.
- A Notice of Objection goes in inside the ninety-day window after a reassessment, and we apply for taxpayer relief on Form RC4288 where a predecessor’s error produced the penalties; one objection removed $46,000 of tax and interest.
- A CSRS 4200 compilation engagement covering two fiscal years is what a lender wants before financing a shear, a baler line or the operating room you need to hold material through a soft market.
- The statement of financial position carries the floor at the lower of cost and net realizable value, with a grade-by-grade schedule behind the single number so a lender can see what it is actually lending against.
- Receivables are presented against mill and broker settlement terms, because a yard that pays for material the day it arrives and collects weeks later is financing that gap out of its own working capital.
- The statement of operations separates purchase cost, processing cost and outbound freight from gross sales, so two years read consistently against each other and the figures tie to the T2 already filed with CRA.
- Compiled statements are back with you inside thirty days of the records and the year’s figures arriving, because a credit decision on a baler line will not wait; one set supported a $480,000 equipment facility.
- We incorporate the company so the yard’s liabilities sit inside it and active profit is taxed near the roughly 12.2% Ontario small-business rate instead of a personal rate that reaches 53.53% at the top.
- A section 85 rollover on Form T2057 carries the existing equipment, rolling stock, material on hand and goodwill in at elected amounts, which defers the gain an outright sale would have crystallized; that transfer sheltered $220,000 on one file.
- Opening pools are set from the rollover, trucks and trailers, yard equipment, small tools and scale systems, so the corporation begins with a Schedule 8 that is right rather than reconstructed years later from memory.
- The corporation’s Business Number, HST and payroll accounts are opened inside the first thirty days, and the scale, the banking and the mill accounts move into the corporate name before the first load is bought.
- The chart of accounts is built with inbound tickets, grade-level margin and outbound freight in it from the first week, so the records accumulate in a usable shape instead of being rebuilt at the first year end.
- We rebuild months or years of records from bank activity, mill settlements, purchase tickets and cash payout sheets, so a yard that ran two seasons without bookkeeping finishes with a ledger that reconciles.
- The inventory is rebuilt grade by grade rather than as one figure, because a single blended number cannot be tested, cannot be defended, and cannot be reduced credibly once the market has moved against you.
- The equipment schedule is rebuilt from purchase invoices and each machine placed on a determination of its use, which is almost always wrong when we inherit a yard’s file and almost always worth real money to fix.
- Input tax credits buried in unrecorded equipment, freight and repair invoices are recovered while the window is open, which on a yard that bought a baler or a loader is often five figures; one catch-up returned $23,800.
- Wages and payments to independent operators are tied back to the remittance record and the slips brought up to date, so the caught-up T2 rests on what people were actually paid rather than on an estimate.
- Where material is sold to an American consumer or broker, we review the export rules against what actually moved and the evidence that it left the country, rather than treating a foreign billing address as the answer.
- Dividends paid out of Canada to a non-resident shareholder attract Part XIII withholding, and we set the rate, 25% or whatever a treaty reduces it to, and file the NR4 slips that have to sit behind it.
- Owners whose specified foreign property has a cost amount over $100,000 have to file Form T1135, and the penalty attaches to the missed filing itself, entirely independent of whether any tax was owing on what they held.
- An American shareholder or owner brings US filing duties that reach back into a Canadian corporation, and we run both sides together so the position is settled in advance instead of surfacing years afterwards.
- Both returns are reconciled so the foreign tax credit is genuinely claimed and the same profit is not taxed on both sides of the border; one correction put $18,500 of tax back where it belonged.
- Where purchases were paid for in cash and never recorded, we bring those years forward with a reconstruction of what was bought and from whom, because an unrecorded purchase leaves an unsupported cost of sales behind it.
- Where inventory was never valued and closing figures were simply guessed, we restate each year on ITA 10(1) and disclose the corrected results, which usually moves income between years rather than creating any.
- HST never remitted on sales of processed material is disclosed together with the corrected returns and the tax paid, rather than waiting for the period to be assessed with penalties already attached to it.
- Slips never issued to yard crew or to independent operators are filed with the summaries under the disclosure, so the per-slip penalty is cancelled instead of assessed; one application covered 26 people over two years.
- A thin disclosure gets refused, so we assemble the whole package, narrative, schedules and Form RC199, and stay on the file through every CRA question until it is accepted; one acceptance removed $57,000 in penalties.
Recycling Company Inventory & Tax Check
Six quick questions on your year-end valuation, your inbound ticket trail, your scale reconciliation, your freight costing, how your machines are pooled and whether it is time to incorporate. No fee shown.
1. Is the material in your yard valued at the lower of cost and net realizable value at year end?
2. Does every inbound load leave a ticket showing weight, grade, price and who was paid?
3. Do your weigh-in and weigh-out figures reconcile to inventory, payments out and sales?
4. Is freight to the mill costed against the shipment rather than left sitting in overhead?
5. Has each processing machine been pooled on a determination of how it is actually used?
6. Is your recycling company incorporated?
Free CPA Consultation for Recycling Companies
Case Studies: Recycling Accounting & Tax
Brockville Nonferrous Yard — The Write-Down Nobody Took
The problem: A Brockville yard held roughly 400 tonnes of mixed nonferrous and insulated wire at its December year end. The market had dropped hard through the autumn, and much of that floor was worth materially less than the yard paid at the scale in the summer. The books still carried every grade at cost, so the corporation faced tax on a profit that had already evaporated.
What we did: We rebuilt closing inventory grade by grade from the ticket file, established each grade’s price at the valuation date from published settlements, and applied ITA 10(1) so the floor was carried at the lower of its cost and its net realizable value in the year the fall happened.
The result:
- Closing inventory restated grade by grade
- Tax of $41,000 landed in the correct year
- Price evidence filed with the working papers
Timmins Scrap Processor — An Inbound Trail That Did Not Exist
The problem: A Timmins processor bought heavily from small contractors and from members of the public, paying at the scale and frequently in cash. Nothing about the trade was improper, but the purchase side of the ledger was a weekly cash total copied from a notebook. No record showed what a load weighed, how it graded, what it was paid or who received the money.
What we did: We built a numbered inbound ticket capturing gross, tare and net weight, grade, unit price, total paid and payee, tied each payout to the ticket that caused it, and reconciled weigh-in against weigh-out and sales monthly, keeping the six-year file ITA 230 expects.
The result:
- Every inbound load now leaves a numbered ticket
- Payouts reconcile to tickets and to the scale
- Six-year record file built and maintained
Chatham Plastics Recycler — The Freight Inside the Grade
The problem: A Chatham plastics recycler shipped baled film, HDPE and mixed rigid to four consumers and treated all outbound haulage as overhead. On paper every grade earned. Once freight was loaded onto the shipment that had actually incurred it, one grade turned out to have been shipped at a loss for the better part of two years, and settlements on a second were being cut for moisture with nobody reconciling the deduction to the weight that left.
What we did: We coded freight to the shipment, rebuilt margin by commodity family after purchase cost, processing and haulage, and reconciled every settlement back to the outbound ticket behind it before it was posted.
The result:
- $27,000 a year of loss-making shipments stopped
- Margin now read by commodity family
- Settlements reconciled to outbound weights
Our clear, efficient process ensures every step is transparent, building trust and long-term client relationships.
Kickoff (Document Request)
Collect prior T2 returns, the inbound ticket file, mill and broker settlements, equipment invoices, the closing inventory listing by grade, payroll records, freight bills and bank statements.
First 30 Days (Cleanup & Setup)
Set up QuickBooks Online or Xero against your scale software, rebuild the capital pools on a determination of each machine’s use, and build the grade-level inventory schedule from the ground up.
Monthly Close
Inbound tickets posted, weigh-in reconciled to weigh-out and to payouts, settlements matched to shipments, freight costed to the load, HST filed, and payroll and PD7A reconciled.
Quarterly Planning Review
Salary and dividend mix, equipment purchase timing, margin by grade after freight, a working estimate of where the year-end valuation is heading, and instalments reset onto it.
Year-End Close & T2 Filing
Trial balance, statements with the floor at the lower of cost and net realizable value and the grade schedule behind it, recapture and terminal loss settled, T2 with GIFI, and CRA preparation.
Get Your Recycling Company Taxes Done Right Today
Affordable Pricing for Recycling Companies
We believe in clear, upfront pricing so you know exactly what to expect. All fees include HST.
- Tax Preparation (Corporation) — From $400
- Tax Return Filing (Corporation) — From $400
- Tax Compliance Audit — FREE CRA audit support for our clients
- Tax Strategy — FREE for our clients
- Accounting Base Plan — From $100 per month
- Bookkeeping Management — Free for our Accounting clients
- Financial Reporting — Free for our Accounting clients
- Business Formation — Flat $35
- Incorporation Process — Flat $35
- Entity Setup Assistance — Flat $35
- Full-Service Payroll — From $125 per month
Payment is by Interac e-Transfer to info@gondaliyacpa.ca only. Security question: Not Applicable, as auto-deposit is enabled.
Meet Your Lead Recycling Accountant
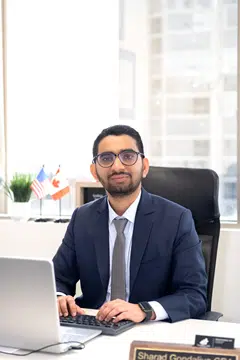
Meet your lead recycling accountant. The same two people handle your inventory, your records and your corporate tax every year, not a different name each spring.
What Our Clients Say
1300+ five-star reviews from yard owners, processors and material traders across Ontario and Canada.
Serving Recycling Companies Across Ontario
Recycling companies right across Ontario work with our CPA team for accounting and tax built around how a yard actually trades. We know how material is bought at the scale, why the floor has to be valued grade by grade, what an inbound ticket has to prove, and where haulage quietly takes a grade’s margin away.
Toronto (ON)
55 Queen St E Ste 1205, Toronto, ON M5C 1R6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Mississauga (ON)
2100 Camilla Rd #716, Mississauga, ON L5A 2J8
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Brampton (ON)
4 Starhill Crescent, Brampton, ON L6R 2P9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Scarborough (ON)
24 Clementine Square, Scarborough, ON M1G 2V7, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Vaughan (ON)
19 Cabinet Crescent, Woodbridge, ON L4L 6H9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Oshawa (ON)
210 Durham St, Oshawa, ON L1J 5R3, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Ottawa (ON)
2090 Neepawa Ave a314, Ottawa, ON K2A 3L6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Etobicoke (ON)
60 Stevenson Rd #1601, Etobicoke, ON M9V 2B4, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Hamilton (ON)
70 Starling Dr, Hamilton, ON L9A 0C5, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Guelph (ON)
1155 Gordon St, Guelph, ON N1L 1S8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Windsor (ON)
4387 Guppy Ct, Windsor, ON N9G 2N8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
North York (ON)
150 Graydon Hall Dr #912, North York, ON M3A 3B2, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Recycling Accounting & Tax FAQs
Related Industries We Serve
Waste Collection Companies
- Fleet and container capital cost allowance
- Deferred revenue on prepaid service
- Corporate tax filing and payroll
Demolition Contractors
- Project job costing and progress billing
- Equipment pools and recapture on disposals
- Corporate tax planning and bookkeeping
Small Businesses
- Owner-manager remuneration each year
- Year-end statements and T2 filing
- Bookkeeping and payroll support
Incorporated Businesses
- T2 returns with GIFI schedules
- Dividend and salary mix planning
- Compilation statements for lenders
Recycling Accounting & Tax Done Right.
T2 filing with the floor carried at the lower of cost and net realizable value under ITA 10(1) and the reduction taken in the year the grade fell, a numbered inbound ticket behind every load so cost of sales and inventory both have something standing behind them, freight costed to the shipment it moved, processing machinery pooled on a determination of its use, haul trucks and trailers in Class 10 at 30% and scale systems in Class 50 at 55%, and yard payroll with WSIB from the first hire. AFFORDABLE flat fees, no hourly billing. Licensed CPA Ontario. 1300+ five-star reviews. 30-Day Money-Back Guarantee.