



Tax Accountant for Environmental Consultants in Ontario and Across Canada
You sell a conclusion, and the conclusion outlives the engagement. The assessment is signed, the fee is collected, the file closes — and a purchaser, a lender or a regulator goes on relying on that document for years afterwards. That is the fact your financial statements have to cope with, and it is why we raise with every practice the question of whether a signed opinion creates an obligation that belongs in the statements, and treat it as a question to answer rather than a conclusion to assume. It is also why professional liability written on a claims-made basis responds to the claim made while the policy is live rather than to the work done while it was live, which makes run-off and tail arrangements a real structuring and deduction question when you retire, sell or change insurer. We bring unbilled work in progress into income because the ITA section 34 election does not reach this practice, split multi-phase assessments into the separately authorised engagements they actually are, and carry laboratory, drilling and disposal recharges at gross. Whether you run phase one and phase two assessments, long-running monitoring programs, remediation oversight or expert review work, we handle the phases, the field costs and the long tail — with AFFORDABLE flat fees.
AFFORDABLE Environmental Consultant Tax Accountant
An environmental practice has a balance sheet problem that most service businesses never face: the thing it sold is still working long after the invoice was paid. A signed assessment or a site condition opinion is relied on by people who were not parties to the engagement, for years, and none of that exposure appears anywhere in the accounts. Whether it should — whether a signed opinion creates an obligation that ought to be provided for in the financial statements — is a real question, and it is one we raise with you and work through on your facts rather than answer for you on a web page. The same long tail explains the insurance. Professional liability in this field is ordinarily written on a claims-made basis, which means the policy that responds is the one in force when the claim is made, not the one that was in force when the work was done. That is why run-off or tail cover becomes the decisive question when a practitioner retires, sells the practice or moves insurer, and why a retired practitioner still paying premiums needs somewhere sensible to deduct them. At Gondaliya CPA, we specialize in phase accounting, work in progress and the long-tail exposure that comes with signing your name, providing AFFORDABLE flat-fee support that keeps you CRA-compliant and stops you paying more tax than you owe.
As an environmental consultants accountant, we work with site assessment practices, hydrogeology and contaminated sites specialists, monitoring and compliance firms, and remediation oversight consultants across Ontario, with year-round support rather than a once-a-year scramble. We tell you what each authorised phase actually earned after laboratory and drilling costs, how much work you have done that nobody has been invoiced for yet, and where your subconsultant exposure sits.
Let us handle the numbers so you can focus on the site, the sampling and the report.
Our Official Partners
Accounting That Understands How an Environmental Consulting Practice Actually Works
Selling a signed opinion is not selling a deliverable that stops mattering on delivery. Your real exposure sits outside the accounts, your cover responds on a claims-made basis rather than to the year the work was done, your engagements arrive in separately authorised phases, and a large part of your cost base is laboratory and drilling work you pay for and recharge. At Gondaliya CPA, we understand that reality and provide practical, industry-focused solutions across Ontario.
Stay Compliant and Minimize Your Environmental Consulting Tax
For an environmental practice, staying onside with CRA and with your regulator and paying the least legal tax are the same job. We keep every filing on schedule while claiming every field, laboratory, instrument and insurance dollar the T2 allows, so nothing is missed and nothing invites a reassessment.
Accounting & Tax Experts for Environmental Consultants
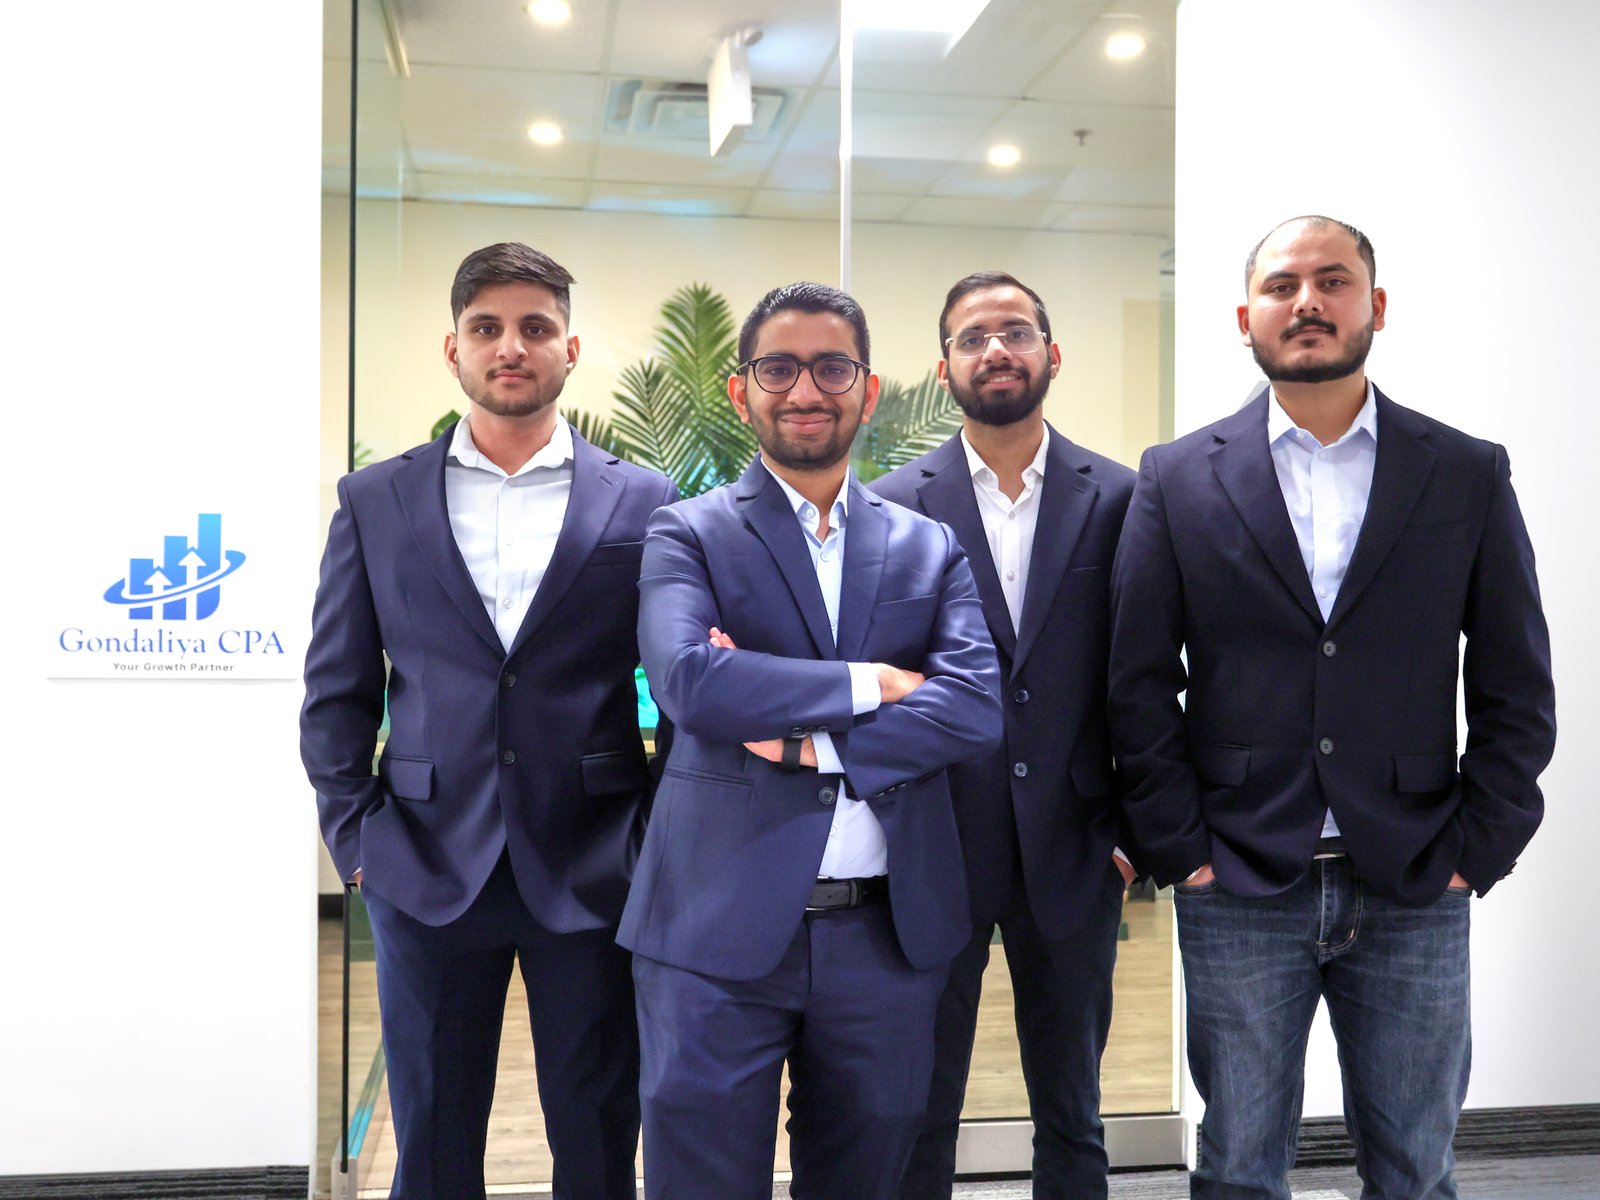
- AFFORDABLE + Registered CPA Firm
- Business and Corporate Tax Expert
- Small & Medium Business Expert
- Accounting, bookkeeping, and tax filing
- CPA (Chartered Professional Accountant)
- 1300+ 5-star Google reviews
- 30-Day Money-Back Guarantee
- 60-Day Fees Matching Policy
Why Choose Our Accounting Services for Environmental Consultants?
Tax Planning — Phases & Pools
We bring unbilled phases into income properly, split Class 8 field instruments from Class 50 workstations, and protect the $500,000 Small Business Deduction on active income.
Consulting — Field Costing & Recoveries
Our bookkeeping costs each authorised phase against the laboratory, drilling and field spend it consumed, and shows what a recharge actually recovered after the work behind it.
CRA Representation — Subcontracts & WIP
When CRA challenges the subcontract line, the work in progress position or your field costs, we prepare the response and pursue relief on Form RC4288 where a prior error caused the penalties.
Bookkeeping — Long Tail & Succession
We build the cash flow that funds field mobilisation before a client pays, produce the statements your lender reads, and raise the run-off and tail question years before you retire.
Google Reviews
Environmental Consultant Clients
Environmental Consultant Tax and Accounting Services in Ontario
Corporate Tax Filing (T2) for Environmental Consultants
Professional T2 preparation with unbilled work in progress brought into income, field instruments in Class 8, workstations in Class 50, and CRA compliance on every line.
Bookkeeping & Accounting for Environmental Consultants
Books built by file and by authorised phase, with laboratory, drilling and disposal costs carried at gross and unbilled work in progress visible every month.
Payroll Services for Environmental Consultants
Field staff and subconsultant payments handled properly, with PD7A remittances, T4 and T4A slips filed on time and classification tested against CRA guide RC4110.
GST/HST Filing for Environmental Consultants
AFFORDABLE HST filing with the place of supply rate set on the client’s address, disbursement recharges analysed under ETA section 178, and credits recovered on your field cost base.
Tax Planning for Environmental Consultants
Smart tax planning on instrument purchases across Class 8 and Class 50, the Small Business Deduction, the personal services business test, and the run-off question at retirement.
Corporate Catch-Up Filing for Environmental Consultants
File overdue T2 and HST years, rebuild the work in progress and capital pools you never had, and get back into CRA compliance with accurate catch-up support.
CRA Audit Resolution for Environmental Consultants
Expert support on subcontractor classification, work in progress and field cost audits, handled with confidence from the first letter.
CPA Financial Statements (Notice to Reader) for Environmental Consultants
CPA-compiled financial statements that lenders accept, stating unbilled work in progress and the receivable ledger honestly rather than burying them in revenue.
Incorporation Services for Environmental Consultants
Full incorporation including NUANS, articles, share structure confirmed with your regulator, and the section 85 rollover of your instruments, vehicles and goodwill.
Catch-Up Bookkeeping Services for Environmental Consultants
Months or years of laboratory invoices, drilling subcontracts, field receipts and billings reconstructed and reconciled, so your revenue figure is finally accurate.
US Corporation & LLC Tax Filing for Environmental Consultants
Cross-border filing where sites, subconsultants, owners or shareholders sit outside Canada, covering withholding, NR4 reporting and T1135 obligations.
Voluntary Disclosure Program for Environmental Consultants
Come forward on unfiled T4A slips, work in progress left out of income or disbursements reported on the wrong basis before CRA calls, cancelling penalties through a Voluntary Disclosures Program application.
Accounting & Tax Services Tailored for Environmental Consultants
Real, practitioner-level CPA expertise for site assessment practices, hydrogeology and contaminated sites specialists, monitoring and compliance firms, and remediation oversight consultants across Ontario — built for a practice whose product is a signed conclusion.
- We prepare your T2 with GIFI on Schedule 100 and Schedule 125, separating phase one assessment fees, phase two investigation work, monitoring program revenue, review engagements and recovered laboratory disbursements onto their correct lines so the return reads properly.
- We bring unbilled work in progress into income at year-end, because the ITA section 34 election names accountants, dentists, lawyers, medical doctors, veterinarians and chiropractors, and an environmental practice is not on that list.
- We claim capital cost allowance on Schedule 8 with field and sampling instruments in Class 8 at 20%, workstations and servers in Class 50 at 55%, and application software in Class 12 at 100%.
- We treat each authorised phase as its own engagement with its own revenue recognition point, so a reconnaissance stage billed in March and an intrusive investigation authorised in November are not collapsed into one contract on your return.
- We record laboratory, drilling and disposal recharges at gross rather than netting them against fees, because a return built on net numbers understates your revenue and your cost base on the very same page.
- We reconcile every laboratory invoice, drilling subcontract and disposal ticket back to the file it belongs to, so each phase carries the cost it actually incurred instead of landing in one undifferentiated field expense account.
- We carry unbilled work in progress on the balance sheet by file and by phase, because a stage worked while the next authorisation is still with the client is real value the books should already show.
- We track field time, mileage, accommodation and away-from-office costs against the engagement that caused them, with the records kept as they are incurred rather than reconstructed from memory when CRA asks for them.
- We run project accounting in Deltek Vantagepoint or BQE Core alongside QuickBooks Online or Xero, so billable hours, subconsultant costs and recovered disbursements reconcile to the general ledger every month instead of once a year.
- We capture laboratory, drilling, rental and insurance invoices through Dext and reconcile monthly, keeping the six years of records ITA section 230 requires and making sure no recoverable input tax credit is quietly lost.
- We test your field technicians, drillers, samplers and subconsultant hydrogeologists against the CRA guide RC4110 factors, because a large subcontract line with no analysis behind it is the first thing a payroll auditor pulls.
- We file T4A slips on the people who are genuinely contractors, so the drilling, sampling and specialist review payments you deducted are reported the way CRA expects rather than sitting inside an unsupported subcontract total.
- We set up staff payroll with income tax, CPP and EI withheld and remitted on the PD7A by the fifteenth of the following month, because CRA’s late-remittance penalty on source deductions reaches 10%.
- Where a subconsultant is a non-resident performing services in Canada, we address Regulation 105 withholding and the T4A-NR reporting that follows, rather than paying the invoice as though the border made no difference at all.
- We file your T4 slips and T4 Summary by the last day of February, reconcile them to the PD7A remittances made, monitor WSIB on field staff, and watch the $1,000,000 Employer Health Tax exemption.
- We file your GST34 returns with environmental consulting treated as the taxable supply it ordinarily is, and the rate set by the place of supply rules on the client’s address rather than on where the site sits.
- We establish whether a laboratory or drilling recharge is made as principal or as agent for the client, because ETA section 178 and the agency analysis decide it and the retainer wording is where the answer lives.
- We do not assume that answer runs one way across your files: it is reached engagement by engagement on what the agreement actually says, documented in writing, and revisited whenever your standard retainer changes.
- We recover the input tax credits sitting in analytical fees, drilling subcontracts, equipment rental, disposal costs and software, which on a practice with a heavy pass-through cost base is a meaningful amount every single quarter.
- Where any part of your revenue is not uniform in treatment, we allocate input tax credits under ETA section 141.01 on a method we can defend, instead of claiming everything and waiting for a reviewer to disagree.
- We time instrument and vehicle purchases against your fiscal year-end, weighing the 20% Class 8 rate on sampling and monitoring equipment against the 55% Class 50 rate on workstations, so the deduction lands where it is worth most.
- We set the salary-versus-dividend mix for the owner, paying enough T4 salary to build RRSP room while the balance flows as dividends, so combined tax stays near the 12.2% Ontario small-business rate instead of 53.53%.
- We keep active income under the $500,000 Small Business Deduction limit using ITA section 125, and watch the associated-corporation rules where the same owner also holds a drilling company or a separate remediation contracting entity.
- Where you bill a single client through your corporation on their site and their schedule, we work through the ITA subsection 125(7) personal services business test with you on the facts, and we do not assume the conclusion.
- We plan at least two years ahead so your shares qualify for the $1.25M Lifetime Capital Gains Exemption under ITA 110.6, purifying retained cash that would otherwise fail the active-business asset test at the wrong moment.
- We reconstruct assessment fees, monitoring revenue, review engagements and recovered disbursements from project records, invoices and bank deposits across your unfiled years, rebuilding the six years of records ITA section 230 requires.
- Late filing costs 5% of the balance owing plus 1% per month up to twelve months, so we file your oldest unfiled T2 first to stop the penalty compounding and limit the arrears interest CRA charges.
- We rebuild the work in progress position year by year, because a catch-up filing that ignored unbilled phases understates income in the years the work was done and overstates it in the year the invoice finally went out.
- We rebuild the capital pools across the missing years and move field instruments, meters and pumps out of Class 50 into Class 8 and computers the other way, recovering deduction that was misstated in every year it ran.
- We file a Voluntary Disclosures Program application on Form RC199 before CRA contacts you, because a disclosure accepted under the general program cancels penalties in full and gives roughly 50% interest relief on the older years.
- When CRA questions your subcontract line, we produce the agreements, invoices and CRA guide RC4110 analysis for each driller, sampler and specialist reviewer, because that line is where an environmental consulting audit almost always begins.
- When CRA tests your revenue against billings, we show the work in progress reconciliation by file and phase, because unbilled work has always been income for a practice the ITA section 34 election does not reach.
- When CRA reviews field, travel and vehicle costs, we produce the trip records, the engagement each cost was charged to and the treatment of the food and beverage portion under ITA section 67.1, with no rate assumed.
- When CRA opens a full audit, we manage the file and answer the revenue, credit and payroll queries inside the deadlines, so a one-year review does not expand across the three prior years CRA is able to reopen.
- We file the Notice of Objection within 90 days of a reassessment and pursue taxpayer relief on Form RC4288 where a prior accountant’s error caused the penalties, protecting your Tax Court rights while the file is open.
- We prepare the CSRS 4200 compilation engagement financial statements a lender requires across two fiscal years for the operating line that funds field mobilisation, laboratory costs and payroll before the client’s invoice is paid.
- Your compiled statement of financial position shows unbilled work in progress and the receivable ledger honestly, because a practice whose assets are people, instruments and a ledger is read on exactly those two lines.
- We raise with you the question of whether a signed assessment or site condition opinion creates an obligation that should be provided for in the statements, and we treat it as a question to answer rather than a conclusion to assume.
- We build the statement of operations with assessment fees, monitoring revenue, review work and recovered disbursements classified consistently across two years and tied to the T2 filed with CRA, so the bank accepts the file.
- We deliver the compiled statements within 30 days of receiving your records and the year’s T2 figures, because a financing decision ahead of a field season does not wait for a slow accountant to catch up.
- We incorporate your practice under the Ontario Business Corporations Act and confirm with your regulator what form of entity and share ownership is open to you, because that is a regulator question rather than an accounting one.
- We complete the section 85 rollover on Form T2057, transferring your existing instruments, vehicles, client list and goodwill into the corporation at elected amounts, deferring the capital gain a straight sale would otherwise trigger.
- We set the opening Class 8, Class 50, Class 12, Class 10 and Class 14.1 schedules from the rollover, so the corporation starts with an asset base that is correct rather than rebuilt from memory years later.
- We open the corporation’s CRA Business Number, HST and payroll accounts within the first 30 days and move your billing, insurance and laboratory accounts across, so the revenue lands in the entity that has to report it.
- We set the chart of accounts with phase revenue, unbilled work in progress, recovered disbursements, field costs and the professional liability premium built in from day one, so the records accumulate correctly instead of being rebuilt.
- We rebuild months or years of neglected books from project files, laboratory invoices, drilling subcontracts, bank statements and credit card records, so a practice that ran two field seasons without bookkeeping finally gets a ledger that ties.
- We unwind netted disbursements back into gross fees and gross laboratory, drilling and disposal costs across the whole backlog, which is the single correction that changes both your revenue figure and every cost line behind it.
- We rebuild the equipment schedule from purchase invoices and split it across Class 8, Class 50, Class 12 and Class 10, which is almost always pooled incorrectly when we inherit an environmental consulting file from another firm.
- We recover the input tax credits buried in unentered laboratory, drilling, rental, disposal and software invoices, because two years of unposted purchases on a pass-through cost base can hide five figures of recoverable tax.
- We reconstruct the unbilled work in progress balance at each year-end across the caught-up months, so an accurate T2 can be filed without guessing how much of the work done had never been invoiced.
- Where you assess a site outside Canada or work for a foreign parent, we review the place of supply and export rules against what was actually supplied and to whom, rather than treating a foreign billing address as the answer.
- Where a non-resident laboratory, driller or specialist performs services in Canada, we address the Regulation 105 withholding question and the treaty position separately, and we assert no rate, waiver or outcome for any particular payment.
- Where a non-resident owns shares in your company, we handle the Part XIII withholding on dividends paid out of Canada and the NR4 reporting that follows, so nothing is missed at 25% or at the treaty rate.
- We file Form T1135 where the owners’ foreign property costs more than $100,000, avoiding a penalty regime CRA applies whether or not any tax was actually owing on the holding itself in that year.
- We record foreign-currency fees and laboratory invoices at the rate on the transaction date and coordinate the Canadian and United States returns where a shareholder is a US citizen, because those obligations reach into a Canadian corporation.
- We bring your company forward on drilling, sampling and specialist payments made for years with no T4A slips filed, because the per-slip penalties and the classification exposure both sit behind that one subcontract line.
- We disclose unbilled work in progress left out of income year after year, correcting the position before a reviewer finds the same gap and assesses penalties and interest on every open year at once.
- We file your submission on Form RC199 with a full reconstruction from project files, laboratory invoices, billing records and bank statements, so a practice that outgrew its bookkeeping is not left facing an arbitrary CRA assessment.
- We correct disbursement recharges reported on a basis the retainer never supported, and we document the principal or agent analysis under ETA section 178 going forward so the same correction is not needed twice.
- We confirm your disclosure is genuinely voluntary before CRA contacts you, the single condition that makes it valid, and secure the roughly 50% interest relief on the older years, turning a prosecution risk into a managed correction.
Environmental Consultant Tax & Work in Progress Check
Six quick questions on your unbilled work in progress, your phase authorisations, your disbursement recharges, your capital pools, your subconsultant reporting and whether it is time to incorporate. No fee shown.
1. Is unbilled work in progress brought into income at every year-end?
2. Is each authorised phase tracked as its own engagement with its own revenue point?
3. Are laboratory and drilling recharges recorded at gross rather than netted off fees?
4. Are field instruments in Class 8 and computers in Class 50 rather than pooled together?
5. Are subconsultant payments supported by slips and non-resident reporting?
6. Is your environmental consulting practice incorporated?
Free CPA Consultation for Environmental Consultants
Case Studies: Environmental Consultant Accounting & Tax
Toronto Site Assessment Practice — The Phase Nobody Had Invoiced
The problem: A Toronto practice ran assessments in stages, and the intrusive stage on three large files had been started as soon as the client verbally approved it, weeks before the written authorisation and the invoice followed. At the December year-end, none of that work appeared anywhere. The prior accountant had left work in progress out of income entirely, on the understanding that unbilled time is not income until it is billed, which is not the position for a practice the ITA section 34 election does not name.
What we did: We rebuilt work in progress file by file and phase by phase from timesheets, field notes and subcontract records, brought the unbilled balance into income at each year-end, restated the prior year on the same basis, and put a monthly work in progress report in place so the balance is visible rather than discovered.
The result:
- $284,000 of unbilled work in progress brought onto the balance sheet
- Two prior years restated voluntarily before any CRA contact
- Work in progress now reported monthly by file and phase
Mississauga Contaminated Sites Consultancy — Recharges Netted Into Nothing
The problem: A Mississauga consultancy paid the analytical laboratory, the drilling subcontractor and the disposal carrier directly, then recharged the cost to the client on the next invoice. The bookkeeping netted every recharge against the fee, so gross revenue and the entire pass-through cost base vanished into a single number. Nobody could say what a phase two investigation earned, the HST returns were filed off the netted figure, and the retainer wording had never been read to establish whether the practice was acting as principal or as agent on those recharges.
What we did: We read the standard retainer, established the principal or agent basis engagement by engagement under ETA section 178 and documented the reasoning, rebuilt the ledger with gross fees and gross laboratory, drilling and disposal costs, corrected the prior HST returns, and recovered the input tax credits that had been lost inside the netted amounts.
The result:
- $47,800 of previously unclaimed input tax credits recovered
- Gross fees and pass-through costs visible by phase for the first time
- Disbursement basis documented in writing for every retainer type
Ottawa Monitoring and Compliance Firm — Instruments Pooled With Laptops
The problem: An Ottawa firm had bought water quality meters, interface probes, sampling pumps, data loggers and a field trailer over six years, alongside the usual workstations and modelling software. Every one of those purchases had been dropped into a single capital pool, and some had simply been expensed on the year they were bought with no analysis at all. The retiring founder also had a separate problem nobody had raised: premiums on cover written on a claims-made basis, and no plan for where a run-off arrangement would be paid from or deducted.
What we did: We rebuilt the capital schedule from purchase invoices and split it across Class 8, Class 50, Class 12 and Class 10, amended the open years, and put the run-off and tail question in front of the founder and the insurer years before the succession date, with the deduction location decided deliberately rather than discovered afterwards.
The result:
- Six years of equipment purchases correctly classified by pool
- $19,600 of understated capital cost allowance recovered on open years
- Run-off and tail planning started ahead of the succession, not after
Our clear, efficient process ensures every step is transparent, building trust and long-term client relationships.
Kickoff (Document Request)
Collect prior T2 returns, the open project list with phase authorisations, timesheets and work in progress, laboratory and drilling invoices, subconsultant agreements, your standard retainer and disbursement terms, the insurance schedule, and bank statements.
First 30 Days (Cleanup & Setup)
Set up QuickBooks Online or Xero with Dext alongside your project accounting, establish the principal or agent basis of disbursement recharges, rebuild the Class 8, 50, 12, 10 and 13 schedules, and run the RC4110 analysis.
Monthly Close
Work in progress updated by file and phase, laboratory and drilling costs matched to the engagement that incurred them, field and travel records reviewed, GST34 filed with credits recovered, and subconsultant reporting reconciled.
Quarterly Planning Review
Salary and dividend mix, instrument purchases across Class 8 and Class 50, the personal services business test where one client dominates, non-resident subconsultant reporting, and the run-off and tail question against your succession horizon.
Year-End Close & T2 Filing
Trial balance, financial statements with unbilled work in progress stated honestly and the provision question raised on your facts, capital pools settled, T2 with GIFI, and CRA preparation.
Get Your Environmental Consulting Taxes Done Right Today
Affordable Pricing for Environmental Consultants
We believe in clear, upfront pricing so you know exactly what to expect. All fees include HST.
- Tax Preparation (Corporation) — From $400
- Tax Return Filing (Corporation) — From $400
- Tax Compliance Audit — FREE CRA audit support for our clients
- Tax Strategy — FREE for our clients
- Accounting Base Plan — From $100 per month
- Bookkeeping Management — Free for our Accounting clients
- Financial Reporting — Free for our Accounting clients
- Business Formation — Flat $35
- Incorporation Process — Flat $35
- Entity Setup Assistance — Flat $35
- Full-Service Payroll — From $125 per month
Payment is by Interac e-Transfer to info@gondaliyacpa.ca only. Security question: Not Applicable, as auto-deposit is enabled.
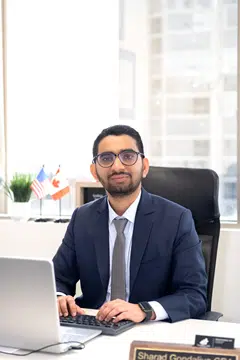
Meet Your Lead Environmental Consultant Accountant
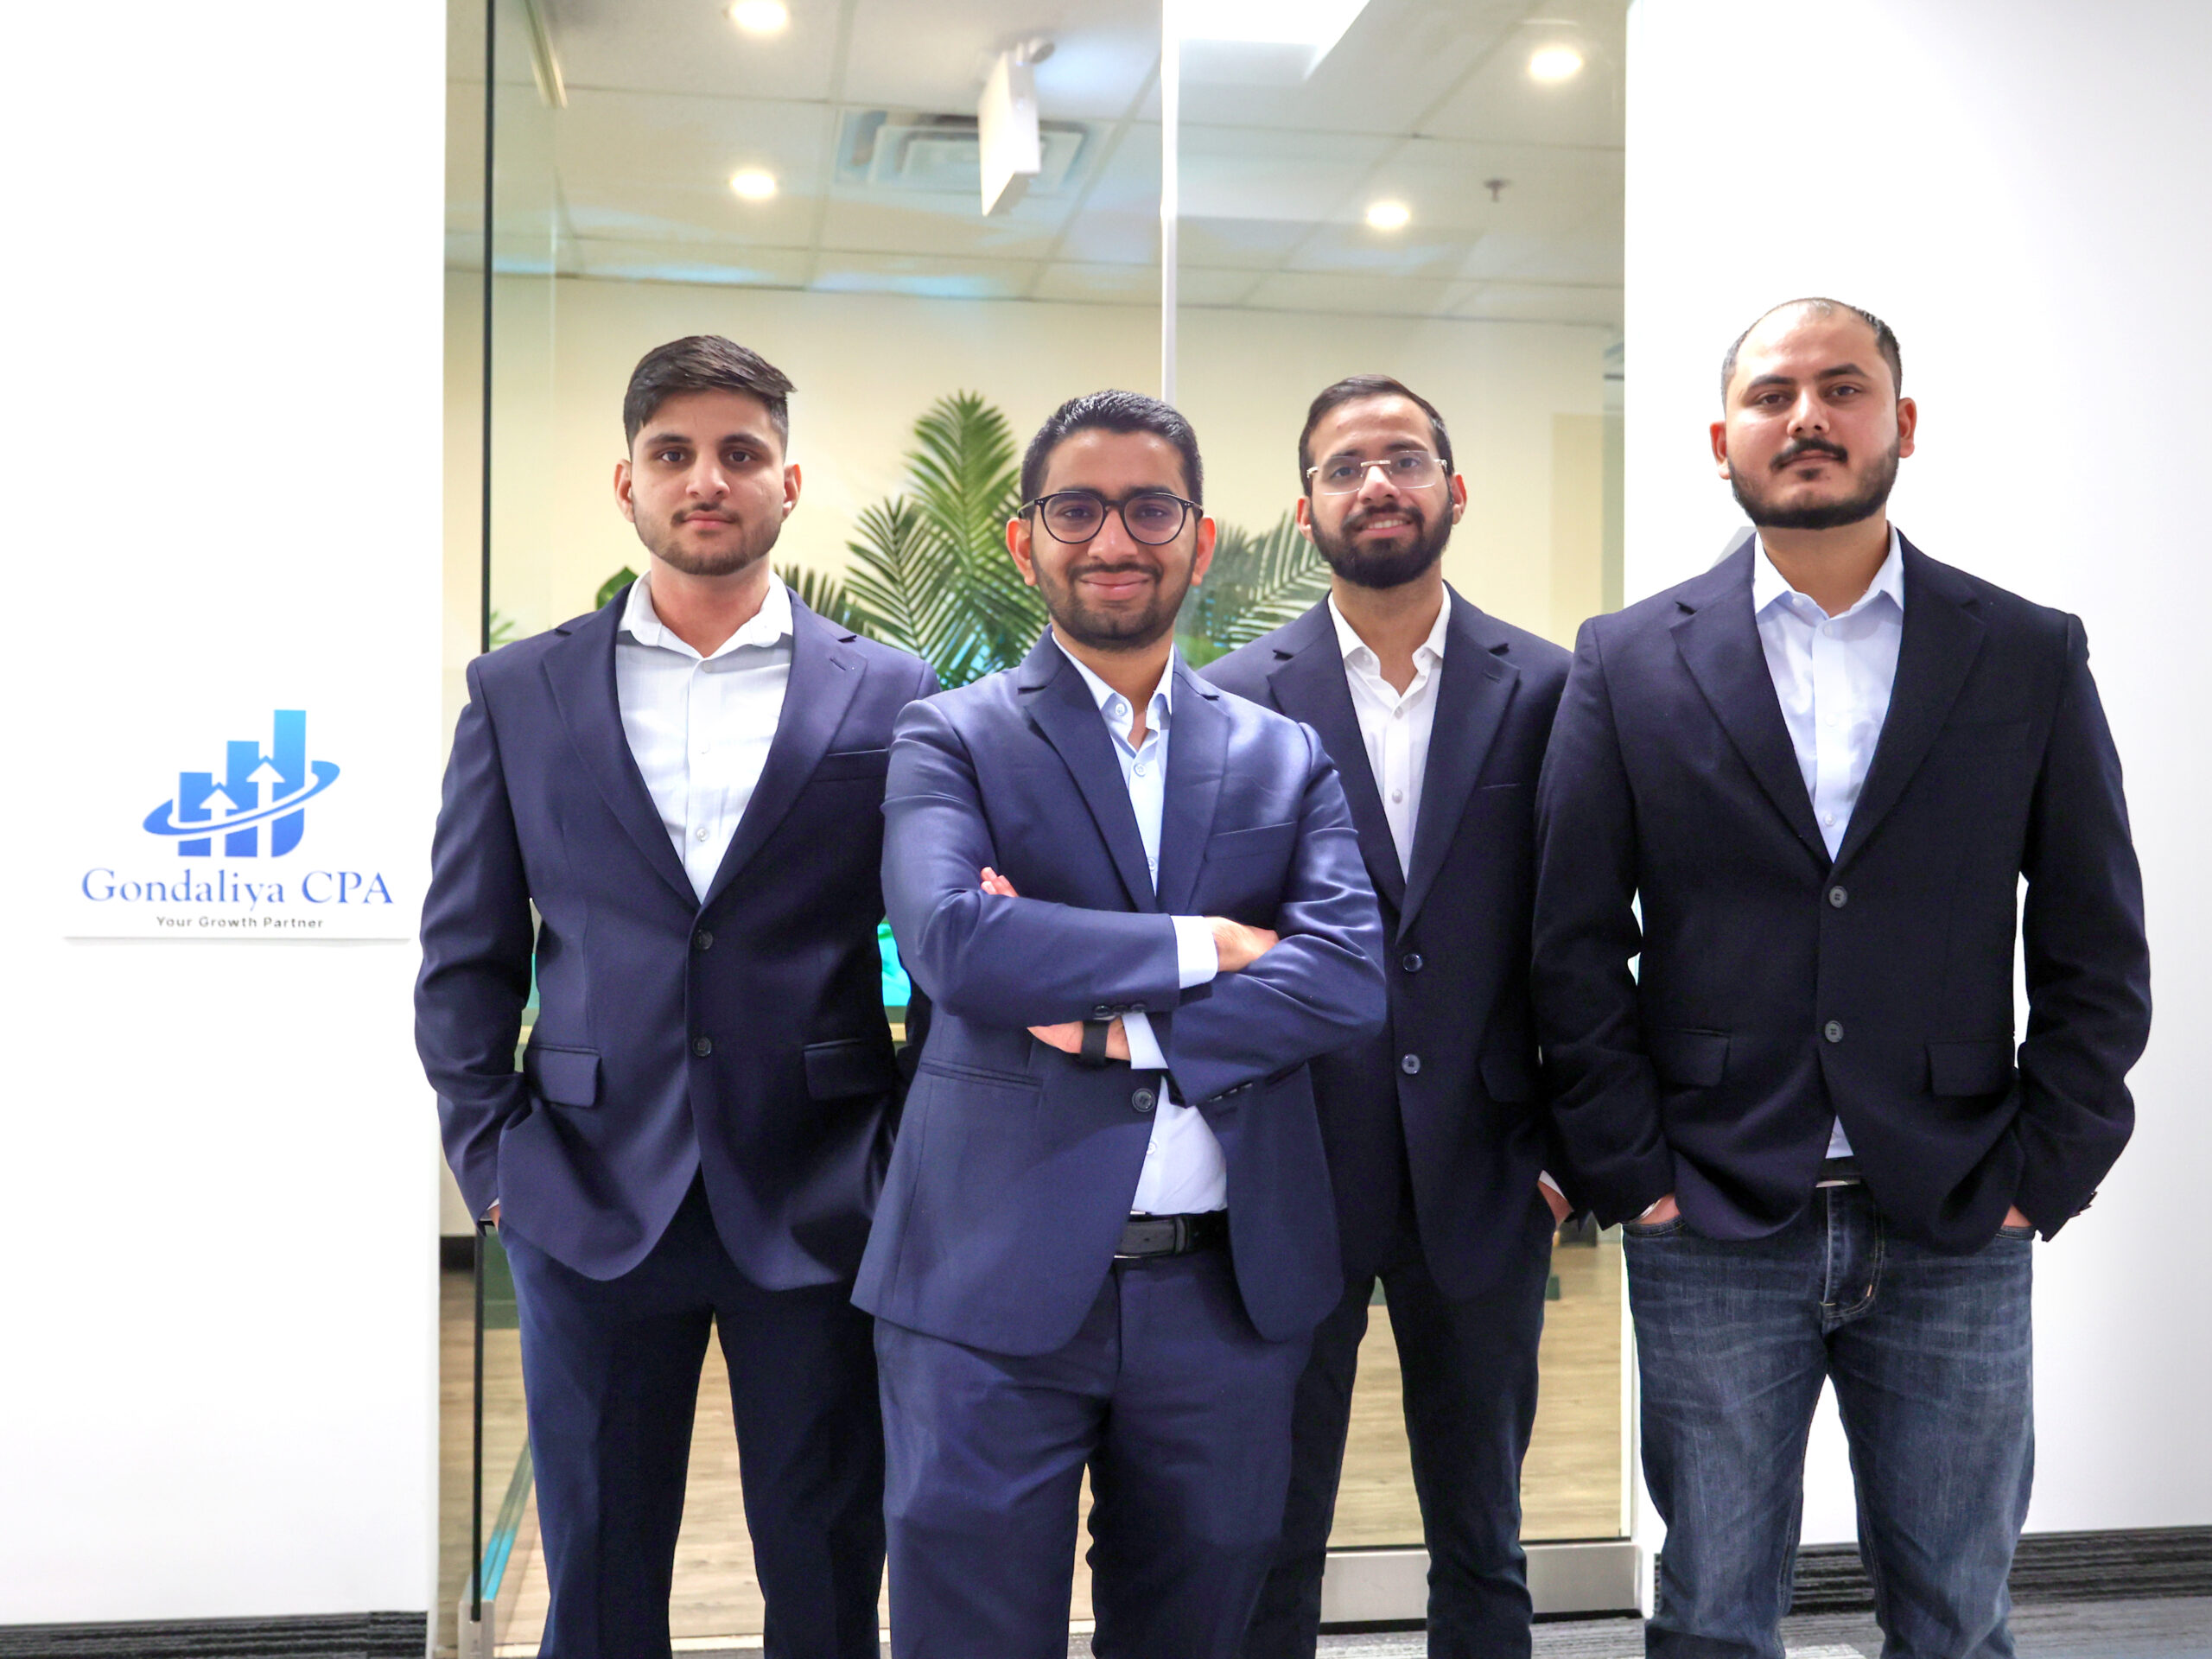
Meet your lead environmental consultant accountant. As your consulting practice and corporate tax adviser, you deal with the same two people every year.
What Our Clients Say
1300+ five-star reviews from environmental consultants, engineering practices and professional service firms across Ontario and Canada.
Serving Environmental Consultants Across Ontario
Our CPA team provides specialized accounting and tax solutions for environmental consultants, site assessment practices and monitoring firms throughout Ontario. We understand why a signed opinion keeps mattering long after the file closes, why cover written on a claims-made basis makes run-off a real question, how a multi-phase assessment earns revenue phase by phase, and what CRA looks at first when it opens an environmental consulting file.
Toronto (ON)
55 Queen St E Ste 1205, Toronto, ON M5C 1R6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Mississauga (ON)
2100 Camilla Rd #716, Mississauga, ON L5A 2J8
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Brampton (ON)
4 Starhill Crescent, Brampton, ON L6R 2P9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Scarborough (ON)
24 Clementine Square, Scarborough, ON M1G 2V7, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Vaughan (ON)
19 Cabinet Crescent, Woodbridge, ON L4L 6H9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Oshawa (ON)
210 Durham St, Oshawa, ON L1J 5R3, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Ottawa (ON)
2090 Neepawa Ave a314, Ottawa, ON K2A 3L6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Etobicoke (ON)
60 Stevenson Rd #1601, Etobicoke, ON M9V 2B4, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Hamilton (ON)
70 Starling Dr, Hamilton, ON L9A 0C5, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Guelph (ON)
1155 Gordon St, Guelph, ON N1L 1S8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Windsor (ON)
4387 Guppy Ct, Windsor, ON N9G 2N8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
North York (ON)
150 Graydon Hall Dr #912, North York, ON M3A 3B2, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Environmental Consultant Accounting & Tax FAQs
Related Industries We Serve
Accountant for Recycling Companies
- Disposal and haulage cost tracking
- Equipment pools and capital planning
- Corporate tax filing and statements
Accountant for Tree Service Companies
- Field crew payroll and WSIB
- Equipment and vehicle CCA pools
- Corporate tax planning and bookkeeping
Accountant for Forestry Companies
- Subcontractor classification and slips
- Seasonal cash flow and financing
- Corporate tax filing and statements
Accountant for Oil and Gas Companies
- Field and site cost allocation
- Capital pools and asset schedules
- Corporate tax planning and advisory
Environmental Consultant Accounting & Tax Done Right.
Unbilled work in progress brought into income because the ITA section 34 election does not reach this practice, each authorised phase accounted for as its own engagement, laboratory and drilling recharges carried at gross with the principal or agent basis established under ETA section 178, input tax credits recovered on a heavy field cost base and allocated under ETA section 141.01 where treatment is not uniform, field instruments in Class 8 at 20% instead of pooled with Class 50 workstations, subconsultant payments tested on CRA guide RC4110 and reported on T4A, and the long-tail questions — whether a signed opinion belongs in your provisions, and what run-off looks like when you retire — raised early and worked through on your facts. AFFORDABLE flat fees, no hourly billing. Licensed CPA Ontario. 1300+ five-star reviews. 30-Day Money-Back Guarantee.