



Tax Accountant for Motorcycle Dealers in Ontario and Across Canada
We carry the bikes on your floor as section 10 inventory at the lower of cost and fair market value rather than depreciable property, deduct floor plan interest as it is incurred and reconcile the payable to the units every month, charge HST on the net consideration after the trade credit where a trade comes from a customer who is not a registrant under subsection 153(4), apportion your input tax credits because financing and insurance commissions are exempt financial services under Schedule V Part VII, match manufacturer holdbacks and factory incentives under paragraph 12(1)(x), and defer extended warranty income with the paragraph 20(1)(m) reserve. Whether you sell cruisers, sport bikes, touring machines and scooters, run a used-bike lot, take bikes on consignment or operate a full sales, parts, riding apparel and service store, we handle the inventory, HST and payroll accounting and plan for a selling season that runs roughly April to September against twelve months of carrying cost — with AFFORDABLE flat fees.
AFFORDABLE Motorcycle Dealer Tax Accountant
A motorcycle dealership is three businesses under one roof — a high-value retailer, a parts, accessory and riding apparel store with a service shop behind it, and a finance office — and the tax result turns on how each one is accounted for. The bikes on your floor are inventory under section 10 of the Income Tax Act at the lower of cost and fair market value, never depreciable property, so no capital cost allowance is claimed on stock; only a bike genuinely taken into use as a demonstrator or a service and delivery vehicle moves into a capital cost allowance class. Floor plan financing interest is deductible when incurred, curtailment payments reduce the payable rather than the expense line, and that payable has to be reconciled to the units on the floor every month or the balance sheet drifts. On the sales floor, where a used bike is taken in trade from a customer who is not a registrant, HST applies to the net consideration after the trade credit under subsection 153(4) of the Excise Tax Act, and selling a bike on consignment for a non-registrant owner engages the agency rules in section 177, where you are generally deemed to have made the supply and account for tax on the full selling price. In the finance office, commissions for arranging financing and insurance commissions are exempt financial services under Schedule V Part VII, which makes your dealership a mixed supplier that must apportion input tax credits rather than claim them in full. That is why you need a specialist who knows the trade. At Gondaliya CPA, we specialize in unit inventory and floor plan accounting, trade-in and consignment HST, finance office apportionment and corporate tax planning for motorcycle dealerships, providing AFFORDABLE flat-fee support that keeps you CRA-compliant and stops you paying more tax than you owe.
As a motorcycle dealership accountant, we work with franchised cruiser, sport bike and touring dealers, scooter retailers, used-bike lots, consignment sellers, vintage bike specialists and full sales, parts, apparel and service stores across Ontario, with year-round support rather than a once-a-year scramble. We tell you plainly what you can deduct, what you cannot, and where the real margin sits on each department and each deal through a selling season that only runs about six months.
Let us handle the numbers so you can focus on the work that actually pays you.
Our Official Partners
Accounting That Understands How a Motorcycle Dealership Actually Works
Running a motorcycle dealership comes with financial pressures a desk-bound business never faces. Your money is tied up in bikes that are inventory rather than depreciable property, financed on a floor plan whose interest and curtailment payments are handled separately, sold on deals that often include a trade or a consignment unit, and supported by a parts counter, a riding apparel wall, a service shop, a winter storage program and a finance office that each carry a different tax treatment — all against a selling season that runs roughly April to September. At Gondaliya CPA, we understand that reality and provide practical, trade-focused solutions across the GTA and all of Ontario.
Stay Compliant and Minimize Your Motorcycle Dealership Tax
For a motorcycle dealership, staying onside with CRA and WSIB and paying the least legal tax are the same job. We keep every filing on schedule while claiming every inventory, floor plan and capital cost allowance dollar the T2 allows, so nothing is missed and nothing invites a reassessment.
Accounting & Tax Experts for Motorcycle Dealers
- AFFORDABLE + Registered CPA Firm
- Business and Corporate Tax Expert
- Small & Medium Business Expert
- Accounting, bookkeeping, and tax filing
- CPA (Chartered Professional Accountant)
- 1300+ 5-star Google reviews
- 30-Day Money-Back Guarantee
- 60-Day Fees Matching Policy
Why Choose Our Accounting Services for Motorcycle Dealers?
Tax Planning — Inventory & Floor Plan Expertise
We know the trade: bikes carried as section 10 inventory rather than depreciable property, floor plan interest deducted as incurred, Class 10 service and delivery vehicles at 30%, Class 8 shop and showroom equipment at 20%, Class 13 leasehold improvements and the Class 1 building. We time equipment purchases and protect the $500,000 Small Business Deduction at the 12.2% Ontario rate.
Consulting — Trade-In, Consignment & Finance Office HST
Our bookkeeping charges 13% on bikes, parts, apparel, service and storage, applies subsection 153(4) to trades taken from customers who are not registrants, handles consignment sales under the section 177 agency rules, and apportions input tax credits against exempt financing and insurance commission income. We department your books so every margin is visible.
CRA Representation — Inventory & Trade-In Audit
When CRA reviews your inventory valuation, your capital cost allowance schedule, your trade-in billing or your input tax credit apportionment, we prepare the response from the deal jackets and the dealer management system, reconcile WSIB, and pursue relief on Form RC4288 where penalties came from a prior error.
Bookkeeping — Payroll, Holdbacks & Sale
We run technician and salesperson payroll with WSIB and Employer Health Tax, match manufacturer holdbacks and factory incentives under paragraph 12(1)(x), defer extended warranty income with the 20(1)(m) reserve, and get you ready to sell the dealership when the time comes.
Google Reviews
Motorcycle Dealer Clients
Motorcycle Dealer Tax and Accounting Services in Ontario
Corporate Tax Filing (T2) for Motorcycle Dealers
Professional T2 preparation with section 10 bike inventory, no capital cost allowance on stock, Schedule 8 for your service vehicles, shop equipment and building, and CRA compliance on every line.
Bookkeeping & Accounting for Motorcycle Dealers
Bike, parts, apparel, service and storage departments, floor plan reconciliation, holdback and warranty tracking with financial statements, clean records and monthly reporting built for a dealership.
Payroll Services for Motorcycle Dealers
Technician, service advisor and salesperson payroll with WSIB, PD7A remittances, T4s with box 42 commissions, and Employer Health Tax once payroll passes the $1 million exemption.
GST/HST Filing for Motorcycle Dealers
AFFORDABLE HST filing at 13% on bikes, parts, apparel, service and storage, with subsection 153(4) trade-in netting, section 177 consignment sales and input tax credit apportionment, matched to your T2 to avoid CRA penalties.
Tax Planning for Motorcycle Dealers
Smart tax planning to protect the Small Business Deduction, time equipment purchases, plan the 20(1)(m) warranty reserve and holdback timing, and set salary, dividends and the eventual sale.
Corporate Catch-Up Filing for Motorcycle Dealers
File overdue T2 and HST years, rebuild missing bike inventory, floor plan and deal records, and get back into CRA compliance with accurate catch-up support.
CRA Audit Resolution for Motorcycle Dealers
Expert support for inventory valuation, trade-in HST, consignment and input tax credit apportionment audits, with deal-jacket and floor plan reviews handled with confidence.
CPA Financial Statements (Notice to Reader) for Motorcycle Dealers
CPA-compiled financial statements that floor plan lenders and banks accept for your dealership corporation.
Incorporation Services for Motorcycle Dealers
Full incorporation including NUANS, articles, share structure, and the section 85 rollover of your bike inventory, shop equipment and goodwill from your unincorporated business.
Catch-Up Bookkeeping Services for Motorcycle Dealers
We rebuild months of missing deal, bike inventory, floor plan, holdback and service-ticket records so your dealership books are current and CRA-ready.
US Corporation & LLC Tax Filing for Motorcycle Dealers
Cross-border filing for dealers sourcing bikes in the United States or holding a US selling entity, covering 1120 and treaty-based 1120-F returns, Form 5472 reporting and state obligations.
Voluntary Disclosure Program for Motorcycle Dealers
We file a VDP disclosure to correct trade-in HST billed on the gross price, unreported holdbacks, unapportioned input tax credits or unfiled T2 years before CRA contacts you, cancelling penalties and reducing interest.
Accounting & Tax Services Tailored for Motorcycle Dealers
Real, practitioner-level CPA expertise for franchised cruiser, sport bike and touring dealers, scooter retailers, used-bike lots, consignment sellers and full sales, parts, apparel and service stores across Ontario — built for how a dealership actually runs.
- We prepare your T2 with GIFI on Schedule 100 and Schedule 125, splitting new bike sales, used bike sales, parts, riding apparel, service labour and storage revenue in QuickBooks Online so CRA’s automated matching never flags the return.
- We carry the bikes on your floor as section 10 inventory at the lower of cost and fair market value, never as depreciable property, because CRA disallows every dollar of capital cost allowance claimed on stock; one correction reversed $46,000.
- We claim capital cost allowance on Schedule 8 for Class 10 service and delivery vehicles at 30 percent, Class 8 shop and showroom equipment at 20 percent, Class 13 leasehold improvements and the Class 1 building; one reclassified van added $10,500.
- We report manufacturer holdbacks, rebates and co-op advertising credits under paragraph 12(1)(x) in the year each amount becomes receivable, tracked in Xero, because CRA matches factory statements to the return; one file moved $58,000 into the correct year.
- We deduct floor plan interest when it is incurred and take the paragraph 20(1)(m) reserve on the unexpired term of extended warranty contracts in QuickBooks, so CRA cannot tax that income years early; one dealer deferred $84,000 correctly.
- We department your books in QuickBooks Online so new bike sales, used bikes, parts and accessories, riding apparel, service labour and winter storage each carry their own margin, because a single sales account hides where the dealership actually earns.
- We reconcile the floor plan payable to the units physically on the floor every month and post curtailment payments against the balance rather than to interest expense; one cleanup tied out a $900,000 payable and corrected the interest deduction.
- We post every deal from the jacket with the trade allowance, the net consideration, freight and pre-delivery inspection recovery and the finance reserve shown separately, so the HST return ties to the dealer management system line by line.
- We book exempt financing and insurance commission income to its own account in Xero so the input tax credit apportionment has a defensible base; on one file we apportioned credits against $220,000 of exempt commission before CRA asked.
- We run receipt capture through Dext, code parts, shop supplies, freight and apparel purchases to the department that bought them, and issue monthly statements your floor plan lender accepts without a follow-up request each quarter.
- We run technician, service advisor and salesperson payroll in Wagepoint, remit source deductions on the PD7A by the due date and reconcile the remittance account monthly, because CRA charges a penalty on every late payroll remittance.
- We report sales commissions in box 42 of the T4 and handle chargebacks when a financed deal unwinds, so a salesperson’s reported income matches what the dealership actually paid across the riding season.
- We reconcile WSIB premiums to actual shop and showroom wages each quarter rather than to a rough estimate, so the annual reconciliation produces no surprise; one dealership recovered $5,300 of premiums overpaid on misclassified staff.
- We monitor Ontario Employer Health Tax as payroll approaches the $1 million exemption, register the corporation once it is exceeded and file the annual return, since a missed EHT account is an easy provincial assessment.
- We issue records of employment when seasonal sales and detailing help finish at the end of the riding season, keeping the dealership onside with Service Canada while winter payroll drops back to a core year-round crew.
- We charge 13% on new and used bike sales, parts and accessories, riding apparel, service labour and winter storage, and recover the tax paid on taxable inputs as input tax credits on line 108 of the return.
- We apply subsection 153(4) so a trade taken from a customer who is not a registrant reduces the consideration by the trade credit; correcting one dealership’s billing across sixty deals recovered $38,000 of over-remitted tax.
- We handle a bike sold on consignment for a non-registrant owner under the section 177 agency rules, remitting tax on the full selling price and paying the owner the agreed net, because the deemed supply is yours.
- We document a fair and reasonable apportionment method for input tax credits, since financing and insurance commissions are exempt financial services under Schedule V Part VII and make the dealership a mixed supplier that CRA reviews closely.
- We reconcile every HST return to the general ledger and to the revenue reported on Schedule 125 before filing, because a mismatch between the two filings is one of the fastest ways to attract a CRA query.
- We protect the $500,000 Small Business Deduction at the roughly 12.2% Ontario combined rate and set the salary and dividend mix for the owners, modelling both against the corporation’s actual seasonal cash flow.
- We time shop equipment, lift and diagnostic tool purchases so the capital cost allowance claim starts in the year it helps, using Class 8 at 20 percent and Class 10 at 30 percent for service and delivery vehicles.
- We plan the paragraph 20(1)(m) reserve on extended warranty and prepaid service contracts and the paragraph 12(1)(x) timing on holdbacks, so income lands in the year it is truly earned; one plan deferred $84,000 of revenue.
- We review aged bikes before year-end and write inventory down to fair market value where section 10 permits, because a three-season-old unit carried at original cost overstates both the balance sheet and the tax bill.
- We forecast working capital through the winter, when floor plan interest, rent and wages run for months against almost no unit sales, so the corporation is not borrowing at the worst possible point of its year.
- We rebuild and file overdue T2 years from deal jackets, factory statements and bank records, because CRA can raise an arbitrary assessment under subsection 152(7) when a corporation simply stops filing its returns altogether.
- We file the missing HST returns for the same periods with the trade-in netting and the exempt-commission apportionment applied, so the income tax and HST filings agree instead of setting up a second CRA review.
- We request penalty and interest relief on Form RC4288 where the arrears came from a prior bookkeeper’s error rather than a deliberate choice, supporting the request with the reconstructed dealership records and a clear timeline.
- We reconstruct the section 10 inventory at each missing year end at the lower of cost and fair market value, since an unsupported opening inventory figure distorts the profit reported in every later year.
- We bring the corporation back to current filing status so the floor plan lender and the OMVIC renewal both have clean statements; one catch-up cleared four years and $27,000 of assessed penalties and interest.
- We answer trade-in HST audits by pulling the sampled deal jackets, showing the customer’s non-registrant status and the subsection 153(4) calculation, rather than letting an auditor project one error across every deal in the period.
- We defend the input tax credit apportionment by documenting the method, the revenue split between taxable departments and exempt commissions, and the periods applied, because an undocumented split is what turns a review into an assessment.
- We respond to inventory and capital cost allowance reassessments by reconciling the section 10 stock ledger to the units on the floor and removing any allowance claimed on stock before the auditor finds it.
- We handle payroll and source deduction reviews by tying PD7A remittances, T4 box 42 commissions and WSIB premiums back to the payroll register, so a trust examination closes without widening into the corporation’s other accounts.
- We file the notice of objection within the ninety-day window when a reassessment is wrong and negotiate the file with the appeals officer; one objection removed $46,000 of allowance CRA had disallowed on stock.
- We prepare compilation engagement financial statements, still widely called a notice to reader, in the form your floor plan lender and bank expect at renewal, delivered on the schedule the credit agreement actually sets.
- We present bikes as section 10 inventory beside the floor plan payable so the statements show the real relationship between what is sitting on the floor and what is still owed on it.
- We show deferred extended warranty and prepaid service revenue as a liability for the unexpired term, matching the paragraph 20(1)(m) reserve claimed on the T2, so the two documents tell the same story.
- We calculate the working capital and debt service figures your floor plan agreement measures, and flag a covenant that is drifting before the lender raises it, which matters most heading into the winter months.
- We turn the statements around quickly after the fiscal year end so the corporation can file its T2, renew the credit line and support a $1.5 million floor plan facility without a reporting gap.
- We complete the incorporation including the NUANS report, articles, minute book and a share structure that leaves room for a future family or investor freeze, all handled for a flat fee.
- We roll your existing bike inventory, shop tools and goodwill into the corporation on a section 85 election filed on Form T2057, so the transfer happens at elected cost instead of triggering an immediate gain.
- We open the corporate HST, payroll and corporate income tax accounts, and coordinate the OMVIC registration and the floor plan facility moving into the corporate name rather than staying in yours personally.
- We structure the shares so the $1.25 million lifetime capital gains exemption is available on an eventual sale of the dealership, and we start purifying the balance sheet years before you sell.
- We model the break-even before you incorporate, comparing the roughly 12.2% Ontario rate on the first $500,000 of active income against personal rates reaching 53.53%; one owner saved $31,000 in the first year.
- We rebuild unreconciled bike sales, trade allowances, parts and service tickets and factory statements from deal jackets and bank deposits in QuickBooks Online, restoring the section 230 record trail CRA demands; one dealership recovered $19,000 of holdback credits.
- We reconstruct the section 10 stock ledger nobody kept, valuing each unit at the lower of cost and fair market value and separating the demonstrators genuinely taken into use, which CRA treats as capital property instead.
- We rebuild the floor plan payable month by month against the units on the floor, posting curtailments against the balance rather than to expense, because a doubled interest deduction is disallowed the moment CRA reviews it.
- We recover the 13% paid on parts, freight and shop supplies across the missing months through Dext and apply the exempt-commission apportionment, since unposted purchase invoices simply lose recoverable tax; one cleanup reclaimed $9,700 of credits.
- We catch up technician and salesperson payroll postings in Wagepoint and reconcile the PD7A remittances, WSIB premiums and T4 wages that fell behind, so box 42 commissions and Employer Health Tax tie out before CRA matches them.
- We handle cross-border filing for dealers buying bikes from United States suppliers or holding a US selling entity, covering Form 1120 for a US corporation and the treaty-based Form 1120-F where no permanent establishment exists.
- We file Form 5472 for a US corporation with a foreign owner and its reportable transactions, because the penalty for a missed information return is charged per form and applies whether or not any tax is owing.
- We review state registration and sales tax obligations where a Canadian dealership stores inventory or attends rallies and shows across the border, so an unfiled state return does not surface years later during a sale.
- We coordinate the United States result with the Canadian T2 so foreign tax paid is claimed correctly and the same profit is not taxed twice, and we file T1134 where a foreign affiliate is involved.
- We keep the cross-border structure documented for CRA and the IRS in parallel, including the pricing on bikes and parts moved between the two entities; one restructuring saved $24,000 of duplicated tax in a year.
- We file a Voluntary Disclosures Program application to correct HST billed on the gross price of trade-in deals before CRA contacts you, which is the single most common error we find in dealership records.
- We disclose unreported manufacturer holdbacks, rebates and co-op credits that were never picked up under paragraph 12(1)(x), rebuilding the factory statements year by year so the disclosure CRA receives is genuinely complete.
- We correct input tax credits claimed in full while exempt financing and insurance commissions were being earned, quantifying the apportionment for every reporting period; one disclosure resolved $52,000 of over-claimed credits without a penalty.
- We bring unfiled T2 and HST years into a single disclosure together, because an application CRA considers incomplete can be rejected and leaves the dealership corporation exposed to the full penalty and interest.
- We confirm the application meets the program conditions, including that it is voluntary, complete and at least one year overdue, and we deal with CRA through to acceptance, penalty relief and reduced interest.
Motorcycle Dealer Tax & HST Check
Six quick questions on your trade-in HST, consignment sales, input tax credit apportionment, floor plan reconciliation, extended warranty deferral and whether it is time to incorporate. No fee shown.
1. Are you charging HST on the net consideration after the trade credit when a bike is traded in by a customer who is not a registrant?
2. Are bikes you sell on consignment for a non-registrant owner handled under the agency rules, with tax remitted on the full selling price?
3. Are your input tax credits apportioned against exempt financing and insurance commission income rather than claimed in full?
4. Is your floor plan payable reconciled to the units physically on the showroom floor every month?
5. Is extended warranty income deferred over the unexpired term of the contract?
6. Is your motorcycle dealership incorporated?
Free CPA Consultation for Motorcycle Dealers
Case Studies: Motorcycle Dealer Accounting & Tax
Barrie Motorcycle Dealership — Trade-In HST on the Net Consideration
The problem: A Barrie motorcycle dealership had charged 13% HST on the full selling price of every deal that included a trade-in taken from a retail customer, across two selling seasons. Because those customers were not GST/HST registrants, subsection 153(4) reduced the consideration by the trade credit, so tax had been over-collected and over-remitted on roughly sixty deals, and the error was hard-coded into the deal template.
What we did: We rebuilt the deal-jacket analysis bike by bike, identified every non-registrant trade, filed adjusted HST returns for the affected periods and corrected the billing template so the net consideration calculates automatically.
The result:
- Five-figure refund of over-remitted HST recovered
- Trade-in billing corrected under subsection 153(4)
- Deal template fixed so the error cannot repeat
London-Area Motorcycle Dealer — Credit Apportionment and Bike Inventory
The problem: A London-area motorcycle dealer was claiming 100% of its input tax credits while booking roughly $220,000 a year of financing and insurance commission income, which is an exempt financial service under Schedule V Part VII. The same file carried the bikes on the floor as depreciable property, with capital cost allowance claimed on stock, so both the HST position and the T2 were wrong when a CRA questionnaire arrived.
What we did: We set a documented apportionment method for input tax credits, moved the bikes back to section 10 inventory at the lower of cost and fair market value, reversed the allowance claimed on stock and refiled.
The result:
- Credits apportioned against $220,000 of exempt commission
- Bikes restored to section 10 inventory, no allowance on stock
- Live assessment exposure closed before reassessment
Ottawa Motorcycle Sales and Service Centre — Floor Plan, Holdbacks and Departments
The problem: An Ottawa motorcycle sales and service centre had a floor plan payable that had not been reconciled to the units on the floor in more than a year, curtailment payments posted to interest expense, holdbacks booked whenever the cheque arrived, and winter storage, riding apparel and service revenue mixed straight into bike sales. Nobody could say what the shop actually earned.
What we did: We reconciled the floor plan payable to the units monthly, reposted curtailments against the balance, matched holdbacks to the period they became receivable under paragraph 12(1)(x), and split bike sales, parts, apparel, service and storage into departments in QuickBooks Online.
The result:
- Floor plan payable reconciled to units every month
- Holdbacks matched under paragraph 12(1)(x)
- Departmental margins visible; clean, audit-ready books
Our clear, efficient process ensures every step is transparent, building trust and long-term client relationships.
Kickoff (Document Request)
Collect prior T2 returns, deal jackets, bike inventory and floor plan statements, factory holdback and incentive statements, parts, apparel and service reports, storage contracts, equipment list, payroll and commission records, and bank statements.
First 30 Days (Cleanup & Setup)
Set up QuickBooks Online or Xero alongside your dealer management system, build the section 10 bike inventory and floor plan registers, set the input tax credit apportionment method, and configure payroll, commission and WSIB tracking.
Monthly Close
Monthly reconciliations, receipt capture, floor plan payable tied to the units on the floor, departmental margin reporting, and HST on bikes, parts, apparel, service and storage with apportioned credits.
Quarterly Planning Review
Salary and dividend mix, trade-in and consignment HST review, holdback and warranty reserve timing, equipment purchase timing, off-season working capital, and aged bike write-down review.
Year-End Close & T2 Filing
Trial balance, financial statements with bike inventory and the floor plan payable, T2 with GIFI, and CRA preparation.
Get Your Motorcycle Dealership Taxes Done Right Today
Affordable Pricing for Motorcycle Dealers
We believe in clear, upfront pricing so you know exactly what to expect. All fees include HST.
- Tax Preparation (Corporation) — From $400
- Tax Return Filing (Corporation) — From $400
- Tax Compliance Audit — FREE CRA audit support for our clients
- Tax Strategy — FREE for our clients
- Accounting Base Plan — From $100 per month
- Bookkeeping Management — Free for our Accounting clients
- Financial Reporting — Free for our Accounting clients
- Business Formation — Flat $35
- Incorporation Process — Flat $35
- Entity Setup Assistance — Flat $35
- Full-Service Payroll — From $125 per month
Payment is by Interac e-Transfer to info@gondaliyacpa.ca only. Security question: Not Applicable, as auto-deposit is enabled.
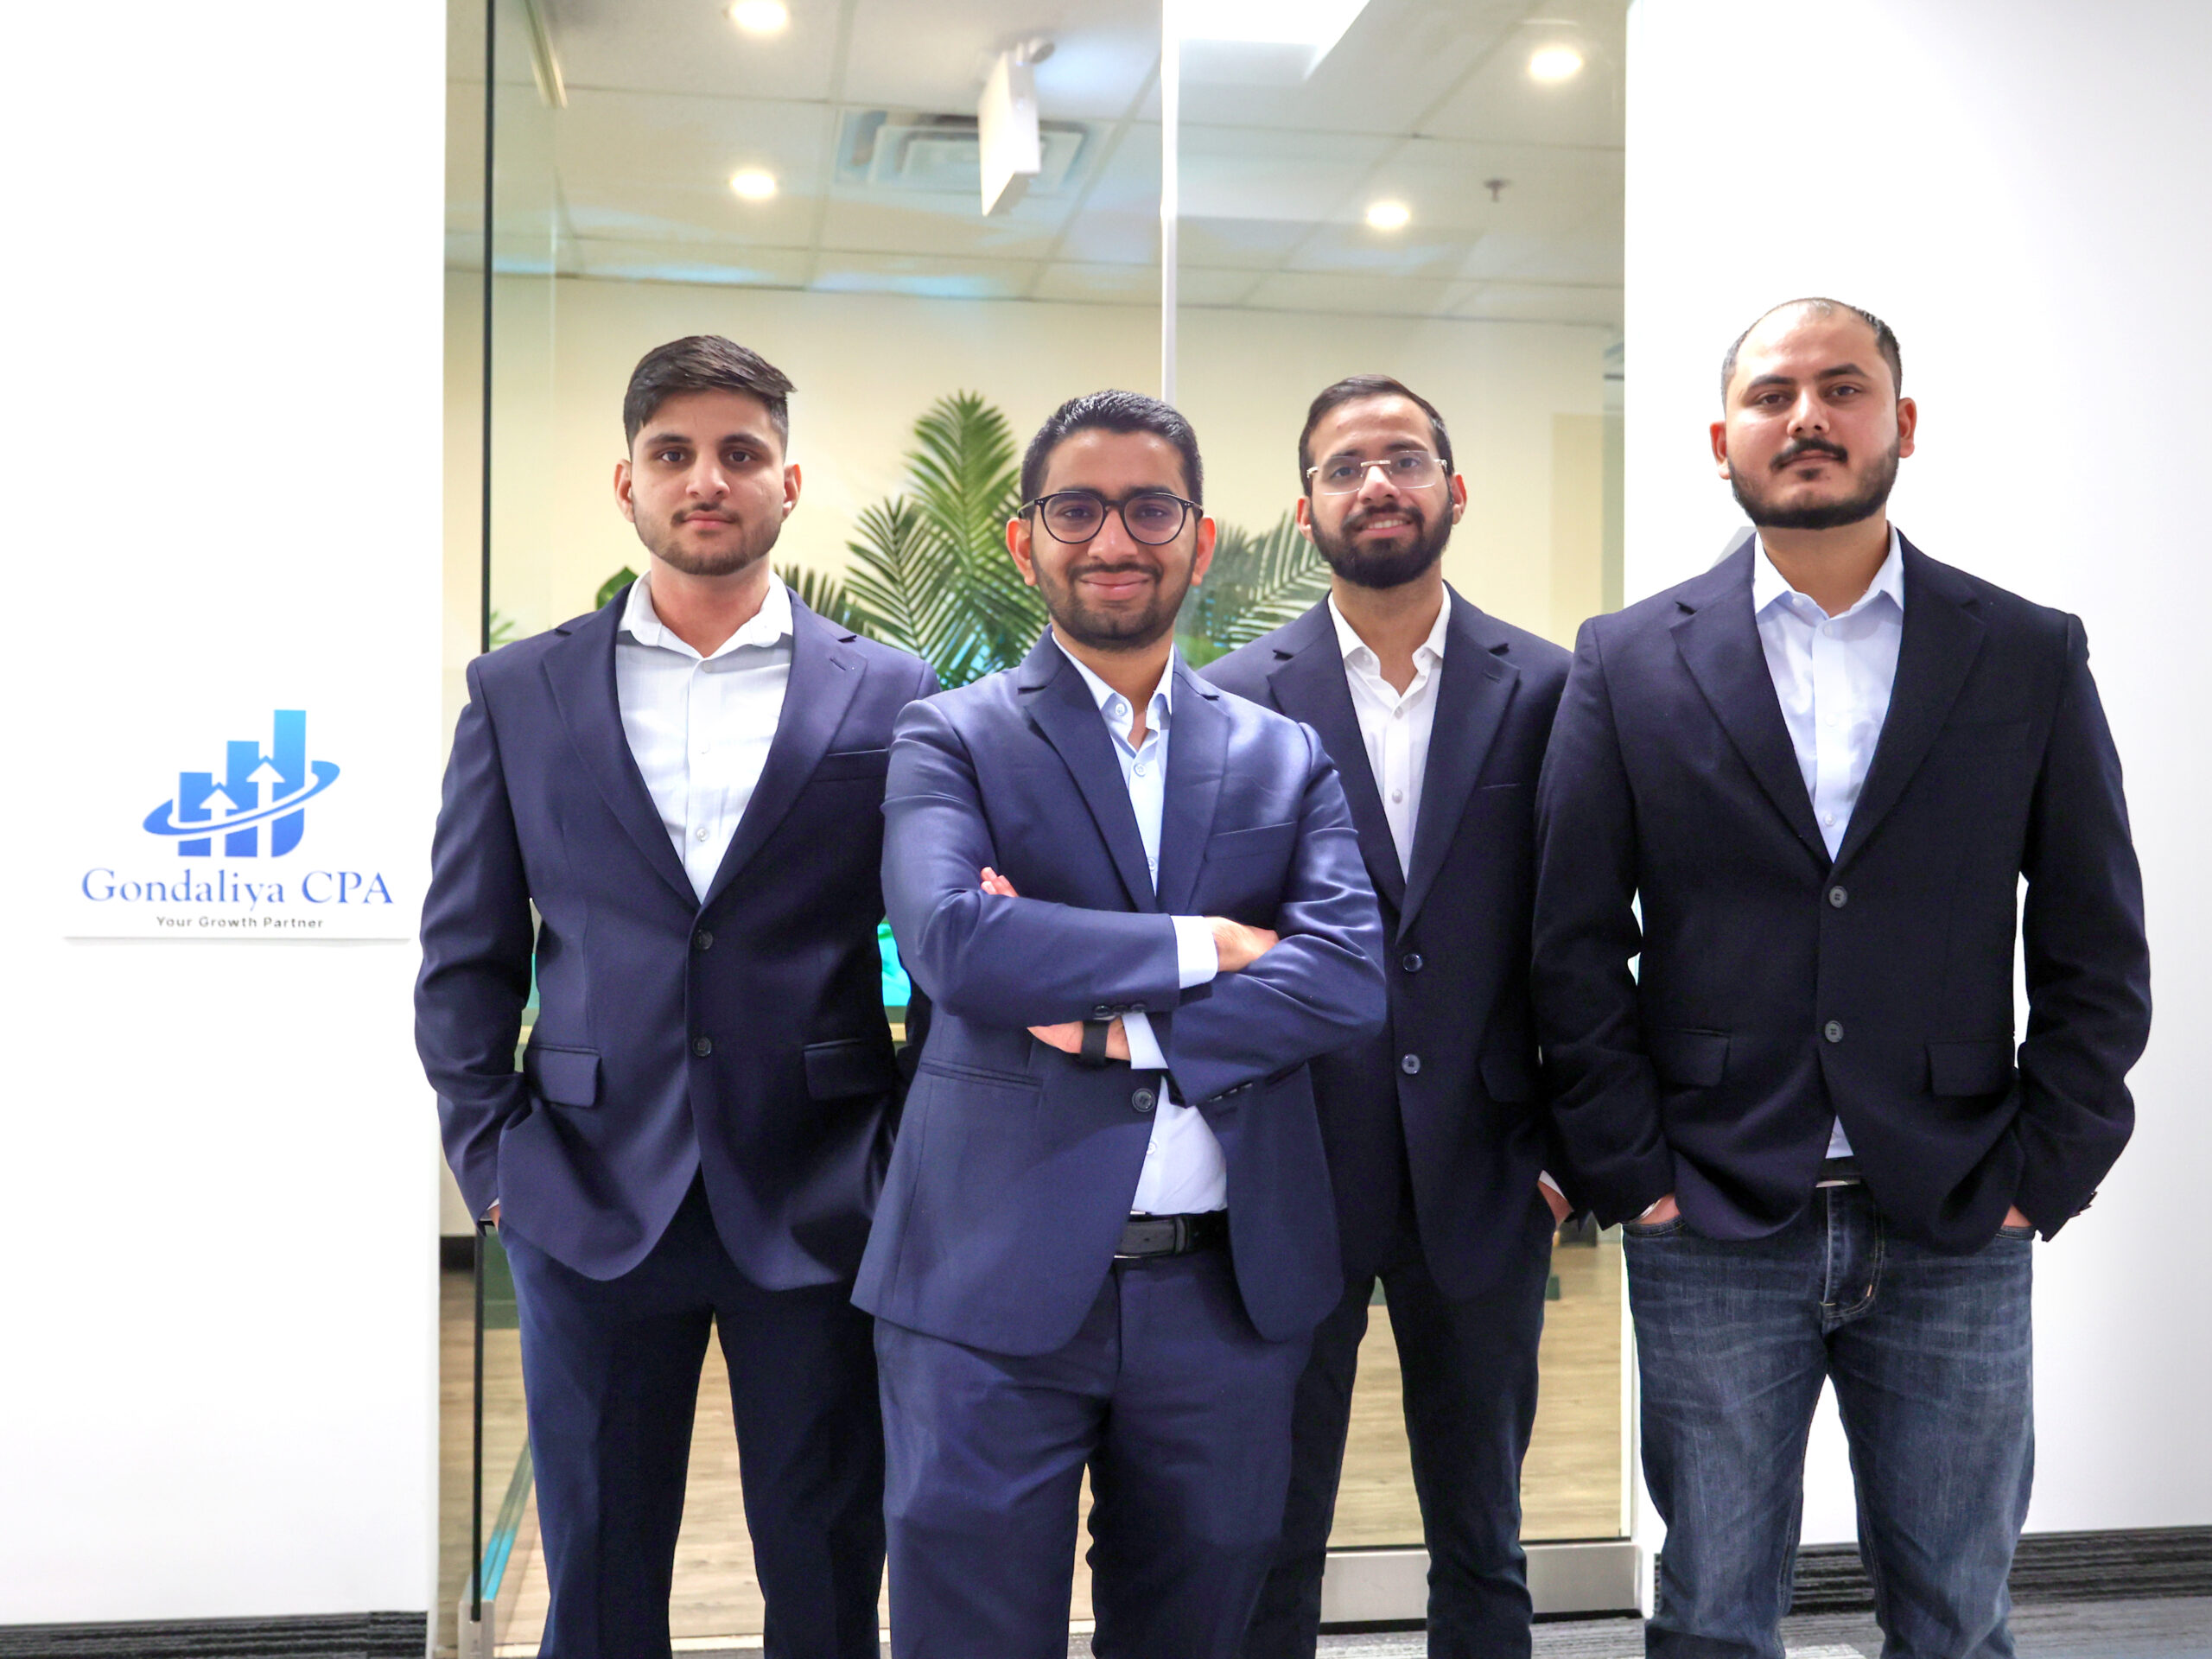
Meet Your Lead Motorcycle Dealer Accountant
Meet your lead motorcycle dealer accountant. As your trade and corporate tax adviser, you deal with the same two people every year.


What Our Clients Say
1300+ five-star reviews from dealership and retail business owners across Ontario and Canada.
Serving Motorcycle Dealers Across Ontario
Our CPA team provides specialized accounting and tax solutions for motorcycle dealerships throughout Ontario. We understand how bike inventory and floor plan financing, trade-in and consignment HST, exempt financing and insurance commissions with input tax credit apportionment, manufacturer holdbacks and extended warranty deferral actually flow through a dealership, what CRA looks at on a dealership file, and how to put your inventory, credits and reserves in the right place.
Toronto (ON)
55 Queen St E Ste 1205, Toronto, ON M5C 1R6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Mississauga (ON)
2100 Camilla Rd #716, Mississauga, ON, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Brampton (ON)
4 Starhill Crescent, Brampton, ON L6R 2P9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Scarborough (ON)
24 Clementine Square, Scarborough, ON M1G 2V7, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Vaughan (ON)
19 Cabinet Crescent, Woodbridge, ON L4L 6H9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Oshawa (ON)
210 Durham St, Oshawa, ON L1J 5R3, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Ottawa (ON)
2090 Neepawa Ave a314, Ottawa, ON K2A 3L6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Etobicoke (ON)
60 Stevenson Rd #1601, Etobicoke, ON M9V 2B4, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Hamilton (ON)
70 Starling Dr, Hamilton, ON L9A 0C5, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Guelph (ON)
1155 Gordon St, Guelph, ON N1L 1S8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Windsor (ON)
4387 Guppy Ct, Windsor, ON N9G 2N8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
North York (ON)
150 Graydon Hall Dr #912, North York, ON M3A 3B2, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Motorcycle Dealer Accounting & Tax FAQs
Related Industries We Serve
Powersports Dealers
- Unit inventory and floor plan interest
- Trade-in, consignment and warranty HST
- Corporate tax filing and bookkeeping
Used-Car Dealerships
- Unit inventory, trade-ins and HST
- Floor plan interest and lot financing
- Corporate tax filing and bookkeeping
Small Businesses
- Corporate tax planning for small businesses
- Business tax filing and financial statements
- Payroll and bookkeeping services
Incorporated Businesses
- T2 corporate returns and GIFI
- Salary, dividend and SBD planning
- Compilation statements and incorporation
Motorcycle Dealer Accounting & Tax Done Right.
T2 filing, 13% HST on bikes, parts, riding apparel, service and storage with subsection 153(4) trade-in netting and section 177 consignment rules, input tax credit apportionment against exempt financing and insurance commissions, section 10 bike inventory with no capital cost allowance on stock, floor plan interest and curtailment payments, paragraph 12(1)(x) holdbacks, the paragraph 20(1)(m) warranty reserve, capital cost allowance and technician payroll with WSIB under one roof. AFFORDABLE flat fees, no hourly billing. Licensed CPA Ontario. 1300+ five-star reviews. 30-Day Money-Back Guarantee.