



Tax Accountant for RV Parks in Ontario and Across Canada
We charge 13% on a short-term stay of under one month, and where an annual or seasonal site agreement sits on the other side of that boundary we determine the treatment per site type on the facts of the agreement and write the reasoning into the file rather than reading an answer off a rate sheet. We hold the fees contracted over winter in deferred revenue and release them across the period they buy, apply tax on a deposit when it lands against the invoice under ETA subsection 168(9), carry metered utility recovery on one consistent basis with the meters reconciled to the billing, keep winter storage on its own revenue line, and test the ITA 125(7) specified investment business position before your small business deduction is ever claimed. Whether you run a long-stay resort property, a serviced park with a few hundred annual pads or a mixed operation selling both seasons and nights, we handle the contracts, the sites and the infrastructure — with AFFORDABLE flat fees.
AFFORDABLE RV Park Tax Accountant
Most RV parks do not sell nights. They sell seasons. The agreements are signed over the winter, the money arrives in one or two waves in early spring, the trailer goes on the pad in April and stays there until the water is shut off in October, and the same names come back the following year. That single fact reshapes almost every number in the business, and it is why an RV park and a business selling transient accommodation do not file the same return even when they look identical from the road. It decides the GST/HST question first. Where a stay is short-term and runs under one month, the supply is taxable and carries 13% in Ontario, and that part of the price list raises no real question. An annual or seasonal site agreement sits on the other side of the under-one-month boundary, so the short-stay answer does not simply carry across to it. What does apply has to be determined per site type on the facts of the agreement and documented rather than assumed. A park selling both is answering two questions from one price list. At Gondaliya CPA we specialize in long-stay site revenue, deferred revenue on contracted fees, metered utility recovery and the ITA 125(7) small business deduction risk, with AFFORDABLE flat-fee support that keeps you CRA-compliant and stops you paying more tax than you owe.
As an RV park accountant we work with long-stay resort properties, serviced parks running a few hundred annual pads, mixed operations selling both seasons and shorter stays, and family-held parks in cottage country across Ontario, with year-round support rather than a once-a-year scramble. We tell you what the contracted year actually earned, what your land and improvements are worth on the books, whether your corporation is still standing on active-business footing, and where your GST/HST and payroll exposure sits.
Let us handle the numbers so you can look after the property and the people on it.
Our Official Partners
Accounting That Understands How an RV Park Actually Works
An RV park carries a set of financial problems that a business selling transient accommodation never meets. Your revenue is contracted months before it is earned, your biggest tax question has two different answers depending on which site type you are looking at, a large share of what you bill out is electricity somebody else supplied, and the rule that decides whether you keep the small business deduction turns on how many people are on your payroll rather than on how much you make. Gondaliya CPA sets the books up around those four facts from the first posting, for RV park owners in every part of Ontario.
Stay Compliant and Minimize Your RV Park Tax
Filing everything on time and paying the least tax the law allows are not two separate projects at an RV park. Every income tax, GST/HST and payroll deadline is calendared and met, every position that needed to be determined is determined and written down before it is needed, and every site, infrastructure and payroll dollar the return permits is claimed.
Accounting & Tax Experts for RV Parks
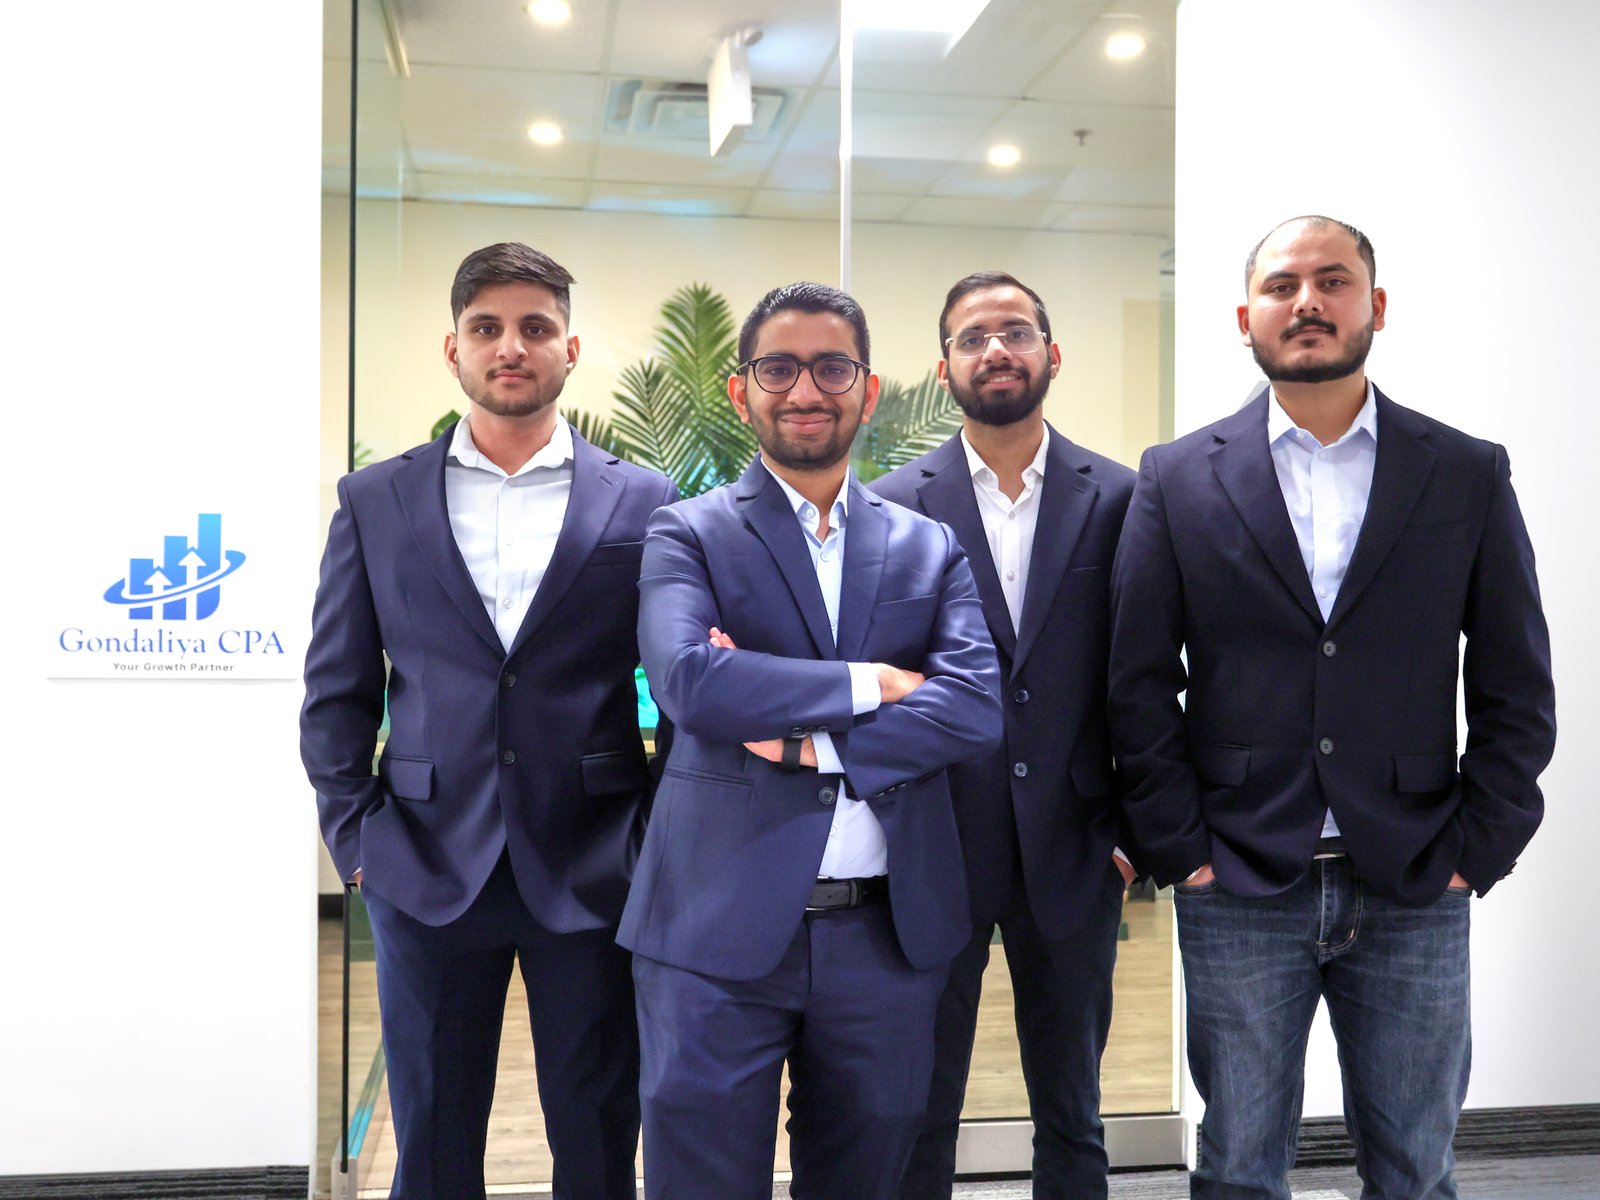
- AFFORDABLE + Fully Registered CPA Firm
- Business and Corporate Tax Expert
- Small & Medium Business Expert
- Accounting, bookkeeping, and tax filing
- Certified CPA
- 1300+ 5-star Google reviews
- 30-Day Money-Back Guarantee
- 60-Day Fees Matching Policy
Why Choose Our Accounting Services for RV Parks?
Tax Planning — The Small Business Deduction Test
We model ITA 125(7) against your real head count before year-end, because the specified investment business rule denies the deduction below six full-time employees and that answer changes what the whole year costs.
Consulting — Contract Revenue & Recovery
Our bookkeeping splits annual, seasonal and short-stay revenue, releases contracted fees across the period they buy, and carries metered utility recovery on one basis you can defend year after year.
CRA Representation — Site Supply & Capital Audit
If CRA challenges the position taken on a site type, or a capital call on water, septic or site electrical work, we produce the file behind it and seek relief on Form RC4288 where an earlier error drove the penalties.
Bookkeeping — Balance Sheet & Exit
We produce statements that separate land from improvements the way a lender reads them, and we open the share-versus-asset sale question years before the property is ever listed.
Google Reviews
RV Park Clients
RV Park Tax and Accounting Services in Ontario
Corporate Tax Filing (T2) for RV Parks
Professional T2 preparation with the ITA 125(7) position tested before filing, buildings in Class 1, roads and pads in Class 17, and contracted fees carried as deferred revenue.
Bookkeeping & Accounting for RV Parks
Annual, seasonal, short-stay, utility-recovery and storage revenue tracked on separate lines, meters reconciled to billing, and statements built from records that reconcile.
Payroll Services for RV Parks
Payroll with WSIB from the first hire, PD7A remittances on time, T4 and T4A slips filed, and the full-time head count documented for the 125(7) question.
GST/HST Filing for RV Parks
AFFORDABLE filing with short supplies of under one month at 13%, every other site type determined on its facts and documented, and credits claimed to match.
Tax Planning for RV Parks
Planning that starts with the specified investment business test, moves to the timing of infrastructure spending against your year-end, and ends with the eventual sale of the land.
Corporate Catch-Up Filing for RV Parks
Overdue T2 and GST34 years filed oldest first, capital pools and deferred revenue rebuilt from the agreements and invoices, and your CRA standing restored.
CRA Audit Resolution for RV Parks
Expert support on site-supply, capital-versus-repair and specified investment business reviews, handled with confidence from the very first CRA letter.
CPA Financial Statements (Notice to Reader) for RV Parks
Compiled statements a lender will accept, with the land, the improvements and the equipment valued apart and the deferred revenue shown as the liability it is.
Incorporation Services for RV Parks
NUANS search, articles, share structure and CRA account setup, with the 125(7) exposure tested first and the section 85 rollover handled on Form T2057.
Catch-Up Bookkeeping Services for RV Parks
Years of site agreements, deposits, utility records, supplier invoices and payroll reconstructed and reconciled, so your asset schedule is finally accurate.
US Corporation & LLC Tax Filing for RV Parks
Cross-border filing where an owner holds US citizenship, where a shareholder is non-resident and Part XIII withholding and NR4 slips apply, or where foreign holdings must be reported.
Voluntary Disclosure Program for RV Parks
Come forward on tax never charged, a deduction claimed where the head count never supported it, or staff paid off the books, cancelling penalties on an accepted disclosure.
Accounting & Tax Services Tailored for RV Parks
Real, practitioner-level CPA expertise for long-stay resort properties, serviced parks running a few hundred annual pads, mixed operations selling both seasons and shorter stays, and family-held parks across Ontario — built for a business that contracts its revenue long before it earns it.
- We prepare your T2 with GIFI on Schedule 100 and Schedule 125, carrying annual site contracts, seasonal site contracts, short-stay pads, metered utility recovery and winter storage on separate lines so CRA reads the park the way it actually earns.
- We test ITA 125(7) before the return leaves our office, because a corporation whose principal purpose is earning income from property is a specified investment business and that rule denies the deduction below six full-time employees.
- Capital cost allowance goes on Schedule 8 with the office and service buildings in Class 1, your tractors, mowers and maintenance machinery in Class 8 at 20%, and the internal roads, parking and the pads themselves in Class 17.
- We release the fees contracted over the winter across the months of occupancy they actually buy, so a $240,000 spring intake reports as the period you delivered instead of landing as one enormous April.
- When a tractor, a utility vehicle or a run of service pedestals is sold or scrapped the pool has to move, so we settle recapture against undepreciated capital cost and claim the terminal loss where a class empties.
- We build the chart of accounts so annual site contracts, seasonal site contracts, short-stay pads, metered utility recovery, winter storage and every other income source land on their own line instead of one blended site-revenue total.
- Where the park makes both a short supply and a longer site supply, we keep those revenue lines apart from the first posting, because a determination made per site type is worthless unless it can be traced to the dollars it governs.
- We reconcile the site-management system to the bank every month, so a $4,200 gap between what was contracted and what was deposited surfaces in July rather than eighteen months later during a year-end review.
- We carry the fees collected before the season opens in deferred revenue, because money taken in February against occupancy running through to October is a liability you owe in site time, not February profit.
- Hydro invoices, pump-out tickets, gravel loads and contractor bills go into Dext as they arrive and are reconciled monthly, which keeps the six years of records CRA expects and stops input tax credits disappearing over the winter.
- Head count is never a side issue at an RV park, because the specified investment business rule turns directly on it, so we document who is genuinely a full-time employee and who is not before anybody asks.
- Source deductions are remitted on the PD7A by the fifteenth of the month after they are withheld, and we hold that date because the graduated late-remittance penalty climbs to 10%, which on an $11,000 remittance is $1,100.
- We register WSIB coverage before the first hire, since grounds work, pad servicing, equipment operation and snow clearing around stored trailers are exactly the activities an uncovered employer cannot afford an injury on.
- The payroll year closes in February: T4 slips and the T4 Summary go in by the last day of that month and are proved back line by line against what the park actually sent CRA on the PD7A.
- We watch your Ontario payroll against the $1,000,000 Employer Health Tax exemption, and where staff finish at the end of a short season we issue records of employment so nobody is chasing paperwork in November.
- A short-term stay of under one month is a taxable supply and carries 13% in Ontario, so short-stay pads are billed and reported at that rate on every GST34 return we prepare for you.
- An annual or seasonal site agreement sits on the other side of the under-one-month boundary, and the treatment must be determined per site type on the facts of the agreement and documented rather than assumed from your rate sheet.
- We claim input tax credits consistently with the determination actually reached, because recovering tax on one basis while reporting the revenue on another is the mismatch a GST/HST reviewer finds first.
- Under ETA subsection 168(9) the tax on a deposit is collected when the deposit is applied against the invoice, not on the day a site was reserved, so we set the billing system up to follow that timing.
- We establish the date registration was actually required once taxable revenue passed $30,000 over four consecutive calendar quarters, file from that point forward, and recover credits on hydro, gravel, equipment and contractor work.
- We model ITA 125(7) against your real staffing well before year-end, because a park with two hundred long-stay pads and three people on the payroll is precisely the profile the specified investment business rule was written to catch.
- Where the small business deduction is available, the first $500,000 of active income is taxed at roughly 12.2% combined in Ontario against a top personal rate of 53.53%, and protecting that spread is what planning is for.
- If the rule does apply, the income falls into investment-income treatment instead of the active rate, so we put a dollar figure on the difference and set out what would have to change before the next year-end.
- We time infrastructure spending across Class 1, Class 8 and Class 17 against your year-end, and we get the capital-versus-repair call on water, septic and site electrical work made in writing before the invoice is ever posted.
- On exit the land usually outweighs the operation, so we open the share-versus-asset sale question years ahead, including the $1.25M lifetime capital gains exemption and a balance sheet clean enough to support a claim.
- Overdue T2 years go in oldest first, because the late-filing penalty opens at 5% of the balance owing and climbs 1% for each month a return stays outstanding, with arrears interest running underneath it.
- We rebuild the capital pools nobody opened, sorting years of pad, road, service-pedestal and building spending into Class 1, Class 8 at 20% and Class 17 from the scope written on each individual invoice.
- We reconstruct the deferred revenue position year by year, because a park that reported every contract as income the day the cheque cleared has filed returns that never matched the occupancy it went on to deliver.
- We revisit the 125(7) question in every catch-up year, since the small business deduction may have been claimed in periods where the full-time head count never supported it, and that is a reassessment waiting to happen.
- Where a prior error caused the penalties and interest we apply for relief on Form RC4288, and we bring the missing GST34 returns in alongside the T2 years so the two finally agree with each other.
- When a reviewer asks how a particular site type was treated, we produce the determination, the agreement it rested on and the revenue lines that follow from it, which is the file most parks cannot lay hands on.
- On a capital-versus-repair review we go back to the scope written on each invoice, because replacing a water main or rebuilding a run of pads is capital while flushing, testing and patching comes off in the year paid.
- Where CRA proposes that the corporation is a specified investment business, we set out the full-time head count, the services genuinely supplied with a site and the facts behind the active-business position before a proposal hardens.
- We answer utility queries with the meter readings, the supplier invoices and the recovery postings lined up beside each other, so what was billed out to the sites traces cleanly to what the park itself was charged.
- We carry the correspondence end to end from the first letter, and we pursue penalty and interest relief on Form RC4288 where the exposure came from a genuine error rather than from anything deliberate.
- We compile statements a lender will accept, carrying the land separately from the buildings, from the roads and pads, and from the equipment, because those four things are underwritten at completely different values.
- The deferred revenue on annual and seasonal contracts is stated as the liability it genuinely is, so a strong February bank balance is never mistaken for a year that has already been earned and banked.
- Winter storage appears as its own revenue line with its own direct costs against it, which is the only honest way to see whether the off-season carries any share of twelve months of fixed cost.
- Metered utility recovery is presented on whichever basis was chosen and then held there period after period, because a treatment that drifts between revenue and cost recovery makes two consecutive years impossible to compare.
- We reconcile the statements back to your filed GST34 returns and your T2 before they are issued, so a refinancing conversation never stalls on numbers that disagree with what CRA is already holding.
- We run the NUANS search, file the articles, set the share structure and open the CRA program accounts, so the corporation is ready to file rather than assembled in a rush at the first year-end.
- Before anything is incorporated we test the 125(7) exposure, because moving a property-heavy park into a corporation without checking the full-time head count can deliver investment-income treatment instead of the rate you were promised.
- Where the land, buildings and equipment still sit personally, we handle the section 85 rollover on Form T2057 so they transfer in at elected amounts rather than triggering a gain on the day of the move.
- We build the share structure with the eventual sale in view, because the $1.25M lifetime capital gains exemption and a clean balance sheet take years of purification rather than a phone call in the closing month.
- We set the salary and dividend mix against what the family actually draws, since a park earning more than the owners take out is exactly where a corporation earns back its cost in deferral.
- We reconstruct years of site agreements, bank deposits, utility records, supplier invoices and payroll from source documents, so the park finally owns a set of books that matches what the property genuinely did.
- We rebuild the deferred revenue schedule from the signed agreements themselves and tie the closing balance back to the contracts sitting behind it, instead of accepting whatever figure the prior file carried forward.
- We separate annual, seasonal and short-stay revenue retroactively, because a determination reached on each site type means nothing if the underlying dollars were never recorded in a way that can support it.
- We reconcile the meters to what was billed across every recovered period, which is usually where a park discovers it has quietly been absorbing consumption that was never charged out to the sites at all.
- We rebuild the capital cost allowance schedule from the invoices, opening Class 1, Class 8 and Class 17 properly, so the asset values on your statements finally become something a lender can rely on.
- Parks in cottage country very often have an American in the ownership or a cross-border family behind them, and we file both sides on one timetable so the same income is not taxed twice under the treaty.
- Where a non-resident shareholder is paid we handle Part XIII withholding and the NR4 slips, because the withholding obligation sits with the corporation and amounts never remitted come with penalties of their own.
- We report foreign holdings on Form T1135 where the cost of specified foreign property passes $100,000, a threshold that catches more park-owning families than expect it, and a missed filing carries its own penalty.
- We prepare the US corporation and LLC returns alongside the Canadian T2 rather than months apart, so the two sets of numbers agree and neither filing has to be rebuilt from the other afterwards.
- We work out whether a US entity in the structure helps or hurts before it is ever created, because an LLC that looks simple on the American side can be an expensive mismatch on the Canadian one.
- Where a park never registered although its short-stay revenue had long since passed the $30,000 threshold, we quantify the 13% that was never billed and disclose the whole period before CRA opens the file itself.
- Where the small business deduction was claimed across years the full-time head count never supported, we disclose the 125(7) position rather than sit and wait for a reassessment to arrive with penalties attached.
- Unreported wages are among the simplest things for CRA to reconstruct from bank withdrawals, so where a park has paid help off the books we disclose it and rebuild those payroll years properly.
- The submission goes in on Form RC199 supported by a reconstruction built from the site agreements, the utility records and the bank statements, which is what keeps CRA from assessing on an estimate of its own.
- A disclosure only works if it meets the program conditions, so we confirm nothing has already been requested by CRA, that the filing covers everything, and that the oldest year reaches far enough back.
RV Park Site & Tax Check
Six quick questions on your short-stay HST, the determination on your annual and seasonal site types, contracted fees held as deferred revenue, metered utility recovery, the ITA 125(7) head-count test and whether it is time to incorporate. No fee shown.
1. Are you charging 13% on short-term stays of under one month?
2. Has the treatment of each annual and seasonal site type been determined and documented?
3. Are contracted site fees carried as deferred revenue and released across the period they buy?
4. Do your meter readings reconcile to what you billed out and to what the supplier charged?
5. Has your ITA 125(7) position been tested against your full-time head count?
6. Is your RV park incorporated?
Free CPA Consultation for RV Parks
Case Studies: RV Park Accounting & Tax
Grand Bend RV Park — The Deduction That Was Never Tested
The problem: A three-hundred-pad park near Grand Bend had claimed the small business deduction on four consecutive T2 returns. Almost all of its income came from annual and seasonal site agreements, the payroll carried the owner, a part-time bookkeeper and two grounds staff, and nobody had ever looked at ITA 125(7). The previous preparer had simply assumed that a property with a busy office was an active business, and the corporation had been planning its dividends, its instalments and its owner compensation around a rate it may never have been entitled to at all.
What we did: We tested the specified investment business position year by year against the actual full-time head count and the services genuinely supplied with a site, quantified the gap between the active rate and investment-income treatment, and disclosed the affected years before CRA reached them.
The result:
- Four years re-tested against the 125(7) head-count rule
- $61,400 of reassessment exposure quantified before CRA raised it
- Penalties cancelled through an accepted voluntary disclosure
Bancroft Seasonal RV Park — Hydro Nobody Reconciled
The problem: A park north of Bancroft metered every long-stay pad and billed the readings out each autumn, but the recovery had been posted three different ways across five years: sometimes as revenue, sometimes as a credit against the hydro expense, and once straight to the shareholder loan. Nobody had ever compared the total billed out to the sites against the total the utility had charged the park. Reported margin swung by tens of thousands of dollars from one year to the next for no operating reason at all, and the bank had started asking pointed questions.
What we did: We rebuilt five years of meter readings against the supplier invoices, settled on one treatment and applied it to every period, restated the statements so the years became comparable, and recovered the input tax credits lost when the recovery had gone to the wrong account.
The result:
- Five years restated on one consistent recovery treatment
- $18,900 of unbilled consumption identified and recovered
- Meters now tie to both the site billing and the utility invoice
Bobcaygeon RV Park — One Price List, Two Questions
The problem: A park outside Bobcaygeon ran roughly forty short-stay pads alongside a hundred and sixty annual and seasonal agreements, and applied one tax answer straight across the whole rate sheet without ever asking whether the same answer belonged on both. Winter storage was buried as a line inside the following season site fee. All the revenue landed in a single account, so there was no way to show which dollars belonged to which kind of supply, and nothing in the file explained why anything had been treated the way it was.
What we did: We split the revenue by site type, determined and documented the treatment for each on the facts of the signed agreements rather than on the rate sheet, lifted winter storage onto its own line with its own costs, and brought the input tax credit claim into line with the determinations made.
The result:
- Revenue split by site type with each determination documented
- Winter storage carried as its own revenue line with its own costs
- Credits now claimed consistently with the position on file
Our clear, efficient process ensures every step is transparent, building trust and long-term client relationships.
Kickoff (Document Request)
Gather the prior T2 returns, every signed annual and seasonal site agreement, the site-management export, filed GST34 returns, meter readings against utility invoices, infrastructure and contractor billing, payroll records, property tax and loan paperwork, and the bank statements.
First 30 Days (Cleanup & Setup)
Set up QuickBooks Online or Xero, split annual, seasonal, overnight, utility-recovery and storage revenue onto separate lines, rebuild the Class 1, Class 8 and Class 17 pools, and test the ITA 125(7) head-count position.
Monthly Close
Deferred revenue released month by month against the signed agreements, meters reconciled to what was billed out, GST34 with short supplies of under one month at 13% and every other site type reported on its documented determination, and payroll reconciled to the PD7A.
Quarterly Planning Review
Salary and dividend mix, infrastructure timing across Class 1, Class 8 and Class 17, the ITA 125(7) exposure modelled against real head count, and the share-versus-asset sale question opened years before anyone lists the property.
Year-End Close & T2 Filing
Trial balance, statements that keep land apart from buildings, surfaces and equipment and show the deferred revenue as a liability, every capital pool closed out with recapture or terminal loss, the T2 filed with GIFI, and a file ready for review.
Get Your RV Park Taxes Done Right Today
We believe in clear, upfront pricing so you know exactly what to expect. All fees include HST.
- Tax Preparation (Corporation) — From $400
- Tax Return Filing (Corporation) — From $400
- Tax Compliance Audit — FREE CRA audit support for our clients
- Tax Strategy — FREE for our clients
- Accounting Base Plan — From $100 per month
- Bookkeeping Management — Free for our Accounting clients
- Financial Reporting — Free for our Accounting clients
- Business Formation — Flat $35
- Incorporation Process — Flat $35
- Entity Setup Assistance — Flat $35
- Full-Service Payroll — From $125 per month
Payment is by Interac e-Transfer to info@gondaliyacpa.ca only. Security question: Not Applicable, as auto-deposit is enabled.
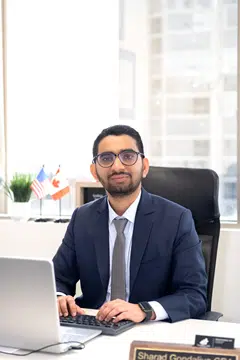
Meet Your Lead RV Park Accountant
Meet your lead RV park accountant. One pair of hands carries your site contracts, your GST34 returns and your T2 from one year into the next, so the file never restarts from scratch.
What Our Clients Say
1300+ five-star reviews from RV park, resort property, recreation and land-based business owners across Ontario and Canada.
Serving RV Parks Across Ontario
Our CPA team provides specialized accounting and tax solutions for RV parks, long-stay resort properties and serviced-site operations throughout Ontario. We know why a supply of under one month answers a different question from a site held for a whole season, why head count decides whether the small business deduction survives, how metered utility recovery should be carried, and what a reviewer turns to first when an RV park file is opened.
Toronto (ON)
55 Queen St E Ste 1205, Toronto, ON M5C 1R6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Mississauga (ON)
2100 Camilla Rd #716, Mississauga, ON L5A 2J8
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Brampton (ON)
4 Starhill Crescent, Brampton, ON L6R 2P9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Scarborough (ON)
24 Clementine Square, Scarborough, ON M1G 2V7, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Vaughan (ON)
19 Cabinet Crescent, Woodbridge, ON L4L 6H9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Oshawa (ON)
210 Durham St, Oshawa, ON L1J 5R3, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Ottawa (ON)
2090 Neepawa Ave a314, Ottawa, ON K2A 3L6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Etobicoke (ON)
60 Stevenson Rd #1601, Etobicoke, ON M9V 2B4, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Hamilton (ON)
70 Starling Dr, Hamilton, ON L9A 0C5, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Guelph (ON)
1155 Gordon St, Guelph, ON N1L 1S8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Windsor (ON)
4387 Guppy Ct, Windsor, ON N9G 2N8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
North York (ON)
150 Graydon Hall Dr #912, North York, ON M3A 3B2, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
RV Park Accounting & Tax FAQs
Related Industries We Serve
Accountant for Campgrounds
- Seasonal revenue and deposits
- GST/HST on short-term accommodation
- Corporate tax filing and statements
Accountant for RV Dealers
- Bookkeeping and year-end statements
- GST/HST and payroll compliance
- Corporate tax planning and CRA support
Accounting for Small Businesses
- Bookkeeping and HST filing
- Payroll and year-end statements
- Tax planning and CRA support
Accountant for Incorporated Businesses
- T2 filing and GIFI schedules
- Salary and dividend planning
- Small Business Deduction protection
RV Park Accounting & Tax Done Right.
T2 filing with the ITA 125(7) specified investment business position tested before the small business deduction is claimed, buildings in Class 1, equipment in Class 8 at 20% and internal roads, parking and pads in Class 17, a short-term stay of under one month charged at 13% with every annual and seasonal site type determined on the facts of its agreement and documented, contracted fees carried as deferred revenue and released across the period they buy, deposits handled under ETA subsection 168(9), metered utility recovery held on one consistent basis with the meters reconciled to the billing, winter storage carried on its own line, and capital kept apart from repair on the water, septic and site electrical systems. AFFORDABLE flat fees, no hourly billing. Licensed CPA Ontario. 1300+ five-star reviews. 30-Day Money-Back Guarantee.