



Environmental Consulting Business Tax Planning in Canada: Managing Projects, Contractors & Business Taxes
Environmental consultant tax planning Canada explained: accrued pay, provisions, allowances and SR&ED timing
Environmental consultant tax planning Canada plays a key role in managing environmental consulting business taxes effectively, and Gondaliya CPA offers clear guidance on accounting and tax strategies specifically designed for environmental consulting firms. Our approach includes careful review of tax credits, deductions, and compliance requirements to help Canadian environmental consultants optimize their financial outcomes.
Quick Summary
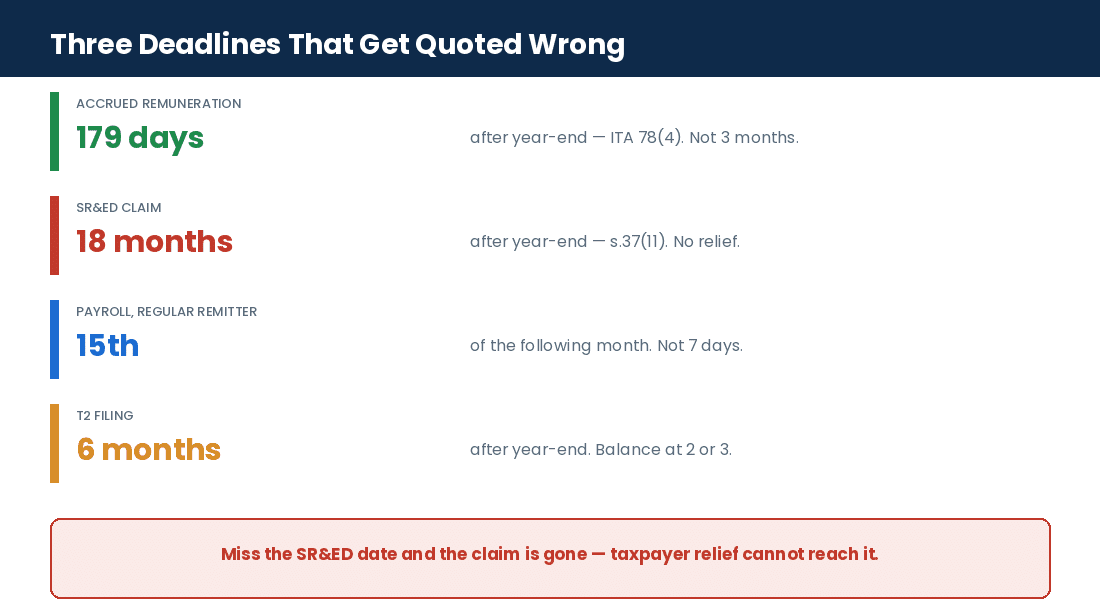
Accrued pay has 179 days after year-end, not three months. SR&ED has 18 months, not six. And payroll source deductions are due on the 15th of the following month for a regular remitter, not seven days after each pay period.
Reading time: 47 minutes.
Table of Contents
- Three Deadlines You Have Been Given
- Key Considerations and Obligations
- Accounting and Financial Statements
- Specialized Tax Services
- Business Structure
- Year-End Planning Checklist
- Record-Keeping Best Practices
- Frequently Asked Questions
- Essential Topics and Best Practices
- Businesses We Serve
- Professional Guidance and Quick Reference
The Numbers That Matter
This article covers Canada, with Ontario and Toronto context, and reflects rules current to 30 September 2026. It is written for incorporated Canadian environmental consulting firms running phased projects, engaging subcontractors and deploying field crews, including across provincial lines. Gondaliya CPA performs compilation engagements; we do not perform audits or review engagements, and where a lender or contract requires one we refer it out. Figures marked illustrative are examples, not quotes, and any masked engagement notes end with “Figures changed for privacy.” This is educational information only and not tax or legal advice. Provincial rules differ, so please confirm the position where you operate.
Three Deadlines You Have Been Given
Three Deadlines You Have Been Given
The Corrections
Three dates circulate in consulting tax guidance and all three are wrong. Each one denies a deduction or a credit outright, so they are worth settling before anything else.
Accrued Pay Has 179 Days, Not Three Months
Subsection 78(4) is precise: remuneration owed at year-end and still unpaid on the 179th day after the end of that taxation year is deemed not to have been incurred in the year. It is instead deducted in the year it is actually paid.
The gap between three months and 179 days is roughly ninety days, and a firm working to the shorter figure is simply early. The real risk runs the other way: a firm told “about six months” pays on day 181 and loses the deduction for a full year. For a 31 December year-end, the 179th day falls on 28 June.
SR&ED Has 18 Months, Not Six
The SR&ED reporting deadline is 12 months after the T2 filing due date, which is 18 months after the fiscal year-end — not the six-month T2 deadline itself.
| Obligation | Deadline | Relief available? |
|---|---|---|
| T2 return | Six months after year-end | Penalty relief under 220(3.1) |
| SR&ED claim | 18 months after year-end | No — a statutory bar |
| Balance of tax | Two months; three for an eligible CCPC | Interest relief under 220(3.1) |
The second row is the one that matters. Subsection 37(11) makes the SR&ED filing requirement a condition of the deduction itself, so a late claim is not a late filing that attracts a penalty — it is no claim at all. Taxpayer relief under 220(3.1) reaches penalties and interest; it does not resurrect an expired SR&ED claim.
Payroll Is Not Seven Days After the Pay Period
Source deductions are remitted under section 153 and Regulation 108, and the due date turns on your average monthly withholding amount, not on your pay cycle.
| Remitter type | AMWA | Due |
|---|---|---|
| Quarterly | Under $1,000 with a clean record | 15th of the month after the quarter |
| Regular | Under $25,000 | 15th of the following month |
| Accelerated, threshold 1 | $25,000 to $99,999.99 | 25th of the same month; 10th of the following |
| Accelerated, threshold 2 | $100,000 or more | Within 3 working days of the period end |
No band is “seven days after each pay period ends”. Most environmental consulting firms are regular remitters on the 15th. Getting this wrong attracts a penalty under subsection 227(9) that starts at 3% and reaches 10%, with directors personally liable under section 227.1.
A Toronto environmental firm had been paying accrued bonuses to its owner-managers at the six-month mark, on the understanding that the window matched the T2 deadline.
It does not. Two of three years landed past day 179, and roughly $140,000 of deduction shifted into the following year each time. Nothing was lost permanently, but the corporation paid tax a year early, twice. Figures changed for privacy.
Risk Warning: Please check your SR&ED filing date against 18 months from year-end, not six. A missed SR&ED deadline cannot be relieved.
Environmental Consultant Tax Planning in Canada: Key Considerations for Your Business
Key Considerations and Obligations
Foundations
Importance of Tax Planning for Environmental Consultants
Phased projects, subcontracted fieldwork, crews on remote sites and clients in several provinces put an environmental consulting firm into four or five tax rules that a straightforward service business never meets. Planning is mostly about timing: when income falls, when a cost becomes deductible, and which day a payment has to clear.
Know Your Deductible Expenses
- Site assessment, monitoring and remediation costs, deductible under paragraph 18(1)(a) where incurred to earn income and reasonable under section 67.
- Subcontractor invoices for drilling, laboratory analysis and specialist survey work.
- Field consumables, sampling media, calibration and disposal charges.
- Professional liability and errors and omissions insurance.
- Association dues, professional licensing and continuing education.
Accrual or Cash Accounting
Risk Warning: This is not a choice. Section 9 requires business income to be computed as profit on the accrual basis, and the cash method in section 28 is available only to farming and fishing businesses. An environmental consulting firm accrues, incorporated or not.
Accrual also means expenses are recognised when incurred, not when billed or paid. A subcontractor who completed the drilling in November and invoices in February is a November cost.
Manage Subcontractors Carefully
- Written agreements setting scope, control, tools and risk of loss.
- A T4A where fees for services exceed $500 in the calendar year.
- GST/HST charged by registered subcontractors, recoverable by you as an input tax credit on a compliant invoice.
- Non-resident subcontractors working in Canada: 15% withholding under Regulation 105, reported on a T4A-NR, unless a waiver is granted on Form R105.
Watch Provincial Rules
Where a crew works in another province, the question is whether the corporation has a permanent establishment there under Regulation 400(2). If it does, taxable income is allocated by the formula in Regulation 402: half on the share of gross revenue reasonably attributable to each province, half on the share of salaries and wages paid there. That allocation is filed on Schedule 5.
Check Research Claims
SR&ED is available where the work meets the section 248(1) definition: basic research, applied research or experimental development addressing a scientific or technological uncertainty through systematic investigation. Routine sampling, standard assessment and regulatory reporting are not SR&ED, however technical they feel. A novel remediation technique being developed because no known method resolves the problem may be.
Handle Future Work Provisions Correctly
Money set aside for a future phase is not deductible until the cost is incurred. Paragraph 18(1)(e) denies a deduction for a reserve, contingent liability or sinking fund except where the Act expressly permits one, and nothing in the Act permits a provision for future remediation phases.
Know How Employee Allowances Work
Board and lodging at a special work site or a remote work location may be excluded from the employee’s income under subsection 6(6), which has its own conditions and its own certification on Form TD4. Where the site does not qualify, the allowance is a taxable benefit under paragraph 6(1)(b) and belongs on the T4.
Keep Detailed Records, Use a Professional’s Help, and Review Regularly
- Costs coded to project and phase from entry, not reconstructed at year-end.
- Subcontractor agreements filed against the slips actually issued.
- A bookkeeping review each quarter rather than one scramble in month seven.
- The accrued pay date, the SR&ED date and the remittance band confirmed in writing once a year.
Key Stat: Provincial allocation is 50% gross revenue and 50% salaries and wages, under Regulation 402. Where the crew works matters as much as where the client is.
Accounting and Financial Statement Services for Environmental Consulting Firms
Accounting and Financial Statements
Reporting
Importance of Accurate Financial Reporting for Environmental Consultants
- Compliance with tax laws and funding requirements: records kept under section 230, with grant and funding reports traceable to the same ledger.
- Accurately tracking revenue streams and project costs: income included when it becomes receivable under paragraph 12(1)(b), with costs matched to the same period.
- Facilitating informed business decisions: profitability visible by project and phase, which is the only way to price the next proposal.
Risk Warning: unbilled work is not deferred income. Work in progress at year-end is inventory of a business under subsection 10(5) and is included at the lower of cost and fair market value. Holding the invoice back until January does not move the income; the work was done, and the value sits on the balance sheet either way.
The billed-basis election in section 34, which once let certain professionals exclude work in progress, was eliminated and fully phased out by 2024. It never extended to environmental consultants in any event — section 34 listed accountants, dentists, lawyers, medical doctors, veterinarians and chiropractors, and no one else.
Holdbacks are different. Where a statutory holdback under provincial construction legislation is not legally receivable until certification or substantial performance, the amount is not yet receivable under 12(1)(b) and is not income until it becomes so. That turns on the contract and the statute, not on when you choose to invoice.
Types of Financial Reports: Audit, Review, Compilation
| Engagement | Assurance | Standard | Typical use |
|---|---|---|---|
| Compilation | None | CSRS 4200 | Tax filing, internal use, most small firms |
| Review | Limited | CSRE 2400 | Some lenders and franchisors |
| Audit | Reasonable | CAS | Contract or regulatory requirement |
Differences between audits, reviews, and compilations come down to that assurance column. A compilation engagement under CSRS 4200 provides no assurance and carries only a basis of accounting note — it is not a light audit and not audit preparation.
Choosing the right financial statement service is usually decided for you. If nobody outside the business has asked for assurance, a compilation is the fit. If a lender or a contract specifies a review or an audit, that is the requirement, and Gondaliya CPA refers those out rather than performing them.
Ensuring Compliance with Canadian Accounting Standards: ASPE and IFRS Application for Consultants
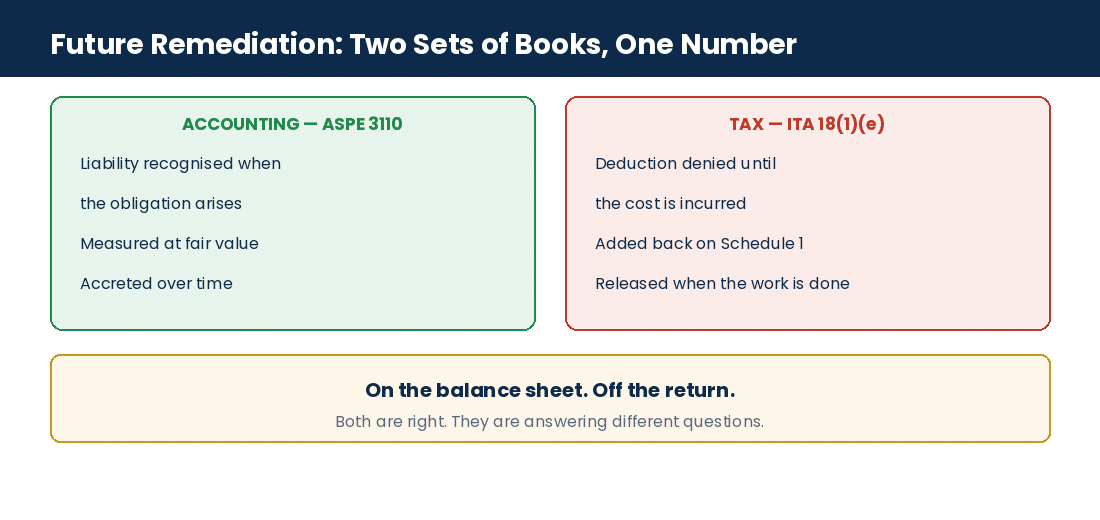
Key Stat: future remediation costs are recognised differently for accounting and for tax, and the gap is the whole point. Under ASPE 3110, an asset retirement obligation is recognised as a liability when the obligation arises, measured at fair value and accreted over time.
For tax, paragraph 18(1)(e) denies that same amount until the cost is actually incurred. So the liability sits on the balance sheet and is added back on Schedule 1. Saying future cleanup costs are recognised “only when paid” describes the tax rule and gets the accounting wrong.
Most private Canadian companies apply ASPE — Part II of the CPA Canada Handbook — rather than IFRS, which is required only for publicly accountable enterprises. “Canadian GAAP” as a single body has not existed since the 2011 changeover.
Reporting Obligations Specific to Environmental Consulting Businesses
Risk Warning: disbursements recharged to a client are usually part of your taxable supply, not a pass-through. Where you incur a cost in your own name and recharge it, the recharge is consideration for your supply and takes your GST/HST treatment — even if you pass it on at exactly cost.
The exception is a cost incurred as agent for the client, where the agency is real and documented. For income tax the recharge is revenue under section 9 with the cost deducted, which nets to the same profit but reports very differently.
- Payroll across provinces changes both the remittance and the Regulation 402 allocation.
- Input tax credit support is prescribed by subsection 169(4) and the ITC Information Regulations: over $30 the supplier’s name and date, over $150 the supplier’s GST/HST registration number, the recipient’s name, terms and a description.
- Multi-year contracts with holdbacks need the contract terms on file, not just the invoices.
Specialized Tax Services for Environmental Consulting Businesses
Specialized Tax Services
Tax Services
Overview of Canadian Tax Requirements for Environmental Consultants
| Obligation | Deadline | Provision |
|---|---|---|
| T2 return | Six months after year-end | ITA 150(1)(a) |
| Balance of tax | Two months; three for an eligible CCPC | ITA 157(1)(b) |
| Corporate instalments | Last day of each month or quarter | ITA 157(1)(a), 157(1.1) |
| GST/HST, annual filer | Three months after year-end | Taxable supplies to $1.5M |
| GST/HST, quarterly filer | One month after quarter-end | $1.5M to $6M |
| GST/HST, monthly filer | One month after month-end | Over $6M |
| T4 slips and summary | Last day of February | Reg 205(1) |
Income is computed on the accrual basis under section 9, included when receivable under paragraph 12(1)(b), with work in progress carried under subsection 10(5). Unbilled work and holdbacks both need a standing schedule at year-end.
Tax Planning Strategies to Minimize Liabilities
Our fee is a flat annual amount including HST, quoted on your structure before any work begins. What moves it is the number of active projects, how many subcontractors you engage, the split between field staff and contractors, whether you operate in more than one province, and how much of your cost base is recharged to clients. We do not publish a single figure, because a single-province firm with two projects and a multi-province firm with thirty are not the same engagement.
Top Planning Mistakes
| Mistake | What Happens | How To Fix It |
|---|---|---|
| Deducting future phase provisions | Denied under 18(1)(e); reassessment with interest | Expense only when incurred; carry the ASPE 3110 liability and add it back |
| Treating a site allowance as non-taxable | Reclassified as a taxable benefit, with payroll arrears | Test against 6(6) and certify on Form TD4 |
| Paying accrued wages late | Deduction shifts to the year of payment | Pay within 179 days of year-end, ITA 78(4) |
| Filing SR&ED with the T2 | Nothing — but filing after 18 months loses it entirely | Diarise 18 months; no relief exists |
| Remitting payroll seven days after the pay period | Either early, or late with a 227(9) penalty | Confirm your remitter band and use its date |
| Holding invoices to defer income | No deferral; WIP is still included | Recognise when receivable under 12(1)(b) |
Maximizing Eligible Tax Credits and Deductions
SR&ED pays an investment tax credit at 35%, fully refundable, for a CCPC on its first $3 million of qualified expenditures, and 15% above that. Overhead is claimed either on the traditional method at actual cost or on the proxy method at 55% of directly engaged salaries — one or the other, never both.
Capital cost allowance on field equipment sits in Class 8 at 20% declining balance, with the rate set by Regulation 1100(1)(a)(viii) and the class described in Schedule II. The first claim is gated by the available-for-use rule in subsections 13(26) to (32).
Risk Warning: the half-year rule is suspended, so the arithmetic that circulates with it is wrong twice over. A Toronto firm buying $50,000 of air quality monitors mid-year claims $10,000 in year one — the full 20%.
Under the old half-year rule that figure would have been $5,000, so any worked example showing $10,000 “using half-year rule calculations” has contradicted itself. The rule is suspended for eligible property acquired after 31 December 2024 and available for use before 2034 under Bill C-15, which is why the full claim is right now.
Managing CRA Audits and Ongoing Compliance
- Provisions deducted before the cost was incurred.
- Site allowances with no 6(6) test and no TD4 on file.
- Unbilled work absent from income at year-end.
- Payroll allocated to the wrong province, or no Schedule 5 filed at all.
- Subcontractor payments with no slips issued.
For catch-up filing: order project costs by date, reconcile subcontractor agreements against the slips actually issued, assemble payroll by province, and correct the oldest year first so each year’s opening balances carry forward properly. Records are kept six years from the end of the taxation year to which they relate under paragraph 230(4)(b) — from the year-end, not from the filing date.
An Ontario firm had accrued roughly $85,000 for a future remediation phase and deducted it in the year the obligation was recognised.
The ASPE 3110 liability was correct on the balance sheet; the deduction was not. Paragraph 18(1)(e) denied it until the work was actually done, and the amount should have been added back on Schedule 1 and released when incurred. Figures changed for privacy.
Business Structure and Its Impact on Environmental Consultant Taxes
Business Structure
Structure
Sole Proprietorship vs Corporation: Tax Implications
| Aspect | Sole Proprietorship | Corporation |
|---|---|---|
| Tax filing | T1, business income on form T2125 | T2, six months after year-end |
| Tax rates | Personal marginal rates | 12.2% Ontario combined on small business income; 26.5% general |
| Income splitting | Limited | Possible, but subject to TOSI under section 120.4 |
| Liability | Unlimited personal liability | Limited to business assets |
| Deferral | None | Earnings retained at corporate rates |
Risk Warning: paying family members dividends is not free income splitting. Section 120.4 applies tax on split income at the top marginal rate to dividends paid to a related individual unless an exclusion applies.
The usual routes out are the excluded business test — an average of 20 hours a week in the business during the year or any five prior years — and the excluded shares test, which is unavailable to a corporation earning 90% or more of its income from services. An environmental consulting firm is a services business, so excluded shares are usually off the table. A reasonable salary for work actually performed is outside TOSI entirely.
Benefits of Incorporation for Environmental Consulting Firms
- The small business deduction on the first $500,000 of active business income, under section 125.
- Deferral, since retained earnings are taxed at 12.2% in Ontario rather than at personal rates.
- Limited liability, which matters where site work carries real exposure.
- Credibility with clients and lenders, and access to contracts that require a corporate counterparty.
Two grinds reduce the business limit. Taxable capital employed in Canada between $10 million and $50 million reduces it on a straight line under subsection 125(5.1). Adjusted aggregate investment income above $50,000 reduces it by $5 for every $1, eliminating it at $150,000. Associated corporations share one limit under section 256.
Incorporation also brings obligations: a T2 each year, payroll registration and remittance, the Ontario Annual Return through the Ontario Business Registry, and provincial allocation on Schedule 5 where you have a permanent establishment elsewhere. Books are kept under ASPE, Part II of the CPA Canada Handbook.
Corporate Structures Supporting Tax Optimization and Risk Management
- Canadian-controlled private corporation: defined in subsection 125(7), the usual structure, with access to the small business deduction and the salary-versus-dividend choice.
- Holding company: separates accumulated cash and equipment from the operating risk of site work, with intercorporate dividends usually flowing tax-free under section 112 subject to subsection 55(2).
- Professional corporation: please check the profession. In Ontario, professional corporations under section 3.1 of the Business Corporations Act are limited to a defined list — regulated health professions, lawyers, chartered professional accountants, social workers and veterinarians. Engineers are not on it. An engineering or environmental firm incorporates as an ordinary business corporation and holds a Certificate of Authorization from Professional Engineers Ontario.
Non-arm’s-length transactions between related corporations are tested under subsection 69(1), which deems fair market value where the price is not, and cross-border charges fall under section 247. Paragraph 18(1)(a) is the general earning-income test and does not govern intercompany pricing.
Two environmental firms a year arrive having been told they need a professional corporation because the principals are P.Eng.
Ontario does not offer one to engineers. What they need is an ordinary corporation and a Certificate of Authorization from PEO, which is a regulatory requirement rather than a tax structure. Figures changed for privacy.
Year-End Tax Planning Checklist for Environmental Consulting Firms in Canada
Year-End Planning Checklist
Year-End
Key Deadlines and Documentation Requirements
- Corporate T2 filing: six months after year-end. A 30 June year-end files by 31 December.
- Balance of tax: two months after year-end, or three for a CCPC claiming the small business deduction — before the filing date, not after it.
- Payroll remittance: by your remitter band. Regular remitters pay by the 15th of the following month.
- GST/HST: by assigned frequency. Late filing carries a penalty under ETA 280.1 of 1% plus 0.25% per month, on top of interest.
- Accrued remuneration: paid within 179 days of year-end.
- SR&ED: filed within 18 months of year-end.
- Records: retained six years from the end of the taxation year.
Organise contracts, phase reports, invoices, subcontractor agreements and payroll by province so year-end is assembly rather than reconstruction.
Essential Tax Deductions Relevant to Environmental Consultants
Risk Warning: overnight travel does not lift the 50% meals limit. Section 67.1 restricts food, beverages and entertainment to 50%, and being away from home overnight is not one of the exceptions.
The exceptions in subsection 67.1(2) are narrow: meals billed to a client and separately identified on the invoice, employer-hosted events for all employees at a location (up to six a year), registered fundraising events, and amounts included in an employee’s income as a taxable benefit. Long-haul truck drivers get 80% under 67.1(1.1). Subsection 67.1(2)(e) also relieves meals provided at a temporary or remote work site — which is the exception that actually matters for field crews, and it turns on the site, not on the overnight stay.
- Capital cost allowance: Class 8 field equipment at 20%, claimable once the asset is available for use.
- Board and lodging allowances: excluded under subsection 6(6) only where the special work site or remote work location conditions are met and Form TD4 is completed.
- Vehicle costs: Class 10.1 ceiling of $39,000 for a passenger vehicle; a work truck meeting the 248(1) tests is Class 10 at full cost.
- Professional insurance, dues and licensing, deducted as incurred.
Income Optimization and Deferral Strategies
Risk Warning: delaying the invoice does not defer the income. Income is included when it becomes receivable under paragraph 12(1)(b), and work in progress is carried under subsection 10(5) whether invoiced or not. Holding back billing moves the paperwork, not the tax.
Nor does buying equipment “at the start of a fiscal period” spread the deduction. CCA turns on whether the asset is available for use before year-end, not on which month you bought it — and with the half-year rule suspended, a purchase in month eleven gives the same first-year claim as one in month one.
What does work: paying accrued remuneration before day 179, timing discretionary bonuses across year-ends where the corporate and personal rates differ, managing the passive income grind under 125(5.1), and keeping instalments current so interest does not accrue on a cash flow that was always going to arrive.
Employee Compensation and Payroll Considerations
- Remit by your band; the 15th of the following month for a regular remitter.
- Pay accrued wages within 179 days of year-end under subsection 78(4).
- Classify workers on the Wiebe Door factors as refined in Sagaz and Connor Homes, with CRA Guide RC4110 and a ruling available on Form CPT1.
- Employees receive a T4 with CPP and EI; contractors invoice and receive a T4A above $500.
- Employer CPP at 5.95% and EI at 1.4 times the employee premium for 2026, plus CPP2 above the first ceiling.
- Directors are personally liable for unremitted source deductions under section 227.1.
A firm with crews on three northern sites had been paying a flat daily site allowance to everyone and reporting none of it.
Two sites met the subsection 6(6) conditions and one did not, and no TD4 had ever been completed for any of them. The fix was a site-by-site test, TD4s where they qualified, and T4 amendments where they did not. Figures changed for privacy.
Best Practices in Accounting and Record-Keeping for Environmental Consulting Businesses
Record-Keeping Best Practices
Records
Digital Record Keeping and Cloud Accounting Solutions
- QuickBooks Online or Xero for the ledger, with Wagepoint or an equivalent handling multi-province payroll.
- Invoices linked to billing milestones, with the unbilled balance visible rather than inferred.
- Costs coded to project and phase at entry.
- Subcontractor payments tracked against agreements so the T4A run at February is mechanical.
- Records kept in electronic form are acceptable under section 230, provided they are readable and retrievable for the full retention period.
Small firms with a handful of single-province projects can run their own bookkeeping. Once subcontractors, holdbacks, site allowances and a second province are in play, the judgement calls — what is incurred, what is receivable, which allowance qualifies — are where the money is, and they are not software questions.
Maintaining Critical Tax Documentation for Audit Readiness
The retention period is six years from the end of the taxation year to which the records relate, under paragraph 230(4)(b) — not six years from the filing date, and not six years from when you last used them. Section 286 of the Excise Tax Act imposes the same period for GST/HST.
- Client contracts showing scope, phases and holdback terms.
- Phase completion reports and milestone certificates.
- Invoices tied to those milestones, with the unbilled schedule at each year-end.
- Payroll records by province, supporting the Schedule 5 allocation.
- Site allowance logs and completed TD4 forms.
- Subcontractor agreements matched to slips issued.
- SR&ED project documentation contemporaneous with the work, not written up afterwards.
Secure and Confidential Financial Data Management
Client financial information is handled under PIPEDA, the federal private-sector privacy statute, together with the confidentiality obligations in the CPA Ontario Code of Professional Conduct. Ontario has no general private-sector privacy law of its own. Encryption at rest and in transit, access limited to staff who need it, and backups held somewhere that survives the loss of the office are the practical minimum.
Pro Tip: Please write the SR&ED documentation while the work is happening. A claim reconstructed seventeen months later rarely survives a technical review, even when the science was real.
A firm arrived with four years of records held only in a departed bookkeeper’s personal cloud account.
Section 230 requires records to be readable and retrievable for the full six years, and access that depends on one person’s login does not meet it. Nothing was lost in the end, but the CRA request sat unanswered for six weeks. Figures changed for privacy.
Frequently Asked Questions
Frequently Asked Questions
FAQ
What is the corporate T2 tax filing deadline for environmental consulting firms?+
Six months after the fiscal year-end under paragraph 150(1)(a). The balance of tax is due earlier, at two months after year-end, or three for a CCPC claiming the small business deduction.
When must accrued remuneration be paid to remain deductible?+
Within 179 days after the end of the taxation year, under subsection 78(4). Not three months, and not six. For a 31 December year-end that is 28 June. Pay later and the deduction moves to the year of payment.
What is the CCA rate for Class 8 field equipment?+
20% declining balance, under Regulation 1100(1)(a)(viii). The first claim requires the asset to be available for use under subsections 13(26) to (32), and the half-year rule is suspended for eligible property acquired after 31 December 2024.
How much of meal expenses can environmental consultants deduct?+
50% under section 67.1. Being away overnight is not an exception. The relevant carve-out for field crews is meals provided at a temporary or remote work site, which turns on the site rather than the travel.
What determines the GST/HST filing frequency?+
Annual taxable supplies. Annual filing to $1.5M with payment three months after year-end; quarterly to $6M; monthly above, each due one month after the period ends.
What is the payroll remittance deadline?+
It depends on your average monthly withholding amount, not your pay cycle. A regular remitter pays by the 15th of the following month. Accelerated remitters pay twice or four times a month. “Seven days after each pay period” is not a CRA band.
How long should environmental consultants retain tax records?+
Six years from the end of the taxation year to which they relate, under paragraph 230(4)(b) — from the year-end, not the filing date.
When is the SR&ED claim deadline?+
18 months after the fiscal year-end, being 12 months after the T2 due date. It is not the six-month T2 deadline. Subsection 37(11) makes filing a condition of the claim, so a late claim is lost and taxpayer relief cannot restore it.
How should income from phased projects and milestone billing be recorded?+
Included when it becomes receivable under paragraph 12(1)(b), with work in progress carried under subsection 10(5) at the lower of cost and fair market value. Reaching a milestone usually makes the amount receivable; not invoicing it does not change that.
How do you report unbilled work and holdbacks?+
Unbilled work is work in progress and is included. A holdback that is not legally receivable until certification or substantial performance under provincial construction legislation is not yet receivable, and so not yet income. The contract and the statute decide, not the invoicing.
What is the difference between a disbursement and a provision?+
A disbursement is a cost you incurred and recharge — revenue under section 9 with the cost deducted, and generally part of your taxable supply for GST/HST unless incurred as agent. A provision is an estimate of a future cost, recognised for accounting but denied for tax by paragraph 18(1)(e) until incurred.
How should accrued costs be handled?+
Deducted when the liability is incurred, meaning the obligation is certain and the amount determinable — not when invoiced or paid. Accrued remuneration has the extra 179-day condition in subsection 78(4).
What defines a special work site or remote work location?+
Subsection 6(6). A special work site requires duties of a temporary nature, a principal residence elsewhere that remains available, and at least 36 hours away. A remote work location requires that a self-contained domestic establishment could not reasonably be established or maintained. Both need Form TD4 completed.
What establishes a permanent establishment across provinces?+
Regulation 400(2): a fixed place of business such as an office, branch, workshop or warehouse, with deeming rules for employees or agents with general contracting authority, and for substantial machinery or equipment used in a province. “Significant activity” is not the test.
How does provincial allocation affect multi-provincial environmental consultants?+
Regulation 402 splits taxable income 50/50 between the share of gross revenue reasonably attributable to each permanent establishment and the share of salaries and wages paid there. It is filed on Schedule 5 with the T2.
What determines subcontractor versus employee status?+
The Wiebe Door factors as refined in Sagaz and, where there is a written agreement, Connor Homes: control, ownership of tools, chance of profit and risk of loss, tested against the actual working relationship. CRA Guide RC4110 sets out the approach and either party can request a ruling on Form CPT1.
What are the catch-up filing procedures for missed returns?+
Order project costs by date, reconcile subcontractor agreements against slips issued, assemble payroll by province, and file the oldest year first so opening balances and loss carryforwards flow correctly. Penalty and interest relief may be requested under subsection 220(3.1) on Form RC4288, within ten calendar years.
Can I defer income by holding back invoices?+
No. Income is included when receivable, and work in progress is carried under subsection 10(5) regardless of billing. The billed-basis election in section 34 was eliminated and phased out by 2024, and it never covered environmental consultants.
Eighteen questions, and the three on deadlines account for most of what actually goes wrong on an environmental consulting file.
The rest is documentation. The dates are where a deduction or a credit is won or lost outright. Figures changed for privacy.
Essential Tax Topics for Canadian Environmental Consulting Firms
Essential Topics and Best Practices
Quick Reference
Additional Key Points: Effective Tax Planning & Compliance
- Plan It Yourself or Hand It to a CPA Firm: single-province, single-project firms can self-manage; subcontractors, holdbacks and site allowances are judgement calls.
- Consulting Accounting: DIY vs CPA vs Non-CPA: a bookkeeper runs the day-to-day; only a licensed firm issues a CSRS 4200 compilation report.
- How Do We Handle a Firm at Gondaliya CPA: bookkeeping, GST/HST, payroll, compiled statements, the T2 and SR&ED timing on one flat annual fee.
- What Deliverables Do You Get: compiled financial statements, the T2 with GIFI and Schedule 5, GST/HST returns, payroll filings, an unbilled and holdback schedule, and CRA correspondence handled.
- How Much Does Consulting Accounting Cost in Canada: a flat annual fee including HST, quoted on your structure before work begins.
- Top Planning Mistakes and How to Prevent Them: provisions deducted early, allowances untested, accrued pay past day 179, SR&ED filed to the wrong deadline.
- Which Decisions Matter Across Segments: income timing, expense classification, worker status, provincial allocation, allowance treatment, CCA claims, record keeping, audit readiness, structure choice, payroll compliance.
- A Realistic Numeric Walkthrough: $50,000 of Class 8 monitors available for use in the year gives $10,000 of CCA at 20%, in full, because the half-year rule is suspended.
What to Prepare Before Planning Work Starts
- Organised contracts and invoices, with holdback terms visible.
- Project expense logs coded to phase.
- Payroll records by province.
- Subcontractor agreements and the slips issued against them.
- Prior tax filings and any CRA notices.
- The unbilled work schedule at your last year-end.
How to Choose the Right CPA Firm in Ontario
- Experience with phased project revenue, holdbacks and unbilled work.
- A working position on 6(6) site allowances and Form TD4.
- SR&ED handled to the 18-month deadline, not the T2 one.
- Provincial allocation on Schedule 5 actually prepared, not assumed away.
- A flat annual fee including HST, quoted before work begins.
- A licence to issue a CSRS 4200 compilation report, verifiable on the CPA Ontario directory.
Points Worth Carrying
- Accrued remuneration has 179 days, not three months.
- SR&ED has 18 months, and there is no relief for missing it.
- Payroll remittance follows your withholding band, not your pay cycle.
- A corporation cannot elect cash accounting.
- Overnight travel does not lift the 50% meals limit.
- The half-year rule is suspended for property acquired after 31 December 2024.
- Future remediation is an ASPE 3110 liability and a Schedule 1 add-back.
- Holding an invoice does not defer the income.
- Engineers cannot form a professional corporation in Ontario.
- Records run six years from the year-end, not the filing date.
Thirty points, and the ten at the end are all things a firm principal was told confidently by something they read.
None are obscure provisions. They are ordinary rules quoted with the wrong number of days attached. Figures changed for privacy.
Businesses We Serve
Industry Expertise
Environmental and technical consulting practices share the same issues. Here are ten and the usual finding.
| Practice | The Issue That Usually Appears |
|---|---|
| Phase I and II site assessment firms | Unbilled work absent from year-end income |
| Remediation contractors | Future phase provisions deducted before incurred |
| Air and water quality monitoring | Class 8 equipment claimed before available for use |
| Firms with northern field crews | Site allowances paid with no 6(6) test and no TD4 |
| Multi-province consultancies | No Schedule 5 allocation filed at all |
| Firms using drilling subcontractors | Payments made with no T4A issued |
| Practices developing novel techniques | SR&ED filed to the six-month deadline and lost |
| Owner-managed firms paying bonuses | Accrued pay cleared past day 179 |
| Firms recharging lab and disposal costs | Disbursements treated as a GST/HST pass-through |
| Engineering-led environmental practices | Professional corporation attempted where none exists |
- Phase I and II site assessment firms: WIP is income under 10(5).
- Remediation contractors: ASPE 3110 liability, Schedule 1 add-back.
- Air and water quality monitoring: available for use first, then CCA.
- Firms with northern field crews: test each site, file the TD4.
- Multi-province consultancies: Regulation 402, 50/50 formula.
- Firms using drilling subcontractors: T4A above $500.
- Practices developing novel techniques: 18 months, no relief.
- Owner-managed firms paying bonuses: 179 days, ITA 78(4).
- Firms recharging lab and disposal costs: your supply unless you acted as agent.
- Engineering-led environmental practices: ordinary corporation plus a PEO Certificate of Authorization.
The projects change. The questions do not: when did the income become receivable, when was the cost incurred, and which day did the payment clear.
A soil remediation contractor and an air quality monitoring practice look nothing alike on site and file nearly identical returns. Figures changed for privacy.
Professional Guidance and Quick Reference
Guidance
Professional Guidance: How Gondaliya CPA Handles Your Consulting Firm
Environmental consulting firms get into difficulty in a predictable set of ways: paying accrued remuneration at the three-month mark or at six months rather than within the 179 days that subsection 78(4) actually allows; filing the SR&ED claim with the T2 at six months instead of within 18 months, which under subsection 37(11) loses the claim outright with no relief available; remitting payroll “seven days after each pay period” when the due date follows the average monthly withholding amount and is the 15th of the following month for most firms; deducting a provision for a future remediation phase that paragraph 18(1)(e) denies until incurred, even though ASPE 3110 correctly puts the liability on the balance sheet; paying site allowances without testing the location against subsection 6(6) or completing Form TD4; and holding invoices back in the belief that income can be deferred, when it is included the moment it becomes receivable. Gondaliya CPA handles environmental consulting accounting on a flat annual fee.
We handle what decides the outcome: diarising the 179-day and 18-month dates separately from the T2 deadline, confirming your payroll remitter band in writing, building the unbilled work and holdback schedule at each year-end rather than reconstructing it, carrying the ASPE 3110 obligation on the statements while adding it back on Schedule 1, testing each field site against the 6(6) conditions and filing the TD4s, preparing the Regulation 402 provincial allocation on Schedule 5, issuing the T4A slips your subcontractor payments require, and keeping the SR&ED documentation contemporaneous so the claim survives a technical review.
Our team starts with your contracts, your unbilled schedule and one payroll cycle. Whatever you assess or remediate, you get clear advice and a fixed price before we start.
Quick Answers
At a Glance
- Accrued remuneration: 179 days after year-end, ITA 78(4)
- SR&ED deadline: 18 months after year-end, no relief
- SR&ED credit: 35% refundable on the first $3M for a CCPC
- Payroll, regular remitter: 15th of the following month
- T2 filing: six months; balance at two or three
- Accounting method: accrual; cash is farming and fishing only
- Future provisions: denied by ITA 18(1)(e) until incurred
- Meals: 50% under section 67.1
- Field equipment: Class 8 at 20%, half-year rule suspended
- Site allowances: ITA 6(6), certified on Form TD4
- Provincial allocation: Regulation 402, 50/50 formula
- Records: six years from the end of the taxation year
Who This Is For
Fit Check
- For: Incorporated Canadian environmental consulting firms running phased site assessment, monitoring or remediation work, engaging subcontractors, and deploying crews including across provincial lines.
- Not For: Sole proprietors, who file a T1 with form T2125 on different dates, and firms requiring a review or audit engagement, which we refer out.
People Also Ask
Quick Answers
Is accrued pay due in three months or 179 days?+
179 days after the end of the taxation year, under subsection 78(4). Three months is early and six months is late; 28 June for a 31 December year-end.
Can I file SR&ED with my T2?+
You can, but the deadline is 18 months after year-end, not six. Filing to the six-month date is safe; assuming that is the deadline is what loses claims, because subsection 37(11) makes late filing fatal.
Do I remit payroll seven days after each pay period?+
No. The due date follows your average monthly withholding amount. A regular remitter pays by the 15th of the following month; accelerated remitters pay twice or four times a month.
Can I deduct money set aside for a future remediation phase?+
Not until the cost is incurred. Paragraph 18(1)(e) denies reserves and contingent amounts. The ASPE 3110 liability still belongs on the statements — it is added back on Schedule 1.
Can an engineering firm be a professional corporation in Ontario?+
No. Ontario’s professional corporation list does not include engineers. An environmental or engineering practice incorporates ordinarily and holds a Certificate of Authorization from Professional Engineers Ontario.
Glossary of Key Terms
Glossary
- Subsection 78(4): The 179-day rule for unpaid remuneration.
- Paragraph 18(1)(e): The denial of reserves and contingent amounts.
- Subsection 37(11): Makes SR&ED filing a condition of the claim.
- Work in progress: Unbilled work, carried under subsection 10(5).
- Holdback: An amount not receivable until certification or substantial performance.
- Disbursement: A cost incurred and recharged, generally part of your supply.
- Provision: An estimated future cost, recognised for accounting, denied for tax.
- ASPE 3110: Asset retirement obligations, recognised when the obligation arises.
- Special work site: A temporary site qualifying under subsection 6(6).
- Remote work location: A location where domestic establishment is unreasonable.
- Form TD4: The declaration certifying a 6(6) exclusion.
- Permanent establishment: A fixed place of business under Regulation 400(2).
- Regulation 402: The 50/50 provincial allocation formula.
- Available for use: When an asset becomes eligible for CCA, ITA 13(26) to (32).
- Proxy method: SR&ED overhead at 55% of directly engaged salaries.
- CSRS 4200: The standard for a compilation engagement.
Environmental Consulting Tax Check
This quick self-check indicates where your firm most likely has room. Please answer the five questions below.
Environmental Consulting Tax Check
Five quick questions on your business. No fee shown.
Points to raise with us:
This is a general prompt, not tax or legal advice or a quote. Your position depends on your full facts. For a real review, please book a free consultation.
Want a checklist to work from? You can download our free environmental consulting tax checklist before your consultation.
Pay accrued remuneration within 179 days of the year-end, which is 28 June for a December year-end, and treat three months as early rather than as the rule. File SR&ED within 18 months, diarised separately from the T2, because subsection 37(11) makes a late claim no claim at all and taxpayer relief cannot reach it. Confirm your payroll remitter band in writing and use its date rather than a pay-cycle rule of thumb. Carry the future remediation obligation on the balance sheet under ASPE 3110 and add it back on Schedule 1, since paragraph 18(1)(e) denies it until incurred. Test every field site against subsection 6(6) and file the TD4, rather than paying a flat allowance and reporting nothing. Include unbilled work and recognise income when it becomes receivable, because holding the invoice defers the paperwork and not the tax. Prepare the Regulation 402 allocation on Schedule 5 wherever a crew creates a permanent establishment. And please keep six years of records from the year-end.
2026 Update — what is current: This article reflects rules current to 30 September 2026. The six-month T2 filing deadline under 150(1)(a), the Class 8 rate of 20%, the 50% meals limit in section 67.1 and the six-year retention requirement under 230(4)(b) are unchanged. Please note that accrued remuneration must be paid within 179 days of the year-end under subsection 78(4), not three months; that the SR&ED reporting deadline is 18 months after the year-end, being 12 months after the T2 due date, and that subsection 37(11) makes it a statutory condition with no taxpayer relief available; that SR&ED investment tax credits run at 35% fully refundable for a CCPC on the first $3 million of qualified expenditures and 15% above, with overhead on the traditional or 55% proxy method but never both; that payroll source deductions are remitted under section 153 and Regulation 108 by remitter band — the 15th of the following month for a regular remitter — with penalties under subsection 227(9) and director liability under 227.1; that business income is computed on the accrual basis under section 9, included when receivable under 12(1)(b), with work in progress carried under subsection 10(5) and the section 34 billed-basis election eliminated and fully phased out by 2024; that future remediation is an ASPE 3110 asset retirement obligation for accounting and a paragraph 18(1)(e) add-back for tax; that the half-year rule is suspended for eligible property acquired after 31 December 2024 and available for use before 2034 under Bill C-15; that site allowances follow subsection 6(6) with Form TD4; that provincial allocation follows Regulation 400(2) and Regulation 402 on Schedule 5; and that private-sector privacy is governed federally by PIPEDA, Ontario having no general private-sector privacy statute of its own.
Environmental Consultant Tax Planning Canada: How Gondaliya CPA Supports Firms
Start with your contracts and your unbilled schedule
Gondaliya CPA diarises the 179-day and 18-month dates separately from your T2 deadline, confirms your payroll remitter band, builds the unbilled work and holdback schedule at year-end, carries the ASPE 3110 obligation on the statements while adding it back on Schedule 1, tests each field site against subsection 6(6) and files the TD4s, prepares the Regulation 402 allocation on Schedule 5, issues the T4A slips your subcontractor payments require, and keeps SR&ED documentation contemporaneous — on a flat annual fee including HST with a one-business-day response. Please book a free consultation.
Next Steps
Please book a free consultation with Gondaliya CPA and bring your project contracts with their holdback terms, your unbilled work schedule at the last year-end, and one payroll cycle. Those three settle the income timing question, the accrued pay question and the remittance band, which is where the deductions and credits are won or lost. You will get a flat annual fee including HST before any work begins. We serve Toronto, Mississauga, Vaughan, Brampton, Ottawa and the rest of Ontario, and work with firms running projects across Canada. If our content helps, please add gondaliyacpa.ca as a preferred source on Google.
Published: · Last updated:
Editorial policy: We research against CRA, CPA Canada and CPA Ontario sources, fact-check the figures, and Sharad Gondaliya, CPA, reviews the content, which we update as the rules change.
Disclaimer: This article is educational information only and is not tax, legal, or financial advice. Figures marked illustrative are examples rather than quotes or guarantees. It reflects rules current to 2026, including the 179-day rule in subsection 78(4), the 18-month SR&ED reporting deadline, the Class 8 rate, the suspension of the half-year rule and the six-year retention requirement. Rates, limits and provincial rules change and outcomes depend on your specific facts. Please consult a licensed CPA before acting.

Sharad Gondaliya is a CPA Canada & CPA USA with 15 Years+ experience of Accounting, Tax, Payroll of Corporate Small Businesses as Tax Accountant. He is fully certified CPA Ontario and CPA USA and is well known among corporate small businesses for tax planning, efficient tax solutions, and affordable CPA services. Sharad is the Principal (Director) of Gondaliya CPA – Affordable CPA Firm in Canada. Licenses: CPA Ontario: 61040184 | CPA USA (MT): PAC-CPAP-LIC-033176 | CPA USA (WA): 57629 | CPA Firm License: 61330051 View Full Author Bio