



How to Respond to a CRA Audit Notice: Step-by-Step Guide for Canadian Businesses
Responding to a CRA Audit Notice in Canada: What to Do, in What Order
Receiving a CRA audit notice can feel stressful, but responding correctly is key to staying compliant and avoiding penalties. This guide walks Canadian business owners through the exact steps to take after receiving a notice, from reviewing the audit request and gathering required documents to communicating with the CRA, meeting deadlines, and managing the audit process efficiently.
Gondaliya CPA offers reliable CRA audit notice response and tax audit help Canada, guiding taxpayers through audit letters and information requests. Our expertise in handling audits ensures accurate responses to CRA audit notices, helping clients maintain compliance and reduce stress during tax audit processes.
Quick Summary
Read the notice, diarise the deadline, authorise your representative, and answer exactly what was asked. Those four steps in the first week matter more than anything you do afterwards, because they set the scope, the channel and the tone for the rest of the audit.
Reading time: 55 minutes.
Table of Contents
The Numbers That Matter
This article covers Canada, with Ontario and Toronto context, and reflects rules current to 2026. It is written for incorporated Canadian businesses that have received a CRA audit notice. Figures marked illustrative are examples, not quotes, and any masked engagement notes end with “Figures changed for privacy.” This is educational information only and not tax or legal advice. A criminal investigation follows a separate process with different powers and rights, and anyone who suspects one should obtain legal advice immediately.
Understanding the Notice
Understanding the Notice
Day One
What a CRA Audit Means for Canadian Businesses
Getting a Canada Revenue Agency audit notice can feel alarming for any business owner. It means the CRA wants to check your financial records to see whether you followed tax laws in Canada. They will look at your business financial statements, receipts, and other documents.
Knowing what an audit means helps you stay calm. It is not just about numbers. You also have rights as a taxpayer in Canada, and you can expect fair treatment during this process. You also need to know your responsibilities.
Key Points
- Tax Obligations: Make sure all your income is reported correctly.
- Business Financial Records: Keep clear records of expenses and revenues.
- Taxpayer Rights: You can object to and appeal CRA decisions.
- Taxpayer Responsibilities: Work with auditors while protecting your position.
How the CRA Selects Files for Audit
The CRA does not pick every file randomly for audits. It uses risk assessment to identify potential non-compliance. Knowing the factors helps businesses understand why a file was selected.
Common Triggers Include
- Inconsistent Reporting: Where reported income does not match third-party information such as slips filed by others.
- High Deductions Relative to Income: Large claims may attract attention, particularly where they are unusual for the sector.
- Industry Norms Deviations: Figures very different from comparable businesses may prompt a closer look.
- Random Selection: Some files are chosen as part of routine verification, carrying no implication at all.
Please note the last point specifically. Being selected does not mean the CRA has concluded anything about your file, and treating it as an accusation leads to over-responding in ways that make the audit harder.
Types of CRA Audits and Their Scope in Canada
The CRA runs several kinds of audits. Each has its own scope depending on the issues identified and the complexity of the file.
1. On-Site Audit
Auditors attend premises to review records directly. The premises need not be yours. A request to hold the work at your representative’s office is granted more often than businesses expect, and it changes the character of the whole audit by routing questions through someone who understands them.
2. Off-Site Audit
Conducted remotely on records you send, without an on-site visit. Scope is typically narrower, and you control what is provided.
3. Income Tax Audit
Focuses on whether income and deductions reported agree with the underlying financial records over the periods examined.
4. GST/HST Audit Procedures
Checks whether Goods and Services Tax or Harmonized Sales Tax was properly collected, reported and remitted, and whether input tax credits claimed meet the documentary requirements. Please remember that tax collected is held in trust, which puts this category in a different risk class from the others.
Key Information in a CRA Audit Notice
When you get an audit notification letter, read it carefully.
- It identifies which taxation years are being examined.
- It lists what information or documents you must provide.
- It names the auditor assigned and gives contact details.
- It states the taxes involved, which may be more than one.
- It sets a date for the first response.
This letter is an official request. Treat it seriously and respond within the time given to avoid penalties or further difficulty later.
Immediate Steps to Take After Receiving a CRA Audit Letter
Right after getting a CRA audit notice, act promptly.
- Review Your Documents: Collect the items relating to the years mentioned, such as invoices, bank statements and payroll records.
- Respond Timely: Follow the deadlines carefully so you do not create avoidable problems.
- Cooperate Fully: Be straightforward with auditors, while answering what was asked rather than volunteering material beyond it.
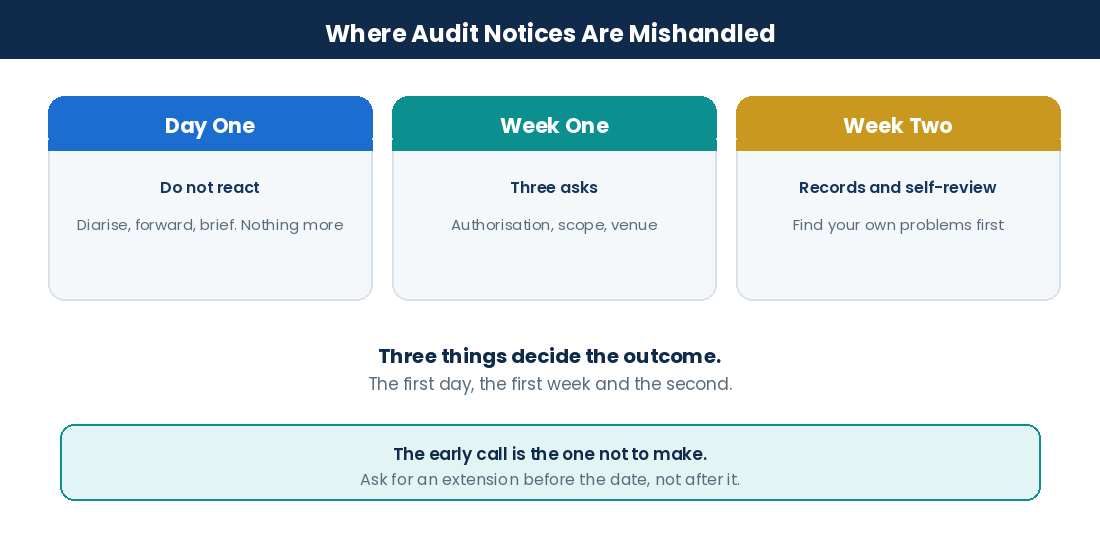
One addition to that list, and it matters more than the other three: do not reply informally by telephone before you know what you are answering. An off-the-cuff answer creates a record that may later need correcting, and correcting it costs more than the delay would have.
The most expensive minute in an audit is the first phone call answered without preparation. Nothing else in the first week is as easy to get wrong. Figures changed for privacy.
Risk Warning: Please do not answer substantive questions by telephone before you have read the notice properly and taken advice.
Preparing Your Response to a CRA Audit Notice
Preparing Your Response
Week One
Overview of the CRA Communication Process During an Audit
Communication matters a great deal during a CRA audit.
- Initial Contact: The auditor makes contact setting out the scope and next steps.
- Information Requests: Further questions follow, based on what the review surfaces.
- Proposal Stage: Where adjustments are contemplated, they are generally set out with an opportunity to respond before assessment.
- Final Report Issued: After the review concludes, the CRA sets out its findings.
The third stage is the one most guidance leaves out, and it is the most valuable point in the entire process. Responding properly there is cheaper, faster and more likely to succeed than objecting after an assessment has issued.
Preparing Your Response to a CRA Audit Notice
Getting a CRA audit notice can make any business owner nervous. Reacting promptly with a clear, complete reply puts you in a far better position.
First, read the notice carefully and establish exactly what the CRA wants. This step shapes your entire CRA audit response in Canada.
Steps to Respond to a CRA Audit Letter
- Read the letter closely. Note the issues, the review periods, and the deadlines.
- Confirm you received the notice within the time frame given.
- Check your records and identify which files match the questions asked.
- Get help from a tax accountant early, before substantive contact rather than after.
- Write clear answers addressing each point raised, and nothing beyond them.
- Send your response on time. Late replies can cause penalties or worse problems.
The fourth point is worth doing first rather than fourth. Authorising a representative before any substantive contact means questions arrive at someone who can assess what is really being asked before an answer is given.
Managing Deadlines and Extension Requests With the CRA
Meeting deadlines from the Canada Revenue Agency matters during audits. Missing them can lead to an assessment based on the information the CRA already holds.
Where deadlines are tight:
- Ask for an extension early, before the due date, with a genuine reason such as waiting on records from a third party.
- Keep in touch with written updates about progress, which shows engagement rather than avoidance.
- Understand that extensions are not guaranteed, so prepare on the basis you may not get one.
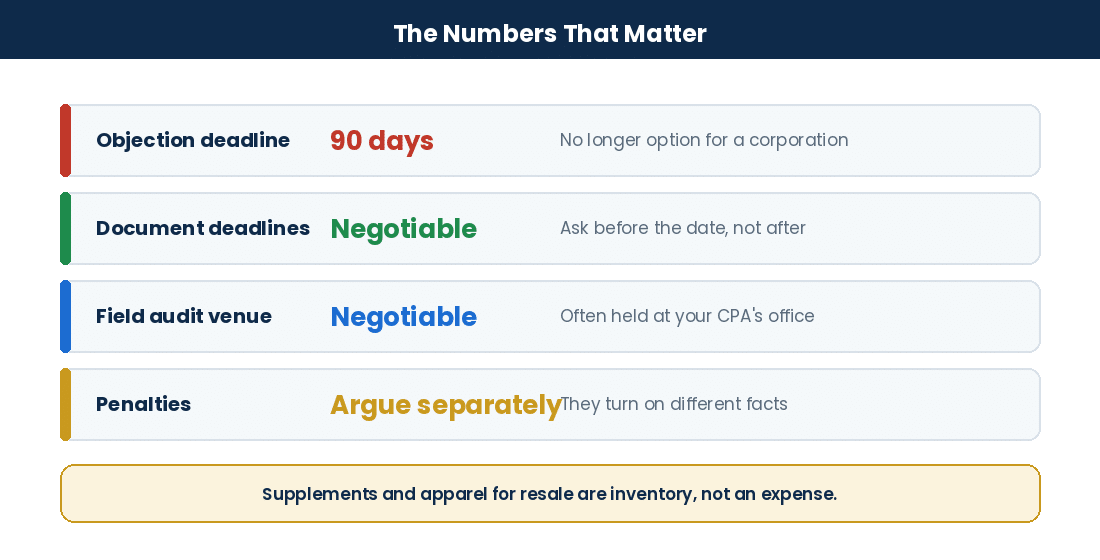
A distinction worth drawing here, because guidance frequently blurs it. Deadlines set by an auditor for producing documents are administrative and negotiable. The 90-day period to file a notice of objection is statutory and is not. Treating the first as immovable causes unnecessary panic; treating the second as flexible loses rights.
How to Respond to a CRA Audit Letter Effectively
Answering an audit letter means more than sending papers. It needs clear, direct communication.
Tips for your response
- Address each question one by one, using the same numbering as the notice.
- Give facts backed by documents rather than assertions.
- Do not guess. Check with your CPA, or say you will confirm and come back.
- Stay professional and avoid emotional language even where the position looks difficult.
- Send your reply before the deadline unless an extension has been agreed.
- Send what was asked, completely, and nothing beyond it.
The last item is an addition to the source list and it is the one that governs everything else. A wide response to a narrow question introduces material nobody asked about and is the most common way a scoped audit widens.
Authorising a representative is a form, and it takes ten minutes. It changes who fields every question for the next several months. Figures changed for privacy.
Key Stat: Auditor document deadlines are administrative and negotiable. The 90-day objection deadline is statutory and is not. Please treat them differently.
Records and Submission
Records and Submission
The Assembly
Reviewing and Organizing Bookkeeping Records for CRA Audit
Good bookkeeping makes audits easier to handle. The CRA looks closely at financial proof during reviews.
What records does the CRA expect
- General ledger showing income and costs
- Bank statements proving cash flow
- Invoices for sales and purchases
- Receipts for deductible expenses
- Payroll data, including slips and remittance confirmations
- Electronic files from accounting software
- Contracts and agreements for significant transactions
- The asset register with acquisition and disposal detail
Sort both paper and digital copies by date or transaction type so that what is requested can be produced quickly. Keeping clean corporate bookkeeping throughout the year shows you follow tax laws, and it makes an audit substantially cheaper to run.
Meeting CRA Document Submission Requirements
The CRA has clear expectations on how documents are provided. Following them avoids delays and returned submissions.
Here’s what you should do
- Follow exactly what the audit letter says about format.
- Use secure channels such as the CRA’s online portal rather than unprotected email.
- Include the identifying details requested, such as business and account numbers.
- Label files clearly with dates and contents so they can be located easily.
- Keep copies of everything sent, with proof of the date it went.
- Provide copies rather than originals wherever possible.
The last two are additions and both earn their place. A request and response log settles disputes months later that would otherwise become disagreements about memory, and originals that leave your possession are difficult to recover.
How to Provide Information and Records Securely to the CRA
Providing information securely protects your data during an audit.
- Use the CRA’s secure online portal for submissions where available.
- Avoid sending confidential files as unencrypted email attachments.
- Convert paper files into clear digital copies before submission.
- Name each file according to the auditor’s instructions.
- Use passwords where anything must travel outside official channels.
Business Tax Audit Checklist for Canadian SMBs
| Checklist Item | Description |
|---|---|
| Review All Filed Tax Returns | Check accuracy before sending further information |
| Gather Complete Financial Statements | Income statement and balance sheet for each year |
| Compile Supporting Documentation | Invoices, receipts and contracts that back the claims |
| Verify Payroll & GST/HST Filings | Confirm amounts agree to the payroll records and returns |
| Prepare Written Explanations | Explain any unusual transactions in writing |
| Reconcile Revenue to Sales Tax Filings | The comparison most likely to be run on your file |
| Identify Weak Points First | Before the auditor reaches them |
The last two rows are additions. Knowing where your own problems sit means preparing a position rather than improvising when the question arrives.
Common Areas of Focus in Small Business Audits
Small businesses are commonly examined on the areas where errors most often occur.
- Income reported consistently across all sales channels
- Valid expense deductions, including travel and meals
- Payroll treatment, especially contractor against employee status
- Correct GST/HST collection and remittance
- Capital asset classification and depreciation claims
- Shareholder account movement and personal expenditure
Responding to Additional Information Requests from the CRA
After the initial submission, the CRA may ask for more detail. Answer promptly with information backed by the invoices or contracts referenced in the question. Delay only extends the audit.
Keep copies of everything sent back, with dates noted. Where a request is broad, ask what specifically the auditor is trying to establish. The underlying question is usually much narrower than the request, and asking turns a large task into a small one.
Audit Evidence Submission Best Practices
- Follow the formats specified in the CRA’s instructions.
- Label files clearly with dates and contents for easy access.
- Use secure portals wherever possible to protect business data.
- Index attachments and reference them in a covering letter.
- Answer technical questions in writing rather than verbally.
Secure Audit Document Transfer Guidelines
- Avoid unsecured email attachments and use approved encrypted channels only.
- Convert paper files into clear digital copies before submission for easier processing.
- Retain the originals, and send copies.
Asking what a broad request is trying to establish turns it into a narrow one more often than not. It is the single most useful question in an audit. Figures changed for privacy.
Key Stat: Records must be kept six years from the end of the year they relate to, and longer for capital property. Please keep everything while a dispute is open.
Pro Tip: Please keep a log of every request and every document provided, with dates. It settles disputes that memory cannot.
The Examination and Its Outcome
The Examination and Its Outcome
The Middle Months
Understanding The CRA Audit Timeline in Canada
Knowing how long an audit usually takes helps businesses plan and seek support at the right moment.
Common stages in a tax audit timeline
- Receiving the first letter setting out scope and documents required
- The auditor reviewing submitted materials
- Follow-up questions asking for further information
- A proposal letter setting out intended adjustments, with time to respond
- Final decisions on adjustments and any penalties
- Closing correspondence confirming the results
Your cooperation affects duration. Prompt replies shorten an audit; slow ones extend it. Stage four is added to the source list because it is where the outcome is still changeable, and omitting it from a timeline hides the one point that matters most.
Navigating the CRA Audit Process
The CRA audit process starts when a business is selected, whether through risk assessment or routine verification. Knowing what to expect helps you prepare.
The timeline depends on complexity, and audits commonly run for months. Canada Revenue Agency audits come in two forms: desk audits conducted remotely, and field audits conducted at premises. Workload complexity varies by business size, industry, transaction volume and compliance history, and more detailed cases take longer because auditors examine more.
Throughout the audit, stay in contact. Reply promptly to notices and requests, and follow the communication arrangements agreed at the outset.
Managing Complex Audit Workloads and Risk Assessment
- Larger or more detailed cases need more preparation because more is examined.
- Identify the areas most likely to attract further review before the auditor reaches them.
- Maintain consistent record keeping to demonstrate compliance across the years examined.
What to Expect During the CRA Audit Examination
During the examination, expect a close look at the financial records supporting income and expenses.
An audit inquiry response means answering specific questions about your filings, clearly and honestly. A comprehensive examination can include off-site review of documents you send and on-site inspection of books, receipts, invoices, bank statements, contracts and payroll records.
On-site work lets auditors examine records directly and lets you explain matters immediately. That immediacy cuts both ways. Questions arrive conversationally over several days, and it feels unnatural to defer. An answer given from memory in a corridor carries the same weight as one given carefully in writing, and “I will confirm that and come back to you” remains complete and proper throughout.
Having organised bookkeeping reduces difficulty in this phase considerably, and having a CPA involved means questions are understood before they are answered.
How to Avoid Penalties During a CRA Audit
Penalties can be significant, so knowing how to avoid penalties during a CRA audit matters. The CRA applies penalties for late filing, for failures to remit, and for understatements involving a degree of culpability.
- Reply Quickly: Answer within the deadlines shown in the audit notice.
- Send Full Documents: Provide the records requested, organised as asked.
- Keep Accurate Records: Ensure bookkeeping is current and supportable.
- Be Honest: Raise errors you find yourself, with a proposed correction.
- Ask Experts Early: Speak to professionals experienced in CRA penalty avoidance.
A point on the fourth item. Where an error is real and within the scope, raising it with a proposed correction is materially better than having it found, and it bears directly on whether a gross negligence penalty is considered. Where the error sits outside the scope, the calculation is different and worth taking advice on first.
Handling Audit Penalties and Compliance Order Warnings
- Respond within deadlines to avoid penalties related to late or incomplete filings.
- Provide documentation showing genuine effort toward compliance.
- Remember that penalty structures are formula-based on the amounts and periods involved, so no article can tell you what a particular failure will cost.
Recognizing Common Triggers That Lead to Further Scrutiny
- Audit Risk Factors: Significant gaps between reported figures and sector norms, repeated adjustments to past returns, and large swings in deductions without explanation.
- Common Triggers: Expenses disproportionate to income, inconsistent bookkeeping, and missing documents supporting claims.
- Fraud Suspicion: The CRA looks closely where it appears income has been concealed or records fabricated.
- Deliberate Errors vs Simple Mistakes: Honest mistakes generally lead to reassessment without heavy penalties where corrected promptly. Deliberate misstatement attracts substantially worse consequences.
Understanding the CRA Reassessment Explanation and Outcomes
When the audit concludes, the CRA issues a Notice of Reassessment explaining any changes made.
The notice shows whether more tax is owed, with any interest and penalty, or whether a refund arises. The normal reassessment period is generally three years for a Canadian-controlled private corporation, running from the date of the original notice of assessment rather than from the filing date. Please note there is no time limit at all where there was misrepresentation attributable to neglect, carelessness or wilful default.
Review the notice carefully with professional advice before responding, comparing it against the proposal letter, because adjustments are sometimes dropped or modified after a submission.
Understanding the Tax Reassessment Process Post-Audit
- The CRA issues a Notice of Reassessment setting out the adjustments made.
- Check the arithmetic independently, and identify what is tax, interest and penalty.
- Note the date, because the objection period runs from it.
- Seek advice before responding or appealing.
The proposal letter is the cheapest place to change an outcome and the one businesses most often treat as a formality. After the reassessment everything costs more. Figures changed for privacy.
Risk Warning: The reassessment clock runs from the original notice of assessment, not the filing date, and there is no limit where misrepresentation is involved.
If You Disagree
If You Disagree
The Dispute
Steps to Take If You Disagree with a CRA Reassessment
Disagreeing with a reassessment is normal. Handling it correctly means using the official channels available for audit dispute resolution in Canada.
- Look Over the Reassessment Notice. Check carefully why the figures changed, comparing against what you filed and against the proposal letter.
- Send a Notice of Objection. This starts the formal process. A corporation has 90 days from the date of the notice. Include clear reasons and the facts supporting your position.
- Gather Support Papers. Collect receipts, contracts and ledgers establishing the position, using the business tax audit checklist standards above.
- Get Help if Needed. Tax accountants skilled in audit objections can construct the objection properly.
- Look Into Relief Options. A due diligence argument may answer certain penalties, and taxpayer relief may cancel penalties and interest where circumstances were beyond your control.
Two corrections belong here, because both circulate widely and both cost people rights.
The first concerns the deadline. Guidance often states you have 90 days “or one year if no payment is due”. That extended alternative, the later of 90 days from the notice or one year after the return’s filing due date, is available to individuals and certain trusts. It does not apply to corporations. A corporation has 90 days. Where the date is missed, an application for an extension of time may be possible within limits, but it is a separate application and it is not guaranteed.
The second concerns relief. A due diligence defence and a taxpayer relief request are different things. Due diligence argues that a penalty should not apply because reasonable care was taken. Taxpayer relief asks the CRA to cancel penalties and interest as a discretionary matter, and does not change the underlying tax. Conflating them means arguing the wrong thing in the wrong forum.
Overview of the Audit Dispute Process in Canada
Canada provides clear steps for taxpayers contesting audit results.
Main steps are:
- File an objection setting out why you disagree, with the facts and the reasons
- An Appeals officer independent of the audit reconsiders the file
- Discussion may resolve the matter without proceeding further
- Where it does not, an appeal to the Tax Court of Canada is available
During this process:
- Keep careful records of all communication with the CRA
- Answer all requests before their deadlines
- Understand that interest generally continues to accrue on a disputed amount
The independence of Appeals is the reason objections succeed more often than businesses expect. The officer did not conduct the audit and has no investment in its conclusions. That only helps where the objection gives them something to work with, which is why it needs to be a properly argued document rather than a letter expressing disagreement.
Navigating the Tax Audit Appeal Procedure Efficiently
- File objections within 90 days using the official route, explaining the dispute factually.
- Engage professionals familiar with the legislation for the best result.
- Decide whether to pay the disputed amount pending the objection, since interest continues.
- Weigh the cost of Tax Court against the amount genuinely in dispute.
Important Taxpayer Fairness and Compliance Obligations
- Understand your rights under Canada’s tax laws, including fair treatment.
- Meet your obligation to provide complete and accurate records.
- Protect your information while sharing it securely with CRA auditors.
- Cooperate fully, while knowing when to seek advice on complex issues.
- Monitor statutory time limits closely to preserve your rights.
Key Audit Communication Protocols for Canadian Businesses
- Respond clearly and on time to all CRA letters.
- Confirm receipt of notices and requests promptly.
- Use secure document submission channels.
- Keep copies of all correspondence and proof of delivery.
- Address each auditor query with precise explanations backed by documents.
- Avoid informal or emotional language in communications.
- Route everything through one point of contact so answers stay consistent.
The 90-day corporate objection deadline is the one people get wrong, because the extended alternative they have read about applies to individuals. Figures changed for privacy.
Risk Warning: A corporation has 90 days to object. The “or one year” alternative applies to individuals and certain trusts, not to corporations.
Professional Help and Working With Gondaliya CPA
Professional Help and Working With Us
The Support
When and How to Seek Tax Accountant or Professional Audit Help
Dealing with a CRA audit notice alone can cause small businesses real problems, since missed obligations lead into penalties and long disputes.
When To Reach Out
- Right after getting any CRA audit letter, before replying to anything
- If unclear about what documents the CRA needs
- Facing difficult issues such as reassessments or suggestions of concealment
- Preparing appeals or filing a notice of objection
- Where a proposal letter has arrived and a submission needs building
Why Hire A CPA Or Tax Pro
- They explain what CRA letters actually mean
- They organise records to match what the auditor is asking
- They represent you in communications, reducing stress and error
- They advise on penalty exposure and relief options
- They know when a broad request has a narrow question behind it
Our flat fees and 30-day money-back arrangement make costs clear. Contact us at 647-212-9559 or info@gondaliyacpa.ca for help during your CRA audit response.
Best Practices for Corporate Tax Compliance Support
Keeping up with corporate tax compliance support helps avoid penalties and keeps dealings with the CRA straightforward. Canadian businesses need to follow the Income Tax Act and the Excise Tax Act carefully.
- File and pay on time. Deadlines matter, and penalties track the amount owing.
- Treat transactions the same way every time. Changing methods without reason invites questions.
- Keep clear, detailed records. Proof of income, expenses, credits and deductions.
- Check your controls regularly. Catch mistakes before an auditor does.
- Watch for law changes. New rules may affect your business or sector.
Maintaining Accurate Bookkeeping Records Post-Audit
Once an audit concludes, tidy records matter more rather than less.
- Full financial records: Revenue, costs, assets, liabilities and equity.
- Electronic filing systems: Invoices, receipts and statements stored accessibly and readably.
- Invoices: Both sales invoices issued and purchase invoices received.
- Bank reconciliation: Match statements to the books monthly.
- Retention: Six years from the end of the year the records relate to.
Correcting the years examined without changing how the books are kept means the same finding arrives at the next examination. Our bookkeeping and accounting services keep the controls in place afterwards.
Proactive Audit Preparation Steps for Canadian Businesses
- Read your audit notice carefully to understand what the CRA wants.
- Gather the requested documents promptly, including statements, contracts and payroll records.
- Check your returns against your documents.
- Find any unclear or wrong items before speaking to auditors.
- Reply within the deadlines set.
Industry-Specific Considerations for Doctors, Dentists, Construction, Real Estate and More
| Industry | Common Audit Risks | Key Focus Areas |
|---|---|---|
| Doctors & Dentists | Claims on office supplies and professional fees | Proof of expenses, and apportionment where supplies are exempt |
| Construction Companies | How labour costs are classified | Payroll accuracy and subcontractor reporting |
| Real Estate | Whether income is capital or on account of income | Property sale documentation and intention at acquisition |
| Skilled Trades | Cash handling | Clear invoices and deposits reconciled to revenue |
| Daycare Providers | Reconciling subsidies | Government funding detail, and exempt supply treatment |
| E-commerce | Tracking sales across provinces | GST/HST collection, and processor settlements recorded gross |
The Role of Professional CPA Support in Minimizing Future Audits
- CPAs guide filings that match the current rules.
- They clear up confusion between you and the auditor.
- They put controls in place so data stays accurate.
- They stay with you from the first letter through to any appeal.
- Their involvement means questions are understood before answers are given.
Choosing Gondaliya CPA for Your Tax Audit Needs
Gondaliya CPA handles Canadian tax audits for incorporated small and medium businesses. We give clear guidance and handle the detail so you do not have to.
How Gondaliya CPA Supports Canadian Businesses with CRA Audit Notice Response
- Replying on time to meet CRA deadlines
- Cooperating fully with auditors while keeping responses to scope
- Providing requested information, organised and accurate
- Explaining tax matters in plain language
- Building a real submission at the proposal stage
The CPA Process Deliverables for Effective Tax Audit Help Canada
| Deliverable | What It Involves |
|---|---|
| Initial Case Assessment | Detailed review of the notice and strategy planning |
| Document Preparation | Complete organisation and verification, limited to scope |
| Communication Management | Direct liaison with the CRA as authorised representative |
| Comprehensive Examination Support | In-depth analysis and identification of the real issues |
| Representation at Meetings | Full representation during the audit |
| Post-Audit Follow-up | Assistance with proposal submissions and reassessment disputes |
Pricing Factors and Flat-Fee Structure at Gondaliya CPA
| Service Component | Description | Pricing Impact |
|---|---|---|
| Initial Consultation | Review case details | Included |
| Document Review & Organization | Verification and preparation | Included |
| Correspondence Handling | Responding to letters | Included |
| Audit Representation | Meetings and negotiations | Quoted by complexity |
| Additional Research/Analysis | Complex issues identified | Quoted before proceeding |
Fees are quoted before work begins, including HST. Where something unexpected arises, we tell you before doing it.
Risks of Non-Compliance and How Gondaliya CPA Helps Manage Them
| Risk Category | Potential Consequence | Benefit of Professional Help |
|---|---|---|
| Penalties | Charges arising from late or inaccurate filings | Timely, complete replies reduce exposure |
| Scope Expansion | An audit widening beyond its original subject | Controlled disclosure keeps it contained |
| Missed Deadlines | Losing the right to object | Deadline management preserves your options |
| Enforcement Action | Collection activity on assessed amounts | Representation and payment arrangements |
Comprehensive Business Tax Audit Checklist Provided by Gondaliya CPA
- Organised financial statements showing income and expenses
- Complete bookkeeping supporting the reported figures
- Payroll records matching the returns and remittances
- Receipts and invoices proving the expenses claimed
- Bank statements reconciled to the books
- Consistent corporate filings across the years examined
- Clear evidence that records are properly maintained
Why Trust Gondaliya CPA: Credentials, Experience, and Client Commitment
- Sharad Gondaliya, CPA, brings 15+ years focused on Canadian small business tax and audits.
- We check the detail carefully to avoid errors that extend an audit or raise questions.
- Clients get ongoing updates and plain explanations without jargon.
- We handle your information in accordance with privacy obligations.
- We tell you plainly where we think a position will not hold, rather than defending it at your cost.
Next Steps: Contact Gondaliya CPA for Professional Tax Audit Assistance
Bring three things: the CRA letter, the returns for the years covered, and your records for the scope. Those let us tell you where the exposure sits and what the response should be. Our CRA audit guide covers preparation, and our comparison of a CRA audit against a CRA review explains what the letter you received actually is.
Contact Gondaliya CPA at info@gondaliyacpa.ca, call 647-212-9559, or send us a message.
We tell clients where a position will not hold at the start rather than at the proposal stage. Defending the indefensible costs money on the way to the same answer. Figures changed for privacy.
Pro Tip: Please fix the process alongside the years examined. Otherwise the same finding arrives at the next audit.
FAQs on Responding to a CRA Audit Notice
Frequently Asked Questions
FAQ
What is the audit response extension process in Canada?+
You can request an extension from the CRA if you need more time to submit documents. Ask before the due date with a genuine reason. Extensions on auditor document deadlines are administrative and commonly granted; they are not guaranteed.
How does the CRA manage audit timelines and deadlines?+
Auditor deadlines for producing documents are administrative and negotiable. The 90-day objection period is statutory and is not. Timely responses shorten audits, while delays extend them.
What are common reasons for audit follow-up requests by CRA?+
The CRA may seek clarification or further documents after an initial submission. Prompt, accurate replies reduce audit duration. Where a request is broad, ask what it is trying to establish.
How does Gondaliya CPA ensure satisfactory response during CRA audits?+
We provide clear, documented answers addressing each query, keeping the response to the scope of what was asked and routing everything through a single point of contact.
What is the role of professional judgment in responding to a CRA audit letter?+
Professional judgment guides how to interpret questions, what a broad request is really asking, which documents actually answer it, and where a position should be conceded rather than defended.
How can taxpayers protect their rights and meet obligations during an audit?+
Cooperate, provide truthful information, maintain records, and take advice. Answering what was asked completely is full cooperation; volunteering material beyond it is not required.
What should be included in audit evidence collection for a tax audit?+
Invoices, receipts, bank statements, contracts, payroll data and bookkeeping reports for the audit periods, indexed and referenced in a covering letter.
How does the audit dispute process work in Canada?+
File a notice of objection within the deadline. An Appeals officer independent of the audit reconsiders the file, and an appeal to the Tax Court is available if that does not resolve it.
How long does a corporation have to object to a reassessment?+
90 days from the date of the notice. The alternative of one year after the filing due date applies to individuals and certain trusts, not to corporations.
What if I miss the objection deadline?+
An application for an extension of time may be possible within limits, but it is a separate application and it is not guaranteed. The 90-day date should be diarised the day the notice arrives.
What is the importance of monitoring procedures during an ongoing tax audit?+
Tracking deadlines and communications prevents missed responses and gives you a record of what was asked and what was provided, which settles later disputes.
When should a taxpayer consider changing their taxpayer representative during an audit?+
Where communication has broken down or the necessary expertise is not there. A change can be made by filing a new authorisation, and it is better done early than late.
Should I tell the auditor about an error I found myself?+
Where it is real and within the scope, usually yes, with a proposed correction. It affects how the file is viewed and bears on whether a gross negligence penalty is considered.
Can I hold a field audit somewhere other than my premises?+
Often yes. Holding it at your representative’s office keeps records controlled and your operation undisturbed, and it is granted more often than businesses expect.
Is due diligence the same as taxpayer relief?+
No. A due diligence argument says a penalty should not apply because reasonable care was taken. Taxpayer relief asks the CRA to cancel penalties and interest as a discretionary matter, and does not change the tax.
How far back can the CRA reassess?+
Generally three years from the original notice of assessment for a CCPC. There is no time limit where there was misrepresentation attributable to neglect, carelessness or wilful default.
Sixteen questions and one underneath most of them: is this deadline administrative or statutory. The answer decides how much room you have. Figures changed for privacy.
The Response Protocol
The Response Protocol
Quick Reference
Day One
- Read the notice for years, taxes, issues and the auditor’s name.
- Diarise the response deadline immediately.
- Do not answer substantive questions by telephone yet.
- Send the notice to your accountant before replying to anything.
- Confirm receipt within the time frame given.
Week One
- Authorise your representative before substantive contact.
- Ask for the scope in writing, covering years, taxes and issues.
- Request the venue and schedule that suit you.
- Ask for an extension now if the timeline is unrealistic.
- Start the request and response log.
- Identify your own weak points before the auditor reaches them.
Through the Examination
- Provide what was asked, completely, and nothing beyond it.
- Route every response through one point of contact.
- Ask what a broad request is trying to establish.
- Send copies, not originals.
- Use secure channels rather than unprotected email.
- Label and index files as instructed.
- Answer technical questions in writing.
- Say you will confirm rather than guessing.
- Take advice before raising anything outside the scope.
- Follow up where weeks pass without a reply.
Proposal and After
- Treat the proposal letter as the main event, not a formality.
- Concede plainly what is genuinely correct.
- Give specific grounds and documents for each disputed point.
- Argue any penalty separately from the tax.
- Compare the reassessment against the proposal letter.
- Check the arithmetic independently.
- Diarise the 90-day objection date the day the notice arrives.
- Decide whether to pay the disputed amount pending objection.
- Fix the process behind each adjustment, not just the numbers.
For help with a notice you have received, contact Gondaliya CPA at info@gondaliyacpa.ca, call 647-212-9559, or book a free consultation.
Thirty points across four phases, and the first eleven happen in the first week. That week sets the terms for the rest. Figures changed for privacy.
Businesses We Serve
Industry Expertise
What the notice asks about differs by business. Here are ten and where the effort belongs.
| Situation | Where the Effort Belongs |
|---|---|
| A notice just received | Authorisation, scope and venue, this week |
| A visit proposed at your premises | Requesting your accountant’s office instead |
| A GST/HST examination | Trust money, so the exposure is different |
| A payroll examination | Classification and remittance, with director exposure |
| Broad information requests arriving | Asking what they are trying to establish |
| Staff being asked questions directly | Routing everything through one person |
| An error you found yourself | Advice on whether and how to raise it |
| A proposal letter on the desk | A documented submission before assessment |
| A reassessment you dispute | An objection within 90 days, no extension by right |
| Records that will not support the filing | Advice before anything is submitted |
- A notice just received: Three steps, straight away.
- A visit proposed at your premises: Ask for the alternative.
- A GST/HST examination: Collected tax is not yours.
- A payroll examination: Directors carry it personally.
- Broad information requests arriving: Narrow the question.
- Staff being asked questions directly: One voice only.
- An error you found yourself: Timing changes everything.
- A proposal letter on the desk: The cheapest leverage there is.
- A reassessment you dispute: Ninety days, properly argued.
- Records that will not support the filing: Fix first, reply second.
The notice changes the detail. It does not change the first week, which is authorisation, scope and venue. Figures changed for privacy.
Professional Guidance and Quick Reference
Guidance
Professional Guidance: How Gondaliya CPA Handles Your Audit Notice
Businesses mishandle CRA audit notices in a predictable set of ways: answering substantive questions by telephone on the day the letter arrives, never authorising a representative so every question lands on whoever picks up, letting a field audit run at their own premises where staff answer informally, providing whatever is requested without asking what it is for, missing an administrative deadline silently when an extension was available for the asking, treating the proposal letter as a formality rather than the last cheap chance to change the outcome, and assuming the objection deadline is flexible when for a corporation it is 90 days with no alternative. Gondaliya CPA handles CRA audit notice response on a fee quoted before work begins.
We handle what decides the outcome: reading the notice to establish scope and taxes, authorising representation before substantive contact, agreeing venue and schedule in writing, preparing records for the scope rather than generally, providing documents through one controlled channel with a full log, answering technical questions in writing, building a real submission at the proposal stage, and objecting within 90 days where the reassessment is wrong.
Our team starts with the CRA letter, the returns for the years covered and your records for the scope. Those three tell us where the exposure sits. Whatever your sector, you get clear advice and a fixed price before we start.
Quick Answers
- Day one: Diarise, and stop replying
- Week one: Authorise a representative
- Scope: Ask for it in writing
- Venue: Often can sit at your CPA’s office
- Document deadlines: Administrative and negotiable
- Objection deadline: Statutory, and 90 days
- The “one year” alternative: Individuals, not corporations
- Disclosure: What was asked, nothing beyond
- Proposal letter: The cheapest place to change it
- Penalties: Argue them separately from the tax
Who This Is For
- For: Incorporated Canadian businesses that have received a CRA audit notice, or that want to understand the sequence before one arrives.
- Not For: Criminal investigations, which follow a separate process with different powers and rights and require legal advice rather than general guidance.
People Also Ask
What is the proposal letter and why does it matter?+
It sets out the adjustments the CRA intends to make before the assessment issues, with time to respond. It is the cheapest and most effective point to change an outcome.
Does interest stop while I object?+
Generally not. Interest continues to accrue on a disputed amount, so there is a cash decision about whether to pay it pending the objection.
What if this becomes a criminal matter?+
Stop and obtain legal advice immediately. A criminal investigation follows a separate process with different powers and rights, and general audit guidance does not apply.
Glossary of Key Terms
- Audit notice: The letter opening an examination, naming the auditor.
- Scope: The years, taxes and issues the examination covers.
- On-site audit: Conducted at premises, which need not be yours.
- Off-site audit: Conducted remotely on records you send.
- Representative: A person you authorise to deal with the CRA for you.
- Request log: Your record of what was asked and what was provided.
- Administrative deadline: An auditor’s date for documents, negotiable.
- Statutory deadline: A date set by legislation, such as the 90 days to object.
- Proposal letter: Intended adjustments set out before assessment.
- Notice of reassessment: The formal revision of a previously assessed return.
- Notice of objection: A formal dispute, filed within 90 days for a corporation.
- Appeals: The function that reconsiders, independent of the audit.
- Due diligence: An argument that a penalty should not apply despite an error.
- Taxpayer relief: A discretionary request to cancel penalties and interest.
- Normal reassessment period: Generally three years for a CCPC.
- Misrepresentation: Where no reassessment time limit applies.
Audit Notice Check
This quick self-check indicates where your operation most likely has room. Please answer the six questions below.
Audit Notice Check
Six quick questions on your notice. No fee shown.
Points to raise with us:
This is a general prompt, not tax or legal advice or a quote. Your position depends on your full facts. For a real review, please book a free consultation.
Want a checklist to work from? You can download our free audit notice response checklist before your consultation.
Diarise the deadline the day the notice arrives. Do not answer substantive questions by telephone first. Authorise a representative before substantive contact. Ask for the scope in writing. Provide what was asked and nothing beyond it. Build a real submission at the proposal stage. Object within 90 days, since a corporation has no longer alternative. Please keep six years of records.
2026 Update — what is current: This article reflects rules current to 2026. The 90-day period to file a notice of objection, the generally three-year normal reassessment period for a CCPC, the six-year record retention requirement and the formula-based structure of the late-filing, failure-to-remit and gross negligence penalties are unchanged. Please note that a corporation has 90 days from the date of the notice of reassessment to object, and the alternative of one year after the return\u2019s filing due date applies to individuals and certain trusts rather than corporations, so guidance offering corporations a longer alternative is wrong; that an application for an extension of time may be possible within limits but is a separate application and not guaranteed; that deadlines set by an auditor for producing documents are administrative and negotiable while the objection period is statutory and is not, and the two should not be treated alike; that a due diligence argument and a taxpayer relief request are different things addressed to different questions; that the normal reassessment period runs from the original notice of assessment rather than the filing date, with no limit at all where there was misrepresentation attributable to neglect, carelessness or wilful default; that the proposal stage before assessment is the most effective point to change an outcome and belongs in any accurate audit timeline; and that a field audit can often be held at your representative\u2019s office rather than your premises.
CRA Audit Notice Response Canada: How Gondaliya CPA Supports Businesses
Start with the notice itself
Gondaliya CPA reads the notice to establish scope and taxes, authorises representation before substantive contact, agrees venue and schedule in writing, prepares records for the scope rather than generally, provides documents through one controlled channel with a full request log, answers technical questions in writing, builds a real submission at the proposal stage and objects within 90 days where the reassessment is wrong, on a fee quoted before work begins including HST with a one-business-day response. Please book a free consultation.
Next Steps
Please book a free consultation with Gondaliya CPA and bring the CRA letter, the returns for the years covered, and your records for the scope. Those three tell us where the exposure sits, what the response should be, and what remains to claim on the equipment, and where the documentation is thin. You will get a flat annual fee including HST before any work begins. If our content helps, please add gondaliyacpa.ca as a preferred source on Google.
Published: · Last updated:
Editorial policy: We research against CRA and CPA Ontario sources, fact-check the figures, and Sharad Gondaliya, CPA, reviews the content, which we update as the rules change.
Disclaimer: This article is educational information only and is not tax, legal, or financial advice. Figures marked illustrative are examples rather than quotes or guarantees. It reflects CRA rules current to 2026, including the $30,000 GST/HST threshold, the Class 8 rate, Class 13 leasehold treatment, the half-year rule, and the six-year retention requirement. Rates, limits and expensing rules change and outcomes depend on your specific facts. Please consult a CPA Ontario member before acting.

Sharad Gondaliya is a CPA Canada & CPA USA with 15 Years+ experience of Accounting, Tax, Payroll of Corporate Small Businesses as Tax Accountant. He is a CPA Ontario member (61040184) and holds US CPA licences in Washington and Montana and is well known among corporate small businesses for tax planning, efficient tax solutions, and affordable CPA services. Sharad is the Principal (Director) of Gondaliya CPA – Affordable CPA Firm in Canada. Licenses: CPA Ontario: 61040184 | CPA USA (MT): PAC-CPAP-LIC-033176 | CPA USA (WA): 57629 | CPA Firm License: 61330051 View Full Author Bio