How to Maximize Input Tax Credits (ITCs) During GST/HST Filing
Quick Summary
Input Tax Credits (ITCs) allow Canadian businesses to recover GST/HST paid on eligible business expenses, helping reduce overall tax payable. This guide explains how to correctly claim ITCs during GST/HST filing, which expenses qualify, common mistakes to avoid, and practical strategies to maximize your credits while staying fully compliant with CRA rules.
Input Tax Credits Canada are essential for GST/HST registrants looking to reduce tax costs by claiming eligible ITCs on business expenses. Gondaliya CPA helps with GST/HST filing, preparing taxes, and ensuring accurate claims of input tax credits to maximize your tax benefits.
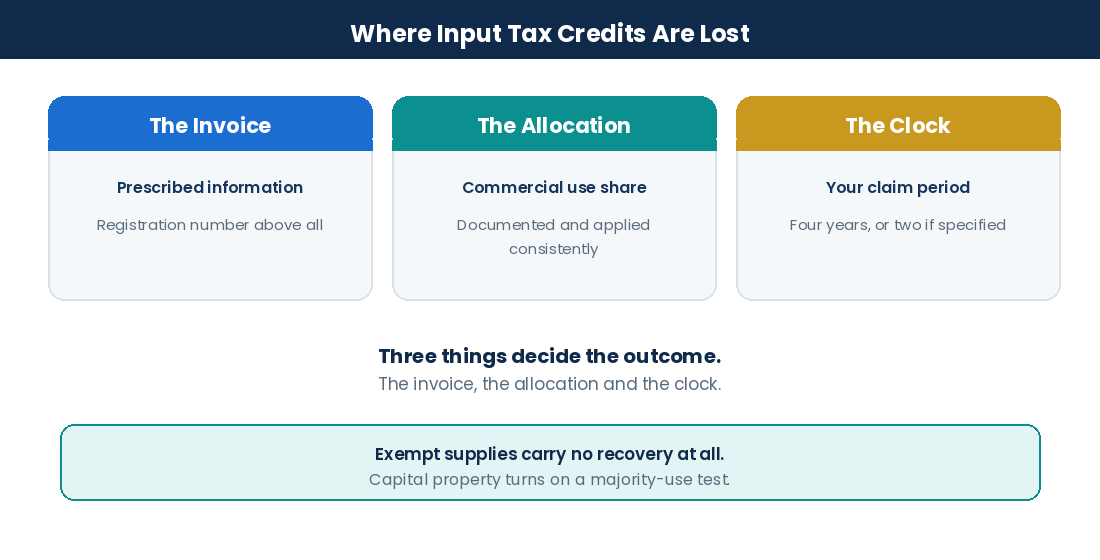
The framing that helps most: sort every claim by which of the three tests it might fail. Documentation denies more credits than eligibility does, and it does so on one line item most businesses never look at.
Reading time: 54 minutes.
Table of Contents
- The Three Tests
- Essential Information on Input Tax Credits Canada
- Eligibility, Claims and Bookkeeping
- Strategies and Recovering Missed Credits
- Industry-Specific ITC Considerations
- The Numbers and Working With Us
- Frequently Asked Questions
- Your ITC Claim Checklist
- Businesses We Serve
- Professional Guidance and Quick Reference
The Numbers That Matter
This article covers Canada, with Ontario and Toronto context, and reflects rules current to 2026. It is written for incorporated Canadian businesses registered for GST/HST. Figures marked illustrative are examples, not quotes, and any masked engagement notes end with “Figures changed for privacy.” This is educational information only and not tax or legal advice. Provincial rates and eligibility depend on your own facts, so please confirm before acting.
The Three Tests
The Three Tests
The Framing
What Actually Decides a Claim
Every input tax credit has to survive three separate tests. Most guidance on maximising credits covers eligibility at length and treats the other two as afterthoughts, which is backwards relative to how claims are actually lost.
| Test | The Question | Where It Fails |
|---|---|---|
| Documentation | Does the invoice carry what the rules require | Missing supplier registration number |
| Allocation | How much of the use is commercial | Mixed use claimed in full |
| Timing | Is the claim within your claim period | Period expired, and it does not reopen |
The first row is the one worth internalising. A purchase can be entirely legitimate, entirely for the business, and entirely within time, and the credit still goes if the invoice does not carry the supplier’s registration number. No amount of explanation substitutes for it.
Why the Registration Number Matters So Much
The documentary requirements scale with the amount of the purchase, and above a modest threshold the supplier’s GST/HST registration number becomes mandatory. Small receipts from counter purchases are where it is most often absent.
- Check for it at the counter, not two years later during a review
- Ask suppliers to reissue where an invoice is incomplete, since most will
- Verify the number itself where a supplier is new or the amount is significant
- A supplier who is not registered charged you nothing to recover
- Never accept a bank or card statement as a substitute for an invoice
The fourth point catches businesses out regularly. Where a supplier is not registered, no tax was properly charged, so there is nothing to claim regardless of what the invoice says.
The Test Nobody Runs
Before optimising anything, run one check on a sample of your purchase invoices for the last quarter: does each one carry the supplier’s name, registration number, date, a description, and the tax shown separately or a statement that it is included.
Businesses that run this find a failure rate that surprises them, and every failure is a credit already claimed that would not survive a review. That is a more useful starting point than a list of eligible expense categories.
The credit is almost never denied because the expense was wrong. It is denied because the invoice was incomplete, and usually on one line. Figures changed for privacy.
Risk Warning: An invoice missing the supplier’s registration number will not support a credit however genuine the purchase. Please check at the counter.
Essential Information on Input Tax Credits Canada
Essential Information on Input Tax Credits Canada
The Basics
Maximizing Your Input Tax Credits for GST/HST Tax Savings
Maximising your input tax credits helps lower the GST or HST you owe. Claiming ITCs properly can boost your business’s cash flow and financial position. Here is a quick snapshot:
- Who It Is For: Small to medium businesses registered for GST/HST in Canada
- Who It Is Not For: Businesses not registered for GST/HST, or making only exempt supplies
- Key Benefits: Recover more credits, reclaim missed ones within time, improve cash flow
Understanding Input Tax Credits Canada and the GST/HST System
What is GST/HST in Canada?
GST and HST are value-added taxes on most goods and services sold in Canada, administered by the Canada Revenue Agency. Businesses collect the tax from customers and remit it. They can recover GST or HST paid on business purchases as input tax credits.
Please note that tax collected is held in trust. It is not working capital, and directors can be assessed personally for amounts not remitted.
The Core Concept of Input Tax Credits (ITCs)
Input tax credits let businesses recover the GST or HST paid on purchases tied to their commercial activities. The effect is that only the final consumer bears the tax, while registrants offset what they paid against what they collected.
Why Input Tax Credits are Important for GST/HST Registrants
Getting ITCs right affects the net amount you remit each period. Careful tracking and complete documentation mean you claim everything you are entitled to and keep what you claim when it is examined.
The Importance of GST/HST Filing for Canadian Businesses
Obligations for GST/HST Registrants
Businesses registered for GST/HST must file returns on their assigned frequency, showing tax collected less credits claimed. Filing on time keeps your account in order.
Consequences of Non-Compliance with GST/HST Filing
Failing to file properly produces penalties, interest and closer examination. The failure-to-file penalty is formula-based on the amount owing, which is why a nil return filed late generally carries little penalty while a large balance carries a serious one.
Benefits of Timely and Accurate GST/HST Filing
Filing on time keeps cash flow steady because credits are recovered sooner. It also means the claim period is never the reason a credit is lost, which is the most avoidable way to lose one.
Eligibility, Claims, and Bookkeeping for ITC Optimization
Who Can Claim Input Tax Credits Canada?
Input tax credits let registered businesses recover GST or HST paid on eligible purchases. You need to know who can claim and what counts as commercial activity.
Defining a GST/HST Registrant and Commercial Activity
A GST/HST registrant is a business or person registered to collect and remit GST or HST. This covers sole proprietors, corporations, partnerships and other entities making taxable supplies.
Commercial activity means business operations involving supplies subject to GST/HST, including zero-rated supplies. Only expenses tied to those activities support credits. Personal purchases and expenses relating to exempt supplies do not.
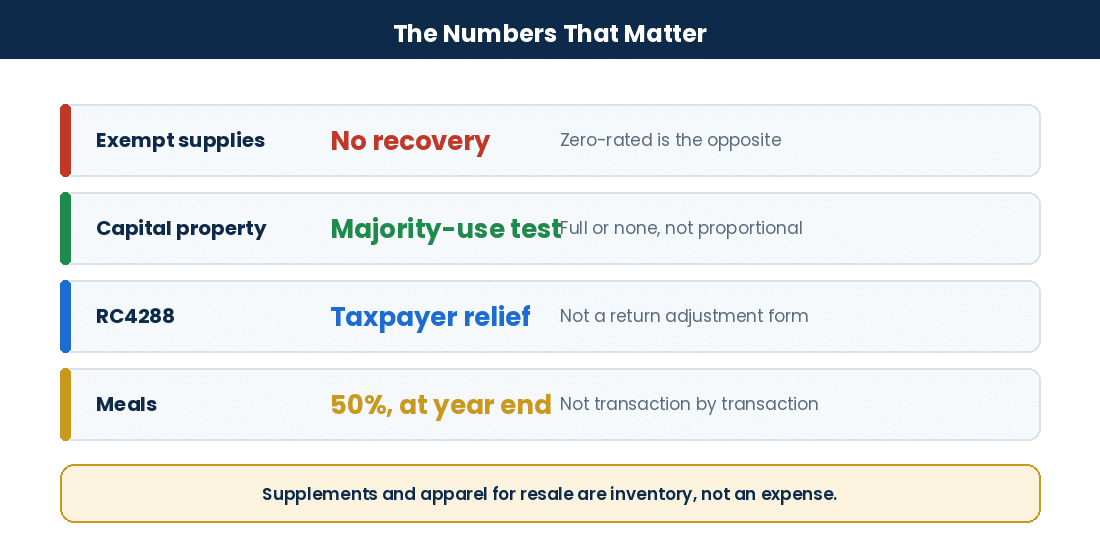
Please note the distinction between exempt and zero-rated, because it decides recovery. Zero-rated supplies are taxable at 0%, and credits on related costs are recoverable. Exempt supplies are outside the tax, and credits on related costs are not. Guidance treating the two as equivalent has the consequence backwards.
Criteria for Input Tax Credit Eligibility
You can claim an input tax credit if:
- You are a registered person under the Excise Tax Act.
- The purchase relates to your commercial activities.
- Tax was properly charged by a registered supplier.
- You hold documentation containing the prescribed information.
- You claim within your claim period.
Eligible expenses cover office supplies, utilities at business premises, professional fees, rent on business property and equipment acquired for business use. The last two criteria are the ones added here, and between them they account for most denied claims.
Special Considerations for New Registrants and ITCs
New registrants can generally claim credits on tax paid on inventory and certain property held at the time of registration, subject to the rules. Costs incurred before that point are more limited, and the position depends on what was acquired and when.
Register earlier rather than later where you expect to exceed the small supplier threshold, because credits before registration are constrained in a way credits after it are not. Our guide to GST/HST registration covers the mechanics.
Zero-rated and exempt sound similar and behave in opposite ways. Getting them the wrong way round costs recovery on every cost in the business. Figures changed for privacy.
Key Stat: Zero-rated supplies allow full credit recovery. Exempt supplies do not. Please confirm which yours are before claiming.
Eligible Business Expenses for ITC Claims Canada
Eligibility, Claims and Bookkeeping
The Detail
Knowing which expenses count avoids both under-claiming and adjustments on review.
Common Operating Expenses Qualifying for ITCs
Most regular costs tied to running the business qualify where properly documented:
- Office supplies
- Utilities at business locations
- Professional fees, legal and accounting
- Advertising linked to taxable supplies
- Rent on leased business premises
- Software and subscription services
Capital Property and ITC Claims: Rules and Limitations
Capital property is acquired for lasting use rather than resale. The rules differ from operating expenses and are frequently misstated.
- For capital personal property, a registrant that is not a financial institution generally claims a full credit where commercial use exceeds 50%, and none where it does not. It is not a proportional claim.
- Capital real property follows different rules, with allocation based on the extent of commercial use.
- Passenger vehicles are capped. The credit is limited by reference to the capital cost limit, so tax on the amount above the limit is not recoverable.
- Where the extent of use changes materially after acquisition, change-in-use rules may require an adjustment.
A correction on terminology that circulates widely. Recaptured input tax credits are not the change-in-use rules. That term refers to a specific provincial regime that applied to large businesses on certain specified property and services, and the Ontario recapture rate was reduced to zero from 1 July 2018. Describing RITCs as what happens when a business asset moves to personal use is wrong on both counts.
Specific Scenarios: Meals, Entertainment, and Vehicle Expenses
| Expense Type | Treatment | Notes |
|---|---|---|
| Meals & Entertainment | Credits limited to 50% | Adjusted in the last reporting period of the fiscal year |
| Passenger vehicles | Capped by the capital cost limit | Tax above the limit is not recoverable |
| Vehicle operating costs | Based on extent of commercial use | Keep distance records |
| Home premises | Restricted, and different for a corporation | A corporation does not prorate as a proprietor does |
The first row includes a mechanism most guidance omits. The 50% restriction on meals and entertainment is generally applied as an adjustment in the final reporting period of the fiscal year rather than transaction by transaction, which changes how the bookkeeping should be set up.
Purchases and Expenses Not Eligible for Input Tax Credits
- Personal living costs
- Club memberships whose main purpose is recreation or dining
- Costs relating to exempt supplies
- Purchases from suppliers who are not registered
- Fines and penalties, which carry no tax to recover
The last item is worth stating precisely. A fine is not disallowed as a credit; there is simply no GST/HST on it, so nothing exists to claim.
What Is Diligent Bookkeeping for Maximizing Input Tax Credits?
Accurate records are what turn an entitlement into a credit you keep.
The Role of Accurate Business Expense Tracking Canada
Regular tracking separates taxable, exempt and personal expenditure clearly. Where a business makes both taxable and exempt supplies, an allocation method has to be chosen, applied consistently and documented, because an allocation you cannot explain is an allocation that will be challenged.
Organizing Your Financial Records for ITC Claims Canada
Well-organised records make filing and any subsequent review far simpler. Keep invoices sorted by period and supplier, with bank statements reconciled, so everything is available whether for routine tax preparation or a CRA examination.
Efficient systems also help with mixed-use assets, where partial allocations must follow a reasonable method consistently. Electronic records are acceptable provided they stay readable and retrievable for the retention period, and a system migration that leaves years of attachments unopenable is a retention failure even though the data technically exists.
Gondaliya CPA supports small and medium businesses across Ontario with transparent flat-fee pricing quoted before work begins, including HST.
Key Documentation Required for CRA Compliant GST Claims
Documentary requirements scale with the amount of the purchase. Broadly, each claimed transaction needs:
- The supplier’s name or trading name
- The supplier’s GST/HST registration number, above the relevant threshold
- The date of the invoice
- A description sufficient to identify what was supplied
- The amount, with tax shown separately or stated as included
- The recipient’s name, above the higher threshold
Digital copies are acceptable provided the retention rules are met. Please note that the registration number is the item most often missing and the one that most often defeats an otherwise valid claim.
Common ITC Mistakes and How To Avoid Them
The most common mistake is claiming without documentation containing the prescribed information. Missing invoices, incomplete receipts and records without registration numbers all produce denied claims on review. Keep organised records and check invoices carry what is required.
The second is claiming mixed-use expenditure incorrectly. Vehicles, premises and phones used for both purposes must be allocated on a reasonable and documented basis. Overclaiming produces adjustments and, where the pattern suggests carelessness, penalties.
The third is claiming in the wrong reporting period, or claiming on costs relating to exempt supplies. Reviewing your position periodically, and taking advice where supplies are mixed, prevents both.
Consistent bookkeeping and regular reconciliation reduce all three. A proactive approach also shortens the work at filing time considerably.
Businesses ask which expenses qualify. The more useful question is which of their invoices would survive being read closely, and that is a different list. Figures changed for privacy.
Risk Warning: Recaptured input tax credits are a provincial large-business regime, not what happens when an asset moves to personal use. Please do not confuse the two.
GST/HST Tax Savings: Strategies to Maximize Your ITC Refunds Canada
Strategies and Recovering Missed Credits
The Recovery
Maximising input tax credits reduces what you remit and improves cash flow. It means claiming eligible costs correctly, planning ahead, and recovering what was missed while the GST/HST tax savings are still available.
Proactive Tax Planning for GST Filing
Tax planning pays off at filing time. Businesses can identify recoverable costs early and time significant purchases sensibly.
- Keep clear records of all business purchases carrying GST/HST.
- Consider timing significant acquisitions relative to your reporting period.
- Separate personal expenditure from business costs carefully.
- Choose and document an allocation method where supplies are mixed.
- Review reporting frequency, since it affects how quickly credits are recovered.
The last point is often overlooked. Filing more frequently recovers credits sooner, which matters for a business in a persistent refund position, though it also means more filing work.
Reviewing Supplier Invoices for Correct GST/HST Charges
Supplier invoices must be correct to support a claim. Check for:
- The correct provincial rate for the place of supply
- A valid supplier registration number
- Tax shown separately, or stated as included
- A description sufficient to identify what was supplied
Where a supplier has charged the wrong rate, the recoverable amount is the tax properly payable rather than the amount shown. Overcharged tax is recovered from the supplier, not from the CRA through a credit.
Identifying and Recovering Missed GST Credits
Credits get missed through ordinary bookkeeping gaps rather than anything unusual. Recovery is available within the claim period.
- Compare purchase records against credits actually claimed.
- Look for unclaimed costs such as rent, utilities, professional fees and vehicle operating costs.
- Check invoices filed but never entered, which is the largest single category.
- Claim within your claim period, in a current return where the rules allow.
Recovering missed credits produces cash without any new sales, which is why it is worth a periodic review.
Exploring the Simplified Method for Input Tax Credits
The Simplified Method lets eligible smaller registrants calculate credits from total taxable purchases using a factor, rather than extracting the tax from each transaction.
The eligibility conditions are based on size, not on the proportion of commercial activity. Broadly, annual taxable supplies and annual taxable purchases must each be under set thresholds, tested annually. Guidance stating that the method suits businesses where under 90% of purchases relate to commercial activity has confused it with a different rule entirely.
- It reduces bookkeeping effort at filing time
- It does not reduce the documentation you must retain
- You still need invoices meeting the prescribed requirements
- Eligibility is tested each year, so it can be lost as you grow
When to Review Past GST/HST Filings for ITC Claims
Reviewing earlier filings periodically prevents losing credits that were simply never entered, particularly where a period was prepared under time pressure or by someone no longer with the business.
Identifying Opportunities for GST/HST Tax Recovery Services
| Benefit | Description |
|---|---|
| Full Claim Analysis | Identifies unclaimed credits by category and period |
| Compliance Check | Tests each claim against the documentary requirements |
| Recovery Within Time | Prioritises periods approaching the end of the claim period |
| Both Directions | Identifies over-claims as well as omissions |
The last row matters for credibility. A review that reports only good news is not a review, and filing a correction that reflects one side of the position is not defensible.
How to Adjust a Previously Filed GST/HST Return for ITCs
Where a credit was missed, the usual route is to claim it in a later return within your claim period rather than to amend the original. Where the return itself needs correcting, an amended return can be filed through your CRA business account or by written request to your tax centre.
A correction on forms, because the wrong one circulates widely. Form RC4288 is the Request for Taxpayer Relief, used to ask for cancellation of penalties and interest. It is not a GST/HST return adjustment form and filing it to correct a credit will not achieve that.
Equally, references to GSTR forms belong to India’s tax system and have nothing to do with Canadian GST/HST. Canadian returns are filed on the GST34 series or electronically.
- Assemble the invoices supporting the claim.
- Calculate the correct amount, and check the period it belongs in.
- Claim in a current return where the rules permit, or request an adjustment.
- Retain the working papers explaining what changed and why.
Understanding Time Limits for Adjustments and Recovering Missed GST Credits
The general claim period is four years after the due date of the return for the period in which the credit could first have been claimed.
Please note the exception, because it catches larger businesses. Specified persons, broadly registrants with annual taxable supplies above a set threshold in each of the two preceding fiscal years, and financial institutions, have a shorter period of generally two years. A business that grew across that threshold may have a shorter window than it assumes.
References to a date such as April 30 belong to personal income tax and have no application to GST/HST claim periods.
The claim period is the one thing in this subject that is genuinely final. Everything else can be corrected; an expired period cannot. Figures changed for privacy.
Key Stat: Form RC4288 is the Request for Taxpayer Relief, not a GST/HST adjustment form. Please do not use it to correct a credit.
Industry-Specific ITC Considerations
Industry-Specific ITC Considerations
By Sector
Doctors and Dentists: Unique ITC Rules
Medical professionals operate with a mix of supplies, and the mix decides recovery. Most healthcare services are exempt, which means tax paid on related costs is not recoverable at all.
Where a practice also makes taxable supplies, such as certain cosmetic procedures or the sale of products, credits must be apportioned on a reasonable and documented basis. Practices claiming in full across mixed supplies are the ones that get adjusted, and the adjustment covers every period examined.
Daycare Businesses: Exemptions and ITC Claims
Childcare services are exempt supplies, not zero-rated. Tax paid on premises, supplies and equipment used for exempt childcare is not recoverable, and no allocation method changes that.
Where a daycare also makes taxable supplies, only the portion relating to those supports credits. Guidance describing childcare as zero-rated has the consequence exactly backwards and leads operators to claim credits they will lose.
Real Estate Professionals: ITCs on Commissions and Operating Costs
Credits cover costs relating to taxable activity, including commissions paid on taxable transactions and marketing costs, where documentation meets the requirements.
Please note that residential resale property is generally exempt while new housing and commercial property are generally taxable. Costs relating to exempt transactions do not support credits, so the allocation for an agent working across both matters.
Property Developers & Builders: Complex ITC Rules and New Housing Rebates
Developers claim credits on construction inputs for taxable development, alongside the new housing rebate regime which operates separately and on its own conditions.
The self-supply rules deserve particular attention. Where a builder constructs residential property and then leases it rather than selling, a deemed supply can arise, changing the position materially. This is one of the areas where taking advice before the transaction rather than after is worth considerably more than the fee.
Construction Companies and Skilled Trades: Materials, Subcontractors, and Capital Assets
Accounting services here focus on separating consumed materials from capital assets, since the rules differ and the timing does too.
- Materials consumed on jobs are ordinary operating inputs
- Equipment is capital property, with the majority-use test applying
- Subcontractor invoices need registration numbers like any other
- Holdbacks affect when the credit becomes claimable
The last point is specific to the sector and often missed in both directions.
Startups: Initial Expenses and Early ITC Recovery
Startups should track early expenditure carefully. New registrants can generally claim credits on tax paid on inventory and certain property held at the time of registration, subject to the rules, but the position on costs incurred earlier is more constrained.
Where you expect to exceed the small supplier threshold, registering earlier rather than later preserves recovery that would otherwise be limited. Costs paid on a founder’s personal card and never entered are the largest single source of missed credits on these files.
Restaurants: Food Costs, Equipment, and Dining Expenses
Basic groceries are zero-rated, and restaurant meals are taxable, so a restaurant sits on both sides of the line at once. Credits on ingredient purchases follow the ordinary rules; the sector-specific issue is that prepared food purchased for staff or hospitality attracts the meals and entertainment restriction.
Equipment bought in a busy month and coded to supplies is the other recurring finding, and it costs both the credit treatment and the depreciation claim.
Transportation & Logistics Companies: Fuel, Vehicle Maintenance, and Cross-Provincial Operations
Detailed records matter here because place of supply determines the rate and the rate varies by province. Fuel purchased in different provinces carries different amounts, and reconciling fuel purchased against distance travelled is the check that finds unentered purchases.
Note also that certain freight transportation services are zero-rated, particularly international movements. Where a carrier makes zero-rated supplies, credits on related costs remain fully recoverable, which is the opposite of the exempt position.
Exempt against zero-rated decides more recovery in these sectors than every optimisation technique combined. It is worth being certain which side you are on. Figures changed for privacy.
Pro Tip: Please establish whether your supplies are taxable, zero-rated or exempt before anything else. That answer governs every claim you make.
Numeric Example: Calculating Your Input Tax Credits
The Numbers and Working With Us
The Worked Example
Two illustrations showing how documentation and allocation change the recoverable amount. All figures are illustrative only and assume an Ontario business at 13% unless stated.
| Scenario | Purchases Before Tax | Rate | Eligible Portion | Credit |
|---|---|---|---|---|
| Scenario 1 – Office Supplies Only | $50,000 | 13% | 100% | $6,500 |
| Scenario 2 – Mixed Use Assets | $120,000 | 13% | Allocated | See breakdown |
Detailed Breakdown – Scenario 2
| Item | Purchase Amount | Eligible | Rate | Credit |
|---|---|---|---|---|
| Construction Materials | $70,000 | 100% | 13% | $9,100 |
| Company Vehicles | $30,000 | 60% | 13% | $2,340 |
| Office Equipment | $20,000 | 100% | 13% | $2,600 |
| Total | $120,000 | $14,040 |
Three points about this example, because published versions of it usually contain errors.
First, the rate must match the place of supply. An Ontario business does not apply 5% to one line and 13% to another in the same purchase list; a 5% figure would indicate a supply made in a GST-only province, which needs stating rather than appearing unexplained.
Second, the vehicle line is simplified. Where the vehicle is a passenger vehicle, the credit is capped by reference to the capital cost limit, so the recoverable amount on a vehicle above that limit is less than the calculation shows. Where it is capital personal property used more than 50% commercially, the claim is generally full rather than proportional. Which rule applies depends on the vehicle and the use.
Third, none of it survives without documentation. A $9,100 credit on materials is worth nothing if the supplier invoices do not carry a registration number.
For help with your next filing cycle, call Gondaliya CPA at 647-212-9559 or email info@gondaliyacpa.ca.
DIY vs. CPA vs. Non-CPA for GST/HST Filing and ITC Claims
| Aspect | DIY Approach | Non-CPA Service Provider | CPA Services |
|---|---|---|---|
| Expertise | Limited, higher error risk | Moderate, less specialised | Extensive |
| Compliance | Risk of non-compliance | Variable | Professional standards apply |
| Maximizing Refunds | Often misses eligible credits | May overlook allocation rules | Comprehensive identification |
| Tax Planning | Minimal | Basic | Proactive |
| Time Investment | High | Moderate | Low |
| Audit Support | You handle it | Available if authorised | Available if authorised |
| Cost | Lowest upfront | Moderate fees | Fixed fee quoted before work |
One correction to the version of this table that circulates. In Canada there is no professional monopoly on CRA representation, so anyone you authorise may act for you. The difference is technical depth and regulatory accountability, not legal authority.
The Gondaliya CPA Process for GST/HST Return Optimization
Initial Consultation and Needs Assessment
We establish the shape of the business first: transaction volume, sector, supply mix across taxable, zero-rated and exempt, reporting frequency, past filings and the state of the bookkeeping.
Comprehensive Bookkeeping for ITC Claims
Clean books mean accurate claims. We check every transaction carrying input tax so nothing is missed, and we identify costs paid personally that were never entered.
Meticulous Review of Eligible Business Expenses GST/HST
We review expenditure against the documentary requirements and the allocation rules, including the sector-specific positions, and we flag invoices that would not survive a review before they become a problem.
Preparing and Filing Your GST/HST Return with ITC Claims
We prepare the return with credits supported and allocations documented, and we apply the meal and entertainment adjustment in the correct period rather than transaction by transaction.
Ongoing Support and GST/HST Accounting Services
Rules and rates change. Ongoing work keeps filings current and catches claim periods approaching expiry before they close.
Deliverables: What to Expect from Gondaliya CPA for Your ITC Claims
| Deliverable | Description |
|---|---|
| Bookkeeping Cleanup Report | A detailed report showing corrections made during cleanup |
| Audit Support Documentation | Files organised to the documentary requirements supporting each credit |
| Compliance Verification | Confirmation that claimed items meet the eligibility and documentation tests |
| Tax Planning Consultation | A session on improving recovery in future periods |
| Ongoing Accounting Services | Regular filings reflecting current rules and rates |
| Claim Period Schedule | Which periods remain open, and which are closing |
Pricing Factors for GST/HST Accounting Services
| Factor | Description |
|---|---|
| Volume of Transactions | More transactions need more work, so costs rise |
| Complexity of Business Expenses | Mixed supplies and allocation requirements add review |
| Number of Reporting Periods | Monthly filing involves more work than quarterly |
| Catch-Up Filings Add Fees | Periods in arrears are additional work |
| Industry-Specific Compliance Requirements | Sectors such as construction and healthcare involve particular rules |
Fees are quoted before work begins, including HST, with a one-business-day response, evening and weekend availability, a 30-day money-back arrangement and a 60-day fee-matching arrangement.
Risks & CRA Compliance: Ensuring Accuracy in Your GST Claims
| Risk Area | What Happens |
|---|---|
| Missing ITC claim deadlines | The credit is lost permanently once the claim period closes |
| Incorrect ITC calculations | Adjustments with interest, and penalties where carelessness is found |
| Insufficient documentation | Claims denied on review regardless of the underlying purchase |
| Claiming ineligible expenses | Adjustments, and it affects how the rest of the file is viewed |
| Claiming on exempt supplies | Denied, since exempt costs carry no recovery |
| Failing to adjust for change in use | An adjustment arises that should have been made |
Gondaliya CPA manages these by tracking claim periods, verifying documentation against the requirements, applying allocations consistently, and keeping working papers that explain each position.
How to Choose a CPA Firm for Your GST/HST Needs
Picking the right firm matters if you want full recovery with claims that hold up. Look for a firm that identifies eligible expenditure across your supply mix, keeps records to the documentary requirements, advises on reporting frequency and timing, and quotes fees before work begins. Our guide to late GST/HST filing in Canada covers where things go wrong.
Read what clients say about accuracy and responsiveness rather than star counts alone, and verify any firm on the CPA Ontario public directory before engaging them.
Why Trust Gondaliya CPA for Your GST/HST Filing and ITC Claims
Gondaliya CPA is a Chartered Professional Accountant firm focused on helping incorporated small businesses recover input tax credits fully while keeping claims defensible.
Sharad Gondaliya, CPA (Canada & USA), leads the team with 15+ years across healthcare, real estate, trades, startups, restaurants and transport. Compliance comes first, because a credit claimed and later denied costs more than one never claimed. We tell clients plainly where a claim will not hold.
| Guarantee Type | Description |
|---|---|
| 30-Day Refund Policy | A full refund if you are not satisfied within one month |
| 60-Day Fee Match | We match a lower competing fee on request |
Results depend on your own facts and current CRA rules. Contact Gondaliya CPA at info@gondaliyacpa.ca, call 647-212-9559, or send us a message.
A credit claimed and later denied costs more than one never claimed, because it comes back with interest and it colours the rest of the file. Figures changed for privacy.
Risk Warning: Please match the rate to the place of supply. A single purchase list mixing 5% and 13% without explanation is an error, not a strategy.
FAQs on Input Tax Credits and GST/HST Filing
Frequently Asked Questions
FAQ
What is the difference between DIY, CPA, and Non-CPA GST/HST filing services?+
DIY filing risks errors and missed credits. Non-CPA services offer basic support with less specialised knowledge. CPAs bring technical depth and regulatory accountability. All three can act as your representative if authorised.
How does corporate bookkeeping cleanup help maximize Input Tax Credits?+
Cleanup finds purchases never entered, particularly costs paid on personal cards, and tests existing claims against the documentary requirements before a reviewer does.
What is catch-up filing and when is it necessary?+
Submitting past-due GST/HST returns. It stops penalties accruing and lets you recover credits still within their claim period, which is the part most at risk from delay.
What deliverables should I expect from a CPA when handling my GST/HST filings?+
A cleanup report, audit support documentation organised to the requirements, compliance verification, a planning consultation, ongoing filings and a schedule of which claim periods remain open.
What pricing factors influence GST/HST filing services by a CPA firm?+
Transaction volume, complexity of the supply mix, reporting frequency, whether periods are in arrears, and sector-specific requirements. Fees are quoted before work begins, including HST.
What are common mistakes to avoid when claiming Input Tax Credits?+
Incomplete documentation, claiming mixed-use costs in full, claiming on exempt supplies, claiming in the wrong period, and letting a claim period expire on credits never entered.
How can I prepare for a CRA audit regarding GST/HST claims?+
Keep invoices carrying the prescribed information, document your allocation method and apply it consistently, and retain records for six years in a readable form.
Why is ongoing support important after GST/HST filing?+
Rates and rules change, reporting frequency can shift as you grow, and claim periods run continuously. Ongoing work catches periods approaching expiry before they close.
What role does tax planning consultation play in maximizing ITC claims?+
It addresses timing of significant purchases, reporting frequency, allocation method and registration decisions, all of which affect recovery more than transaction-level optimisation does.
How long do I have to claim a missed input tax credit?+
Generally four years after the due date of the return for the period in which it could first have been claimed. Specified persons, broadly larger registrants and financial institutions, have generally two years.
What form do I use to adjust a GST/HST return?+
Not RC4288, which is the Request for Taxpayer Relief. A missed credit is usually claimed in a later return within the claim period, or an amended return is filed through your CRA business account.
Are GSTR forms used in Canada?+
No. Those belong to India’s tax system. Canadian GST/HST returns are filed on the GST34 series or electronically.
What is the difference between exempt and zero-rated supplies?+
Zero-rated supplies are taxable at 0%, and credits on related costs are recoverable. Exempt supplies are outside the tax, and credits on related costs are not. The distinction decides all recovery.
Are recaptured input tax credits about assets moving to personal use?+
No. That term refers to a provincial regime requiring large businesses to recapture the provincial portion on certain specified property and services. The Ontario recapture rate reached zero from 1 July 2018.
Can I claim a full credit on capital equipment used partly for business?+
For capital personal property, a registrant that is not a financial institution generally claims a full credit where commercial use exceeds 50%, and none where it does not. It is not proportional.
What if my supplier is not registered for GST/HST?+
No tax was properly charged, so there is nothing to recover. Check the registration number before assuming a credit exists on the purchase.
Sixteen questions and one underneath most of them: which of the three tests would this claim fail. Figures changed for privacy.
Your ITC Claim Checklist for GST/HST Tax Savings
Your ITC Claim Checklist
Quick Reference
Getting the most from your Input Tax Credits during GST/HST filing lowers what you remit and improves cash flow. Work through this every reporting cycle.
The Six Checks Before You File
- GST/HST Registration Status: Confirm you are registered before claiming, and match registration dates to when expenses were incurred.
- Commercial Activity Confirmation: Test each expense against taxable or zero-rated supplies, and exclude costs relating only to exempt supplies.
- Eligible Expense Verification: Confirm tax was properly charged by a registered supplier and the cost relates to commercial activity.
- Complete Documentation: Save invoices carrying supplier name, registration number, date, description and tax shown or stated as included.
- Accurate Calculation: Use the rate for the place of supply, apply your documented allocation method, and check totals against the invoices.
- Timely Filing: Submit on your assigned frequency, since late filing costs interest and delays recovery.
Ongoing Practice
- Regular Bookkeeping for ITC Claims: Enter transactions promptly and reconcile supplier statements against what is recorded.
- Review For Missed Credits: Check purchase records against credits claimed, focusing on invoices filed but never entered.
- Seek Professional Advice: Take advice where supplies are mixed, where capital property is involved, or where a claim period is closing.
- CRA Account Monitoring: Watch for notices, answer queries about claimed inputs promptly, and adjust future filings accordingly.
Essential Bullet Points: Optimizing Your GST/HST Filing with Gondaliya CPA
- Check every invoice carries the supplier’s registration number.
- Ask suppliers to reissue incomplete invoices rather than claiming anyway.
- Confirm whether your supplies are taxable, zero-rated or exempt.
- Document your allocation method and apply it consistently.
- Apply the majority-use test correctly to capital personal property.
- Check the passenger vehicle cap before claiming on a vehicle.
- Apply the meals and entertainment restriction in the correct period.
- Track which claim periods are approaching expiry.
- Check whether you are a specified person with a shorter period.
- Never treat a bank statement as a substitute for an invoice.
- Keep records six years, readable throughout.
- Reconcile fuel or stock purchases against operational data.
Next Steps: Optimize Your GST/HST Filing and Recover Missed Credits. Contact Gondaliya CPA at info@gondaliyacpa.ca, call 647-212-9559, or book a free consultation.
Twenty-two points, and the first one in the third group decides more claims than the other twenty-one combined. Figures changed for privacy.
Businesses We Serve
Industry Expertise
What limits recovery differs by business. Here are ten and the usual constraint.
| Business | What Usually Limits Recovery |
|---|---|
| Medical and dental practices | Exempt supplies, so most costs carry no recovery |
| Daycare operators | Exempt supplies, not zero-rated |
| Real estate agents | Residential resale is exempt, new and commercial are not |
| Property developers | Self-supply rules and the rebate regime |
| Construction and trades | Holdbacks affecting when a credit becomes claimable |
| Startups | Costs before registration, and founder card purchases |
| Restaurants | Zero-rated inputs against taxable sales, plus the 50% restriction |
| Transport operators | Place of supply changing the rate across provinces |
| Larger registrants | A two-year claim period rather than four |
| Anyone with counter purchases | Invoices missing the supplier registration number |
- Medical and dental practices: Apportion on a real basis.
- Daycare operators: Exempt is not zero-rated.
- Real estate agents: The transaction type decides it.
- Property developers: Advice before, not after.
- Construction and trades: Watch the timing on holdbacks.
- Startups: Register earlier than you think.
- Restaurants: Both sides of the line at once.
- Transport operators: Rate follows the province.
- Larger registrants: Check which period applies to you.
- Anyone with counter purchases: Check at the till.
The business changes the constraint. It does not change the three tests, which are the invoice, the allocation and the clock. Figures changed for privacy.
Professional Guidance and Quick Reference
Guidance
Professional Guidance: How Gondaliya CPA Handles Your ITC Claims
Businesses lose input tax credits in a predictable set of ways: claiming on invoices that do not carry the supplier registration number, treating exempt supplies as though they were zero-rated and claiming recovery that does not exist, applying a proportional claim to capital personal property where the majority-use test governs, ignoring the passenger vehicle cap, applying the meals restriction transaction by transaction instead of as a year-end adjustment, assuming a four-year claim period when a growing business may be a specified person with two, and letting periods expire on invoices filed but never entered. Gondaliya CPA handles GST/HST filing and credit claims on a fee quoted before work begins.
We handle what decides recovery: establishing your supply mix across taxable, zero-rated and exempt, testing documentation against the prescribed requirements, choosing and documenting an allocation method, applying the capital property and vehicle rules correctly, adjusting meals and entertainment in the right period, tracking which claim periods remain open, and recovering credits still within time.
Our team starts with your last filed GST/HST return, a sample of purchase invoices and a description of what you supply. Those three tell us where recovery is being lost. Whatever your sector, you get clear advice and a fixed price before we start.
Quick Answers
- Three tests: Invoice, allocation, clock
- Most denials: Documentation, not eligibility
- The missing item: Supplier registration number
- Zero-rated: Full recovery on related costs
- Exempt: No recovery on related costs
- Claim period: Generally four years
- Specified persons: Generally two years
- Capital personal property: Majority-use test, not proportional
- Meals: 50%, adjusted at year end
- RC4288: Taxpayer relief, not a return adjustment
Who This Is For
- For: Incorporated Canadian businesses registered for GST/HST that want full, defensible recovery on their input tax credits.
- Not For: Businesses making only exempt supplies, where credits on related costs are not recoverable regardless of documentation.
People Also Ask
Who qualifies for the Simplified Method?+
Eligibility is based on size, with annual taxable supplies and taxable purchases each under set thresholds tested annually. It is not based on the proportion of commercial activity.
How are meals and entertainment credits restricted?+
Credits are limited to 50%, and the restriction is generally applied as an adjustment in the last reporting period of the fiscal year rather than transaction by transaction.
Does a corporation claim home premises costs the way a proprietor does?+
No. A corporation does not prorate by space used. It pays a reasonable amount under a proper arrangement or reimburses supported costs, with the tax position following that.
Glossary of Key Terms
- Input tax credit: Recovery of GST/HST paid on business inputs.
- Registrant: A business registered to collect and remit GST/HST.
- Commercial activity: Making taxable or zero-rated supplies.
- Taxable supply: A supply on which GST/HST is charged.
- Zero-rated supply: Taxable at 0%, with full recovery on related costs.
- Exempt supply: Outside the tax, with no recovery on related costs.
- Prescribed information: What an invoice must contain to support a credit.
- Registration number: The supplier identifier required above the threshold.
- Place of supply: What determines which provincial rate applies.
- Claim period: How long a credit remains claimable.
- Specified person: A larger registrant with a shorter claim period.
- Capital personal property: Lasting assets, subject to the majority-use test.
- Passenger vehicle cap: The limit restricting recovery on a vehicle.
- Change in use: Rules requiring adjustment when use shifts materially.
- Simplified Method: A factor-based calculation for eligible smaller registrants.
- Self-supply: A deemed supply arising in certain residential construction cases.
ITC Readiness Check
This quick self-check indicates where your operation most likely has room. Please answer the six questions below.
ITC Readiness Check
Six quick questions on your claims. No fee shown.
Points to raise with us:
This is a general prompt, not tax or legal advice or a quote. Your position depends on your full facts. For a real review, please book a free consultation.
Want a checklist to work from? You can download our free ITC claim checklist before your consultation.
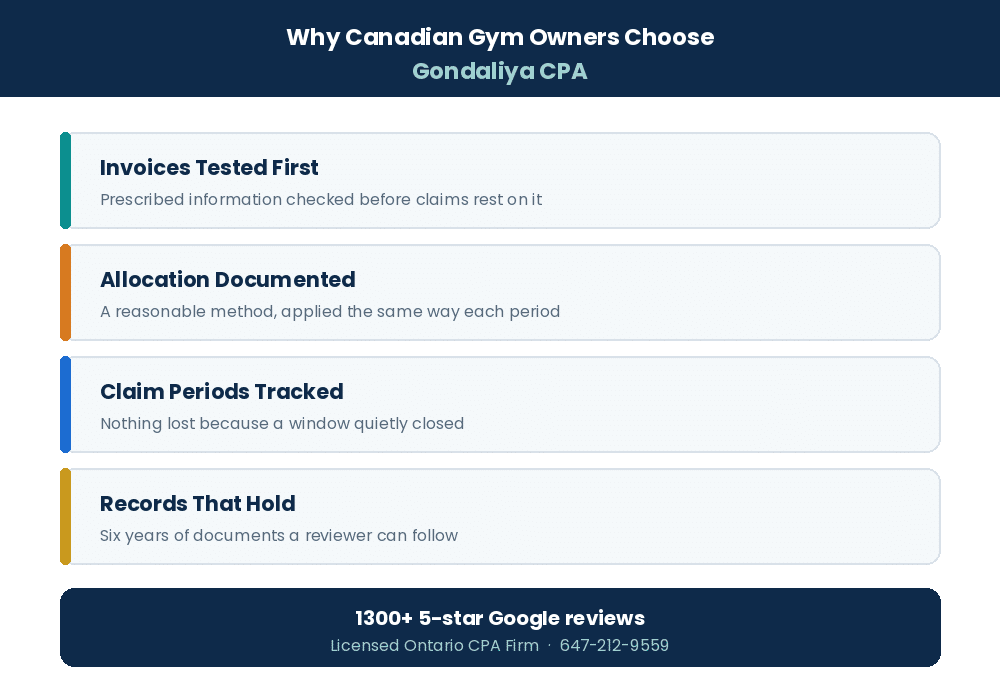
Check every invoice carries the supplier registration number. Establish whether your supplies are taxable, zero-rated or exempt. Document an allocation method and apply it consistently. Apply the majority-use test to capital personal property. Watch the passenger vehicle cap. Adjust meals at year end, not per transaction. Track which claim periods are closing. Please keep six years of records.
2026 Update — what is current: This article reflects rules current to 2026. The general four-year input tax credit claim period, the shorter period of generally two years for specified persons and financial institutions, the 50% restriction on meals and entertainment credits, the six-year record retention requirement and the documentary requirements scaling with purchase amount are unchanged. Please note that Form RC4288 is the Request for Taxpayer Relief and is not a GST/HST return adjustment form, so guidance directing you to it for a missed credit is wrong; that references to GSTR forms belong to India\u2019s tax system and have no application in Canada, where returns are filed on the GST34 series or electronically; that recaptured input tax credits are a provincial regime applying to large businesses on specified property and services rather than what happens when an asset moves to personal use, with the Ontario recapture rate reduced to zero from 1 July 2018; that eligibility for the Simplified Method is based on size thresholds tested annually rather than on the proportion of commercial activity; that for capital personal property a registrant that is not a financial institution generally claims a full credit where commercial use exceeds 50% and none where it does not, rather than a proportional amount; that credits on passenger vehicles are capped by reference to the capital cost limit; that zero-rated supplies allow full recovery while exempt supplies allow none, so childcare and most healthcare services carry no recovery on related costs; and that the meals and entertainment restriction is generally applied as an adjustment in the last reporting period of the fiscal year.
Input Tax Credits Canada: How Gondaliya CPA Supports GST/HST Registrants
Start with the invoices
Gondaliya CPA establishes your supply mix across taxable, zero-rated and exempt, tests documentation against the prescribed requirements, chooses and documents an allocation method, applies the capital property and passenger vehicle rules correctly, adjusts meals and entertainment in the right period, tracks which claim periods remain open and recovers credits still within time, on a fee quoted before work begins including HST with a one-business-day response. Please book a free consultation.
Next Steps
Please book a free consultation with Gondaliya CPA and bring your last filed GST/HST return, a sample of purchase invoices, and a description of what you supply. Those three tell us where recovery is being lost, which periods are closing, and what remains to claim on the equipment, and where the documentation is thin. You will get a flat annual fee including HST before any work begins. If our content helps, please add gondaliyacpa.ca as a preferred source on Google.
Published: · Last updated:
Editorial policy: We research against CRA and CPA Ontario sources, fact-check the figures, and Sharad Gondaliya, CPA, reviews the content, which we update as the rules change.
Disclaimer: This article is educational information only and is not tax, legal, or financial advice. Figures marked illustrative are examples rather than quotes or guarantees. It reflects CRA rules current to 2026, including the $30,000 GST/HST threshold, the Class 8 rate, Class 13 leasehold treatment, the half-year rule, and the six-year retention requirement. Rates, limits and expensing rules change and outcomes depend on your specific facts. Please consult a licensed CPA before acting.
Sharad Gondaliya is a CPA Canada & CPA USA with 15 Years+ experience of Accounting, Tax, Payroll of Corporate Small Businesses as Tax Accountant. He is fully certified CPA Ontario and CPA USA and is well known among corporate small businesses for tax planning, efficient tax solutions, and affordable CPA services. Sharad is the Principal (Director) of Gondaliya CPA – Affordable CPA Firm in Canada. Licenses: CPA Ontario: 61040184 | CPA USA (MT): PAC-CPAP-LIC-033176 | CPA USA (WA): 57629 | CPA Firm License: 61330051 View Full Author Bio