



Accountant for Personal Support Worker Businesses in Ontario and Across Canada
Home care is a payroll- and compliance-heavy people business, and most of your revenue is HST-exempt. We keep you from charging HST on personal-care and homemaker work billed through Ontario Health atHome, split any taxable private-pay lines so your input tax credits are apportioned correctly, handle the placement-agency CPP and EI withholding rule that catches agencies who pay workers as “contractors,” classify your PSWs correctly under CRA guide RC4110, register and reconcile your mandatory WSIB coverage, run T4 and T4A payroll with PD7A remittances, ROEs and ESA vacation pay, and claim the per-kilometre allowance for PSWs driving between client homes. When your agency scales, we plan the incorporation, the section 85 rollover and the $500,000 small business deduction. Flat-fee, no hourly billing, CPA Ontario, 1300+ five-star.
AFFORDABLE Personal Support Worker Business Accountant
A personal support worker business earns most of its revenue from personal-care and homemaker services that are HST-exempt under ETA Schedule V, Part II, especially the government-funded work billed through Ontario Health atHome. Exempt status means you do not charge HST on that revenue and you generally cannot recover the HST you pay on your inputs as input tax credits, so charging HST in error or over-claiming credits are the two most costly and audit-attracting mistakes an agency makes. Your workforce sits on the employee-versus-contractor line, and the placement-agency deeming rule forces you to withhold CPP and EI even where a PSW calls themselves self-employed. That is why you need a home care and PSW accountant who knows the exemption, the payroll and the classification rules. At Gondaliya CPA, we specialize in exempt-versus-taxable revenue splitting, payroll, WSIB and corporate tax planning for home-care agencies, providing AFFORDABLE flat-fee support that keeps you CRA-compliant and stops you paying more tax than you owe.
As a home-care agency accountant, we work with PSW staffing agencies, private-pay home-care businesses, community and senior home-care providers, and respite and palliative in-home care operators across Ontario, with year-round support rather than a once-a-year scramble. We tell you plainly what you can deduct, what you cannot, and where the real margin sits once payroll and WSIB are paid.
Let us handle the numbers so you can focus on the care that actually pays you.
Our Official Partners
Accounting That Understands How a Personal Support Worker Business Actually Works
Running a home-care agency comes with financial pressures a standard retail or service company never faces. Most of your revenue is HST-exempt, so you cannot recover the tax on your inputs, your workforce sits on the employee-versus-contractor line where the placement-agency rule can make you liable for CPP and EI, your WSIB coverage is mandatory from day one, and payroll is the core of your ledger. At Gondaliya CPA, we understand the financial reality of a personal support worker business and provide practical, home-care-focused solutions across the GTA and all of Ontario.
Stay Compliant and Minimize Your Personal Support Worker Business Tax
For a home-care agency, staying onside with CRA and WSIB and paying the least legal tax are the same job. We keep every filing on schedule while classifying your revenue and payroll the way the rules actually require, so nothing is missed and nothing invites a reassessment.
Accounting & Tax Experts for Personal Support Worker Businesses
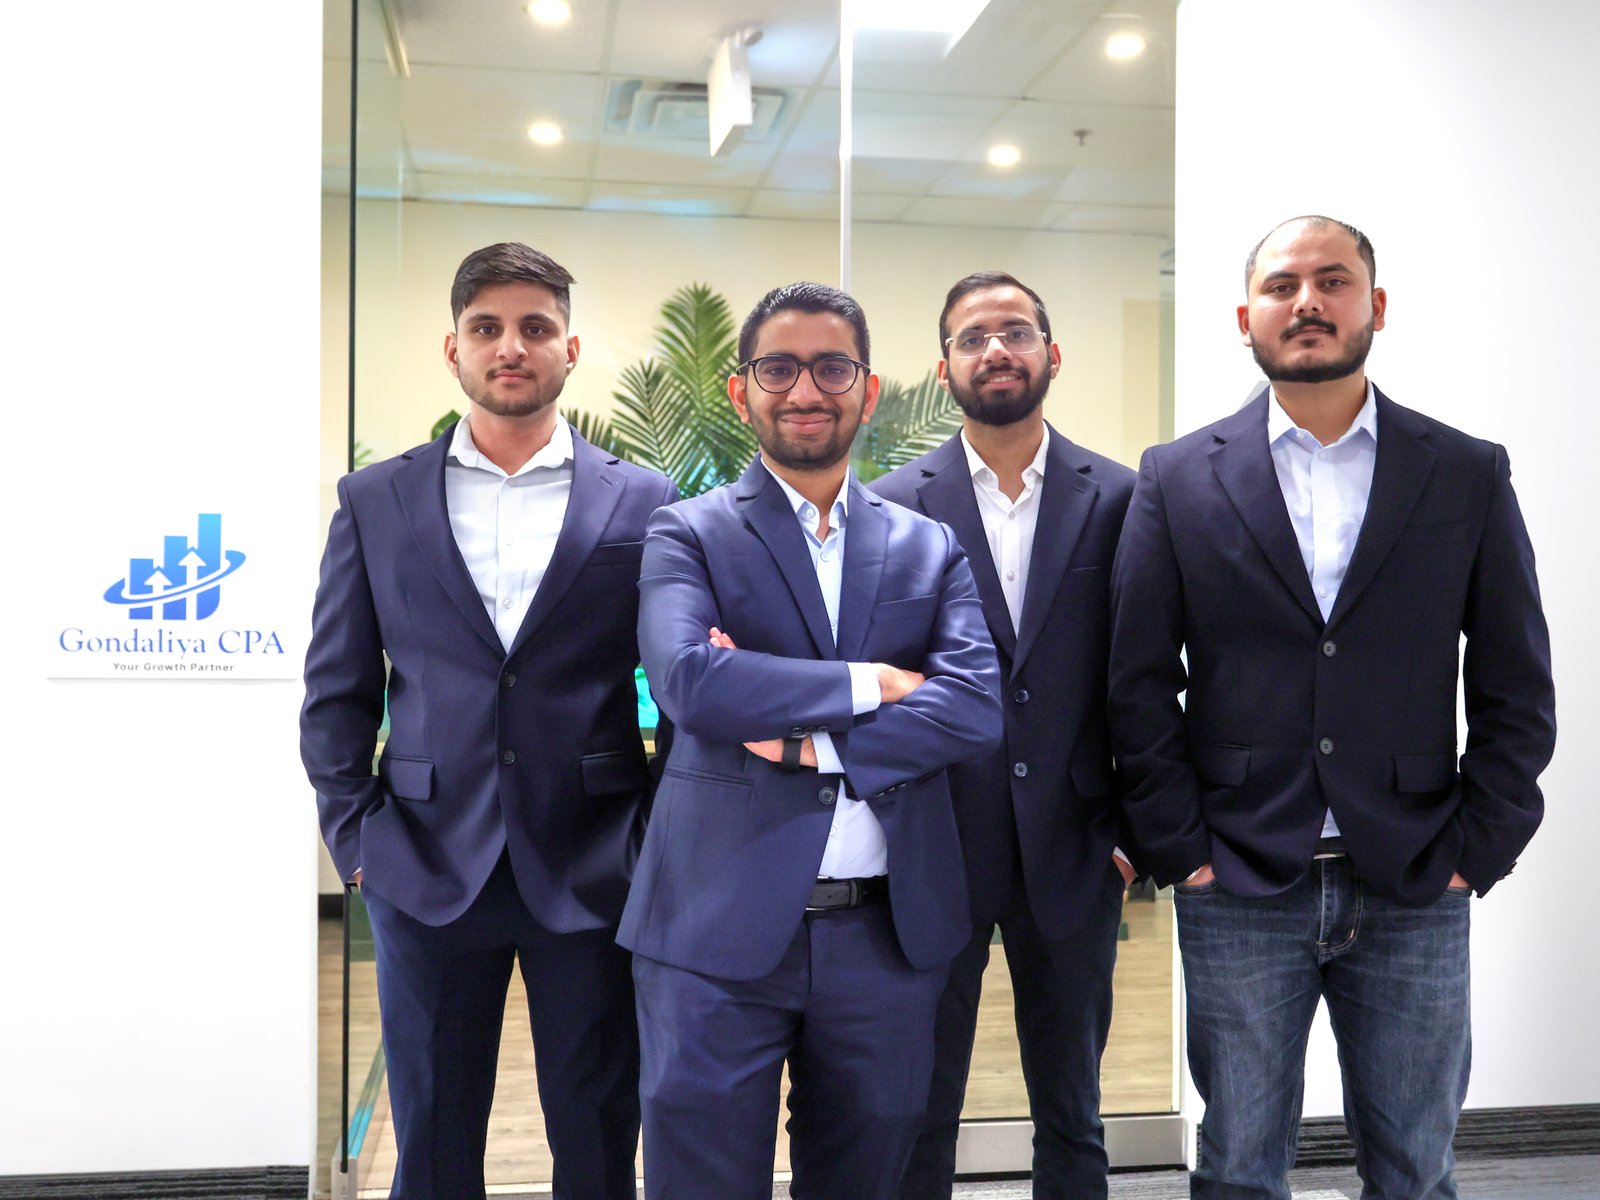
- AFFORDABLE + Fully Registered CPA Firm
- Business and Corporate Tax Expert
- Small & Medium Business Expert
- Accounting, bookkeeping, and tax filing
- Certified CPA
- 1300+ 5-star Google reviews
- 30-Day Money-Back Guarantee
- 60-Day Fees Matching Policy
Why Choose Our Accounting Services for Personal Support Worker Businesses?
Tax Planning — Home Care & Payroll Expertise
We keep your active income under the $500,000 Small Business Deduction at roughly 12.2% in Ontario, set the salary-and-dividend mix, plan the section 85 rollover on incorporation, and protect the $1.25M Lifetime Capital Gains Exemption on your future sale.
Consulting — Exempt Revenue & Payroll Bookkeeping
Our bookkeeping splits exempt Ontario Health atHome revenue from taxable private-pay lines, apportions your input tax credits, runs T4 and T4A payroll with WSIB, and tracks the per-kilometre mileage allowance for PSWs on the road.
CRA Representation — Classification & Payroll Audit
When CRA questions your worker classification under RC4110, the placement-agency CPP and EI withholding, or your exempt HST position, we prepare the response, reconcile source deductions, and pursue relief on Form RC4288 where penalties came from a prior error.
Bookkeeping — WSIB, ROEs & Growth
We register and reconcile WSIB, issue ROEs on separation, accrue ESA vacation pay, and get you ready to scale. We model the profit level where incorporating pays off and handle the move from sole proprietor to corporation.
Google Reviews
Personal Support Worker Business Clients
Personal Support Worker Business Tax and Accounting Services in Ontario
Corporate Tax Filing (T2) for Personal Support Worker Businesses
Professional T2 preparation with Schedule 125 revenue split into exempt and taxable lines, Schedule 8 CCA on vehicles and equipment, and CRA compliance on every line.
Bookkeeping & Accounting for Personal Support Worker Businesses
Exempt-versus-taxable revenue and payroll bookkeeping with financial statements, clean records, and monthly reporting built for a home-care agency.
Payroll Services for Personal Support Worker Businesses
T4 and T4A payroll with PD7A remittances, ROEs, ESA vacation pay, WSIB, and placement-agency CPP and EI withholding handled correctly.
GST/HST Filing for Personal Support Worker Businesses
AFFORDABLE HST handling of exempt home care under Schedule V Part II, with input-tax-credit apportionment on any taxable private-pay revenue.
Tax Planning for Personal Support Worker Businesses
Smart tax planning to protect the Small Business Deduction, set salary and dividends, time the section 85 rollover, and plan the eventual sale.
Corporate Catch-Up Filing for Personal Support Worker Businesses
File overdue T2 and payroll years, rebuild missing revenue and remittance records, and get back into CRA and WSIB compliance with accurate catch-up support.
CRA Audit Resolution for Personal Support Worker Businesses
Expert support for worker-classification, placement-agency CPP and EI, and exempt-HST audits, with source-deduction and RC4288 relief handled with confidence.
CPA Financial Statements (Notice to Reader) for Personal Support Worker Businesses
CPA-compiled financial statements that banks and lenders accept for your home-care corporation, separating exempt and private-pay revenue.
Incorporation Services for Personal Support Worker Businesses
Full incorporation including NUANS, articles, share structure, and the section 85 rollover from your unincorporated home-care business.
Catch-Up Bookkeeping Services for Personal Support Worker Businesses
We reconstruct months or years of exempt Ontario Health atHome and taxable private-pay records, split correctly for HST, and get your books ready for T2 and payroll catch-up.
US Corporation & LLC Tax Filing for Personal Support Worker Businesses
Cross-border 1120, 1120-F and 5472 filing for home-care owners with US-source income or a US entity, coordinated with your Canadian T2 so nothing is taxed twice.
Voluntary Disclosure Program for Personal Support Worker Businesses
We bring unfiled T2s, unremitted source deductions or a mishandled HST position forward through Form RC199 to reduce penalties and stop interest before CRA finds it.
Accounting & Tax Services Tailored for Personal Support Worker Businesses
Real, practitioner-level CPA expertise for PSW staffing agencies, private-pay home-care businesses, community and senior home-care providers, and respite and palliative in-home care operators across Ontario — built for how a home-care agency actually runs.
- We prepare your T2 with GIFI, reporting exempt Ontario Health atHome revenue and taxable private-pay revenue on their correct Schedule 125 lines and the balance sheet on Schedule 100, so CRA’s matching program never flags your file for a needless desk audit.
- We claim capital cost allowance on Schedule 8 with care vehicles in CCA Class 10 at 30% and office and lift equipment in Class 8 at 20%, because most agencies under-claim these pools and overpay CRA by thousands each year against active income.
- We add computers and tablets used for scheduling to CCA Class 50 at 55% rather than burying them in Class 8, and one recent home-care client recovered $4,600 of depreciation the prior preparer had misclassified across two open years.
- We keep your active income under the $500,000 Small Business Deduction so the first half-million is taxed near the 12.2% Ontario small-business rate, and we watch the associated-corporation rules before CRA grinds the limit toward the higher general rate.
- We file the T2 within six months of your fiscal year-end and pay any balance by the two- or three-month due date, so a home-care corporation earning $180,000 of profit never carries the arrears interest CRA charges on a late balance.
- We build your chart of accounts in QuickBooks Online or AlayaCare so government-funded Ontario Health atHome billings post separately from private-pay revenue, giving the clean exempt-versus-taxable split CRA expects behind your HST position and saving one agency $14,200 of wrongly-charged HST.
- We reconcile each Ontario Health atHome remittance against invoiced hours in Xero so the exempt revenue you report on the T2 ties to the funder’s payments, keeping the six years of records section 230 of the Income Tax Act requires behind every dollar.
- We apportion input tax credits where you run both exempt home care and taxable private-pay lines, so you recover HST only on the taxable portion of inputs and never over-claim credits CRA reverses with interest on a review.
- We capture PPE, gloves, uniform and criminal-record-check costs through Dext and attach them to each transaction, so a $9,000 supplies pool is fully documented instead of lost to a missing receipt when CRA asks for support.
- We run the payroll ledger monthly, accruing ESA vacation pay at 4% and WSIB premiums as they build, so your books show the true cost of care and month-end reporting is a clean transfer to the T2 rather than a year-end rebuild.
- We run pay through Wagepoint, issue T4 slips for employee PSWs and T4A slips for genuine subcontractors, and remit source deductions on the PD7A by the deadline, so a missed monthly remittance never triggers the 10% CRA penalty on late source deductions.
- We apply the placement-agency deeming rule under CPP Regulations section 34 and EI Regulations section 8, withholding CPP and EI on placed workers even where a PSW is “self-employed,” so your agency avoids the assessment for both halves plus penalties that misclassification brings.
- We issue ROEs within five days of a PSW’s separation and accrue ESA vacation pay at 4% of wages, so a home-care agency with 30 caregivers never faces the Service Canada and Ministry of Labour complaints that late slips and unpaid vacation invite.
- We register WSIB and reconcile premiums by rate group against actual care payroll, so an agency running a $600,000 wage bill pays the correct premium and avoids the retroactive assessment an unregistered employer carries back two years.
- We set up the per-kilometre motor-vehicle allowance at the CRA rate of 72 cents on the first 5,000 kilometres and 66 cents after for PSWs driving between client homes, keeping a reasonable allowance non-taxable and issuing a T2200 where employees use their own car.
- We confirm your personal-care and homemaker services are exempt under ETA Schedule V, Part II, so you do not charge HST on that revenue, and we stop the common error of adding 13% to Ontario Health atHome billings that would cost you thousands to unwind.
- We test the $30,000 small-supplier threshold on your taxable private-pay revenue only, because exempt home care is excluded from the calculation, so an agency whose exempt work runs into the millions is not forced to register on revenue that never counts.
- We deny input tax credits on inputs used to make exempt supplies, because exempt status blocks recovery, and we correct the over-claim CRA most often finds, saving one provider a $7,800 reassessment on credits it should never have taken.
- Where you run genuinely taxable private-pay or ancillary lines, we register for HST, apportion credits between exempt and taxable use, and file the return so line 101 ties to the taxable revenue on your T2 and nothing invites a match.
- We document the exempt-versus-taxable split on every filing period so a CRA review of your home-care corporation finds the classification already supported, rather than an agency scrambling to prove which revenue was exempt after the query letter lands.
- We set the salary-versus-dividend mix for your owners, paying enough T4 salary to build RRSP room while the balance flows as dividends, so combined tax stays near the 12.2% Ontario small-business rate rather than the personal rate that reaches 53.53%.
- We complete the section 85 rollover on Form T2057 when you incorporate, moving your goodwill, client contracts and care vehicles across at elected amounts, and one growing agency deferred $22,000 of tax that a straight sale of those assets would have triggered.
- We plan at least two years ahead so your shares qualify for the $1.25M Lifetime Capital Gains Exemption on qualified small business corporation shares, purifying the company of passive assets so selling your home-care business defers tax CRA would otherwise collect.
- We time equipment and vehicle purchases before your fiscal year-end so the half-year rule and the 30% Class 10 and 20% Class 8 declining-balance rates give the largest first-year deduction against a profitable year of care revenue.
- We structure the per-kilometre allowance and reasonable-allowance policy so mileage paid to driving PSWs stays non-taxable, keeping a $12,000 annual travel cost fully deductible to the company without adding taxable benefits to your caregivers’ T4s.
- We reconstruct exempt Ontario Health atHome revenue and taxable private-pay lines from bank deposits and funder statements where no bookkeeping exists across your unfiled years, so CRA cannot arbitrarily assess your agency on its own estimate and overcharge you on tax.
- Late filing costs 5% of the balance owing plus 1% per month up to twelve months, so we file your oldest unfiled T2 first to stop the penalty compounding and limit the arrears interest CRA charges your home-care corporation.
- We prepare the unfiled T4 and T4A slips and the PD7A reconciliations for every year you paid PSWs, filing them with the catch-up returns so CRA does not add the per-slip and late-remittance penalties on top of the late T2.
- We register WSIB retroactively and reconcile the premiums owed on prior-year care payroll, so an agency that ran wages without coverage clears the back assessment before it grows with interest and jeopardizes new contracts.
- We rebuild the undepreciated capital cost pools across the unfiled years so missed CCA on your care vehicles in Class 10 and computers in Class 50 is recovered within the reassessment period, instead of surfacing later as a CRA reassessment that costs you more.
- When CRA challenges whether your PSWs are employees or contractors, we build the RC4110 analysis on control, tools, chance of profit and integration, defending the classification before a reassessment for both halves of CPP and EI plus penalties lands on your agency.
- Where CRA applies the placement-agency deeming rule to workers you paid as contractors, we quantify the exposure and negotiate the assessment, and one staffing agency recovered $9,800 of misclassified CPP and EI exposure through a corrected filing rather than a full penalty.
- We answer a source-deduction payroll audit with the T4, T4A and PD7A records in one package inside the 30-day query deadline, because a remittance disallowed for missing support cannot be restored later at the objection stage.
- We defend your exempt-HST position under Schedule V Part II when CRA questions why you did not charge or remit tax on home care, showing the supply is exempt so your corporation is not assessed HST it never collected from funders.
- We file the Notice of Objection on Form T400A within 90 days of a reassessment and pursue taxpayer relief on Form RC4288 where a prior accountant’s error caused the penalties, protecting your right to the Tax Court and interest your agency should not carry.
- We prepare CSRS 4200 compilation engagement financial statements, the Notice to Reader a bank requires across two fiscal years before it approves the operating line or the $50,000-plus financing a growing home-care agency needs to make payroll while funders pay in arrears.
- Your compiled statement of financial position presents WSIB payable, vacation-pay accrual, source-deduction liabilities and care vehicles at net book value, giving a lender the working-capital picture a bare T2 cannot, so financing is approved faster.
- We build the statement of operations with exempt Ontario Health atHome revenue and taxable private-pay revenue classified consistently across two years and tied to the T2 filed with CRA, so a lender approves the credit rather than declining on reclassified noise.
- The CSRS 4200 communication discloses that no audit or review was performed and sets out the basis of accounting and owner withdrawals, without which a bank and the Business Development Bank of Canada reject the file for a home-care agency.
- We deliver the compiled statements within 30 days of receiving your records and the year’s T2 figures, because an agency’s financing approval collapses when the lender’s conditional offer expires before the accountant produces the file.
- We incorporate your business under the Ontario Business Corporations Act, giving you limited liability and the roughly 12.2% Ontario small-business rate on active income, so a home-care agency earning more than the owner draws stops paying tax at the 53.53% personal rate.
- We complete the section 85 rollover on Form T2057, transferring your goodwill, client contracts and care vehicles into the corporation at elected amounts, deferring the capital gain and recapture a straight sale of those assets would trigger for CRA.
- We complete your WSIB registration before the first caregiver starts, because home-care work makes coverage mandatory from day one, and an unregistered agency faces retroactive premiums going back two years plus penalties that immediate registration avoids.
- We open the corporation’s CRA Business Number, payroll and, where you have taxable private-pay revenue, HST accounts within the first 30 days, set the source-deduction remittance schedule, and close the old accounts so your agency never remits the same revenue twice.
- We structure the share classes and set the first fiscal year-end up to 53 weeks out so the first T2 and CRA balance-due date defer to save cash, and where you buy a franchised home-care brand we record the franchise fee in CCA Class 14.1.
- We reconstruct exempt Ontario Health atHome and taxable private-pay revenue from bank deposits and funder statements across unfiled years, so your HST position and the exempt-versus-taxable split are supportable before we prepare the overdue T2 returns.
- We rebuild caregiver payroll for prior periods, recalculating CPP, EI and income-tax source deductions on the PD7A, issuing missing T4 and T4A slips and ROEs, so a $9,000 remittance gap is corrected before CRA assesses gross-negligence penalties.
- We apportion input tax credits across the catch-up period wherever you ran both exempt home care and taxable private-pay lines, so historical HST returns recover credits only on the taxable portion and never over-claim what a review reverses with interest.
- We reconcile each Ontario Health atHome remittance and WSIB premium against invoiced caregiver hours, catching up the mileage log for PSWs driving between client homes so every deductible kilometre is captured and the six-year records rule under section 230 is met.
- We build a clean chart of accounts in QuickBooks Online or AlayaCare that separates government-funded exempt billings from private-pay revenue going forward, giving you a monthly close and a trial balance that ties to the funder before your next filing deadline.
- We prepare Form 1120 for a US C-corporation or 1120-F where your home-care company has US-source income or a US branch, coordinating the return with your Canadian T2 so the same profit is not taxed twice across the border.
- We file Form 5472 for any US corporation or LLC that is 25% foreign-owned by you or your Canadian agency, disclosing reportable transactions to avoid the $25,000 penalty the IRS levies for each unfiled information return.
- We treat a US LLC correctly for Canadian purposes, because CRA sees it as a corporation while the IRS may flow it through, and we structure the reporting so the caregiver-business owner claims foreign tax credits and avoids double taxation.
- We keep your exempt Ontario Health atHome revenue and taxable private-pay lines properly characterized on both sides of the border, so US filings and the Canadian T2 report the home-care income consistently and no funder payment is misclassified between jurisdictions.
- We apply the Canada-US treaty to your PSW corporation’s cross-border activity, determining permanent-establishment exposure and withholding on any US management fees, so a company expanding caregiver placement into a US state files on time and pays only the tax it truly owes.
- We file your application under the CRA Voluntary Disclosures Program on Form RC199 before an audit letter arrives, so your home-care corporation gains penalty relief and partial interest relief on unfiled T2s and unremitted source deductions.
- We correct a mishandled HST position through the program where an agency wrongly charged 13% on exempt Ontario Health atHome billings or over-claimed input tax credits, disclosing the error and repaying $18,000 before CRA finds it in a desk audit.
- We disclose caregiver payroll that was never remitted, where PSWs were paid as contractors despite the placement-agency deeming rule, bringing unpaid CPP and EI current so your agency escapes the gross-negligence penalties this classification error normally triggers.
- We confirm your disclosure is valid, voluntary, complete and involves a penalty, and covers information at least one year overdue, so CRA accepts the PSW corporation into the program rather than rejecting a filing prompted by an enforcement query.
- We assemble the back-filed returns, worker-classification support under CRA guide RC4110 and the exempt-versus-taxable revenue records the program requires, then negotiate a payment arrangement so a caregiver business clears years of arrears without a crippling lump-sum demand.
PSW & Home Care Tax & Payroll Check
Six quick questions on your exempt and taxable revenue, HST, worker classification, WSIB, mileage and whether it is time to incorporate. No fee shown.
1. Do you split your exempt home care from any taxable private-pay revenue?
2. Are you correctly NOT charging HST on your home-care work?
3. Are your PSWs classified correctly as T4 employees or T4A contractors?
4. Is your agency registered for WSIB and paying premiums?
5. Are you handling mileage or a per-kilometre allowance for driving PSWs?
6. Is your home-care business incorporated yet?
Free CPA Consultation for Personal Support Worker Businesses
Case Studies: Personal Support Worker Business Accounting & Tax
Toronto PSW Staffing Agency — Exempt HST & Input Tax Credits
The problem: A Toronto PSW staffing agency was charging 13% HST on its exempt Ontario Health atHome home-care billings and remitting it to CRA, while also claiming input tax credits on its inputs as though the revenue were taxable. Because personal-care and homemaker services are exempt under ETA Schedule V, Part II, the agency should never have charged the tax and could not recover the credits it took, leaving it out of pocket on the remitted HST and exposed to a reassessment on the over-claimed credits every filing period.
What we did: We reclassified the revenue as exempt under Schedule V Part II, corrected the prior HST returns, stopped the HST from being added to funder billings, and fixed the input-tax-credit apportionment so credits were claimed only against genuinely taxable private-pay work.
The result:
- Recovered $14,200 of wrongly-charged and remitted HST
- Over-claimed input tax credits corrected before a CRA audit
- Home-care billings no longer carry HST in error
Mississauga Home-Care Business — Incorporation & Worker Status
The problem: A growing Mississauga home-care business was still a sole proprietor, so roughly $180,000 of profit was taxed at the owner’s top personal rate, and its PSWs were all paid as “contractors” with no CPP or EI withheld. Under the placement-agency deeming rule the agency was liable to withhold anyway, so the misclassification was building an exposure to both halves of CPP and EI plus penalties, and there was no split between exempt home care and taxable private-pay lines on the books.
What we did: We incorporated the business and moved the assets across on a section 85 rollover, applied the $500,000 Small Business Deduction, split the private-pay taxable revenue from the exempt Ontario Health atHome work, and corrected the worker status under the placement-agency rule with proper T4 payroll.
The result:
- Cut the tax bill materially at the 12.2% small-business rate
- Removed the CPP and EI exposure on misclassified PSWs
- Exempt and taxable revenue now split on every filing
Ottawa Home-Care Agency — Clean Books, WSIB & Remittances
The problem: An Ottawa home-care agency had no clean split between government-funded Ontario Health atHome revenue and private-pay work, was not registered for WSIB despite running a payroll of care staff, and had fallen behind on its PD7A source-deduction remittances. The mixed books made the exempt-versus-taxable position impossible to support, the unregistered WSIB coverage was accruing a retroactive exposure, and the late remittances were drawing CRA penalties on every cycle.
What we did: We rebuilt the chart of accounts around Ontario Health atHome billing versus private pay, registered WSIB and reconciled the premiums, and set up the PD7A remittance schedule and the ROE workflow in QuickBooks so payroll ran on time.
The result:
- Clean exempt-versus-private-pay books the agency can defend
- WSIB registered and premiums reconciled by rate group
- Zero late-remittance penalties since the cleanup
How We Work With Personal Support Worker Businesses
Our clear, efficient process ensures every step is transparent, building trust and long-term client relationships.
Kickoff (Document Request)
Collect prior T2 returns, Ontario Health atHome and private-pay billing records, payroll and T4/T4A records, WSIB account, contractor agreements, mileage logs, and bank statements.
First 30 Days (Cleanup & Setup)
Set up QuickBooks Online or AlayaCare, split exempt from taxable revenue, confirm your HST and classification position, and configure payroll, WSIB and PD7A tracking.
Monthly Close
Monthly reconciliations, receipt capture, payroll and remittances, WSIB accrual, and exempt-versus-taxable revenue tracking.
Quarterly Planning Review
Salary and dividend mix, worker-classification check, HST and ITC apportionment review, and incorporation break-even.
Year-End Close & T2 Filing
Trial balance, financial statements splitting exempt and private-pay revenue, T2 with GIFI, payroll slips, and CRA preparation.
Get Your Personal Support Worker Business Taxes Done Right Today
Affordable Pricing for Personal Support Worker Businesses
We believe in clear, upfront pricing so you know exactly what to expect. All fees include HST.
- Tax Preparation (Corporation) — From $400
- Tax Return Filing (Corporation) — From $400
- Tax Compliance Audit — FREE CRA audit support for our clients
- Tax Strategy — FREE for our clients
- Accounting Base Plan — From $100 per month
- Bookkeeping Management — Free for our Accounting clients
- Financial Reporting — Free for our Accounting clients
- Business Formation — Flat $35
- Incorporation Process — Flat $35
- Entity Setup Assistance — Flat $35
- Full-Service Payroll — From $125 per month
Payment is by Interac e-Transfer to info@gondaliyacpa.ca only. Security question: Not Applicable, as auto-deposit is enabled.
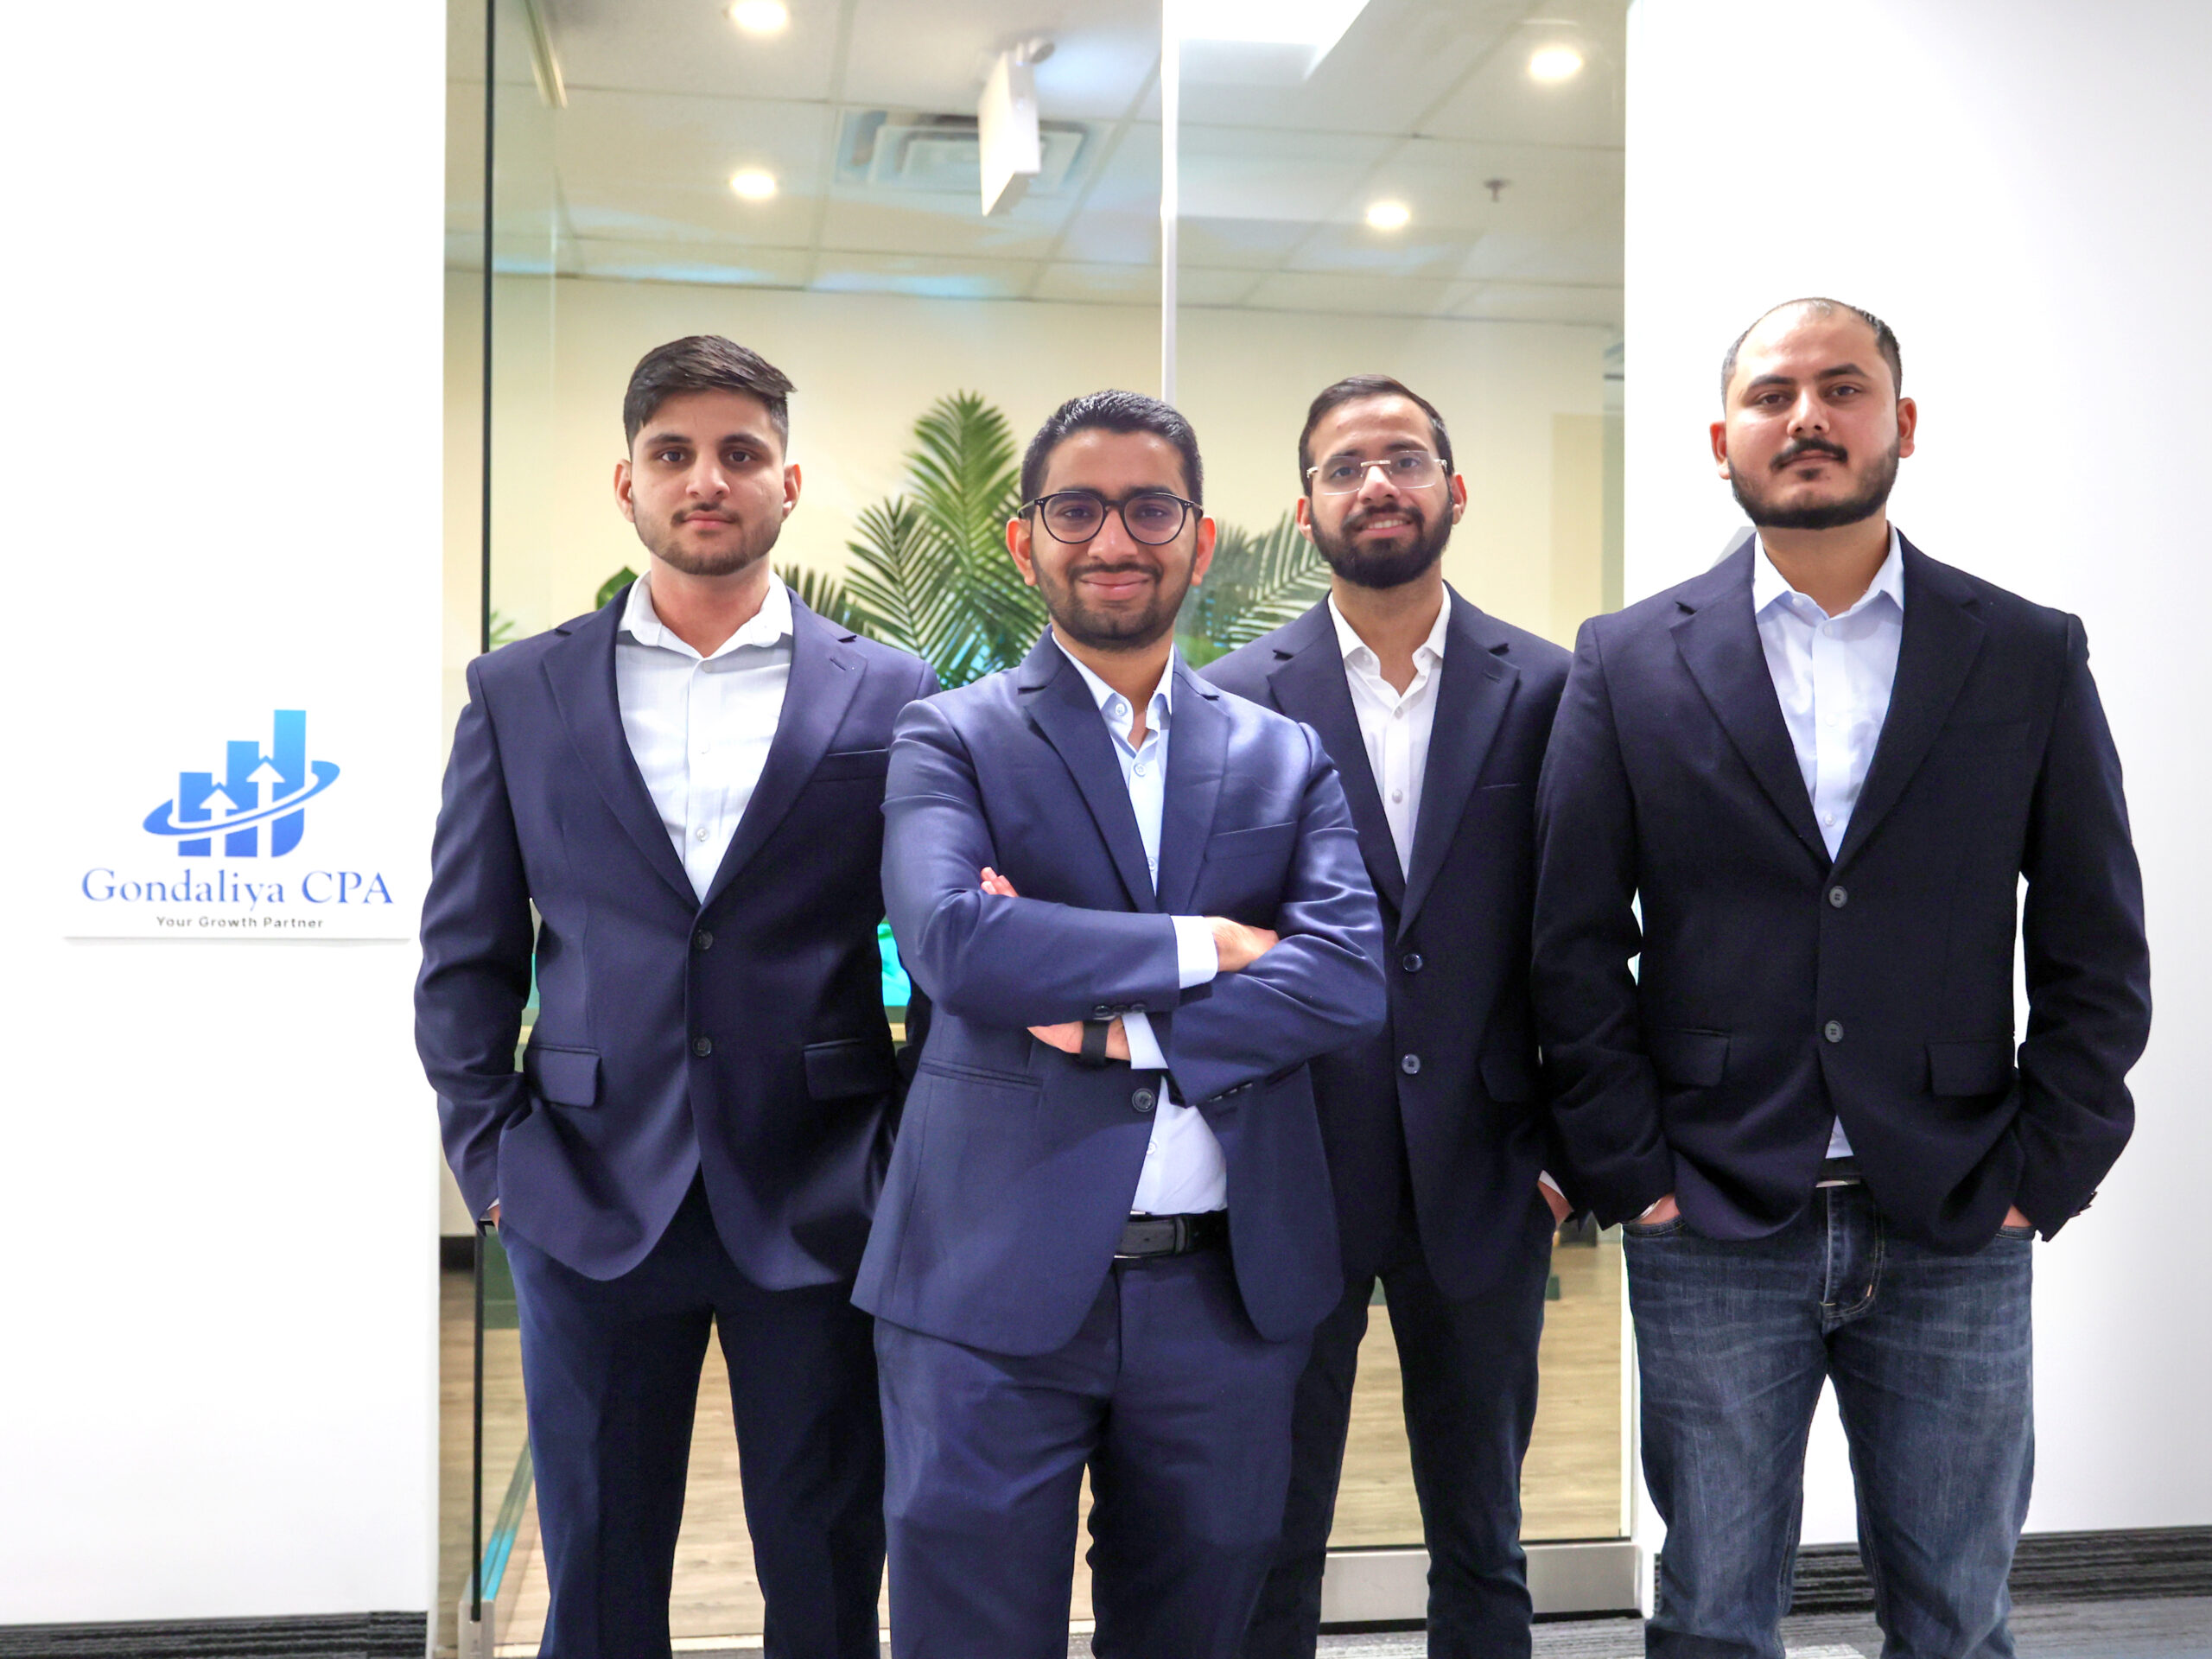
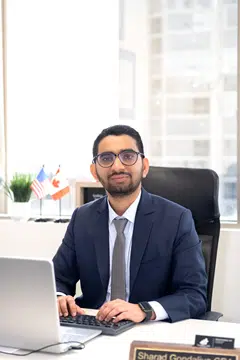
Meet Your Lead Home Care & PSW Accountant
Meet your lead home care and PSW accountant. As your payroll and corporate tax adviser, you deal with the same two people every year.
What Our Clients Say
1300+ five-star reviews from home-care agencies and small-business owners across Ontario and Canada.
Serving Personal Support Worker Businesses Across Ontario
Our CPA team provides specialized accounting and tax solutions for personal support worker and home-care businesses throughout Ontario. We understand how exempt Ontario Health atHome revenue, private-pay work, payroll and WSIB actually flow through a home-care agency, what CRA looks at on a worker-classification file, and where the real margin sits once care wages are paid.
Toronto (ON)
55 Queen St E Ste 1205, Toronto, ON M5C 1R6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Mississauga (ON)
5373 Bullrush Dr, Mississauga, ON, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Brampton (ON)
4 Starhill Crescent, Brampton, ON L6R 2P9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Scarborough (ON)
24 Clementine Square, Scarborough, ON M1G 2V7, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Vaughan (ON)
19 Cabinet Crescent, Woodbridge, ON L4L 6H9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Oshawa (ON)
210 Durham St, Oshawa, ON L1J 5R3, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Ottawa (ON)
2090 Neepawa Ave a314, Ottawa, ON K2A 3L6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Etobicoke (ON)
60 Stevenson Rd #1601, Etobicoke, ON M9V 2B4, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Hamilton (ON)
70 Starling Dr, Hamilton, ON L9A 0C5, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Guelph (ON)
1155 Gordon St, Guelph, ON N1L 1S8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Windsor (ON)
4387 Guppy Ct, Windsor, ON N9G 2N8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
North York (ON)
150 Graydon Hall Dr #912, North York, ON M3A 3B2, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Personal Support Worker Business Accounting & Tax FAQs
Related Industries We Serve
Accountant for Retirement Homes
- Exempt and taxable revenue splitting
- Payroll, WSIB and source deductions
- Corporate tax planning and financial statements
Accountant for Nurses
- Incorporation and section 85 planning
- Salary, dividend and SBD planning
- Bookkeeping and personal tax
Accounting for Small Businesses
- Corporate tax planning for small businesses
- Business tax filing and financial statements
- Payroll and bookkeeping services
Accountant for Incorporated Businesses
- T2 corporate returns and GIFI
- Salary, dividend and SBD planning
- Compilation statements and incorporation
Personal Support Worker Business Accounting & Tax Done Right.
T2 filing, exempt-versus-taxable HST under Schedule V Part II, input-tax-credit apportionment, placement-agency CPP and EI, worker classification, WSIB, T4 and T4A payroll with PD7A and ROEs, mileage allowances and incorporation under one roof. AFFORDABLE flat fees, no hourly billing. Licensed CPA Ontario. 1300+ five-star reviews. 30-Day Money-Back Guarantee.