



Tax Accountant for Wedding Venues in Ontario and Across Canada
We carry your booking deposits as deferred revenue until the wedding is actually hosted instead of taxing you a year early on money that is still the couple’s, hold the tax until the deposit is applied under ETA subsection 168(9), account for the forfeited deposit on a cancellation under ETA section 182 rather than keeping it quietly, split the mandatory service charge from the voluntary gratuity because only one of them carries tax, put the building in Class 1 and the build-out in Class 13, and decide early whether the land belongs inside the operating company at all. Whether you run a barn or estate venue, a winery or golf club, a hotel ballroom, or an all-inclusive package venue, we handle the deposits, the bar and the event payroll — with AFFORDABLE flat fees.
AFFORDABLE Wedding Venue Tax Accountant
A wedding venue gets paid a long time before it does the work, and almost every tax problem in the trade starts there. A couple books eighteen months out and pays a deposit. That money sits in your bank account, and it is not yours: it is client money held against a date you have not yet delivered. Book it as revenue when it arrives and you pay tax a year early on a wedding that has not happened, and your balance sheet tells a lender you are far stronger than you are. The sales tax works the same way and catches people out in both directions: under ETA subsection 168(9) a deposit is not consideration until you apply it, so no tax comes off when the couple books. But cancel that wedding and keep the money, and ETA section 182 treats the forfeited deposit as tax-included, so the money you keep carries tax even though nobody ever walked down the aisle. At Gondaliya CPA, we specialize in deposit, bar and event payroll accounting for venues, providing AFFORDABLE flat-fee support that keeps you CRA-compliant and stops you paying more tax than you owe.
As a wedding venue accountant, we work with barn and estate venues, winery and golf club venues, hotel ballrooms, and all-inclusive package venues across Ontario, with year-round support rather than a once-a-year scramble. We tell you plainly what you can deduct, what you cannot, and what your bank balance actually means in February.
Let us handle the numbers so you can focus on the season and the couples who booked you.
Our Official Partners
Accounting That Understands How a Wedding Venue Actually Works
Running a venue comes with financial pressures a restaurant never faces. You are paid long before you deliver, your revenue arrives in a five-month window and your costs run all twelve, your bar can quietly eat the margin on a full calendar, and a single cancellation is a tax event most owners have never heard of. At Gondaliya CPA, we understand that reality and provide practical, trade-focused solutions across Ontario.
Stay Compliant and Minimize Your Wedding Venue Tax
For a venue, staying onside with the AGCO, public health and CRA and paying the least legal tax are the same job. We keep every filing on schedule while claiming every food, bar, furniture and building dollar the T2 allows, so nothing is missed and nothing invites a reassessment.
Accounting & Tax Experts for Wedding Venues
- AFFORDABLE + Fully Registered CPA Firm
- Business and Corporate Tax Expert
- Small & Medium Business Expert
- Accounting, bookkeeping, and tax filing
- Certified CPA
- 1300+ 5-star Google reviews
- 30-Day Money-Back Guarantee
- 60-Day Fees Matching Policy
Why Choose Our Accounting Services for Wedding Venues?
Tax Planning — Deposits & Property
We know the trade: deferred revenue on the booking calendar, ETA subsection 168(9) on deposits, the building in Class 1 and the build-out in Class 13. We protect the $500,000 Small Business Deduction.
Consulting — Event Costing & Bar Control
Our bookkeeping costs each wedding against the food, bar, staff hours and linens it consumed, tracks bar cost against LCBO purchases, and shows what the all-inclusive package really earns.
CRA Representation — Deferred Revenue & Cancellation Audit
When CRA questions your deferred revenue or the HST on forfeited deposits, we prepare the response and pursue relief on Form RC4288 where a prior error caused the penalties.
Bookkeeping — Seasonality & Sale
We build the cash flow that carries you from November to April, produce the statements your mortgage lender reads, and settle the property question long before you go to market.
Google Reviews
Wedding Venue Clients
Wedding Venue Tax and Accounting Services in Ontario
Corporate Tax Filing (T2) for Wedding Venues
Professional T2 preparation with deposits carried as deferred revenue, Schedule 8 CCA across Class 1, Class 13 and Class 8, and CRA compliance on every line.
Bookkeeping & Accounting for Wedding Venues
Deposit ledger, event costing and bar control bookkeeping with financial statements, clean records, and margin reporting per wedding.
Payroll Services for Wedding Venues
Event staff and bartender payroll with WSIB coverage, PD7A remittances, T4s filed by the last day of February, and service charge distribution handled correctly.
GST/HST Filing for Wedding Venues
AFFORDABLE HST filing with the tax held until deposits are applied, forfeited deposits accounted for, and every input tax credit recovered.
Tax Planning for Wedding Venues
Smart tax planning on your year-end date, the Small Business Deduction, furniture replacement timing and the property structure before a sale.
Corporate Catch-Up Filing for Wedding Venues
File overdue T2 and HST years, rebuild missing booking, deposit and bar records, and get back into CRA compliance with accurate catch-up support.
CRA Audit Resolution for Wedding Venues
Expert support for deferred revenue, cancellation HST and service charge audits, handled with confidence from the first letter.
CPA Financial Statements (Notice to Reader) for Wedding Venues
CPA-compiled financial statements that mortgage lenders accept on the property and that carry the deposit liability a bank needs to see.
Incorporation Services for Wedding Venues
Full incorporation including NUANS, articles, share structure, and the section 85 rollover of your furniture, equipment and bookings into the company.
Catch-Up Bookkeeping Services for Wedding Venues
Months or years of contracts, deposits, LCBO statements and supplier invoices reconstructed and reconciled, so your deposit ledger is finally accurate.
US Corporation & LLC Tax Filing for Wedding Venues
Cross-border filing where owners or shareholders are non-resident or American, covering withholding, treaty positions and T1135 reporting.
Voluntary Disclosure Program for Wedding Venues
Come forward on unreported cancellation HST, deposits taxed in the wrong year or unfiled T4 slips before CRA calls, cancelling penalties through a Voluntary Disclosures Program application.
Accounting & Tax Services Tailored for Wedding Venues
Real, practitioner-level CPA expertise for barn and estate venues, winery and golf club venues, hotel ballrooms, and all-inclusive package venues across Ontario — built for a business that is paid long before it delivers.
- We prepare your T2 with GIFI on Schedule 100 and Schedule 125, separating room rental, ceremony fees, food and beverage, bar revenue and the mandatory service charge onto their correct lines so CRA’s automated matching does not misread your file.
- We carry booking deposits as deferred revenue until the wedding is actually hosted, because a venue holding a full season of deposits is sitting on client money, not income, and taxing it a year early is money gone.
- We claim capital cost allowance on Schedule 8 with the venue building in Class 1 at 4%, tables, chairs, linens and kitchen equipment in Class 8 at 20%, and shuttle vehicles in Class 10 at 30%.
- Where the venue is leased we capitalize the build-out to Class 13 over the lease term rather than expensing it, so a $200,000 fit-out is deducted across the years it serves instead of wrecking one.
- We separate the mandatory service charge from voluntary gratuities on the revenue lines, because the charge is taxable consideration with a payroll consequence and the tip is neither, and blending them gets both wrong.
- We run the deposit ledger against the booking calendar in Tripleseat or Event Temple, so at any point you know what is client money held against future dates and what is actually yours to spend.
- We cost each wedding against the food, bar, staff hours and linens it consumed, and on one venue this showed the all-inclusive package losing money once bar cost and overtime were loaded against it.
- We track bar cost as a percentage of bar revenue every month against LCBO purchases, because a consumption bar with no pour control is the fastest way for a venue to lose margin it never sees.
- We build a thirteen-period cash flow across the season and the trough, because a venue banks most of its revenue between May and October and pays rent, insurance and salaried staff for all twelve months.
- We capture every LCBO, food, linen and licence invoice through Dext and reconcile monthly, keeping the six years of records ITA section 230 requires and making sure no input tax credit is lost to a missing bill.
- We set up event staff payroll in Wagepoint, withholding income tax, CPP and EI and remitting on the PD7A by the 15th of the following month, because CRA’s late-remittance penalty on source deductions climbs to 10%.
- We register your WSIB coverage before the first server is hired and keep it current through the season, because a kitchen and a bar floor are exactly the workplaces an unregistered employer cannot afford an injury on.
- We handle the payroll side of the mandatory service charge where it is distributed to staff, because money the venue collects and pays out is not the same as a tip left directly and does not get the same treatment.
- We file your T4 slips and T4 Summary by the last day of February and reconcile them to the PD7A remittances actually made, so a venue that triples its crew for August never generates a penalty for a mismatch.
- We monitor total Ontario payroll against the $1,000,000 Employer Health Tax exemption, which a venue running a full kitchen and bar crosses sooner than the owner expects, so you register in the right year.
- A booking deposit is not consideration until you apply it, so under ETA subsection 168(9) the tax is not collected when the couple books and is collected when the deposit lands against the invoice on the event date.
- When a wedding is cancelled and you keep the deposit, ETA section 182 treats the forfeited amount as tax-included, so the money you keep carries tax even though no wedding was ever hosted.
- We separate the mandatory service charge, which is taxable consideration, from a voluntary gratuity, which is not, because a venue that charges tax on tips is over-collecting and one that does not charge it on service is under-remitting.
- We claim the input tax credits on food, linens, kitchen equipment, grounds upkeep, insurance and the build-out, which on a venue carrying real property and a full kitchen is a substantial recovery every period.
- We reconcile the HST on your returns to the revenue on your T2 every filing period, because CRA’s matching program compares the two and a company whose figures disagree by even $5,000 is among the fastest files pulled for audit.
- We choose a fiscal year-end outside the season, because a year-end in August means counting linens and valuing deposits in the weeks your team has least capacity and the numbers are least reliable.
- We set the salary-versus-dividend mix for the owners, paying enough T4 salary to build RRSP room while the balance flows as dividends, so combined tax stays near the 12.2% Ontario small-business rate instead of 53.53%.
- We keep your active income under the $500,000 Small Business Deduction limit using ITA section 125, and watch the associated-corporation rules where the owner also holds the land in a second company.
- We time linen, furniture and kitchen replacement against your fiscal year-end so the 20% Class 8 rate gives the largest first-year deduction against a season that actually filled the calendar.
- We plan at least two years ahead so your shares qualify for the $1.25M Lifetime Capital Gains Exemption under ITA 110.6, which on a venue means looking hard at whether the real property belongs inside the operating company.
- We reconstruct room rental, food and beverage, bar and service charge revenue from bank deposits, the booking system and issued contracts across your unfiled years, rebuilding the six years of records ITA section 230 requires.
- Late filing costs 5% of the balance owing plus 1% per month up to twelve months, so we file your oldest unfiled T2 first to stop the penalty compounding and limit the arrears interest CRA charges your corporation.
- We rebuild the deposit liability at each year-end from the booking calendar, because a catch-up filing that treats every dollar received as revenue in the year it arrived is wrong in every year it covers.
- We rebuild the capital cost pools so missed allowance on the Class 1 building, the Class 13 build-out and Class 8 furniture and kitchen equipment is recovered rather than lost along with the years themselves.
- We file a Voluntary Disclosures Program application on Form RC199 before CRA contacts you, because a disclosure accepted under the general program cancels penalties in full and gives roughly 50% interest relief on the older years.
- When CRA questions your deferred revenue, we produce the booking calendar, the signed contracts and the deposit ledger showing which dates were still in the future at year-end, rather than a figure nobody can trace.
- When CRA tests the HST on cancellations, we show the section 182 treatment applied to each forfeited deposit, because a venue that kept money on a cancelled wedding and reported nothing is the easy adjustment on a review.
- We answer service charge and gratuity queries with the contracts, the distribution records and the payroll, because how the charge is presented to the couple and paid to staff is what actually decides the treatment.
- When CRA opens a full audit, we manage the file and answer the revenue, deposit and payroll queries inside the deadlines, so a one-year review does not expand across the three prior years CRA is entitled to reopen.
- We file the Notice of Objection within 90 days of a reassessment and pursue taxpayer relief on Form RC4288, cancelling penalties and interest that can top $15,000 where a prior accountant’s error caused them, protecting your right to the Tax Court.
- We prepare the CSRS 4200 compilation engagement financial statements a bank requires across two fiscal years for the mortgage on the property and for the operating line that carries the venue through the winter trough.
- Your compiled statement of financial position carries the deposit liability against the cash balance, which is the single most important thing a lender needs to see, because the bank account overstates the venue’s position.
- We present the building, the build-out, furniture and kitchen equipment at net book value by class, so a lender underwriting against the property reads asset values rather than guessing from a tax return.
- We build the statement of operations with room rental, food and beverage, bar and service charge revenue classified consistently across two years and tied to the T2 filed with CRA, so the bank accepts the file.
- We deliver the compiled statements within 30 days of receiving your records and the year’s T2 figures, because a mortgage renewal or a conditional offer on a neighbouring property collapses when the file is not produced in time.
- We incorporate your venue under the Ontario Business Corporations Act, giving you limited liability on liquor service and public-occupancy exposure and roughly the 12.2% Ontario small-business rate against the 53.53% top personal rate.
- We complete the section 85 rollover on Form T2057, transferring furniture, kitchen equipment, bookings and goodwill into the corporation at elected amounts, deferring the capital gain a straight sale of those assets would trigger.
- We decide early whether the land and building go into the operating company or a separate one, because real property inside the opco can put the QSBC asset test at risk years before you think about selling.
- We open the corporation’s CRA Business Number, HST and payroll accounts within the first 30 days and confirm the AGCO liquor sales licence transfers to the new entity rather than lapsing with the old one.
- We set the chart of accounts with the deposit liability, the service charge split and bar cost tracking built in from the first booking, so the records accumulate correctly rather than being rebuilt at year-end.
- We rebuild months or years of neglected books from bank deposits, the booking system, LCBO statements and supplier invoices, so a venue that let its records slide through two seasons gets a clean ledger.
- We reconstruct the deposit ledger across the backlog and tie every held deposit to a date on the calendar, because an unreconciled deposit balance is the single most common mess we find on a venue file.
- We recover the input tax credits buried in unentered food, linen, licence and build-out invoices, because a venue with a full kitchen and real property can hide five figures of credits over a couple of neglected years.
- We rebuild bar cost against LCBO purchases month by month so the caught-up statements show a beverage margin your bank will believe rather than one that swings wildly for no operational reason.
- We rebuild the Class 1, Class 13, Class 8 and Class 10 asset schedules and reconcile payroll across the caught-up months, so an accurate T2 can be filed without guessing at a lost year.
- A wedding held at your Ontario property is taxable here whatever passport the couple holds, because a supply in relation to real property situated in Canada does not become an export just because the client lives abroad.
- Where a non-resident owns shares in your venue corporation, we handle the Part XIII withholding on dividends paid out of Canada and the NR4 reporting that follows, so nothing is missed at 25% or the treaty rate.
- We file Form T1135 where the owners’ foreign property passes the $100,000 threshold, avoiding a penalty regime CRA applies whether or not any tax was actually owing on the holding itself.
- Where a US citizen is a shareholder or an owner of the venue, we coordinate the Canadian and US returns, because their reporting obligations reach into a Canadian corporation in ways most families discover far too late.
- We reconcile the Canadian and US returns so foreign tax credits actually land, ensuring tax paid on the same income in one country offsets tax in the other rather than being written off as a cost.
- We bring your venue forward on HST never accounted for on forfeited deposits, because a season of cancellations kept without reporting the section 182 treatment adds up quickly and a disclosure cancels the penalty.
- We disclose deposits taken and reported as income in the wrong year, correcting the deferred revenue position on your own terms rather than waiting for a reviewer to reassess every open year at once.
- We file your VDP submission on Form RC199 with a full reconstruction from the booking system, contracts and bank records, so a venue that outgrew its bookkeeping is not left facing an arbitrary CRA assessment.
- We correct unfiled T4 slips on event staff paid in cash, sparing the venue the per-slip penalties and the source deduction assessment CRA raises once it matches the wage line to its own records.
- We confirm your disclosure is genuinely voluntary before CRA contacts you — the single condition that makes it valid — and secure the roughly 50% interest relief on the older years, turning a prosecution risk into a managed correction.
Wedding Venue Deposit & Tax Check
Six quick questions on your deposit accounting, your cancellation HST, your service charge, your year-end date, your property structure and whether it is time to incorporate. No fee shown.
1. Are booking deposits carried as deferred revenue until the event?
2. Do you account for HST when a deposit is forfeited on a cancellation?
3. Is your mandatory service charge separated from voluntary gratuities?
4. Is your fiscal year-end outside the wedding season?
5. Has the land and building structure been reviewed against the QSBC test?
6. Is your wedding venue incorporated?
Free CPA Consultation for Wedding Venues
Case Studies: Wedding Venue Accounting & Tax
Guelph Barn Venue — A Season of Deposits
The problem: A Guelph barn venue booked eighteen months ahead and recognized every deposit as revenue the day it cleared. By its December year-end it had taken deposits on forty-one weddings for the following summer and reported the lot as income. It paid corporate tax on a season it had not yet worked, its balance sheet showed no liability for the money it owed back if anything went wrong, and the owner genuinely believed the bank balance was profit.
What we did: We rebuilt the deposit ledger against the booking calendar, moved the held deposits to deferred revenue, restated the prior year comparatives, and set a monthly routine that ties the liability to the calendar so the number is right at every close rather than once a year.
The result:
- Deposits on 41 future weddings moved off income
- Tax paid in the year the work is done, not a year early
- Deposit liability now reconciled monthly
Hamilton Estate Venue — Cancellations and the Service Charge
The problem: A Hamilton estate venue had two problems that both lived in the same invoice. It kept the deposit on every cancelled wedding and reported nothing at all on those amounts, having been told forfeited money was not a sale. And it applied an eighteen per cent charge to every event, called it a gratuity, charged no tax on it, and distributed it to staff outside payroll. One error under-remitted HST on cancellations; the other under-remitted on a charge that was never really a tip.
What we did: We applied the ETA section 182 treatment to the forfeited deposits across the open periods, reworked the contracts so the mandatory charge is presented as what it is, brought it onto the taxable revenue line, and moved the distribution onto payroll.
The result:
- Cancellation HST brought current under section 182
- Service charge now taxed and distributed correctly
- Both corrected by disclosure, penalties cancelled
Ottawa Winery Venue — The Property Inside the Opco
The problem: An Ottawa winery venue owned its land and buildings inside the same corporation that ran the events business, and the owners were three or four years from selling. Nobody had looked at what that meant. Real property of that size sitting in the operating company put the asset test for the Lifetime Capital Gains Exemption at genuine risk, and the answer to that question cannot be fixed in the month before a sale: the tests look back over time, so a late reorganization does not help.
What we did: We mapped the asset base against the QSBC tests, modelled holding the real property in a separate corporation, set out the timing and the cost of getting there, and started the runway early enough that the structure would be settled well before a buyer appeared.
The result:
- Asset test risk identified years before the sale
- Property structure modelled with costs and timing
- $1.25M exemption protected with runway to spare
Our clear, efficient process ensures every step is transparent, building trust and long-term client relationships.
Kickoff (Document Request)
Collect prior T2 returns, the booking calendar and signed contracts, the deposit ledger, LCBO and food supplier statements, the AGCO licence, building and build-out costs, payroll records, and bank statements.
First 30 Days (Cleanup & Setup)
Set up QuickBooks Online or Xero against Tripleseat or Event Temple, establish the deposit liability, split the service charge from gratuities, and rebuild the asset schedule across Class 1, 13, 8 and 10.
Monthly Close
Deposit ledger to booking calendar reconciliation, per-wedding costing, bar cost against LCBO purchases, GST34 with deposits and forfeitures handled, and payroll and PD7A reconciliation.
Quarterly Planning Review
Salary and dividend mix, booking pace against last season, furniture and linen replacement timing, the property structure review, and cash flow into the winter trough.
Year-End Close & T2 Filing
Trial balance, financial statements with the deposit liability carried against cash and assets at net book value by class, T2 with GIFI, and CRA preparation.
Get Your Wedding Venue Taxes Done Right Today
Affordable Pricing for Wedding Venues
We believe in clear, upfront pricing so you know exactly what to expect. All fees include HST.
- Tax Preparation (Corporation) — From $400
- Tax Return Filing (Corporation) — From $400
- Tax Compliance Audit — FREE CRA audit support for our clients
- Tax Strategy — FREE for our clients
- Accounting Base Plan — From $100 per month
- Bookkeeping Management — Free for our Accounting clients
- Financial Reporting — Free for our Accounting clients
- Business Formation — Flat $35
- Incorporation Process — Flat $35
- Entity Setup Assistance — Flat $35
- Full-Service Payroll — From $125 per month
Payment is by Interac e-Transfer to info@gondaliyacpa.ca only. Security question: Not Applicable, as auto-deposit is enabled.
Meet Your Lead Wedding Venue Accountant
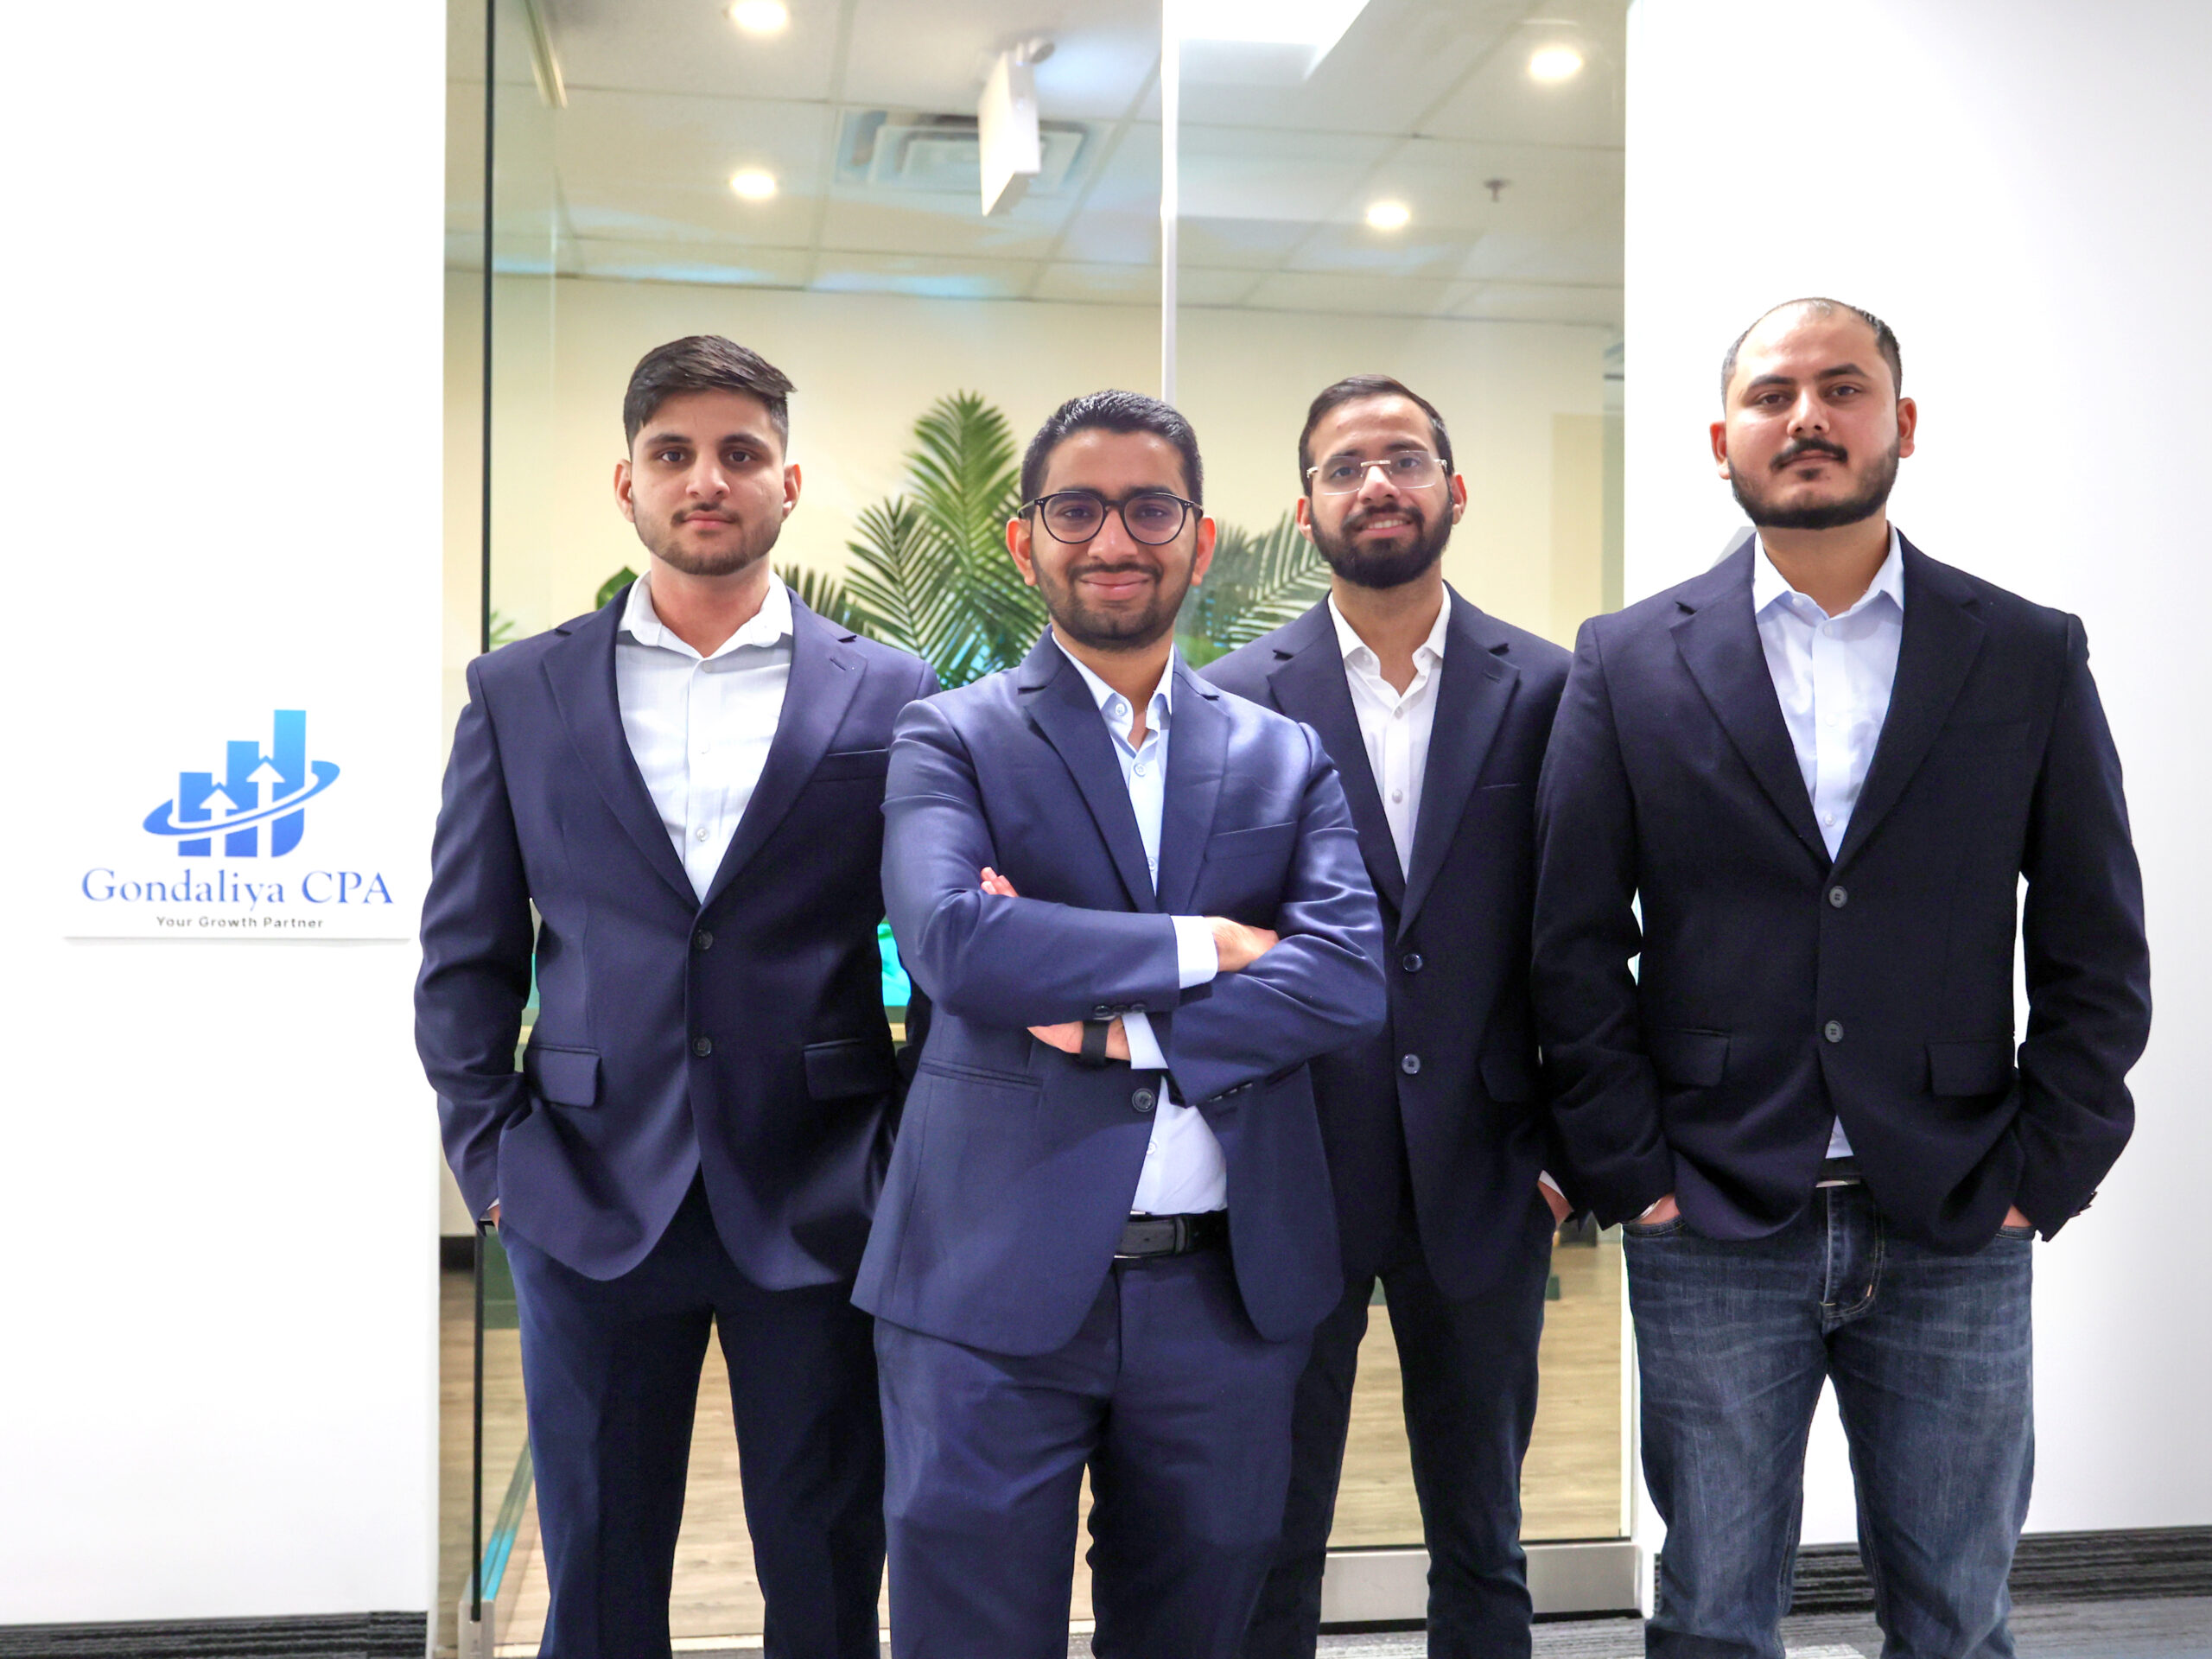
Meet your lead wedding venue accountant. As your events and corporate tax adviser, you deal with the same two people every year.
What Our Clients Say
1300+ five-star reviews from venue, hospitality and events business owners across Ontario and Canada.
Serving Wedding Venues Across Ontario
Our CPA team provides specialized accounting and tax solutions for wedding and event venues throughout Ontario. We understand how deposits, cancellations, bar cost and event payroll actually flow through a venue, what CRA looks at on a deferred-revenue file, and how the property structure decides what you keep on a sale.
Toronto (ON)
55 Queen St E Ste 1205, Toronto, ON M5C 1R6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Mississauga (ON)
2100 Camilla Rd #716, Mississauga, ON L5A 2J8
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Brampton (ON)
4 Starhill Crescent, Brampton, ON L6R 2P9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Scarborough (ON)
24 Clementine Square, Scarborough, ON M1G 2V7, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Vaughan (ON)
19 Cabinet Crescent, Woodbridge, ON L4L 6H9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Oshawa (ON)
210 Durham St, Oshawa, ON L1J 5R3, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Ottawa (ON)
2090 Neepawa Ave a314, Ottawa, ON K2A 3L6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Etobicoke (ON)
60 Stevenson Rd #1601, Etobicoke, ON M9V 2B4, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Hamilton (ON)
70 Starling Dr, Hamilton, ON L9A 0C5, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Guelph (ON)
1155 Gordon St, Guelph, ON N1L 1S8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Windsor (ON)
4387 Guppy Ct, Windsor, ON N9G 2N8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
North York (ON)
150 Graydon Hall Dr #912, North York, ON M3A 3B2, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Wedding Venue Accounting & Tax FAQs
Related Industries We Serve
Accountant for Event Venues
- Deposits and deferred revenue
- Bar and food and beverage margin
- Corporate tax filing and statements
Accountant for Banquet Halls
- AGCO liquor licence and bar cost
- Event staff payroll and WSIB
- Corporate tax planning and bookkeeping
Accountant for Party Rental Businesses
- Rental fleet as capital property
- Damage waivers and delivery charges
- Corporate tax filing and statements
Accountant for Audio Visual Companies
- Show costing and subrentals
- Freelance technician classification
- Corporate tax planning and payroll
Wedding Venue Accounting & Tax Done Right.
T2 filing with booking deposits carried as deferred revenue until the wedding is actually hosted, the tax held until the deposit is applied under ETA subsection 168(9), forfeited deposits accounted for under section 182 rather than kept quietly, the mandatory service charge separated from the voluntary gratuity on both the tax and the payroll side, the building in Class 1 and the build-out in Class 13, and the property structure settled long before you go to market. AFFORDABLE flat fees, no hourly billing. Licensed CPA Ontario. 1300+ five-star reviews. 30-Day Money-Back Guarantee.