



Tax Accountant for Audio Visual Companies in Ontario and Across Canada
We cost every show as a project with gear, crew, subrental, travel and trucking loaded against the invoice, so twelve profitable shows never hide three that lost money. We put media servers, switchers, encoders and computers in Class 50 at 55% instead of leaving them pooled in Class 8, because those are the assets that lose value fastest. We treat subrental as a cost of sale rather than an equipment purchase, test your freelance technicians against the Form RC4110 factors and file the T4A slips, set the rate job by job on out-of-province shows, and calculate recapture when obsolete gear is traded in. Whether you run live event AV, corporate meeting production, integration and installation, or streaming and hybrid production, we handle the gear, the crew and the shows — with AFFORDABLE flat fees.
AFFORDABLE Audio Visual Company Tax Accountant
An AV company sells two completely different things on one invoice, and that is where the accounting goes wrong. The gear is capital: you bought the line arrays, the lighting rig and the LED wall, and they earn every time they leave the warehouse. The crew is labour: the techs, the riggers and the operators cost you the day they work. Both go out on the same show and both come back on the same invoice line, and the result is a company that genuinely cannot say whether it is a rental house that happens to supply people or a crewing agency that happens to own gear. The second problem is depreciation. Media servers, switchers and encoders are obsolete in a handful of years, but they get pooled into Class 8 at 20% with the staging and the truss, so the deduction runs long after the asset stopped being worth anything. At Gondaliya CPA, we specialize in show costing, gear pools and crew classification for AV companies, providing AFFORDABLE flat-fee support that keeps you CRA-compliant and stops you paying more tax than you owe.
As an audio visual accountant, we work with live event AV companies, corporate meeting production firms, AV integration and installation businesses, and streaming and hybrid production companies across Ontario, with year-round support rather than a once-a-year scramble. We tell you what each show earned, what the gear is actually worth, and where your crew exposure sits.
Let us handle the numbers so you can focus on the shows and the calendar.
Our Official Partners
Accounting That Understands How an Audio Visual Company Actually Works
Production comes with financial pressures a rental house never faces. You bill gear and labour together, you front crew and subrental before the client pays, your most expensive assets go obsolete years before their capital cost allowance runs out, and your crew are freelance in a way CRA regularly disagrees with. At Gondaliya CPA, we understand that reality and provide practical, trade-focused solutions across Ontario.
Stay Compliant and Minimize Your Audio Visual Company Tax
For an AV company, staying onside with the ESA, the MTO and CRA and paying the least legal tax are the same job. We keep every filing on schedule while claiming every gear, crew and trucking dollar the T2 allows, so nothing is missed and nothing invites a reassessment.
Accounting & Tax Experts for Audio Visual Companies
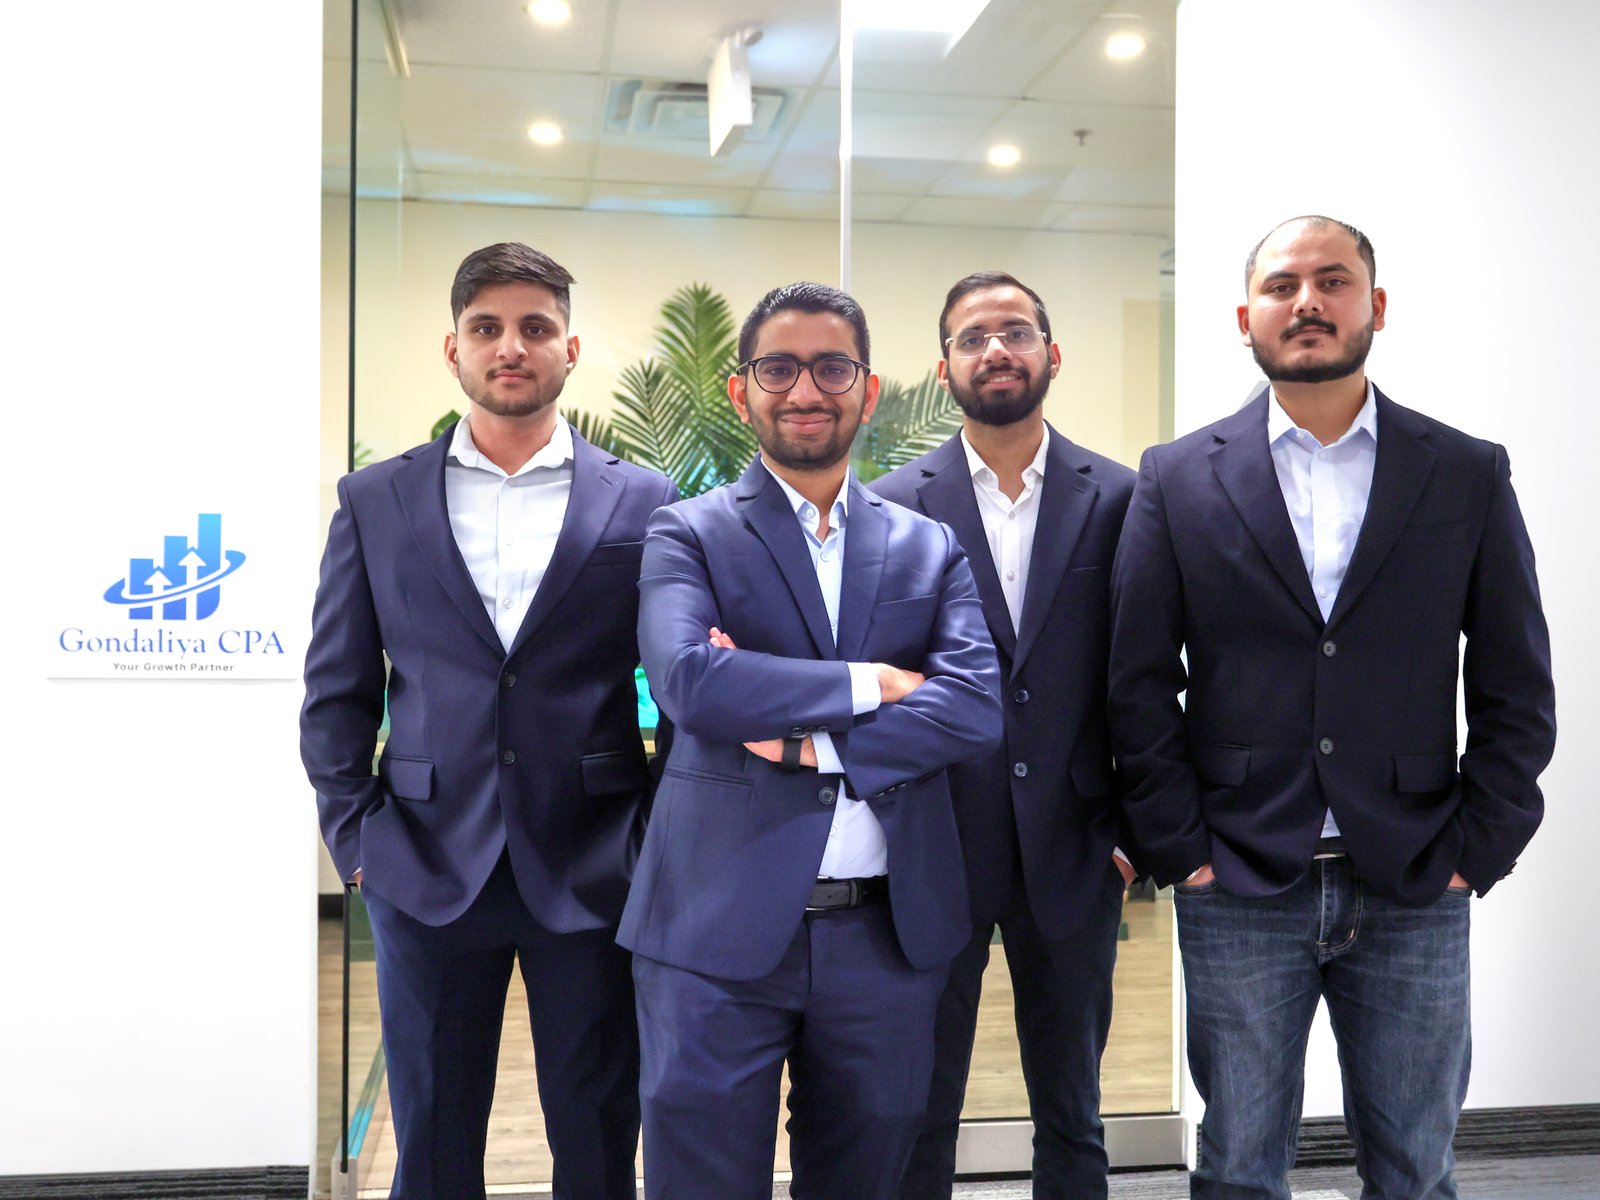
- AFFORDABLE + Fully Registered CPA Firm
- Business and Corporate Tax Expert
- Small & Medium Business Expert
- Accounting, bookkeeping, and tax filing
- Certified CPA
- 1300+ 5-star Google reviews
- 30-Day Money-Back Guarantee
- 60-Day Fees Matching Policy
Why Choose Our Accounting Services for Audio Visual Companies?
Tax Planning — Gear Pools & Obsolescence
We know the trade: Class 50 at 55% on media servers and switchers, Class 8 on staging and lighting, recapture on a trade-in. We protect the $500,000 Small Business Deduction.
Consulting — Show Costing & Margin
Our bookkeeping costs each show as a project, splits the labour margin from the gear margin, and tracks subrental against revenue so you know when to buy what you keep renting.
CRA Representation — Crew & Disposal Audit
When CRA challenges the subcontractor line or a gear disposal, we prepare the response and pursue relief on Form RC4288 where a prior error caused the penalties.
Bookkeeping — Cash Flow & Sale
We build the cash flow that funds crew and subrental before the client pays, produce the statements your equipment lender reads, and model the exit years ahead.
Google Reviews
Audio Visual Clients
Audio Visual Company Tax and Accounting Services in Ontario
Corporate Tax Filing (T2) for Audio Visual Companies
Professional T2 preparation with media servers in Class 50, staging and lighting in Class 8, subrental as cost of sale, and CRA compliance on every line.
Bookkeeping & Accounting for Audio Visual Companies
Show-by-show project costing with the labour and gear margin split out, work in progress carried properly, and financial statements from clean records.
Payroll Services for Audio Visual Companies
Technician payroll with WSIB coverage, PD7A remittances, T4s and T4A slips filed on time, and freelance classification tested against Form RC4110.
GST/HST Filing for Audio Visual Companies
AFFORDABLE HST filing with the rate set job by job on out-of-province shows, deposits handled correctly, and every input tax credit recovered.
Tax Planning for Audio Visual Companies
Smart tax planning on gear purchase timing across Class 50 and Class 8, the Small Business Deduction, and the exit structure years ahead.
Corporate Catch-Up Filing for Audio Visual Companies
File overdue T2 and HST years, rebuild the missing gear pools and show records, and get back into CRA compliance with accurate catch-up support.
CRA Audit Resolution for Audio Visual Companies
Expert support for contractor classification, gear disposal and place of supply audits, handled with confidence from the first letter.
CPA Financial Statements (Notice to Reader) for Audio Visual Companies
CPA-compiled financial statements that equipment lenders accept, carrying the gear at net book value split by class.
Incorporation Services for Audio Visual Companies
Full incorporation including NUANS, articles, share structure, and the section 85 rollover of your gear, trucks and client list into the company.
Catch-Up Bookkeeping Services for Audio Visual Companies
Months or years of show invoices, subrental, crew payments and gear purchases reconstructed and reconciled, so your asset schedule is finally accurate.
US Corporation & LLC Tax Filing for Audio Visual Companies
Cross-border filing on US client work and where owners or shareholders are non-resident or American, covering withholding and T1135 reporting.
Voluntary Disclosure Program for Audio Visual Companies
Come forward on unfiled T4A slips, unreported recapture or HST charged at the wrong rate before CRA calls, cancelling penalties through a Voluntary Disclosures Program application.
Accounting & Tax Services Tailored for Audio Visual Companies
Real, practitioner-level CPA expertise for live event AV companies, corporate meeting production firms, AV integration and installation businesses, and streaming and hybrid production companies across Ontario — built for a business that sells gear and labour on one invoice.
- We prepare your T2 with GIFI on Schedule 100 and Schedule 125, separating show and project fees, equipment rental revenue, technician labour billing and integration work onto their correct lines so CRA’s matching reads your file properly.
- We split media servers, switchers, encoders and computers into Class 50 at 55% rather than leaving them pooled in Class 8, because those are exactly the assets that lose their value fastest.
- We claim capital cost allowance on Schedule 8 with staging, rigging, lighting fixtures, consoles, line arrays and LED wall panels in Class 8 at 20%, trucks and trailers in Class 10 at 30%, and software in Class 12.
- We treat subrental from another AV company as a cost of sale rather than an equipment purchase, because gear you never owned does not belong on your asset schedule inflating a fleet you cannot point at.
- When obsolete gear is sold or traded in, we calculate the recapture where proceeds exceed undepreciated capital cost, and claim the terminal loss where a class is emptied for less than its balance.
- We cost every show as a project in Flex Rental Solutions or Current RMS, loading gear, crew, subrental, travel and trucking against the invoice, so twelve profitable shows do not hide three losing ones.
- We split the labour margin from the gear margin on every job, because an AV company that bills both on one line genuinely cannot tell whether it is a rental house or a crewing agency.
- We track subrental as a percentage of each show’s revenue, which is the number that tells you when buying the gear you keep cross-renting has finally become cheaper than renting it in.
- We carry work in progress across shows that span a year-end, because a job loaded in December and invoiced in January belongs in the right period rather than wherever the invoice happened to land.
- We capture supplier, subrental, travel and repair invoices through Dext and reconcile monthly, keeping the six years of records ITA section 230 requires and making sure no input tax credit is lost.
- We test whether your freelance technicians are employees or contractors against the Form RC4110 factors, because a large subcontractor line with no analysis behind it is the first thing a payroll auditor pulls.
- We file T4A slips on the freelance technicians who are genuinely contractors, so the payments you deducted are reported the way CRA expects rather than sitting in an unsupported subcontractor total.
- We set up staff payroll in Wagepoint, withholding income tax, CPP and EI and remitting on the PD7A by the 15th of the following month, because CRA’s late-remittance penalty on source deductions reaches 10%.
- We register your WSIB coverage before the first technician is hired, because rigging, working at heights and truck loading are exactly the activities an unregistered employer cannot afford an injury on.
- We file your T4 slips and T4 Summary by the last day of February, reconcile them to the PD7A remittances made, and monitor Ontario payroll against the $1,000,000 Employer Health Tax exemption.
- Gear and labour on the same invoice are both taxable at 13% in Ontario, so the tax is simple, but we still split them because the costing is where an AV company actually makes or loses its money.
- On an out-of-province show, the place of supply rules decide which rate applies and they generally follow the client’s address rather than where the show happened, so we set the rate job by job.
- Where the client is a genuine non-resident, we review the export rules against what was actually supplied rather than assuming a foreign address means zero-rating, because a show performed in Canada is a different question.
- A deposit is not consideration until you apply it, so under ETA subsection 168(9) the tax on a booking deposit is collected when it lands against the invoice rather than when the client reserves the date.
- We claim the input tax credits on gear purchases, subrental, trucking, warehouse rent and repairs, which on a company replacing media servers every few years is a substantial recovery every filing period.
- We time gear purchases against your fiscal year-end, weighing the 55% Class 50 rate on media servers and switchers against the 20% Class 8 rate on staging and lighting, so the deduction lands where it is worth most.
- We set the salary-versus-dividend mix for the owners, paying enough T4 salary to build RRSP room while the balance flows as dividends, so combined tax stays near the 12.2% Ontario small-business rate instead of 53.53%.
- We keep your active income under the $500,000 Small Business Deduction limit using ITA section 125, and watch the associated-corporation rules where the owner also holds the warehouse in a second company.
- Where you build novel control, streaming or automation systems, we assess the technological-uncertainty test honestly before claiming anything, because a weak research claim costs more in review time than it ever returns.
- We plan at least two years ahead so your shares qualify for the $1.25M Lifetime Capital Gains Exemption under ITA 110.6, purifying the balance sheet of assets that would otherwise fail the asset test.
- We reconstruct show fees, rental revenue, labour billing and integration work from bank deposits, the rental system and issued invoices across your unfiled years, rebuilding the six years of records ITA section 230 requires.
- Late filing costs 5% of the balance owing plus 1% per month up to twelve months, so we file your oldest unfiled T2 first to stop the penalty compounding and limit the arrears interest CRA charges.
- We rebuild the capital cost pools across the missing years and move media servers, switchers and computers out of Class 8 into Class 50, recovering deduction that was understated in every year it ran.
- We separate subrental cost from gear purchases across the backlog, because a catch-up filing that capitalized every cross-rental invoice shows an asset base that does not exist and a margin nobody can test.
- We file a Voluntary Disclosures Program application on Form RC199 before CRA contacts you, because a disclosure accepted under the general program cancels penalties in full and gives roughly 50% interest relief on the older years.
- When CRA challenges the subcontractor line, we produce the contracts, the invoices and the Form RC4110 analysis for each freelance technician, because that line is where an AV company’s audit almost always begins.
- When CRA tests a gear disposal, we show the recapture calculation against undepreciated capital cost, because obsolete equipment sold or traded in is a disposal whether or not anybody recorded it as one.
- We answer place of supply queries on out-of-province shows with the invoices and client addresses behind each rate applied, rather than leaving a reviewer to assume every job should have carried Ontario tax.
- When CRA opens a full audit, we manage the file and answer the revenue, asset and payroll queries inside the deadlines, so a one-year review does not expand across the three prior years CRA can reopen.
- We file the Notice of Objection within 90 days of a reassessment and pursue taxpayer relief on Form RC4288, cancelling penalties and interest that can top $15,000 where a prior accountant’s error caused them, protecting your Tax Court rights.
- We prepare the CSRS 4200 compilation engagement financial statements a lender requires across two fiscal years for equipment finance on a gear package and for the operating line that funds a large show.
- Your compiled statement of financial position carries the gear at net book value by class, separating the Class 50 assets that depreciate fast from the Class 8 staging and lighting that holds its value.
- We present receivables against production company payment terms, because an AV company that fronts crew and subrental on a large show waits a long time for the money and the lender needs to see that.
- We build the statement of operations with show fees, rental revenue and labour billing classified consistently across two years and tied to the T2 filed with CRA, so the bank accepts the file without questions.
- We deliver the compiled statements within 30 days of receiving your records and the year’s T2 figures, because an equipment finance approval ahead of a booked season does not wait for a slow accountant.
- We incorporate your AV company under the Ontario Business Corporations Act, giving you limited liability on rigging and temporary power work and roughly the 12.2% Ontario small-business rate against 53.53% personally.
- We complete the section 85 rollover on Form T2057, transferring your existing gear, trucks, client list and goodwill into the corporation at elected amounts, deferring the capital gain a straight sale would trigger.
- We set the opening Class 8, Class 50, Class 10 and Class 13 schedules from the rollover so the corporation starts with an asset base that is correct rather than rebuilt from memory years later.
- We open the corporation’s CRA Business Number, HST and payroll accounts within the first 30 days and confirm insurance certificates, CVOR registration and venue vendor approvals move to the new entity.
- We set the chart of accounts with project costing, subrental as cost of sale and the labour and gear margin split built in from the first show, so the records accumulate correctly from day one.
- We rebuild months or years of neglected books from bank deposits, the rental system, subrental invoices and crew records, so a company that ran three seasons without bookkeeping gets a clean ledger.
- We rebuild the gear schedule item by item from purchase invoices and split it across Class 8, Class 50, Class 12 and Class 10, which is almost always wrong when we inherit an AV file.
- We recover the input tax credits buried in unentered gear purchases, subrental, trucking and repair invoices, because a company buying capital assets can hide five figures of credits over a couple of years.
- We reconstruct show costing across the backlog so the caught-up statements show gross margin per project, rather than one blended number that tells the owner nothing about which work to chase.
- We reconcile payroll and subcontractor payments to the PD7A and T4A filings across the caught-up months, so an accurate T2 can be filed without guessing at what the crew were actually paid.
- On a show performed for a US client, we review the export and place of supply rules against what was actually supplied and where, rather than treating a foreign billing address as an automatic zero-rating.
- Where a non-resident owns shares in your company, we handle the Part XIII withholding on dividends paid out of Canada and the NR4 reporting that follows, so nothing is missed at 25% or the treaty rate.
- We file Form T1135 where the owners’ foreign property passes the $100,000 threshold, avoiding a penalty regime CRA applies whether or not any tax was actually owing on the holding itself.
- Where a US citizen is a shareholder or an owner of the company, we coordinate the Canadian and US returns, because their reporting obligations reach into a Canadian corporation in ways most families discover too late.
- We reconcile the Canadian and US returns so foreign tax credits actually land, ensuring tax paid on the same income in one country offsets tax in the other rather than being written off as a cost.
- We bring your company forward on freelance technicians paid for years with no T4A slips filed, because the per-slip penalties and the classification exposure both sit behind that one subcontractor line.
- We disclose recapture never reported on obsolete gear sold or traded in, because a disposal nobody recorded does not disappear and the penalty on catching it late is the part a disclosure removes.
- We file your VDP submission on Form RC199 with a full reconstruction from the rental system, show invoices and bank records, so a company that outgrew its bookkeeping is not left facing an arbitrary assessment.
- We correct HST charged at the wrong rate on out-of-province shows across several years, which is a quiet and cumulative error on a company that tours and one CRA finds on the first review.
- We confirm your disclosure is genuinely voluntary before CRA contacts you — the single condition that makes it valid — and secure the roughly 50% interest relief on the older years, turning a prosecution risk into a managed correction.
Audio Visual Company Gear & Tax Check
Six quick questions on your show costing, your gear pools, your crew classification, your subrental treatment, your out-of-province rates and whether it is time to incorporate. No fee shown.
1. Do you cost each show as a project with crew and subrental loaded against it?
2. Are media servers and computers in Class 50 rather than pooled in Class 8?
3. Have your freelance technicians been tested against the RC4110 factors?
4. Is subrental recorded as cost of sale rather than an equipment purchase?
5. Is the HST rate set job by job on out-of-province shows?
6. Is your audio visual company incorporated?
Free CPA Consultation for Audio Visual Companies
Case Studies: Audio Visual Accounting & Tax
Toronto Live Event AV — The Servers in the Wrong Pool
The problem: A Toronto live event company had bought media servers, switchers, encoders and a rack of production computers over five years, and every one of them had gone into Class 8 at 20% alongside the truss and the staging. Those assets were effectively worthless after four seasons, replaced or retired, while the deduction was still crawling along at a rate meant for steel. The company was paying tax on income that its fastest-depreciating assets should have been sheltering.
What we did: We rebuilt the asset schedule from purchase invoices, moved the qualifying servers, switchers and computers into Class 50 at 55%, restated the capital cost allowance across the open years, and set an intake rule so new gear is classified correctly the day it arrives.
The result:
- Five years of computer gear reclassified to Class 50
- Deduction rate on those assets raised from 20% to 55%
- New purchases now classified at intake
Mississauga Corporate Production — The Subcontractor Line
The problem: A Mississauga corporate meeting production firm ran almost entirely on freelance technicians. The same twelve people worked most of its shows, used the company’s gear and trucks, were scheduled by the company’s producer, and invoiced as contractors. No Form RC4110 analysis had ever been done and no T4A slips had ever been filed. The subcontractor line was the largest expense on the return, with nothing at all behind it, which is precisely the profile a payroll audit is built to find.
What we did: We ran the classification analysis technician by technician against the control, tools, subcontracting and risk factors, moved the ones who were plainly employees onto payroll with WSIB, filed T4A slips for the genuine contractors, and brought the historical slips forward voluntarily.
The result:
- Every technician classified on documented factors
- Historical T4A slips filed through a disclosure
- Payroll and WSIB in place before an audit, not after
Ottawa AV Company — Three Shows Nobody Priced
The problem: An Ottawa AV company billed gear and labour on one invoice line and had never costed a show. Revenue was growing every year and the bank balance was not. The owner assumed the large conference work was carrying the company. Once we loaded crew, subrental, travel, per diems and trucking against each job, three large shows a year turned out to be losing money outright, and they were the three the owner was proudest of, because the crew count and the subrental bill scaled faster than the fee ever did.
What we did: We built project costing in the rental system, split labour margin from gear margin, tracked subrental as a share of each show’s revenue, and gave the owner a per-show gross margin report before quoting the next season.
The result:
- Three loss-making shows identified and repriced
- Labour and gear margin visible per project
- Subrental tracked against a buy-versus-rent decision
Our clear, efficient process ensures every step is transparent, building trust and long-term client relationships.
Kickoff (Document Request)
Collect prior T2 returns, gear purchase invoices, the rental system export, show invoices and quotes, subrental and crew records, truck and CVOR documents, warehouse lease, payroll records, and bank statements.
First 30 Days (Cleanup & Setup)
Set up QuickBooks Online or Xero against Flex Rental Solutions or Current RMS, rebuild the Class 8, 50, 12, 10 and 13 schedules, and run the RC4110 analysis on every freelance technician.
Monthly Close
Project costing by show, labour and gear margin split, subrental as a share of revenue, GST34 with the rate set job by job, and payroll, PD7A and subcontractor reconciliation.
Quarterly Planning Review
Salary and dividend mix, gear purchase timing across Class 50 and Class 8, buy-versus-subrent decisions, replacement cycle on fast-obsolescing assets, and cash flow against production company terms.
Year-End Close & T2 Filing
Trial balance, financial statements with the gear at net book value split by class and work in progress carried, recapture and terminal loss settled, T2 with GIFI, and CRA preparation.
Get Your Audio Visual Company Taxes Done Right Today
Affordable Pricing for Audio Visual Companies
We believe in clear, upfront pricing so you know exactly what to expect. All fees include HST.
- Tax Preparation (Corporation) — From $400
- Tax Return Filing (Corporation) — From $400
- Tax Compliance Audit — FREE CRA audit support for our clients
- Tax Strategy — FREE for our clients
- Accounting Base Plan — From $100 per month
- Bookkeeping Management — Free for our Accounting clients
- Financial Reporting — Free for our Accounting clients
- Business Formation — Flat $35
- Incorporation Process — Flat $35
- Entity Setup Assistance — Flat $35
- Full-Service Payroll — From $125 per month
Payment is by Interac e-Transfer to info@gondaliyacpa.ca only. Security question: Not Applicable, as auto-deposit is enabled.
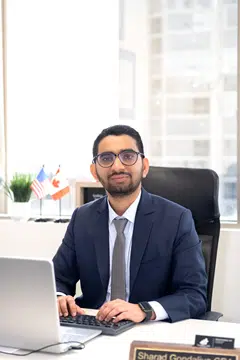
Meet Your Lead Audio Visual Accountant
Meet your lead audio visual accountant. As your production and corporate tax adviser, you deal with the same two people every year.
What Our Clients Say
1300+ five-star reviews from production, events and equipment business owners across Ontario and Canada.
Serving Audio Visual Companies Across Ontario
Our CPA team provides specialized accounting and tax solutions for audio visual and event production companies throughout Ontario. We understand how a show is costed, why media servers do not belong in the same pool as truss, where the crew classification exposure sits, and what CRA looks at first when it opens a production file.
Toronto (ON)
55 Queen St E Ste 1205, Toronto, ON M5C 1R6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Mississauga (ON)
2100 Camilla Rd #716, Mississauga, ON L5A 2J8
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Brampton (ON)
4 Starhill Crescent, Brampton, ON L6R 2P9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Scarborough (ON)
24 Clementine Square, Scarborough, ON M1G 2V7, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Vaughan (ON)
19 Cabinet Crescent, Woodbridge, ON L4L 6H9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Oshawa (ON)
210 Durham St, Oshawa, ON L1J 5R3, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Ottawa (ON)
2090 Neepawa Ave a314, Ottawa, ON K2A 3L6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Etobicoke (ON)
60 Stevenson Rd #1601, Etobicoke, ON M9V 2B4, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Hamilton (ON)
70 Starling Dr, Hamilton, ON L9A 0C5, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Guelph (ON)
1155 Gordon St, Guelph, ON N1L 1S8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Windsor (ON)
4387 Guppy Ct, Windsor, ON N9G 2N8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
North York (ON)
150 Graydon Hall Dr #912, North York, ON M3A 3B2, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Audio Visual Accounting & Tax FAQs
Related Industries We Serve
Accountant for Film Production Companies
- Project costing and work in progress
- Crew classification and T4A slips
- Corporate tax filing and statements
Accountant for Recording Studios
- Studio gear capital cost allowance
- Session musicians and engineers
- Corporate tax planning and bookkeeping
Accountant for Party Rental Businesses
- Rental fleet as capital property
- Recapture on a category sale
- Corporate tax filing and statements
Accountant for Wedding Venues
- Deposits and deferred revenue
- In-house AV and bar margin
- Corporate tax planning and payroll
Audio Visual Accounting & Tax Done Right.
T2 filing with media servers, switchers and computers in Class 50 at 55% instead of pooled in Class 8, staging and lighting in Class 8 at 20%, subrental treated as cost of sale rather than an equipment purchase, every show costed as a project with crew and subrental loaded against it, freelance technicians tested against the Form RC4110 factors with T4A slips filed, and the HST rate set job by job on out-of-province work. AFFORDABLE flat fees, no hourly billing. Licensed CPA Ontario. 1300+ five-star reviews. 30-Day Money-Back Guarantee.