



Tax Accountant for Campgrounds in Ontario and Across Canada
We treat a short-term stay of under one month as a taxable supply and charge 13% on it, determine and document the treatment where a stay runs longer than that instead of assuming an answer, record the accommodation tax your municipality levies as money held in trust rather than sales, release the seasonal fees banked in March across the camping season they buy, apply tax on a deposit when the deposit lands against the invoice, and split your water, septic, road and washroom spending between capital and repair before the return is filed. Whether you run a tent and trailer campground, a waterfront property with cabins and yurts, a group and youth camping ground or a rural family campground, we handle the season, the sites and the infrastructure — with AFFORDABLE flat fees.
AFFORDABLE Campground Tax Accountant
A campground earns its year in about fifteen weeks and pays for it in fifty-two. The gate money arrives between the May long weekend and Thanksgiving; the property tax, the septic contract, the water system, the road gravel, the loan principal and the insurance arrive regardless of whether anybody is on site. That compression is the whole business, and it decides every question an owner actually has: whether the washroom rebuild pays for itself, what a site earns once services and staffing are loaded against it, and whether the seasonal cheques banked in March are profit or a liability owed across the entire summer. Two tax points shape the books more than anything else. A short-term stay of under one month is a taxable supply for GST/HST, charged at 13% in Ontario, while a stay that runs longer than a month is not automatically the same answer and has to be determined on the facts of that arrangement rather than assumed. And where a municipality levies an accommodation tax, the money is collected in trust and remitted, never earned. At Gondaliya CPA, we specialize in seasonal revenue recognition, short-term accommodation tax and infrastructure capital cost allowance for campgrounds, providing AFFORDABLE flat-fee support that keeps you CRA-compliant and stops you paying more tax than you owe.
As a campground accountant, we work with tent and trailer campgrounds, waterfront properties with cabins and yurts, group and youth camping grounds and rural family campgrounds across Ontario, with year-round support rather than a once-a-year scramble. We tell you what the season actually earned, what your infrastructure is worth on the books, and where your accommodation tax and payroll exposure sits.
Let us handle the numbers so you can focus on the season and the property.
Our Official Partners
Accounting That Understands How a Campground Actually Works
A campground carries financial pressures a year-round business never faces. You take most of your money in a fifteen-week window and pay bills for fifty-two, you bank seasonal fees months before you deliver the camping they buy, you collect a tax that was never yours to earn, and the largest cheques you write go into wells, beds, poles and gravel that CRA reads as capital. Gondaliya CPA builds the accounting around that calendar rather than against it, for campground owners right across Ontario.
Stay Compliant and Minimize Your Campground Tax
A campground that files everything on time and a campground that pays the least legal tax are, in practice, the same campground. Every income tax, HST and accommodation tax deadline is calendared and met, and every site, infrastructure and payroll dollar the return permits is claimed, so nothing slips and nothing draws a second look.
Accounting & Tax Experts for Campgrounds
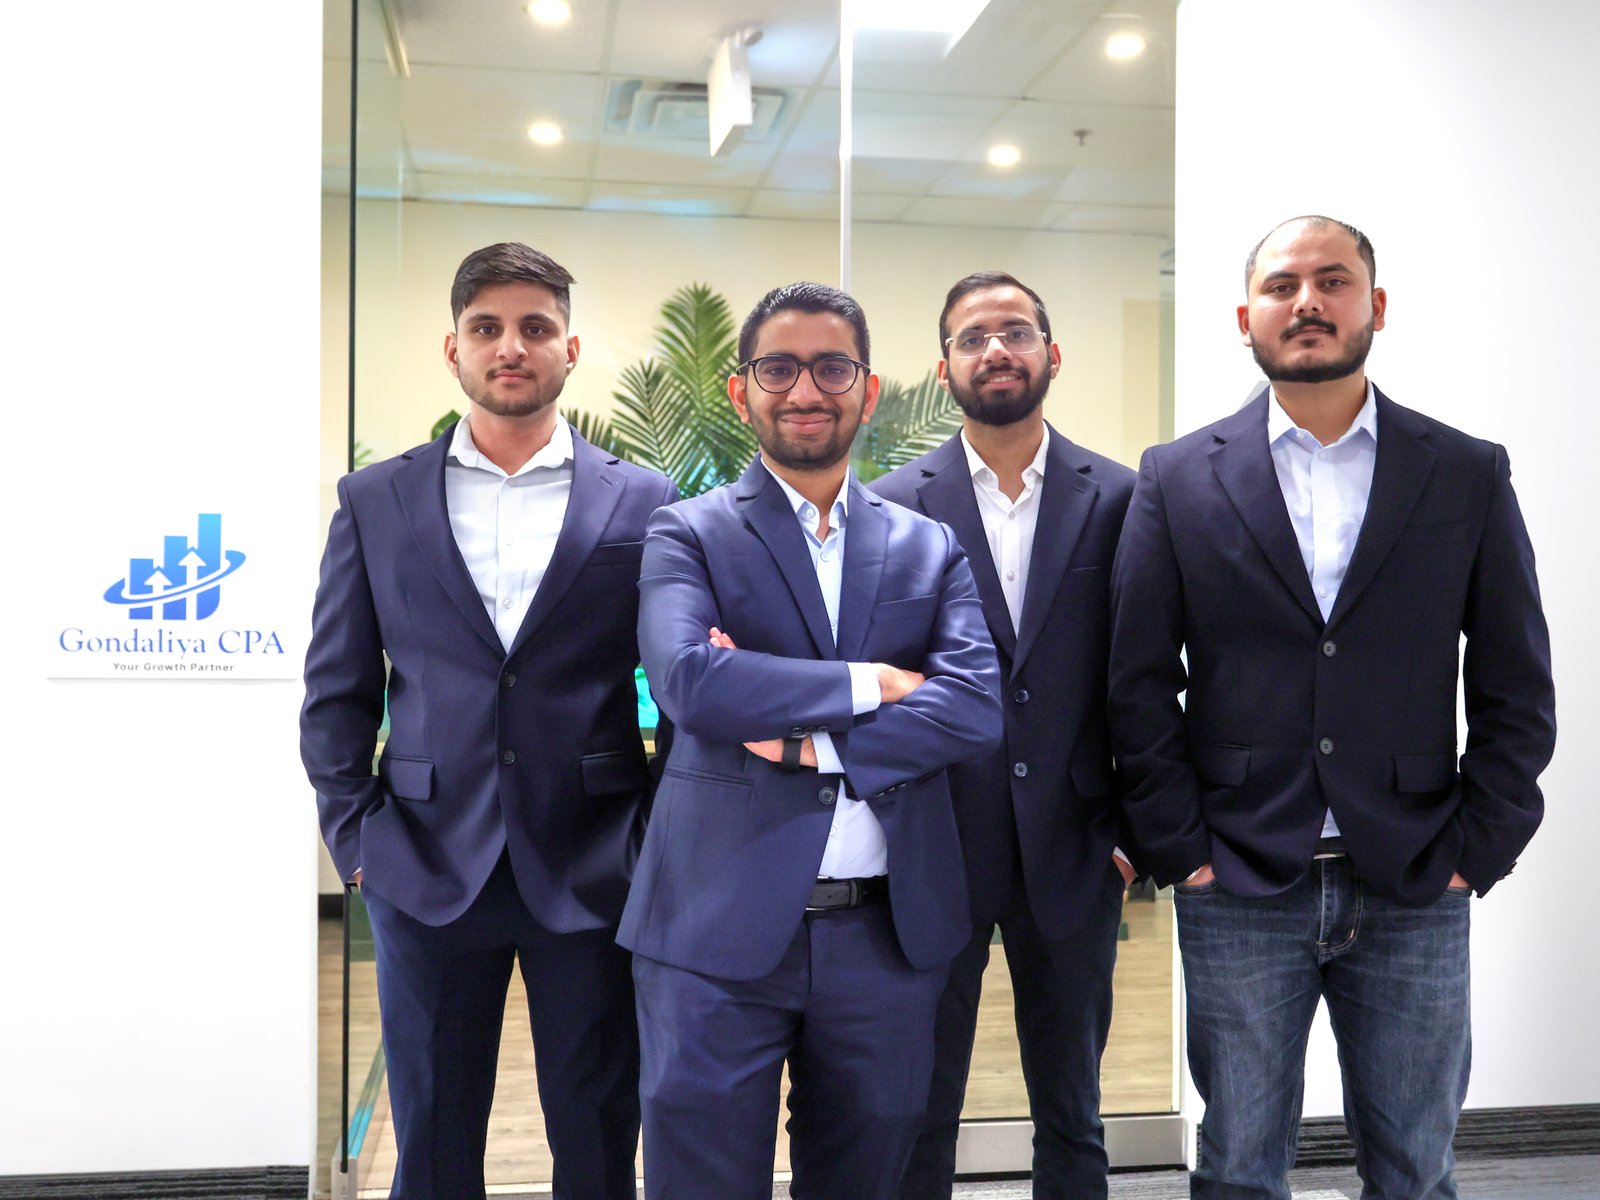
- AFFORDABLE + Fully Registered CPA Firm
- Business and Corporate Tax Expert
- Small & Medium Business Expert
- Accounting, bookkeeping, and tax filing
- Certified CPA
- 1300+ 5-star Google reviews
- 30-Day Money-Back Guarantee
- 60-Day Fees Matching Policy
Why Choose Our Accounting Services for Campgrounds?
Tax Planning — Infrastructure & Capital Cost Allowance
We know the property: Class 1 buildings, Class 8 at 20% on equipment and furnishings, Class 17 on roads and surfaces, and capital kept apart from repair. We protect the $500,000 Small Business Deduction.
Consulting — Season Costing & Revenue Mix
Our bookkeeping separates site, cabin, group and store revenue, releases seasonal fees across the season they buy, and shows what the year really earned once off-season costs are loaded against it.
CRA Representation — Accommodation & Capital Audit
When CRA questions your short-term accommodation position or a capital-versus-repair call on the water and septic systems, we prepare the response and pursue relief on Form RC4288 where a prior error caused the penalties.
Bookkeeping — Off-Season Cash Flow & Sale
We build the cash plan that carries a fifteen-week business through fifty-two weeks of bills, produce the statements your lender reads, and model the sale of the property years ahead.
Google Reviews
Campground Clients
Campground Tax and Accounting Services in Ontario
Corporate Tax Filing (T2) for Campgrounds
Professional T2 preparation with buildings in Class 1, roads and surfaces in Class 17, seasonal fees carried as deferred revenue, and CRA compliance on every line.
Bookkeeping & Accounting for Campgrounds
Site, cabin, group and store revenue tracked separately, the accommodation tax held as a trust liability, and financial statements built from reconciled records.
Payroll Services for Campgrounds
Seasonal crew payroll with WSIB from the first hire, PD7A remittances, T4 and T4A slips filed on time, and records of employment issued at season end.
GST/HST Filing for Campgrounds
AFFORDABLE HST filing with short-term sites taxed at 13%, longer arrangements determined on their facts and documented, and every input tax credit recovered.
Tax Planning for Campgrounds
Smart planning on infrastructure timing across Class 1, Class 8 and Class 17, the Small Business Deduction, and the sale of the property years ahead.
Corporate Catch-Up Filing for Campgrounds
Overdue T2 and HST years filed in order, the capital pools and season records rebuilt from source documents, and your CRA standing restored.
CRA Audit Resolution for Campgrounds
Expert support on short-term accommodation, capital-versus-repair and seasonal payroll audits, handled with confidence from the very first CRA letter.
CPA Financial Statements (Notice to Reader) for Campgrounds
CPA-compiled financial statements your lender accepts, carrying land, buildings, surfaces and equipment separately at net book value.
Incorporation Services for Campgrounds
NUANS search, articles, share structure and CRA account setup, plus the section 85 rollover that moves the property in at elected amounts.
Catch-Up Bookkeeping Services for Campgrounds
Seasons of gate sheets, reservation exports, supplier invoices and payroll reconstructed and reconciled, so your asset schedule is finally accurate.
US Corporation & LLC Tax Filing for Campgrounds
Filing for campground families with an American in the ownership, non-resident shareholders, Part XIII withholding, NR4 slips or foreign property to report.
Voluntary Disclosure Program for Campgrounds
Come forward on unremitted accommodation tax, HST never billed or summer crew paid in cash before CRA calls, cancelling penalties through a Voluntary Disclosures Program application.
Accounting & Tax Services Tailored for Campgrounds
Real, practitioner-level CPA expertise for tent and trailer campgrounds, waterfront properties with cabins and yurts, group and youth camping grounds and rural family campgrounds across Ontario — built for a business that earns in fifteen weeks and pays for it across fifty-two.
- We prepare your T2 with GIFI on Schedule 100 and Schedule 125, keeping site fees, cabin and yurt bookings, store and firewood sales and group-area rentals on their own lines so CRA reads your campground the way it actually earns.
- We claim capital cost allowance on Schedule 8 with the washroom block, store and office buildings in Class 1, site furnishings, mowers and maintenance equipment in Class 8 at 20%, and your internal roads and hard surfaces in Class 17.
- We carry the seasonal fees banked in March as deferred revenue on the balance sheet and release them across the months of camping they buy, so the T2 reports the season you delivered rather than the day the cheque cleared.
- We split your water, septic and electrical spending between capital and repair before filing, because a $60,000 well and distribution replacement is capital while the season chlorination, testing and pump servicing is deductible in the year you pay it.
- A mower, a service vehicle or a block of site furnishings that leaves the property is a disposal, so we settle the recapture against undepreciated capital cost and take the terminal loss where a class empties below its balance.
- We build your chart of accounts so nightly site fees, seasonal fees, cabin and yurt bookings, group-area rentals, store and firewood sales and the accommodation tax each sit on their own line rather than in one blended camping total.
- We post the accommodation tax you collect to a liability account rather than to sales, so the roughly 4% held for the municipality never inflates the revenue you are taxed on and never disappears before the remittance is due.
- We reconcile your reservation system to the bank every month, matching Campspot, CampLife or Firefly bookings against deposits, so a $3,000 gap between what the gate recorded and what landed is found in July rather than the following March.
- We hold the seasonal fees collected in spring in deferred revenue and release them month by month across the camping season, because a $180,000 spring intake is a liability you owe in campsites, not profit earned in April.
- Fuel, propane, chlorine, gravel and repair invoices go into Dext as they arrive and get reconciled every month, which keeps the six years of records ITA section 230 asks for and stops credits vanishing into an off-season shoebox.
- We test whether your gate staff, groundskeepers and washroom cleaners are employees or contractors on the real facts of control, tools and financial risk, because a large casual-labour line with nothing behind it is what a payroll auditor opens first.
- We run seasonal payroll in Wagepoint, withholding income tax, CPP and EI and remitting on the PD7A by the 15th of the following month, because the graduated late-remittance penalty reaches 10%, which at the top of that scale is $900 on a $9,000 remittance.
- We issue records of employment when the season ends and your summer crew leave, because most of them will file for benefits that autumn and a missing record turns into a phone call you do not want in October.
- We register your WSIB coverage before the first hire, because mowing, tree work, pool and beach supervision and washroom cleaning are exactly the activities an unregistered employer cannot afford an injury on.
- February closes the payroll year: the T4 slips and Summary are filed by its last day, proved back against what the campground actually sent CRA on the PD7A, and Ontario wages are checked for the $1,000,000 Employer Health Tax exemption.
- A short-term stay of under one month is a taxable supply, so we register you once taxable revenue passes $30,000 over four consecutive calendar quarters and charge 13% in Ontario on nightly and weekly sites.
- Where a stay runs longer than a month the treatment is not automatically the same, so we read the actual agreement, make the determination on its facts and document it in your file rather than letting a price list decide it.
- Store goods, firewood and propane are ordinary taxable retail at 13% and belong in their own department with their own margin, rather than folded into site revenue where nobody can see what the shop actually earns across a season.
- Taking a deposit is not the same as being paid, so ETA subsection 168(9) puts the tax at the moment you apply that money to the invoice rather than the March afternoon a camper phones to hold a week.
- We recover the input tax credits on your well and septic work, road gravel, mowers, propane, store inventory, electricity and equipment repairs, which on a campground rebuilding a washroom block is often $20,000 or more in one filing year.
- We time washroom, road and electrical upgrades against your fiscal year-end so the capital cost allowance lands in a year it is worth something, rather than in a year the season already left you with nothing to shelter.
- Owner compensation gets planned rather than guessed: we decide each year how much comes out as T4 wage, how much as dividends and how much stays in the company at roughly 12.2% instead of a personal rate that tops out at 53.53%.
- We keep active income inside the $500,000 Small Business Deduction limit under ITA section 125 and watch the associated-corporation rules where the land sits in one company and the camping operation runs in another.
- We build the off-season cash plan, because a business that earns in fifteen weeks still pays property tax, insurance, loan principal and electricity for fifty-two, and the instalments CRA expects do not pause between Thanksgiving and May.
- A campground is usually sold once, so we start the $1.25M Lifetime Capital Gains Exemption work under ITA 110.6 two years before you list, clearing investments and surplus cash off the balance sheet while there is still time.
- We reconstruct site fees, seasonal fees, cabin bookings and store sales from bank deposits, the reservation system and the gate records across your unfiled years, rebuilding the six years of records ITA section 230 requires.
- The penalty on a late T2 starts at 5% of the balance owing and adds 1% for each month it stays unfiled, to a twelve-month ceiling, so the oldest year goes in first and the compounding stops there.
- We rebuild the capital cost allowance pools across the missing years, putting buildings in Class 1, equipment and furnishings in Class 8 at 20% and internal roads and surfaces in Class 17, which on a $750,000 asset base recovers deduction nobody ever claimed.
- We separate the accommodation tax collected from the sales recorded across the backlog, because a catch-up filing that ran it through revenue reports income the campground never had and overstates tax on money owed to the municipality.
- Where the arrears are large, we go in through the Voluntary Disclosures Program on Form RC199 before CRA reaches you, because acceptance cancels the penalties outright and can remove part of the interest on the oldest years.
- When CRA questions the HST on your sites, we produce the registrations, the stay lengths and the agreements behind each supply, because the under-one-month boundary is exactly where a campground review begins.
- Where longer arrangements are in the file, we show the determination that was made, the facts it rested on and the date it was documented, instead of leaving a reviewer to assume the campground simply stopped charging tax.
- When capital and repair is the issue, we set out what was replaced, what was maintained and what was upgraded on the water, septic and electrical systems, with the invoices and the scope behind every line.
- On a full audit we take over the correspondence and answer every revenue, payroll and asset query inside the stated deadline, keeping a one-season look from widening into the three earlier years CRA remains entitled to reopen.
- A reassessment gets a Notice of Objection inside the 90-day window, and where a prior bookkeeper mistake created the penalties and interest we pursue relief on Form RC4288, which on a neglected file can be worth $15,000 on its own.
- We prepare the CSRS 4200 compilation engagement statements a lender asks for across two fiscal years, which is what a campground needs when it refinances the property or borrows to rebuild a washroom block.
- Your compiled balance sheet carries land, buildings, roads and equipment separately at net book value, because a lender underwriting a campground reads the land and the improvements very differently from the mowers.
- The deferred revenue you are holding on seasonal fees shows as the liability it is, so the lender sees that a strong March bank balance is money owed in campsites rather than profit already earned.
- We build the statement of operations with site revenue, cabin and group bookings, store and firewood margin and off-season costs classified the same way across both years and tied to the T2 you filed with CRA.
- Compiled statements land within 30 days of us having your records and the year T2 figures, because a spring financing decision on a $400,000 infrastructure project cannot sit waiting on an accountant.
- We incorporate your campground in Ontario or federally, giving you limited liability across a property the public walks on and roughly the 12.2% Ontario small-business rate on the first $500,000 of active income against up to 53.53% personally.
- We complete the section 85 rollover on Form T2057, moving the land, buildings, roads, equipment and goodwill into the corporation at elected amounts so a straight transfer does not trigger the capital gain.
- We set the opening Class 1, Class 8 and Class 17 schedules from the rollover, so the corporation begins with an asset base that is documented rather than reconstructed from memory five years later.
- We open the corporation CRA Business Number, HST and payroll accounts inside the first 30 days and make sure the municipal accommodation tax account, your insurance and your utility accounts move to the new entity before the season starts.
- We set the chart of accounts with site, cabin, group and store revenue separated, the accommodation tax as a trust liability and seasonal fees in deferred revenue from the first booking, so the records build correctly from day one.
- We rebuild months or years of neglected books from bank deposits, the reservation system, gate sheets and supplier invoices, so a campground that ran three seasons on a cash box and a notebook finally has a ledger.
- We rebuild the asset schedule line by line from purchase invoices and split it across Class 1, Class 8 and Class 17, which is almost always wrong or missing entirely when we inherit a campground file.
- We pull the accommodation tax back out of revenue across the caught-up months and restate it as a liability, so the campground stops paying income tax on roughly 4% that was never its money.
- We recover the input tax credits buried in unentered gravel, lumber, propane, well and septic invoices, which on a campground that spent two years catching up on infrastructure regularly runs past $25,000.
- Summer wages and casual-labour cheques get matched back to the PD7A and to the T4 and T4A filings across every caught-up month, so the T2 rests on what the crew were paid rather than on an estimate.
- Where a US visitor pays for a site in Ontario, the supply happened here and carries Ontario tax, so we do not let a foreign billing address turn a domestic camping stay into a zero-rated one.
- A dividend paid to a shareholder living outside Canada carries Part XIII withholding at 25% unless a treaty lowers it, and we prepare the NR4 slips that have to follow that payment out of the country.
- We file Form T1135 where the owners foreign property passes the $100,000 threshold, which catches more campground families than they expect once a Florida condo or a US account is in the picture.
- An American shareholder or an owner holding US citizenship changes the whole picture, so we line the Canadian and US filings up together rather than letting each be prepared in isolation and discovering the overlap years later.
- We reconcile the two sets of returns so foreign tax credits actually land, and tax paid once on the same income offsets tax in the other country instead of being written off as a cost of doing business.
- We bring a campground forward where the accommodation tax was collected from campers but reported as revenue and never remitted, because money held in trust and then spent is the exposure a disclosure is built to fix.
- We disclose HST that should have been charged on sites, cabins and the store after taxable revenue passed $30,000, calculating the 13% never billed and the years it quietly accumulated across.
- We come forward on summer crew paid in cash for years with no T4 slips, no source deductions and no records of employment, because that exposure grows every season it is left alone.
- We file the submission on Form RC199 with a full reconstruction from the reservation system, gate records and bank statements, so a campground that outgrew its bookkeeping is not handed an arbitrary assessment instead.
- We confirm the disclosure is genuinely voluntary, complete and at least one year past due before it goes in, because those are the conditions that make it valid and turn a prosecution risk into a managed $30,000 correction.
Campground Season & Tax Check
Six quick questions on your HST on sites, the under-one-month boundary, the accommodation tax you hold in trust, your seasonal fees, your capital pools and whether it is time to incorporate. No fee shown.
1. Are you charging 13% HST on stays of under one month?
2. Has the treatment of stays running longer than a month been determined and documented?
3. Is the accommodation tax you collect recorded as a liability rather than revenue?
4. Are seasonal fees carried as deferred revenue and released across the season?
5. Are buildings, surfaces and equipment in separate capital cost allowance classes?
6. Is your campground incorporated?
Free CPA Consultation for Campgrounds
Case Studies: Campground Accounting & Tax
Parry Sound Waterfront Campground — The Spring Cheque Problem
The problem: A waterfront campground near Parry Sound banked its whole spring seasonal intake in March, and the bookkeeper recorded every dollar of it as March income. The internal statements showed a spectacular first quarter and a long loss afterwards, the owners could never say whether a season had actually made money, and because the fiscal year-end fell in August the corporation had twice reported income it had not yet earned and funded instalments a full year ahead of need. Nothing at all was carried as a liability, even though the camping those cheques bought had not been delivered.
What we did: We built a deferred revenue schedule off the seasonal agreements, restated two years so the fees released month by month across the camping they bought, tied the closing deferred balance back to the bookings behind it, and reset the instalment base.
The result:
- Two years restated with seasonal fees in deferred revenue
- Freed $9,600 of instalments funded a full season early
- Closing deferred balance now ties to the bookings behind it
Haliburton Family Campground — Roads, Wells and the Repair Account
The problem: A family campground in the Haliburton Highlands had spent two seasons rebuilding the property: a replacement septic bed on the north loop, a new well pump and distribution line, and roughly nine hundred metres of regraded and regravelled internal road. Every dollar of it had gone into the repairs and maintenance account. The T2 showed an operating loss the bank simply did not believe, the capital pools sat empty, and CRA had opened a query on the largest of the three invoices.
What we did: We went back to the scope written on each invoice, separated genuine maintenance from replacement and upgrade, opened Class 1, Class 8 and Class 17 pools, restated both years, answered the CRA query with the invoices behind every line, and recovered the input tax credits nobody had claimed.
The result:
- Capital and repair separated invoice by invoice across two seasons
- Recovered $14,200 in unclaimed input tax credits
- CRA query closed with no adjustment to the restated years
Tobermory Campground and Cabins — Four Years and Nobody Filing
The problem: A campground with eight cabins outside Tobermory had not filed a T2 in four years. The gate ran on a cash box and a paper day sheet, cabin bookings came through an online system nobody ever exported, summer staff were paid in cash with no slips and no records of employment, and the owners had assumed a business open for only fifteen weeks did not really need to file. HST had never been registered even though site and cabin revenue had passed the threshold three seasons earlier.
What we did: We reconstructed four seasons from bank deposits, the booking export and the day sheets, registered for HST from the correct historical date, rebuilt the payroll year by year with slips and records of employment, and filed everything through a voluntary disclosure before CRA made contact.
The result:
- Four unfiled T2 years reconstructed and filed in order
- HST registered from the correct historical date
- Penalties cancelled through an accepted voluntary disclosure
Our clear, efficient process ensures every step is transparent, building trust and long-term client relationships.
Kickoff (Document Request)
Collect prior T2 returns, the reservation system export, gate and seasonal fee records, HST and accommodation tax filings, supplier and infrastructure invoices, payroll records, the property tax and loan documents, and bank statements.
First 30 Days (Cleanup & Setup)
Set up QuickBooks Online or Xero against Campspot, CampLife or Firefly, separate site, cabin, group and store revenue, open the trust liability for the accommodation tax, and rebuild the Class 1, 8, 17 and 10 schedules.
Monthly Close
Reservation-to-bank reconciliation, the deferred revenue release on seasonal fees, accommodation tax liability tracking, GST34 with short-term sites at 13%, and payroll and PD7A reconciliation.
Quarterly Planning Review
Salary and dividend mix, timing of infrastructure spending against the year-end, capital-versus-repair calls on water, septic and electrical work, and off-season cash flow against twelve months of fixed costs.
Year-End Close & T2 Filing
Trial balance, financial statements with the deferred revenue and the trust liability stated, capital pools settled with recapture and terminal loss, T2 with GIFI, and CRA preparation.
Get Your Campground Taxes Done Right Today
Affordable Pricing for Campgrounds
We believe in clear, upfront pricing so you know exactly what to expect. All fees include HST.
- Tax Preparation (Corporation) — From $400
- Tax Return Filing (Corporation) — From $400
- Tax Compliance Audit — FREE CRA audit support for our clients
- Tax Strategy — FREE for our clients
- Accounting Base Plan — From $100 per month
- Bookkeeping Management — Free for our Accounting clients
- Financial Reporting — Free for our Accounting clients
- Business Formation — Flat $35
- Incorporation Process — Flat $35
- Entity Setup Assistance — Flat $35
- Full-Service Payroll — From $125 per month
Payment is by Interac e-Transfer to info@gondaliyacpa.ca only. Security question: Not Applicable, as auto-deposit is enabled.
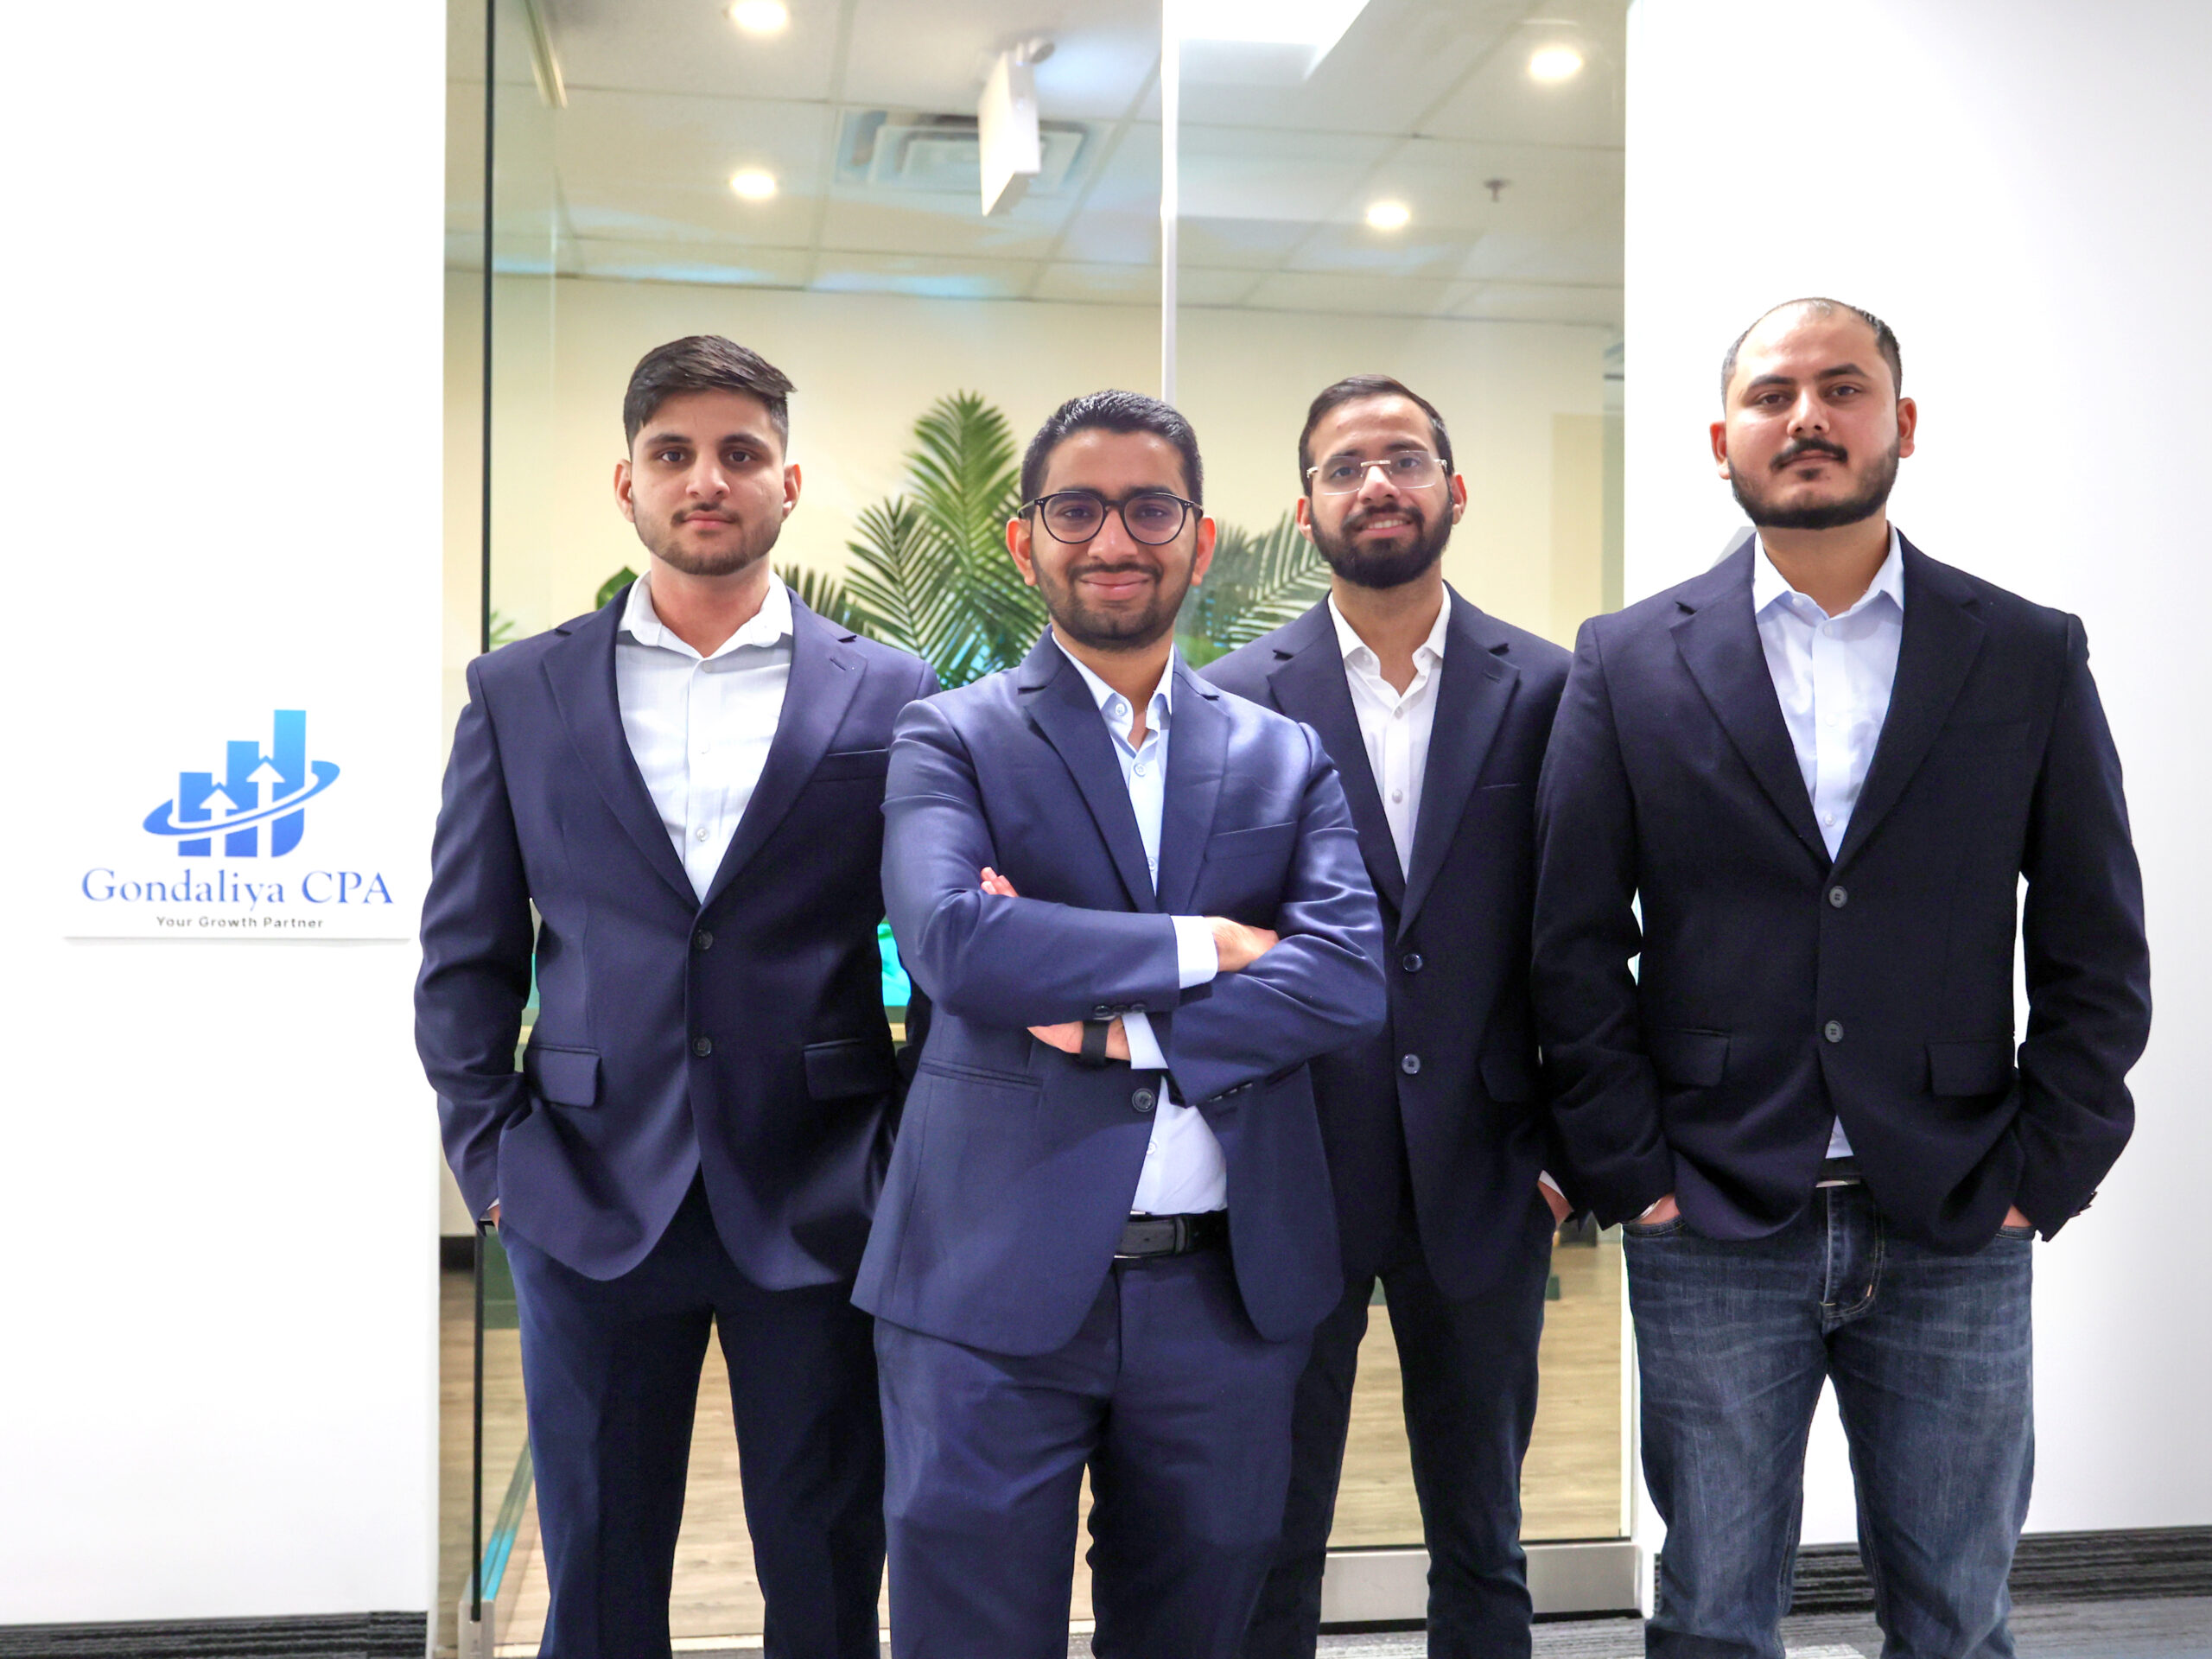
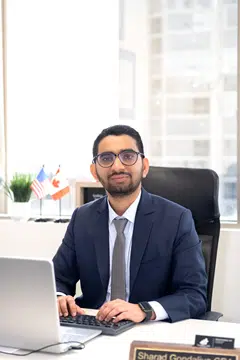
Meet Your Lead Campground Accountant
Meet your lead campground accountant. The same two people handle your season, your HST and your T2 every year, so nothing ever has to be explained twice.
What Our Clients Say
1300+ five-star reviews from campground, cabin, recreation and seasonal business owners across Ontario and Canada.
Serving Campgrounds Across Ontario
Our CPA team provides specialized accounting and tax solutions for campgrounds, cabin and yurt operations and seasonal recreation properties throughout Ontario. We understand why a stay of under one month is taxed differently from a longer arrangement, why the accommodation tax you collect is not revenue, when a spring cheque becomes income, and what CRA looks at first when it opens a campground file.
Toronto (ON)
55 Queen St E Ste 1205, Toronto, ON M5C 1R6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Mississauga (ON)
2100 Camilla Rd #716, Mississauga, ON L5A 2J8
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Brampton (ON)
4 Starhill Crescent, Brampton, ON L6R 2P9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Scarborough (ON)
24 Clementine Square, Scarborough, ON M1G 2V7, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Vaughan (ON)
19 Cabinet Crescent, Woodbridge, ON L4L 6H9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Oshawa (ON)
210 Durham St, Oshawa, ON L1J 5R3, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Ottawa (ON)
2090 Neepawa Ave a314, Ottawa, ON K2A 3L6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Etobicoke (ON)
60 Stevenson Rd #1601, Etobicoke, ON M9V 2B4, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Hamilton (ON)
70 Starling Dr, Hamilton, ON L9A 0C5, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Guelph (ON)
1155 Gordon St, Guelph, ON N1L 1S8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Windsor (ON)
4387 Guppy Ct, Windsor, ON N9G 2N8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
North York (ON)
150 Graydon Hall Dr #912, North York, ON M3A 3B2, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Campground Accounting & Tax FAQs
Related Industries We Serve
Accountant for RV Parks
- Site revenue and capital pools
- HST on short-term accommodation
- Corporate tax filing and statements
Accountant for Adventure Tourism Businesses
- Seasonal revenue and deposits
- Seasonal staff payroll and WSIB
- Corporate tax planning and bookkeeping
Accounting for Small Businesses
- Bookkeeping and HST filing
- Payroll and year-end statements
- Tax planning and CRA support
Accountant for Incorporated Businesses
- T2 filing and GIFI schedules
- Salary and dividend planning
- Small Business Deduction protection
Campground Accounting & Tax Done Right.
T2 filing with buildings in Class 1, equipment and furnishings in Class 8 at 20% and internal roads and surfaces in Class 17, a short-term stay of under one month charged at 13% with longer arrangements determined on their facts and documented, the accommodation tax your municipality levies held in trust and remitted rather than booked as income, seasonal fees carried as deferred revenue and released across the camping they buy, deposits handled under ETA subsection 168(9), and capital kept apart from repair on the water, septic and electrical systems. AFFORDABLE flat fees, no hourly billing. Licensed CPA Ontario. 1300+ five-star reviews. 30-Day Money-Back Guarantee.