



Tax Accountant for Family Entertainment Centres in Ontario and Across Canada
We hold every dollar loaded onto a play card, every prepaid credit and every party package paid in advance as deferred revenue until the play has actually happened, so your return reports what the centre earned rather than what the tills counted. We recognise unredeemed balances on a documented basis supported by your own redemption history, applied the same way every period. We put games, redemption equipment, soft play and furnishings in Class 8 at 20% and the point of sale, card readers and computers in Class 50 at 55%, carry the fit-out as a leasehold improvement, hold prize stock as inventory at the lower of cost and net realizable value, and settle recapture under ITA 13(1) when a machine is sold or traded. Whether you run an arcade and redemption floor, a trampoline and soft play venue, a bowling and party centre or a mixed-attraction site, we handle the cards, the floor and the payroll — with AFFORDABLE flat fees.
AFFORDABLE Family Entertainment Centre Tax Accountant
A family entertainment centre gets paid before it delivers, and that one fact is where the accounting goes wrong. A parent loads fifty dollars onto a card and walks away: the centre now holds cash and an obligation, not a sale. A birthday booked in September for November is paid for in September. On the night the tills close, a substantial part of what they counted is play the centre still owes, and books that treat it as revenue describe a business stronger than it is and pay tax on the difference. The second problem is the floor itself. Games, redemption equipment, soft play and furnishings, the terminals and computers that run them, and the fit-out you put into a leased building all depreciate on different schedules, and pooling them into one pile stretches the deduction on precisely the assets that lose value fastest. At Gondaliya CPA, we specialize in card liability, breakage and floor economics for family entertainment centres, providing AFFORDABLE flat-fee support that keeps you CRA-compliant and stops you paying more tax than you owe.
As a family entertainment centre accountant, we work with arcade and redemption venues, trampoline and soft play centres, bowling and party venues and mixed-attraction operators across Ontario, with year-round support rather than a once-a-year scramble. We tell you what each machine earns, what your card liability genuinely is, and where the payroll exposure sits on a floor that turns its staff over twice a year.
Let us handle the numbers so you can focus on the floor and the party book.
Our Official Partners
Accounting That Understands How a Family Entertainment Centre Actually Works
A centre takes most of its money before it delivers anything. Cards are loaded, parties are booked months ahead and memberships are sold in advance, so a large share of what the tills count on any given night is an obligation rather than a sale. Underneath that sits a floor full of capital depreciating on three different schedules, and a prize stockroom most operators deduct on the day it arrives. At Gondaliya CPA, we understand that reality and provide practical, industry-focused solutions across Ontario.
Stay Compliant and Minimize Your Family Entertainment Centre Tax
For a family entertainment centre, keeping CRA onside and paying the least legal tax are the same job. We hold every deadline while claiming the full machine, prize, payroll and occupancy cost the T2 permits, so nothing is left behind and nothing on the return draws a second look.
Accounting & Tax Experts for Family Entertainment Centres
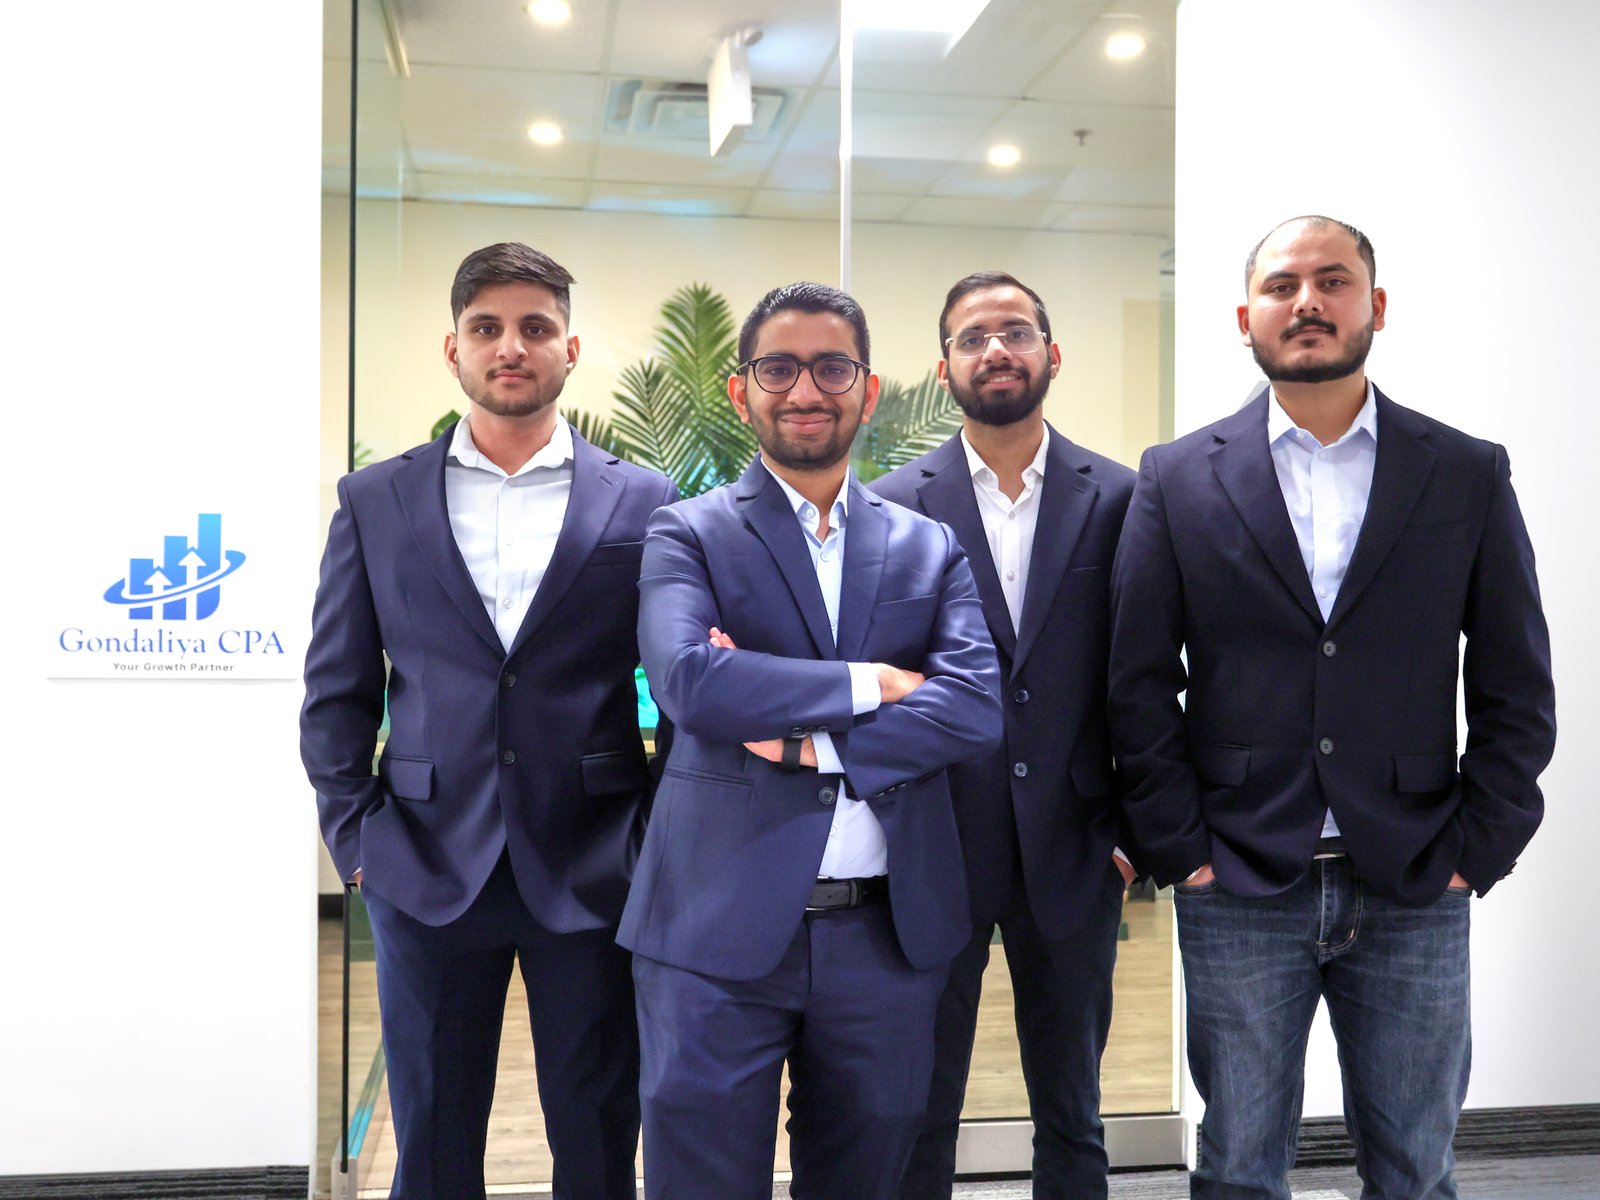
- AFFORDABLE + Fully Registered CPA Firm
- Business and Corporate Tax Expert
- Small & Medium Business Expert
- Accounting, bookkeeping, and tax filing
- Certified CPA
- 1300+ 5-star Google reviews
- 30-Day Money-Back Guarantee
- 60-Day Fees Matching Policy
Why Choose Our Accounting Services for Family Entertainment Centres?
Tax Planning — Card Liability & Capital
We know the file: loads held as deferred revenue, breakage on a documented basis, Class 8 machines against Class 50 terminals, recapture on a trade-in. We protect the $500,000 Small Business Deduction.
Consulting — Floor Economics
Our bookkeeping reports revenue per machine and per square foot, splits food and beverage out as a department, and shows which attractions earn their footprint and which are being carried.
CRA Representation — Cards & Disposals
When CRA questions the card liability, the breakage basis or a machine disposal, we prepare the response and pursue relief on Form RC4288 where an earlier error caused the penalties.
Bookkeeping — Cash and the Forward Book
We keep money held for play apart from money earned, show the forward book on the balance sheet, and build the cash plan that carries a centre through a quiet February.
Google Reviews
Family Entertainment
Centre Clients
Family Entertainment Centre Tax and Accounting Services in Ontario
Corporate Tax Filing (T2) for Family Entertainment Centres
Professional T2 preparation with card loads held as deferred revenue, games in Class 8, point of sale in Class 50, prize stock as inventory, and CRA compliance on every line.
Bookkeeping & Accounting for Family Entertainment Centres
Monthly books that reconcile the card system to the ledger, report revenue per machine and per square foot, and split food and beverage out as its own department.
Payroll Services for Family Entertainment Centres
Payroll for a part-time floor, with WSIB from the first hire, PD7A remittances on schedule, records of employment issued as staff leave, and T4 or T4A filed correctly.
GST/HST Filing for Family Entertainment Centres
AFFORDABLE HST filing at 13% on admissions, play, food and retail, with gift cards taxed only on redemption, deposits timed correctly, and every input tax credit recovered.
Tax Planning for Family Entertainment Centres
Machine purchase timing across Class 8 and Class 50, the Small Business Deduction protected, the salary and dividend mix set, and the exit structured years ahead.
Corporate Catch-Up Filing for Family Entertainment Centres
File overdue T2 and HST years, rebuild the card liability, prize inventory and asset pools behind them, and get back into CRA compliance with accurate catch-up support.
CRA Audit Resolution for Family Entertainment Centres
Expert support on card liability, breakage basis, machine disposal and worker-status reviews, handled with confidence from the first letter CRA sends.
CPA Financial Statements (Notice to Reader) for Family Entertainment Centres
Notice to Reader statements for a lender, a landlord or an incoming partner, showing the card liability, the prize inventory and every attraction valued class by class.
Incorporation Services for Family Entertainment Centres
Full incorporation including NUANS, articles, share structure, and the section 85 rollover of your machines, prize stock and fit-out into the new company.
Catch-Up Bookkeeping Services for Family Entertainment Centres
Months or years of card exports, point of sale takings, prize orders and machine invoices reconstructed and reconciled, so the asset schedule and the card liability are finally right.
US Corporation & LLC Tax Filing for Family Entertainment Centres
Cross-border filing where owners or shareholders are non-resident or American, or a location trades on both sides of the border, covering withholding and T1135 reporting.
Voluntary Disclosure Program for Family Entertainment Centres
Come forward on card loads reported as sales, unreported recapture or HST charged on gift card sales before CRA calls, cancelling penalties through a Voluntary Disclosures Program application.
Accounting & Tax Services Tailored for Family Entertainment Centres
Real, practitioner-level CPA expertise for arcade and redemption venues, trampoline and soft play centres, bowling and party venues and mixed-attraction family entertainment centres across Ontario — built for a business that takes most of its money before it delivers anything.
- We prepare your T2 with GIFI on Schedule 100 and Schedule 125, putting admissions and play time, card value released on redemption, party packages, food and beverage and retail on separate lines rather than one blended sales figure.
- We move the money still sitting on loaded play cards off the sales line and onto the balance sheet as deferred revenue, because a centre that reports loads as income pays tax years before it has earned a dollar of it.
- We claim capital cost allowance on Schedule 8 with games, redemption equipment, soft play structures and furnishings in Class 8 at 20%, point of sale terminals, card readers and computers in Class 50 at 55%, and the fit-out as a leasehold improvement in Class 13.
- We carry redemption prize stock as inventory at the lower of cost and net realizable value, so a pallet of plush toys bought in November is not deducted in a year when most of it is still sitting on the shelf.
- When a machine leaves the floor, sold outright or traded against its replacement, we work out recapture under ITA 13(1) wherever proceeds run past the undepreciated capital cost of the class, and take a terminal loss where the class is cleared out for less.
- We build a chart of accounts where loaded card value, party packages and unearned membership fees each sit in liability accounts of their own, and revenue is released only as play, parties and admissions are genuinely delivered.
- We report revenue per machine and revenue per square foot every month, which is the operating test that shows which attractions earn their floor space and which are being carried by the ones standing beside them.
- We run food and beverage as its own department with its own cost of sales and margin, instead of letting pizza and drinks vanish into an admissions total where nobody can see whether the kitchen makes money.
- We reconcile the card system to the general ledger every month, so the liability on the balance sheet matches the value your terminals report as still loaded rather than the two drifting quietly apart across a year.
- We push supplier, prize, repair and utility invoices through Dext and reconcile every month, satisfying the six-year retention ITA section 230 calls for and stopping input tax credits slipping past unclaimed.
- We set up payroll in Wagepoint for a floor staffed by students and part-timers, withholding income tax, CPP and EI and remitting on the PD7A on schedule, because CRA’s graduated late-remittance penalty on source deductions reaches 10%.
- We issue records of employment as staff cycle out, which on a high-turnover floor happens constantly, and getting them out on time is the difference between a quiet payroll file and a steady stream of CRA enquiries.
- We test party hosts, birthday attendants and floor technicians against the employee-versus-contractor factors on how the work is really carried out, and file T4 or T4A accordingly rather than letting an invoice settle the question.
- We file your T4 slips and T4 Summary by the last day of February, reconciled to the PD7A remittances made across the year, so the slips, the remittances and the wage expense on the T2 all agree with one another.
- We register WSIB coverage before the first hire and watch Ontario employer health tax once payroll passes the $1,000,000 exemption, so a growing centre is not caught by an obligation that quietly started mid-year.
- We file GST34 returns with admissions, play time, attraction access, food and retail as taxable supplies at 13% in Ontario, recovering in full every input tax credit on machines, prizes, rent, utilities and repairs.
- We register you once taxable revenue passes $30,000 over four consecutive calendar quarters, and where a centre is near that line we register early so the credits on a fit-out year are not left behind.
- We configure the till so no tax is charged when a gift card or stored-value card is sold or loaded, and the tax instead applies at the moment that card is redeemed against a taxable supply.
- We time party deposits under ETA subsection 168(9), which places the collection point in the period the deposit is applied against the invoice rather than in the month a parent reserves the date.
- We reconcile HST collected back to the card system and the point of sale at every filing, because a centre with three revenue streams and a stored-value float is exactly where returns and ledger part company.
- We plan machine purchase timing across Class 8 and Class 50, because buying a bank of games and the terminals that run them in the same year draws deductions at two very different rates.
- We protect the small business deduction on the first $500,000 of active income, where the Ontario combined rate is roughly 12.2% against a top personal rate of 53.53% on money taken out of the company.
- We set the salary and dividend mix each year against what the owner actually draws, so the corporation keeps the surplus it can defer tax on rather than pushing every dollar into a personal return.
- We model the replacement cycle on the attractions that earn against the ones merely paying rent for their footprint, so the capital budget is set by revenue per square foot rather than by whichever machine broke last.
- We plan the exit years ahead so the shares can qualify for the $1.25 million lifetime capital gains exemption, which usually means correcting an asset mix that has drifted long before a buyer ever appears.
- We file your overdue T2 and HST years in order, rebuilding each year’s card liability, prize inventory and capital cost allowance pools so the returns describe the centre that existed rather than a guess at it.
- We reconstruct the deferred balance on loaded cards at every past year-end from the card system, because the largest single error on an unfiled centre is years of loads sitting in income where they never belonged.
- We work through the missing years machine by machine, restoring each capital cost allowance pool from the original invoices, separating the fit-out from the equipment standing on it, and settling disposals nobody ever wrote down.
- We apply for penalty and interest relief on Form RC4288 where the delay has a genuine explanation, which on a multi-year file frequently recovers more than the catch-up work itself costs to complete.
- We bring the instalment base back to income actually earned, so a centre that had been over-reporting card loads stops paying instalments on revenue it has not yet delivered a single hour of play against.
- When a reviewer questions the card liability, we reconcile balances outstanding at the year-end date to the card system report, so the figure on the balance sheet is supported by the centre’s own records.
- We defend the breakage entry by producing the redemption history it was built from and showing that the same basis was applied in every period, which turns a judgment call into a documented position.
- On a capital cost allowance review we produce the invoice behind every machine, the class it was assigned and why, and the disposal record for anything sold, which closes most attraction queries on the first response.
- On a payroll review we produce the worker-status analysis, the slips filed and the records of employment issued, so a floor full of part-time staff is not treated as an unexamined contractor problem.
- We handle the correspondence from the first letter through to the notice of reassessment, and pursue relief on Form RC4288 where an earlier error rather than neglect produced the penalties being charged.
- We produce compilation engagement statements that satisfy a lender, a landlord reviewing a renewal or an incoming partner, valuing each attraction class by class and keeping the fit-out distinct from the equipment sitting on it.
- We present outstanding card balances and unearned party packages as deferred revenue on a line of their own, because a reader looking at $180,000 of cash needs to know how much of it is already owed back in play.
- We show food and beverage as a department with its own revenue and cost of sales, so a reader can see whether the kitchen contributes margin or quietly consumes the margin the floor is generating.
- We state redemption prize inventory at the lower of cost and net realizable value, which stops a stockroom of plush and novelty items being carried at a value the prize counter would never actually recover.
- We reconcile the statements to your filed HST returns and to the T2 with GIFI, so the three documents a reviewer or a lender might compare all tell the same story about the same year.
- We handle the full incorporation including the NUANS search, articles and a share structure that leaves room for a spouse, a family trust or a future partner, rather than one class of shares issued in a hurry.
- We roll your existing machines, prize stock and fit-out into the new corporation under section 85 on Form T2057, so assets built up as a sole proprietor transfer across without triggering tax on the way in.
- We open the books with card liability, party deferral and prize inventory accounts already in place, so the first year accumulates correctly instead of being untangled two years later by somebody else entirely.
- We register the HST account, the payroll account and WSIB coverage at the same time, so a centre opening in April is not discovering a registration obligation halfway through its first busy summer.
- We set the first year-end date against your quietest trading month, which makes the prize stock count and the card balance reconciliation a manageable evening rather than a week lost inside a peak period.
- We rebuild months or years of neglected records from bank deposits, the card system export, supplier invoices and payroll records, until a centre that traded three years without bookkeeping has a ledger that ties out.
- We separate loaded card value from redeemed play right across the backlog, which is the entry a bookkeeper without arcade experience misses and the one that most changes what the caught-up years actually owed.
- We rebuild the asset schedule from machine purchase invoices and assign every item to Class 8, Class 50 or leasehold improvements — a schedule that on an inherited centre file is usually either incorrect or absent altogether.
- We recover the input tax credits buried in unentered machine purchases, prize orders, rent and repair invoices, because a centre fitting out or re-equipping can hide five figures of credits across two years.
- We reconstruct revenue per machine and the food and beverage department across the caught-up months, so the owner ends up holding a floor report and a real margin rather than only a set of filed returns.
- Where shares in your centre are held by a non-resident, we deal with Part XIII withholding on dividends leaving Canada and the NR4 reporting behind it, at 25% or at whatever the treaty reduces it to.
- Form T1135 goes in whenever the owners’ specified foreign property crosses the $100,000 threshold, a pure reporting obligation CRA penalises even in a year when the holdings themselves produced no tax at all.
- Where a US citizen holds shares or owns the business, we run the Canadian and the US filings together, because US reporting reaches inside a Canadian corporation in ways families usually learn about far too late.
- Where a family entertainment centre operates a location on both sides of the border, we keep the two sets of books and the two returns aligned as the year runs rather than reconciling them afterwards.
- We line the two returns up against one another so foreign tax credits actually land, and income already taxed once on one side of the border is not quietly taxed a second time on the other.
- We bring a centre forward on years of card loads reported as sales, because correcting the timing yourself through a disclosure is a very different conversation from having a reviewer find it first.
- We disclose recapture that went unreported when machines were sold or swapped out, since an unrecorded disposal simply stays on the file, and the late-catch penalty is exactly what a disclosure is able to lift.
- Your submission goes in on Form RC199 backed by a reconstruction drawn from the card system, the point of sale and the bank, so a centre that simply outgrew its bookkeeping avoids an arbitrary assessment.
- We correct HST charged on gift card sales that should have been taxed only on redemption, a quiet and cumulative error on a centre that sells cards heavily through every December.
- We confirm your disclosure is genuinely voluntary and at least one year past due before CRA contacts you, the conditions that make it valid, and pursue interest relief on the older years of the file.
Family Entertainment Centre Card & Tax Check
Six quick questions on your card liability, your gift card tax point, your unredeemed balances, your capital cost allowance classes, your per-machine reporting and whether it is time to incorporate. No fee shown.
1. Is money loaded onto play cards held as deferred revenue until it is redeemed?
2. Is HST charged only when a gift card is redeemed, rather than when it is sold?
3. Are unredeemed balances recognised on a documented, consistently applied basis?
4. Are your point of sale terminals and computers in Class 50 rather than pooled in Class 8?
5. Do you report revenue per machine and per square foot every month?
6. Is your family entertainment centre incorporated?
Free CPA Consultation for Family Entertainment Centres
Case Studies: Family Entertainment Centre Accounting & Tax
Whitby Family Entertainment Centre — Fifty Dollars a Card, Booked as Sales
The problem: A Whitby centre with an arcade floor, soft play and four party rooms recorded every dollar loaded onto a play card as revenue the day it was loaded. Three years of returns therefore reported income the centre had not yet earned, tax was paid on it, and the instalment base climbed off a figure that included balances still sitting on cards in customers’ wallets.
What we did: We exported the balance still sitting on cards at each year-end, restated it as deferred revenue, released it to income as credits were spent on the floor, built a documented breakage basis from the centre’s own redemption history, and reset the instalments.
The result:
- $138,000 moved from revenue into card liability
- Instalments rebuilt on play actually delivered
- Breakage basis documented from the centre’s own history
Belleville Bowling and Arcade Centre — A Stockroom Expensed on Arrival
The problem: A Belleville centre bought redemption prizes in two large orders a year and expensed each invoice the week it arrived. Plush, novelty items and small electronics worth tens of thousands sat in the stockroom at every year-end carried at nothing, so profit collapsed in the buying month and looked inflated afterwards. Four machines had also been traded in with no disposal recorded anywhere.
What we did: We counted the stockroom, brought prize inventory onto the balance sheet at the lower of cost and net realizable value, moved the deduction to when prizes were handed over, and settled the trade-ins through Class 8 so recapture under ITA 13(1) landed correctly.
The result:
- $41,000 of prize stock brought onto the balance sheet
- Four machine trade-ins settled through the Class 8 pool
- Monthly profit stopped swinging with the prize order
Peterborough Family Entertainment Centre — The Machines Nobody Measured
The problem: A Peterborough centre ran sixty-odd machines on a leased floor with no idea which of them earned. Revenue arrived as a single arcade total, the food counter was folded into the same line, and capital spending went on whatever had broken most recently. The owner was certain the newest racing cabinets carried the business and assumed party bookings were the least profitable thing the centre did.
What we did: We tagged revenue by machine and by zone, reported revenue per machine and per square foot monthly, and split food and beverage out as a department with its own cost of sales, so each part of the floor was judged on what it returned.
The result:
- Eleven machines earning less than their floor space
- Food and beverage margin visible as a department
- Replacement planned on earnings, not on breakdowns
Our clear, efficient process ensures every step is transparent, building trust and long-term client relationships.
Kickoff (Document Request)
Collect prior T2 returns, card system liability and redemption reports, point of sale exports, machine purchase and trade-in invoices, prize orders, the lease and fit-out costs, party booking records, payroll records, and bank statements.
First 30 Days (Cleanup & Setup)
Set up QuickBooks Online or Xero against your card and point of sale systems, open the deferred revenue and prize inventory accounts, rebuild the Class 8, Class 50 and leasehold schedules, and document the breakage basis.
Monthly Close
Card liability reconciled to the system, revenue released on redemption, revenue per machine and per square foot reported, food and beverage margin split out, GST34 filed, and payroll and PD7A reconciled.
Quarterly Planning Review
Salary and dividend mix, machine purchase timing across Class 8 and Class 50, replacement decisions on attractions earning less than their footprint, prize cost per redemption, and cash measured against the forward book.
Year-End Close & T2 Filing
Trial balance, card and party balances reconciled to deferred revenue, prize stock counted and valued, attractions at net book value by class, recapture or terminal loss settled, T2 with GIFI, and CRA preparation.
Get Your Family Entertainment Centre Taxes Done Right Today
Affordable Pricing for Family Entertainment Centres
We believe in clear, upfront pricing so you know exactly what to expect. All fees include HST.
- Tax Preparation (Corporation) — From $400
- Tax Return Filing (Corporation) — From $400
- Tax Compliance Audit — FREE CRA audit support for our clients
- Tax Strategy — FREE for our clients
- Accounting Base Plan — From $100 per month
- Bookkeeping Management — Free for our Accounting clients
- Financial Reporting — Free for our Accounting clients
- Business Formation — Flat $35
- Incorporation Process — Flat $35
- Entity Setup Assistance — Flat $35
- Full-Service Payroll — From $125 per month
Payment is by Interac e-Transfer to info@gondaliyacpa.ca only. Security question: Not Applicable, as auto-deposit is enabled.
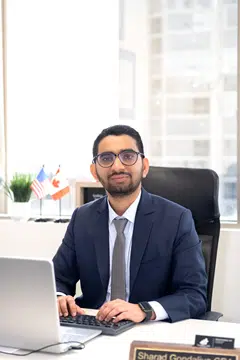
Meet Your Lead Family Entertainment Centre Accountant
Meet your lead family entertainment centre accountant. As your corporate tax adviser, you deal with the same two people every year.
What Our Clients Say
1300+ five-star reviews from entertainment, recreation and hospitality business owners across Ontario and Canada.
Serving Family Entertainment Centres Across Ontario
Our CPA team provides specialized accounting and tax solutions for family entertainment centres, arcades and play venues throughout Ontario. We understand why money loaded onto a card is not yet a sale, how a floor of machines depreciates across three schedules, what a documented breakage basis looks like, and what CRA examines first when it opens a centre’s file.
Toronto (ON)
55 Queen St E Ste 1205, Toronto, ON M5C 1R6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Mississauga (ON)
2100 Camilla Rd #716, Mississauga, ON L5A 2J8
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Brampton (ON)
4 Starhill Crescent, Brampton, ON L6R 2P9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Scarborough (ON)
24 Clementine Square, Scarborough, ON M1G 2V7, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Vaughan (ON)
19 Cabinet Crescent, Woodbridge, ON L4L 6H9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Oshawa (ON)
210 Durham St, Oshawa, ON L1J 5R3, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Ottawa (ON)
2090 Neepawa Ave a314, Ottawa, ON K2A 3L6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Etobicoke (ON)
60 Stevenson Rd #1601, Etobicoke, ON M9V 2B4, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Hamilton (ON)
70 Starling Dr, Hamilton, ON L9A 0C5, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Guelph (ON)
1155 Gordon St, Guelph, ON N1L 1S8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Windsor (ON)
4387 Guppy Ct, Windsor, ON N9G 2N8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
North York (ON)
150 Graydon Hall Dr #912, North York, ON M3A 3B2, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Family Entertainment Centre Accounting & Tax FAQs
Related Industries We Serve
Accountant for Escape Rooms
- Booking revenue and deferred income
- Leasehold fit-out and equipment classes
- Corporate tax filing and statements
Accountant for Event Venues
- Deposits and unearned bookings
- Food and beverage margin
- Corporate tax planning and payroll
Accounting for Small Businesses
- T2 filing and monthly bookkeeping
- HST returns and payroll setup
- Year-round CPA support
Accountant for Incorporated Businesses
- Salary and dividend mix
- Capital cost allowance pools
- Corporate statements and tax planning
Family Entertainment Centre Accounting & Tax Done Right.
T2 filing with money loaded onto play cards carried as deferred revenue until it is redeemed, unredeemed balances recognised on a documented basis drawn from your own redemption history and applied the same way every period, games, redemption equipment, soft play and furnishings in Class 8 at 20% with the point of sale and computers in Class 50 at 55%, the fit-out carried as a leasehold improvement, no HST on a gift card until it is redeemed, party deposits timed under ETA subsection 168(9), prize stock held as inventory at the lower of cost and net realizable value, and recapture under ITA 13(1) settled on every machine disposal. AFFORDABLE flat fees, no hourly billing. Licensed CPA Ontario. 1300+ five-star reviews. 30-Day Money-Back Guarantee.