



Tax Accountant for Freight Forwarders in Ontario and Across Canada
Roughly half of what moves through a forwarder’s bank account was never the forwarder’s money. You advance the duty for a client, you settle the line’s terminal charge, you pay a storage bill so a box is released today instead of Monday — and then you recharge it. Those are amounts paid on a customer’s behalf, and books that call them sales report a company several times the size of the one you actually run, with a margin that frightens every lender who reads it. We separate the two, then handle the things underneath: one box carrying several shippers’ goods under one master document and a house document per consignment, with the freight cost broken back down across consignments that were never the same size or weight; demurrage and detention that arrive weeks late and get disputed; balances in US dollars and euros that have to be restated at your year end. Add T2 filing with warehouse and yard equipment in Class 8 at 20%, vehicles in Class 10 at 30% and computers in Class 50 at 55%, HST at 13% on a purely domestic movement, payroll for your operations and documentation staff, and a straight answer on incorporating — with AFFORDABLE flat fees.
AFFORDABLE Freight Forwarder Tax Accountant
Ask a forwarder what the company turned over last year and you will usually get a number that is mostly somebody else’s money. The duty you advanced so a consignment cleared, the terminal charge you settled on the line’s invoice, the storage bill you paid to get a box released — you fronted all of it and you recharged all of it. These are amounts paid on behalf of a customer and recovered, and in the books that is exactly what they have to look like. Run them through the sales account and the damage is immediate: turnover balloons, gross margin collapses to single digits, and a lender comparing your statements against anything else in the trade concludes you are running a business that cannot pay for itself. Whether a given charge was your own supply or one you handled for the customer is a question of fact, decided by what the contract and the invoice actually say, so the distinction has to be documented charge type by charge type rather than assumed once and forgotten.
Underneath that sits the part nobody outside the trade sees. You consolidate: several shippers’ goods in one box, one master document covering the move, a house document for each consignment, and a single freight cost that has to be divided across consignments that differ in weight, volume and value. Choose a basis, apply it the same way every time, and write it down — because the number that comes out of it is the only thing standing between you and a margin figure per consignment that is pure guesswork. Then there is demurrage and detention, which arrive after the box has gone, are frequently argued about, and belong against the shipment that caused them rather than smeared across overhead. And there is currency: receivables and payables in US dollars and euros that produce real gains and losses, which have to be recorded and the balances restated at the year end.
We put all of that in order and give you a revenue line you can show a bank.
Our Official Partners
Accounting That Understands How a Freight Forwarder Actually Works
A forwarder’s books have to answer a question most businesses never face: of the money that came in, how much was ever yours? You front duty, terminal charges and storage for clients and take it back later. You buy space in a box and resell it in pieces. You get billed for delay you may or may not be able to recover. You invoice in one currency and pay in two others. Get those four things coded properly and the statements start describing the company you actually own; get them wrong and no amount of tax planning will make the file readable. At Gondaliya CPA we work on that ordering problem first, across the GTA and all of Ontario.
Stay Compliant and Minimize Your Freight Forwarding Tax
Filing on time and paying the least legal tax are one job, not two. We keep the HST periods, the payroll remittances, the WSIB account and the T2 on schedule while claiming every credit and every capital cost allowance dollar the returns allow, and we keep the supporting paper assembled shipment by shipment so a review finds an answer rather than a gap.
Accounting & Tax Experts for Freight Forwarders
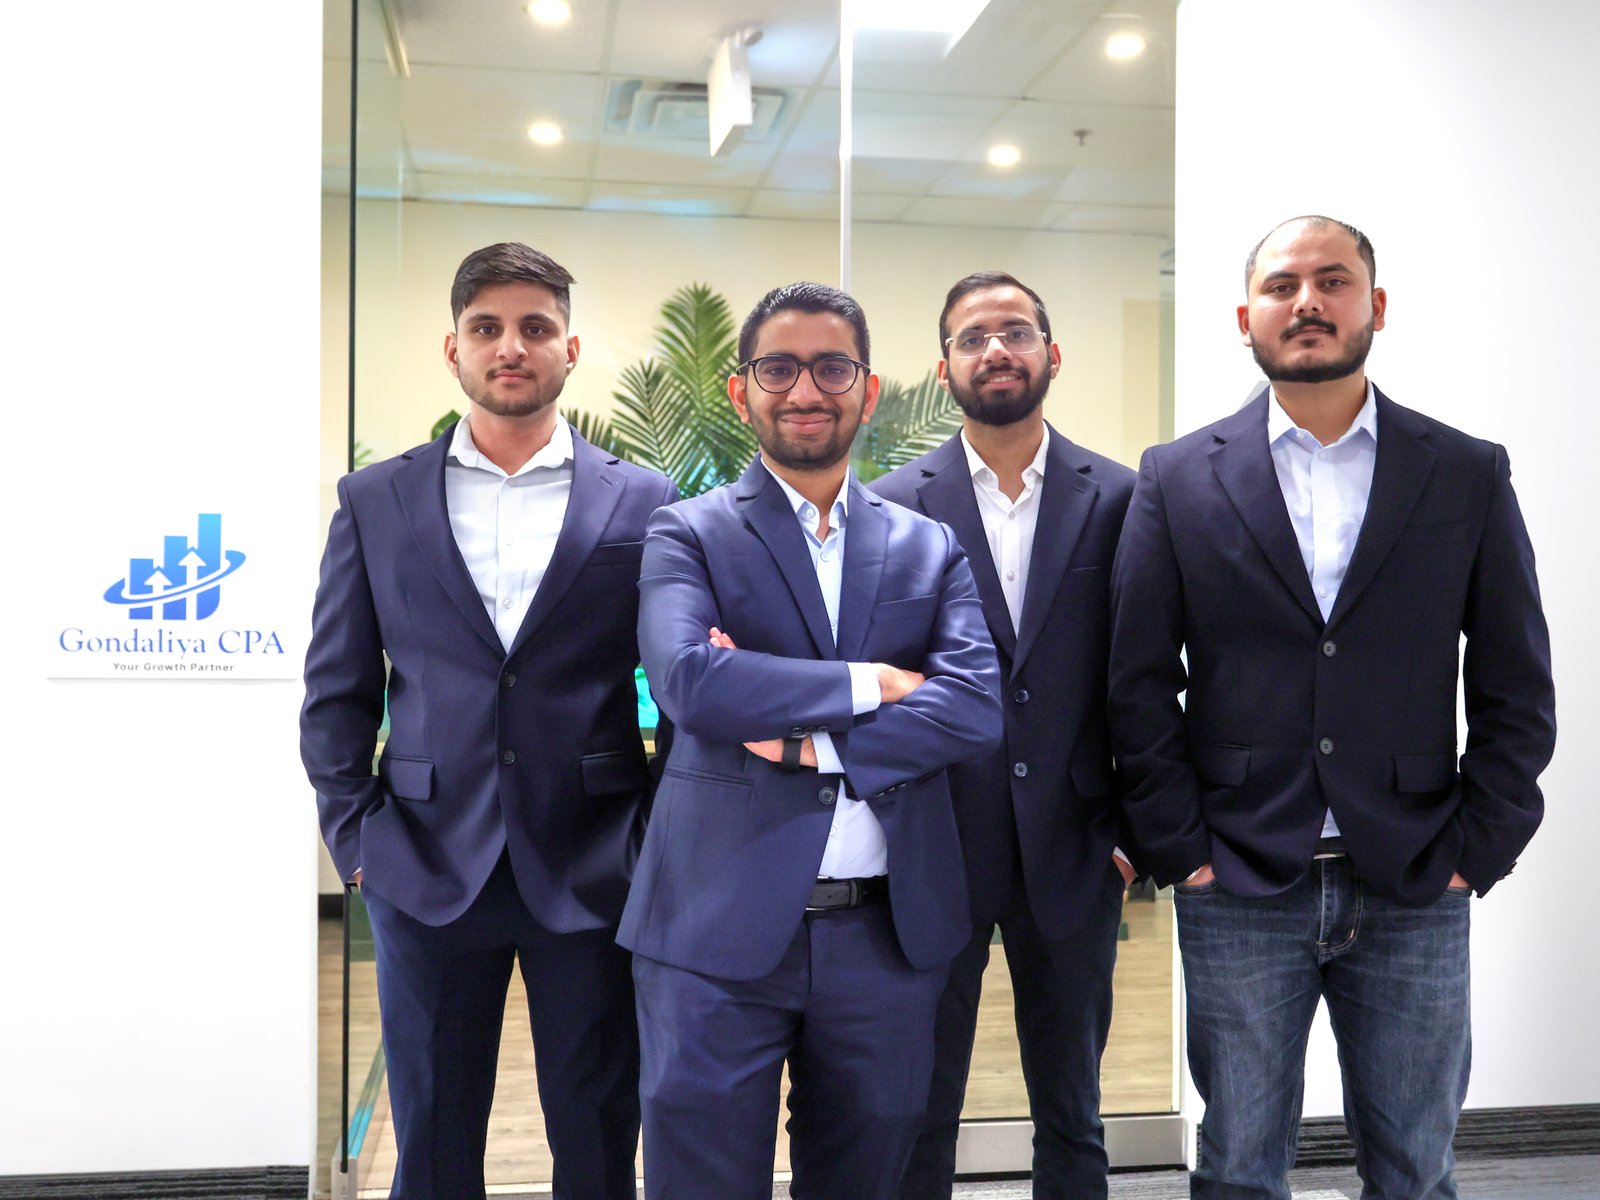
- AFFORDABLE + Registered CPA Firm
- Business and Corporate Tax Expert
- Small & Medium Business Expert
- Accounting, bookkeeping, and tax filing
- CPA (Chartered Professional Accountant)
- 1300+ 5-star Google reviews
- 30-Day Money-Back Guarantee
- 60-Day Fees Matching Policy
Why Choose Our Accounting Services for Freight Forwarders?
Tax Planning — The Revenue Line First, Then the Pools
We fix the revenue line first, then plan around it: roughly 12.2% combined in Ontario on active profit up to the $500,000 ceiling rather than a personal rate reaching 53.53%, Class 8 yard and warehouse equipment, Class 10 vehicles and Class 50 computers timed across year ends, and the ITA 110.6 conditions behind a $1.25M Lifetime Capital Gains Exemption settled years before you sell.
Consulting — Consolidation Costing and Pass-Through Bookkeeping
Our bookkeeping keeps recovered advances out of sales at the point of entry, attaches the master and house documents to one job, divides a box’s freight cost across its consignments on a basis you have written down, and accrues demurrage and detention against the shipment that caused them.
CRA Representation — Revenue, Records and Recovery Reviews
When a reviewer asks why turnover dwarfs margin, or how one box’s cost was split, or why a delay charge was deducted, we produce the advance, the receipt and the recovery tied to that shipment, and where penalties came out of somebody else’s mistake we ask for them to be lifted on Form RC4288.
Bookkeeping — Payroll, Currency and Sale
We run operations, documentation and accounts payroll with WSIB and Employer Health Tax, restate US dollar and euro balances every month instead of once a year, and put a number on the profit level at which incorporating actually starts to pay.
Google Reviews
Freight Forwarder Clients
Freight Forwarder Tax and Accounting Services in Ontario
Corporate Tax Filing (T2) for Freight Forwarders
T2 preparation where recovered advances sit outside sales on Schedule 125, Schedule 8 carries your Class 8, Class 10 and Class 50 pools, and a shipment still in transit at the year end is dealt with rather than ignored.
Bookkeeping & Accounting for Freight Forwarders
Per-shipment bookkeeping that keeps pass-through money out of revenue, ties master and house documents to one job, allocates a box’s cost across its consignments, and restates foreign-currency balances monthly.
Payroll Services for Freight Forwarders
T4 payroll for operations, documentation and accounts staff with PD7A remittances, the T4 Summary reconciled by the last day of February, WSIB from your first hire and Employer Health Tax tracked against the $1,000,000 line.
GST/HST Filing for Freight Forwarders
HST filing with 0% on international freight transportation and 13% on a purely domestic movement coded at entry, recovered advances kept out of reported sales, and credits claimed in the period they arose.
Tax Planning for Freight Forwarders
Planning around the first $500,000 of active income, the timing of equipment and vehicle purchases, currency exposure on long settlement cycles, and the exemption you will want available on a future sale.
Corporate Catch-Up Filing for Freight Forwarders
Overdue T2 and HST years rebuilt from line invoices, terminal statements and bank activity, with advances reclassified out of sales and the depreciation pools reconstructed.
CRA Audit Resolution for Freight Forwarders
Support when CRA questions your revenue line, your consolidation cost split, a delay charge you deducted or a credit you claimed, with the shipment-level paper produced to match.
CPA Financial Statements (Notice to Reader) for Freight Forwarders
CPA-compiled statements banks and equipment lessors accept, showing revenue net of pass-through recoveries and foreign balances at the year-end rate.
Incorporation Services for Freight Forwarders
Incorporation with NUANS, articles and share classes, HST registration from day one, and the ITA 85 rollover of assets, contracts and goodwill on Form T2057.
Catch-Up Bookkeeping Services for Freight Forwarders
We rebuild months of unposted line invoices, terminal charges, delay bills, foreign receipts and unclaimed credits until the books tie to the bank and to the shipment file.
US Corporation & LLC Tax Filing for Freight Forwarders
Cross-border work for forwarders with a US warehouse, a US dollar account or a US subsidiary: Form 1120, treaty-based Form 1120-F, Form 5472 and the LLC mismatch that strands a credit.
Voluntary Disclosure Program for Freight Forwarders
A disclosure on Form RC199 filed before CRA makes contact, correcting years where advances were reported as sales, currency gains went unrecorded or returns were never filed.
Accounting & Tax Services Tailored for Freight Forwarders
Practitioner-level CPA work for ocean, road and rail forwarders, consolidators and groupage operators across Ontario — written for a business where the bank statement and the income statement were never going to match.
- Your T2 begins with a clean Schedule 125: money you fronted on a customer’s behalf and later recovered is lifted out of sales, because a duty advance was never earnings. One Oakville restatement removed $1.9 million of turnover that had never belonged there.
- We claim capital cost allowance on Schedule 8 with warehouse and yard equipment in Class 8 at 20%, vehicles in Class 10 at 30% and servers and workstations in Class 50 at 55%; one rebuilt fixed-asset register released $28,000 of deduction nobody had taken.
- A shipment still on the water at your year end gets dealt with rather than ignored: ITA 12(1)(a) brings in an amount received for a service not yet rendered, with the ITA 20(1)(m) reserve claimed where the customer was billed before the work was done.
- Balances owed to you and by you in US dollars and euros are translated at the year-end rate and the resulting gains and losses are put on the return instead of disappearing into bank charges; one year-end correction surfaced $21,000 of currency loss.
- A customer whose payment is genuinely doubtful supports a reserve under ITA 20(1)(l) for as long as you keep chasing the money. The write-off under ITA 20(1)(p) is a later and quite separate entry, reached only when the amount has gone bad for good.
- We open dedicated ledger accounts for pass-through money, so a storage bill you settled becomes a receivable from the customer the moment it is entered, never a sale. One Niagara Falls cleanup cut reported revenue by 44% without touching profit.
- Where several shippers’ goods travel in one box, we divide the freight cost back out across the consignments on a basis you have chosen, apply it identically every time, and record what the basis is and why it was chosen.
- The master document and each house document are filed against the same job, so the sea leg, the inland leg, the terminal charge and what you recovered reconcile to one another rather than to one undifferentiated revenue total.
- Delay bills land weeks after the box has moved, so we accrue each one against the shipment that generated it and mark the ones still being argued over; one review found $17,000 already recoverable from customers and never invoiced.
- US dollar and euro customer accounts are kept in their own currency in the ledger and restated at each month end, so the exchange result shows up twelve times a year instead of once, as a surprise, in the year-end adjusting entries.
- Operations, documentation and accounts staff go on T4 payroll, and the source deductions reach CRA on the PD7A by the deadline, because a graduated late-remittance penalty runs as high as 10% — on a $30,000 remittance that is $3,000 gone for nothing.
- The T4 Summary and every slip behind it are due on the last day of February, and we reconcile them against what actually reached CRA during the year, so the payroll account and the T2 stop telling a reviewer two different stories.
- WSIB coverage is opened from your first hire rather than after somebody notices, and premiums are tied back to the wages you reported; one registration closed a retroactive exposure a client had been carrying for two years at roughly $14,000.
- Ontario Employer Health Tax begins once annual remuneration passes $1,000,000, so we watch the payroll run against that line through the year and file it beside the T4 Summary instead of finding it after the books have closed.
- Dock and warehouse hands taken on for a busy season are tested against CRA’s own employee-versus-contractor factors before the first payment, because the reclassification bill arrives at your door; one review headed off an exposure of about $19,000.
- International freight transportation services are zero-rated, so the movement is billed at 0%, while a purely domestic movement inside Ontario carries 13%; one coding correction reversed $46,000 of tax that had been charged on the wrong side of that line.
- Four consecutive calendar quarters of taxable revenue above $30,000 makes registration compulsory, and we usually have you registered well ahead of that anyway, because credits come back only to a registrant and on a forwarding file they are substantial.
- Amounts you merely fronted and recovered are not your own supply, so they stay out of reported sales and the treatment is documented charge type by charge type, because the answer turns on the facts rather than on a rule of thumb.
- We claim the 13% you paid on warehouse rent, drayage invoices, terminal charges, accounting software and professional fees on line 108 in the period it arose rather than a year later; one quarter of captured invoices returned $9,800.
- Where a delay charge is recovered from a customer it is a recovery of what you paid; where you absorb it, the 13% on that charge is still yours to claim. One reconciliation brought back $6,200 of tax written off in error.
- We decide how much leaves as T4 salary and how much as dividends, so the low-rate room inside the corporation is used before anything is drawn at a top personal rate; on one owner that sequencing deferred $31,000 by a full year.
- Equipment and vehicle purchases are timed across year ends so the Class 8, Class 10 and Class 50 claims land where they are worth most, with an owned warehouse named as Class 1 and leasehold improvements as Class 13; one plan shifted $23,000.
- Two years before any sale we begin on the share conditions ITA 110.6 imposes, because the $1.25M Lifetime Capital Gains Exemption is lost by a company still carrying surplus cash and passive investments it should have moved out long ago.
- Exposure on euro and US dollar payables is reviewed quarterly, not annually, because a forwarder with a long settlement cycle can hand the entire margin on a consignment back to a rate movement that nobody was watching for six weeks.
- Whether a charge is your own supply or one handled for the customer as their agent has to be determined on the facts, so we settle the contract wording and the invoice format before the pattern hardens into something a reviewer reads differently.
- We rebuild the unfiled years from line invoices, terminal statements and bank activity, because where records are absent CRA may assess under ITA 152(7) on whatever figures it has; one reconstruction replaced an estimate with a liability $27,000 smaller.
- Advances and recoveries buried inside the old sales figure are pulled back out year by year, so each overdue T2 reports what the company actually earned rather than the gross volume of money that happened to pass through the bank.
- The depreciation pools are reconstructed from purchase invoices so the Class 8, Class 10 and Class 50 deductions skipped across the closed years come back into play, which on one file meant $41,000 of undepreciated capital cost nobody had been claiming.
- Overdue HST returns go in alongside the T2s with the 0% and 13% split rebuilt shipment by shipment and the unclaimed credits brought back in, which on one file turned an expected assessment into a refund of $22,000.
- Form RC4288 asks CRA to lift penalties that came out of a previous bookkeeper’s mistake rather than anything you did, and we put the oldest outstanding year in first so nothing keeps compounding behind us while the rest is assembled.
- When a reviewer asks how turnover that large supports a margin that small, we produce the advance, the receipt and the recovery for each charge, tied shipment by shipment; one file closed with no adjustment on $2.3 million of billings.
- ITA 230 requires the books and the supporting documents to be kept for six years, so we assemble the master document, the house document, the line invoice, the disbursement receipt and the recovery as one bundle per job instead of five separate piles.
- Where a reviewer questions how one box’s cost was divided among several consignments, we show the basis, the consistency and the contemporaneous note behind it rather than reverse-engineering an explanation once the query has already arrived.
- Argued demurrage and detention are defended with the terminal’s own statement and the correspondence, so a charge you absorbed is deducted against the shipment it belongs to; one review left $38,000 of those deductions standing.
- Where a reassessment has already issued we object inside the statutory window, and Form RC4288 goes in separately to ask that penalties arising from a previous error be lifted; on one file $8,400 of penalty and interest was cancelled outright.
- A compilation engagement produces the Notice to Reader a lender asks for, and on a forwarding file the most valuable thing it corrects is a revenue line that was never revenue. That single correction, on one client, carried a $275,000 operating line.
- The statement of financial position shows US dollar and euro balances at the year-end rate, delay charges accrued but not yet invoiced, and yard equipment at net book value — three things a bare T2 never tells the person deciding on your credit.
- Where a shipment was in transit at the year end, the statements present that position identically across both comparative years, so the reader is not measuring a full recognition against a deferred one, and on one file that presentation got $180,000 of financing approved.
- The communication states plainly that no audit and no review was performed, which is precisely what a bank or an equipment lessor needs on file before it will lend against your receivables rather than against your building.
- We deliver the compiled statements within four weeks of receiving a complete set of records, because a conditional offer expires while everyone waits; on one deal that timing preserved a $120,000 facility the client had already spent.
- Active profit inside the corporation is taxed in Ontario at about 12.2% combined up to the $500,000 limit, against a personal rate that can top 53.53%, and a cargo claim stops at the company; one owner kept roughly $29,000 in year one.
- Existing assets, the customer list and goodwill move in under ITA 85 on Form T2057 at elected amounts, so the gain and the recapture that a straight sale into the company would have triggered are deferred rather than paid now.
- We register the HST account on day one instead of waiting for the $30,000 test, because a forwarder billing most of its work at 0% gets its credits back only as a registrant; one launch recovered $11,600 on start-up and fit-out costs.
- The corporation’s payroll, HST and multi-currency bank accounts are opened before the first invoice leaves, and the old accounts are closed behind you, so nothing gets reported twice in the year the structure changes.
- Share classes and the first fiscal year end are chosen deliberately, which sets when the first T2 balance falls due and leaves room to split dividends among family shareholders where the facts genuinely support doing so.
- We rebuild the missing months from line invoices, terminal statements and bank activity, restoring the six-year ITA 230 trail a reviewer can actually test; one Sarnia rebuild recovered $16,400 of input tax credits that nobody had ever claimed.
- Every advance found in the old bank feed is matched to the recovery that followed it and reclassified out of sales, which on a forwarder’s catch-up file is almost always the largest single correction in the whole engagement.
- Unposted demurrage and detention bills are entered against the shipments that caused them, and the ones a customer had already agreed to cover are invoiced out; one cleanup collected $12,900 that had simply been forgotten about.
- Foreign-currency receipts are converted at the rate that applied when the invoice was issued rather than at whatever the bank used on the day it cleared, and the difference is booked; one rebuild surfaced $8,700 of unrecorded gain.
- Payroll postings, PD7A remittances and WSIB premiums that fell behind are brought back into line so the payroll account and the ledger agree with each other before anybody starts preparing the corporate return.
- Whether a US warehouse, a US bank account or somebody acting for you there creates a taxable presence has to be determined on the facts, so we document the position while the evidence still exists rather than after a notice arrives.
- Where a US return is required we prepare Form 1120 for a US subsidiary, or the treaty-based Form 1120-F with Form 8833 where the position taken is that the profits are not attributable to a US establishment at all.
- Form 5472 reports transactions between a US corporation and its Canadian owner, and the intercompany charges behind it have to be priced and documented before the form is signed, not reconstructed a year afterwards under questioning.
- A US LLC is looked through by the IRS and treated as a corporation by CRA, and that mismatch can strand your foreign tax credit entirely; one restructuring on a cross-border forwarding file restored $37,000 of credit that had been lost.
- Form W-8BEN-E goes to your US customers so they do not withhold 30% at source, and a US dollar account over $10,000 brings FinCEN Form 114 into play; one filing released $9,400 that had been held back for two years.
- We file the disclosure on Form RC199 before CRA makes contact, because coming forward first is what makes relief available at all; a file opened after the query letter has landed no longer qualifies, whatever the underlying merits are.
- Years in which fronted advances and recoveries were reported as sales are corrected through the disclosure, so the company comes back onside without facing a gross-negligence penalty on revenue that it never actually earned in the first place.
- Unrecorded gains and losses on US dollar and euro balances are rebuilt and included, because a disclosure has to be complete before it can be accepted; one submission corrected $54,000 of currency movement that had never reached a return.
- Delay charges recovered from customers but never put through the books are disclosed with the terminal statements behind them; one operator settled roughly $23,000 rather than carrying that exposure into a year when CRA might find it first.
- Where interest or penalties survive an accepted disclosure, a separate Form RC4288 request goes in on the specific facts of your file, and we make certain the corrected returns beside it are complete on their face before anything is submitted.
Freight Forwarder Revenue & HST Check
Six quick questions on pass-through advances, the 0% and 13% split, consolidation cost allocation, delay charges and whether it is time to incorporate. No fee shown.
1. Are amounts you front for a customer and recover later kept out of your revenue line?
2. Is a purely domestic movement inside Canada billed with 13% HST?
3. Are you registered for HST, so your input tax credits are actually recoverable?
4. Is one box’s cost allocated across its house consignments on a written, consistent basis?
5. Are demurrage and detention accrued against the shipment that caused them?
6. Is your freight forwarding business incorporated?
Free CPA Consultation for Freight Forwarders
Case Studies: Freight Forwarder Accounting & Tax
Oakville Ocean Forwarder — The Revenue That Was Never Ours
The problem: An Oakville forwarder moving ocean freight to Europe and the Gulf ran every duty advance, line terminal charge and drayage invoice through the sales account, then recharged it out of the same account. Reported turnover was $4.6 million on a gross margin of 9%, and two banks had already declined an operating line on the strength of those statements.
What we did: We reclassified the advances as amounts paid on a customer’s behalf, rebuilt two years of Schedule 125 around what the company had genuinely earned, and set up ledger accounts that keep a recovery out of sales at the point of entry.
The result:
- $1.9 million of pass-through money removed from reported revenue
- Gross margin restated from 9% to 31% on identical profit
- A $250,000 operating line approved on the second application
Niagara Falls Consolidator — Delay Charges Nobody Owned
The problem: A Niagara Falls forwarder consolidating cross-border road and rail shipments treated demurrage and detention as overhead. Bills arrived five to eight weeks after the box had moved, landed in one general charges account, and were never matched to a shipment or to the customer whose delay had caused them. Some were recoverable, some were not.
What we did: We accrued each charge against the shipment that generated it, read the customer terms to split the file into recoverable, absorbed and still disputed, and put the disputed ones behind the terminal’s own statements before anybody answered them.
The result:
- $31,000 of recoverable detention invoiced and collected
- $18,000 of absorbed demurrage deducted against the right shipments
- Disputed charges tracked rather than written off by default
Sarnia Groupage Forwarder — One Box, Six Consignments
The problem: A Sarnia forwarder groups several shippers’ goods into one box and issues a house document per consignment under a single master document. The full box cost sat on one line, so a consignment of light bulky goods and a consignment of dense valuable goods carried the same notional cost. Euro payables were converted at whatever rate the bank used that day.
What we did: We settled an allocation basis with the owner, recorded why it was chosen, and applied it identically to every consolidation. Euro and US dollar balances went into their own ledger accounts and are now restated at each month end.
The result:
- Cost visible per house consignment instead of per box
- An allocation basis written down and applied the same way every time
- Currency movement reported monthly rather than once a year
Our clear, efficient process ensures every step is transparent, building trust and long-term client relationships.
Kickoff (Document Request)
Prior T2 and HST returns, a sample of master and house documents, line and drayage invoices, the delay-charge file, customer contracts, the equipment list, payroll records and bank statements in every currency you hold.
First 30 Days (Cleanup & Setup)
Separate ledger accounts for pass-through advances, the 0% and 13% coding built into the sales items, an allocation basis agreed and recorded, foreign-currency accounts opened, and the depreciation pools rebuilt from invoices.
Monthly Close
Reconciliations, receipt capture, delay charges accrued to their shipments, foreign balances restated, the HST return filed with credits claimed in period, and margin reported per consignment rather than per box.
Quarterly Planning Review
Salary and dividend mix, currency exposure on open payables, the recoverable-versus-absorbed split on delay charges, bad-debt reserves, and equipment timing against the year end.
Year-End Close & T2 Filing
Trial balance, in-transit shipments dealt with, foreign balances at the closing rate, compiled statements where a lender needs them, and the T2 with GIFI tied back to the HST periods.
Get Your Freight Forwarding Taxes Done Right Today
Affordable Pricing for Freight Forwarders
We believe in clear, upfront pricing so you know exactly what to expect. All fees include HST.
- Tax Preparation (Corporation) — From $400
- Tax Return Filing (Corporation) — From $400
- Tax Compliance Audit — FREE CRA audit support for our clients
- Tax Strategy — FREE for our clients
- Accounting Base Plan — From $100 per month
- Bookkeeping Management — Free for our Accounting clients
- Financial Reporting — Free for our Accounting clients
- Business Formation — Flat $35
- Incorporation Process — Flat $35
- Entity Setup Assistance — Flat $35
- Full-Service Payroll — From $125 per month
Payment is by Interac e-Transfer to info@gondaliyacpa.ca only. Security question: Not Applicable, as auto-deposit is enabled.
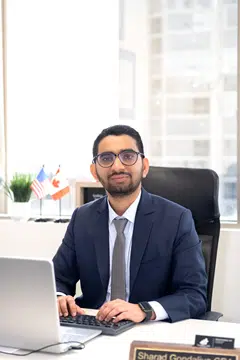
Meet Your Lead Freight Forwarder Accountant
Meet your lead freight forwarder accountant. The same two people prepare and sign your file every year, and neither of them needs telling what a house document is.
What Our Clients Say
1300+ five-star reviews from freight forwarding and logistics business owners across Ontario and Canada.
Serving Freight Forwarders Across Ontario
Our CPA team works with ocean, road and rail forwarders, consolidators and groupage operators throughout Ontario. We know why a forwarder’s bank statement is twice the size of its income statement, how a box’s cost has to be divided among the consignments inside it, where delay charges belong once the argument is over, and what a reviewer expects to find behind each shipment.
Toronto (ON)
55 Queen St E Ste 1205, Toronto, ON M5C 1R6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Mississauga (ON)
5373 Bullrush Dr, Mississauga, ON, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Brampton (ON)
4 Starhill Crescent, Brampton, ON L6R 2P9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Scarborough (ON)
24 Clementine Square, Scarborough, ON M1G 2V7, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Vaughan (ON)
19 Cabinet Crescent, Woodbridge, ON L4L 6H9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Oshawa (ON)
210 Durham St, Oshawa, ON L1J 5R3, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Ottawa (ON)
2090 Neepawa Ave a314, Ottawa, ON K2A 3L6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Etobicoke (ON)
60 Stevenson Rd #1601, Etobicoke, ON M9V 2B4, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Hamilton (ON)
70 Starling Dr, Hamilton, ON L9A 0C5, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Guelph (ON)
1155 Gordon St, Guelph, ON N1L 1S8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Windsor (ON)
4387 Guppy Ct, Windsor, ON N9G 2N8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
North York (ON)
150 Graydon Hall Dr #912, North York, ON M3A 3B2, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Freight Forwarder Accounting & Tax FAQs
Related Industries We Serve
Freight Brokers
- Margin reporting on arranged freight
- Corporate returns and lender statements
- Bookkeeping across the HST periods
Air Cargo Businesses
- HST coding on international movements
- Multi-currency books and corporate tax
- Payroll, WSIB and compiled statements
Importers
- Landed cost and inventory accounting
- Recovering the tax paid at the border
- Corporate returns and bookkeeping
Exporters
- Foreign receivables and year-end translation
- Sales coding and credit recovery
- Tax planning and financial statements
Freight Forwarder Accounting & Tax Done Right.
A revenue line that excludes the money you only handled, consolidation cost split across house consignments on a basis you can defend, demurrage and detention accrued and settled where they belong, US dollar and euro balances restated at the year end, T2 filing with Class 8, Class 10 and Class 50 on Schedule 8, 13% on domestic movements, in-transit shipments handled under ITA 12(1)(a), six years of records under ITA 230, and payroll with WSIB under one roof. AFFORDABLE flat fees, no hourly billing. Licensed CPA Ontario. 1300+ five-star reviews. 30-Day Money-Back Guarantee.