



Tax Accountant for Freight Brokers in Ontario and Across Canada
You never take custody of the freight. You find the load, you find the truck, and what you keep is the spread between what the shipper pays you and what the carrier bills you. Nothing moves through your hands but money and paper, which makes a brokerage a margin business running on somebody else’s working capital: the carrier expects payment in days, the shipper takes weeks, and every load you book widens that gap. We build the file around that reality. Arranging carriage inside Canada is a taxable supply, so your brokerage fee carries 13% HST in Ontario, with input tax credits on what it costs to run the desk, and you must register once four consecutive calendar quarters of taxable revenue add up to more than $30,000. We settle whether your revenue line carries the whole amount billed to the shipper or only your margin, hold a doubtful-debt reserve under paragraph 20(1)(l) of the Income Tax Act while a shipper receivable is genuinely in question, and keep detention, layover and lumper charges visible instead of buried in the spread. AFFORDABLE flat fees.
AFFORDABLE Freight Broker Tax Accountant
A freight brokerage arranges carriage. It does not haul, it takes no custody of the goods, and it issues no bill of lading — the carrier does that. That one line separates you from the carriers and the forwarders whose accounting advice keeps landing on your desk, and it decides how your numbers behave, beginning with what your revenue line is allowed to contain. What you own is a spread: the shipper’s rate less the carrier’s rate, earned by finding capacity and standing behind the booking. Because the service is arranged and consumed inside Canada, it is a taxable supply at 13% HST in Ontario, with input tax credits recoverable on the operating costs behind the desk, and the $30,000 small-supplier line, measured across four consecutive calendar quarters, is what makes registration compulsory. Nothing in the domestic picture softens that rate.
The harder problem is cash. Good trucks answer the phone for brokers who pay quickly, so the carrier is paid within a couple of days of the proof of delivery; the shipper pays you in forty-five. A brokerage carrying $400,000 a month of carrier payables against a thirty-day collection gap is funding several hundred thousand dollars of somebody else’s freight at every moment of the year, and that funding grows with the business instead of shrinking. It is why a brokerage can report a profit on the T2 and still be empty at the bank in the same quarter, and why we report margin, collection speed and the payable cycle together rather than one at a time. Some brokerages finance their receivables to close the gap.
Book the load, cover the load, get paid for the load. We keep the accounting behind the third part honest.
Our Official Partners
Accounting That Understands How a Freight Brokerage Actually Works
A brokerage owns no iron and holds no cargo, so the pressure lands somewhere unusual: on the distance between paying and being paid, on a revenue line whose size depends on how your contracts were written, and on the handful of documents that prove a load existed at all. Get those three right and the file holds under any question. We work with brokerages across the GTA and the rest of Ontario on margin reporting, carrier payables against shipper receivables, doubtful-debt reserves, 13% HST on domestic brokerage, and the payroll behind a desk of dispatch and sales staff.
Stay Compliant and Minimize Your Freight Brokerage Tax
For a brokerage the compliance work and the tax work are one job, because both rest on the load file. A rate confirmation, a load confirmation, a carrier invoice and a proof of delivery, matched load by load, are what stand behind the revenue you reported and the costs you deducted. We keep those moving alongside the filing calendar rather than behind it.
Accounting & Tax Experts for Freight Brokers
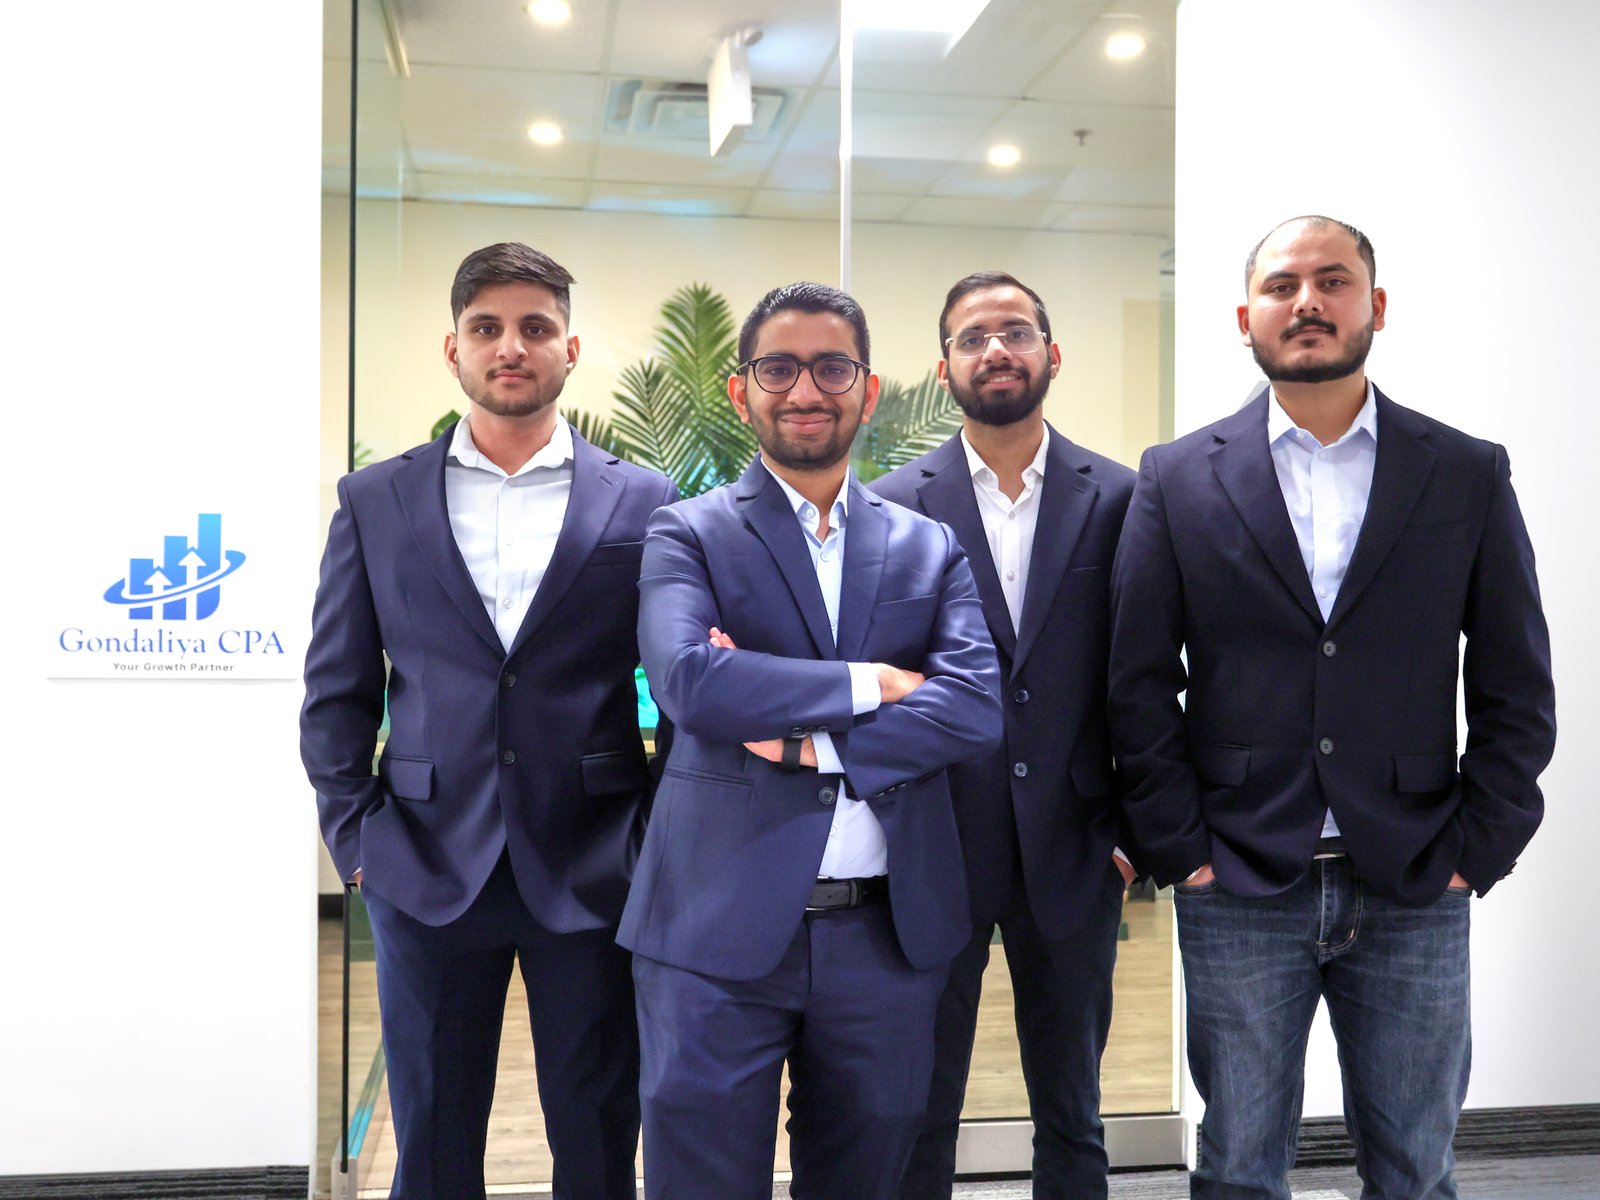
- AFFORDABLE + Registered CPA Firm
- Business and Corporate Tax Expert
- Small & Medium Business Expert
- Accounting, bookkeeping, and tax filing
- CPA (Chartered Professional Accountant)
- 1300+ 5-star Google reviews
- 30-Day Money-Back Guarantee
- 60-Day Fees Matching Policy
Why Choose Our Accounting Services for Freight Brokers?
Tax Planning — Margin, Timing and the Reserve
We plan around the two levers a brokerage actually has: when revenue is recognised and when a bad receivable becomes deductible. That means deferring amounts invoiced ahead of delivery under ITA 12(1)(a) and claiming the reserve ITA 20(1)(m) provides, holding the ITA 20(1)(l) doubtful-debt reserve where collection is genuinely in question, and keeping active profit inside the $500,000 small business limit, where Ontario’s combined rate sits near 12.2%.
Consulting — Load-Level Margin and the Cash Gap
Our bookkeeping costs each load with its own carrier charge and its own accessorials, so detention, layover and lumper amounts appear as revenue when billed and as cost when incurred instead of vanishing into the spread. We report days to collect beside days to pay every month, because that distance is what your growth is funded out of.
CRA Representation — Records and Reassessments
When a review lands on your revenue treatment, your reserve or your accessorial billing, we assemble the load files that stand behind the return, file the objection where an assessment does not match those records, and apply for relief on Form RC4288 where penalties followed somebody else’s error rather than yours.
Bookkeeping — Payroll, Slips and Succession
We run payroll for dispatch and sales staff, treat commissions paid to employees as the payroll they are, remit on the PD7A and match the T4 Summary back to those remittances before the February deadline. We also model the profit level at which incorporating pays, and plan the eventual sale of the shares.
Google Reviews
Freight Broker Clients
Freight Broker Tax and Accounting Services in Ontario
Corporate Tax Filing (T2) for Freight Brokers
T2 preparation with the GIFI detail on Schedules 100 and 125, a revenue line matching what your shipper contracts actually say, amounts invoiced ahead of delivery deferred under ITA 12(1)(a), and Schedule 8 depreciation.
Bookkeeping & Accounting for Freight Brokers
Load-level bookkeeping in QuickBooks Online or Xero: shipper rate, carrier rate and spread on every load, accessorials on their own lines, and receivables aged beside payables at each month end.
Payroll Services for Freight Brokers
T4 payroll for dispatch and sales staff, commissions treated as payroll, PD7A remittances on their dates, the T4 Summary agreed to those remittances at February’s close, and WSIB from your first hire.
GST/HST Filing for Freight Brokers
Returns covering 13% HST on domestic brokerage and the accessorials billed with it, input tax credits on operating costs, and the $30,000 four-quarter registration line tracked continuously.
Tax Planning for Freight Brokers
Planning across reserve timing, active profit kept below the $500,000 small business limit at about 12.2% combined, compensation set against the 53.53% top personal rate, and a share sale planned years ahead.
Corporate Catch-Up Filing for Freight Brokers
Unfiled T2 and HST years rebuilt from rate confirmations, carrier invoices and proofs of delivery, filed oldest first, with relief sought on Form RC4288 where the charges were not your doing.
CRA Audit Resolution for Freight Brokers
Full CRA representation on revenue treatment, reserves and accessorial billing, with the load file assembled load by load and an objection filed where an assessment does not match the records.
CPA Financial Statements (Notice to Reader) for Freight Brokers
Compilation engagement statements showing receivables and payables at their real ages and the doubtful-debt reserve account by account, ready for a lender or an insurer reviewing the business.
Incorporation Services for Freight Brokers
NUANS search, articles, share structure and organising records, plus the section 85 rollover on Form T2057 where an existing unincorporated brokerage is being brought in.
Catch-Up Bookkeeping Services for Freight Brokers
We rebuild months of missing load, carrier and banking records so your brokerage books are current, your receivables are aged correctly and your next filing has something behind it.
US Corporation & LLC Tax Filing for Freight Brokers
Cross-border filing for brokerages that have set up a US entity, covering US corporation and LLC returns, the treaty position that fits your presence, and state-level obligations.
Voluntary Disclosure Program for Freight Brokers
A disclosure filed on Form RC199 to correct unreported brokerage fees, HST never charged on domestic loads or years never filed, while the submission is still voluntary.
Accounting & Tax Services Tailored for Freight Brokers
Practitioner-level CPA work for domestic freight brokerages and logistics intermediaries across Ontario — built around margin reporting, the distance between carrier payables and shipper receivables, and the load documents that have to stand behind both.
- We file your T2 with the GIFI detail on Schedules 100 and 125 and a revenue line that matches how your shipper contracts actually read, because a brokerage reporting the wrong figure invites questions the ledger alone cannot answer.
- We settle and document whether you report as principal on the whole amount billed or as agent on the margin alone, since that test turns on the contract and on who carries the risk of the load itself.
- We defer amounts invoiced before a load is delivered under ITA 12(1)(a) and claim the reserve ITA 20(1)(m) allows, so revenue lands in the year the freight moved; one brokerage moved $86,000 into the right year.
- We claim capital cost allowance on Schedule 8 across Class 50 computers at 55%, Class 8 office equipment at 20% and any vehicle in Class 10 at 30%, which on one file produced $7,400 of depreciation nobody had claimed.
- We reconcile every HST period to the T2 before filing, so the revenue reported for income tax and the revenue reported for the 13% tax agree on the page; one brokerage cleared a $14,000 discrepancy that way.
- We post every load as its own record carrying the shipper rate, the carrier rate and the spread between them, so margin is visible load by load rather than arriving monthly as a single figure nobody can take apart.
- We keep detention, layover and lumper charges on their own lines, revenue when billed on and cost when incurred, because netting them into the spread hides which loads lost money; one cleanup exposed $23,000 of unbilled accessorials.
- We age shipper receivables and carrier payables beside each other every month and report days to collect against days to pay, because that distance is the number your growth is actually being financed out of.
- We match the carrier invoice to the rate confirmation and the proof of delivery before it is paid, which on one brokerage caught $11,600 of duplicated and over-billed carrier charges inside a single quarter.
- We run QuickBooks Online or Xero beside your booking system rather than instead of it, so the load list and the ledger carry the same loads at the same amounts when the month closes.
- We put dispatch and sales staff on T4 payroll, we withhold at source and remit on the PD7A, and we agree every slip and the T4 Summary to those remittances before the February filing date arrives.
- We treat sales commissions paid to employees as the payroll they are rather than as something sitting outside it, so withholding and deduction both land properly; one brokerage corrected $61,000 of commissions booked the wrong way.
- We register WSIB from your first hire rather than from the first time somebody asks, and we watch the Ontario Employer Health Tax line, which starts to bite above $1,000,000 of payroll in a calendar year.
- We keep remittances on their due dates because the late-remittance penalty is graduated and climbs, reaching 10% at the top of the scale; getting one file current removed a recurring charge worth $4,800 a year.
- We separate owner compensation from staff payroll, so the T4 you draw as a shareholder is planned against the dividend you draw instead of being whatever the operating account happened to allow that month.
- Arranging domestic carriage is a taxable supply, so we charge and report 13% HST in Ontario on your brokerage fee and on the accessorial amounts billed with it, with nothing on the invoice quietly treated as outside the tax.
- We track taxable revenue against the $30,000 line measured across four consecutive calendar quarters, so you register in the quarter you cross it rather than discovering it a year later in the middle of a cleanup.
- We claim input tax credits on software, rent, phones, credit reports, professional fees and vehicle costs, which on one brokerage recovered $9,300 of tax that had simply never been claimed on any return.
- We file on the frequency CRA assigns you and reconcile each period to the ledger before it goes out, so the return agrees with the revenue you will report on the T2 rather than contradicting it months later.
- We correct periods already filed where accessorials went out without tax or credits were claimed on costs that were not business costs, because a voluntary correction costs far less than the same adjustment found later.
- We hold active profit under the $500,000 small business limit, where the combined Ontario rate runs near 12.2%, because a brokerage reporting the whole billed amount rather than the margin reads very differently against that ceiling.
- We time the ITA 20(1)(l) doubtful-debt reserve and the ITA 20(1)(p) write-off as two separate decisions in two separate years, which on one file pulled $48,000 of deduction into the year where it actually belonged.
- We plan compensation against the 53.53% top personal rate in Ontario, splitting salary and dividends so the money you genuinely need reaches you at the lowest combined cost rather than by default at year-end.
- We plan a share sale early enough that the $1.25M lifetime capital gains exemption under ITA 110.6 is available when you want it, instead of finding the conditions unmet in the month a buyer finally appears.
- We treat the payable cycle as a tax question too, because paying carriers faster than you collect changes when deductions land and can leave you with a taxable profit and no cash standing behind it.
- We rebuild unfiled years from the load records themselves — rate confirmations, carrier invoices and proofs of delivery — rather than from bank deposits, so the revenue figure can be supported line by line.
- We file the oldest outstanding T2 first so arrears stop compounding on the largest balance, working in order rather than filing whichever year happens to be easiest to assemble from what survived.
- We reconstruct the HST periods alongside the T2 years, because a brokerage that stopped filing one usually stopped filing both; one catch-up covered four years and $118,000 of previously unreported brokerage fees.
- We apply for relief on Form RC4288 where penalties and interest followed a prior adviser’s error or circumstances outside your control, which on one brokerage file removed $7,900 of accumulated charges.
- We build the bookkeeping as we go, so the catch-up ends with a system that stays current rather than a tidy set of old years followed by exactly the same drift.
- We assemble the load file a review asks for: the rate confirmation, the load confirmation, the carrier invoice and the proof of delivery, matched load by load rather than handed over as four unrelated stacks of paper.
- ITA 230 holds you to those records for a full six years, and we keep them in a shape that can be handed over on request, because most of what a review costs is the cost of reassembling what was never filed properly.
- ITA 152(7) means a filed return is not the last word: an assessment can be raised on another footing where the load documents do not carry the figures, and overturning it is then your burden. We build the support that carries it.
- We answer the revenue question with documents, showing which contracts put the whole billed amount on your books and which leave only the margin, so the treatment is evidenced rather than argued in the abstract.
- We file the objection where an assessment is wrong and seek relief on Form RC4288 where the charges arose from something other than your own choices; one brokerage had $16,200 of penalties and interest cancelled.
- We prepare compilation engagement statements carrying shipper receivables and carrier payables at their real ages, so a reader sees the working-capital gap instead of one net figure that conceals it entirely.
- We present the doubtful-debt reserve account by account rather than as a round percentage of receivables, because whoever lends against your book wants to know which shippers are the ones in question.
- We show the revenue line on the basis your contracts support, since the figure a reader prices a renewal against is the one printed on the statement rather than the one offered in conversation.
- We tie the statements to the T2 and the HST returns so all three tell one story, which on one brokerage removed a financing condition the lender had been pricing at $6,000 a year.
- We turn the statements around inside a working week once your records are complete, because a lender or an insurer who asks for them rarely gives a brokerage a full month to produce them.
- We work out whether incorporating pays at your profit level before anything is filed, weighing an Ontario combined rate near 12.2% below the $500,000 small business limit against a 53.53% top personal rate.
- We complete the incorporation itself — NUANS search, articles, share structure and the organising records — with a share structure that leaves room for the exemption and for a future buyer.
- We roll an existing unincorporated brokerage in under section 85 on Form T2057, electing amounts that defer the gain on your book of shipper relationships rather than triggering it on the way through the door.
- We set the opening balance sheet up so shipper receivables and carrier payables transfer cleanly, because a brokerage incorporating mid-year almost always has more of both outstanding than anyone expected.
- We register the payroll, HST and corporate accounts together and file the first short-year T2 on time, which on one new brokerage avoided $3,200 of penalties on a filing that was nearly missed entirely.
- We rebuild months of missing records load by load from rate confirmations, carrier invoices and proofs of delivery, so what comes out is a file you can hand to a lender rather than a reconstructed guess.
- We re-age every shipper receivable and carrier payable as at each month end, which on one brokerage surfaced $31,000 of completed loads that had never been invoiced to the shipper at all.
- We separate detention, layover and lumper amounts back out of the revenue line where they had been netted, so margin by lane is visible again the moment the catch-up work is finished.
- We reconcile the bank against the load list rather than against the deposits, because a brokerage receives money in batches that bear no tidy relationship to the loads that generated them.
- We finish by setting a monthly close so the same gap cannot reopen, handing you a short checklist and a working system instead of a box of carefully restored history.
- We file the US corporation and LLC returns a brokerage picks up once it sets up south of the border, and we make certain the Canadian and US returns describe one brokerage income rather than two different ones.
- We treat an LLC the way Canada treats it rather than the way its US paperwork reads, because the mismatch between the two systems is where brokers most often finish up taxed twice on a single margin.
- We take the Canada-United States treaty position that fits your actual presence, so profit is reported where the work is genuinely done instead of being claimed in both places and defended properly in neither.
- We line the US filing calendar up with your T2 so credits claimed in one country match tax actually paid in the other, which on one brokerage recovered $12,800 of double-counted tax.
- We handle the state-level obligations that follow from holding a US entity, and we tell you plainly where a structure is costing more in compliance work than it will ever save you in tax.
- We lodge the Voluntary Disclosures Program submission on Form RC199 while you still can, because the relief exists only for a disclosure that is genuinely voluntary and closes off the moment a review opens.
- We confirm the disclosure is complete and reaches a year at least one year past due, since an incomplete submission can be turned away and leaves you worse placed than before you ever filed it.
- We disclose brokerage fees that never reached a return and HST never charged on domestic loads, reconciling the shortfall load by load; one brokerage regularised $142,000 of unreported margin this way.
- We fold the payroll side into the same submission where dispatch or sales wages went out without withholding, so the correction is complete rather than inviting a second look at years just accepted.
- We present the disclosure with its supporting load documents attached, because a submission arriving with its own evidence is resolved on the numbers; one file closed with $21,400 of penalties relieved.
Freight Broker Margin & Cash-Gap Check
Six questions on your revenue basis, the distance between paying carriers and collecting from shippers, accessorial reporting, the doubtful-debt reserve, your load records and whether it is time to incorporate. No fee shown.
1. Does your revenue line report the basis your shipper contracts actually support, rather than whatever the software produced?
2. Do you know your days to collect from shippers against your days to pay carriers for this month?
3. Are detention, layover and lumper charges reported on their own lines rather than netted into the margin?
4. Is there a doubtful-debt reserve on the books where a shipper receivable is genuinely in question?
5. Can you produce the rate confirmation, carrier invoice and proof of delivery for any load from the last six years?
6. Is your freight brokerage incorporated?
Free CPA Consultation for Freight Brokers
Case Studies: Freight Broker Accounting & Tax
Cambridge Freight Brokerage — The Gap Nobody Had Measured
The problem: A Cambridge brokerage booking roughly $400,000 a month of carrier charges paid its carriers on two-day terms and collected from shippers on forty-five. The T2 showed a profit every year while the operating account ran empty every month, and nobody could say how much of its own cash sat permanently tied up in delivered freight.
What we did: We aged shipper receivables and carrier payables beside each other each month end, reported days to collect against days to pay, and rebuilt the close so both numbers arrived together. Amounts invoiced ahead of delivery moved into the year the freight ran, under ITA 12(1)(a) with the reserve ITA 20(1)(m) allows.
The result:
- Several hundred thousand dollars identified as permanently funded
- $86,000 of revenue landed in the year the freight ran
- Collection cycle shortened by eleven days across two quarters
Woodstock Freight Brokerage — A Shipper Failed, the Carriers Still Billed
The problem: A Woodstock brokerage lost a produce shipper owing $74,000 across nineteen delivered loads. The carriers had been paid within days and their invoices were never in question. The previous bookkeeping wrote the whole amount off in one entry in one year, claiming a deduction the records could not yet support.
What we did: We separated the two events the rules keep apart: a reserve under ITA 20(1)(l) for the year collection was genuinely in doubt, and an ITA 20(1)(p) deduction taken account by account only as recovery failed. Support was rebuilt from the rate confirmations, carrier invoices and proofs of delivery.
The result:
- $74,000 of bad debt deducted in the correct years
- Reserve and write-off documented as two separate entries
- $9,600 of exposure removed from an earlier filed year
Belleville Freight Brokerage — Accessorials Buried in the Spread
The problem: A Belleville brokerage billed detention, layover and lumper charges to shippers and absorbed the matching costs, then posted both to a single revenue line. Monthly margin looked steady, but nobody could tell which lanes were carrying the accessorials and which were quietly losing money on them, and load paperwork lived in three separate places.
What we did: We split accessorial revenue and accessorial cost onto their own lines, costed every load with its own carrier charge, and built one load file holding the rate confirmation, the load confirmation, the carrier invoice and the proof of delivery together for the whole six-year period ITA 230 sets.
The result:
- Margin visible on every load and every lane
- Accessorials revenue when billed, cost when incurred
- Load records retrievable from one place for the full period
Our clear, efficient process ensures every step is transparent, building trust and long-term client relationships.
Kickoff (Document Request)
Collect prior T2 and HST returns, the shipper contracts and rate agreements, a month of rate confirmations, carrier invoices and proofs of delivery, the receivable and payable ageings, payroll records and bank statements.
First 30 Days (Cleanup & Setup)
Set up QuickBooks Online or Xero beside your booking system, build the revenue basis your contracts support, separate accessorial revenue from accessorial cost, and configure payroll, WSIB and the HST filing calendar.
Monthly Close
Monthly reconciliations, margin by load, shipper receivables aged beside carrier payables, days to collect reported against days to pay, and 13% HST on domestic brokerage with input tax credits claimed.
Quarterly Planning Review
Compensation mix, the doubtful-debt reserve reviewed account by account, the revenue line checked against the small business limit, and the cash position sitting behind the reported profit.
Year-End Close & T2 Filing
Trial balance, statements showing receivables and payables at their real ages, revenue deferred under ITA 12(1)(a), Schedule 8 depreciation, and the T2 with GIFI filed on time.
Get Your Freight Brokerage Taxes Done Right Today
Affordable Pricing for Freight Brokers
We believe in clear, upfront pricing so you know exactly what to expect. All fees include HST.
- Tax Preparation (Corporation) — From $400
- Tax Return Filing (Corporation) — From $400
- Tax Compliance Audit — FREE CRA audit support for our clients
- Tax Strategy — FREE for our clients
- Accounting Base Plan — From $100 per month
- Bookkeeping Management — Free for our Accounting clients
- Financial Reporting — Free for our Accounting clients
- Business Formation — Flat $35
- Incorporation Process — Flat $35
- Entity Setup Assistance — Flat $35
- Full-Service Payroll — From $125 per month
Payment is by Interac e-Transfer to info@gondaliyacpa.ca only. Security question: Not Applicable, as auto-deposit is enabled.
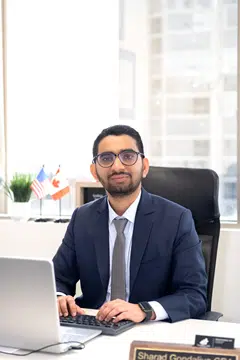
Meet Your Lead Freight Broker Accountant
Meet your lead freight broker accountant. The same two people handle your brokerage every year, from the monthly margin reporting through to the T2.
What Our Clients Say
1300+ five-star reviews from freight brokerage, logistics and transportation business owners across Ontario and Canada.
Serving Freight Brokers Across Ontario
Our CPA team works with freight brokerages throughout Ontario. We understand how a margin business funded by somebody else’s working capital actually behaves: what the revenue line is allowed to contain, how quickly carriers have to be paid against how slowly shippers pay, when a shipper receivable becomes a reserve and when it becomes a deduction, and which load documents have to stand behind all of it.
Toronto (ON)
55 Queen St E Ste 1205, Toronto, ON M5C 1R6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Mississauga (ON)
5373 Bullrush Dr, Mississauga, ON, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Brampton (ON)
4 Starhill Crescent, Brampton, ON L6R 2P9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Scarborough (ON)
24 Clementine Square, Scarborough, ON M1G 2V7, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Vaughan (ON)
19 Cabinet Crescent, Woodbridge, ON L4L 6H9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Oshawa (ON)
210 Durham St, Oshawa, ON L1J 5R3, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Ottawa (ON)
2090 Neepawa Ave a314, Ottawa, ON K2A 3L6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Etobicoke (ON)
60 Stevenson Rd #1601, Etobicoke, ON M9V 2B4, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Hamilton (ON)
70 Starling Dr, Hamilton, ON L9A 0C5, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Guelph (ON)
1155 Gordon St, Guelph, ON N1L 1S8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Windsor (ON)
4387 Guppy Ct, Windsor, ON N9G 2N8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
North York (ON)
150 Graydon Hall Dr #912, North York, ON M3A 3B2, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Freight Broker Accounting & Tax FAQs
Related Industries We Serve
Freight Forwarders
- Revenue recognition across movement legs
- T2 filing, GIFI and HST returns
- Payables, receivables and bookkeeping
Specialized Haulers
- Heavy equipment depreciation and disposals
- Load costing and HST filing
- Corporate tax planning and payroll
Fleet Owners
- Vehicle depreciation pools and financing
- Per-unit costing and HST returns
- Corporate filing, payroll and bookkeeping
Factoring Companies
- Fee and interest income reporting
- Receivable portfolio accounting
- T2 corporate returns and HST filing
Freight Broker Accounting & Tax Done Right.
T2 filing with a revenue line your shipper contracts actually support, margin reported load by load, shipper receivables aged against carrier payables, doubtful-debt reserves under ITA 20(1)(l) kept separate from write-offs under ITA 20(1)(p), 13% HST on domestic brokerage with input tax credits, detention, layover and lumper charges reported where they can be seen, and T4 payroll for dispatch and sales staff with WSIB from the first hire. AFFORDABLE flat fees, no hourly billing. Licensed CPA Ontario. 1300+ five-star reviews. 30-Day Money-Back Guarantee.