



The Ultimate Guide to Insurance Agent Taxes and Accounting in Canada
Insurance agent taxes Canada explained: commission income, exempt supplies, chargebacks and corporate filing
Insurance agent taxes Canada require careful management of commission income, corporate tax filing, and eligible deductions like licensing fees and marketing costs. Gondaliya CPA offers expert insurance agent tax planning, bookkeeping, and accounting services to handle GST/HST on commission, financial statements, payroll slips, and CRA representation for licensed agents, brokers, and agency owners.
Quick Summary
The $30,000 small supplier threshold counts taxable supplies only, so exempt commissions are excluded from it entirely. The exemption lives in Schedule V, Part VII, not in section 123(1) or section 165. And a shareholder loan is caught by subsection 15(2) unless repaid within one year after the corporation’s year-end.
Reading time: 48 minutes.
Table of Contents
- Three Things You Have Been Told
- Commission Income and Obligations
- Bookkeeping and Financial Statements
- Tax Planning Strategies
- Corporate and Business Taxes
- GST/HST Registration and Compliance
- Professional Accounting Services
- Frequently Asked Questions
- Essential Topics and Best Practices
- Businesses We Serve
- Professional Guidance and Quick Reference
The Numbers That Matter
This article covers Canada, with Ontario and Toronto context, and reflects rules current to 30 September 2026. It is written for licensed insurance agents, brokers, agency owners, dual-licensed advisors and managing general agencies, whether operating personally or through a corporation. Gondaliya CPA performs compilation engagements; we do not perform audits or review engagements, and where a lender or regulator requires one we refer it out. Figures marked illustrative are examples, not quotes, and any masked engagement notes end with “Figures changed for privacy.” This is educational information only and not tax or legal advice. Provincial licensing and rules differ, so please confirm the position where you operate.
Three Things You Have Been Told
Three Things You Have Been Told
The Corrections
Three points about insurance agent taxes circulate widely and all three are wrong. The first can push an agent into a registration they never needed.
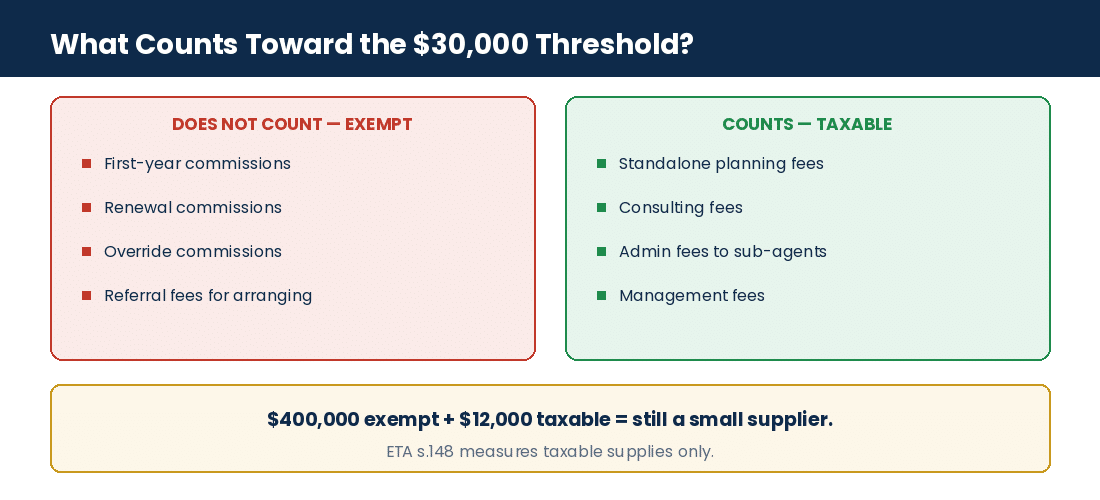
Exempt Commissions Do Not Count Toward $30,000
Risk Warning: the small supplier threshold counts taxable supplies only. Guidance stating that you must register once “total revenue from all sources exceeds $30,000 a year, including exempt and taxable activities combined” is describing a test that does not exist.
Section 148 of the Excise Tax Act measures taxable supplies made worldwide. Exempt commission income is excluded from the calculation entirely. An agent earning $400,000 of exempt commissions and $12,000 of taxable consulting fees is still a small supplier and is not required to register.
| Revenue | Counts toward $30,000? |
|---|---|
| First-year and renewal commissions on arranging insurance | No — exempt |
| Override commissions from an MGA | No — exempt |
| Referral fees for arranging a financial service | No — exempt |
| Standalone financial planning or consulting fees | Yes — taxable |
| Administrative or management fees charged to sub-agents | Yes — taxable |
Section 165 Imposes Tax, It Does Not Exempt Anything
Two provisions get cited for the exemption and neither is it. Section 123(1) contains the definition of “financial service”. Section 165 is the charging provision — it imposes GST/HST. Neither exempts a supply.
The exemption is in Schedule V, Part VII, which lists exempt financial services. Arranging for the issuance of an insurance policy falls within the definition in 123(1) and is then exempted by Schedule V. Citing section 165 as the source of an exemption is citing the rule that does the opposite.
Shareholder Loans Turn on a Date, Not an Agreement
Risk Warning: subsection 15(2) does not require a formal agreement stating terms. It includes the loan in the shareholder’s income in the year it was made, unless an exception applies.
The exception most agency owners rely on is subsection 15(2.6): the loan is repaid within one year after the end of the corporation’s taxation year in which it was made, and the repayment is not part of a series of loans and repayments. For a 31 December year-end, a loan taken in March 2026 must be repaid by 31 December 2027. A written agreement is good practice and proves nothing about 15(2).
Separately, section 80.4 imputes an interest benefit on any outstanding balance at the prescribed rate, reduced by interest actually paid within 30 days of the year-end.
A Toronto life agent registered for GST/HST on the strength of roughly $380,000 in commissions, having been told the threshold counted all revenue.
The commissions were exempt and none of it counted. Taxable fee work came to about $8,000, well under the threshold. Deregistering meant charging clients nothing on fees and, because input tax credits were only ever available on the taxable portion, almost nothing was lost. Figures changed for privacy.
Understanding Insurance Agent Taxes and Accounting in Canada
Commission Income and Obligations
Foundations
How Commission Income Is Taxed for Insurance Agents
Commission income is business income under section 9, included when it becomes receivable under paragraph 12(1)(b) rather than when the cheque lands. That covers first-year commissions, renewals, overrides, bonuses and referral fees alike.
Business income is computed on the accrual basis. The cash method in section 28 is confined to farming and fishing, so “when received or earned” is not a choice an agent gets to make.
Income Reporting Requirements for Independent Agents and Incorporated Agencies
- Independent agents report on the T1, with business income on form T2125.
- Incorporated agencies file a T2 with GIFI Schedules 100, 125 and 141.
- Carrier statements reconciled to reported income each period, since mismatches are a standard review trigger.
- First-year, renewal, override and referral commissions tracked separately — they behave differently in the year they arise and on any chargeback.
Difference Between Sole Proprietorship and Incorporated Agent Filings
| Aspect | Sole proprietor | Corporation |
|---|---|---|
| Return | T1 with T2125 | T2 with GIFI |
| Rate | Personal marginal | 12.2% Ontario combined on small business income; 26.5% general |
| Filing due | 15 June, balance 30 April | Six months; balance at two or three months |
| Liability | Unlimited personal | Limited to corporate assets |
| Home workspace | Claimed under ITA 18(12) | Rent paid under a written agreement |
Common Filing Documentation Needed
- T1 with T2125, or T2 with compiled financial statements and GIFI.
- Carrier commission statements, including advance and chargeback notices.
- T4A slips received from carriers or agency owners.
- Receipts for licensing, continuing education, marketing and office costs.
- Vehicle logbooks and home workspace measurements.
Insurable vs Non-Insurable Revenue and GST/HST Application
Arranging for the issuance of an insurance policy is an exempt financial service — defined in section 123(1) and exempted by Schedule V, Part VII. Commission on that activity carries no GST/HST.
Standalone advice, financial planning or administration charged as a separate fee is a taxable supply. The line is what you were actually paid to do, not what licence you hold while doing it.
Key Stat: Making exempt supplies is not commercial activity under section 123(1). That is why input tax credits are restricted — section 169 allows them only to the extent an input is used in commercial activity.
GST/HST Remittance and Reporting Deadlines
| Annual taxable supplies | Assigned frequency | Filing and payment due |
|---|---|---|
| $1.5 million or less | Annual | Three months after fiscal year-end |
| Over $1.5 million to $6 million | Quarterly | One month after quarter-end |
| Over $6 million | Monthly | One month after month-end |
Frequency is assigned by threshold, not chosen. Describing registrants as remitting “usually quarterly” misses that most agents with any taxable fee work will be annual filers.
Eligible Insurance Agent Tax Deductions and Business Expenses Explained
- Provincial licensing fees and regulatory levies.
- Errors and omissions insurance premiums.
- Association and professional dues — though paragraph 18(1)(l) denies dues for a club whose main purpose is dining, recreation or sport.
- Marketing, advertising and client development.
- Office supplies, software and communications.
- Travel and vehicle costs on the business-use share.
- Continuing education maintaining a licence; a programme conferring a lasting new qualification may be capital.
Bookkeeping and Financial Statement Preparation for Insurance Agents
Bookkeeping and Financial Statements
Bookkeeping
Importance of Accurate Bookkeeping in Managing Insurance Agent Finances
An agent’s ledger has to carry four things that an ordinary service business does not: commission by type, advances, chargebacks, and the split between exempt and taxable revenue. Mixing first-year commissions with renewals, or netting a chargeback against income rather than deducting it, produces a number that will not reconcile to the carrier statement.
Tracking Licensing Fees, Marketing Costs, and Continuing Education Expenses
| Expense | Deductible? | Record | Authority |
|---|---|---|---|
| Licensing fees | Yes, fully | Receipt or invoice | ITA 18(1)(a) |
| Marketing and advertising | Yes, fully | Invoice | ITA 18(1)(a); s.67 |
| Meals and entertainment at client events | 50% | Receipt with attendees and purpose | ITA 67.1 |
| Conference fee including unstated meals | $50/day deemed meals, then 50% | Registration and agenda | ITA 67.1(3) |
| Continuing education maintaining a licence | Yes | Registration and payment | ITA 18(1)(a) |
| E&O insurance | Yes, over the policy period | Policy and invoice | ITA 18(9) |
Section 67.1 is the meals limitation. Section 67.2 is the $350 monthly cap on vehicle loan interest — a different rule entirely, frequently cited in its place.
Handling Payroll Slips, Shareholder Loans, and Agency Owner Financials
- T4 slips for employees, with CPP and EI withheld and remitted by your remitter band.
- T4A slips for sub-agents and contractors where fees for services exceed $500 in the calendar year.
- Note that T5018 does not apply here — it is the construction subcontractor return and has no application to an insurance agency.
- Both slip types due by the last day of February under Regulation 205(1).
- Shareholder loans tracked against the 15(2.6) deadline, with the 80.4 interest benefit calculated on any balance.
- Owner draws coded as salary, dividend or loan at the time — not sorted out in June.
Preparing and Understanding Insurance Agent Financial Statements
Risk Warning: a compilation engagement provides no assurance. Describing it as adding trust over a do-it-yourself version, or as checking internal consistency, overstates what CSRS 4200 actually delivers.
A compilation assembles information supplied by management into financial statement form, with a basis of accounting note and a compilation engagement report stating that no assurance is provided. It is the right engagement for most agencies and it is not a light audit. Where a lender or regulator needs assurance, that is a review under CSRE 2400 or an audit, and we refer those out.
- Income statement: commissions by type, fee income, operating costs.
- Balance sheet: receivables from carriers and sub-agents, unearned advances as a liability, shareholder loan balances, owner equity.
- Cash flow statement under ASPE 1540, where presented.
- A purchased book of business on the balance sheet as Class 14.1 property.
Utilizing Bookkeeping To Support CRA Representation And Audit Readiness
- Commission slips matched to reported income, line by line.
- The exempt and taxable split documented against Schedule V, Part VII.
- An advance and chargeback log showing date, amount, policy and repayment.
- Carrier T4A slips reconciled before filing, not after a mismatch letter arrives.
- Records retained six years from the end of the taxation year to which they relate, under paragraph 230(4)(b).
An agency owner had been treating every draw as a shareholder loan and clearing it “whenever there was cash”.
Two balances sat past the 15(2.6) window and were includable in income under subsection 15(2) for the year the loans were made — with no deduction on eventual repayment for one of them, because the timing had gone. Recoding the draws as salary going forward, with the loan account cleared inside the window, fixed it prospectively. Figures changed for privacy.
Tax Planning Strategies Specific to Canadian Insurance Agents
Tax Planning Strategies
Planning
Planning Around Chargebacks, Policy Lapses, and Advance on Commission
A commission advance is included in income when it becomes receivable or is received on account of commissions, and a later chargeback is deducted in the year the repayment obligation arises — not by amending the year the advance was reported.
Key Stat: the chargeback lands in a later year only if it actually falls in one. An advance received on 15 January 2026 is 2026 income. A cancellation six months later is July 2026 — the same taxation year, with the deduction in the same return.
A worked example putting the advance in 2026 and the chargeback in 2027 has quietly moved six months into eighteen. The year in which the repayment obligation arises is what decides it, and for a December year-end that is usually the same year.
- A chargeback log with date, policy, amount advanced, amount repaid and the carrier notice.
- Repayments recorded as a deduction, never netted against gross commission income.
- Unearned advances shown as a liability where the carrier can reclaim them.
- Policy lapse patterns reviewed before year-end, since a wave of lapses changes the reserve position.
Managing Dual-Licensed Advisors, Sub-Agents, and Managing General Agency Setups
- Dual-licensed advisors: commissions split by activity. Arranging insurance and arranging mutual fund trades are both exempt financial services; a separately charged planning fee is taxable.
- Sub-agents: tested on the Wiebe Door factors as refined in Sagaz and Connor Homes, with CRA Guide RC4110 and a ruling available on Form CPT1. Contractors receive a T4A; employees a T4 with source deductions.
- MGAs: override commissions tracked by source, since they arrive from a different payer than the agent’s own production and reconcile to a different statement.
- Agreements on file setting control, tools, risk of loss and the right to subcontract.
Incorporating Motor Vehicle Expenses, Logbooks, and Home Workspace Claims
Risk Warning: the home workspace does not have to be used only for work. Subsection 18(12) gives two alternative tests. Test (a), the individual’s principal place of business, carries no exclusivity requirement. Only test (b) — exclusive use plus regular client meetings — does.
The real limit is that the deduction cannot create or increase a loss, with the excess carried forward. And 18(12) applies to an individual: an incorporated agency pays rent to the shareholder under a written agreement instead.
- A logbook with date, destination, purpose, kilometres and odometer readings.
- The simplified method: a full base year, then a three-month sample in later years, provided business use stays within 10 percentage points of the base year.
- Vehicle limits: $1,100 monthly lease, $39,000 in Class 10.1, $61,000 in Class 54, $350 monthly loan interest under section 67.2.
- Home costs apportioned by area: utilities, insurance, maintenance, rent, and mortgage interest and property tax for an owner. Principal is not an expense at all.
- Travel between home and a regular place of business is personal.
Addressing Client Event Meals, Association Dues, and Errors & Omissions Coverage
Meals and entertainment are limited to 50% by section 67.1, with the input tax credit recaptured to 50% for registrants. Where a conference or seminar fee includes food or entertainment that is not separately stated, subsection 67.1(3) deems $50 per day to be for food, and that amount is then subject to the 50% limit.
Association and licensing body dues are fully deductible where required or reasonably related to the practice. E&O premiums are deductible over the period the policy covers, with subsection 18(9) pushing the portion relating to a later year forward.
Benefits of Proactive Insurance Agent Tax Planning
- The registration question settled before you register unnecessarily.
- The exempt and taxable split documented, so input tax credit claims match taxable use.
- Advance and chargeback timing scheduled rather than reconstructed.
- Shareholder loan balances cleared inside the window.
- A flat annual fee including HST covering bookkeeping, the compilation, the T2 and any GST/HST filing.
Corporate and Business Taxes for Insurance Agencies
Corporate and Business Taxes
Corporate
Distinction Between Personal and Corporate Tax Obligations, and When to File as Each
Commissions earned personally are reported on the T1 with form T2125 at personal marginal rates. Commissions earned by a corporation are reported on the T2 at corporate rates — 12.2% combined in Ontario on active business income within the small business deduction limit of $500,000, and 26.5% above it.
Two grinds reduce that limit: taxable capital employed in Canada between $10 million and $50 million under subsection 125(5.1), and adjusted aggregate investment income above $50,000, eliminating the limit at $150,000. Associated corporations share one limit under section 256.
Salary vs Dividend Compensation Structures
| Feature | Salary | Dividend |
|---|---|---|
| Deductible to the corporation | Yes | No |
| CPP | Payable, both shares | None |
| RRSP room | Creates it | None |
| Slip | T4 | T5 |
| Paid to family | Must be reasonable for work done | TOSI under section 120.4 applies |
That last row matters for agency owners. Section 120.4 taxes split income at the top marginal rate unless an exclusion applies, and the excluded shares test is unavailable where 90% or more of the corporation’s income comes from services. An insurance agency is a services business, so the usual route out is the excluded business test — an average of 20 hours a week in the business — or a reasonable salary for work actually performed.
T2 Return Process and Timelines
| Obligation | Deadline | Provision |
|---|---|---|
| T2 return | Six months after fiscal year-end | ITA 150(1)(a) |
| Balance of tax | Two months; three for a CCPC claiming the SBD | ITA 157(1)(b) |
| Corporate instalments | Last day of each month or quarter | ITA 157(1)(a), 157(1.1) |
| Electronic filing | Mandatory for most corporations | ITA 150.1(2.1) |
| Ontario Annual Return | Six months after year-end | Ontario Business Registry |
The three-month payment window is not about “active status”. It applies to a CCPC claiming the small business deduction with taxable income within the business limit. And mandatory electronic filing is a federal requirement that has applied since 2024 — not a new Ontario rule starting in 2026.
Filing Corporate Taxes Including Compilations and Catch-Up Filings
| Event | Treatment | Records needed |
|---|---|---|
| Late incorporation | File all missing returns, oldest first | Carrier statements and expense documents |
| Missed prior year filing | Submit catch-up returns in sequence | Rebuilt ledgers and invoices |
| Penalty and interest exposure | Relief may be requested | Form RC4288, within ten years |
Filing oldest year first matters because opening balances, loss carryforwards and CCA pools flow between years. Relief from penalties and interest is available under subsection 220(3.1) on Form RC4288, within ten calendar years.
Purchase of a Book of Business
A purchased book of business is Class 14.1 property at 5% declining balance. Eligible capital property, where these assets once sat, was abolished on 1 January 2017. Incorporation costs are separately deductible to $3,000 under paragraph 20(1)(b), with any excess to Class 14.1.
Key Compliance Requirements and Penalties
Risk Warning: the late filing penalty is not “5% then up to 12% annually”. Subsection 162(1) charges 5% of the unpaid tax at the filing due date plus 1% per complete month the return is late, to a maximum of twelve months — a ceiling of 17%, not 12% a year.
Where CRA issued a demand and a penalty was charged in any of the three prior years, subsection 162(2) doubles it: 10% plus 2% per month to twenty months. Both are penalties on unpaid tax, so a nil return filed late attracts no 162(1) penalty. Interest under subsection 161(1) is separate and compounds daily.
- Exempt commissions separated from taxable fees in the ledger and on the return.
- Payroll remitted by your band under section 153 and Regulation 108, with penalties under 227(9) from 3% to 10% and director liability under 227.1.
- Instalments paid on the last day of the month or quarter, with none required below $3,000 of taxes payable or in a first taxation year.
- Source documents held six years from the year-end under paragraph 230(4)(b).
Common Pitfalls and How to Avoid Costly Mistakes in Corporate Tax Filings
- Claiming input tax credits on costs relating to exempt commission activity.
- Netting chargebacks against income instead of deducting them in the right year.
- Failing to issue T4A slips for sub-agent payments above $500.
- Vehicle claims with no logbook to support the business-use percentage.
- Personal and corporate transactions run through one account.
- Renewal commissions recognised in the wrong period.
- Shareholder loans left outstanding past the 15(2.6) window.
- Home workspace abandoned because of a supposed exclusivity requirement that test (a) does not impose.
- A purchased book of business expensed rather than added to Class 14.1.
- Instalments missed because the payment date was read as the filing date.
Frequent Errors in Filings and How to Prevent Them
Prevention is procedural rather than clever: code revenue as exempt or taxable at entry, reconcile carrier statements every period, run a monthly shareholder loan schedule, keep the vehicle log as you drive, and diarise the payment date separately from the filing date. Most of the list above disappears when those five habits are in place.
A brokerage had been filing its T2 at the six-month mark and paying the balance at the same time for years.
The balance had been due at three months throughout. Nothing was late in filing terms, but arrears interest had been compounding on a three-month gap every year. Moving the payment forward and requesting relief under 220(3.1) closed it. Figures changed for privacy.
GST/HST Registration Thresholds and Voluntary Registration
GST/HST Registration and Compliance
GST/HST
When Insurance Agencies Must Register for GST/HST
Registration under subsection 240(1) is required once you cease to be a small supplier under section 148 — and section 148 measures taxable supplies only. Exempt commissions are outside the calculation.
| Route across the threshold | When small supplier status ends | Time to register |
|---|---|---|
| Over $30,000 in a single calendar quarter | Immediately, on the supply that crosses it | 29 days |
| Over $30,000 across four consecutive quarters | End of the month after that quarter | One further month |
An agent whose taxable fee work never reaches $30,000 is not required to register, however large the commission book. Registering anyway is a choice, not an obligation, and it carries consequences.
Voluntary Registration Benefits and Risks
- Benefit: input tax credits on inputs used in commercial activity — which for most agents is only the taxable fee side.
- Risk: you must charge and remit on all taxable supplies, file on your assigned frequency, and defend the allocation.
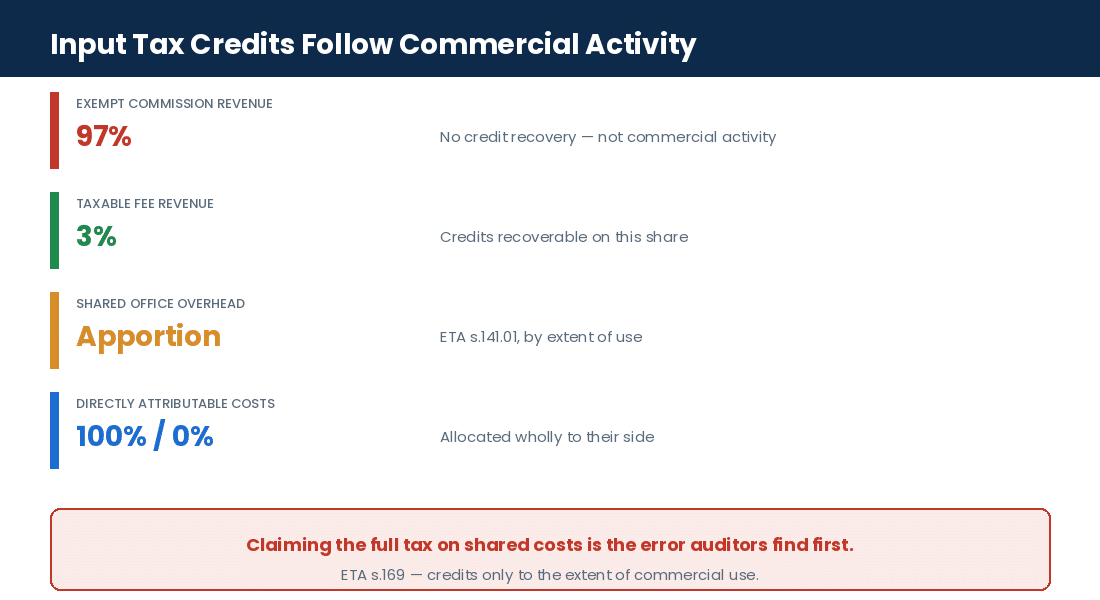
- The allocation: section 141.01 requires inputs to be apportioned by the extent of use in making taxable supplies. An agent with 3% taxable revenue recovers roughly 3% of the tax on shared overhead, not all of it.
- The arithmetic: if taxable fees are small, the recoverable credits are small too, and the compliance cost often exceeds them.
Risk Warning: input tax credits are the most common reassessment on an insurance file. Section 169 allows a credit only to the extent an input is acquired for consumption or use in commercial activity, and making exempt supplies is expressly excluded from commercial activity by section 123(1).
So the office rent, the software and the phone bill of an agent earning 97% exempt commissions are 97% unrecoverable. Claiming the full tax on shared costs is the error auditors find first, and it comes back with interest.
Mixed Activity Apportionment
- Revenue coded exempt or taxable at entry, not sorted at year-end.
- A documented, consistent allocation method under section 141.01, applied to shared inputs.
- Directly attributable inputs allocated in full to the side they belong to.
- Input tax credit support under subsection 169(4): over $30 the supplier’s name and date, over $150 the supplier’s registration number, the recipient’s name, terms and a description.
- Credits claimed within the four-year window.
A general insurance brokerage with about 4% of revenue from taxable administration fees had been claiming input tax credits on the full office overhead.
Section 141.01 allowed roughly 4% of it. The reassessment covered three years plus interest. Rebuilding the allocation and applying it consistently forward resolved the position, and the small recoverable amount turned out not to justify staying registered at all. Figures changed for privacy.
Leveraging Professional Accounting Services for Insurance Agents
Professional Accounting Services
Services
Overview of Insurance Agent Accounting and Bookkeeping Offerings
Books kept in QuickBooks Online or Xero with commission coded by type, advances and chargebacks logged against policies, licensing and education costs captured, and the exempt and taxable split maintained from entry rather than reconstructed. A flat annual fee including HST covers bookkeeping and compiled financial statements under ASPE, prepared as a CSRS 4200 compilation.
How Expert Tax Advisory Supports Financial Health and Growth
- The registration question answered on the real threshold before you register.
- Deductions identified across licensing, E&O, marketing, vehicle and workspace.
- Input tax credits apportioned under section 141.01, so the claim survives review.
- Advance and chargeback timing planned against the year-end.
- Instalments set so a variable commission year does not produce arrears interest.
Role of Professional Accounting in Managing Complex Commission Structures
Commission reconciles to the carrier statement or it does not. Separating first-year from renewal, override from own production, and exempt arranging from taxable fee work is what makes a reconciliation possible — and what makes the GST/HST position defensible. Chargebacks are deducted when the repayment obligation arises, with the log to show it.
Support with Tax Filing, CRA Representation, and Financial Consulting
- T2 preparation with GIFI schedules tied to the compiled statements.
- GST/HST returns on your assigned frequency, with the allocation documented.
- Payroll, T4 and T4A slips by the last day of February.
- CRA representation on worker status, exemption classification and input tax credit disputes.
- Tax planning on salary and dividend mix, with TOSI tested.
Highlighting Client Success Stories and Testimonials Related to the Insurance Sector
Clients across Toronto, Vaughan, Brampton and Mississauga come to us with the same three problems: a registration that was never required, input tax credits claimed on exempt activity, and chargebacks netted against income. All three are fixable, and all three are cheaper to fix before a review than after one.
Contact and Support: How to Get in Touch with Gondaliya CPA for Personalized Insurance Agent Tax Assistance
Call 647-212-9559 or email info@gondaliyacpa.ca. We reply within one business day, including weekends around deadlines, and offer a free initial consultation.
Availability of Consultations Tailored to Licensed Agents, Brokers, and Agency Owners
Sessions cover commission-based agents, agency owners with sub-agents, advisors under an MGA, dual-licensed advisors and new agents. We work through income type under section 9 — not section 5(1), which is employment income — the exempt and taxable split under Schedule V Part VII and section 141.01, deductions including licensing under paragraph 18(1)(a), vehicle documentation, and the filing dates that follow.
Client Support Resources: Documentation Checklists and Tax Planning Guides
- Commission statements from carriers or agencies.
- Advance and chargeback notices.
- Licensing fee invoices and continuing education receipts.
- Marketing invoices, with attendee lists where meals are involved.
- Vehicle mileage logs in the CRA format.
- Home workspace measurements, or the rent agreement where incorporated.
- Prior filings, notices of assessment and the shareholder loan schedule.
Encouragement to Connect for a Free Evaluation of Insurance Agent Bookkeeping Needs
A no-obligation review checks whether your records meet the six-year retention requirement in paragraph 230(4)(b), whether the exempt and taxable split holds up, and whether the registration you have is the one you need.
Commitment to Ongoing Updates on Tax Law Changes Affecting Canadian Insurance Agents
What is genuinely current: mandatory electronic filing of the T2 under subsection 150.1(2.1) since 2024, the suspension of the half-year rule for eligible property acquired after 31 December 2024, and the Class 14.1 treatment of a purchased book of business since eligible capital property ended in 2017. What is not current is any 2026 change to exempt financial services, commission advance rules or corporate filing deadlines — all three circulate and none exist.
Frequently Asked Questions
Frequently Asked Questions
FAQ
What is the corporate tax filing deadline for insurance agencies in Canada?+
Six months after the fiscal year-end under paragraph 150(1)(a). The balance of tax is due earlier — two months after year-end, or three for a CCPC claiming the small business deduction — which is the date most agencies miss.
How long must insurance agents keep their tax and bookkeeping records?+
Six years from the end of the taxation year to which they relate, under paragraph 230(4)(b) — not six years from the filing date. Section 286 of the Excise Tax Act imposes the same period for GST/HST records.
When are payroll remittance deadlines for agents with employees?+
They follow your average monthly withholding amount, not your pay cycle. A regular remitter (AMWA under $25,000) pays by the 15th of the following month. Accelerated remitters pay twice or four times a month; quarterly remitters by the 15th after the quarter.
What penalties apply for late filings or remittances?+
Subsection 162(1): 5% of unpaid tax plus 1% per complete month to a maximum of twelve months — a ceiling of 17%, not 12% a year. Subsection 162(2) doubles it on a repeat within three years following a demand. Interest under 161(1) is separate and compounds daily. Late payroll remittance is penalised under 227(9) from 3% to 10%.
Are override commissions and referral fees taxable income?+
Yes, for income tax — they are business income under section 9. For GST/HST they are generally exempt, being consideration for arranging a financial service under Schedule V, Part VII. Two different questions with two different answers.
Do insurance agents receive T4A and T4 slips, and what is their purpose?+
T4A reports commission and fees for services paid to a self-employed agent or sub-agent, required above $500 in the calendar year. T4 reports employment income where the agency employs someone. A sub-agent who is genuinely a contractor gets a T4A, not a T4. T5018 does not apply — it is the construction subcontractor return.
Which provision actually exempts insurance commissions from GST/HST?+
Schedule V, Part VII of the Excise Tax Act. Section 123(1) defines “financial service” and section 165 imposes tax — it does not exempt anything. Citing 165 as the source of an exemption cites the charging provision.
What is the meal and entertainment limit?+
50% under section 67.1, with the input tax credit recaptured to 50% for registrants. Where a conference fee includes food that is not separately stated, subsection 67.1(3) deems $50 per day to be for food, and that amount is then halved.
What shareholder loan rules are relevant to incorporated insurance agencies?+
Subsection 15(2) includes the loan in the shareholder’s income for the year it was made, unless repaid within one year after the end of the corporation’s taxation year under 15(2.6). A formal agreement is good practice but is not what the exception turns on. Section 80.4 imputes an interest benefit on any balance outstanding.
How should sub-agents be classified for tax purposes in an agency structure?+
On the Wiebe Door factors as refined in Sagaz and, where there is a written agreement, Connor Homes: control, tools, chance of profit and risk of loss, tested against the actual relationship. CRA Guide RC4110 sets out the approach and either party may request a ruling on Form CPT1.
What special considerations apply to managing general agencies?+
Override commissions arrive from a different payer than the agent’s own production and reconcile to a different statement, so they need separate tracking. Their GST/HST character is the same — consideration for arranging a financial service, exempt under Schedule V Part VII.
How is mixed activity apportionment handled?+
Section 141.01 requires inputs to be apportioned by the extent of their use in making taxable supplies. Directly attributable inputs go wholly to their side; shared overhead is allocated on a documented, consistent method applied year to year.
What restrictions apply to input tax credits for insurance agents?+
Section 169 allows a credit only to the extent an input is used in commercial activity, and making exempt supplies is excluded from commercial activity by section 123(1). An agent with 97% exempt revenue recovers roughly 3% of the tax on shared costs.
Does exempt commission income count toward the $30,000 threshold?+
No. Section 148 measures taxable supplies only. An agent with $400,000 of exempt commissions and $12,000 of taxable fees remains a small supplier and is not required to register.
How are commission advances and chargebacks timed?+
The advance is income when received or receivable on account of commissions. The chargeback is deducted in the year the repayment obligation arises, not by amending the earlier year — and where a cancellation happens six months after a January advance, that is the same taxation year for a December year-end.
How is a purchased book of business treated?+
Class 14.1 at 5% declining balance. Eligible capital property, where these assets once sat, was abolished on 1 January 2017. It is capital, never a current expense.
Must my home workspace be used only for business?+
Not under test (a) of subsection 18(12), the principal-place-of-business test, which has no exclusivity requirement. Only test (b) does. The deduction cannot create or increase a loss, and an incorporated agency pays rent under an agreement instead of claiming under 18(12) at all.
Is there a new electronic filing rule for Ontario in 2026?+
No. Mandatory electronic filing of the T2 is a federal requirement under subsection 150.1(2.1) that has applied to most corporations since 2024. There is no separate Ontario rule beginning in 2026.
Eighteen questions, and the two on GST/HST carry more money than the other sixteen combined.
Registration that was never required and input tax credits claimed on exempt activity are the two findings that recur on almost every insurance file we take over. Figures changed for privacy.
Key Insurance Agent Tax & Accounting Essentials
Essential Topics and Best Practices
Quick Reference
- Financial Statements: balance sheet, income statement and, where presented, a cash flow statement under ASPE 1540, compiled under CSRS 4200 with no assurance.
- Commission Statements: first-year, renewal, override and referral tracked separately and reconciled to carrier reports.
- GIFI Schedules: Schedules 100, 125 and 141 filed with the T2.
- Advance on Commission & Chargebacks: advances included when received or receivable; chargebacks deducted in the year the repayment obligation arises.
- Purchase of Book of Business: Class 14.1 at 5%, since eligible capital property ended in 2017.
- CRA Representation: support on worker status, exemption classification and input tax credit disputes.
- CRA Review Triggers: T4A mismatches, missing receipts, full credits claimed on exempt activity, no vehicle logbook.
- Instalment Payments: last day of each month or quarter, none required below $3,000 or in a first year.
- Payroll Slips: T4 and T4A by the last day of February; T4A above $500 for services.
- Electronic Filing: mandatory federally under 150.1(2.1) since 2024, not a 2026 Ontario rule.
- Logbook Retention: six years from the end of the taxation year, with the simplified base-year method available.
- Errors & Omissions Coverage: deductible over the policy period under subsection 18(9).
An agent who had bought a small book of business for roughly $60,000 had expensed the whole amount in the year of purchase.
It is Class 14.1 property at 5%, so the deduction was about $3,000 in year one, not $60,000. Correcting it meant a reassessment for the purchase year and a capital cost allowance schedule running forward for the life of the book. Figures changed for privacy.
Points Worth Carrying
- Exempt commissions do not count toward the $30,000 threshold.
- Schedule V Part VII exempts; section 165 imposes; section 123(1) defines.
- Input tax credits follow commercial activity, apportioned under section 141.01.
- Shareholder loans turn on the 15(2.6) date, not on a written agreement.
- The late filing penalty tops out at 17%, not 12% a year.
- The corporate balance is due before the filing deadline, not with it.
- Section 67.1 is meals; section 67.2 is vehicle loan interest.
- Test (a) of 18(12) has no exclusivity requirement.
- A purchased book of business is Class 14.1, not an expense.
- Mandatory T2 e-filing began in 2024 and is federal.
Twenty-two points, and the ten at the end are all things a licensed agent was told confidently by something they read.
None are obscure. They are ordinary rules attached to the wrong section number, the wrong threshold or the wrong year. Figures changed for privacy.
Businesses We Serve
Industry Expertise
Insurance practices share the same issues whatever they place. Here are ten and the usual finding.
| Practice | The Issue That Usually Appears |
|---|---|
| Life insurance agents | Registered for GST/HST when never required |
| Property and casualty brokers | Renewal commissions recognised in the wrong period |
| Dual-licensed advisors | Planning fees not separated from exempt commissions |
| Agency owners with sub-agents | T4A slips never issued above $500 |
| Managing general agencies | Override commissions pooled with own production |
| Brokers with taxable fee lines | Full input tax credits claimed on shared overhead |
| Agents carrying advances | Chargebacks netted against income |
| Owner-managed brokerages | Shareholder loans past the 15(2.6) window |
| Agents buying a book of business | Purchase expensed instead of added to Class 14.1 |
| Home-based agents | Workspace claim abandoned over a supposed exclusivity rule |
- Life insurance agents: taxable supplies only, under section 148.
- Property and casualty brokers: receivable under 12(1)(b).
- Dual-licensed advisors: code the fee side separately at entry.
- Agency owners with sub-agents: $500 threshold, last day of February.
- Managing general agencies: different payer, separate reconciliation.
- Brokers with taxable fee lines: apportion under section 141.01.
- Agents carrying advances: deduct, do not net.
- Owner-managed brokerages: one year after the corporate year-end.
- Agents buying a book of business: Class 14.1 at 5%.
- Home-based agents: test (a) requires no exclusivity.
The product changes. The questions do not: is this revenue exempt, when did the commission become receivable, and what proportion of the input was used commercially.
A life agent and a P&C brokerage look nothing alike on the street and file nearly identical returns. Figures changed for privacy.
Professional Guidance and Quick Reference
Guidance
Professional Guidance: How Gondaliya CPA Handles Your Agency
Insurance agents get into difficulty in a predictable set of ways: registering for GST/HST because guidance said the $30,000 threshold counts all revenue, when section 148 measures taxable supplies only and exempt commissions are outside it entirely; citing section 165 or section 123(1) as the source of the exemption, when 165 imposes tax, 123(1) merely defines the term, and Schedule V, Part VII does the exempting; claiming full input tax credits on shared overhead when section 141.01 apportions them by extent of use in commercial activity; believing subsection 15(2) requires a formal loan agreement, when what it actually requires is repayment within one year after the corporation’s year-end under 15(2.6); netting chargebacks against commission income rather than deducting them in the year the repayment obligation arises; and expensing a purchased book of business that belongs in Class 14.1 at 5%. Gondaliya CPA handles insurance agent accounting on a flat annual fee.
We handle what decides the outcome: testing whether registration is required at all before you register, documenting the exempt and taxable split at entry and apportioning shared inputs on a consistent method, keeping the advance and chargeback log so the timing is provable, tracking shareholder loan balances against the 15(2.6) date, putting the corporate balance and instalments on the calendar separately from the filing date, reconciling carrier T4A slips before the return goes in rather than after a mismatch letter, issuing T4A slips for sub-agent payments above $500, and adding a purchased book of business to Class 14.1 with the CCA claimed each year.
Our team starts with one carrier statement, your last GST/HST return and your shareholder loan account. Whatever you place, you get clear advice and a fixed price before we start.
Quick Answers
At a Glance
- Threshold: $30,000 of taxable supplies, ETA 148
- Exemption: Schedule V, Part VII
- Section 165: imposes tax, does not exempt
- Input tax credits: commercial activity only, s.169 and 141.01
- Commission income: receivable under 12(1)(b)
- Chargebacks: deducted when the obligation arises
- Shareholder loans: one year after the corporate year-end
- Book of business: Class 14.1 at 5%
- T2 filing: six months; balance at two or three
- Late filing penalty: 5% + 1%/month, max 17%
- Meals: 50% under section 67.1
- Records: six years from the taxation year-end
Who This Is For
Fit Check
- For: Licensed insurance agents, brokers, agency owners, dual-licensed advisors and managing general agencies in Canada, operating personally or through a corporation.
- Not For: Salaried employees of an insurer, whose employment expenses run through form T2200 on a T1, and agencies requiring a review or audit engagement, which we refer out.
People Also Ask
Quick Answers
Do my exempt commissions push me over $30,000?+
No. Section 148 counts taxable supplies only. Exempt commission income is excluded from the threshold calculation entirely, however large.
Does section 165 exempt insurance commissions?+
No — section 165 is the charging provision that imposes GST/HST. The exemption is in Schedule V, Part VII. Section 123(1) supplies the definition of “financial service”.
Can I claim all the GST on my office costs?+
Only to the extent those costs are used in commercial activity. Section 141.01 apportions shared inputs, so an agent with 97% exempt revenue recovers roughly 3% of the tax on overhead.
Does a shareholder loan need a written agreement?+
It is good practice, but subsection 15(2) does not turn on it. The exception in 15(2.6) is repayment within one year after the end of the corporation’s taxation year in which the loan was made.
Is a purchased book of business deductible?+
Not as an expense. It is Class 14.1 property at 5% declining balance, since eligible capital property was abolished on 1 January 2017.
Glossary of Key Terms
Glossary
- Exempt supply: No tax charged and no input tax credit recovery.
- Schedule V, Part VII: The exempting provision for financial services.
- Section 123(1): Defines “financial service” and “commercial activity”.
- Section 148: The $30,000 small supplier threshold on taxable supplies.
- Section 141.01: Apportions inputs by extent of use in taxable supplies.
- Commission advance: An amount paid on account of commissions not yet earned.
- Chargeback: A repayment obligation arising when a policy lapses or is cancelled.
- Override commission: A commission on a sub-agent’s production, paid by the MGA.
- Book of business: A purchased client list, Class 14.1 property at 5%.
- Subsection 15(2): Includes shareholder loans in income unless repaid in time.
- Subsection 15(2.6): The one-year-after-year-end repayment exception.
- Subsection 18(12): The two alternative home workspace tests.
- Section 67.1: The 50% meals and entertainment limitation.
- GIFI: Schedules 100, 125 and 141 filed with the T2.
- CSRS 4200: The compilation engagement standard, providing no assurance.
- Trust amounts: Collected sales tax and payroll source deductions.
Insurance Agent Tax Check
This quick self-check indicates where your practice most likely has room. Please answer the five questions below.
Insurance Agent Tax Check
Five quick questions on your business. No fee shown.
Points to raise with us:
This is a general prompt, not tax or legal advice or a quote. Your position depends on your full facts. For a real review, please book a free consultation.
Want a checklist to work from? You can download our free insurance agent tax checklist before your consultation.
Test whether you need to be registered for GST/HST at all, because section 148 counts taxable supplies only and exempt commissions sit outside the $30,000 threshold entirely. Cite the exemption to Schedule V, Part VII rather than to section 165, which imposes tax, or section 123(1), which only defines the term. Apportion input tax credits under section 141.01 by extent of use in commercial activity, and accept that an agent earning almost entirely exempt commissions recovers almost nothing on shared overhead. Include commission when it becomes receivable, and deduct chargebacks in the year the repayment obligation arises rather than netting them against income or amending the earlier year. Clear shareholder loan balances within one year after the corporate year-end, since that date and not a written agreement is what subsection 15(2.6) turns on. Add a purchased book of business to Class 14.1 at 5%. Pay the corporate balance at two or three months, before the six-month filing deadline. And please keep six years of records from the year-end.
2026 Update — what is current: This article reflects rules current to 30 September 2026. The six-month T2 filing deadline under 150(1)(a), the 50% meals limit in section 67.1, the $500 T4A threshold and the six-year retention requirement under 230(4)(b) are unchanged. Please note that the $30,000 small supplier threshold in ETA 148 counts taxable supplies only, so exempt commissions are excluded from it; that the exemption for arranging insurance sits in Schedule V, Part VII, with section 123(1) supplying the definition and section 165 imposing tax rather than relieving it; that input tax credits under section 169 are available only to the extent of use in commercial activity, apportioned under section 141.01; that commission income is included when receivable under paragraph 12(1)(b) on the accrual basis required by section 9, with chargebacks deducted in the year the repayment obligation arises; that subsection 15(2) includes shareholder loans in income unless repaid within one year after the end of the corporation’s taxation year under 15(2.6), with an imputed interest benefit under section 80.4; that a purchased book of business is Class 14.1 at 5% following the abolition of eligible capital property in 2017, and the half-year rule is suspended for eligible property acquired after 31 December 2024; that the corporate balance is due at two months, or three for a CCPC claiming the small business deduction, with instalments on the last day of each month or quarter; that the late filing penalty under 162(1) is 5% plus 1% per month to a maximum of twelve months, doubled under 162(2) on repeat; and that mandatory electronic filing of the T2 under subsection 150.1(2.1) has applied federally since 2024 — there is no new Ontario electronic filing rule beginning in 2026, and no 2026 change to exempt financial services or commission advance treatment.
Insurance Agent Taxes Canada: How Gondaliya CPA Supports Agents and Brokers
Start with one carrier statement and your last GST/HST return
Gondaliya CPA tests whether GST/HST registration is required at all before you register, documents the exempt and taxable split at entry and apportions shared inputs under section 141.01, keeps the advance and chargeback log so the timing is provable, tracks shareholder loan balances against the 15(2.6) date, reconciles carrier T4A slips before the return goes in, issues sub-agent slips above $500, adds a purchased book of business to Class 14.1, and files the GST/HST, the compiled statements and the T2 with its GIFI from one reconciled set of books — on a flat annual fee including HST with a one-business-day response. Please book a free consultation.
Next Steps
Please book a free consultation with Gondaliya CPA and bring one carrier commission statement, your last GST/HST return if you file one, and your shareholder loan account. Those three settle the registration question, the input tax credit question and the loan timing question, which is where most of the exposure sits for a licensed agent. You will get a flat annual fee including HST before any work begins. We serve Toronto, Vaughan, Brampton, Mississauga, Ottawa and the rest of Ontario, and work with agents across Canada. If our content helps, please add gondaliyacpa.ca as a preferred source on Google.
Published: · Last updated:
Editorial policy: We research against CRA, CPA Canada and CPA Ontario sources, fact-check the figures, and Sharad Gondaliya, CPA, reviews the content, which we update as the rules change.
Disclaimer: This article is educational information only and is not tax, legal, or financial advice. Figures marked illustrative are examples rather than quotes or guarantees. It reflects rules current to 2026, including the $30,000 taxable supply threshold, the Schedule V Part VII exemption, the section 141.01 apportionment rules, the subsection 15(2.6) repayment window and the six-year retention requirement. Rates, limits and provincial licensing rules change and outcomes depend on your specific facts. Please consult a licensed CPA before acting.

Sharad Gondaliya is a CPA Canada & CPA USA with 15 Years+ experience of Accounting, Tax, Payroll of Corporate Small Businesses as Tax Accountant. He is fully certified CPA Ontario and CPA USA and is well known among corporate small businesses for tax planning, efficient tax solutions, and affordable CPA services. Sharad is the Principal (Director) of Gondaliya CPA – Affordable CPA Firm in Canada. Licenses: CPA Ontario: 61040184 | CPA USA (MT): PAC-CPAP-LIC-033176 | CPA USA (WA): 57629 | CPA Firm License: 61330051 View Full Author Bio