



Tax Accountant for Corporate Trainers in Ontario and Across Canada
A training business gets paid by people who were never in the room. The employer books the programme, the participants turn up, and a share of the invoice is settled by a public funder under an agreement signed months earlier. That third cheque is the one the bookkeeping gets wrong, because money received as assistance toward the cost of delivering training is not a fee for service. Paragraph 12(1)(x) of the Income Tax Act pulls an inducement, reimbursement, contribution, allowance or government assistance into income in the year it becomes receivable; subsection 12(2.2) offers the alternative, an election reducing the cost of the outlay the money relates to instead. Printed workbooks are no deduction on the day the pallet lands either: stock held for intakes still to run is property, and subsection 10(1) measures it at whichever is lower, cost or fair market value. Per-seat billing against a day rate, associate facilitators classified before the day rates are paid, 13% on your taxable supplies, projectors in Class 8 and authoring software in Class 12 — all of it handled, with AFFORDABLE flat fees.
AFFORDABLE Corporate Trainer Tax Accountant
Watch the money on a funded programme and it arrives from two directions at once. The employer signs the booking and pays part of the invoice. The balance comes later, from a public authority, against a claim form and a signed attendance register, sometimes two quarters after the room emptied. Books that drop both into one sales account have characterised a receipt nobody examined. Assistance toward the cost of training you delivered is caught by paragraph 12(1)(x) of the Income Tax Act whether or not anybody coded it that way, and the alternative under subsection 12(2.2) has to be elected, not assumed. The second gap sits in a storage unit: workbooks, manuals and participant kits printed in a run of four hundred are inventory until they are handed out, not a cost of the month the printer invoiced.
The practices we act for run from a single facilitator with a projector and a car boot of manuals to twelve-person firms with an associate roster, a print contract and three programmes running in different cities on the same Tuesday: safety and compliance providers, leadership and management development practices, technical and software training firms, sales academies and regulatory-update specialists. What they share is a profit figure built on two numbers nobody has tested — what the funded work earned, and what the paper in the cupboard is worth.
You deliver the programme. We will carry the funding, the materials and the returns.
Our Official Partners
Accounting That Understands How a Corporate Trainer Actually Works
A training practice is paid partly by the organisation that booked it and partly by a body with no one in the room, bills by the seat on one contract and by the day on the next, and carries printed stock for intakes still weeks out. At Gondaliya CPA we work with that reality rather than around it, across Ontario.
Stay Compliant and Minimize Your Corporate Training Tax
For a training practice, keeping CRA satisfied and paying no more tax than the law asks are the same piece of work. We hold every deadline while claiming the materials, venue, associate and equipment cost the T2 allows, so nothing is left behind and nothing invites a second look.
Accounting & Tax Experts for Corporate Trainers
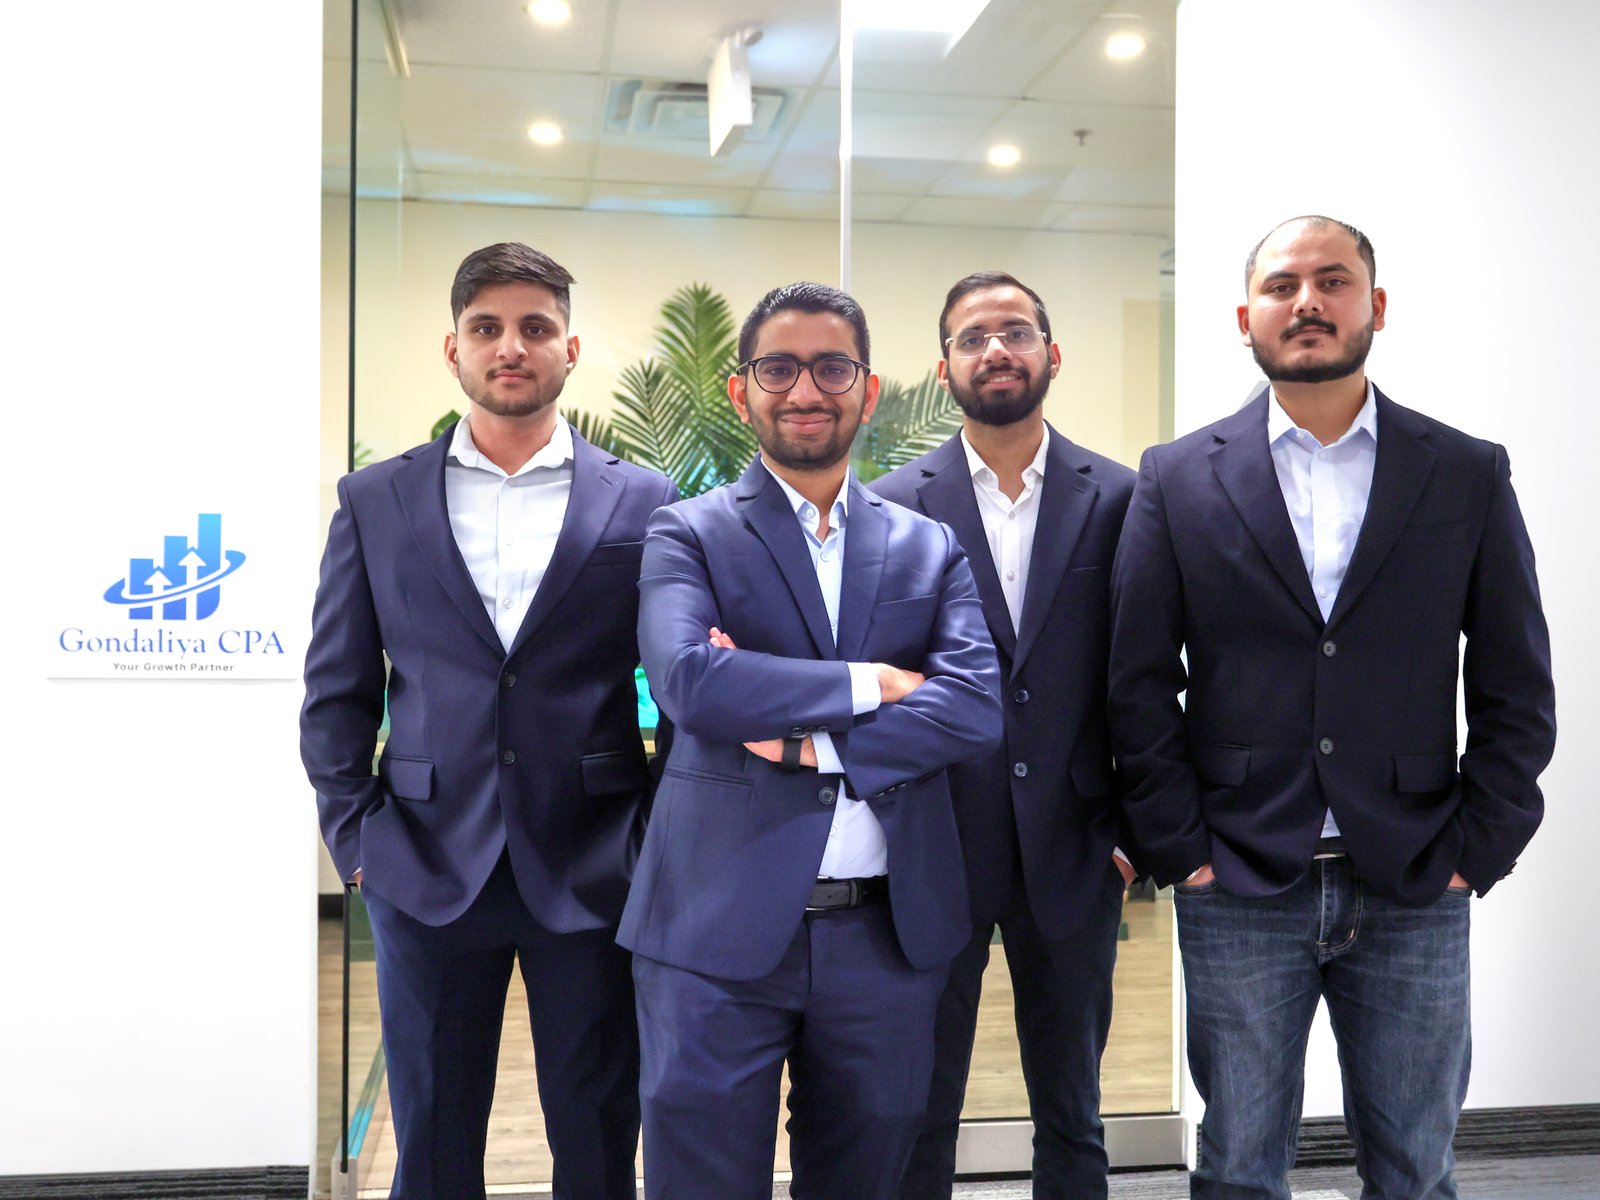
- AFFORDABLE + Registered CPA Firm
- Business and Corporate Tax Expert
- Small & Medium Business Expert
- Accounting, bookkeeping, and tax filing
- CPA (Chartered Professional Accountant)
- 1300+ 5-star Google reviews
- 30-Day Money-Back Guarantee
- 60-Day Fees Matching Policy
Why Choose Our Accounting Services for Corporate Trainers?
Tax Planning — Funding, Materials and Timing
We model the paragraph 12(1)(x) receipt against the subsection 12(2.2) election before the return is filed, time print runs and equipment against your year-end, and protect the first $500,000 of active business income under section 125.
Consulting — What a Funded Day Really Earns
Our bookkeeping costs each programme against the delivery that produced it, separating funded from commercial work and seat revenue from day-rate revenue, so a full room that lost money stops being invisible.
CRA Representation — Assistance and Stock Reviews
When CRA questions how a funded receipt was treated or what the closing materials were worth, we assemble the agreements, claims, registers and counts, and pursue relief on Form RC4288 where an earlier error caused the penalties.
Bookkeeping — Registers, Counts and Cash
We build books a funder and a reviewer can both read: delivery by delivery, intake by intake, with the materials ledger, the associate roster and the receivable ageing all tied back to the same calendar.
Google Reviews
Corporate Trainer Clients
Corporate Training Tax and Accounting Services in Ontario
Corporate Tax Filing (T2) for Corporate Trainers
T2 preparation with funded assistance characterised under paragraph 12(1)(x), the subsection 12(2.2) election where it helps, closing materials on the subsection 10(1) test, and every line CRA checks.
Bookkeeping & Accounting for Corporate Trainers
Books built programme by programme, with funded and commercial delivery split, seat revenue kept apart from day-rate revenue, and a materials ledger that matches an actual count.
Payroll Services for Corporate Trainers
Associates and employed trainers both handled properly: remittances on the PD7A, T4 and T4A slips in on time, WSIB from your first hire, and each engagement classified before a day rate is paid.
GST/HST Filing for Corporate Trainers
AFFORDABLE filing with 13% charged on your taxable training in Ontario, registration timed against the $30,000 threshold, and credits claimed on materials, venue and associate costs.
Tax Planning for Corporate Trainers
Planning on the funding election, the timing of print runs and equipment against your year-end, the small business deduction, the owner’s pay mix and the eventual sale.
Corporate Catch-Up Filing for Corporate Trainers
Overdue T2 and sales tax years filed, funded receipts and materials stock rebuilt from claims and print invoices, and your corporation back inside CRA’s expectations.
CRA Audit Resolution for Corporate Trainers
Support on assistance, inventory and associate classification reviews, handled from the first letter with the registers, agreements and counts that answer the question.
CPA Financial Statements (Notice to Reader) for Corporate Trainers
CPA-compiled statements a lender or a funder accepts, showing undelivered seats as an obligation and the materials stock at a figure that was counted.
Incorporation Services for Corporate Trainers
Incorporation end to end — NUANS, articles, share classes — plus the section 85 rollover that carries your curriculum, your materials stock and your equipment into the new company.
Catch-Up Bookkeeping Services for Corporate Trainers
Months or years of claims, print invoices, associate billings and venue costs reconstructed and reconciled, so your delivery figure is finally the real one.
US Corporation & LLC Tax Filing for Corporate Trainers
Cross-border work where the client, the owner or a shareholder sits outside Canada, covering currency conversion, foreign property reporting and coordinated returns.
Voluntary Disclosure Program for Corporate Trainers
Come forward on funded receipts never characterised, materials never inventoried or associate slips never filed, and have the penalties cancelled rather than assessed.
Accounting & Tax Services Tailored for Corporate Trainers
Practitioner-level CPA work for safety and compliance training providers, leadership and management development practices, technical and software training firms, sales and service academies and health and regulatory-update specialists across Ontario — built for a business whose invoice is settled by more than one party.
- Your T2 carries GIFI on Schedule 100 and Schedule 125 with funded delivery, commercially booked delivery, materials sold on to clients and associate recharges each on its own line, so the return reads like your delivery calendar.
- We test every receipt that did not come from the organisation that booked you, because assistance toward the cost of training is caught by paragraph 12(1)(x) of the Income Tax Act in the year it becomes receivable, and that is tested agreement by agreement.
- Where a funded amount attaches to an identifiable outlay you made, we model the subsection 12(2.2) election, which reduces the cost of that outlay instead of taking the receipt into income, and we file the election with the return rather than mentioning it afterwards.
- Closing course materials are measured the way subsection 10(1) of the Income Tax Act requires, cost against fair market value, from a count of what is physically in the cupboard rather than from whatever the printer invoiced over the year.
- We claim capital cost allowance on Schedule 8 with projectors, staging, flipchart easels and office furniture in Class 8 at 20%, laptops and the file server in Class 50 at 55%, and authoring and simulation software in Class 12 at 100%.
- We cost each programme as its own job in QuickBooks Online or Xero, loading venue, print run, associate days and travel against the delivery that produced the revenue, so a full room that lost money becomes visible in the month it ran.
- We keep funded work and commercially booked work in separate revenue accounts and tie every claim you submit to the delivery days it covers, because the paragraph 12(1)(x) question cannot be answered later from a single undifferentiated sales figure.
- We run a materials ledger that takes a print run in at cost, releases units as each intake collects them, and leaves a closing quantity you can walk into the storage unit and verify, which is what the inventory measurement depends on.
- We separate revenue billed by the seat from revenue billed by the facilitation day, because the two are earned at different moments and a mixed sales account hides the only question that matters at year-end: how much delivery do you still owe?
- Print, venue, software, travel and associate invoices come in through Dext and are reconciled monthly, which builds the six-year record trail section 230 of the Income Tax Act expects and stops a recoverable credit on a taxable input disappearing.
- We test each associate facilitator against the control, tools, chance of profit and integration factors in CRA guide RC4110, because one who sets her own rate and brings her own deck sits very differently from one delivering only your curriculum.
- We file a T4A for fees for services paid to a facilitator who is genuinely in business on her own account, so the day rates you deducted are reported the way CRA expects instead of resting inside an unsupported subcontract total nobody can break down.
- We run payroll for trainers you actually employ in Wagepoint, withholding income tax, Canada Pension Plan contributions and employment insurance premiums and remitting on the PD7A, and we note that the penalty on a late source-deduction remittance is graduated by how late it is.
- The last day of February is the deadline for your T4 slips and the T4 Summary, which we tie back to the remittances CRA actually received, and annual Ontario payroll stays under review against the employer health tax exemption of $1,000,000.
- We register you for WSIB coverage from the first employee you hire rather than the first year you remember to ask, and keep the clearance paperwork a corporate client’s procurement team will request before it lets a facilitator onto a plant floor.
- We charge 13% on your taxable training supplied in Ontario and file the GST34 on a cycle that suits your delivery pattern, because a practice billing in bursts around programme launches should not be forced into a period that fights its cash flow.
- We track taxable supplies toward the $30,000 small-supplier line, tested across four consecutive calendar quarters, and register you ahead of it, because two corporate contracts signed in one quarter can carry a practice past it unnoticed.
- We claim the credits on your print runs, room hire, audiovisual rental, authoring software and associate invoices, which on a training practice is most of the cost base and is the difference between a filing that returns cash and one that merely reports.
- We confirm that who settles the invoice does not change what you supplied: where a public authority pays part of a booking, the sales tax follows the training supplied to the employer, and we document that so it is not re-opened later.
- We reconcile the sales tax returns to the delivery calendar and the materials ledger, so the revenue CRA matches against your T2 is the same revenue your programme records support, line by line and quarter by quarter under the Excise Tax Act.
- We run every funded amount both ways before the return goes out: taken into income under paragraph 12(1)(x), or applied against the related outlay through the subsection 12(2.2) election, and we show what each route does to this year’s tax.
- We time the next print run and the next equipment purchase against your fiscal year-end, so four hundred workbooks ordered for a spring intake and a replacement projector land where the deduction and the inventory position work in your favour.
- We keep active business income inside the first $500,000 taxed at roughly 12.2% combined in Ontario under section 125, measured on active business income rather than on what you invoiced, and we watch association where you also run a separate consulting company.
- We set the owner’s remuneration deliberately: enough salary to carry registered retirement savings room and keep the employer health tax position clean, with the remainder taken as dividends rather than drawn against the top personal rate of 53.53%.
- We start positioning the shares two years before a sale, so the $1.25M lifetime capital gains exemption under section 110.6 is genuinely available on a curriculum library you spent a decade building rather than lost to a failed asset test.
- We rebuild funded and commercial delivery revenue across your unfiled years from claim submissions, signed registers, employer purchase orders and bank deposits, which on a training practice is usually the only surviving evidence of what was actually delivered and when.
- The late-filing penalty under subsection 162(1) escalates with every month a return stays outstanding up to a twelve-month ceiling, so the arithmetic rewards filing on rebuilt figures promptly rather than waiting until every schedule is perfect.
- We characterise the funded receipts year by year under paragraph 12(1)(x) and claim the subsection 12(2.2) election only where the related outlay can still be identified from the records, because a catch-up filing that guesses this creates its own problem.
- We rebuild the closing materials figure at each missed year-end from print invoices and intake numbers, since a practice that expensed every run on purchase has understated income in one year and overstated it in the next for as long as that went on.
- Across the gap we restore the undepreciated capital cost pools and lift the laptops from Class 8 into Class 50 where they always belonged, which returns deduction that had been understated for as long as the error ran.
- When CRA asks why a receipt from a public authority was not in income, we produce the funding agreement, the claims submitted, the delivery days covered and the outlay each attached to, which is the whole paragraph 12(1)(x) story in one file.
- When the closing materials figure is challenged, we show the count sheets, the print invoices behind each run and the basis on which withdrawn programme stock was written down, because an inventory number with no count behind it is simply replaced by the reviewer’s own.
- When the associate line is questioned, we produce the agreements, the invoices, the rates each facilitator set and the classification analysis we prepared when they were engaged, rather than building that reasoning for the first time under a deadline.
- We manage the scope of the review itself, answering within the dates set so a single year does not quietly widen, and noting only that subsection 152(7) permits CRA to assess on its own figures where yours are absent.
- We file the objection inside the statutory window after a reassessment and pursue taxpayer relief on Form RC4288 where the penalties and interest trace back to a previous adviser’s error rather than to anything you did or failed to do.
- We prepare the two fiscal years of compilation engagement statements under CSRS 4200 that a bank asks for before approving the operating line paying for a print run and a venue deposit long before the invoice settles.
- Your compiled statement of financial position shows seats invoiced for intakes that have not yet run as the obligation they are, so a lender does not read cash collected for undelivered training as equity the practice already owns.
- We carry the materials stock at net realizable value for accounting purposes under ASPE, which is a different measure from the lower of cost and fair market value that subsection 10(1) applies for tax, and we keep the two reconciled rather than conflated.
- We present amounts still owed by a funder separately from amounts owed by employers, because the two behave nothing alike in collection and a reader who cannot tell them apart will misjudge how quickly the receivable actually turns into money.
- Compiled statements reach you inside a month of your records and the year’s T2 figures arriving, because a financing decision taken before a programme season opens will not wait while somebody hunts for print invoices.
- We incorporate the practice under the Ontario Business Corporations Act, which puts a company between you and a claim arising from a training day and brings active business income down to roughly 12.2% combined in Ontario from a personal rate that tops out at 53.53%.
- Form T2057 carries the section 85 rollover that puts your curriculum, your materials stock, your equipment and your client list inside the company at elected amounts, so nothing is realised the way an outright sale of those assets would be.
- The opening Class 8, Class 50 and Class 12 schedules come straight off the rollover and the materials inventory opens on a physical count, so the company begins with an asset base nobody has to reconstruct from memory later.
- We register the corporation’s business number together with its sales tax and payroll accounts, then move the employer contracts, the funding agreements and the merchant account across, so the revenue is reported by the entity that is actually contractually earning it.
- We build the chart of accounts with funded delivery, commercial delivery, seat revenue, day-rate revenue, materials and associate cost already separated, so the records accumulate correctly from the first programme instead of being untangled at the first year-end.
- We rebuild months or years of neglected books from funder claim files, print invoices, associate billings, venue contracts and bank statements, so a practice that ran two busy delivery seasons with no bookkeeping at all finally has a ledger that balances.
- Funded and commercial delivery are pulled apart across the whole backlog first, because no paragraph 12(1)(x) conclusion can be reached on any year until that split exists, and it moves the revenue figure as well as the tax.
- We reconstruct the materials position at each year-end inside the caught-up period from print quantities and intake sizes, so an accurate return can be filed without guessing how much paper was still sitting in storage on the closing date.
- We recover the input tax credits buried in unposted print, venue, audiovisual, software and associate invoices, because two delivery seasons of unentered purchases on a training practice can hide a five-figure amount of recoverable tax.
- We age the receivable properly and claim the doubtful debt reserve under paragraph 20(1)(l) while a corporate balance is still in genuine doubt, then the bad debt deduction under paragraph 20(1)(p) only once the money is actually gone: two entries, two different years.
- Where a United States client pays your day rate in US dollars, we convert each receipt at the rate on the day it arrived and book the exchange difference on income account, because converting only at year-end misstates revenue and tax.
- We complete the Form W-8BEN-E certification a US corporate client asks for before it releases payment, so your invoice is settled in full rather than reduced at source while somebody in their accounts department waits for paperwork nobody told you about.
- We keep the travel, accommodation, shipping of materials and venue cost of a delivery day run outside Canada supported and deductible, with the itinerary and the client agreement on file rather than a credit card statement and a recollection.
- Where a shareholder of the company is a United States citizen, we coordinate the Canadian and United States filings together, because that status reaches into a Canadian corporation in ways training-practice families usually discover several years too late.
- We flag United States state and local tax as a live question for an adviser in that state wherever you deliver on the ground there, and we assert no threshold, rate or registration conclusion inside another country’s system.
- We bring the corporation forward on funded amounts that were banked and never characterised, correcting the paragraph 12(1)(x) position across the open years before a reviewer finds the same gap by comparing your claims against your reported revenue.
- We disclose years in which every print run was expensed on purchase and no closing materials figure was ever carried, which is a quiet and cumulative error on a practice that prints in batches and delivers in intakes.
- Day rates paid to associates with no slip behind them are disclosed too. That one subcontract line carries two exposures at once, a penalty for each missing slip and the classification question itself, and waiting improves neither.
- We submit on Form RC199 and confirm the disclosure is voluntary, complete and at least a year past due before it goes in, since a submission made after CRA has already made contact loses the relief it was filed to obtain.
- We correct seats invoiced in one fiscal year for programmes that ran in the next, which overstates income in the year the purchase order arrived and understates it in the year the facilitator actually stood up and delivered.
Corporate Training Funding & Materials Check
Six questions on how funded money was treated, whether your course materials are counted as stock, how seat revenue and day-rate revenue are timed, the associate facilitator position and whether it is time to incorporate. No fee shown.
1. Has every amount received from a government or agency programme been characterised under paragraph 12(1)(x) rather than simply banked as revenue?
2. Have you considered the subsection 12(2.2) election against an outlay the funding related to?
3. Are printed workbooks, manuals and participant kits carried as stock until an intake collects them?
4. Is revenue billed by the seat separated from revenue billed by the facilitation day?
5. Are associate facilitator engagements classified and reported before the day rates are paid?
6. Is your corporate training practice incorporated?
Free CPA Consultation for Corporate Trainers
Case Studies: Corporate Training Accounting & Tax
Milton Safety Training Provider — Funded Money Straight Into Revenue
The problem: A Milton provider delivering working-at-heights and confined-space programmes to manufacturers had three years of bookings part-settled by a public training programme. Every deposit from the funder went into the same sales account as the employer invoices on the day it cleared. Nobody had asked whether assistance toward the cost of delivering training is the same thing as a fee for that training, so paragraph 12(1)(x) of the Income Tax Act had never been applied and the subsection 12(2.2) election never considered.
What we did: We pulled funder receipts away from employer receipts over the three years, tied every claim to the delivery days and the outlays it answered, took the amounts into income under paragraph 12(1)(x) in their proper years, and elected under subsection 12(2.2) wherever an outlay was still identifiable in the records.
The result:
- Funder and employer revenue permanently separated
- Subsection 12(2.2) election made where the outlay was identifiable
- Three years restated before any CRA contact
Brantford Leadership Development Practice — Two Intakes’ Paper In Storage
The problem: A Brantford practice printed its workbooks, assessment booklets and facilitator guides in runs of four hundred to get the unit cost down, then expensed the whole print invoice in the month the pallet arrived. At the December year-end a rented storage unit held enough stock for two intakes that would not run until spring, none of it on the balance sheet. The practice was deducting materials it had not delivered, showing a loss in the year it printed and a profit in the year it taught.
What we did: We counted the storage unit, rebuilt the materials position at each of the two prior year-ends from print invoices and intake registers, and brought closing stock onto the balance sheet measured on the subsection 10(1) test at the lower of cost and fair market value, with the superseded edition written down because it would never be handed to anyone.
The result:
- Closing course materials counted and carried, not estimated
- Superseded edition written down on a documented basis
- Two years of profit restated onto the right side of the line
Peterborough Technical Training Firm — Seats Sold For Next Year’s Intakes
The problem: A Peterborough firm teaching controls and automation sold its programmes per seat, took purchase orders from employers in the autumn for intakes scheduled after its March year-end, and reported every one of those seats as revenue the day the purchase order was raised. Forty-one seats across three programmes sat in income for delivery that had not happened, in the year the firm had already paid venue deposits and a print run for those same intakes.
What we did: We rebuilt the sales ledger against the delivery calendar seat by seat, pulled per-seat bookings apart from facilitation fees earned as the days ran, took the amounts into income under paragraph 12(1)(a) and claimed against them the reserve paragraph 20(1)(m) allows for days not yet taught, then put the prior year on the same footing.
The result:
- Forty-one undelivered seats moved into the year they were taught
- Per-seat and per-day revenue now timed separately
- Corporate tax aligned with the delivery calendar, not the purchase orders
Our clear, efficient process ensures every step is transparent, building trust and long-term client relationships.
Kickoff (Document Request)
We collect prior T2 and sales tax returns, your funding agreements and every claim submitted under them, the delivery calendar and attendance registers, print invoices and current materials counts, associate facilitator agreements and invoices, venue contracts, payroll records and bank statements.
First 30 Days (Cleanup & Setup)
We set up QuickBooks Online or Xero with Dext, split funded from commercial delivery and seat revenue from day-rate revenue, open a materials ledger from a physical count, rebuild the Class 8, Class 50 and Class 12 pools, and work through the associate classification file.
Monthly Close
Programme-by-programme costing against the delivery that produced it, materials released and counted, funder claims tracked to the days they cover, receivable ageing reviewed, sales tax return filed, and associate invoices reconciled to the roster.
Quarterly Planning Review
The funding characterisation and the subsection 12(2.2) position on each new agreement, print run and equipment timing against the year-end, the owner’s salary and dividend mix, the small business deduction position, and cash committed to venues ahead of revenue.
Year-End Close & T2 Filing
Trial balance, a counted closing materials figure, undelivered seats reserved, the paragraph 12(1)(x) and subsection 12(2.2) treatment settled and filed, statements where a lender or funder needs them, and the T2 with GIFI agreeing to the sales tax returns.
Get Your Corporate Training Taxes Done Right Today
Affordable Pricing for Corporate Trainers
We believe in clear, upfront pricing so you know exactly what to expect. All fees include HST.
- Tax Preparation (Corporation) — From $400
- Tax Return Filing (Corporation) — From $400
- Tax Compliance Audit — FREE CRA audit support for our clients
- Tax Strategy — FREE for our clients
- Accounting Base Plan — From $100 per month
- Bookkeeping Management — Free for our Accounting clients
- Financial Reporting — Free for our Accounting clients
- Business Formation — Flat $35
- Incorporation Process — Flat $35
- Entity Setup Assistance — Flat $35
- Full-Service Payroll — From $125 per month
Payment is by Interac e-Transfer to info@gondaliyacpa.ca only. Security question: Not Applicable, as auto-deposit is enabled.
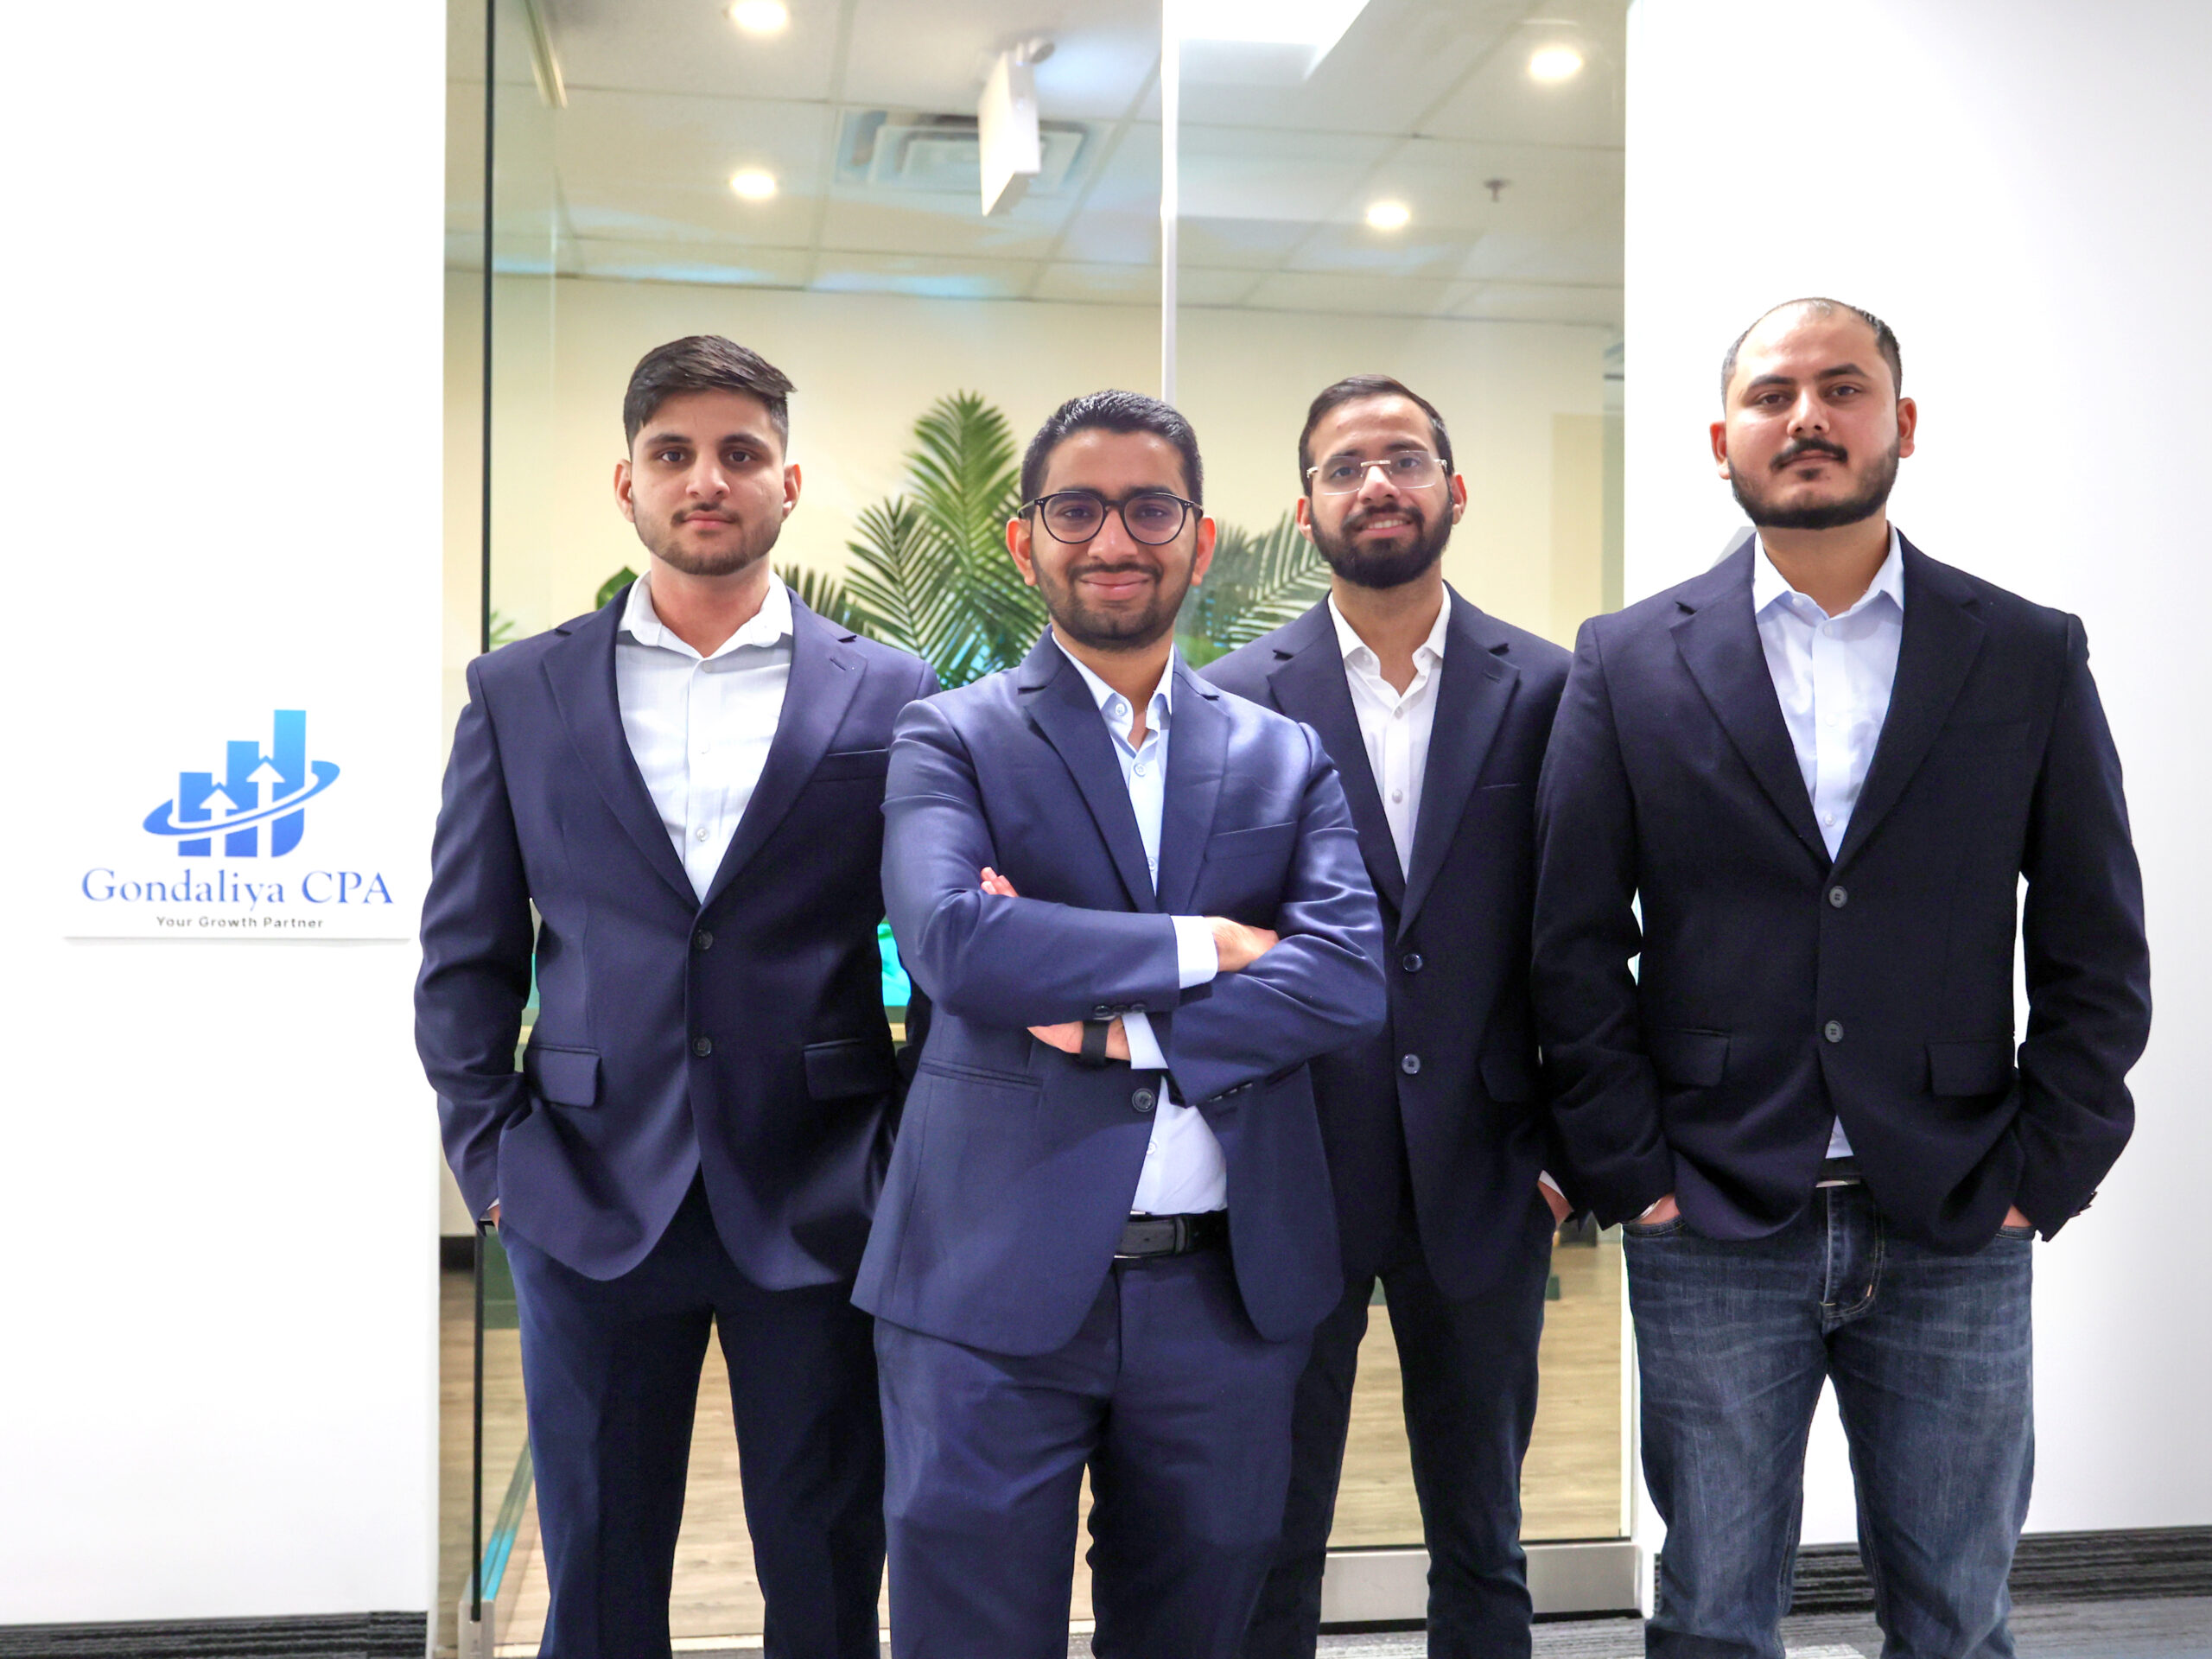
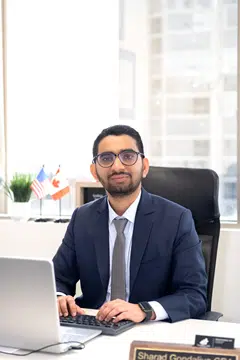
Meet Your Lead Corporate Training Accountant
Meet your lead corporate training accountant. Two people hold your file and they do not rotate: the principal who sets the funding and materials position, and the specialist who runs it every month.
What Our Clients Say
1300+ five-star Google reviews, written by people who run training and facilitation businesses here in Ontario and in every other province.
Serving Corporate Trainers Across Ontario
Our CPA practice looks after corporate training providers and independent facilitators across Ontario. We know why a receipt from a public funder has to be characterised before it is banked, why a print run of workbooks is stock rather than a deduction, and how a seat sold in October for a March intake is actually earned.
Toronto (ON)
55 Queen St E Ste 1205, Toronto, ON M5C 1R6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Mississauga (ON)
2100 Camilla Rd #716, Mississauga, ON L5A 2J8
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Brampton (ON)
4 Starhill Crescent, Brampton, ON L6R 2P9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Scarborough (ON)
24 Clementine Square, Scarborough, ON M1G 2V7, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Vaughan (ON)
19 Cabinet Crescent, Woodbridge, ON L4L 6H9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Oshawa (ON)
210 Durham St, Oshawa, ON L1J 5R3, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Ottawa (ON)
2090 Neepawa Ave a314, Ottawa, ON K2A 3L6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Etobicoke (ON)
60 Stevenson Rd #1601, Etobicoke, ON M9V 2B4, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Hamilton (ON)
70 Starling Dr, Hamilton, ON L9A 0C5, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Guelph (ON)
1155 Gordon St, Guelph, ON N1L 1S8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Windsor (ON)
4387 Guppy Ct, Windsor, ON N9G 2N8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
North York (ON)
150 Graydon Hall Dr #912, North York, ON M3A 3B2, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Corporate Training Accounting & Tax FAQs
Related Industries We Serve
Accountant for E-Learning Platforms
- Subscription and access-term revenue
- Platform payout reconciliation
- Corporate tax filing and planning
Accountant for Online Course Creators
- Launch and programme revenue timing
- Contractor and production cost
- Corporate tax filing and statements
Accountant for Administrative Service Businesses
- Service revenue and billing cycles
- Payroll and contractor reporting
- T2 preparation with GIFI schedules
Accountant for Staffing Agencies
- Placement and contract revenue
- Worker classification and slips
- Corporate tax planning and advisory
Corporate Training Accounting & Tax Done Right.
Assistance from a public funder characterised under paragraph 12(1)(x) of the Income Tax Act, the subsection 12(2.2) election modelled and filed where it serves you, course materials counted and carried on the subsection 10(1) test, superseded stock written down while a general refresh provision stays out under paragraph 18(1)(e), per-seat bookings for later intakes reserved rather than taxed on the purchase order, associate facilitators classified and slipped properly, 13% charged on taxable training under the Excise Tax Act with the credits on print, venue and associate cost recovered, and the capital pools kept apart. AFFORDABLE flat fees, no hourly billing. Licensed CPA Ontario. 1300+ five-star reviews. 30-Day Money-Back Guarantee.