



Tax Accountant for Administrative Service Businesses in Ontario and Across Canada
You may never meet the client whose invoice you are about to send, and that is precisely why the sales tax on it is so easy to get wrong. For a service the rate is fixed by the province of the recipient — taken from the address you obtain in the ordinary course of business — and not by the desk you happen to be sitting at, so an Ontario operator who puts 13% on everything is billing the wrong figure to a good share of the list. The same geography runs through your payroll from the other end: engage somebody who works full time from their own home in another province and the province of employment has to be determined for that person rather than assumed from your letterhead. Underneath both sits the risk that costs the most. A corporation whose work comes almost wholly from one payer may be carrying on a personal services business, and that finding removes the small business deduction and tightens what the company may deduct at all. We set the invoicing, the payroll and the structure up so none of the three goes quietly wrong. AFFORDABLE flat fees.
AFFORDABLE Administrative Service Business Tax Accountant
Virtual assistant practices, answering and call services, document and records preparation, back-office outsourcing, bookkeeping and payroll bureaus: the whole trade shares one unusual feature. It can be run from a single room and sold to every province at once. That reach is the business model, and it is also where the tax quietly goes wrong, because the rate on an invoice is set by where your client is and not by where you are. Ontario work carries 13% HST. A client in a province or territory with no HST carries 5% GST. A client in a participating province carries that province’s own rate, applied exactly as it stands for that province — and because several of those rates have moved recently, the figure has to be read off the current table rather than remembered. Putting your own rate on the whole list is the characteristic error of this trade, and it fails in both directions at the same time: too little collected on some invoices, which you end up funding yourself, and too much on others, which a client may eventually ask you to hand back. Our HST Place of Supply Rate Calculator is the fastest way to see what a given client should actually be billed.
The second half of the same problem sits on the payroll side, because hiring stopped being local for a business like yours some years ago. For an employee who works remotely full time, the province of employment follows CRA’s administrative approach and has to be determined on the facts of the arrangement; it does not default to the address on your letterhead, and getting it wrong means the provincial tax withheld is wrong from the first pay cheque. Then there is a third matter, quieter than either, which we raise before anybody mentions incorporating. Where one payer supplies nearly all the revenue and what that payer is really buying is one individual’s own services, a corporation sitting in the middle may be a personal services business under the Income Tax Act. Whether it is has to be determined on the facts of the case, but the consequences if it is are heavy enough that the question belongs before the incorporation rather than after it.
Send us a month of invoices and the list of who does the work, and we will tell you which of the three is already costing you money.
Our Official Partners
Accounting That Understands How an Administrative Service Business Actually Works
An administrative service business carries almost no inventory, very little equipment and a client list that can stretch across five time zones, so its tax problems are not the ones a generic bookkeeping template was built to solve. The rate on each invoice depends on the client’s province. The withholding on each pay cheque depends on the employee’s. Money frequently arrives before the work is done, which means it is not yet income. The deductions are software, subscriptions, subcontractors and a computer rather than machinery. And where the revenue comes mostly from one place, the corporation itself becomes the thing CRA looks at. Gondaliya CPA works on exactly these files across the GTA and the rest of Ontario, for owners whose clients are everywhere.
Stay Compliant and Minimize Your Administrative Service Business Tax
In this trade the compliance work and the tax saving are the same exercise. Get the rate right on each invoice, the withholding right on each employee and the timing right on money received in advance, and there is nothing left to reassess and nothing you are paying that you never owed. We run the filings on a calendar and keep the evidence behind every position sitting in the file where it belongs.
Accounting & Tax Experts for Administrative Service Businesses
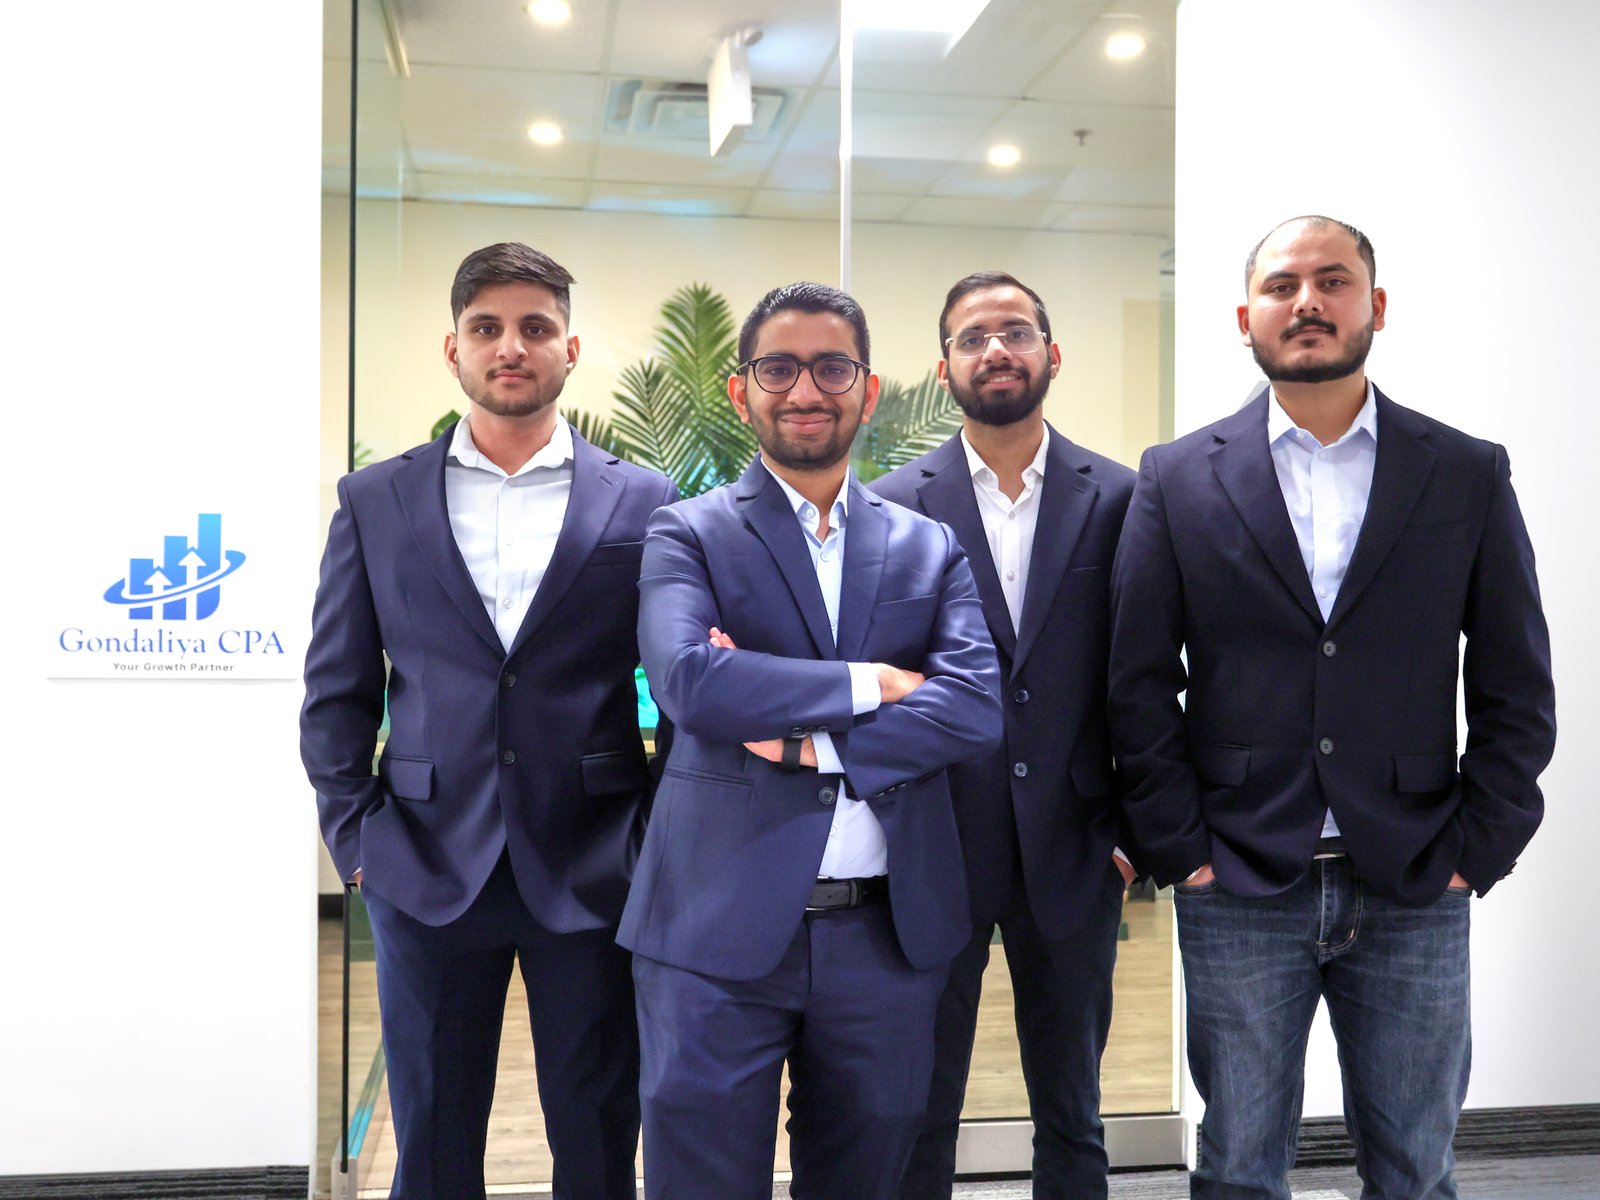
- AFFORDABLE + Registered CPA Firm
- Business and Corporate Tax Expert
- Small & Medium Business Expert
- Accounting, bookkeeping, and tax filing
- CPA (Chartered Professional Accountant)
- 1300+ 5-star Google reviews
- 30-Day Money-Back Guarantee
- 60-Day Fees Matching Policy
Why Choose Our Accounting Services for Administrative Service Businesses?
Tax Planning — Structure Before Rate
We look at your client mix before we look at your tax rate, because a corporation drawing nearly all of its revenue from one payer can lose the small business deduction outright to the personal services business rules. Where the mix is genuine, an Ontario corporation pays about 12.2% on active profit up to $500,000 while the top personal bracket takes 53.53%, and we set the salary and dividend split against what you actually withdraw.
Consulting — Invoicing, Retainers & Rates
We rebuild the invoicing so each client’s province is recorded with the address that supports it, the right rate is applied when the invoice is raised instead of corrected at year-end, and retainers and prepaid hours sit in deferred revenue until the work is done. You stop finding rate errors nine months after the money moved.
CRA Representation — Rate, Payroll & PSB Reviews
When CRA asks about the rate you charged a client in another province, the withholding on a remote employee, or whether your corporation is a personal services business, we assemble the addresses, contracts and payroll records that answer it, respond in writing, and seek taxpayer relief on Form RC4288 where the penalty came from an error you did not make.
Bookkeeping — Payroll, Slips & Growth
We run payroll for staff in more than one province, file the T4 slips and the T4 Summary against the PD7A, watch the $1,000,000 Employer Health Tax line, and keep WSIB current from your first hire. When incorporating is right, we do the section 85 transfer on Form T2057 and set the opening balances.
Google Reviews
Administrative Service Clients
Administrative Service Business Tax and Accounting Services in Ontario
Corporate Tax Filing (T2) for Administrative Service Businesses
T2 preparation with GIFI on Schedule 100 and Schedule 125, retainer income separated from hourly and per-project fees, the deferred revenue reserve claimed, and Schedule 8 capital cost allowance on your equipment.
Bookkeeping & Accounting for Administrative Service Businesses
Client records carrying the province that sets the rate, a live deferred revenue account, subcontractor tracking and a monthly close you can read in five minutes.
Payroll Services for Administrative Service Businesses
Payroll for staff in more than one province, with the province of employment determined per person, remittances on the PD7A, the February slip filing reconciled, WSIB coverage from your first hire and the Employer Health Tax line watched.
GST/HST Filing for Administrative Service Businesses
AFFORDABLE filing with the rate set from each client’s province, 13% in Ontario and 5% where there is no HST, input tax credits claimed on line 108, and the address evidence kept behind every invoice.
Tax Planning for Administrative Service Businesses
Client concentration reviewed before structure, the Small Business Deduction protected, salary and dividends set against what you draw, and purchases timed into the right class and the right year.
Corporate Catch-Up Filing for Administrative Service Businesses
Overdue T2 years filed oldest first, missing GST/HST periods rebuilt at the rate each client’s province required, and the payroll years reconciled so everything finally agrees.
CRA Audit Resolution for Administrative Service Businesses
Support on place-of-supply reviews, remote payroll questions, deferred revenue reserves and personal services business examinations, with the evidence assembled before anything is conceded.
CPA Financial Statements (Notice to Reader) for Administrative Service Businesses
Compilation engagement statements that a bank, a landlord or a buyer will accept, with deferred revenue and revenue concentration presented where a reader can see them.
Incorporation Services for Administrative Service Businesses
The personal services business question answered first, then the name search, the articles, a share structure with room to grow, and the section 85 transfer of your client list and equipment on Form T2057.
Catch-Up Bookkeeping Services for Administrative Service Businesses
We rebuild months of unposted invoicing, retainer balances, subcontractor payments and processor deposits so the books are current and the next return is prepared from real numbers.
US Corporation & LLC Tax Filing for Administrative Service Businesses
Cross-border work for owners billing clients in the United States, covering when a US return is genuinely required, Form 1120-F, treaty positions and the Canadian filing prepared alongside it.
Voluntary Disclosure Program for Administrative Service Businesses
A disclosure on Form RC199 made before CRA contacts you, complete across every year affected, covering tax never charged at the right rate and corporate years never filed at all.
Accounting & Tax Services Tailored for Administrative Service Businesses
Practitioner-level CPA work for virtual assistant practices, answering and call services, document and records preparation, back-office outsourcing and bookkeeping and payroll bureaus across Ontario — built for a business whose clients and staff are not in the same province you are.
- We file the T2 with GIFI on Schedule 100 and Schedule 125, splitting monthly retainer income from hourly work and per-project fees so the figures tie to what you actually delivered; one file moved $14,200 of revenue into the correct year.
- We claim capital cost allowance on Schedule 8, with computers and servers in Class 50 at 55%, application software in Class 12 at 100% and desks, chairs and shelving in Class 8 at 20%; one client recovered $6,300 of depreciation never claimed.
- Paragraph 12(1)(a) of the Income Tax Act picks up a fee billed ahead of the work, and the reserve in paragraph 20(1)(m) then takes back the share standing for service you have not yet given, so reported profit follows delivery.
- We review revenue by client before the return is signed, because a corporation whose work comes almost wholly from one payer may be a personal services business, and that question is far cheaper to answer early than to lose later.
- Where a client has stopped paying we take the reserve under paragraph 20(1)(l) while collection is genuinely in doubt, and the deduction under paragraph 20(1)(p) only once the amount is truly uncollectible; two entries, two different years.
- We put a province on every client record in QuickBooks Online or Xero, carried from the address we hold for them, so the correct rate is applied as each invoice is raised rather than corrected in a year-end scramble.
- We run a deferred revenue account listing each open retainer and every unused block of hours, so you can see at any point how much of the cash sitting in your bank is money you have not yet earned.
- We code subcontracted overflow work to its own account with the payee tracked all year, so February slips are a print run and not a reconstruction; one cleanup surfaced $4,100 of payments never recorded anywhere.
- We split software subscriptions, the phone plan, internet and a coworking desk between the business and anything personal on a basis we can support, and keep the receipts in Dext against the account each one landed in.
- We close each month against the bank and the payment processor, reconcile revenue reported on line 101 and input tax credits on line 108, and send you a statement that takes five minutes to read.
- Before the first pay run we determine the province of employment for each person on your payroll, including anybody working full time from their own home in another province, because that determination sets the provincial tax you withhold.
- We remit source deductions on the PD7A on the schedule CRA has assigned you, because a late remittance draws a graduated penalty that climbs with the delay and reaches 10%; it is never charged at a single flat figure.
- February’s last day is the deadline for the slips and the Summary, and we agree the totals to the remittances that actually reached CRA across the year, so a discrepancy is ours to find rather than yours to explain.
- We register WSIB coverage from your first hire rather than your first busy month, and keep an eye on where annual payroll stands against the $1,000,000 Employer Health Tax line so that return is filed for the right year.
- We issue T4 slips to employees and T4A slips to genuine subcontractors, keep the two populations apart in the payroll file, and reconcile both to the accounts they were paid from; one file corrected $7,800 of misposted fees.
- We set the rate on each invoice from your client’s province, taken from the address obtained in the ordinary course of business, which is 13% in Ontario and 5% in the provinces and territories that have no HST at all.
- Each participating province has its own rate, and we apply it exactly as it currently stands for that province rather than from memory, because these rates move and a figure carried over from an old file is the usual source of error.
- Where you hold more than one address for the same client we use the one most closely connected with the supply, and we record which address was used and why, so the choice can still be explained years afterwards.
- We keep the rolling total in front of you and register the business in the quarter it goes past $30,000, or earlier by choice where credits on software, hardware and subcontractors outweigh the cost of filing.
- Whether a service supplied to a client outside Canada is zero-rated is a determination on the facts of that engagement, subject to exclusions; we make it in writing and keep the support, and one such review recovered $9,600.
- We start with your client mix rather than your tax rate, because where one payer supplies nearly all the revenue the personal services business rules can remove the small business deduction and tighten what the company may deduct.
- Where the mix is genuine, an Ontario company keeps active profit to the $500,000 limit at roughly 12.2% while the top of the personal scale takes 53.53%, and that gap only pays on money you leave inside.
- We set the salary and dividend split against what you actually withdraw to live on, revisit it every year, and keep the payroll account, the T4 and the dividend paperwork consistent with the decision taken.
- We time computer, monitor and software purchases so they land in the right class and the right fiscal year, and say plainly when a purchase should wait; one plan shifted $3,400 of tax by a single month.
- We keep the shares qualifying for the lifetime capital gains exemption in section 110.6, worth $1.25 million on a sale, long before a sale is contemplated, because the conditions are tested against history and not intention.
- We file your overdue T2 years oldest first so interest stops compounding at the earliest possible point, and rebuild each year’s revenue from invoices, engagement letters and deposits rather than from an estimate.
- We reconstruct the missing GST/HST periods at the rate each client’s province actually required in that period, which is often not the rate charged; one catch-up corrected $18,500 of tax across eleven quarters.
- We rebuild the deferred revenue position for every open year, so retainers billed in one year and worked in the next are taxed in the year the work happened instead of the year the cheque cleared.
- We reconcile the payroll years to the PD7A remittances and the slips actually issued, and file whatever is missing, so the payroll account and the corporate return finally agree with one another.
- Where a penalty came from an error made by somebody else, we ask for taxpayer relief on Form RC4288 with the supporting narrative, and say honestly when the facts will not carry the request; one removed $5,200.
- When CRA questions the rate you charged a client in another province, we produce the address held for that client, the invoice it governed and the record made at the time, and answer the query in writing.
- On a payroll review we set out how the province of employment was determined for each remote worker and produce the records behind it, rather than arguing the point after the withholding has already been assessed.
- On a personal services business review we assemble the client list, the contracts and the invoices, address the test as it applies to your own facts, and quantify the exposure before anybody concedes anything.
- Where a reserve on unearned retainers or a doubtful account is challenged, we show the engagement terms, the hours actually delivered and the payment history that support the figure claimed in that year.
- We keep records in the form section 230 of the Income Tax Act requires for six years, because subsection 152(7) lets the Minister assess an amount without being bound by your return; one file closed with $12,700 of the proposed adjustment withdrawn.
- We prepare compilation engagement financial statements under CSRS 4200 for the bank, the landlord or the buyer who asked for them, together with the communication that says plainly what a compilation is and is not.
- We present the deferred revenue balance on the face of the statements instead of burying it, because a reader who cannot see how much of your cash is unearned will misread the working capital completely.
- We produce the comparative year alongside so a lender sees a trend rather than a snapshot, and reconcile both years to the T2 filed for each, which is the first thing a careful reader goes looking for.
- We show the revenue concentration a lender will ask about anyway, because a business where one client is most of the income gets priced differently, and it is better disclosed by you than discovered by them.
- We quote the engagement as a flat fee with a date attached; one owner who needed statements for a $120,000 fit-out and equipment facility had them in hand within two weeks of handing over the books.
- We answer the personal services business question before we answer the incorporation question, because for a one-person business with a single dominant client a corporation can make the tax position worse rather than better.
- Where incorporating does pay, we handle the name search, the articles and a share structure that leaves room for a spouse or a later partner without forcing a reorganization two years in.
- We move the client list, the goodwill and the equipment into the company at elected amounts under section 85 on Form T2057, so nothing you already own is treated as sold on the way in.
- We choose the first fiscal year-end around your retainer cycle and your busiest quarter, so the opening corporate return is prepared from a clean period instead of a half-finished one.
- We open the payroll and GST/HST accounts, set the opening balances from the real cost history of what you own, and give you the fee for the whole crossing before any of it begins; the setup itself is $35.
- We rebuild months of unrecorded invoicing from engagement letters, the sent-mail trail and the deposits, attaching each invoice to the client province it belonged to; one rebuild recovered $11,400 of billings never posted.
- We reconstruct the deferred revenue account from the retainer terms in force at the time, so the opening and closing position of each year is supportable and not simply plugged to make the bank balance agree.
- We code the subcontractor payments that left a personal card or went out by e-transfer, match each one to the work it covered, and build the payee history that the February slips will need.
- We reconcile the bank, the credit cards and the payment processor line by line, including the processor fees netted out of deposits and therefore never recorded as an expense anywhere.
- We catch up the payroll postings and reconcile them to the PD7A remittances and the slips issued, so the wage expense in your books equals the wages CRA already holds; one file fixed $8,700.
- A Canadian corporation doing administrative work from a Canadian desk for a client in the United States usually has no US return to file, but we test that rather than assume it, because the answer changes quickly.
- The moment there is a US entity, a US office or somebody acting for you inside the United States, the position has to be looked at again, and we look at it before the fiscal year closes rather than afterwards.
- Where a US corporation return is required we prepare Form 1120-F for a foreign corporation and set out the treaty position supporting the filing, with the Canadian return prepared alongside it on the same timetable.
- A limited liability company owned by a Canadian is treated one way by the United States and another way by Canada, so we model both sides of that mismatch before the entity is used rather than after.
- We line the two filings up so the same fee income is not taxed twice, claiming foreign tax credits where they are available; on one file this removed $6,800 of duplicated tax altogether.
- We file your disclosure on Form RC199 and file it before CRA contacts you about the issue, because a disclosure that is not voluntary is simply a late filing with penalties attached to it.
- A disclosure has to be complete, so we assemble every year and every account affected rather than the one item that worries you most, and we give you the total before anything is sent.
- The information disclosed has to be at least one year past due, and we check that at the outset, because a recent period is corrected through an amended return and not through this program at all.
- The usual subjects on these files are tax never charged at the rate a client’s province required and corporate years never filed at all, and both can be addressed in the same submission.
- Acceptance brings relief from penalties and part of the interest, the extent depending on which track the disclosure falls into; we assess the track before filing, and one file saved $16,300.
Administrative Service Business Rate & Structure Check
Six quick questions on the rate you charge clients outside Ontario, the address evidence behind it, remote payroll, retainers and personal services business risk. No fee shown.
1. Do you charge the same GST/HST rate to every client, wherever they happen to be?
2. Are there clients whose province you could not prove from a document today?
3. Do retainers or prepaid blocks of hours go straight to revenue when the money arrives?
4. Does anyone on your payroll work from their own home outside your province?
5. Does one single client provide most of your revenue?
6. Is your administrative service business still unincorporated?
Free CPA Consultation for Administrative Service Businesses
Case Studies: Administrative Service Business Accounting & Tax
Richmond Hill Virtual Assistant Practice — One Rate Billed to Every Province
The problem: A Richmond Hill virtual assistant practice with forty-one clients spread across six provinces had charged 13% on every invoice for three years, on the assumption that the rate followed the desk the work was done at. Some clients had therefore been under-charged and others over-charged, none of the client records carried the address the rate depended on, and nobody had looked at a return since the first one was filed.
What we did: We rebuilt the client list against the address held for each account, re-rated every reporting period against the province that governed the supply, filed the corrected returns with the address evidence attached, and reconfigured the billing system so the rate is now drawn from the client record instead of typed in by hand.
The result:
- $22,400 of tax re-rated across eleven reporting periods
- Address evidence now recorded on every client file
- Rate applied at invoicing, not corrected at year-end
Newmarket Back-Office Corporation — Client Concentration and PSB Risk
The problem: A Newmarket back-office outsourcing corporation drew ninety-four percent of its revenue from one payer. The owner had incorporated on a friend’s advice, worked largely to that payer’s direction, and had never heard of the personal services business rules. The T2 claimed the small business deduction, a full slate of operating expenses had been deducted, and no analysis of the arrangement existed anywhere in the file.
What we did: We set out the test and its consequences in writing, modelled what a denial of the small business deduction and the restriction on deductible expenses would do to the last three years, and had the arrangement reviewed against the test before the next return went in rather than after a reassessment arrived. The client concentration decision that followed was the owner’s.
The result:
- Exposure quantified and documented before filing
- Test applied to the facts instead of assumed away
- Structure decision taken with the numbers in hand
St. Catharines Answering Service — Retainers and Out-of-Province Payroll
The problem: A St. Catharines answering service recognized every monthly retainer the day it arrived, so revenue was front-loaded and the company paid tax a year early on work it had not yet done. Two operators hired the previous spring worked full time from their own homes in another province, and both had been set up on payroll as though they sat in the Ontario office.
What we did: We built a deferred revenue account from the engagement terms and released it as the hours were delivered, claimed the reserve for services still owed, and had the province of employment determined for each remote operator before the next pay run so the withholding, the slips and the year-end all matched the facts of the arrangement.
The result:
- $16,900 of tax deferred into the year the work was done
- Province of employment determined for both remote staff
- T4 slips and the T4 Summary reconciled to the PD7A
How We Work With Administrative Service Businesses
Our clear, efficient process ensures every step is transparent, building trust and long-term client relationships.
Kickoff (Document Request)
Prior T2 returns, the client list with the address held for each account, engagement letters and retainer terms, GST/HST returns filed to date, payroll records with each employee’s work location, subcontractor invoices, and bank and processor statements.
First 30 Days (Cleanup & Setup)
Set up QuickBooks Online or Xero with a province on every client record, build the deferred revenue account from the retainer terms, load the current rate table, open or correct the payroll and GST/HST accounts, and register WSIB where staff are on the payroll.
Monthly Close
Bank and processor reconciliation, earned retainer released from deferred revenue, the province checked on every new client before the first invoice, subcontractor coding, and the GST/HST position reviewed against line 101 and line 108.
Quarterly Planning Review
Revenue concentration by client and the personal services business question, salary and dividend mix against what you are drawing, any change to a participating province’s rate, and the province of employment for new remote hires.
Year-End Close & T2 Filing
Trial balance, financial statements with deferred revenue shown on the face, Schedule 8 capital cost allowance, the T2 with GIFI, and the address evidence filed with the year so it can be found again.
Get Your Administrative Service Business Taxes Done Right Today
Affordable Pricing for Administrative Service Businesses
We believe in clear, upfront pricing so you know exactly what to expect. All fees include HST.
- Tax Preparation (Corporation) — From $400
- Tax Return Filing (Corporation) — From $400
- Tax Compliance Audit — FREE CRA audit support for our clients
- Tax Strategy — FREE for our clients
- Accounting Base Plan — From $100 per month
- Bookkeeping Management — Free for our Accounting clients
- Financial Reporting — Free for our Accounting clients
- Business Formation — Flat $35
- Incorporation Process — Flat $35
- Entity Setup Assistance — Flat $35
- Full-Service Payroll — From $125 per month
Payment is by Interac e-Transfer to info@gondaliyacpa.ca only. Security question: Not Applicable, as auto-deposit is enabled.
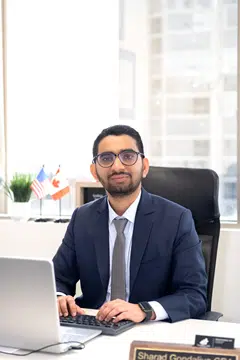
Meet Your Lead Administrative Services Accountant
Two people handle your file year after year, and you speak to them directly rather than to whoever happens to be free. Between them they cover the sales-tax side and the corporate side of a service business that bills across provinces.
What Our Clients Say
1300+ five-star reviews from administrative service and back-office business owners across Ontario.
Serving Administrative Service Businesses Across Ontario
Our CPA team looks after virtual assistant practices, answering and call services, records and document preparation businesses, back-office providers and bookkeeping and payroll bureaus throughout Ontario. We know how place of supply, deferred retainer income, out-of-province payroll and client concentration actually run through a business like yours, what CRA examines on this kind of file, and where the evidence has to sit before anybody asks for it.
Toronto (ON)
55 Queen St E Ste 1205, Toronto, ON M5C 1R6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Mississauga (ON)
5373 Bullrush Dr, Mississauga, ON, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Brampton (ON)
4 Starhill Crescent, Brampton, ON L6R 2P9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Scarborough (ON)
24 Clementine Square, Scarborough, ON M1G 2V7, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Vaughan (ON)
19 Cabinet Crescent, Woodbridge, ON L4L 6H9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Oshawa (ON)
210 Durham St, Oshawa, ON L1J 5R3, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Ottawa (ON)
2090 Neepawa Ave a314, Ottawa, ON K2A 3L6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Etobicoke (ON)
60 Stevenson Rd #1601, Etobicoke, ON M9V 2B4, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Hamilton (ON)
70 Starling Dr, Hamilton, ON L9A 0C5, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Guelph (ON)
1155 Gordon St, Guelph, ON N1L 1S8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Windsor (ON)
4387 Guppy Ct, Windsor, ON N9G 2N8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
North York (ON)
150 Graydon Hall Dr #912, North York, ON M3A 3B2, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Administrative Service Business Accounting & Tax FAQs
Related Industries We Serve
Staffing Agencies
- Worker classification and slips
- High-volume payroll and WSIB
- Corporate tax and HST filing
Home-Based Businesses
- Deductions for a business run from home
- HST registration and filing
- Bookkeeping and personal tax
Small Businesses
- Corporate tax planning for small businesses
- Business tax filing and statements
- Payroll and bookkeeping services
Incorporated Businesses
- T2 corporate returns and GIFI
- Salary, dividend and SBD planning
- Compilation statements and incorporation
Administrative Service Business Accounting & Tax Done Right.
T2 filing with retainer income separated from hourly and per-project fees, GST/HST charged at the rate your client’s province requires with the address evidence kept behind it, 13% in Ontario and 5% where there is no HST, deferred revenue and the reserve for work still owed, payroll with the province of employment determined for every remote employee, the personal services business question answered before you incorporate rather than after, and catch-up and disclosure work when years have been missed. AFFORDABLE flat fees, no hourly billing. Licensed CPA Ontario. 1300+ five-star reviews. 30-Day Money-Back Guarantee.