



Tax Accountant for Human Resources Consultants in Ontario and Across Canada
A policy manual for a manufacturer in Moncton, a compensation study for a hospital group in Halifax, a misconduct investigation for a retailer in Charlottetown, and a fractional engagement with a software firm in Calgary. One consultant, one service, four invoices, and four different rates of tax. Advisory fees are a taxable supply, so the $30,000 small-supplier test over four consecutive calendar quarters is crossed on a single fractional retainer, and from that point the rate on each engagement follows the client: 13% where the supply is made in Ontario, 15% in New Brunswick, Newfoundland and Labrador and Prince Edward Island, 14% in Nova Scotia since the rate came down on 1 April 2025, and 5% GST everywhere else in Canada. Nova Scotia is the figure most often got wrong, because the number carried in most heads and most invoicing templates is the one that stopped applying. Then the credits, which are the reason registration is not purely a cost: the supply is taxable rather than exempt, so section 169 lets you recover the tax on the benchmarking data licences, the practice management software, the laptop and the mileage to a client workplace. Then the corporate side, where a Canadian-controlled private corporation claims the small business deduction under ITA section 125 against the first $500,000 of active business income rather than paying up to 53.53% personally — at an AFFORDABLE flat fee agreed before the work starts.
AFFORDABLE Human Resources Consultant Tax Accountant
Almost every question we are asked on a human resources consulting file narrows down to one box on one invoice. Nobody doubts the fee is taxable and nobody doubts the threshold is crossed, so neither of those is really the issue. The rate is. A practice run out of a spare room in Guelph can carry a client list spread over six provinces and four separate rates, and an invoicing template set up once in the first year will keep repeating whatever was typed into it. Put 13% on all of them and you have over-collected from some clients and under-collected from others, and the two mistakes do not cost the same amount to put right.
The practices we act for are not the national consultancies. A fractional chief human resources officer on three retainers, two of them outside Ontario. A compensation and job evaluation specialist whose year arrives in six-week projects. An investigator taking harassment and misconduct files from employers and from law firms, who subcontracts a second investigator when two complainants need separate interviewers in the same week. A policy and handbook practice billing fixed fees. What they have in common is a client list that crossed a provincial boundary long before anybody sat down and thought about sales tax.
You know the employment law better than we ever will. We will set the rate from the right address, keep the evidence that stands behind it, and file what follows.
Two lines we draw plainly. We give no employment law advice of any kind — not on an employer’s obligations, not on a termination entitlement, not on whether a policy complies with a statute, and not on the conduct or the outcome of an investigation. And we will not tell you on a web page whether a fractional retainer makes your corporation a personal services business, because that turns on your actual engagement. If you supply workers rather than advice, our employment agencies and staffing agencies pages fit better; if training is the whole business, see corporate trainers; if you advise on occupational health and safety, see health and safety consultants.
Our Official Partners
Accounting That Starts With the Client’s Address
Four things make a human resources consultancy different from a generic service business, and all four are decided before the work is done rather than at year end. Each one is a box on an invoice or a line in a ledger that nobody else is going to fix for you.
Stay Compliant on Every Invoice You Issue
The exposure on a consulting practice is rarely the fee total. It is the rate charged on it, the deposit reported in the wrong period, and the associate paid on a handshake.
Accounting & Tax Experts for Human Resources Consultants
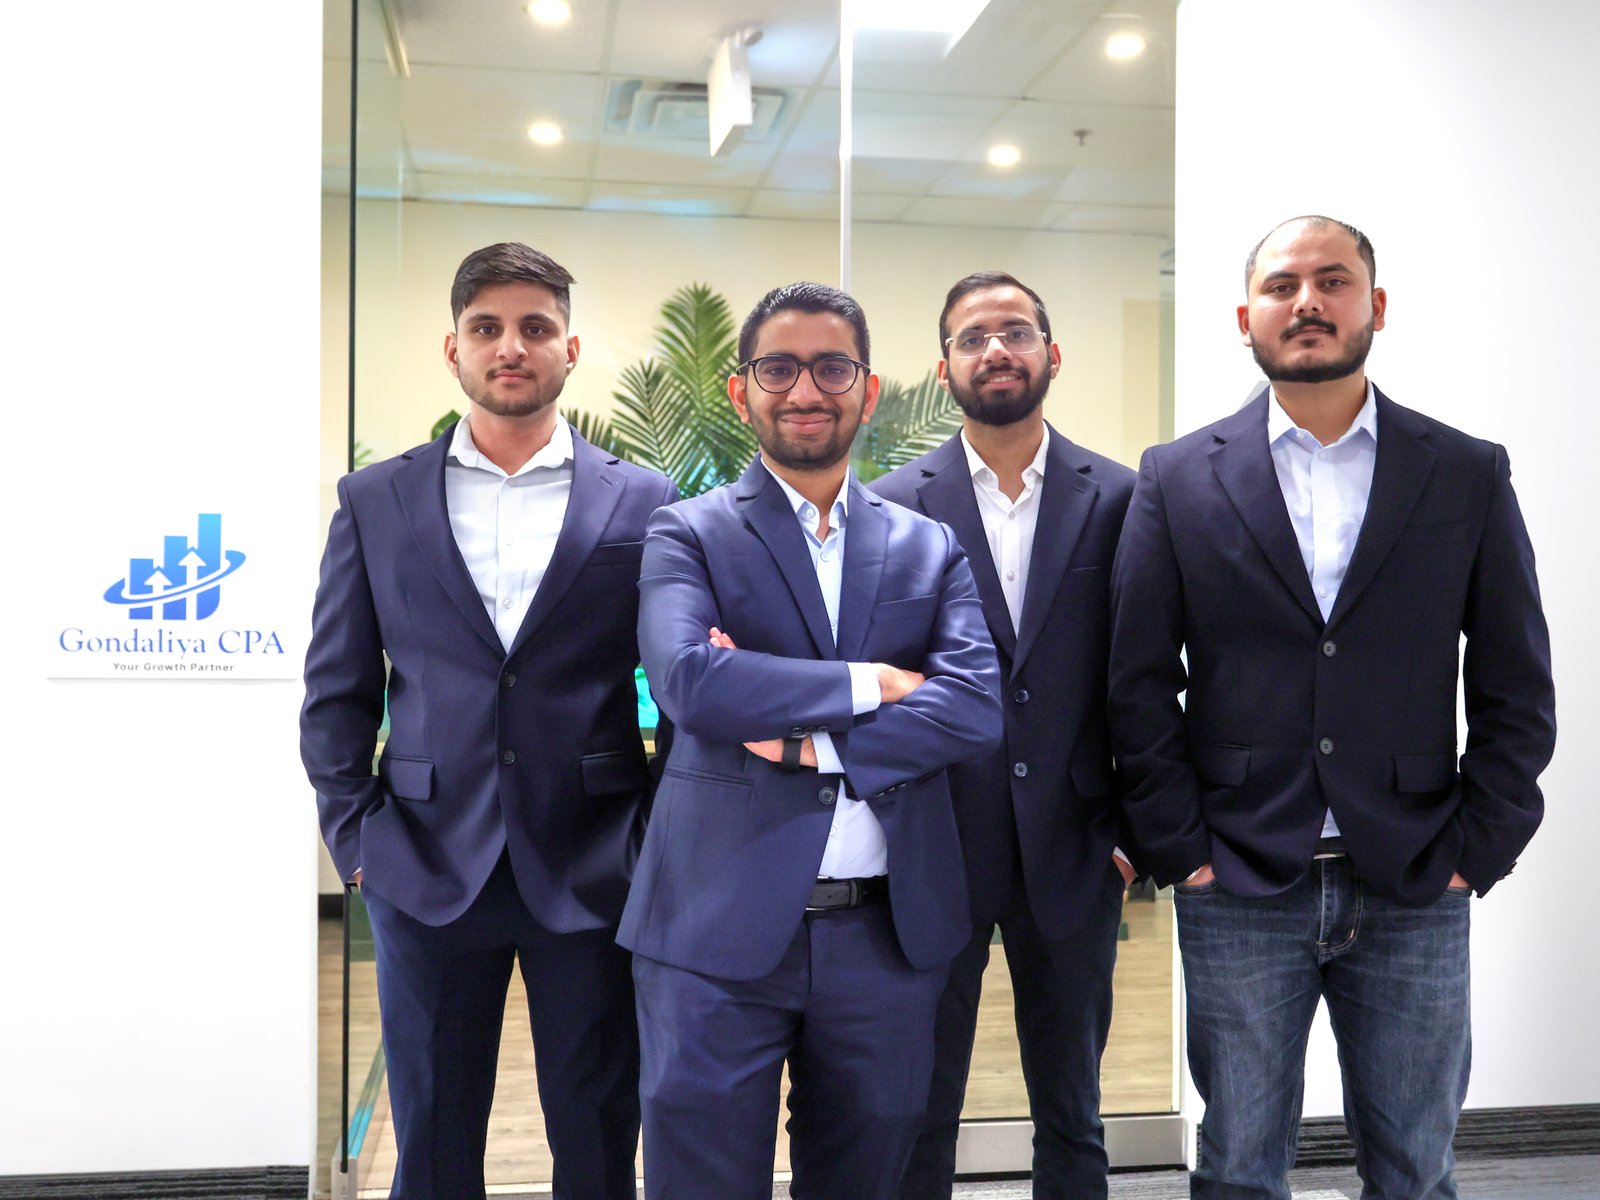
- AFFORDABLE + Registered CPA Firm
- Business and Corporate Tax Expert
- Small & Medium Business Expert
- Accounting, bookkeeping, and tax filing
- CPA (Chartered Professional Accountant)
- 1300+ 5-star Google reviews
- 30-Day Money-Back Guarantee
- 60-Day Fees Matching Policy
Why Choose Our Accounting Services for Human Resources Consultants?
Tax Planning — The Rate Map First
We map every client to a province and a rate before the next invoice goes out, then check what the template has been doing, because a wrong rate repeats quietly until someone looks.
Bookkeeping — Deposits Held Apart
Retainers and project deposits carried as a liability until the work is delivered, with the tax on them reported in the period they were received rather than the period they were earned.
Consulting — Credits and Structure
Section 169 credits claimed on the data licences, software and travel the practice actually runs on, and the incorporation question modelled on your client mix rather than on a rule of thumb.
CRA Representation — On the Facts
When a rate, a credit apportionment or an associate’s status is challenged, we answer with the client address record and the engagement file rather than with an explanation built afterwards.
Google Reviews
HR Consulting Clients
Human Resources Consultant Tax and Accounting Services in Ontario
Business and Corporate Tax Filing
Your T2 or Form T2125 with the small business deduction applied against the $500,000 limit, instalments set once the balance justifies them.
Place of Supply Rate Map
Every client mapped to a province and a rate from the address you obtained in the ordinary course of business, held with the engagement letter.
Wrong Rate Clean-Up
Invoices already issued at the old Nova Scotia rate or at Ontario’s rate for an out-of-province client, reviewed and corrected properly.
Retainers and Deposits
Unearned retainers carried as a liability, with the tax reported in the period received under section 168 rather than when the fee is earned.
Input Tax Credits Under Section 169
Benchmarking data licences, practice management software, the laptop and the mileage to a client workplace, recovered rather than absorbed.
Quick Method Analysis
The Quick Method run against the regular method on your own figures, including the $400,000 ceiling and what it does to your credits.
Personal Services Business Review
Whether ITA subsection 125(7) reaches a fractional retainer, what paragraph 18(1)(p) would cost, and the evidence that points the other way.
Associates and Payroll
The classification question with you as the payer, T4A slips for fees for services, and real payroll from the first cheque where you do hire.
Non-Resident Clients
Where a supply to a client outside Canada is zero-rated, what has to be true for it, and how the credits work when it is.
Vehicle, Home Office and Kit
The mileage log that defends the drive to a client site, the home office under ITA subsection 18(12), and the equipment the practice runs on.
Incorporation and Client Mix
Modelled on your client concentration and your draw, not on a revenue rule of thumb, with salary and dividends compared on real numbers.
Catch-Up Filing
Overdue corporate or personal years and unfiled GST/HST returns brought up to date, with relief requested where the facts support it.
Accounting & Tax Services Tailored for Human Resources Consultants
Real, practitioner-level CPA expertise for sole practitioners, fractional chief human resources officers, compensation specialists, workplace investigators and policy practices — built around the place of supply rules, the retainer, and the associate you bring in for one file.
- We prepare your corporation’s T2 or your Form T2125 as a sole proprietor, claim the small business deduction under ITA section 125 against the $500,000 limit, and file on time so the late filing penalty never starts.
- That penalty is 5% of the balance owing plus 1% for each complete month the return is late, to a maximum of twelve months, and it is charged on a balance you may already have the cash to pay.
- We set instalments once the tax owing justifies them, because nothing is withheld at source on consulting fees and a practice that has never paid instalments meets the requirement in its second profitable year.
- We claim business-use-of-home under ITA subsection 18(12), limited to the income of the business with the excess carried forward, and we keep the calculation on the same basis from one year to the next.
- We keep the six years of records ITA section 230 requires, including the client address evidence behind each rate, because a sales tax question arriving three years later is answered from the file or not at all.
- This is the first thing we build and the one that decides most of what follows. The place of supply rules for a service generally look to the recipient’s address obtained in the ordinary course of business, and that address sets the rate.
- So we map every client to a province: 13% where the supply is made in Ontario, 15% in New Brunswick, Newfoundland and Labrador and Prince Edward Island, 14% in Nova Scotia, and 5% GST everywhere else in Canada.
- The address we use is the business address most closely connected with the supply, which is not always the one on the signature block, and we record which address was used and when it was obtained.
- We then check the template, because the rate is set once in your invoicing software and repeats until somebody looks at it. A practice that added its first Atlantic client in year two usually never changed the default.
- And we keep the map current as the client list moves, since a head office relocation or a new regional contact can change the rate on the next invoice without anybody treating it as a tax event.
- Nova Scotia’s HST rate came down to 14% effective 1 April 2025, the provincial part falling by one percentage point. Supplies made before that date carried the former rate, and both numbers are correct for their own period.
- It is the single most common error we see on a consulting invoice, because the old figure is the one in the template, in the memory and in the spreadsheet somebody built when the practice took its first Halifax client.
- Over-collecting and under-collecting are not symmetrical problems. Tax collected is tax to be remitted whether or not it should have been charged, while tax not charged is usually money you now have to find yourself.
- So we review what has actually been invoiced rather than what the engagement letters say, correct the issued invoices properly, and adjust the returns for the affected periods instead of quietly fixing the rate going forward.
- Where a client has already paid at the wrong rate we deal with the credit note and the refund of the excess tax in the right order, so the correction does not create a second problem in the next return.
- A retainer has two dates and they are rarely in the same quarter. Section 168 makes the tax payable at the earlier of the day the consideration is paid and the day it becomes due, which is usually when the money arrives.
- The revenue, though, is earned only as the service is performed. An unearned retainer is a liability of the practice until the work is delivered, not sales, and that is true however long the engagement runs.
- So we report the tax in the period you received the deposit and carry the fee as deferred revenue until the hours or the deliverables land, which keeps the HST return and the income statement both right.
- On a fixed-fee investigation or a six-week compensation study we track what has been delivered against what was quoted, so the year-end does not depend on somebody remembering how far a file had got in December.
- And we handle the cancelled engagement properly: what is refunded, what is retained for work already done, and what that does to the tax already reported, rather than leaving an old deposit sitting in the ledger for years.
- Registration is not purely a cost, and this is why. Because advisory fees are a taxable supply rather than an exempt one, section 169 lets you recover the tax on what you buy to make them.
- For this practice that means the salary benchmarking data licence, the practice management and survey software, the laptop and second monitor, the professional subscriptions, and the mileage and travel to a client workplace.
- The test is the extent to which the property or service is acquired for consumption, use or supply in your commercial activity, so a laptop used partly at home for other things is claimed on that basis.
- We keep the supporting documentation the credit depends on, because a credit is only as good as the invoice behind it and a card statement showing an amount and a vendor name is not an invoice.
- Where a non-resident supplier charges you tax on a digital subscription, we check that it was charged correctly and that your registration number has been given where it should have been, rather than claiming whatever appears.
- Registration is required once worldwide taxable supplies exceed $30,000 in a single calendar quarter or over the four previous consecutive calendar quarters, and consulting fees count in full toward that test.
- For most of these practices the threshold goes by on a single fractional retainer, so the practical question is not whether to register but when the obligation actually arose and what was invoiced in the meantime.
- The Quick Method is available only where annual taxable supplies stay within $400,000, and the remittance rate depends on the province and the type of business rather than on a single national figure.
- It bars credits on your operating inputs while leaving credits on capital property available, which matters for a practice whose largest recoverable costs are data licences and software rather than equipment.
- So we run both methods on your own figures before choosing, and you can try the arithmetic yourself with our Quick Method calculator before you speak to us.
- A fractional engagement is the fact pattern worth checking. ITA subsection 125(7) defines a personal services business where an incorporated employee performs the services and would reasonably be regarded as an officer or employee of the recipient but for the corporation.
- The exclusions matter as much as the test: the rules do not apply where the corporation employs more than five full-time employees throughout the year, or where the services are supplied to an associated corporation.
- If the rules do reach an engagement the cost is severe. The small business deduction is denied on that income and ITA paragraph 18(1)(p) restricts deductions to the incorporated employee’s salary and benefits and a short list of specified amounts.
- So we work on the evidence that points the other way: concurrent clients, your own tools and premises, a real chance of profit and risk of loss, your own insurance, and engagement letters that match how the work is actually done.
- We will not tell you on a web page whether the rules reach your retainer, because it turns on your actual arrangement. We look at the engagement, we tell you plainly, and we document the position while the work is live.
- When two complainants need separate interviewers in the same week you bring in an associate, and at that moment you are the payer and the classification question becomes yours rather than your client’s.
- It is decided on the whole relationship: control over how the work is done, ownership of tools, chance of profit and risk of loss, and integration into your practice. The label in the agreement does not settle it.
- Where the associate is genuinely independent you report the fees for services on a T4A, with no CPP or EI withheld, and we set that up so the slips are not being reconstructed in February.
- Where the arrangement is employment in substance we say so and set payroll up properly from the first payment, with source deductions, remittances and T4s, because a correction after the fact costs more than doing it once.
- If you take work from law firms as a retained expert, we keep the billing and the subcontract trail separate per engagement, since that is the file where a question about who paid whom is most likely to arrive.
- A consulting supply made to a client outside Canada can be zero-rated, which means tax at 0% while your input tax credits on the inputs to that work remain fully available to you.
- Whether a particular engagement qualifies is a question of fact on the terms of that engagement, so we look at what is actually supplied and to whom before anything is invoiced at 0%.
- That matters more than it sounds, because the difference between a zero-rated supply and an exempt one is the difference between keeping your credits and losing them on the related costs.
- Where you travel to a client outside the province or the country, we keep the expense record on the same basis as the domestic files so the credits and deductions do not fall apart at year end.
- We advise on Canadian tax and coordinate with a specialist where another country’s rules are engaged, rather than guessing at a foreign filing obligation that is not ours to answer.
- Most of this practice runs from a home office and a laptop, so these are the deductions that actually move the number, and they are the ones most often claimed on an estimate rather than a record.
- The home office is claimed under ITA subsection 18(12), deductible only against the income from that business with any excess carried forward, on a reasonable area or usage basis applied consistently each year.
- Vehicle costs are deductible on the business portion, which means a log. The drive to a client workplace for an investigation interview is business; the drive to your own office at home generally is not.
- Equipment, software and the data licences a compensation practice depends on are tracked as current costs or capital depending on what they are, with the input tax credits claimed on the same evidence.
- We keep all of it in one set of books rather than two, so the T2 or the T2125, the HST returns and the credits all come off the same records instead of three versions of the year.
- Incorporation brings the small business deduction under ITA section 125 against the first $500,000 of active business income, which is the whole reason most consultants ask about it in the first place.
- But for this practice the question is inseparable from the client mix, because a corporation whose revenue comes mostly from one long fractional retainer is the arrangement the personal services business rules are aimed at.
- So we model it on your actual engagements and your actual draw rather than on a revenue rule of thumb, and we say plainly when the answer is that incorporating would not help you yet.
- We compare salary against dividends on real numbers, including the RRSP room salary creates, the CPP cost it carries, and what you actually need to take out of the practice each month.
- And we choose a fiscal year end deliberately, which for a practice whose work arrives in project waves is worth a conversation rather than defaulting to December because that is what the forms assume.
- When a rate charged on an out-of-province invoice is questioned, we answer with the client address record and the engagement letter behind it rather than with an explanation assembled after the query arrives.
- When your input tax credits are reviewed, we produce the invoices behind them and the basis on which anything used partly privately was apportioned, which is where most credit reviews are actually won or lost.
- When an associate is reassessed as your employee, we deal with it on the classification factors and the real working arrangement, and we deal with the payroll consequences that follow if the reassessment stands.
- When the personal services business question is raised on a fractional retainer, we put forward the independence evidence built while the engagement was live, which is worth considerably more than evidence assembled afterwards.
- We file the Notice of Objection within 90 days of a reassessment, request relief from penalties and interest on Form RC4288 where the facts support it, and use Form RC199 before the CRA contacts you where that is still open.
HR Consulting Tax Check
Six quick questions on your rates, your retainers, your credits and your associates. No email required, and the result tells you what to raise first.
1. Do you invoice clients in more than one province?
2. Has the rate in your invoicing template been checked since 1 April 2025?
3. Are retainers received in advance carried as a liability until the work is delivered?
4. Do you claim input tax credits on your data licences, software and travel?
5. Does more than half your revenue come from a single retainer or client?
6. Do the associates you subcontract receive a T4A for fees for services?
Free CPA Consultation for Human Resources Consultants
Case Studies: Human Resources Consultants
Toronto HR Consultancy — Three Years of Atlantic Invoices at the Wrong Rate
The problem: A Toronto practice with a fractional retainer in Moncton, a policy project in Charlottetown and two Halifax clients had charged 13% on every invoice since the day it registered. The invoicing template had been set up in the first year, when every client was in Ontario, and nobody had touched the tax field since. Two of the Atlantic engagements had been running for three years.
What we did: We built the client address record first, mapped each client to the province of the address obtained in the ordinary course of business, and worked out what should have been charged in each period, including the Nova Scotia change on 1 April 2025. We corrected the issued invoices, adjusted the affected returns rather than quietly fixing the rate going forward, and reset the template so each client now carries its own rate.
The result:
- Under-collected tax quantified and settled on a known number, not a guess
- Client address evidence held with every engagement letter from then on
- Template rebuilt so a new province no longer inherits Ontario’s rate
Mississauga Compensation Practice — A Year Booked on Deposit
The problem: A Mississauga compensation and job evaluation specialist billed 50% of each project on signature. Deposits were being recorded as revenue when received, so a December that happened to contain four signed engagements looked like the best month in the practice’s history while most of the work was delivered the following spring. The HST on those deposits had also been reported late, in the quarter the work finished.
What we did: We separated the two dates. Tax on each deposit was reported in the period it was received under section 168, and the fee itself was carried as deferred revenue until the study was delivered. We then rebuilt the prior year on the same basis and tracked delivery against what was quoted for every open file.
The result:
- HST on deposits reported in the right period, ending the recurring lateness
- Deposits carried as a liability until delivery, not booked as sales
- Project margin visible per engagement rather than per calendar month
Ottawa Workplace Investigator — An Associate Reassessed
The problem: An Ottawa investigator taking files from employers and law firms used the same associate on roughly forty weeks of work a year, set her schedule, supplied the templates and the case management system, and paid her monthly on an invoice. No slips had ever been issued. The CRA reassessed the arrangement as employment and raised source deductions with penalties and interest.
What we did: We looked at the factors honestly rather than arguing the label in the agreement, and told the client that on control, tools and integration the reassessment was largely right. We dealt with the payroll consequences, set up proper payroll from that point, and separated the genuinely independent associates, who now receive a T4A for fees for services each February.
The result:
- Payroll set up correctly rather than argued about for another year
- Genuinely independent associates identified and reported on T4A slips
- Engagement terms rewritten to match how the work is actually done
Our clear, efficient process ensures every step is transparent, with no surprises and no hourly billing.
Kickoff (Document Request)
Collect your client list with addresses, your engagement letters, your last four HST returns, your invoicing template, and the associate agreements behind anyone you subcontract.
First 30 Days (The Rate Map)
Build the client address record, set the rate for each client, and check what the template has actually been charging against what it should have been.
Position Review
Retainers and deposits separated from earned fees, section 169 credits identified, the Quick Method tested against the regular method, and the associates classified.
Annual Planning Review
Incorporation against your client mix, salary versus dividends on real numbers, the personal services business exposure on any fractional retainer, and your year end.
Year-End Close & Filing
T2 or Form T2125 with the small business deduction claimed, HST returns reconciled to the ledger, T4A slips issued, and instalments set for the year ahead.
Get Your Consulting Rates and Returns Reviewed Today
Affordable Pricing for Human Resources Consultants
We believe in clear, upfront pricing so you know exactly what to expect. All fees include HST.
- Tax Preparation (Corporation) — From $400
- Tax Return Filing (Corporation) — From $400
- Tax Compliance Audit — FREE CRA audit support for our clients
- Tax Strategy — FREE for our clients
- Accounting Base Plan — From $100 per month
- Bookkeeping Management — Free for our Accounting clients
- Financial Reporting — Free for our Accounting clients
- Business Formation — Flat $35
- Incorporation Process — Flat $35
- Entity Setup Assistance — Flat $35
- Full-Service Payroll — From $125 per month
Payment is by Interac e-Transfer to info@gondaliyacpa.ca only. Security question: Not Applicable, as auto-deposit is enabled.
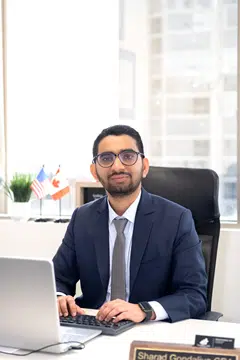
Meet Your Lead Accountant
Meet your lead accountant. As your business and professional needs grow, your dedicated CPA stays the same person.
What Our Clients Say
1300+ five-star reviews from HR consultants, professional practices and owner-managed businesses across Ontario.
Serving Human Resources Consultants Across Ontario
Our CPA team provides specialized accounting and tax solutions for human resources consultants across Ontario, from sole practitioners running a fractional practice out of a home office to incorporated consultancies with associates on several files at once. Wherever your clients are, the rate on the invoice is set from their address and not from yours, so we work the same way whether your list is entirely local or spread across six provinces.
Toronto (ON)
55 Queen St E Ste 1205, Toronto, ON M5C 1R6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Mississauga (ON)
2100 Camilla Rd #716, Mississauga, ON L5A 2J8
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Brampton (ON)
4 Starhill Crescent, Brampton, ON L6R 2P9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Scarborough (ON)
24 Clementine Square, Scarborough, ON M1G 2V7, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Vaughan (ON)
19 Cabinet Crescent, Woodbridge, ON L4L 6H9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Oshawa (ON)
210 Durham St, Oshawa, ON L1J 5R3, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Ottawa (ON)
2090 Neepawa Ave a314, Ottawa, ON K2A 3L6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Etobicoke (ON)
60 Stevenson Rd #1601, Etobicoke, ON M9V 2B4, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Hamilton (ON)
70 Starling Dr, Hamilton, ON L9A 0C5, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Guelph (ON)
1155 Gordon St, Guelph, ON N1L 1S8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Windsor (ON)
4387 Guppy Ct, Windsor, ON N9G 2N8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
North York (ON)
150 Graydon Hall Dr #912, North York, ON M3A 3B2, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Human Resources Consultant Accounting & Tax FAQs
Related Industries We Serve
Accountant for Employment Agencies
- Supplies workers, not advice
- Placement and agency fees
- Payroll as the core activity
Accountant for Staffing Agencies
- Places workers with clients
- Payroll at scale
- Agency rather than adviser
Accountant for Corporate Trainers
- Training as the whole business
- Employer-paid programmes
- Course revenue, not retainers
Accountant for Health and Safety Consultants
- Occupational health and safety advice
- WSIB on both sides
- Certification course revenue
HR Consulting Tax Done Right.
Built for the practice whose invoices cross provincial boundaries: the place of supply rules applied client by client from the address you obtained in the ordinary course of business, Nova Scotia at 14% since 1 April 2025 rather than the figure still sitting in the template, the $30,000 registration test taken seriously on a single fractional retainer, section 169 input tax credits recovered on the benchmarking data licences and the software the practice actually runs on, retainers reported for tax when received under section 168 and carried as deferred revenue until the work is delivered, the personal services business exposure under ITA subsection 125(7) assessed on your real engagement with the paragraph 18(1)(p) consequence explained before it arrives, and the associates you subcontract classified honestly with T4A slips where the arrangement is genuinely independent. No employment law advice, no guessed rates, and an AFFORDABLE flat fee agreed before the work starts.