



Tax Accountant for Business Sellers in Ontario and Across Canada
The buyer wants the assets. You want to sell the shares. The gap between those two prices is mostly a tax number, and it is decided by things that have already happened. ITA section 110.6 gives the lifetime capital gains exemption on qualified small business corporation shares, but the test looks back: substantially all of the asset value used in an active business at closing, and more than half of it throughout the 24 months before. Surplus cash, a portfolio, a rental unit held in the company — any of them can fail it, and purification is a two-year project, not a closing-week adjustment. Then the agreement itself, where what the money is called changes what it is: a non-compete allocation falls under ITA section 56.4 and can be ordinary income rather than a capital gain; an earnout changes when proceeds are recognised; and selling to a corporation you are not at arm’s length from brings ITA section 84.1, which can turn your gain into a dividend. We put the numbers on the table before the letter of intent, at an AFFORDABLE flat fee agreed before the work starts.
AFFORDABLE Business Seller Tax Accountant
Most sellers come to us at the wrong time. Not because they are careless, but because a sale does not feel real until somebody puts a number in writing, and by then the structure is largely set. The questions that decide what you keep are asked much earlier: what is on the balance sheet, who owns the shares, how long they have been owned that way, and whether the corporation has been quietly accumulating cash it no longer needs for the business. None of those can be changed in the week before closing.
The sellers we act for are not running an auction with three banks in the room. An owner-manager in their sixties whose competitor has made an offer. Two partners who have decided to go separate ways and sell. A trades business being bought by a consolidator. A professional practice being handed to a younger partner with a corporation of their own, which is where section 84.1 arrives uninvited. A family business moving to the next generation. What they share is one large transaction, once, with no chance to do it again differently.
You know what your business is worth to a buyer. We will tell you what the structure costs you, in numbers, before you agree to it.
Three lines we draw plainly. We give no legal advice on the purchase agreement — not on an indemnity, a holdback, an escrow, a representation or whether a non-compete is enforceable; that is your counsel’s work. We do not value your business, and no multiple or rule of thumb appears anywhere on this page. And we will not tell you on a web page whether your shares qualify for the exemption, because that turns on your own balance sheet over the last two years. If you are buying rather than selling, our business buyers page fits better; if the business is closing rather than selling, see businesses winding down.
Our Official Partners
Accounting That Starts Before the Letter of Intent
Four things decide what a seller keeps, and three of them are settled before anyone shakes hands. Each is a number we can put in front of you while you still have the option to change it.
Stay Compliant Through a Transaction That Only Happens Once
A buyer’s advisers will look at years you had stopped thinking about. What they find becomes a price adjustment, an indemnity or a holdback, so the cheapest time to fix it is before they look.
Accounting & Tax Experts for Business Sellers
- AFFORDABLE + Registered CPA Firm
- Business and Corporate Tax Expert
- Small & Medium Business Expert
- Accounting, bookkeeping, and tax filing
- CPA (Chartered Professional Accountant)
- 1300+ 5-star Google reviews
- 30-Day Money-Back Guarantee
- 60-Day Fees Matching Policy
Why Choose Our Accounting Services for Business Sellers?
Tax Planning — The Structure First
We price the share route against the asset route on your own figures before the letter of intent, so the structure is a decision you made rather than one the buyer’s draft made for you.
Consulting — The Two-Year Runway
We test the shares against ITA section 110.6 on the last 24 months and say plainly what would have to move, and when, for them to qualify at a closing you have not scheduled yet.
Bookkeeping — Diligence-Ready
Clean statements, filed returns and reconciled remittances before the buyer’s advisers ask, because anything they find turns into a price adjustment, an indemnity or a holdback.
CRA Representation — Afterwards
The years the business operated stay open after you sell. We answer for them with the records that were kept at the time rather than with an explanation built once the query arrives.
Google Reviews
Business Seller Clients
Business Seller Tax and Accounting Services in Ontario
Corporate and Personal Tax Filing
The T2 for the year of sale including any short tax year, and your personal return reporting the disposition and the exemption claim.
Share Sale or Asset Sale
Both routes modelled on your own numbers, including what it costs to get asset-sale proceeds out of the corporation afterwards.
QSBC Qualification Review
The small business corporation test at closing and the 24-month test before it, measured against the corporation’s actual balance sheet.
Purification Planning
Surplus cash, portfolios and non-business property identified and a route out mapped, with the two-year runway stated honestly.
Section 84.1 Review
Where the buyer is a corporation connected to you or your family, whether the gain survives as a capital gain or is deemed a dividend.
Purchase Price Allocation
Inventory, depreciable property, goodwill in Class 14.1 and receivables, and what each line does to recapture against capital gain.
Earnouts and the Reserve
Proceeds not due until a later year brought in under the capital gains reserve, over a maximum of five tax years including the year of sale.
HST and the GST44 Election
Shares as an exempt financial instrument, assets as a taxable supply, and the ETA section 167 election where it is available.
Statements for Due Diligence
Compilation engagement financial statements and the schedules a buyer’s adviser asks for, prepared before the request arrives.
Catch-Up Filing Before Closing
Overdue corporate years, unfiled HST returns and missing slips brought current before they become a holdback in the agreement.
Payroll Through Closing
Final remittances, accrued vacation, bonuses paid before the deal and the T4 slips for a year that ends mid-stream.
CRA Audit Resolution
The operating years stay open after you sell, and an indemnity in the agreement means a reassessment is still your problem.
Accounting & Tax Services Tailored for Business Sellers
Real, practitioner-level CPA expertise for owner-managers selling once: the structure priced before the letter of intent, the shares tested against the two years behind you, and the agreement read for the words that change what the money is.
- We prepare the corporation’s T2 for the year of sale, including the short tax year that a closing date creates when control changes, and your personal return reporting the disposition.
- We claim the small business deduction under ITA section 125 against the $500,000 limit where it remains available, which on an asset sale depends on how much of the year’s income is still active business income.
- We set instalments for the year of the gain, because a capital gain on a sale is not withheld at source and a seller who has never paid instalments now has the largest tax bill of their life.
- We file on time so the late filing penalty never starts: 5% of the balance owing plus 1% for each complete month to twelve months, charged in the one year you can least afford it.
- We keep the six years of records ITA section 230 requires, including the asset-use schedule behind the exemption claim, because the year of sale is the year most likely to be looked at.
- This is the first conversation and the most valuable one. The vendor generally wants a share sale: a capital gain in your hands, one level of tax, and the exemption if the shares qualify.
- The buyer generally wants an asset sale: a cost base stepped up to what they paid, the liabilities they choose rather than the ones you have, and none of the corporation’s history.
- On an asset sale the gain, the recapture and the income arise inside the corporation, so getting the money to you is a second step with its own tax. That second step is what sellers forget to price.
- So we model both on your own figures and give you the after-tax number in each case, which is the only number that matters when you are comparing two offers.
- And we do it before the letter of intent, because a structure agreed in principle is very hard to reopen later without giving something else away to get it.
- The lifetime capital gains exemption applies to qualified small business corporation shares, and the conditions are specific. We test them rather than assume them, because most owners assume.
- At the time of sale the corporation must be a small business corporation: substantially all of the fair market value of its assets used principally in an active business carried on primarily in Canada.
- Throughout the 24 months before the sale, more than half of that asset value must have been so used, and the shares must not have been owned by anyone other than you or a related person.
- That backward-looking test is why this work cannot wait. A corporation that passed two years ago and has been accumulating cash since may not pass today, and nothing at closing changes the history.
- We will not tell you on a web page whether your shares qualify. We look at the balance sheets, we tell you plainly, and where they do not qualify we say what would have to change and over what period.
- Most owner-managed corporations that fail the test fail it for the same reason: they are good businesses that kept their money. Cash, a portfolio, a rental unit, a second property.
- So we identify what is not being used in the active business and what proportion of value it represents, which is the arithmetic the test actually runs on rather than a general impression.
- Then we map a route: what can be moved, what it costs to move it, what has to be paid out and in which year, and how long the whole sequence takes before the shares would qualify.
- The honest part of this conversation is the timing. A seller who wants to close in four months and needs two years of history cannot have both, and we say that rather than implying otherwise.
- Where purification is not realistic we price the alternative properly, including the asset sale and the cost of the second step out of the corporation, so the decision is made on comparable after-tax numbers instead of on hope.
- If the purchaser is a corporation you or your family are connected to, ITA section 84.1 is in play, and it is the provision that most often surprises a seller who thought the hard part was agreeing a price.
- It applies where an individual resident in Canada disposes of shares to another corporation with which they do not deal at arm’s length, where the two corporations are connected afterwards.
- Where it applies it can grind paid-up capital or deem a dividend to you instead of a capital gain, which removes both the capital treatment and the exemption in a single step.
- This is the normal shape of a sale to a child, to a key employee who has incorporated, or to a partner buying you out through their own holding company, so it comes up far more often than people expect.
- We review the structure against the provision before the papers are drawn, and where it reaches the transaction we say so plainly rather than leaving it for the buyer’s accountant to find afterwards.
- What the agreement calls the money changes what the money is, and the clearest example is the non-compete. ITA section 56.4 governs amounts received for a restrictive covenant.
- Subject to its exceptions and elections, such an amount is included in income rather than treated as proceeds of disposition, so a figure moved into that clause can be taxed very differently.
- The same is true of a consulting or employment agreement signed at closing: amounts under it are ordinary income to you, and a buyer who wants deductions has a reason to prefer them.
- On an asset sale the allocation across inventory, depreciable property, goodwill in Class 14.1 and receivables decides how much is recapture taxed in full and how much is a capital gain.
- We read the allocation schedule before it is signed and tell you what each line costs you, which is a different question from whether the total is the number you agreed.
- Very few sales pay everything on closing. Part is held back, part depends on next year’s results, and the tax treatment of each is not the same as the other.
- Where part of the proceeds is not due until a later year, ITA subparagraph 40(1)(a)(iii) allows a capital gains reserve, so the gain is brought into income over a maximum of five tax years including the year of sale.
- A longer reserve period applies to certain transfers of farm or fishing property and of small business corporation shares to a child, which matters on an intergenerational sale.
- An earnout that depends on future performance and a holdback against a warranty claim are different arrangements, and we look at the actual terms rather than the label used in the draft.
- Then we plan the cash: the tax on a gain can be due long before the final instalment of the price arrives, and that mismatch is the one that catches sellers out after closing.
- A sale of shares is a supply of a financial instrument and is exempt, so no GST/HST arises on the price. That alone is a reason buyers and sellers reach different conclusions about structure.
- An asset sale is generally a taxable supply, and on a business worth several million dollars the tax on it is not a rounding error even where the buyer would recover it.
- ETA section 167 permits a joint election where a supplier sells a business or part of a business and the recipient acquires all or substantially all of the property reasonably necessary to carry it on.
- The election is made on Form GST44 and filed with the recipient’s return, and it has conditions: it does not cover a supply of real property to a recipient who is not a registrant, among others.
- We check whether the election is available on your facts, make sure it is filed by the party who has to file it, and deal with closing the HST account afterwards rather than leaving it open and filing nil returns forever.
- A buyer’s advisers will ask for years you had stopped thinking about, and the quality of what comes back sets the tone for everything that follows in the negotiation.
- We prepare compilation engagement financial statements and the supporting schedules, and we reconcile them to the corporate returns already filed so that the statements and the returns tell the same story without needing a covering explanation.
- Where the books have been kept for tax rather than for a reader, we rebuild them to a standard a third party can follow, which is a different job from keeping them compliant.
- We also flag what diligence will find before it finds it: the long-term contractor who looks like an employee, the unremitted payroll balance, the shareholder loan nobody wrote down, the related-party rent nobody documented.
- Each of those becomes a price adjustment, an indemnity or a holdback if the buyer raises it first, and usually costs a fraction of that to deal with beforehand.
- Overdue returns are the most common reason a deal slows down, and they are entirely fixable. We bring the corporate years, the HST returns and the missing slips current.
- Where there is an exposure rather than simply a delay, the Voluntary Disclosures Program on Form RC199 is available before the CRA contacts you, and the timing of that is the whole point.
- Once diligence has raised the issue the voluntary route is harder to argue, so the sequence matters: disclose, then open the data room, rather than the other way around.
- We request relief from penalties and interest on Form RC4288 where the facts support it, and we deal with the balance so the buyer is not holding back against an unknown number.
- And we say plainly what the exposure is rather than minimising it, because an indemnity you signed without knowing the number is worse than a holdback you negotiated knowing it.
- A closing date rarely falls on a pay period boundary, so the final remittance, the accrued vacation and the bonus paid before the deal all need to land in the right year.
- On an asset sale the employees are generally terminated by the vendor and hired by the purchaser, which means final pay, accrued entitlements and T4 slips for a year that ends mid-stream.
- On a share sale the employer does not change, so payroll continues, and the question becomes which accruals sit in the price and which are settled before it.
- Directors remain personally liable for unremitted source deductions under ITA section 227.1, so an arrears balance left behind on closing does not quietly stay behind with the corporation once you have handed over the shares.
- We reconcile the payroll and source deduction accounts before diligence rather than after, because an unremitted balance is the single easiest thing for a buyer’s adviser to find and the hardest to explain away.
- Selling the business does not close the years you ran it. The normal reassessment periods keep running, and on a share sale the corporation carries its own history to its new owner.
- That is exactly why the agreement has an indemnity, so a reassessment of an operating year usually comes back to you whether or not you still own anything.
- When the exemption claim is reviewed, we answer with the asset-use schedule and the balance sheets kept at the time, which is worth considerably more than a reconstruction.
- When the purchase price allocation or a restrictive covenant amount is questioned, we produce the allocation schedule and the correspondence behind the figures the parties actually agreed at the time they agreed them.
- We file the Notice of Objection within 90 days of a reassessment, and we handle the correspondence so the buyer’s advisers are not answering questions about your years for you.
Business Sale Tax Check
Six quick questions on your balance sheet, your buyer and your paperwork. No email required, and the result tells you what to raise first.
1. Does the corporation hold cash, investments or property it no longer uses in the business?
2. Has anyone tested your shares against the 24-month QSBC conditions?
3. Is the buyer a corporation connected to you or to your family?
4. Does the draft agreement allocate an amount to a non-compete?
5. Are all corporate and HST returns filed and up to date?
6. Have you compared the after-tax result of a share sale against an asset sale?
Free CPA Consultation for Business Sellers
Case Studies: Business Sellers
Toronto Trades Business — Good Company, Wrong Balance Sheet
The problem: An owner in his late fifties had an unsolicited offer from a larger competitor and wanted to close in the spring. The corporation was profitable and had been for years, which was the problem: it was carrying several years of retained earnings in cash and a portfolio account, and a unit it had bought and rented out. On the numbers as they stood, non-business assets were well over the proportion the small business corporation test allows.
What we did: We measured the asset use properly, quarter by quarter, for the preceding 24 months rather than taking a general view, and told him plainly that the shares would not qualify at a spring closing. We mapped a purification sequence with the cost and timing of each step, and in parallel priced the asset sale, including the second step to get the proceeds out of the corporation, so the two routes could be compared after tax.
The result:
- Qualification tested on the real balance sheet, not assumed
- Both routes priced after tax before the letter of intent was signed
- Timing decision made by the seller, with the cost of each option known
Mississauga Practice — Sold to a Junior Partner’s Corporation
The problem: A practice owner had agreed to sell to a long-serving junior colleague who had recently incorporated. Price agreed, lawyers instructed, everyone pleased. Nobody had looked at the structure: the purchaser was a corporation that would be connected to the vendor’s corporation after closing, and the vendor was not dealing at arm’s length with it on the facts.
What we did: We raised ITA section 84.1 before the papers were drawn and set out what it would do to the vendor’s position, which was to put the capital treatment and the exemption at risk in a single step. We worked with both sides’ counsel on a structure that reflected the commercial deal the parties had actually agreed, and documented the basis for the position taken.
The result:
- Section 84.1 identified before signing rather than after closing
- Structure reviewed against the commercial terms both sides wanted
- Position documented at the time, not reconstructed later
Ottawa Manufacturer — The Clause That Changed the Tax
The problem: An asset sale was agreed at a headline figure, and late in the drafting the buyer moved a meaningful amount of the consideration into a five-year non-compete and a two-year consulting agreement for the vendor. The vendor read it as the same money arriving on a different schedule. It was not: it was a different kind of income.
What we did: We explained how ITA section 56.4 treats an amount received for a restrictive covenant, and that amounts under a consulting agreement are ordinary income rather than proceeds of disposition. We quantified the after-tax effect of the reallocation on the vendor’s own figures and sent it to counsel, so the point was negotiated as a price issue rather than accepted as drafting.
The result:
- After-tax cost of the reallocation quantified before signature
- Allocation negotiated knowingly instead of conceded in drafting
- Allocation schedule and reasoning kept for the file
Our clear, efficient process ensures every step is transparent, with no surprises and no hourly billing.
Kickoff (Document Request)
Collect the last three years of statements and T2s, the share register, the current balance sheet, the HST and payroll account positions, and anything the buyer has put in writing.
First 30 Days (The Two Tests)
Measure asset use over the preceding 24 months against the QSBC conditions, and review the proposed purchaser against ITA section 84.1 before the papers are drawn.
Structure Review
Share sale and asset sale priced after tax on your own numbers, purification mapped with its timing, and the allocation and covenant clauses read for what they do.
Diligence Support
Compilation statements and schedules prepared, overdue filings cleared, payroll and HST accounts reconciled, and the GST44 election dealt with where it applies.
Closing, Filing & After
The T2 for the year of sale including any short year, your personal return and the exemption claim, the reserve where proceeds are deferred, and instalments for the year ahead.
Get Your Sale Structure Priced Before You Sign
Affordable Pricing for Business Sellers
We believe in clear, upfront pricing so you know exactly what to expect. All fees include HST.
- Tax Preparation (Corporation) — From $400
- Tax Return Filing (Corporation) — From $400
- Tax Compliance Audit — FREE CRA audit support for our clients
- Tax Strategy — FREE for our clients
- Accounting Base Plan — From $100 per month
- Bookkeeping Management — Free for our Accounting clients
- Financial Reporting — Free for our Accounting clients
- Business Formation — Flat $35
- Incorporation Process — Flat $35
- Entity Setup Assistance — Flat $35
- Full-Service Payroll — From $125 per month
Payment is by Interac e-Transfer to info@gondaliyacpa.ca only. Security question: Not Applicable, as auto-deposit is enabled.
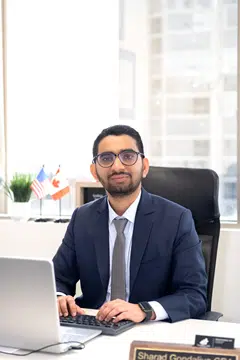
Meet Your Lead Accountant
Meet your lead accountant. As your business and professional needs grow, your dedicated CPA stays the same person.
What Our Clients Say
1300+ five-star reviews from business sellers, owner-managers and incorporated businesses across Ontario.
Serving Business Sellers Across Ontario
Our CPA team provides specialized accounting and tax solutions for business sellers across Ontario, from an owner-manager fielding a single unsolicited offer to partners running a structured process with advisers on both sides. Wherever the buyer is based, the questions that decide what you keep are about your own corporation and the two years behind it, so we start there.
Toronto (ON)
55 Queen St E Ste 1205, Toronto, ON M5C 1R6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Mississauga (ON)
2100 Camilla Rd #716, Mississauga, ON L5A 2J8
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Brampton (ON)
4 Starhill Crescent, Brampton, ON L6R 2P9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Scarborough (ON)
24 Clementine Square, Scarborough, ON M1G 2V7, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Vaughan (ON)
19 Cabinet Crescent, Woodbridge, ON L4L 6H9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Oshawa (ON)
210 Durham St, Oshawa, ON L1J 5R3, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Ottawa (ON)
2090 Neepawa Ave a314, Ottawa, ON K2A 3L6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Etobicoke (ON)
60 Stevenson Rd #1601, Etobicoke, ON M9V 2B4, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Hamilton (ON)
70 Starling Dr, Hamilton, ON L9A 0C5, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Guelph (ON)
1155 Gordon St, Guelph, ON N1L 1S8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Windsor (ON)
4387 Guppy Ct, Windsor, ON N9G 2N8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
North York (ON)
150 Graydon Hall Dr #912, North York, ON M3A 3B2, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Business Seller Accounting & Tax FAQs
Related Industries We Serve
Accountant for Business Buyers
- The other side of the table
- Cost step-up on an asset purchase
- Diligence rather than disclosure
Accountant for Businesses Winding Down
- Closing rather than selling
- Final returns and dissolution
- No purchaser at the table
Accountant for Private Equity Firms
- The institutional buyer
- Fund and portfolio reporting
- Acquires rather than exits
Investment Holding & Investment Companies
- Where proceeds often land
- Passive income and refundable tax
- After the sale, not during it
Business Sale Tax Done Right.
Built for the owner-manager who will sell once: the share route and the asset route priced after tax on your own figures before the letter of intent, the shares tested against the qualification conditions in ITA section 110.6 including the 24 months already behind you, purification mapped with its real timing rather than implied, ITA section 84.1 raised before the papers are drawn on a sale to family or to a key employee’s corporation, the non-compete allocation under ITA section 56.4 quantified so it is negotiated and not conceded, the capital gains reserve applied where proceeds are deferred, the ETA section 167 election dealt with on an asset sale, and the statements and filings cleared before the buyer’s advisers look. No legal advice on the agreement, no valuation, no guessed numbers, and an AFFORDABLE flat fee agreed before the work starts.