



Tax Accountant for Credit Repair Businesses in Ontario and Across Canada
Money taken at signup is not money you have earned yet. An enrolment fee, a six-month programme fee and a monthly subscription are all charged before the work behind them is performed, so on the day the card clears that cash is a liability rather than revenue. ITA 12(1)(a) brings amounts received for services not yet rendered into income, and ITA 20(1)(m) gives the reserve for the part still undelivered, which is how a prepaid programme is recognised month by month as the work is performed. Your fees are also taxable: unlike brokerages and lenders, you charge 13% HST on enrolment, setup, programme and subscription fees, and you claim input tax credits in full on advertising, software, credit report costs, rent and equipment. We build the deferred-revenue schedule, carry a provision where a money-back guarantee is offered, run agent payroll with WSIB, T4 slips and PD7A remittances, and file the T2 that holds your first $500,000 of active income near 12.2% in Ontario. Flat-fee, no hourly billing, CPA Ontario, 1300+ five-star.
AFFORDABLE Credit Repair Business Tax Accountant
A credit repair business sells a taxable service, and that one fact sets it apart from most of the finance category it gets filed under. Brokerages and lenders make exempt supplies and absorb the tax they pay on their own costs. You do not. Enrolment fees, setup fees, fixed-term programme fees and monthly subscriptions all carry 13% HST in Ontario, and every dollar of tax you pay on advertising, subscription software, credit report costs, office rent, computers and furniture comes back to you as an input tax credit. Owners who assumed that anything sitting in the finance aisle must be exempt have usually been paying that tax for years and claiming none of it back.
The second thing that shapes these books is timing. Almost everything you collect arrives before the corresponding work is performed, which means the cash in your bank and the revenue on your income statement are two different numbers in the same month. At Gondaliya CPA we hold prepaid enrolment and programme fees as deferred revenue and release them as the work is performed, and where a money-back guarantee is offered we carry a provision against revenue rather than waiting for a refund to leave the account. We work with fixed-term programme operators, monthly subscription models, credit-education and coaching practices and multi-agent offices, across Ontario and the rest of Canada.
Leave the numbers with us and keep your attention on the files.
Our Official Partners
Accounting That Understands How a Credit Repair Business Actually Works
A programme business carries a timing problem an ordinary service company never meets. The money arrives first and the work follows it across months; a six-month fee taken in January is mostly a liability until June; a money-back guarantee is a cost sitting quietly against revenue already banked; what you are able to bill and when is set by the rules the business operates under, which is a separate question from the month that billing becomes income; and your advertising line, normally the largest in the business, is carrying tax you are entitled to claim back. Gondaliya CPA works with that reality every day and delivers practical, operator-focused solutions throughout the GTA and the rest of Ontario.
Stay Compliant and Minimize Your Credit Repair Business Tax
Here, compliance and tax savings come out of the same place: one revenue schedule, built properly. Classify the deferral, the refund provision, the HST position and the agent payroll once, and the filings largely look after themselves while the tax falls in the year it genuinely belongs to.
Accounting & Tax Experts for Credit Repair Businesses
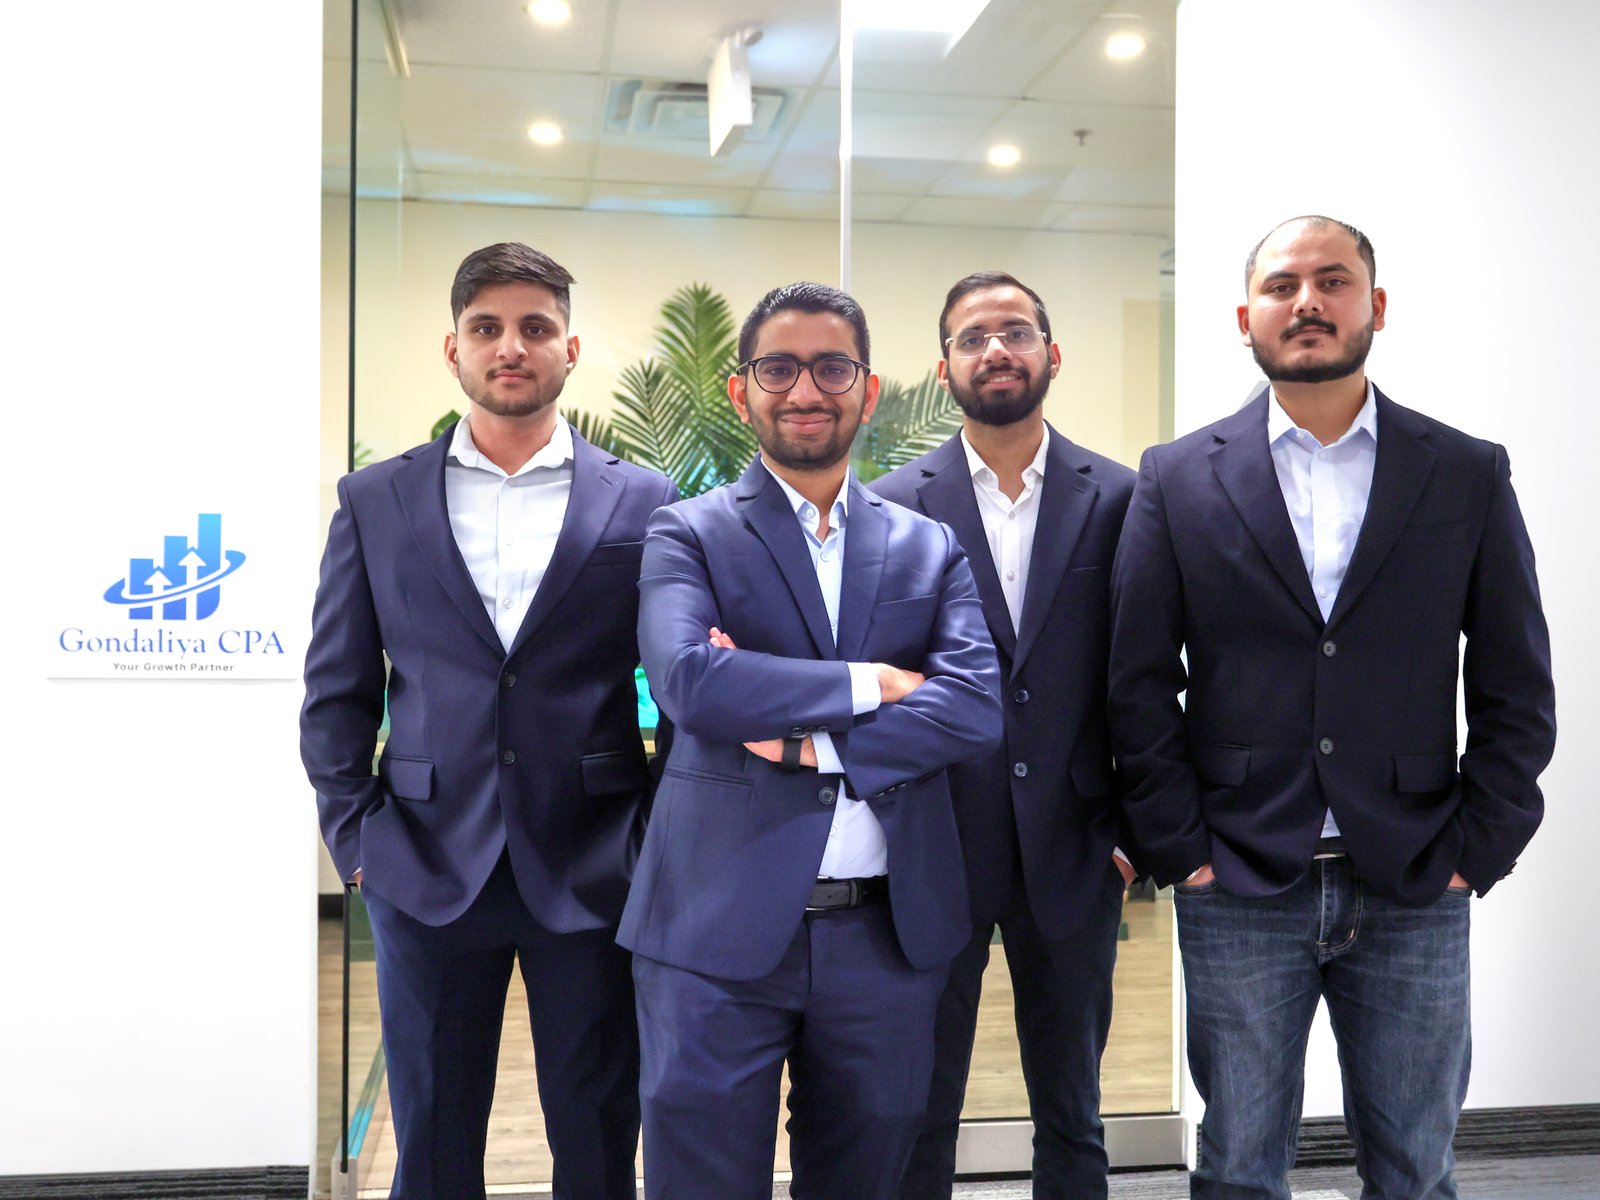
- AFFORDABLE + Fully Registered CPA Firm
- Business and Corporate Tax Expert
- Small & Medium Business Expert
- Accounting, bookkeeping, and tax filing
- Certified CPA
- 1300+ 5-star Google reviews
- 30-Day Money-Back Guarantee
- 60-Day Fees Matching Policy
Why Choose Our Accounting Services for Credit Repair Businesses?
Tax Planning — Deferral & Owner Pay
We keep active income inside the $500,000 Small Business Deduction near 12.2% in Ontario, claim the ITA 20(1)(m) reserve so prepaid fees are taxed in the year they are earned, balance salary against a 53.53% top personal rate, and guard the $1.25M Lifetime Capital Gains Exemption.
Consulting — Revenue Schedules & Refund Provisions
Our bookkeeping holds enrolment and programme fees as deferred revenue, releases them as the work is performed, carries a provision for refunds offered under your guarantee, and keeps the billing calendar and the revenue schedule as two separate reports.
CRA Representation — HST & Revenue Recognition
Where CRA takes issue with your input tax credits, with the year a programme fee entered income, or with how your agents are classified, we draft the response, build the revenue schedule a reviewer opens with, and seek relief on Form RC4288 where a prior error caused the penalty.
Bookkeeping — Agent Payroll & Growth
Agent payroll, commission and bonus runs, WSIB registration and reporting, T4 slips and ROEs all sit with us, and we model the profit level at which incorporating begins to pay before moving you from proprietorship to corporation.
Google Reviews
Credit Repair Clients
Credit Repair Business Tax and Accounting Services in Ontario
Corporate Tax Filing (T2) for Credit Repair Businesses
T2 preparation with delivered programme months on Schedule 125, fees still owed in service shown as a liability on Schedule 100, and Schedule 8 capital cost allowance.
Bookkeeping & Accounting for Credit Repair Businesses
Deferred-revenue and subscription bookkeeping with financial statements, clean payment-processor reconciliations and monthly reporting built for a programme business.
Payroll Services for Credit Repair Businesses
Every pay run for agents and file processors, commission and bonus included, with PD7A source deductions, WSIB reporting, and year-end T4 slips and ROEs.
GST/HST Filing for Credit Repair Businesses
Returns filed on fees taxable at 13%, with input tax credits claimed to the last dollar against advertising, software, credit report costs, rent and equipment.
Tax Planning for Credit Repair Businesses
Salary and dividend mix, the $500,000 small business deduction, the reserve for programme months still undelivered, and the $1.25M capital gains exemption.
Corporate Catch-Up Filing for Credit Repair Businesses
Unfiled T2 years reconstructed from processor statements and enrolment records, lodged in order, with penalty and interest relief pursued on Form RC4288.
CRA Audit Resolution for Credit Repair Businesses
Revenue recognition, HST and payroll queries answered, the schedule a reviewer opens with produced, and CRA handled directly on your behalf.
CPA Financial Statements (Notice to Reader) for Credit Repair Businesses
Compiled statements that present deferred revenue and the refund provision properly, ready for a lender, a landlord or a payment-processor review.
Incorporation Services for Credit Repair Businesses
Incorporation, share structure, the section 85 rollover on Form T2057, and a chart of accounts that separates earned revenue from fees still owed in service.
Catch-Up Bookkeeping Services for Credit Repair Businesses
Revenue schedules reconstructed, processor deposits matched back to client charges, and unclaimed input tax credits recovered until the file is current.
US Corporation & LLC Tax Filing for Credit Repair Businesses
Enrolments that reach across the border bring American filing obligations, permanent-establishment testing under the treaty, and relief for tax already paid there.
Voluntary Disclosure Program for Credit Repair Businesses
Unreported programme income, or HST that was never charged, brought forward on Form RC199 through the CRA Voluntary Disclosures Program ahead of any audit.
Accounting & Tax Services Tailored for Credit Repair Businesses
Real, practitioner-level CPA expertise for fixed-term programme operators, monthly subscription models, credit-education and coaching practices and multi-agent offices across Ontario — built for a business that gets paid well before the work is delivered.
- Your T2 is prepared with GIFI so Schedule 125 carries only the programme months delivered inside the fiscal year, while fees taken for months still to come sit on Schedule 100 as the liability they are.
- Capital cost allowance goes on Schedule 8: desks, chairs and office equipment fall into Class 8 at 20% and computers into Class 50, so the hardware behind a multi-agent floor is written down rather than expensed at once.
- One operator recovered $11,200 across two open years once we claimed the ITA 20(1)(m) reserve for programme months undelivered at each year-end, income the previous preparer had taxed the day every card was charged.
- The Small Business Deduction should hold your first $500,000 of active profit near a 12.2% Ontario combined rate, so we check early whether another company in your group is quietly splitting that limit with you.
- Filing falls due six months after the fiscal year-end and the balance two or three months in, and we work backwards from those dates so arrears interest never attaches to a bill that was affordable all along.
- We run the billing calendar and the revenue schedule as two separate reports, because the day a card is charged and the month the corresponding work is performed are different facts and only one belongs on the income statement.
- Every enrolment fee and fixed-term programme fee is posted to deferred revenue on receipt and released across the service period, so each month of the income statement shows what that particular month actually earned.
- Payment-processor deposits are reconciled back to the underlying client charges rather than banked as one lump, which is how discount fees, declines and partial refunds stop vanishing into an unexplained year-end variance.
- Where a money-back guarantee is offered, we carry a provision against revenue sized on your own cancellation history, instead of recognising the whole cost in whichever month a refund happens to leave the bank.
- One multi-agent office had been treating every deposit as sales; rebuilding fourteen months of the schedule moved $186,000 of undelivered programme fees off revenue and onto the balance sheet where they belonged.
- Sales agents and file processors sit on the employee-versus-contractor line, and it turns on control, tools, chance of profit and how integrated the person is, rather than on what the agreement happens to call them.
- Employees are paid through payroll with source deductions withheld and reported on the PD7A, while a genuinely independent contractor is reported on a T4A instead, and mixing the two is what a payroll review finds first.
- T4 slips and the T4 Summary are due the last day of February, and we reconcile the totals on those slips back against what was actually remitted on the PD7A before anything is filed with CRA.
- WSIB coverage is needed from your first hire and the premiums are deductible, so an account that was never opened is exactly the gap a payroll examination turns up on the day it finally arrives.
- Ontario Employer Health Tax starts only once payroll passes the $1,000,000 exemption, and the late-remittance penalty reaches 10% on a graduated scale, so one office saved roughly $4,300 by changing its remittance schedule.
- Unlike brokerages and lenders, your fees carry HST. Enrolment, setup, programme and monthly subscription billing are all taxable at 13% in Ontario, and that governs both what you charge and what you can claim back.
- Because the revenue is taxable, nothing restricts your input tax credits. We claim the full HST paid on advertising and lead generation, subscription software, credit report costs, office rent, computers and furniture.
- The small-supplier test runs on taxable revenue over four consecutive calendar quarters, and crossing $30,000 makes registering mandatory, so we track that rolling total instead of discovering it long after the fact.
- HST is reported on tax charged in the period, which is not the same thing as the revenue you recognised in it, so we reconcile the return to billing and the income statement to the service period separately.
- One owner who had never registered was sitting on four years of advertising spend with recoverable tax inside it; $27,400 of input tax credits came back against the HST that should have been charged all along.
- ITA 12(1)(a) brings amounts received for services not yet rendered into income, and ITA 20(1)(m) gives the reserve for the part still undelivered, and claiming that reserve is the single largest planning item in this business.
- The salary and dividend split gets reset annually against a 53.53% top personal rate in Ontario, drawing enough salary to fund the household while surplus profit stays inside the corporation near 12.2%.
- Where a year ran unusually heavy on prepaid enrolments, the reserve shifts that income into the year the work is actually performed, which frequently carries a corporation back under the $500,000 small business limit.
- The $1.25M Lifetime Capital Gains Exemption is worth planning for years ahead of any sale, and a corporation whose deferred revenue and refund provision are stated properly is a far easier one to sell.
- Timing advertising spend, equipment purchases and the owner bonus around the year-end saved one operator $8,900 of corporate tax without changing a single thing about the way the business was actually run.
- We rebuild each missing year from payment-processor statements, bank records and your enrolment data, so every return is supported by evidence rather than by an estimate somebody made at the time and never revisited.
- Returns are filed in sequence so the deferred revenue closing one year opens the next one correctly, and that is precisely the step that goes wrong whenever unfiled years are prepared out of order.
- The rebuilt figures usually come as a relief, since the original ones had counted each prepaid programme fee as income the instant it landed and inflated taxable profit in every single year concerned.
- Once the returns are in, we apply for taxpayer relief on Form RC4288 where the penalties and interest followed from a bookkeeping error rather than from anything deliberate on the part of the owner.
- One business carrying five unfiled years finished $14,600 below the corporate tax the owner had budgeted for, simply because the deferral had never once been recognised in any of those earlier years.
- The first document a reviewer asks for on a file like this is the revenue schedule: what was billed, which service period it covers and how much of it was recognised inside the year under review.
- We answer HST queries by reconciling tax charged on enrolment and subscription billing back to the returns filed, and by producing the invoices behind the input tax credits claimed on advertising and software.
- Where agent classification is questioned, we assemble what CRA actually weighs: who sets hours and method, who provides premises and software, whether the worker can gain or lose financially, and how deeply embedded the role is.
- Correspondence comes to us rather than to you, and we keep it moving, because unanswered queries are how a narrow question about one year quietly turns into a review of the three before it.
- One review that opened on $62,000 of questioned input tax credits closed with the full amount allowed, once the advertising invoices and the taxable status of the fees were laid out on a single schedule.
- Compiled statements present deferred revenue as a liability and show only delivered programme months in income, which is the version of your business a lender, a landlord or a payment processor will accept.
- The refund provision appears on the face of the statements rather than buried in a note, because anyone assessing a subscription business wants to see what the guarantee could cost before assessing anything else.
- We tie the compilation back to the T2 and to your HST returns so that all three documents tell one story, which is what stops an analyst at the bank from asking for a fourth.
- Where an owner is preparing to sell, statements separating earned revenue from fees still owed in service make the diligence conversation shorter and the valuation argument considerably easier to hold.
- One operator was declined on a $150,000 credit facility on statements that badly overstated revenue; the recompiled version, properly deferred, was approved by the very same lender inside a month.
- We model the break-even before anything else, because a corporation shelters only the profit you leave behind; draw out everything the business earns and there is simply nothing there for it to defer.
- The corporate rate on the first $500,000 of active income sits near 12.2% in Ontario while the top personal rate reaches 53.53%, and the annual salary-versus-dividend decision becomes a choice rather than an accident.
- Where an existing unincorporated operation is being rolled in, we handle the section 85 rollover on Form T2057 so the transfer happens without triggering tax on the value accrued to that date.
- Incorporation is the right moment to build a chart of accounts that separates earned revenue from fees still owed in service, rather than retrofitting one two years later in the middle of a catch-up.
- Share structure is set with the $1.25M Lifetime Capital Gains Exemption in view, and one owner who incorporated at the point we identified kept roughly $16,000 a year that had been leaving as personal tax.
- We rebuild the deferred-revenue schedule from your enrolment records: every start date, every service period and every cancellation, so each historical month can be given the income that month genuinely earned.
- Processor deposits are matched back to individual client charges year by year, which is how discount fees, declines and partial refunds get separated out from the revenue that actually belonged to the business.
- Unclaimed input tax credits are picked up for every reporting period still open, and on a business spending heavily on advertising that recovery is usually the part which pays for the whole catch-up.
- Fees billed and never collected are written off under ITA 20(1)(p), or reduced by a doubtful-debt reserve under ITA 20(1)(l) where recovery is merely uncertain rather than genuinely hopeless.
- One office three years behind came out of the rebuild with $21,300 of recovered input tax credits and a revenue schedule its bank was finally willing to lend against for the first time.
- Where you enrol clients resident in the United States, we test whether the activity creates a permanent establishment under the treaty before any US filing obligation is assumed one way or the other.
- A US corporation or an LLC inside the structure brings its own federal and state filings, and an LLC needs particular care because Canada and the United States do not treat that vehicle the same way.
- Tax paid in the United States is claimed as a foreign tax credit against your Canadian T2 so that the same profit is not taxed twice, which means the two filings have to be prepared together.
- State-level registration is driven by where your agents work and where the clients sit, and it is the piece most often missed until a notice turns up from a state nobody had expected.
- One operator enrolling clients on both sides of the border cut roughly $9,400 a year from its combined bill once the foreign tax credit was claimed properly against the Canadian return.
- The Voluntary Disclosures Program is the route where programme income went unreported or HST was never charged, and it is only open while CRA has not yet contacted you about that particular issue.
- Eligibility turns on three tests: the disclosure must be voluntary, it must be complete, and it must concern information at least a year overdue, all of which we check before anything at all is lodged.
- The application goes in on Form RC199 with corrected figures behind it, which in this sector almost always means a rebuilt revenue schedule and a restated HST position for every period involved.
- Where the problem is late filing rather than unreported income, Form RC4288 is the right request instead, and choosing correctly between those two routes is most of the work in the first place.
- One business that had charged no HST across three years came forward and had penalties waived, paying roughly $31,000 of tax that input tax credits on advertising had already cut down from far more.
Credit Repair Business HST & Deferred Revenue Check
Six quick questions on your taxable fees, input tax credits, prepaid programme revenue, your refund provision, agent payroll and whether it is time to incorporate. No fee shown.
1. Are you charging 13% HST on your enrolment, programme and subscription fees?
2. Is the HST on advertising, software and rent all coming back to you?
3. Are prepaid programme fees held as deferred revenue rather than booked on receipt?
4. Do you carry a provision for refunds offered under a money-back guarantee?
5. Are your sales agents classified on the facts rather than on the agreement wording?
6. Is your credit repair business incorporated yet?
Free CPA Consultation for Credit Repair Businesses
Case Studies: Credit Repair Business Accounting & Tax
Oakville Credit Repair Business — A Year of Programme Fees Booked on Receipt
The problem: An Oakville operator selling fixed six-month programmes was recording each fee as income on the day the card cleared. Because most of that money covered months of work still to come, the corporation reported a business several times its real size and paid tax on income it had not yet earned. Two filed years were affected, and the balance sheet carried nothing at all for the months still owed.
What we did: We rebuilt the revenue schedule from start dates held in the enrolment system, moved undelivered programme months into deferred revenue, claimed the ITA 20(1)(m) reserve against each year-end balance, and amended both open T2 returns.
The result:
- $24,800 of overpaid corporate tax recovered
- Programme fees now recognised month by month
- Deferred revenue carried on the balance sheet
Markham Credit Repair Business — HST Never Charged on Taxable Fees
The problem: A Markham operator had never charged HST on an enrolment or subscription invoice. Somebody had told the owner that finance-sector businesses make exempt supplies, and the assumption was applied straight across the board. These fees are taxable, so the business owed tax it had never collected, and it had claimed nothing at all against the advertising spend that dominated its cost base year after year.
What we did: We reset the position, worked out the tax that ought to have been charged in each open period, offset the input tax credits available against it, and lodged a disclosure on Form RC199 ahead of any contact from CRA.
The result:
- $33,900 of input tax credits recovered
- Penalties waived under the Voluntary Disclosures Program
- 13% HST now charged on fees and remitted
Guelph Credit Repair Business — Building the Schedule From the Enrolment System
The problem: A Guelph office running monthly subscriptions alongside fixed-term programmes had no way of saying how much of its bank balance was money already earned. Cancellations were handled case by case, refunds landed in whichever month they were paid, and the owner could not tell a strong month from a weak one on any report the business produced.
What we did: We exported start dates, service periods and cancellations, built a schedule that releases each fee across the months it covers, sized a refund provision on two years of the office own cancellation history, and set a monthly close that updates both before statements are issued.
The result:
- Revenue schedule updated at every monthly close
- Refund provision sized on real cancellation history
- Monthly profit finally comparable month to month
Our clear, efficient process ensures every step is transparent, building trust and long-term client relationships.
Kickoff (Document Request)
Prior T2 returns, bank and payment-processor statements, your client agreement and fee schedule, enrolment and cancellation exports, payroll and T4 records, and your advertising invoices.
First 30 Days (Cleanup & Setup)
QuickBooks Online or Xero configured, the deferred-revenue schedule built, your taxable HST position confirmed and registration filed where required, then subscription, cancellation and refund tracking switched on.
Monthly Close
Release the programme months earned, update the refund provision, reconcile processor deposits, run payroll and PD7A remittances, and file HST returns with credits claimed in full.
Quarterly Planning Review
Salary and dividend split, the reserve for months not yet delivered, an agent classification check, an input-tax-credit sweep and the incorporation break-even.
Year-End Close & T2 Filing
Trial balance, year-end statements carrying deferred revenue and the refund provision, a T2 with GIFI, payroll slips, and working papers ready for CRA.
Get Your Credit Repair Business Taxes Done Right Today
Affordable Pricing for Credit Repair Businesses
We believe in clear, upfront pricing so you know exactly what to expect. All fees include HST.
- Tax Preparation (Corporation) — From $400
- Tax Return Filing (Corporation) — From $400
- Tax Compliance Audit — FREE CRA audit support for our clients
- Tax Strategy — FREE for our clients
- Accounting Base Plan — From $100 per month
- Bookkeeping Management — Free for our Accounting clients
- Financial Reporting — Free for our Accounting clients
- Business Formation — Flat $35
- Incorporation Process — Flat $35
- Entity Setup Assistance — Flat $35
- Full-Service Payroll — From $125 per month
Payment is by Interac e-Transfer to info@gondaliyacpa.ca only. Security question: Not Applicable, as auto-deposit is enabled.
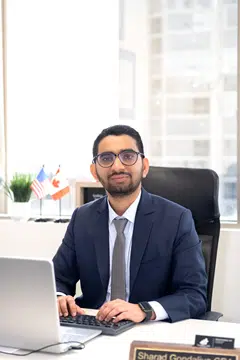
Meet Your Lead Credit Repair Business Accountant
Meet the CPA who signs off on your file. The same two people build your revenue schedule, file your HST and prepare your corporate return every year, so there is never any question who to call.
What Our Clients Say
1300+ five-star reviews from programme operators and small-business owners right across Ontario and Canada.
Serving Credit Repair Businesses Across Ontario
Operators across Ontario come to our CPA team because a business paid months ahead of the work needs books that say so. We know how an enrolment fee, a fixed-term programme, a monthly subscription, a cancellation and a refund each land in the ledgers, why your fees carry HST when much of the sector around you charges none, and where the margin really sits once advertising and agent pay have been settled.
Toronto (ON)
55 Queen St E Ste 1205, Toronto, ON M5C 1R6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Mississauga (ON)
5373 Bullrush Dr, Mississauga, ON, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Brampton (ON)
4 Starhill Crescent, Brampton, ON L6R 2P9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Scarborough (ON)
24 Clementine Square, Scarborough, ON M1G 2V7, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Vaughan (ON)
19 Cabinet Crescent, Woodbridge, ON L4L 6H9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Oshawa (ON)
210 Durham St, Oshawa, ON L1J 5R3, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Ottawa (ON)
2090 Neepawa Ave a314, Ottawa, ON K2A 3L6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Etobicoke (ON)
60 Stevenson Rd #1601, Etobicoke, ON M9V 2B4, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Hamilton (ON)
70 Starling Dr, Hamilton, ON L9A 0C5, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Guelph (ON)
1155 Gordon St, Guelph, ON N1L 1S8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Windsor (ON)
4387 Guppy Ct, Windsor, ON N9G 2N8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
North York (ON)
150 Graydon Hall Dr #912, North York, ON M3A 3B2, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Credit Repair Business Accounting & Tax FAQs
Related Industries We Serve
Accountant for Debt Collection Agencies
- Recovery fee and commission income
- T2 filing and year-end statements
- Payroll and monthly bookkeeping
Accountant for Private Lenders
- Interest income and lending structures
- Corporate tax planning and T5 reporting
- Bookkeeping and financial statements
Accounting for Small Businesses
- Corporate tax planning for small businesses
- Business tax filing and financial statements
- Payroll and bookkeeping services
Accountant for Incorporated Businesses
- T2 corporate returns and GIFI
- Salary, dividend and SBD planning
- Compilation statements and incorporation
Credit Repair Business Accounting & Tax Done Right.
T2 filing, taxable fees at 13% HST with input tax credits claimed in full, deferred revenue on prepaid programmes released as the work is performed, a provision where a money-back guarantee is offered, agent payroll with WSIB and T4 slips, and the $1.25M capital gains exemption under one roof. AFFORDABLE flat fees, no hourly billing. Licensed CPA Ontario. 1300+ five-star reviews. 30-Day Money-Back Guarantee.