



Tax Accountant for Private Lenders in Ontario and Across Canada
A private lending business runs on interest income that is HST-exempt, because lending money is a financial service under ETA section 123(1), so you charge no HST on interest and, as an exempt supplier, generally cannot recover the HST on your inputs. We keep that exempt-supply position clean, determine and document the character of every lender, renewal and discharge fee, and test the $30,000 small-supplier threshold against your taxable fee income only. We measure your corporation against the specified investment business rule in ITA 125(7), which denies the deduction below six full-time employees and pushes interest into aggregate investment income with refundable tax instead of the roughly 12.2% Ontario small-business rate on the first $500,000. We accrue interest as it is earned, reserve for arrears under ITA 20(1)(l), issue T5 slips to your investors, and keep loan principal off the income statement where it belongs. Flat-fee, no hourly billing, CPA Ontario, 1300+ five-star.
AFFORDABLE Private Lender Tax Accountant
A private lending business earns most of its revenue from interest, and interest on lending money is HST-exempt, because lending money is a financial service under ETA section 123(1). Exempt status means you do not charge HST on that interest and you generally cannot recover the HST you pay on your inputs as input tax credits, so charging HST in error and over-claiming credits are the two most costly and audit-attracting mistakes a lender makes. Then the tax side arrives: the specified investment business rule in ITA 125(7) denies the small business deduction below six full-time employees, so a corporation whose principal purpose is earning income from property loses the roughly 12.2% Ontario rate the owner assumed and reports aggregate investment income with refundable tax instead. At Gondaliya CPA, we specialize in exempt-versus-taxable revenue splitting, loan-ledger bookkeeping, T5 reporting and corporate tax planning for lenders, providing AFFORDABLE flat-fee support that keeps you CRA-compliant and stops you paying more tax than you owe.
As a private lender accountant, we work with individual and incorporated private lenders, family lending corporations, syndicated loan groups, bridge and construction financiers and hard-money lenders across Ontario, with year-round support rather than a once-a-year scramble. We tell you plainly what you can deduct, what you cannot, and where the real yield sits once arrears, reserves and realisation costs are settled.
Let us handle the numbers so you can focus on the loans that actually perform.
Our Official Partners
Accounting That Understands How a Private Lending Business Actually Works
Running a lending book comes with financial realities a standard retail or service company never faces. Your interest is HST-exempt, so you cannot recover the tax on your inputs; the money you advance and the money you hold for investors never belong on the income statement; interest accrues whether or not a borrower pays; and the specified investment business rule can take away the small business deduction you assumed you had.
Stay Compliant and Minimize Your Private Lending Tax
For a private lender, staying onside with CRA and paying the least legal tax are the same job. We keep every filing on schedule while classifying your interest, your fees, your investor funds and your reserves the way the rules actually require, so nothing is missed and nothing invites a reassessment.
Accounting & Tax Experts for Private Lenders
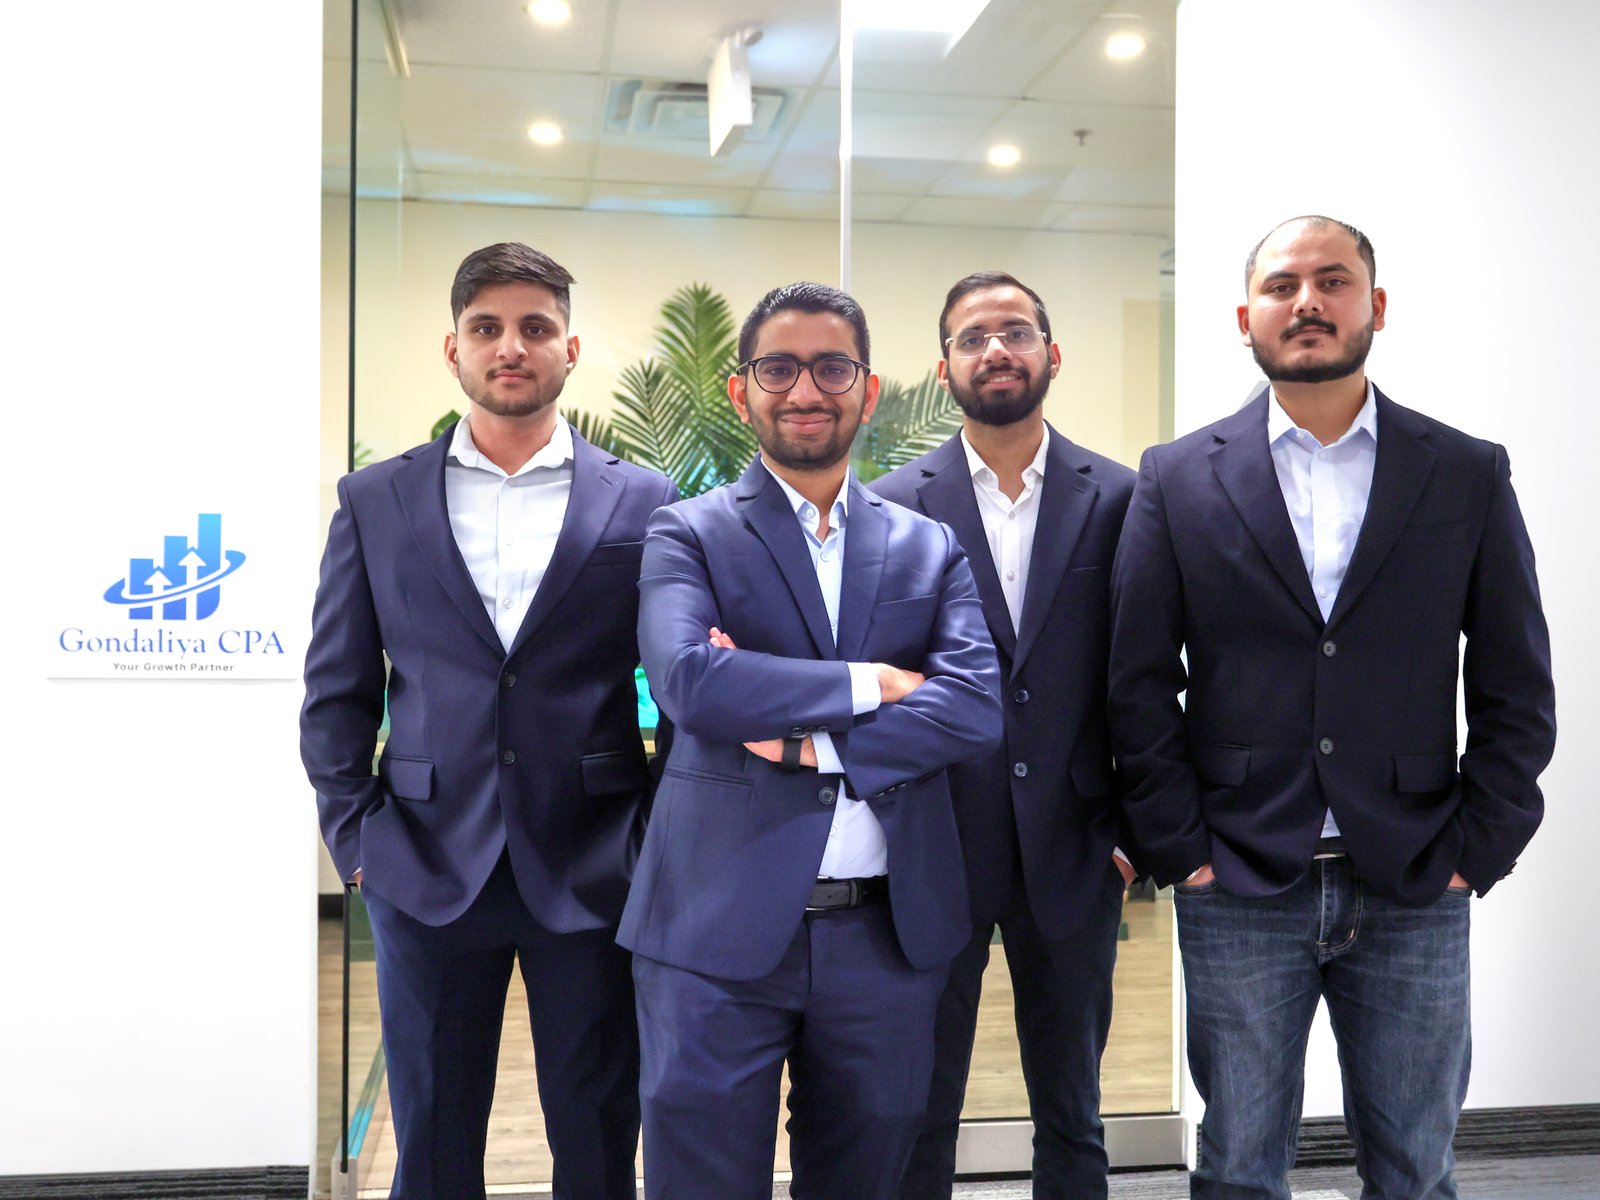
- AFFORDABLE + Fully Registered CPA Firm
- Business and Corporate Tax Expert
- Small & Medium Business Expert
- Accounting, bookkeeping, and tax filing
- Certified CPA
- 1300+ 5-star Google reviews
- 30-Day Money-Back Guarantee
- 60-Day Fees Matching Policy
Why Choose Our Accounting Services for Private Lenders?
Tax Planning — Interest Income & the 125(7) Test
We test your corporation against the specified investment business rule in ITA 125(7) before you file, set the salary-and-dividend mix, plan the section 85 rollover on incorporation, and protect the $1.25M Lifetime Capital Gains Exemption where your structure can qualify for it.
Consulting — Exempt Revenue & Loan Ledger
Our bookkeeping keeps principal on the balance sheet, books investor money as a liability, accrues interest as it is earned, splits taxable fee income from exempt interest, restricts your input tax credits correctly, and tracks arrears loan by loan.
CRA Representation — HST & Investment Income
When CRA questions your restricted input tax credits, your doubtful-debt reserve or your small business deduction claim, we prepare the response, produce the loan and employee records, and pursue relief on Form RC4288 where penalties came from a prior error.
Bookkeeping — Investor Reporting & Growth
We issue T5 slips and the T5 Summary for interest paid to investors, handle the NR4 obligation where an investor is a non-resident, run payroll, and model the profit level at which incorporating your lending actually pays off.
Google Reviews
Private Lending Clients
Private Lending Tax and Accounting Services in Ontario
Corporate Tax Filing (T2) for Private Lenders
Professional T2 preparation with Schedule 125 interest revenue, Schedule 8 capital cost allowance, Schedule 7 investment income, and CRA compliance on every line.
Bookkeeping & Accounting for Private Lenders
Loan-ledger and accrued-interest bookkeeping with financial statements, clean records, and monthly reporting built for a lending book.
Payroll Services for Private Lenders
T4 and T4A payroll with PD7A remittances, records of employment, ESA vacation pay, and employee records that support your 125(7) position.
GST/HST Filing for Private Lenders
AFFORDABLE handling of HST-exempt interest under ETA section 123(1), with input-tax-credit restriction and any taxable fee income split out.
Tax Planning for Private Lenders
Smart tax planning around the specified investment business rule, the salary and dividend mix, the section 85 rollover, and the business limit.
Corporate Catch-Up Filing for Private Lenders
File overdue T2, T5 and payroll years, rebuild missing loan and interest records, and get back into CRA compliance with accurate catch-up support.
CRA Audit Resolution for Private Lenders
Expert support for exempt-supply HST, restricted-ITC, doubtful-debt reserve and specified investment business audits, with RC4288 relief handled with confidence.
CPA Financial Statements (Notice to Reader) for Private Lenders
CPA-compiled financial statements that banks and investors accept, presenting loans receivable, investor liabilities and interest revenue clearly.
Incorporation Services for Private Lenders
Full incorporation including NUANS, articles, share structure, and the section 85 rollover of loans you already hold personally.
Catch-Up Bookkeeping Services for Private Lenders
Reconstruct months or years of loan, interest and arrears records, rebuild clean books, and restore monthly reporting for your lending business.
US Corporation & LLC Tax Filing for Private Lenders
Cross-border filing for lenders with US borrowers or US-situated security, covering Forms 1120, 1120-F and 5472 alongside your Canadian returns.
Voluntary Disclosure Program for Private Lenders
Come forward on unreported interest income and missing T5 slips through the CRA Voluntary Disclosures Program, filing Form RC199 to reduce penalties before an audit.
Accounting & Tax Services Tailored for Private Lenders
Real, practitioner-level CPA expertise for individual and incorporated private lenders, family lending corporations, syndicated loan groups, bridge and construction financiers and hard-money lenders across Ontario — built for how a lending book actually runs.
- We prepare your T2 with GIFI, reporting interest revenue and lender fee income on the correct Schedule 125 lines and your loans receivable on Schedule 100, so the CRA matching program never flags your lending corporation for a needless desk audit.
- We complete Schedule 7 so aggregate investment income is separated from anything genuinely active, because a lending corporation that reports every dollar as active business income is the easiest reassessment a CRA auditor writes in this sector.
- We claim capital cost allowance on Schedule 8 with office equipment in CCA Class 8 at 20% and your site-inspection vehicle in Class 10 at 30%, and one lender recovered $4,800 of depreciation the prior preparer had never claimed.
- We keep loan principal off the income statement entirely, because advancing money to a borrower is a balance-sheet movement and its repayment is not an expense, an error that has badly inflated reported revenue on returns we were later asked to fix.
- We file the T2 within six months of your fiscal year-end and pay the balance by the two- or three-month due date, so a lending corporation earning $250,000 of interest never carries the arrears interest CRA charges on a late balance.
- We build your chart of accounts in QuickBooks Online or Xero so every loan carries its own principal, accrued interest, fee and arrears balance, giving you a ledger that actually ties to your loan schedule at the end of each month.
- We record interest as it is earned rather than when it is collected, so a loan that has stopped paying still reports the income it produced, and your statements stop swinging with cash timing instead of with real performance.
- We book money advanced or held for an investor or a borrower as a liability, never revenue, and we corrected $46,000 of investor funds that a prior bookkeeper had run through the income statement as though it were sales income.
- We reconcile every discharge, renewal and administration fee back to the loan it came from and record the character decision made on each one, so the file supports the treatment if CRA ever asks you to explain it.
- We produce a monthly loan-by-loan report showing principal outstanding, interest earned, interest actually received and days in arrears, which is the single report that tells you whether your reported yield is real.
- We run pay through Wagepoint, issue T4 slips for employed staff and T4A slips for genuine contractors, and remit source deductions on the PD7A by the deadline, so a missed monthly remittance never triggers the 10% CRA penalty.
- Because the specified investment business rule turns on full-time employees, we document who is actually employed, the hours they work and the duties they perform, so the head count behind your claim is evidenced rather than merely asserted.
- We assess worker status on the factors CRA actually applies, control over the work, ownership of tools, chance of profit and risk of loss, and integration into your business, before anybody is paid as an independent contractor.
- We calculate vacation pay under the Employment Standards Act, issue records of employment on separation, and keep your payroll account current, and one lender avoided $3,200 of penalties and interest on remittances filed late across two quarters.
- We set a reasonable owner-manager salary so you build RRSP room and CPP entitlement, then model how much of your interest profit is better taken as dividends once the real corporate rate on that income is known.
- We confirm that lending money and the interest it earns are an exempt financial service under ETA section 123(1), so you do not charge HST on interest, and we stop the costly error of adding 13% that takes years to unwind.
- As an exempt supplier you generally cannot recover the HST on your inputs, so we restrict input tax credits on legal, appraisal and loan servicing costs rather than leaving an over-claim on the return for CRA to reverse with interest.
- We test the $30,000 small-supplier threshold against your taxable fee income only, because exempt interest is excluded from the calculation, so a lender whose interest revenue runs into the millions is not forced to register on income that never counts.
- We determine and document the character of each lender, renewal, discharge and administration fee separately, because the treatment follows what the fee is actually for, and a blanket assumption either way is what turns a review into an assessment.
- Where you genuinely do make taxable supplies, such as consulting or loan administration work billed to another party, we register, charge and file on that stream alone and keep the exempt interest side out of the calculation.
- We test your corporation against the specified investment business rule in ITA 125(7), which denies the deduction below six full-time employees, before you file rather than after CRA reassesses the small business deduction you assumed you had.
- Where the rule applies, your interest falls into aggregate investment income with refundable tax attached rather than the roughly 12.2% Ontario small-business rate, and we model the real combined cost so distributions are timed against it.
- We set the salary-versus-dividend mix for owners, paying enough T4 salary to build RRSP room while the balance flows as dividends, so nothing is left sitting at the personal rate that reaches 53.53% in Ontario.
- We complete the section 85 rollover on Form T2057 when you incorporate an existing loan book, moving the receivables across at elected amounts, and one lender deferred $31,000 of tax that a straight transfer would have triggered.
- We plan around the associated-corporation rules before the $500,000 business limit is shared or ground down, because lenders often hold several corporations and discover the shared limit only when the assessment finally arrives.
- We reconstruct interest revenue, lender fees and principal movements from loan agreements, lawyer statements and bank deposits where no bookkeeping exists across your unfiled years, so CRA cannot assess your corporation on its own estimate.
- Late filing costs 5% of the balance owing plus 1% per month for up to twelve months, so we file your oldest unfiled T2 first to stop the penalty compounding, once saving a client $9,100 in penalties and arrears interest.
- We rebuild the accrued interest position year by year, because a lending corporation that reported only the cash it collected has understated some years and overstated others, and both errors have to be corrected in the right period.
- We prepare and file the T5 slips and T5 Summaries that were never issued for the interest you paid investors in those years, bringing the information returns current alongside the corporate returns themselves.
- We apply for relief from penalties and arrears interest on Form RC4288 where the delay was caused by illness, a prior adviser or circumstances genuinely beyond your control, and we document the grounds properly before submitting.
- When CRA questions why you claimed input tax credits, we show that lending money is an exempt financial service under ETA section 123(1) and that your credits were correctly restricted, defending the position before a reassessment with interest lands.
- When an auditor applies the specified investment business rule to deny your small business deduction, we produce the employee records, job descriptions and hours that support the claim, or we quantify the exposure honestly before it grows.
- Where a doubtful-debt reserve under ITA 20(1)(l) is challenged, we produce the arrears history, the security position and the valuation work behind the number, and one lender cleared a $27,000 proposed adjustment on that evidence.
- When CRA asks why the interest you reported does not match the T5 slips on file, we reconcile the slips back to the loan ledger and correct whichever side is wrong, which is usually the slips rather than the return.
- We pursue relief on Form RC4288 where penalties arose from a prior preparer’s error rather than from anything you did, and we handle the correspondence so you are never negotiating with a CRA auditor on your own.
- We prepare CSRS 4200 compilation engagement financial statements, the Notice to Reader a bank or an incoming investor expects across two fiscal years before it extends a credit facility or commits fresh capital to your lending corporation.
- Your compiled statement of financial position presents loans receivable separately from operating cash and shows money held for investors as a liability, giving a reader the true picture that a bare T2 filing never does.
- We present interest revenue and fee income as distinct lines rather than one blended figure, because anyone assessing your yield needs to see how much of it repeats every month and how much was charged only once.
- Where loans are impaired, the statements disclose the doubtful-debt reserve and the basis for it, so nobody lending to you discovers an arrears problem afterwards and then questions every other number in the file.
- We deliver the statements with the working papers behind them, which is what shortens the engagement next year and what a CRA auditor asks for first when your file is selected for a closer review.
- We incorporate under the Ontario Business Corporations Act, giving you limited liability and a clean separation between your lending capital and your personal assets, with a share structure that can admit later investors without being rebuilt.
- We are honest about the tax result first, because a lending corporation caught by ITA 125(7) does not get the roughly 12.2% small-business rate, and incorporating for that rate alone is the wrong reason to do it at all.
- We complete the section 85 rollover on Form T2057 where you already hold loans personally, transferring the receivables at elected amounts so that incorporating does not itself trigger tax on gains accrued to that date.
- We register the corporation for a business number and open the payroll and information-return accounts you will actually need, so your first T5 filing season is not spent opening accounts under deadline pressure.
- We model the point at which incorporating pays for itself against the annual T2, bookkeeping and filing cost, and we tell you plainly when the answer is not yet rather than selling you a structure you do not need.
- We rebuild months or years of missing books from your loan agreements, discharge statements and bank records, posting interest to the period in which it was actually earned rather than the period the borrower finally paid it.
- We separate your exempt interest income from any taxable side work, such as consulting or loan administration billed to another party, so the catch-up books report each stream the way the corporate and HST returns will need it.
- We reconstruct the principal ledger loan by loan so advances and repayments sit on the balance sheet where they belong, and one lender’s reported revenue fell by $180,000 once principal repayments were removed from income.
- We rebuild the arrears history so that any doubtful-debt reserve you are entitled to is supported by evidence from the period in which it arose, rather than claimed later against a loan nobody ever documented.
- We hand back reconciled monthly statements and a loan schedule that ties to them, so your corporate returns can be filed on real numbers instead of an estimate that nobody would be able to defend.
- When your lending corporation earns interest from a US borrower or holds security over American real property, we determine whether a US filing obligation exists and prepare Form 1120-F where the facts show that it does.
- If you hold a US C-corporation or a single-member LLC to carry American loans, we prepare Form 1120 and the Form 5472 information return that reports transactions between it and its foreign related party.
- We coordinate the US and Canadian returns so the same interest is not taxed twice, claiming foreign tax credits on the Canadian side against tax actually paid rather than tax withheld and later refunded to you.
- We flag the Canadian reporting that follows foreign holdings, including Form T1134 for a foreign affiliate and Form T1135 where specified foreign property costs more than $100,000, because those penalties are assessed for every year.
- We work alongside a US preparer where a state filing is involved rather than guessing at a state position, and we keep the Canadian file consistent with whatever is actually filed south of the border.
- We prepare and file Form RC199 to bring unreported interest income forward under the CRA Voluntary Disclosures Program, restoring years of missing lending revenue before an audit letter or a slip-matching notice arrives.
- We confirm that your disclosure is voluntary, complete and at least one year overdue before submitting it, because an application that does not meet those conditions can be denied and leaves you worse off than before.
- We use the program for T5 slips that were never issued as well as for unreported income, because information return failures are their own exposure and are usually what brings the rest of the file to light.
- We rebuild the underlying books first so that the disclosure is genuinely complete, since a partial disclosure that quietly omits a year or a single loan is the most common reason an application ends up failing.
- Where relief is better pursued as a taxpayer relief request on Form RC4288 than as a disclosure, we say so, because the two routes suit different facts and using the wrong one wastes the only chance you get.
Private Lender Tax & Interest Income Check
Six quick questions on your exempt interest, input tax credits, the specified investment business rule, accrued interest, T5 reporting and whether it is time to incorporate. No fee shown.
1. Are you correctly NOT charging HST on your interest income?
2. Are your input tax credits restricted correctly on the exempt lending side?
3. Has your corporation been tested against the specified investment business rule?
4. Is interest that accrued but was never paid still recorded as income?
5. Are T5 slips issued for all the interest you pay your investors?
6. Is your private lending business incorporated yet?
Free CPA Consultation for Private Lenders
Case Studies: Private Lending Accounting & Tax
Toronto Lending Corporation — The 125(7) Small Business Deduction
The problem: A Toronto corporation lending its own capital had claimed the small business deduction on interest income for three filed years. It had one part-time bookkeeper and no other staff, so its principal purpose was earning income from property and the specified investment business rule in ITA 125(7), which denies the deduction below six full-time employees, applied to every one of those years.
What we did: We quantified the exposure, recharacterised the interest as aggregate investment income, corrected the prior returns before CRA opened a review, and rebuilt the owner remuneration plan around the higher corporate rate and the refundable tax that comes with it.
The result:
- Corrected before reassessment, avoiding gross-negligence exposure
- $38,000 of tax and interest quantified and planned for
- Remuneration rebuilt around the real corporate rate
Vaughan Private Lender — Over-Claimed Input Tax Credits
The problem: A Vaughan private lender had been claiming input tax credits on legal, appraisal and loan servicing costs as though its revenue were taxable. Because lending money is an exempt financial service under ETA section 123(1), the interest it earns is exempt, so no HST is charged on it and the credits behind it generally cannot be recovered. The over-claim had been building quietly across every reporting period.
What we did: We restricted the credits to the genuinely taxable administration fees it also billed, documented the character of each fee, refiled the affected HST returns to reverse the credits taken in error, and set up the bookkeeping so the two streams stay separated.
The result:
- $21,400 of credits reversed before CRA assessed them
- Fee character determined and documented loan by loan
- Exempt-supply position clean going forward
Hamilton Lending Group — T5 Slips Never Issued
The problem: A Hamilton lending group had paid interest to a dozen individual investors for four years without ever issuing a T5 slip or filing a T5 Summary. Investors were reporting whatever figure they remembered, the amounts did not agree with the corporate ledger, and two investors were non-residents, which carries a separate withholding and NR4 reporting obligation nobody had addressed.
What we did: We reconciled four years of interest to each investor, prepared and filed the missing T5 slips and Summaries, addressed the non-resident reporting obligation, and built an annual slip calendar so every February deadline is met without a scramble.
The result:
- Four years of T5 slips and Summaries brought current
- Non-resident reporting obligation identified and addressed
- Investor statements now agree with the corporate ledger
Our clear, efficient process ensures every step is transparent, building trust and long-term client relationships.
Kickoff (Document Request)
Collect prior T2 returns, loan agreements and amortisation schedules, lawyer and discharge statements, investor lists and prior T5 slips, payroll records, and bank statements.
First 30 Days (Cleanup & Setup)
Set up QuickBooks Online or Xero, move principal off the income statement, confirm your exempt-supply HST position, and configure accrued interest, fee and arrears tracking.
Monthly Close
Monthly reconciliations, loan-ledger matching, interest accruals, arrears review, payroll and PD7A remittances, and exempt-versus-taxable revenue tracking.
Quarterly Planning Review
Salary and dividend mix, the specified investment business test, doubtful-debt reserve review, input-tax-credit review, and incorporation break-even.
Year-End Close & T2 Filing
Trial balance, financial statements separating loans receivable from investor liabilities, T2 with GIFI and Schedule 7, T5 slips and Summary, and CRA preparation.
Get Your Private Lending Taxes Done Right Today
Affordable Pricing for Private Lenders
We believe in clear, upfront pricing so you know exactly what to expect. All fees include HST.
- Tax Preparation (Corporation) — From $400
- Tax Return Filing (Corporation) — From $400
- Tax Compliance Audit — FREE CRA audit support for our clients
- Tax Strategy — FREE for our clients
- Accounting Base Plan — From $100 per month
- Bookkeeping Management — Free for our Accounting clients
- Financial Reporting — Free for our Accounting clients
- Business Formation — Flat $35
- Incorporation Process — Flat $35
- Entity Setup Assistance — Flat $35
- Full-Service Payroll — From $125 per month
Payment is by Interac e-Transfer to info@gondaliyacpa.ca only. Security question: Not Applicable, as auto-deposit is enabled.
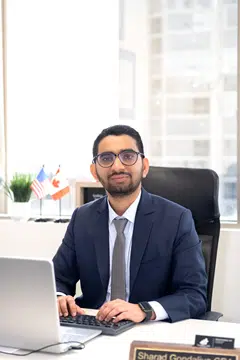
Meet Your Lead Private Lender Accountant
Meet your lead private lender accountant. As your interest income and corporate tax adviser, you deal with the same two people every year.
What Our Clients Say
1300+ five-star reviews from private lending and small-business owners across Ontario and Canada.
Serving Private Lenders Across Ontario
Our CPA team provides specialized accounting and tax solutions for private lenders throughout Ontario. We understand how exempt interest, restricted input tax credits, accrued but unpaid interest, arrears reserves and investor T5 reporting actually flow through a lending book, what CRA looks at on an exempt-supply file, and where the real yield sits once realisation costs are settled.
Toronto (ON)
55 Queen St E Ste 1205, Toronto, ON M5C 1R6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Mississauga (ON)
5373 Bullrush Dr, Mississauga, ON, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Brampton (ON)
4 Starhill Crescent, Brampton, ON L6R 2P9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Scarborough (ON)
24 Clementine Square, Scarborough, ON M1G 2V7, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Vaughan (ON)
19 Cabinet Crescent, Woodbridge, ON L4L 6H9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Oshawa (ON)
210 Durham St, Oshawa, ON L1J 5R3, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Ottawa (ON)
2090 Neepawa Ave a314, Ottawa, ON K2A 3L6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Etobicoke (ON)
60 Stevenson Rd #1601, Etobicoke, ON M9V 2B4, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Hamilton (ON)
70 Starling Dr, Hamilton, ON L9A 0C5, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Guelph (ON)
1155 Gordon St, Guelph, ON N1L 1S8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Windsor (ON)
4387 Guppy Ct, Windsor, ON N9G 2N8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
North York (ON)
150 Graydon Hall Dr #912, North York, ON M3A 3B2, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Private Lending Accounting & Tax FAQs
Related Industries We Serve
Accountant for Investment Companies
- Passive investment income and refundable tax
- Mortgage investment corporation structuring
- Portfolio accounting and adjusted cost base
Accountant for Mortgage Brokers
- Commission income and incorporation
- Salary, dividend and SBD planning
- Bookkeeping and personal tax
Accountant for Insurance Brokers
- Exempt financial services and HST
- Corporate tax planning and financial statements
- Bookkeeping and payroll
Accounting for Small Businesses
- Corporate tax planning for small businesses
- Business tax filing and financial statements
- Payroll and bookkeeping services
Private Lending Accounting & Tax Done Right.
T2 filing, HST-exempt interest under ETA section 123(1), input-tax-credit restriction, the specified investment business test in ITA 125(7), accrued interest and doubtful-debt reserves, T5 slips and investor reporting, catch-up filing and incorporation advice under one roof. AFFORDABLE flat fees, no hourly billing. Licensed CPA Ontario. 1300+ five-star reviews. 30-Day Money-Back Guarantee.