



Tax Accountant for Equipment Finance Companies in Ontario and Across Canada
Most finance businesses live on the exempt side of the HST rules. A lessor does not. When you lease equipment you are supplying tangible personal property, so your lease payments are taxable: you charge 13% HST on them and you recover the HST on the machines you bought to put on lease. When you lend against equipment instead, the interest is an exempt financial service under ETA section 123(1), with no tax charged and credits restricted. Write both and you are a mixed supplier running two opposite tax profiles out of one ledger, and the input tax credits have to be apportioned on a fair and reasonable basis. We split the book, set the HST right, and run the asset side properly: every unit in its capital cost allowance class, the half-year rule applied, recapture and terminal losses planned on disposal, and residual assumptions tracked against what units actually fetch. Flat-fee, no hourly billing, CPA Ontario, 1300+ five-star.
AFFORDABLE Equipment Finance Tax Accountant
An equipment finance company is taxed unlike almost anything else in the finance sector, and the reason is simple. Leasing equipment is a supply of tangible personal property, which is taxable, so you charge 13% HST on lease payments in Ontario and, as a taxable supplier, you claim input tax credits on the equipment and the inputs used to make those supplies. Lending against equipment is the mirror image: interest on the loan is an exempt financial service under ETA section 123(1), no tax is charged, and credits on the inputs used to earn it are restricted. Most lessors write both, often for the same customer in the same week, which makes them mixed suppliers whose input tax credits must be apportioned on a fair and reasonable basis, with the method documented and applied consistently. Getting that split wrong in either direction, tax never charged on a taxable lease, or credits never claimed because the owner assumed the whole book was exempt, is the most expensive mistake in this industry.
Then there is the asset side, which a pure lender never touches. Equipment on lease is depreciable property, never inventory. It sits in a capital cost allowance class, Class 8 at 20% or Class 10 at 30% for qualifying vehicles, with the half-year rule in the year of acquisition. When a unit comes off lease and is sold, the difference between the proceeds and the undepreciated capital cost lands as recapture under ITA 13(1) or as a terminal loss. Lease profit is made or lost on residual realisation, and that number is nowhere in the lease document. At Gondaliya CPA we work with equipment lessors, vendor finance programs, specialty and municipal lessors and asset-based finance companies across Ontario, on flat fees, all year.
Let us run the tax and the asset ledger so you can price deals and fund them.
Our Official Partners









Accounting That Understands How an Equipment Finance Company Actually Works
An equipment finance company carries a tax profile no ordinary service business has. Your lease revenue is taxable and carries HST; your loan interest is an exempt financial service; you are usually making both kinds of supply out of one ledger. Your largest asset is a fleet of depreciable property spread across capital cost allowance classes, and every contract ends in a disposal that produces recapture or a terminal loss. At Gondaliya CPA we understand how a lessor actually earns money and provide practical, asset-aware solutions across the GTA and all of Ontario.
Stay Compliant and Minimize Your Equipment Finance Tax
For a lessor, staying onside with CRA and paying the least legal tax are the same job. We keep every filing on schedule while classifying your lease revenue, your interest income and your fleet the way the rules actually require, so nothing is missed and nothing invites a reassessment.
Accounting & Tax Experts for Equipment Finance Companies
- AFFORDABLE + Fully Registered CPA Firm
- Business and Corporate Tax Expert
- Small & Medium Business Expert
- Accounting, bookkeeping, and tax filing
- Certified CPA
- 1300+ 5-star Google reviews
- 30-Day Money-Back Guarantee
- 60-Day Fees Matching Policy
Why Choose Our Accounting Services for Equipment Finance Companies?
Tax Planning — Residual, Recapture & Rate
We keep active income under the $500,000 Small Business Deduction at roughly 12.2% in Ontario, time disposals so recapture under ITA 13(1) is absorbed by additions to the same class, and plan the eventual share sale around the $1.25M Lifetime Capital Gains Exemption.
Consulting — Lease Book vs Loan Book
Our bookkeeping keeps taxable lease revenue and exempt interest income on separate lines, maintains a unit-level equipment sub-ledger with cost, class and residual, apportions input tax credits on a documented basis, and accretes finance income across the term.
CRA Representation — HST & CCA Audit
When CRA questions your HST on lease billings, your input tax credit apportionment, who is entitled to claim capital cost allowance, or a recapture figure on disposal, we prepare the response, rebuild the class from the original additions, and pursue relief on Form RC4288 where a prior error caused the penalties.
Bookkeeping — Payroll & Portfolio Growth
We run T4 payroll for credit, documentation and remarketing staff with PD7A remittances and records of employment, register you with WSIB from the first hire, and model the profit level at which incorporating pays for itself.
Google Reviews
Equipment Finance Clients
Equipment Finance Tax and Accounting Services in Ontario
Corporate Tax Filing (T2) for Equipment Finance Companies
T2 preparation with GIFI, lease and interest revenue on the right Schedule 125 lines, and Schedule 8 capital cost allowance on every unit you own.
Bookkeeping & Accounting for Equipment Finance Companies
Lease-book and loan-book bookkeeping with a unit-level equipment sub-ledger, monthly reporting and statements built for a lessor.
Payroll Services for Equipment Finance Companies
T4 payroll for credit, documentation and remarketing staff, with PD7A remittances, records of employment and vacation pay handled correctly.
GST/HST Filing for Equipment Finance Companies
AFFORDABLE HST filing that charges 13% on taxable lease billings, recovers your input tax credits, and reports the loan side on its own footing.
Tax Planning for Equipment Finance Companies
Planning around residual realisation, recapture timing, the Small Business Deduction, funding-line interest and the eventual sale of the company.
Corporate Catch-Up Filing for Equipment Finance Companies
File overdue T2, HST and payroll years, rebuild the capital cost allowance schedule, and get back into CRA compliance without guesswork.
CRA Audit Resolution for Equipment Finance Companies
Expert support on HST, input-tax-credit apportionment, capital cost allowance and recapture reviews, with RC4288 relief handled with confidence.
CPA Financial Statements (Notice to Reader) for Equipment Finance Companies
CPA-compiled statements your funder accepts, presenting equipment on lease as depreciable property and splitting lease revenue from interest income.
Incorporation Services for Equipment Finance Companies
Full incorporation including NUANS, articles, share structure, HST registration, and the section 85 rollover of equipment you already own.
Catch-Up Bookkeeping Services for Equipment Finance Companies
Reconstruct months or years of lease billing and unit-level cost records, rebuild the equipment register, and restore monthly reporting.
US Corporation & LLC Tax Filing for Equipment Finance Companies
Cross-border filing for lessors with US customers or subsidiaries, covering Forms 1120, 1120-F and 5472 alongside your Canadian returns.
Voluntary Disclosure Program for Equipment Finance Companies
Come forward on unreported lease revenue or uncharged HST through the CRA Voluntary Disclosures Program, filing Form RC199 before an audit starts.
Accounting & Tax Services Tailored for Equipment Finance Companies
Real, practitioner-level CPA expertise for equipment lessors, vendor finance programs, specialty and municipal lessors, asset-based finance companies and equipment-secured lenders across Ontario — built for how a lease book and a loan book actually run side by side.
- We prepare your T2 with GIFI so lease revenue, finance income and interest income land on the correct Schedule 125 lines, and the equipment you own and lease out appears on Schedule 100 as depreciable property rather than inventory.
- We claim capital cost allowance on Schedule 8 for every unit on lease, with general equipment in Class 8 at 20% and qualifying vehicles in Class 10 at 30%, applying the half-year rule in the year each unit is acquired.
- When a unit comes off lease and sells above its undepreciated capital cost, we compute recapture under ITA 13(1), or the terminal loss where a class is emptied, and timing a replacement purchase into that class absorbed $31,000 of recapture for one lessor.
- We deduct the interest on your own funding line under ITA 20(1)(c) while keeping principal repayments out of the expense account, a split prior preparers get wrong often enough that correcting it moved $18,400 of deductions into the right years.
- We keep your active income under the $500,000 small business deduction limit so the first half-million of lease and finance profit is taxed near 12.2% in Ontario, and we watch the associated-corporation rules before CRA grinds that limit down.
- We build a chart of accounts that keeps the lease book and the loan book on separate revenue lines from day one, because the two carry opposite HST treatments and a single blended account makes your return impossible to support.
- We set up an equipment sub-ledger so every unit on lease carries its cost, its CCA class, its accumulated depreciation and its expected residual, which is the only way to see what a unit is actually worth when it comes back.
- We recognise finance income across the term of each contract instead of taking it up front, and restating this moved $46,000 of income out of the first year and into the periods it was actually earned for one lessor.
- When a unit is repossessed we book it as an asset event, not a bad-debt event: the equipment returns to your books at a supportable carrying value and is re-leased or remarketed, which is a completely different entry from writing off a receivable.
- We capture supplier invoices, delivery and installation costs, inspection fees and freight through Dext and attach each one to the right unit, so a $27,000 pool of capitalisable cost is documented rather than lost to a missing receipt.
- We run payroll for your credit, documentation and remarketing staff with source deductions remitted on the PD7A schedule CRA assigns you, because a late remittance carries a graduated penalty that reaches 10% of the amount you were required to send.
- We file your T4 slips and T4 Summary by the last day of February and reconcile them to every PD7A remitted during the year, so the year-end totals match and CRA never opens a payroll discrepancy review on your file.
- We register you with WSIB from your first hire and keep the classification and reported earnings current, because coverage obligations start with the first employee, and a gap found years later is far more expensive to unwind than registering on time.
- We monitor Ontario employer health tax so you begin remitting only once your payroll passes the $1,000,000 exemption, and we correct the filings of lessors who registered early and paid EHT on payroll that was never subject to it.
- We handle commission and bonus pay for your originators, issue records of employment on separation, track vacation pay under the Employment Standards Act, and one lessor recovered $6,100 in over-remitted source deductions once the register was rebuilt.
- A lease of equipment is a taxable supply of tangible personal property, so we set your billing to charge 13% HST on lease payments in Ontario and file returns that report that tax correctly every single period.
- Because those supplies are taxable, we claim the input tax credits you are entitled to on the equipment you buy to put on lease and on the inputs used to make the supplies, which is money most lessors leave on the table.
- The loan side is the opposite: interest on a loan secured by equipment is an exempt financial service under ETA section 123(1), so no HST is charged on that interest and credits on the inputs used to earn it are restricted.
- Writing both makes you a mixed supplier, so we build an apportionment of your input tax credits on a fair and reasonable basis, document the method in writing, and then apply it consistently period after period.
- Where you lease into another province we determine the place of supply for that contract and set the rate accordingly rather than defaulting to Ontario, and correcting one blanket 13% billing practice returned $14,700 to customers and closed the exposure.
- Residual value is where lease profit is actually made or lost, so we model the end-of-term outcome on every deal, purchase option exercised, renewal or remarketing, and show you the after-tax yield rather than the yield in the contract.
- We plan disposals across the fiscal year so recapture under ITA 13(1) on units sold above undepreciated capital cost is offset by additions to the same class, which for one lessor deferred $22,800 of tax into a later year.
- We set the salary and dividend mix so active income stays inside the $500,000 small business deduction at roughly 12.2% in Ontario rather than being drawn out and taxed at a top personal rate of 53.53%.
- We structure the debt on your funding line so the interest stays deductible under ITA 20(1)(c) and traceable to the equipment it financed, because a commingled draw used partly for personal purposes is the first thing a reviewer unwinds.
- We plan the eventual sale of the company so a gain on qualified small business corporation shares can be sheltered under the $1.25M lifetime capital gains exemption, and we purify the balance sheet years ahead of a sale rather than weeks before.
- When several T2 years are outstanding we file them in order, rebuilding the capital cost allowance schedule year by year so the undepreciated capital cost carried into the current year is defensible instead of simply guessed.
- We reconstruct disposals from bills of sale and remarketing records so every unit that left the fleet is matched to proceeds, and the recapture or terminal loss falls in the year it belongs rather than being dumped into the latest return.
- We file the overdue HST returns alongside the T2s, because a lessor who never charged tax on a taxable supply usually also never claimed the credits on the equipment, and the two corrections have to be worked together.
- We bring payroll current at the same time, filing the missing T4 slips and Summaries and reconciling them to the PD7A record, so a graduated late-remittance penalty reaching 10% is argued down rather than simply paid.
- Where penalties and interest have built up we apply for relief on Form RC4288 under the taxpayer relief provisions, and one lessor four years behind filed everything and had a five-figure penalty balance substantially reduced.
- The audit that finds equipment lessors most often is the HST one: a reviewer asks why tax was not charged on lease payments, or why credits were claimed against income that was never taxable, and we answer with the contracts.
- When your input tax credit apportionment is challenged, we produce the written method, show it was applied consistently across periods, and demonstrate that the basis chosen was fair and reasonable for the mix of business you actually wrote.
- Where CRA questions who is entitled to claim capital cost allowance on a unit, we set out the substance of the arrangement, who bears the risks and rewards of ownership, rather than resting on how the document happens to be titled.
- On a recapture reassessment we rebuild the class from the original additions forward and prove the undepreciated capital cost the auditor is working from is wrong, and one lessor saw a proposed $38,000 income inclusion cut to under $9,000.
- We handle the correspondence, meet the deadlines in the proposal letter, file the notice of objection where the assessment is wrong, and pursue relief on Form RC4288 where penalties and interest arose from a prior preparer error.
- We compile financial statements that present equipment held on lease as depreciable property carried at cost less accumulated depreciation, never as inventory, which is the presentation a funder reads before extending or renewing your facility.
- The statements separate lease revenue from interest income so a reader can see the two halves of your book, and so the HST position behind each half is visible instead of buried in one blended revenue line.
- Whether a contract is a true lease or in substance a conditional sale drives who holds the asset on the balance sheet, and we test that by the substance of the arrangement rather than by what the agreement happens to be called.
- We disclose the residual value assumptions sitting behind the fleet, because a funder who cannot see what you expect units to be worth at end of term cannot size a facility, and one lessor limit rose by $400,000 once they could.
- Finance income is presented as earned across the term of each contract rather than recognised at inception, so the statements show an earnings pattern that matches the cash the portfolio actually produces month after month.
- We handle the full incorporation, NUANS search, articles, minute book and share structure, so your lease and loan book is written inside a corporation taxed near 12.2% on the first $500,000 of active income in Ontario.
- Where you already own equipment personally and want it inside the company, we transfer it on a section 85 rollover filed on Form T2057 so the move happens at an elected amount instead of triggering a gain on day one.
- We set the share structure so a future sale can qualify for the $1.25M lifetime capital gains exemption, and we review the asset tests early because the mix of leasing and lending in your company affects whether the shares will qualify.
- We register the corporation for HST from the start, because a lessor making taxable supplies needs a number before it can charge tax on lease payments or claim credits on the first machines it buys.
- We model the break-even honestly: incorporation costs a flat $35 with us plus annual T2 filing, so if your lease profit is fully drawn out each year the deferral is worth little and we will tell you to wait.
- We reconstruct months or years of lease billing, receipts and unit-level cost records from bank statements, supplier invoices and contract files, so the books behind your overdue returns are built on documents rather than on estimates.
- We rebuild the equipment sub-ledger from scratch where none existed, assigning each unit its cost, class and in-service date, which for one lessor uncovered $63,000 of capital additions that had been expensed and never depreciated.
- We separate the lease book from the loan book retroactively, period by period, so the HST returns that follow can charge tax on one stream and report the other correctly instead of averaging the two together.
- We set up QuickBooks Online or Xero properly once the history is clean, with recurring lease billing, the equipment register and the funding-line schedule all in place, so the catch-up is the last one you ever need.
- We keep six years of supporting records organised the way section 230 of the Income Tax Act requires, so when a reviewer asks for the file on a unit sold three years ago it takes minutes rather than weeks.
- Lessors with equipment on lease to US customers or a US subsidiary face a second filing system, and we prepare Forms 1120 or 1120-F alongside your Canadian T2 so that the two returns tell the same story.
- Where a US corporation is 25% foreign-owned or transacts with a related Canadian party, Form 5472 reporting applies, and we prepare it with the intercompany lease and funding flows documented rather than reconstructed under pressure.
- We apply the Canada-United States tax treaty to determine where your lease and finance income is taxable and claim foreign tax credits on the Canadian side, so that the same profit is not taxed twice over.
- We review whether US state filing obligations arise from equipment physically located in a state, because a machine sitting on a customer floor in another jurisdiction is a fact that state tax authorities pay attention to.
- We coordinate the two year-ends, the two depreciation systems and the currency translation so the fleet is not depreciated on one basis in Canada and an incompatible basis in the United States, saving one group $11,500 in duplicated adjustments.
- Where lease revenue or HST went unreported for years, the Voluntary Disclosures Program lets you come forward before CRA finds you, and we file the application on Form RC199 with the corrected figures attached.
- An application must be genuinely voluntary, complete, and relate to information at least one year past due, so we assess whether you qualify before you disclose anything rather than after the door has already closed.
- Voluntary is the condition lessors lose most often: once CRA has contacted you about the period, or an audit of a customer has already reached your contracts, the opportunity is usually gone for good.
- Complete means every year and every stream, so we rebuild the lease billing, the interest income and the disposals together, because a partial disclosure that leaves one year out can put the whole application at risk.
- A successful application reduces penalties and part of the arrears interest, and for a lessor who had never charged tax on $340,000 of lease billings the relief and the recovered credits together were worth over $40,000.
Equipment Lease & HST Check
Six quick questions on your HST on lease billings, input tax credits, the lease-versus-loan split, capital cost allowance on the fleet, residual tracking and whether it is time to incorporate. No fee shown.
1. Are you charging 13% HST on your lease payments?
2. Are you claiming input tax credits on equipment bought to put on lease?
3. If you also write loans, do you apportion credits on a documented basis?
4. Is capital cost allowance being claimed on every unit you own on lease?
5. Do you track an expected residual value on each contract?
6. Is your equipment finance business incorporated yet?
Free CPA Consultation for Equipment Finance Companies
Case Studies: Equipment Finance Accounting & Tax
Brampton Equipment Lessor — HST Never Charged on Lease Billings
The problem: A Brampton company leasing food-processing equipment had never charged HST on a single lease invoice. The owner had simply assumed finance income was not taxable. In fact a lease of equipment is a taxable supply of tangible personal property, so 13% HST was owed on every payment billed in Ontario, and because the company thought its supplies carried no tax it had never claimed a dollar of input tax credits on the machines it bought.
What we did: We quantified the uncollected tax across the open periods, corrected the billing so lease invoices carried HST, and rebuilt the purchase history of the fleet to claim the credits that had never been taken.
The result:
- Lease billing corrected to a taxable footing
- Input tax credits recovered across the fleet
- Net exposure a fraction of the gross figure
Cambridge Lessor — Fleet Expensed Instead of Capitalised
The problem: A Cambridge lessor of construction and material-handling equipment had been expensing every machine in the year of purchase. Units on lease are depreciable property, not inventory, so the returns showed enormous losses while the fleet was built and nothing to deduct afterwards. There was no equipment register, no capital cost allowance schedule, and no record of what had been sold off lease or what it fetched.
What we did: We rebuilt the fleet from purchase invoices, assigned each unit to its CCA class, ran the half-year rule in the correct acquisition years, and reconstructed every disposal so recapture and terminal losses landed where they belonged.
The result:
- $63,000 of capital additions restored to the schedule
- Recapture and terminal losses placed in the right years
- Unit-level equipment register built and maintained
London Lessor — One Ledger for Two Opposite Tax Profiles
The problem: A London company wrote both equipment leases and equipment-secured loans, often for the same customers, and ran every dollar through one revenue account. Nobody could tell which HST returns covered taxable lease billings and which covered interest that is an exempt financial service under ETA section 123(1). Input tax credits on shared overhead were claimed in full, with no apportionment, no method written down and no consistency between periods.
What we did: We split the ledger into a lease book and a loan book, restated the affected periods, and built an input tax credit apportionment on a fair and reasonable basis, with the method set out in writing.
The result:
- Lease and loan revenue now reported separately
- Documented input tax credit apportionment in place
- Method applied consistently period after period
Our clear, efficient process ensures every step is transparent, building trust and long-term client relationships.
Kickoff (Document Request)
Collect prior T2 and HST returns, the lease and loan contracts, equipment purchase invoices, disposal records, funding-line agreements, payroll and T4 records, and bank statements.
First 30 Days (Cleanup & Setup)
Set up QuickBooks Online or Xero, split the lease book from the loan book, build the unit-level equipment sub-ledger, and set the HST billing and input tax credit apportionment.
Monthly Close
Lease billing and HST reconciliation, finance income accreted over the term, equipment additions and disposals posted, funding-line interest split from principal, payroll and PD7A remittances.
Quarterly Planning Review
Capital cost allowance position by class, recapture exposure on planned disposals, residual assumptions against actual realisations, salary and dividend mix, and input tax credit apportionment review.
Year-End Close & T2 Filing
Trial balance, financial statements carrying the fleet as depreciable property, Schedule 8 tied to the equipment register, T2 with GIFI, payroll slips, and CRA preparation.
Get Your Equipment Finance Taxes Done Right Today
Affordable Pricing for Equipment Finance Companies
We believe in clear, upfront pricing so you know exactly what to expect. All fees include HST.
- Tax Preparation (Corporation) — From $400
- Tax Return Filing (Corporation) — From $400
- Tax Compliance Audit — FREE CRA audit support for our clients
- Tax Strategy — FREE for our clients
- Accounting Base Plan — From $100 per month
- Bookkeeping Management — Free for our Accounting clients
- Financial Reporting — Free for our Accounting clients
- Business Formation — Flat $35
- Incorporation Process — Flat $35
- Entity Setup Assistance — Flat $35
- Full-Service Payroll — From $125 per month
Payment is by Interac e-Transfer to info@gondaliyacpa.ca only. Security question: Not Applicable, as auto-deposit is enabled.
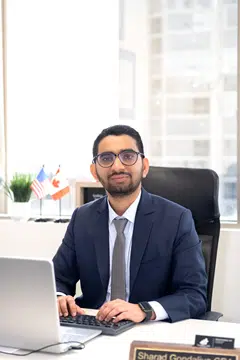
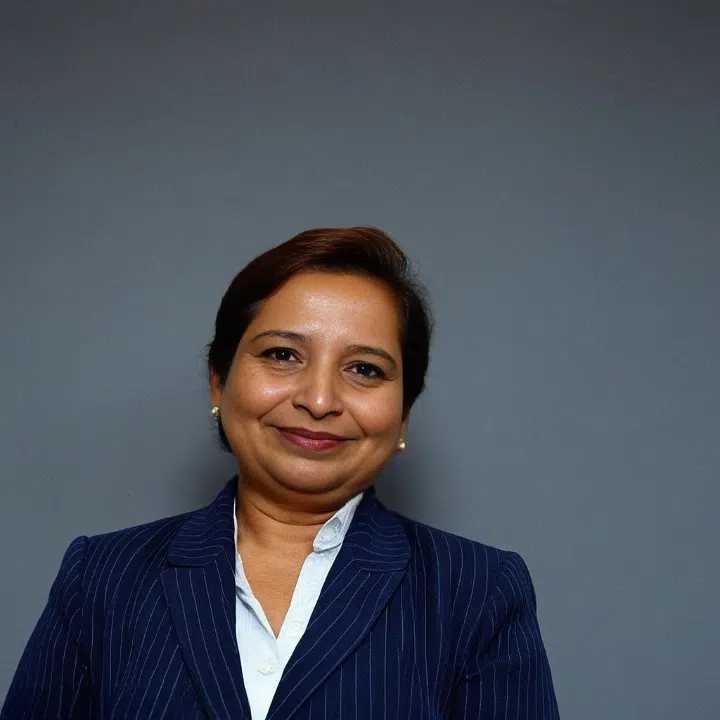
Meet Your Lead Equipment Finance Accountant
Meet your lead equipment finance accountant. As your HST, capital cost allowance and corporate tax adviser, you deal with the same two people every year.
What Our Clients Say
1300+ five-star reviews from equipment finance and small-business owners across Ontario and Canada.
Serving Equipment Finance Companies Across Ontario
Our CPA team provides specialized accounting and tax solutions for equipment finance companies throughout Ontario. We understand how taxable lease billings, exempt interest income, input tax credit apportionment, capital cost allowance on the fleet and end-of-term disposals actually flow through a lessor, what CRA looks at on a mixed-supplier file, and where the real margin sits once residuals are realised.
Toronto (ON)
55 Queen St E Ste 1205, Toronto, ON M5C 1R6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Mississauga (ON)
2100 Camilla Rd #716, Mississauga, ON, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Brampton (ON)
4 Starhill Crescent, Brampton, ON L6R 2P9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Scarborough (ON)
24 Clementine Square, Scarborough, ON M1G 2V7, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Vaughan (ON)
19 Cabinet Crescent, Woodbridge, ON L4L 6H9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Oshawa (ON)
210 Durham St, Oshawa, ON L1J 5R3, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Ottawa (ON)
2090 Neepawa Ave a314, Ottawa, ON K2A 3L6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Etobicoke (ON)
60 Stevenson Rd #1601, Etobicoke, ON M9V 2B4, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Hamilton (ON)
70 Starling Dr, Hamilton, ON L9A 0C5, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Guelph (ON)
1155 Gordon St, Guelph, ON N1L 1S8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Windsor (ON)
4387 Guppy Ct, Windsor, ON N9G 2N8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
North York (ON)
150 Graydon Hall Dr #912, North York, ON M3A 3B2, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Equipment Finance Accounting & Tax FAQs
Related Industries We Serve
Accountant for Private Lenders
- Exempt interest income and restricted credits
- Corporate tax planning and financial statements
- Bookkeeping and loan portfolio accounting
Accountant for Factoring Companies
- HST treatment of fee and discount income
- T2 corporate returns and GIFI
- Bookkeeping and portfolio reporting
Accounting for Small Businesses
- Corporate tax planning for small businesses
- Business tax filing and financial statements
- Payroll and bookkeeping services
Accountant for Incorporated Businesses
- T2 corporate returns and GIFI
- Salary, dividend and SBD planning
- Compilation statements and incorporation
Equipment Finance Accounting & Tax Done Right.
T2 filing, 13% HST charged on taxable lease payments with input tax credits recovered, capital cost allowance on the fleet, recapture and terminal losses on disposal, residual tracking, payroll and incorporation under one roof. Exempt loan interest under ETA section 123(1) is reported on its own footing, with a fair and reasonable input tax credit apportionment built for mixed suppliers. AFFORDABLE flat fees, no hourly billing. Licensed CPA Ontario. 1300+ five-star reviews. 30-Day Money-Back Guarantee.