



Tax Accountant for Pawn Shops in Ontario and Across Canada
A pawn shop is two businesses sharing one till. The charge you earn on a pledge sits on the financial-service side under ETA section 123(1) and carries no HST, while the forfeited goods you put out on the shop floor are ordinary retail stock sold at 13% with input tax credits recoverable. That makes you a mixed supplier, so the HST on rent, alarm monitoring, showcases and hydro has to be apportioned between the two sides on a basis that is fair and reasonable, written down once and applied the same way every period. We build the pledge ledger behind both streams, post forfeiture as an inventory event at loan value instead of a bad debt, carry that stock under ITA section 10, and keep the cash records that prove the income you reported is the income you earned. Flat-fee, no hourly billing, CPA Ontario, 1300+ five-star.
AFFORDABLE Pawn Shop Tax Accountant
A pawn shop earns money in two ways the tax rules treat as opposites. The charge on a pawn loan falls on the financial-service side under ETA section 123(1), so no HST is added to it; the resale of goods nobody came back for is plain retail, taxable at 13%, with the tax on your own purchases recoverable. Running both through one set of books and then claiming every input tax credit, or none of them, is the most expensive habit in the trade and the one CRA spots fastest. Making both kinds of supply makes you a mixed supplier, and the credits on shared costs must be apportioned on a basis that is fair and reasonable, documented, and repeated without variation each period. At Gondaliya CPA we set up the two revenue lines, the pledge ledger sitting behind them and the apportionment working paper, providing AFFORDABLE flat-fee support that keeps you CRA-compliant and stops you paying tax you do not owe.
As a pawn shop accountant we work with single-storefront pawnbrokers, multi-location chains, second-hand goods dealers, gold and scrap buyers, and shops that move forfeited stock through an online channel as well as the counter. You get year-round support rather than a once-a-year scramble. We tell you plainly what the lending side can and cannot recover, what the shop floor can, and where the real margin sits once forfeited goods are costed at what they actually cost you.
Let us handle the numbers so you can stay at the counter, where the money is made.
Our Official Partners
Accounting That Understands How a Pawn Shop Actually Works
A pawn shop meets a financial reality that neither an ordinary retailer nor an ordinary lender ever faces. Part of your revenue is a loan charge carrying no HST; the rest is a retail sale at 13% on goods you acquired by lending against them. Forfeiture is not a bad debt, it is the day you bought stock, and the loan value becomes its cost. Add a cash-heavy counter where the pledge ledger is the only evidence that the income reported is the income earned, and you need a CPA who has worked both halves. At Gondaliya CPA we understand how a pawn shop really earns, and bring practical answers to pawnbrokers right across the GTA and the rest of Ontario.
Stay Compliant and Minimize Your Pawn Shop Tax
For a pawn shop, staying onside with CRA and paying the least legal tax are one exercise, not two. We settle and record the character of each loan charge, each separately billed fee and each counter sale, hold every filing to its own date, and leave nothing loose for a reviewer to pull on.
Accounting & Tax Experts for Pawn Shops
- AFFORDABLE + Registered CPA Firm
- Business and Corporate Tax Expert
- Small & Medium Business Expert
- Accounting, bookkeeping, and tax filing
- CPA (Chartered Professional Accountant)
- 1300+ 5-star Google reviews
- 30-Day Money-Back Guarantee
- 60-Day Fees Matching Policy
Why Choose Our Accounting Services for Pawn Shops?
Tax Planning — Mixed Supply & Inventory
We manage how much profit stays inside the company against the $500,000 threshold and the roughly 12.2% Ontario small-business rate, set the salary and dividend split against a 53.53% top personal rate, plan the section 85 rollover, and keep the $1.25M capital gains exemption within reach.
Consulting — Pledge Ledger & Two Revenue Lines
Our bookkeeping posts exempt loan charges and taxable retail sales to separate lines, runs a pledge ledger that agrees with the general ledger, brings forfeited goods into inventory at loan value, and supports a documented input tax credit apportionment.
CRA Representation — HST & Cash Audit
Questions about your apportionment method, the character of a storage or handling fee, or whether the counter reported everything it took in are all answered from one place: a pledge ledger that ties out. Where penalties trace back to an earlier error, we apply for relief on Form RC4288.
Bookkeeping — Counter Payroll & Growth
We run T4 payroll for counter and security staff, keep source deductions reconciled to the PD7A, issue records of employment on separation, and model the profit level at which opening a second storefront actually pays off.
Google Reviews
Pawn Shop Clients
Pawn Shop Tax and Accounting Services in Ontario
Corporate Tax Filing (T2) for Pawn Shops
Professional T2 preparation with exempt loan charges and taxable retail sales split across Schedule 125, forfeited stock carried on the balance sheet, and CRA compliance on every line.
Bookkeeping & Accounting for Pawn Shops
Two-revenue-line bookkeeping with a pledge ledger that ties out, forfeited goods costed at loan value, and monthly reporting built for a pawn shop.
Payroll Services for Pawn Shops
T4 payroll for counter and security staff, source deductions reconciled to the PD7A, WSIB from the first hire, and clean records every pay run.
GST/HST Filing for Pawn Shops
AFFORDABLE returns that keep the exempt loan charge off the taxable sales line, with a written mixed-supplier apportionment standing behind every credit claimed.
Tax Planning for Pawn Shops
Small business deduction planning, salary and dividend mix, write-down timing on aged shelf stock, and the capital gains exemption protected for a future sale.
Corporate Catch-Up Filing for Pawn Shops
Years of unfiled T2 returns rebuilt and filed in sequence, with forfeited stock restored at loan value so each year finally reports a profit that is real.
CRA Audit Resolution for Pawn Shops
Expert support on input tax credit apportionment, fee characterisation and cash-completeness reviews, with RC4288 relief handled with confidence.
CPA Financial Statements (Notice to Reader) for Pawn Shops
Compilation reports that separate the loan book from the retail book and carry forfeited stock at the lower of cost and net realizable value.
Incorporation Services for Pawn Shops
Flat $35 incorporation, share structure, CRA program accounts, a section 85 rollover of your existing shop, and a year-end chosen around your stock count.
Catch-Up Bookkeeping Services for Pawn Shops
Months or years of pawn shop records rebuilt from point-of-sale exports and the pledge ledger, with forfeiture entries restored and monthly reporting switched back on.
US Corporation & LLC Tax Filing for Pawn Shops
Cross-border filing for shops selling forfeited stock into the United States, covering Forms 1120, 1120-F and 5472 alongside your Canadian returns.
Voluntary Disclosure Program for Pawn Shops
Unreported counter income brought forward on Form RC199 under the CRA Voluntary Disclosures Program, quantified from your own records, before a letter arrives.
Accounting & Tax Services Tailored for Pawn Shops
Real, practitioner-level CPA expertise for single-storefront pawnbrokers, multi-location chains, second-hand goods dealers, gold and scrap buyers, and pawn shops selling forfeited stock online as well as over the counter.
- We prepare your T2 with GIFI, reporting exempt loan-charge revenue and taxable retail sales of forfeited goods on separate Schedule 125 lines with the stock itself on Schedule 100, so a mixed book never reads as one undifferentiated pile of sales.
- We claim capital cost allowance on Schedule 8 with showcases, safes and security equipment in CCA Class 8 at 20% and your point-of-sale terminals and back-office computers in Class 50 at 55%, and one shop recovered $4,900 a prior preparer had skipped.
- We put your store build-out into Class 13 and write it off across the term of your lease, rather than burying a counter renovation in repairs, a reclassification that moved $31,000 of spending onto the correct schedule for one storefront.
- We carry forfeited stock as inventory under ITA section 10 rather than as a written-off advance, because a pledge nobody came back for is a purchase of goods, and the loan value is what those goods cost you.
- Your T2 falls due six months after the fiscal year-end and the balance two or three months after it, so we work to the earlier payment date rather than the filing date, and a shop clearing $180,000 of profit never pays arrears interest.
- We run two revenue lines from the first day: the charge on pledges, which carries no HST under ETA section 123(1), and retail sales of forfeited or purchased goods, which are taxable at 13% with the tax on your own inputs recoverable.
- We keep a pledge ledger that ties to the general ledger every month, so the value out on loan in your counter system and the receivable on your balance sheet are one number rather than two competing estimates.
- We post forfeiture as a journal entry that moves the loan value out of loans receivable and into inventory, giving every item a cost on the day it reaches the shop floor instead of an unexplained margin much later.
- We keep outright purchases from the public in a ledger of their own, because buying an item across the counter is an inventory acquisition at cost and has nothing in common with advancing money against a pledge.
- We reconcile the till and the point-of-sale report to the bank deposit daily, and for one shop that single discipline surfaced $12,400 of sales that had never reached the books at all.
- We set up WSIB coverage from your first counter or security hire, open the payroll program account, and run T4 payroll so staff paid at the close of a busy Saturday are still reported the way CRA expects.
- We file your T4 slips and T4 Summary by the last day of February and reconcile the total to the PD7A statements CRA issued through the year, so the two figures already agree before anyone at CRA compares them.
- We calculate Ontario Employer Health Tax only once your payroll passes the $1,000,000 exemption, and for one two-storefront operator that check alone prevented an unnecessary $7,300 payment on a payroll still under the line.
- We keep source deductions on schedule, because the penalty for paying them late is graduated and reaches 10%, and a cash business that runs a week behind twice a year gives that money away for nothing.
- We issue records of employment on separation, handle seasonal and part-time counter staff, and split payroll by storefront so you can see what each location truly costs before deciding whether to open a third.
- We report the charge on your pawn loans on the financial-service side under ETA section 123(1), so no HST is added to it, and we keep it off the taxable sales line where any reviewer would expect to find tax.
- We charge and report 13% HST on every retail sale of forfeited or purchased goods, because second-hand does not mean tax-free and your shop floor is an ordinary taxable retailer in CRA’s eyes.
- Making both kinds of supply makes you a mixed supplier, so we apportion the HST on rent, alarm monitoring, showcases, hydro and professional fees between the two sides on a fair and reasonable basis and write that method down.
- We then apply the same basis every period instead of recalculating it to suit the quarter, because an apportionment that moves without explanation is the first thing reversed on reassessment, with interest running from the original due date.
- We test whether each separately charged storage, handling or insurance fee belongs on the taxable side and document the conclusion, and one such review corrected $9,600 of HST that had never been charged.
- We manage how much active income stays in the company so the first $500,000 is taxed near the 12.2% Ontario small-business rate, and we watch the associated-corporation rules before a second storefront quietly shrinks that threshold.
- We set the salary and dividend mix against a 53.53% Ontario top personal rate, leaving surplus inside the corporation where you do not need it personally, which deferred roughly $23,000 of tax for one owner in a single year.
- Jewellery, electronics and scrap gold all move in price after they reach your shelf, so we time the write-down on aged stock into the year the decline actually happened rather than letting it drift across a year-end.
- We plan the section 85 rollover on Form T2057 so the stock, showcases and goodwill of an established shop move into a corporation at elected amounts instead of triggering a gain on the transfer itself.
- We protect the $1.25M Lifetime Capital Gains Exemption on a future sale by keeping the shares qualifying, watching the cash and passive assets that pile up inside a profitable shop, and purifying well ahead of any deal.
- We rebuild and file every missing T2, working backwards from bank statements, point-of-sale exports and the pledge ledger so each year reports the loan charges and the retail sales that genuinely happened inside it.
- We reconstruct the stock position at each historic year-end, bringing forfeited goods in at loan value, because a T2 filed without an opening and closing inventory figure reports a cost of goods sold that cannot possibly be right.
- We correct prior returns that treated forfeited pledges as bad-debt write-offs, which understates stock and overstates expense in the same year, and for one shop that single fix changed three years of reported profit.
- Where a shop has left three years unfiled, we typically surface $18,000 or more of unclaimed capital cost allowance, licence and alarm-monitoring costs, cutting the corporate tax owing across the catch-up returns.
- We file everything in sequence with a covering explanation rather than dropping three returns on CRA at once, which keeps the account current and keeps the shop eligible for the taxpayer relief route if penalties have built up.
- When CRA questions your input tax credits, we produce the written apportionment, show the basis was fair and reasonable for the revenue mix you actually had, and demonstrate it was applied the same way every period.
- We answer the cash-completeness questions a pawn shop attracts by tying the pledge ledger, the till reports and the bank deposits to one another, because ITA section 230 makes those records the evidence and not merely the bookkeeping.
- A shop that cannot support its own numbers invites an arbitrary assessment under ITA section 152(7), where CRA sets the income itself from what it can observe and you carry the burden of proving that figure wrong.
- We defend the characterisation of loan charges, storage fees and handling fees line by line with the reasoning recorded at the time, because a conclusion documented before an audit carries weight that one written afterwards simply does not.
- We pursue taxpayer relief on Form RC4288 where penalties and interest grew out of a prior preparer’s error, and one pawn shop had $11,200 of penalty and interest cancelled on exactly that basis.
- We prepare a compilation engagement report, the Notice to Reader a landlord, a bank or an incoming partner expects, built from your books rather than from a summary typed out the night before it was needed.
- The statements separate exempt loan-charge revenue from taxable retail sales, so a reader sees the two margins that genuinely exist inside a pawn shop instead of one blended gross profit figure that explains nothing at all.
- Forfeited stock is presented at the lower of cost and net realizable value, cost being the loan value at forfeiture, so the balance sheet stops carrying aged goods at a number the shop floor abandoned long ago.
- Loans outstanding against pledges appear as a receivable supported by the pledge ledger, which gives a lender a figure it can actually test rather than a balance it has to take entirely on faith.
- One shop declined twice for financing was approved for a $150,000 operating facility once the statements showed the loan book and the retail book separately and the stock was properly costed.
- We incorporate your pawn shop for a flat $35 in professional fees plus the government charge, set the share structure so a spouse or a successor can be brought in later, and open the CRA program accounts.
- We model the break-even honestly: a corporation only pays for itself once you consistently earn more than you withdraw, because the benefit is deferral, and a shop taking home everything it makes gains very little.
- We move an established storefront into the company on a section 85 rollover using Form T2057, transferring stock, showcases and goodwill at elected amounts instead of triggering a gain on the way in.
- We choose a fiscal year-end that falls after your quietest trading stretch, so the physical count of forfeited stock happens when the shelves are lightest and the figure you sign off on is genuinely reliable.
- We register you for HST against your taxable retail sales rather than your total takings, because the $30,000 small-supplier threshold measures taxable supplies and your exempt loan charges do not count toward it.
- We rebuild months or years of missing books from point-of-sale exports, the pledge ledger and bank statements, posting each loan charge and each retail sale to the period it belonged in rather than the period the cash cleared.
- We separate exempt loan-charge revenue from taxable retail sales as we go, because a catch-up that reports one lump of income turns every later HST return and every apportionment into guesswork nobody can defend.
- We reconstruct the forfeiture entries year by year, moving each loan value out of loans receivable and into inventory on the date the pledge lapsed, which is the only way a cost of goods sold comes out right.
- Where a shop has three years unrecorded, we routinely find $15,000 or more of deductible alarm monitoring, licence, insurance and bank charges that were never claimed, reducing the tax owing on the rebuilt returns.
- We finish a standard three-year catch-up within 45 days of receiving your records, then hand you reconciled monthly figures so the next pledge, the next forfeiture and the next sale are recorded as they happen.
- When your shop lists forfeited stock on United States marketplaces or ships to American buyers, we test whether that activity creates a US trade or business and file Form 1120-F where a filing obligation genuinely exists.
- If you hold a US C-corporation or a single-member LLC to run the American sales channel, we prepare Form 1120 and the Form 5472 information return, avoiding the $25,000 penalty for leaving it out.
- We apply the Canada-US tax treaty to test whether the shop has a US permanent establishment, so an Ontario pawnbroker shipping the occasional watch south is not taxed twice on the same margin.
- We complete the W-8BEN-E your American buyers and marketplaces request in order to reduce withholding, and coordinate Form T1135 reporting where the shop keeps a US bank account for settling cross-border sales.
- Where US tax has already been paid on that income, we claim the foreign tax credit on the Canadian T2 so one margin is not taxed twice, which has been worth $10,000 or more a year to shops with genuine cross-border volume.
- We prepare and file Form RC199 to bring unreported counter income forward under the CRA Voluntary Disclosures Program, restoring years of loan charges and retail sales before an audit letter arrives and the door closes.
- The submission must be voluntary, must be complete, and must reach back a year or more that is already past due. Once CRA has made contact the programme is generally shut to you, so timing decides whether relief exists at all.
- A pawn shop disclosure is rarely income tax alone: the retail side is taxable at 13%, so unreported sales usually carry uncollected HST that has to be quantified and included in the very same submission.
- We rebuild the figures from the pledge ledger, till reports and deposits so the disclosed amounts hold up under the review that always follows, rather than offering CRA a round number nobody can trace.
- Relief under the programme lifts gross-negligence penalties, which run as high as 50% of the tax understated, and trims arrears interest; for one shop that had left $90,000 of sales off its returns that came to more than $25,000.
Pawn Shop Mixed-Supply & Inventory Check
Six quick questions on your exempt loan charges, taxable counter sales, input tax credit apportionment, forfeited stock, your pledge ledger and whether it is time to incorporate. No fee shown.
1. Are your loan charges and your retail sales posted to separate revenue lines?
2. Do you charge 13% HST on every sale of forfeited or second-hand goods?
3. Is the split of your input tax credits written down and used the same way each period?
4. Does forfeited stock enter inventory at loan value instead of being written off?
5. Does your pledge ledger agree with your general ledger every month?
6. Is your pawn shop incorporated yet?
Free CPA Consultation for Pawn Shops
Case Studies: Pawn Shop Accounting & Tax
Kingston Pawn Shop — Every Input Tax Credit Claimed on a Mixed Book
The problem: A Kingston pawn shop claimed the full HST on rent, alarm monitoring, showcases, hydro and professional fees as though the whole storefront were taxable retail. Close to half its revenue was the charge on pledges, which sits on the financial-service side under ETA section 123(1), so a large share of those credits was never available. Nothing was written down and the basis drifted from quarter to quarter.
What we did: We measured the two streams from the pledge ledger and the point-of-sale reports, apportioned the shared credits on a fair and reasonable basis, recorded the method in writing, and corrected the affected periods before a review opened.
The result:
- Over $19,000 of exposure cleared before assessment
- Apportionment method written down and applied consistently
- Loan charges and counter sales reported separately
Sudbury Pawn Shop — Forfeited Goods That Never Reached Inventory
The problem: A Sudbury pawn shop treated every unredeemed pledge as a bad debt, writing the advance straight to expense, then sold the goods later with no cost attached to them. Gross margin looked impossible, the stock figure on the balance sheet was a fraction of what stood on the shelves, and two years of reported profit were wrong in opposite directions.
What we did: We rebuilt the forfeiture entries item by item, moved each loan value out of loans receivable into inventory, restated opening and closing stock for both years, took a supported write-down on aged goods, and refiled the T2 returns.
The result:
- $27,400 of stock restored to the balance sheet
- A real gross margin visible on every sale
- Two years of corporate filings corrected
St. Catharines Pawn Shop — A Pledge Ledger That Never Tied to the Books
The problem: A St. Catharines pawn shop ran its loans on a counter system and its accounts in a spreadsheet, and the two had never agreed. Nobody could say what was genuinely out on pledge at month end, forfeitures were noticed only when an item happened to sell, and the owner had no dependable figure for either half of the business.
What we did: We rebuilt the pledge ledger from the counter system, matched it line by line to loans receivable, set a monthly tie-out, added a forfeiture review at each close, and moved the books into QuickBooks Online with two revenue lines.
The result:
- Pledge ledger agrees with the general ledger monthly
- Forfeitures caught at lapse rather than at sale
- Both revenue streams reported on their own lines
Our clear, efficient process ensures every step is transparent, building trust and long-term client relationships.
Kickoff (Document Request)
Collect prior T2 returns, the pledge ledger, till and point-of-sale reports, the count of forfeited stock, payroll and T4 records, HST returns and bank statements.
First 30 Days (Cleanup & Setup)
Set up QuickBooks Online or Xero, split exempt loan charges from taxable counter sales, build the forfeited-stock subledger at loan value, and set the input tax credit apportionment.
Monthly Close
Monthly reconciliations, pledge ledger tie-out to the general ledger, till and point-of-sale cash counts, payroll and source deductions, and both revenue lines checked against the HST return.
Quarterly Planning Review
Salary and dividend mix, apportionment reviewed against the current revenue mix, write-down position on aged shelf stock, storefront profitability, and the incorporation break-even.
Year-End Close & T2 Filing
Trial balance, financial statements separating loan charges from retail sales, stock at the lower of cost and net realizable value, T2 with GIFI, payroll slips, and CRA preparation.
Get Your Pawn Shop Taxes Done Right Today
Affordable Pricing for Pawn Shops
We believe in clear, upfront pricing so you know exactly what to expect. All fees include HST.
- Tax Preparation (Corporation) — From $400
- Tax Return Filing (Corporation) — From $400
- Tax Compliance Audit — FREE CRA audit support for our clients
- Tax Strategy — FREE for our clients
- Accounting Base Plan — From $100 per month
- Bookkeeping Management — Free for our Accounting clients
- Financial Reporting — Free for our Accounting clients
- Business Formation — Flat $35
- Incorporation Process — Flat $35
- Entity Setup Assistance — Flat $35
- Full-Service Payroll — From $125 per month
Payment is by Interac e-Transfer to info@gondaliyacpa.ca only. Security question: Not Applicable, as auto-deposit is enabled.
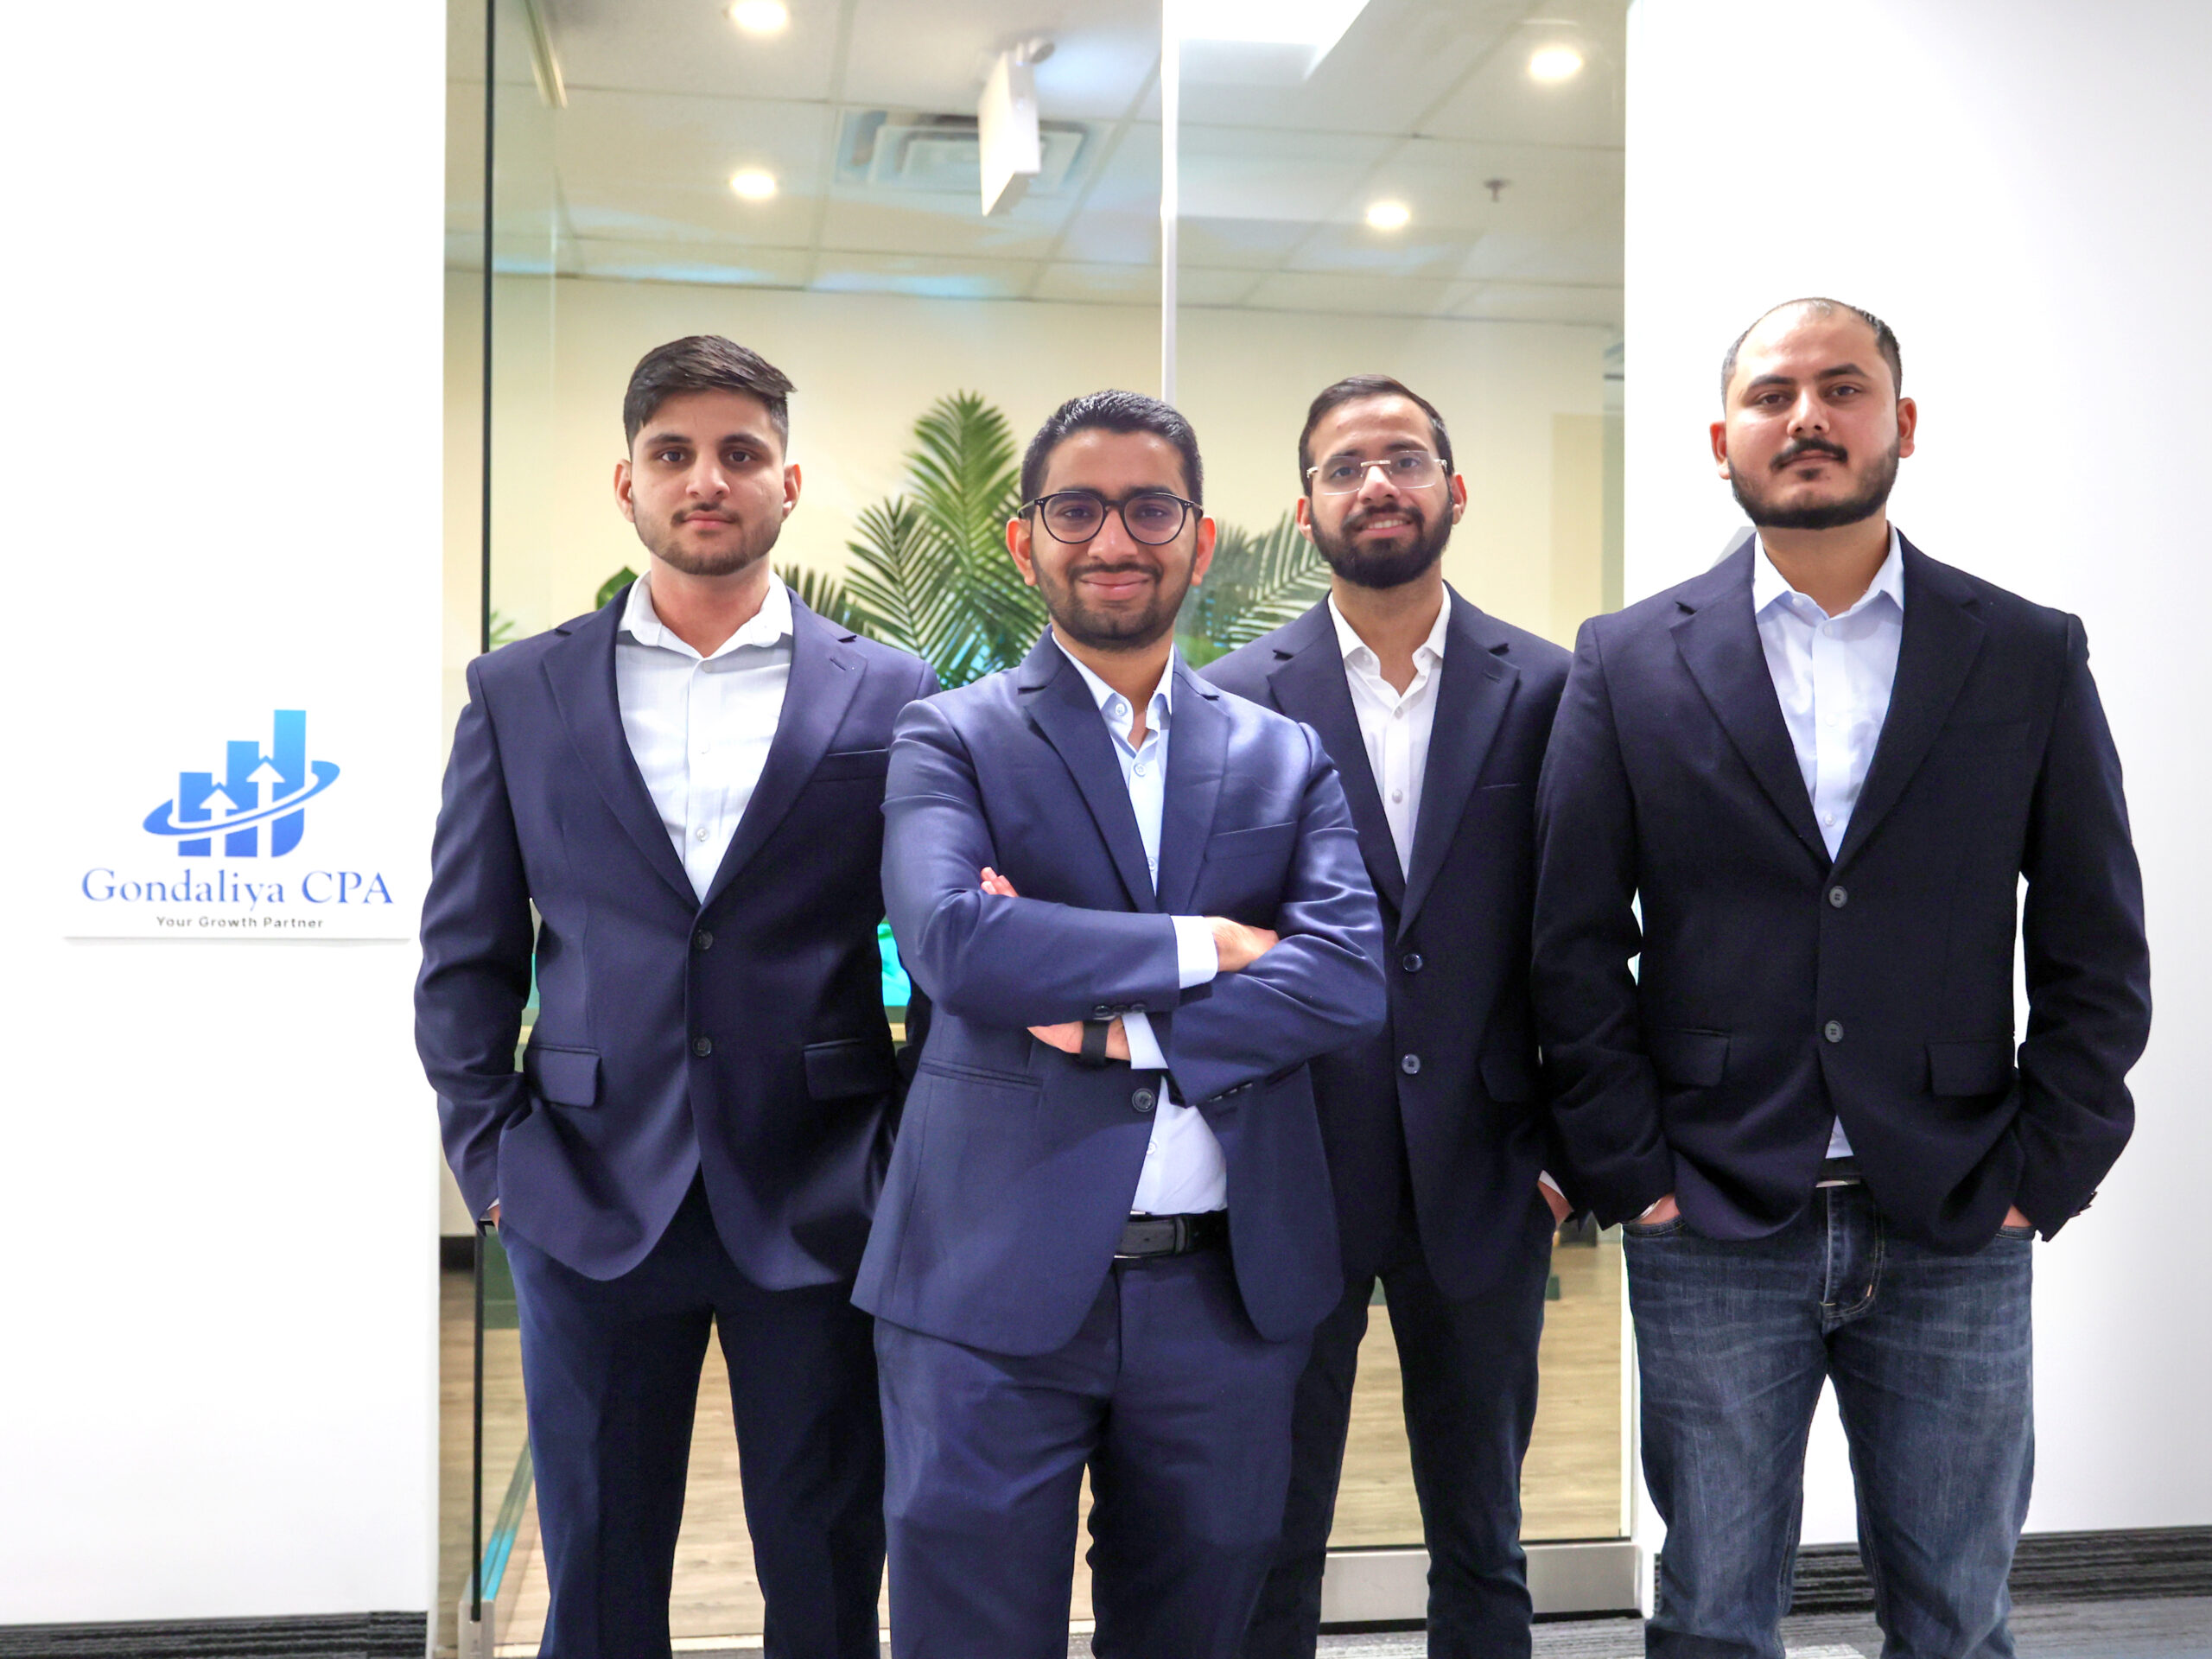
Meet Your Lead Pawn Shop Accountant
Meet your lead pawn shop accountant. The same two people handle your pledge ledger, your HST position and your corporate return, year after year.


What Our Clients Say
Pawnbrokers, retailers and small-business clients throughout Ontario and Canada have left us over 1300 five-star reviews.
Serving Pawn Shops Across Ontario
From single storefronts to small chains, pawnbrokers right across Ontario bring us their books. Shops come to us for one reason: the two halves of the trade need two different answers. We know how an exempt loan charge, a counter sale at 13%, an apportioned credit and a cash-heavy till move through one storefront, which parts of a mixed-supplier file CRA tends to open, and how much margin only becomes visible once forfeited goods carry a real cost.
Toronto (ON)
55 Queen St E Ste 1205, Toronto, ON M5C 1R6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Mississauga (ON)
2100 Camilla Rd #716, Mississauga, ON, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Brampton (ON)
4 Starhill Crescent, Brampton, ON L6R 2P9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Scarborough (ON)
24 Clementine Square, Scarborough, ON M1G 2V7, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Vaughan (ON)
19 Cabinet Crescent, Woodbridge, ON L4L 6H9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Oshawa (ON)
210 Durham St, Oshawa, ON L1J 5R3, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Ottawa (ON)
2090 Neepawa Ave a314, Ottawa, ON K2A 3L6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Etobicoke (ON)
60 Stevenson Rd #1601, Etobicoke, ON M9V 2B4, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Hamilton (ON)
70 Starling Dr, Hamilton, ON L9A 0C5, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Guelph (ON)
1155 Gordon St, Guelph, ON N1L 1S8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Windsor (ON)
4387 Guppy Ct, Windsor, ON N9G 2N8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
North York (ON)
150 Graydon Hall Dr #912, North York, ON M3A 3B2, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Pawn Shop Accounting & Tax FAQs
Related Industries We Serve
Accountant for Private Lenders
- Loan interest on the exempt side
- T5 slips and corporate filings
- Ledgers, statements and planning
Accountant for Currency Exchange Businesses
- Exempt financial services and HST
- Corporate tax filing and compliance
- Bookkeeping and cash controls
Accounting for Small Businesses
- Corporate tax planning for small businesses
- Business tax filing and financial statements
- Payroll and bookkeeping services
Accountant for Incorporated Businesses
- T2 corporate returns and GIFI
- Salary, dividend and SBD planning
- Compilation statements and incorporation
Pawn Shop Accounting & Tax Done Right.
T2 filing, exempt pawn loan charges under ETA section 123(1), taxable resale of forfeited goods at 13%, documented mixed-supplier input tax credit apportionment, forfeited stock costed at loan value under ITA section 10, a pledge ledger that ties out, payroll and the $1.25M capital gains exemption under one roof. AFFORDABLE flat fees, no hourly billing. Licensed CPA Ontario. 1300+ five-star reviews. 30-Day Money-Back Guarantee.