



Tax Accountant for Virtual Assistants in Ontario and Across Canada
One test decides two separate things on your file, and most virtual assistants only ever hear about one of them. Who controls the method and the hours; whose laptop, software licences and client logins the work runs on; who carries a real chance of profit and risk of loss; and how far the work is integrated into the payer’s own operation. CRA guide RC4110 sets those four factors out, and they are applied to you by the client who pays you and applied by you to every assistant you pay. Nothing requires the two answers to agree. A finding of employment lands on whoever paid, which is why a large client’s accountant sometimes raises it before you have, and why the people you subcontract to are your exposure and nobody else’s. We also correct the error that costs most in this trade: bill a client $4,000, pay an associate $2,600, and your revenue is the gross $4,000 with $2,600 of expense beside it — never $1,400 of margin. Expenses come in under section 9 and paragraph 18(1)(a) of the Income Tax Act, we keep paragraph 20(1)(l) clear of paragraph 20(1)(p) when one client is most of the book, charge 13% under the Excise Tax Act, and hold the six years of agreements and hours section 230 asks for. AFFORDABLE flat fees, quoted before we start.
AFFORDABLE Virtual Assistant Tax Accountant
A virtual assistant occupies an unusual position in the tax system. She is somebody else’s contractor, and the moment she hands any part of the work on she becomes somebody else’s payer. Both roles are settled by the same enquiry, and that enquiry has no interest in what either agreement is headed. Four factors carry it. Who sets the method, the order of the work and the hours it is done in. Whose laptop, software licences and client logins it is actually performed on. Whether the person stands to earn more by working well and to lose by working badly — a genuine chance of profit and risk of loss rather than payment for hours put in. And integration: whether the work sits inside the payer’s operation or alongside it, as one engagement in a business holding several. CRA guide RC4110 is where the Canada Revenue Agency sets those factors out. Being a guide, it hands you nothing to submit; what it hands you is the framework, and the work is running it honestly over the relationship above you and each one below you, then recording why you landed where you did while the facts are still fresh. We describe the factors and show you where your arrangements fall against them. What we will not do is tell you how to dress a relationship up so it yields the answer you would prefer, because a conclusion built that way collapses the first time anyone asks how the work is really done.
As an accountant for virtual assistants we act for executive and administrative support operators, inbox and calendar managers, bookkeeping and CRM assistants, social media and podcast production assistants, and small agencies that take work in under one name and pass the hours out to a panel of associates. You hear from us through the year instead of once in April, and the statements you get show your billings and your subcontract cost as two numbers rather than one.
Send us a quarter of invoices and the list of everyone you have paid, and we will tell you which side of the test is the live one on your file.
Our Official Partners
Accounting That Understands How a Virtual Assistant Actually Works
Almost nothing on this file is about equipment or stock. It is about standing in two relationships at once. The client above you is buying your time, and the more of your week one client absorbs the more the arrangement starts to read like employment whatever the invoice says. The assistants below you are being paid for their time, and every factor the Canada Revenue Agency would apply to you, you are applying to them. Underneath both sits a bookkeeping question this trade has mostly answered wrongly: whether your revenue is what you billed or what you kept. Gondaliya CPA works on exactly this shape of file for operators across Ontario.
Stay Compliant and Minimize Your Virtual Assistant Tax
Filing correctly and paying no more than the law asks turn out to be one exercise here rather than two. Most of what a virtual assistant overpays comes from reporting too little revenue and claiming too little cost at the same moment, and most of what she risks comes from a status question nobody ever wrote down. We hold the returns and the slips to their dates, claim what the Income Tax Act genuinely permits, and keep the reasoning behind each position in the file.
Accounting & Tax Experts for Virtual Assistants
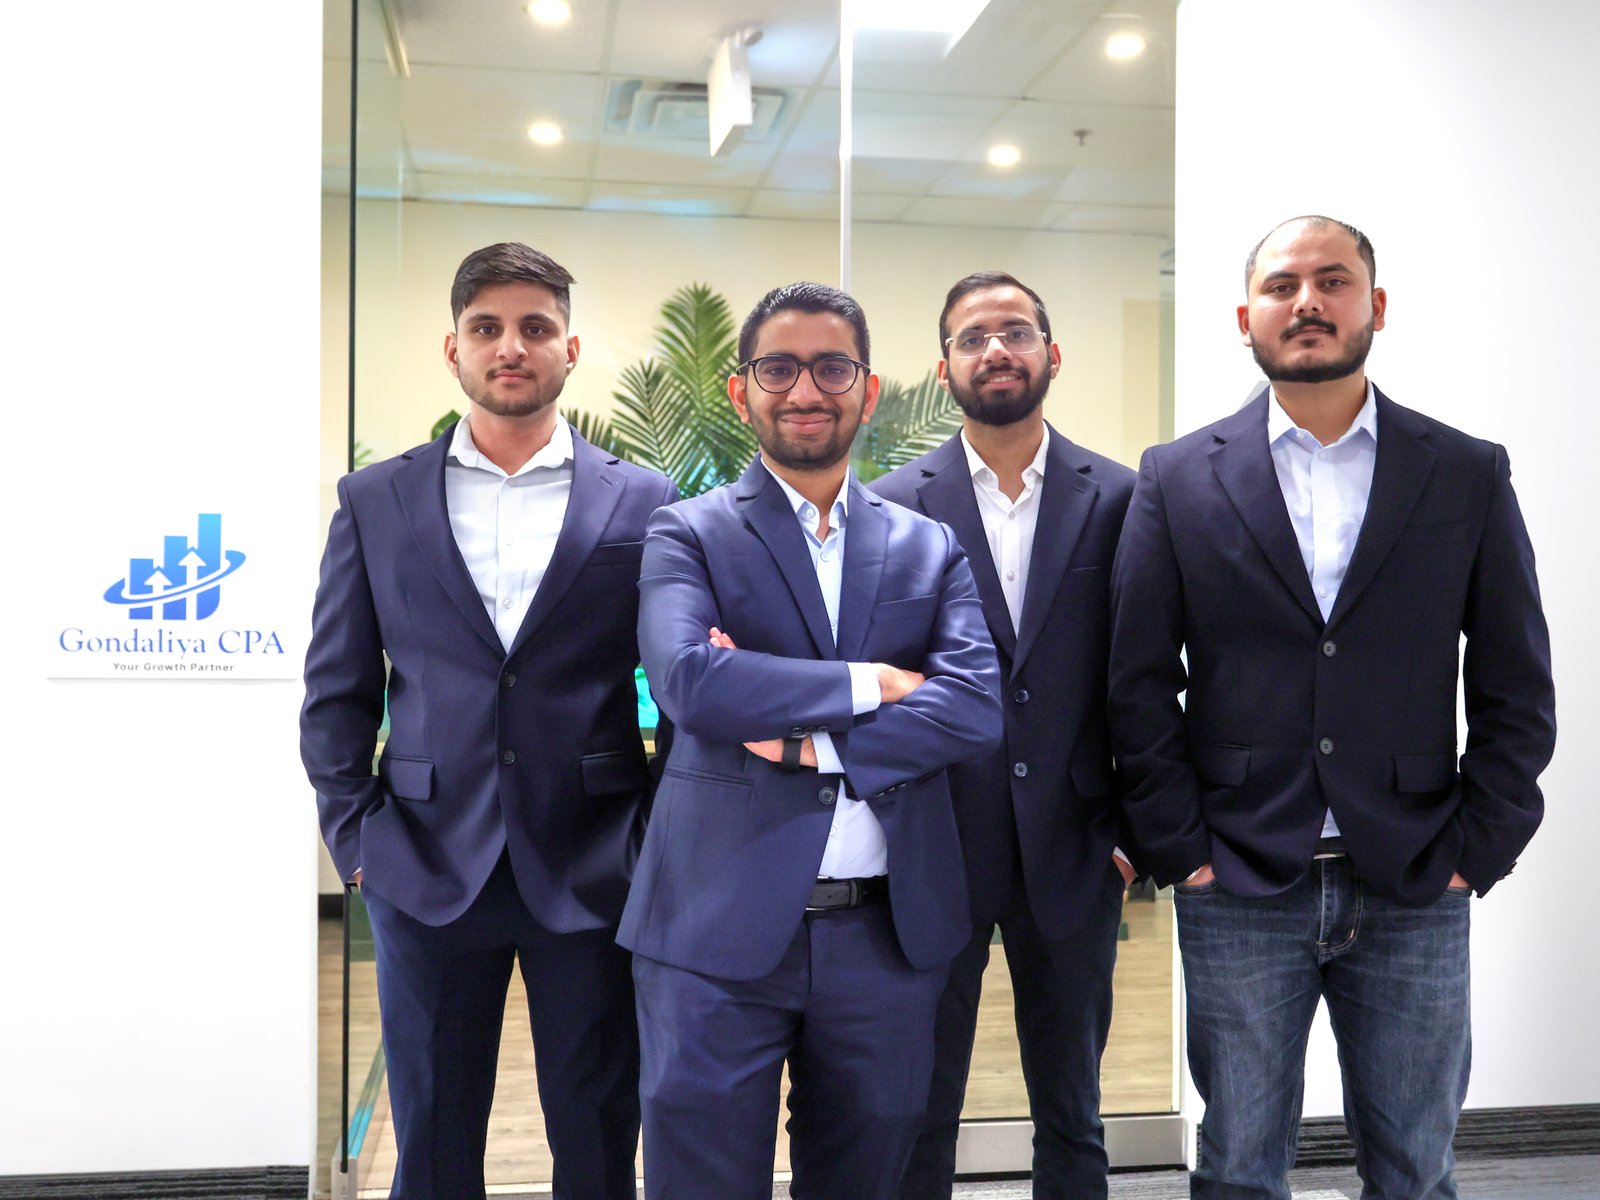
- AFFORDABLE + Registered CPA Firm
- Business and Corporate Tax Expert
- Small & Medium Business Expert
- Accounting, bookkeeping, and tax filing
- CPA (Chartered Professional Accountant)
- 1300+ 5-star Google reviews
- 30-Day Money-Back Guarantee
- 60-Day Fees Matching Policy
Why Choose Our Accounting Services for Virtual Assistants?
Tax Planning — Status at Both Ends
We run the four factors over the client paying you and over every assistant you pay, record each conclusion in writing, and keep active profit working against the limit in section 125.
Consulting — Billings, Not Margin
Your books are rebuilt so gross billings and subcontract cost are two separate figures, platform commissions reappear as the expenses they are, and your top line stops reading like a tenth of the business you run.
CRA Representation — Status, Slips and Records
When worker status, a missing slip or an unfiled year is questioned, we gather the agreements and the hours and answer it. Where a penalty traces to an error that was not yours we ask for it to be cancelled under RC4288.
Bookkeeping — Concentration, Cash and Exit
We show you where your hours are going before a client’s accountant does, plan the cash that funds associate payments while an invoice sits unpaid, and shape the eventual sale years ahead of it.
Google Reviews
Virtual Assistant Clients
Virtual Assistant Tax and Accounting Services in Ontario
Corporate Tax Filing (T2) for Virtual Assistants
Return preparation with gross billings and subcontract cost on separate lines, equipment placed in the right capital cost classes, and recapture settled whenever a machine leaves.
Bookkeeping & Accounting for Virtual Assistants
Engagement-level books that keep what a client paid apart from what an associate was paid, with platform statements and hours by client agreed every month.
Payroll Services for Virtual Assistants
Status tested on each person you pay, payroll and PD7A remittances where the conclusion calls for them, and T4 or T4A slips issued by the end of February.
GST/HST Filing for Virtual Assistants
AFFORDABLE returns with 13% applied to your services, your registration date measured over four consecutive calendar quarters, and the credits on your own costs recovered.
Tax Planning for Virtual Assistants
Planning on where your hours go, how you take money out of the business, the first $500,000 of active business income, and the structure you will eventually leave.
Corporate Catch-Up Filing for Virtual Assistants
Overdue years filed, billings and associate payments rebuilt from the bank record and the platform statements, and slips never issued prepared alongside the returns.
CRA Audit Resolution for Virtual Assistants
Worker status queried from above or below, a slip that never went in, a year that was never reported: we take the letter, gather the evidence and run it to a close.
CPA Financial Statements (Notice to Reader) for Virtual Assistants
Compilation statements showing what you billed, what you paid out of it and how much of the book one client is — the trio a credit officer wants.
Incorporation Services for Virtual Assistants
The company opened with books already able to hold billings and subcontract cost apart, and a register of everyone you pay running from the first entry.
Catch-Up Bookkeeping Services for Virtual Assistants
Years of client invoices, associate payments and platform statements rebuilt and agreed, so what each engagement actually earned stops being guesswork.
US Corporation & LLC Tax Filing for Virtual Assistants
Cross-border filing where American clients are part of your book or an owner is a United States citizen, with the Canadian return prepared beside it.
Voluntary Disclosure Program for Virtual Assistants
Unissued slips, HST collected and never sent on, or years filed on margin: brought forward voluntarily so the penalties can be relieved instead of assessed.
Accounting & Tax Services Tailored for Virtual Assistants
Practitioner depth for executive and administrative support operators, inbox and calendar managers, bookkeeping and CRM assistants, social media and podcast production assistants, and small agencies passing hours out to a panel of associates. One test run in two directions, and a top line reported at the size it genuinely is — nearly everything on this file follows from those two facts.
- Your return opens with the figure this trade most often gets wrong. Everything invoiced to clients is revenue, and what you paid your associates is a separate deduction standing beside it.
- Costs come in under section 9 and paragraph 18(1)(a) of the Income Tax Act because they were laid out to earn that income, while paragraph 18(1)(h) keeps personal and living expenses out.
- Capital cost allowance is a short schedule here and we keep it honest: a laptop and monitors in Class 50 at 55%, a desk and chair in Class 8 at 20%, purchased software in Class 12.
- Where a machine is sold, traded or taken into private use for more than the undepreciated capital cost of its class, subsection 13(1) brings the difference back into income.
- Section 125 holds roughly 12.2% combined in Ontario on the first $500,000 of active business income, and since the limit is measured on that income rather than on what you invoiced, large billings never touch it.
- The ledger is built so a client invoice and the associate invoice behind it never meet in one account. You see what each engagement earned before subcontract cost and after it.
- Every assistant you pay gets a payee record opened the first time money moves, with her agreement attached, so February becomes a printing job rather than an excavation through two years of transfers.
- Hours against each client are captured monthly, because hours are the evidence in a status review and because a client quietly absorbing three quarters of your week is something you want to meet in a report.
- Platform statements are reconciled to what clients were actually charged, so a commission withheld before payout lands in the accounts as the deductible cost it is instead of vanishing inside a net deposit.
- Costs with a genuinely private side, the phone plan, the internet line, a shared room, are split on a basis we can show, with the documents kept in Dext against the account each one reached.
- The moment an associate’s work is directed rather than merely requested, you may be operating a payroll without knowing it, so we review each arrangement you are the payer in.
- Where the conclusion is employment we run it properly: income tax, Canada Pension Plan contributions and Employment Insurance premiums taken at source, remitted against the PD7A on the frequency assigned to you.
- Arriving late is expensive on a graduated scale that climbs with the delay to a ceiling of 10% and is never a flat charge, which is reason enough to keep remittance dates in a calendar.
- February closes the slip year: the T4 set and the T4 Summary are in by the final day of that month and totalled back against each remittance the year actually produced, so any gap is found here.
- Where the conclusion is self-employment the slip is a T4A, and box 048 of it is the line meant for service fees paid to somebody in business on her own account; we prepare one for everybody you paid.
- What a virtual assistant sells is a taxable supply for Excise Tax Act purposes and bears 13% in Ontario, whoever the buyer happens to be: a law office, a coaching practice, a trades business, another assistant.
- Registration stops being optional once taxable supplies pass $30,000, and the measure is four consecutive calendar quarters rather than a fiscal year, which is why the crossing so often happens mid-quarter.
- We put the rolling four-quarter total in front of you monthly, because the obligation runs from the crossing itself and tax you never charged after that point remains tax you owe.
- The credit side is worth collecting: tax on software subscriptions, a laptop, a monitor, the business share of your phone and internet, and the invoices your associates send you all comes back.
- An associate who is registered charges you 13% which you recover, and one who is not charges you nothing, so we keep those populations apart and every credit supported by an invoice that bears tax.
- We begin with where your hours go, because concentration drives both the status question above you and the price anybody would eventually be willing to pay for what you have built.
- We fix the wage-and-dividend split around the money you genuinely need each month, leaving enough T4 salary behind to keep registered room accruing and sheltering retained profit inside the section 125 ceiling.
- On incorporation, section 85 of the Income Tax Act with Form T2057 carries your client contracts, goodwill and equipment across at elected amounts instead of their being treated as sold at fair market value.
- Qualifying for the $1.25 million exemption in section 110.6 turns on where your balance sheet has been, not where you would like it to be, so surplus cash and idle assets come out years early.
- Equipment buying is lined up against your fiscal year end, since the 55% rate on a Class 50 laptop and the 20% rate on Class 8 furniture reward quite different purchase timing.
- Where no bookkeeping exists across the unfiled years we rebuild billings from deposits, invoices and platform statements, and rebuild the subcontract side from whatever left the bank account.
- Lateness is charged twice over, once as a filing penalty and again as arrears interest, and both widen for as long as a year sits unfiled, so the oldest open year is the one prepared first.
- T4A slips never issued for associates paid in those years are prepared and filed alongside the returns, because a per-slip penalty stacked on top of a late return is an avoidable second bill.
- Years reported on margin instead of on gross billings are restated on both sides at once, which often leaves the tax much as it was but corrects a revenue figure a lender would misread entirely.
- We rebuild the undepreciated capital cost pools across the missing years, because a laptop written off outright in one year and never entered on a schedule understates every year after it.
- When the Canada Revenue Agency asks whether a client relationship was really employment, we answer from the engagement terms, the hours worked, whose equipment was used and who set the timetable.
- Where the question runs the other way and concerns the associates you paid, we produce their agreements, their invoices and whatever shows each was free to work for others, and answer only what was asked.
- We do not coach a relationship into a better shape after the event. We set the facts out as they were and say plainly where they are weak, because a dressed-up position is the one that fails.
- Where a reassessment is wrong we prepare the objection, and where penalties and interest accumulated from an error that was never yours we ask to have them cancelled under RC4288.
- The Minister may, under subsection 152(7) of the Income Tax Act, assess an amount otherwise than in accordance with what was filed. We state it exactly as the provision does and build the file accordingly.
- Your statements are compiled under CSRS 4200, which obliges us to attach a page saying in plain terms what was and was not done to the figures, and a credit officer reads that page before any other.
- The statement of operations shows gross billings and subcontract cost as two lines, because a reader handed only the net margin cannot tell a $60,000 practice from a $400,000 one.
- Revenue by client is disclosed where a reader can find it, since concentration is the first thing a lender asks a one-person service business and the last thing it wants to discover alone.
- The compiled figures are tied back to the return as filed and to the GST/HST periods covering the same months, so nothing inside the package contradicts what the Canada Revenue Agency holds.
- The engagement is quoted as a flat fee against a date you can plan around, which matters when a broker has given you a fortnight to produce two years of figures.
- Profit retained by an Ontario corporation is charged at about 12.2% combined within the section 125 ceiling of $500,000, where identical earnings taken in your own name climb a scale ending at 53.53%.
- That gap only pays on money left inside the company, so the question is whether the practice earns materially more than you draw to live on, and we will say wait a year where it does not.
- Section 85 of the Income Tax Act on Form T2057 moves client contracts, goodwill and equipment in at elected amounts, and we set the opening Class 50, Class 8 and Class 12 schedules from the invoices.
- The business number is opened with its GST/HST account and, where anyone you pay is an employee, a payroll account, and WSIB coverage is registered before the first hire rather than after.
- Annual Ontario payroll below $1,000,000 sits inside the employer health tax exemption, and we follow the running figure so you hear it from us in the year before you leave it, not from an assessment.
- Months of unposted client invoices and associate payments are rebuilt and matched to one another, so what every engagement earned before and after subcontract cost becomes a figure you can price from.
- Payments that went out by transfer from a personal account are pulled back in, named to the associate who received them and totalled by payee, so the slips nobody issued can finally be prepared.
- Platform deposits are reopened against the statements behind them, restoring the commission withheld before payout as an expense and the client charge as the revenue it was all along.
- The receivable ledger is reconciled to what clients actually paid, clearing the stale balances and duplicated postings that hide whether your largest account still owes you anything at all.
- Each payee is looked at again across the whole year, and anybody who invoiced you while taking direction from you day to day is flagged, so the rebuilt record states the position honestly from the start.
- Where American clients make up part of your book we test whether anything is in fact owed south of the line rather than assuming either answer, and prepare the Canadian return alongside it.
- Where a United States company paying you as a contractor sends forms and asks for certifications, we tell you which requests reflect a real obligation on you and which are somebody’s standard template.
- The United States and Canada characterise a Canadian-owned limited liability company along quite different lines, and that asymmetry gets modelled on paper before any such entity is put to work.
- Foreign tax actually paid is credited rather than quietly written off, so the same fee income is not taxed on both sides, and the supporting documents are kept with the year they belong to.
- Where you or a shareholder holds United States citizenship, the two filing systems have to be run on one timetable, and we would rather raise that in your first year than your fourth.
- Three conditions govern an RC199 submission: it must be unprompted, it must cover everything, and the information is generally a year or more overdue. We say plainly whether your facts clear all three.
- The commonest disclosure on this file is slips never issued to associates paid across several years, which is a reporting failure rather than a tax one and exactly what the program exists to relieve.
- Next commonest is HST charged to clients and never remitted, or never charged at all because the $30,000 threshold was passed in a quarter nobody was adding up at the time.
- Years reported on margin rather than on gross billings go in as well, since restating revenue across several periods is a correction the Canada Revenue Agency would otherwise make with penalties.
- Coming forward before the Canada Revenue Agency opens the subject is what makes relief available at all, so we assemble the records showing the disclosure is complete before anything is filed.
Virtual Assistant Classification & Subcontractor Check
Six questions on where your hours go, whether each client relationship has been reasoned out and written down, the assistants you pay and the slips they are owed, how your billings reach the books, and whether incorporating earns its keep. No fee shown.
1. Does one client take more than half of the hours you work in a month?
2. Have you written down why each client engagement is a contract and not employment?
3. Do you pay other virtual assistants to carry part of your workload?
4. Has every assistant you pay been tested against the same four factors?
5. Do your books show gross billings and subcontract cost as two separate figures?
6. Is your virtual assistant business incorporated?
Free CPA Consultation for Virtual Assistants
Case Studies: Virtual Assistant Accounting & Tax
Ajax Virtual Assistant — The Client Who Supplied the Laptop
The problem: An Ajax executive assistant had supported one marketing agency for three years. The agency set the hours she was expected to be online, issued her a laptop and an address on its own domain, ran her through its internal task board, and took every hour she worked bar two small accounts kept on from earlier. She invoiced monthly, deducted a share of her internet and her software, and had never thought of the arrangement as anything but contracting. The agency’s new accountant did think about it, and the question arrived as a request to incorporate within thirty days or stop invoicing.
What we did: We set the four factors in CRA guide RC4110 out against the facts as they actually stood, in writing, including the ones that pointed the wrong way, and quantified what a finding of employment would mean for each open year on both sides of the arrangement. We did not advise her how to recast the relationship. We told her what it looked like, what each of the two roads cost, and she negotiated from there.
The result:
- Exposure on four open years quantified before anything was filed
- Factors documented from how the work ran, not from the contract
- New client work now pursued deliberately rather than by accident
Orillia Virtual Assistant Agency — Margin Reported as Revenue
The problem: An Orillia agency took work in under one name and passed roughly two thirds of the hours to a panel of six associates. For two years the books recorded only the difference between what clients paid and what associates were paid, so billings of about $430,000 were reported as $146,000 and the associates’ invoices appeared nowhere at all. The GST/HST returns had been filed on the same net figure, so reported sales never agreed with the tax that had been charged, and a lender had already declined a modest operating line on a top line that read like a side business.
What we did: We rebuilt both sides from the bank record and the platform statements, restated gross billings and the subcontract cost for each of the two years, amended the GST/HST periods so reported sales agreed with the tax actually charged, and prepared the T4A slips that had never been issued to any of the six associates.
The result:
- $430,000 of billings and the matching costs restored to the record
- Reported sales agreed to HST charged across eight periods
- Operating line approved on the restated statements
Sarnia Virtual Assistant — Two Years of Associates, No Slips
The problem: A Sarnia operator had paid four associates across two years, between $9,000 and $31,000 each, on the understanding that one self-employed person paying another has nothing to report. No written agreements existed and no slips had been filed. Two of the four worked for nobody else, to hours she set, on accounts and logins she owned. The payments had all been deducted, which was right, but the reporting side had simply never happened and the status of half the panel was genuinely open rather than merely undocumented.
What we did: We applied the four factors to each of the four relationships separately and wrote the conclusions down. Two were plainly in business on their own account, so the outstanding T4A slips were prepared with box 048 completed and filed for both years. For the other two the factors fell the other way, a payroll account was opened, and the open years went to the Canada Revenue Agency through an RC199 application before anybody came asking.
The result:
- Outstanding slips filed for two years of associate payments
- Penalties cancelled on an accepted voluntary disclosure
- All four relationships now documented and reported correctly
Five stages, each of them dated, so nothing about this engagement ever has to be chased out of us.
Documents We Ask For
Prior returns and notices of assessment, every client agreement and every associate agreement, two years of invoices, the platform statements behind each payout, whatever record of hours exists, bank statements, and a list of everybody you have paid.
First Month: Cleanup and Setup
Books set up with billings and subcontract cost on separate lines, a payee record opened for every associate, the four factors run over each relationship in both directions and written down, and the Class 50, Class 8 and Class 12 pools rebuilt.
The Monthly Cycle
Billings and associate costs posted at full size, platform commissions restored as expenses, hours by client reported, the GST/HST position tied back to the ledger, and any new associate reviewed before her first payment leaves.
Planning Each Quarter
Where your hours are going, the status conclusion on each live engagement, how you are taking money out against what you draw, the section 125 limit, equipment timing, and the receivable sitting on your largest account.
Closing the Year
Trial balance, statements with gross billings and subcontract cost apart, slips reconciled to what was remitted, reserves settled where the Act permits them, and the return filed with its schedules agreeing to the pools.
Get Your Virtual Assistant Taxes Done Right Today
Affordable Pricing for Virtual Assistants
We believe in clear, upfront pricing so you know exactly what to expect. All fees include HST.
- Tax Preparation (Corporation) — From $400
- Tax Return Filing (Corporation) — From $400
- Tax Compliance Audit — FREE CRA audit support for our clients
- Tax Strategy — FREE for our clients
- Accounting Base Plan — From $100 per month
- Bookkeeping Management — Free for our Accounting clients
- Financial Reporting — Free for our Accounting clients
- Business Formation — Flat $35
- Incorporation Process — Flat $35
- Entity Setup Assistance — Flat $35
- Full-Service Payroll — From $125 per month
Payment is by Interac e-Transfer to info@gondaliyacpa.ca only. Security question: Not Applicable, as auto-deposit is enabled.
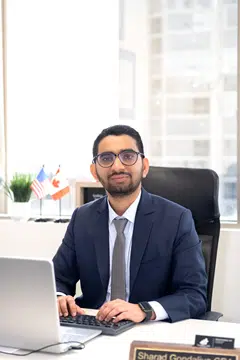
Meet Your Lead Virtual Assistant Accountant
The same two people hold your file from one year to the next. The principal and the accounting specialist who test your arrangements and sign your return are the ones you actually speak to.
What Our Clients Say
1300+ five-star reviews from service, consulting and one-person practice owners across Ontario and the rest of Canada.
Serving Virtual Assistants Across Ontario
Our CPA team acts for virtual assistants and small assistant agencies throughout Ontario. We know how the status question reads from both ends of the chain, why your revenue is what a client was charged rather than what you were left holding, and what the Canada Revenue Agency asks to see once it begins asking.
Toronto (ON)
55 Queen St E Ste 1205, Toronto, ON M5C 1R6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Mississauga (ON)
2100 Camilla Rd #716, Mississauga, ON L5A 2J8
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Brampton (ON)
4 Starhill Crescent, Brampton, ON L6R 2P9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Scarborough (ON)
24 Clementine Square, Scarborough, ON M1G 2V7, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Vaughan (ON)
19 Cabinet Crescent, Woodbridge, ON L4L 6H9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Oshawa (ON)
210 Durham St, Oshawa, ON L1J 5R3, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Ottawa (ON)
2090 Neepawa Ave a314, Ottawa, ON K2A 3L6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Etobicoke (ON)
60 Stevenson Rd #1601, Etobicoke, ON M9V 2B4, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Hamilton (ON)
70 Starling Dr, Hamilton, ON L9A 0C5, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Guelph (ON)
1155 Gordon St, Guelph, ON N1L 1S8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Windsor (ON)
4387 Guppy Ct, Windsor, ON N9G 2N8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
North York (ON)
150 Graydon Hall Dr #912, North York, ON M3A 3B2, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Virtual Assistant Accounting & Tax FAQs
Related Industries We Serve
Administrative Service Businesses
- Rate set by the client’s province
- Prepaid hours and out-of-province payroll
- T2 preparation with GIFI schedules
Home-Based Businesses
- Deductions for a business run from a dwelling
- HST registration and filing
- Bookkeeping and personal tax
IT Staffing Companies
- Placed contractors and non-resident payments
- Worker status and matching slips
- Corporate tax filing and planning
Online Course Creators
- Platform payouts reported at gross
- Prepaid enrolments and cohort timing
- Compiled statements and incorporation
Virtual Assistant Accounting & Tax Done Right.
The four factors in CRA guide RC4110 applied in both directions, to the client who pays you and to every assistant you pay, with the conclusion written down on each. Gross billings and subcontract cost reported at full size instead of netted into a margin. Platform commissions restored as the expense they are. T4 or T4A issued on the conclusion the facts support, with box 048 completed where it belongs, by the last day of February. Expenses allowed under section 9 and paragraph 18(1)(a) of the Income Tax Act with paragraph 18(1)(h) respected, a laptop and monitors in Class 50 at 55%, a desk and chair in Class 8 at 20%, purchased software in Class 12, and recapture under subsection 13(1) whenever equipment leaves. 13% charged under the Excise Tax Act and the tax on your own costs recovered, paragraph 20(1)(l) kept clear of paragraph 20(1)(p), and the six years of agreements and hours section 230 asks for. AFFORDABLE flat fees, no hourly billing. Licensed CPA Ontario. 1300+ five-star reviews. 30-Day Money-Back Guarantee.