



How CRA Selects Businesses for Tax Audits in Canada: Key Red Flags Explained
CRA Audit Triggers Canada: Red Flags, Risk Factors and Selection Explained by Gondaliya CPA
CRA audit triggers Canada often involve inconsistencies in tax returns, unusual expense claims, or missing information, making these common tax audit risk factors for taxpayers. Gondaliya CPA explains how understanding these audit reasons can help reduce the chances of a tax audit and prepare for any CRA review effectively.
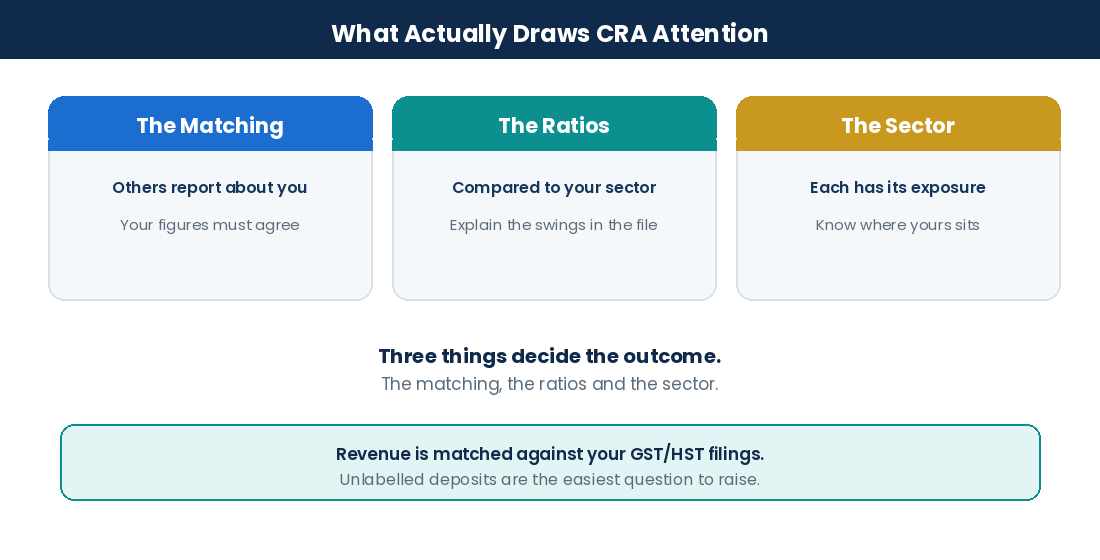
The useful question is not what looks suspicious. It is what the CRA can already see. Most CRA audits begin with a mismatch between your return and information filed by somebody else.
Quick Summary
Selection works on data, not instinct. Third-party reporting is matched against your return, risk models compare you to your sector, and a smaller number of files are picked at random. The mismatches you can control are the ones worth fixing.
Reading time: 51 minutes.
Table of Contents
- How Selection Actually Works
- What the CRA Already Knows About You
- Red Flags in Your Own Numbers
- Sales Tax and Payroll Are Separate Programmes
- Where Your Sector Draws Attention
- Lowering Your Risk and Working With Us
- Frequently Asked Questions
- The Risk Reduction Checklist
- Businesses We Serve
- Professional Guidance and Quick Reference
The Numbers That Matter
This article covers Canada, with Ontario and Toronto context, and reflects rules current to 2026. It is written for incorporated Canadian small businesses. Figures marked illustrative are examples, not quotes, and any masked engagement notes end with “Figures changed for privacy.” This is educational information only and not tax or legal advice. The CRA does not publish its selection algorithms, and any article claiming to reproduce a scoring model is describing something invented rather than something disclosed. What follows describes the mechanisms that are publicly known and observable in practice.
How Selection Actually Works
How Selection Actually Works
The Mechanism
Four Routes to Selection
| Route | What Drives It |
|---|---|
| Information matching | Your return disagrees with data filed by someone else |
| Risk assessment | Your figures sit outside the pattern for your sector and size |
| Project or sector work | The CRA is examining an industry or an issue across many taxpayers |
| Random selection | Genuinely random, used to test compliance generally |
Two things follow. First, the largest single category is not judgement at all, it is arithmetic: two numbers that should agree, and do not. Second, random selection means a clean, well-run business can still be picked, and preparation is worth having regardless.
A Word on Invented Scoring Models
You will find articles presenting a table of audit risk factors with percentage weights, producing a total score. Those numbers are made up.
The CRA does use risk assessment, and it does compare taxpayers against sector patterns, but it does not publish weights and no outside party knows them. A confident-looking table of percentages tells you the author invented a methodology, which is worth knowing when deciding what else to believe in the article.
What is genuinely known is the direction: more inconsistencies, and a larger gap from what is typical for your sector and size, means more attention.
Why the CRA Audits At All
- To verify that reported amounts are supported
- To maintain fairness between compliant and non-compliant businesses
- To address sectors where non-compliance has been identified
- To educate, since many audits close with adjustments and guidance rather than penalties
The last point is worth holding onto. Most small business audits are not investigations of dishonesty. They are verification exercises, and treating one as an accusation tends to produce a worse response than treating it as a request for evidence.
What Changes the Odds
You cannot control random selection or a sector project. You can control whether your numbers agree with the numbers already held about you, and that is where the effort belongs.
Owners assume someone read their return and formed a suspicion. Usually a system compared two figures that disagreed. That is a fixable problem. Figures changed for privacy.
Risk Warning: Articles presenting weighted audit risk scores with exact percentages are describing an invented model. Please treat the rest of that guidance carefully.
What the CRA Already Knows About You
What the CRA Already Knows About You
The Data
Before anyone looks at your return, information about your business has already arrived from other parties. Understanding what is in that file is the single most useful thing in managing audit risk.
The Reporting That Reaches Them
| Source | What It Reports |
|---|---|
| T4 and T4A slips | Employment income and fees you paid for services |
| T5018 contract payment reporting | Payments to subcontractors in construction |
| T5 and T3 slips | Investment and trust income |
| T5013 partnership returns | Allocations of partnership income |
| Land registry and property transfer data | Real property dispositions |
| Customs import records | Goods brought into Canada and duty and tax paid |
| Foreign account information exchange | Accounts held abroad by Canadian residents |
| Requirements issued to third parties | Records held by banks and other businesses |
Each of these can be matched against what you filed. A T4A issued to you that does not appear in your revenue, or a subcontractor reporting payments you never recorded, produces a difference that a machine can find without anyone forming an opinion.
The Reporting You Do About Others
This runs both directions, and it is where small businesses create their own exposure.
- T4 slips for employees, due the last day of February
- T4A slips for fees paid for services, same deadline
- T5018 slips where you are in construction, due six months after the reporting period you chose
- T4A-NR where a non-resident performed services in Canada
Please note the T5018 deadline is six months after the end of your chosen reporting period, not the end of February. The February deadline belongs to T4 and T4A slips, and guidance conflating them is common.
Where you fail to issue slips you should have, two things happen. You face a penalty by slip count, and the recipient’s return no longer matches anything, which can pull both of you into a review.
The Reconciliations That Should Agree
Some numbers exist in more than one place and are expected to tie. Where they do not, that is what surfaces.
| This | Should Agree To |
|---|---|
| Revenue on the corporate return | Sales reported across your GST/HST returns |
| Wage expense on the return | Total employment income on slips filed |
| Payroll remittances made | Deductions shown on the payroll register |
| Subcontractor expense | Amounts reported on contract payment slips |
| Import tax claimed as a credit | Tax shown on customs accounting documents |
| Deposits into business accounts | Recorded revenue, allowing for non-revenue items |
Every one of these is a check you can run yourself before filing. A difference you find and explain in your working papers is a different situation from one the CRA finds and asks about.
The deposit line depends on the account being reconciled first, which is why monthly bank reconciliation sits underneath everything else here. A ledger that has never been agreed to the bank cannot support any of the other comparisons.
The revenue against sales tax line is the one that catches the most businesses, because the two returns are usually prepared at different times, sometimes by different people, and nobody compares them.
The reconciliation between revenue and sales tax filings is the most common gap we find, and the easiest to close. Nobody had ever put the two figures side by side. Figures changed for privacy.
Key Stat: T5018 contract payment slips are due six months after your chosen reporting period ends. The end of February is the T4 and T4A deadline.
Red Flags in Your Own Numbers
Red Flags in Your Own Numbers
The Signals
Separate from matching, your return is compared against what is typical for a business of your type and size. None of the following is wrong in itself. Each simply invites a question, and the question is easier when you have the answer ready.
Margin and Ratio Signals
- Gross margin well below others in your sector
- Expenses high relative to revenue with no visible reason
- A sharp swing year over year in either direction
- Losses reported repeatedly while the business continues operating
- Revenue flat while purchases rise, or the reverse
- Owner drawings that do not correspond to reported profitability
The recurring loss item deserves care. Genuine losses happen, particularly in early years or a bad cycle. What attracts attention is a pattern of losses with no explanation, in a business that keeps trading and funding an owner’s lifestyle.
The answer is not to avoid reporting a loss. It is to be able to explain it, and to have the explanation in the file rather than only in your head.
Expense Signals
| Claim | Why It Draws Attention |
|---|---|
| Vehicle costs with no log | The log is the substantiation; without it the claim is unsupported |
| Meals and entertainment claimed in full | A 50% limitation generally applies |
| Travel with no business purpose recorded | The purpose is what makes it deductible |
| Home office claimed by a corporation | A company is not an individual; the arrangement must be structured |
| Large round-number amounts | Real costs rarely arrive in round figures |
| Consulting or management fees to related parties | Reasonableness and documentation are both tested |
| Personal-looking costs in business accounts | Clothing, groceries, home items and similar |
Round numbers are underrated as a signal. A ledger with several entries at exactly $5,000 and $10,000 reads as estimated rather than recorded, and an auditor will start there.
Cash and Deposits
Cash-intensive businesses attract more attention, not because cash is improper but because it is harder to verify.
- Deposits exceeding recorded revenue, with no explanation for the difference
- Revenue that appears too consistent to be real trading
- Purchases implying more sales than were reported
- Personal accounts used for business receipts
- Large unexplained transfers between accounts
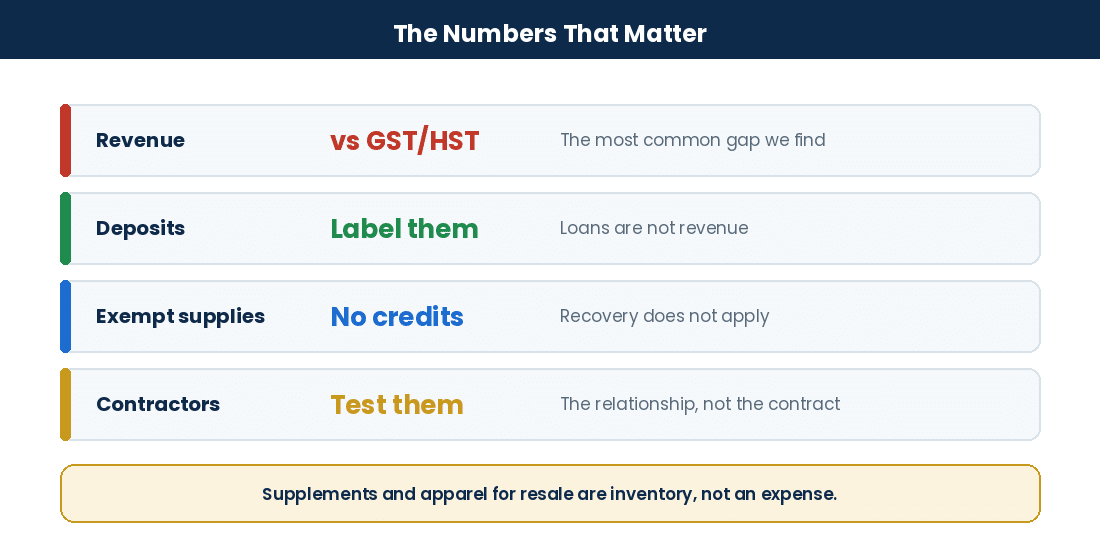
Not every deposit is revenue. Loans, capital contributions, transfers between your own accounts and refunds all appear as deposits. Where they are not identified in the records, they look like unreported income until you prove otherwise.
Label them at the time. Reconstructing the character of a deposit three years later is considerably harder than describing it the week it arrived.
The Shareholder Loan
In owner-managed corporations this account collects everything nobody knew how to code, and it is where an audit tends to go next.
Amounts taken and not repaid within the period the Act allows can be included in your personal income. A growing balance with no supporting entries is both an audit signal and a real tax exposure.
Filing Behaviour
- Repeated late filing across income tax, sales tax or payroll
- Frequent amendments to returns already filed
- Large refund claims, particularly on sales tax
- Balances left outstanding for extended periods
- A return filed with obvious internal inconsistencies
Filing behaviour is visible without anyone examining your books at all, which makes it the cheapest signal for the CRA to act on and the cheapest for you to fix.
Deposits that were loans or transfers, never labelled as such, is the most common way a clean business ends up defending unreported income it never had. Figures changed for privacy.
Key Stat: Not every deposit is revenue. Please identify loans, transfers and refunds when they arrive, not three years later.
Sales Tax and Payroll Are Separate Programmes
Sales Tax and Payroll Are Separate Programmes
Two Other Doors
Businesses think of “an audit” as one thing. In practice a GST/HST examination and a payroll examination are separate exercises with their own selection criteria, and either can arrive without an income tax audit.
GST/HST Selection
- A refund claim large relative to your trading history
- Sales reported for sales tax that do not agree with revenue on the corporate return
- Input tax credits high relative to the tax you collected
- Credits claimed on imports without the customs accounting document
- Zero-rated or exempt sales claimed with no supporting evidence
- Registration that came late relative to when the threshold was crossed
- Returns filed late or in an inconsistent pattern
Refund claims are the practical trigger. A business in a genuine refund position, such as an exporter or one in a build phase, should expect the claim to be reviewed at some point and should keep the supporting documentation assembled rather than scattered.
Documentation is the whole defence on a credit claim. Each credit needs an invoice showing the supplier’s registration number and the tax charged, and import credits need the customs accounting document rather than a broker’s summary. Our guide to maximising input tax credits during GST/HST filing covers what qualifies, and our overview of input tax credits in Canada sets out the recovery rules.
The Exempt Supply Problem
Whether your supplies are taxable or exempt changes everything, and it is frequently misunderstood.
| Position | Charge Tax? | Recover Credits? |
|---|---|---|
| Taxable supply | Yes | Yes |
| Zero-rated supply | At nil | Yes |
| Exempt supply | No | No |
The exempt row is where the errors sit. A business making exempt supplies cannot recover tax on its costs, and claiming credits anyway is a straightforward assessment.
Where a business makes both taxable and exempt supplies, credits have to be apportioned. That applies to dental practices with cosmetic work alongside exempt care, and to other mixed operations, and it is an area where a reasonable apportionment method should be documented rather than assumed.
Payroll Selection
| Issue | What Is Examined |
|---|---|
| Worker classification | Whether contractors are properly employees |
| Remittance timing | Whether deductions were sent on schedule for your remitter type |
| Slip reconciliation | Whether slips agree to the payroll register and the return |
| Taxable benefits | Vehicles, allowances, insurance and similar |
| Owner remuneration | Whether amounts taken were salary, dividend or a loan |
| Cash wages | Whether wages were paid outside the payroll system |
Classification is the most consequential. A worker treated as a contractor who is in substance an employee means the CRA can assess the deductions that should have been withheld, plus penalties and interest, and directors are personally exposed on unremitted source deductions.
The test looks at control over how work is done, who provides the tools, whether the worker carries a chance of profit and risk of loss, and how integrated they are in the business. A written contract stating “independent contractor” does not settle it if the working relationship says otherwise.
The Trust Fund Point
Source deductions withheld from employees are not the company’s money. They are held in trust, and that is why the consequences of not remitting them are more severe than for ordinary tax debt, and why directors carry personal liability.
Of everything in this article, unremitted source deductions is the exposure that most often follows an owner personally out of a failed business.
A payroll examination arrives on its own and surprises owners who thought their income tax filings were the whole picture. Classification is usually the reason. Figures changed for privacy.
Risk Warning: A contract saying “independent contractor” does not settle classification. Please test the working relationship, since directors are personally exposed on source deductions.
Where Your Sector Draws Attention
Where Your Sector Draws Attention
The Sectors
Risk assessment is sector-aware, and each industry has a characteristic exposure. Knowing yours tells you where to concentrate.
Medical and Dental Practices
Most medical services are exempt for sales tax purposes, which means credits on costs generally cannot be recovered. Dental practices are the more complicated case, because cosmetic procedures can be taxable while care is exempt, creating a mixed supply position requiring apportionment.
On the income tax side, the recurring issues are personal costs run through the practice, income from multiple sources such as hospital work, teaching and consulting recorded inconsistently, and incorporation structures where the professional corporation’s rules were not followed.
Construction and Skilled Trades
Contract payment reporting makes this sector unusually visible. Where you pay subcontractors, those payments are reported, and where a subcontractor’s own return does not reflect them, the CRA can work backwards from your slip.
- File contract payment slips, six months after your chosen period end
- Confirm subcontractors are registered where the amounts warrant it
- Test whether long-term subcontractors are in substance employees
- Support holdbacks and progress billing with the contract terms
- Keep timesheets tied to jobs and contracts
Cash wages are the serious exposure here, and they carry both payroll and income tax consequences alongside the personal liability that attaches to unremitted deductions.
Real Estate and Property Development
Property transactions are visible through registry data, and this sector has been an area of sustained CRA focus.
| Issue | What Is Tested |
|---|---|
| Capital gain against business income | Intention at acquisition and the pattern of activity |
| Housing rebates claimed | Whether the conditions, including occupancy, were met |
| New residential construction | Self-supply rules where a property is rented rather than sold |
| Credits on construction costs | Whether the intended use supports the claim |
| Assignment sales | Reporting and the sales tax treatment |
| Principal residence | Dispositions must be reported even where relieved |
The first row is the one that costs the most. Treating a gain as capital when the pattern of activity suggests a trading business can double the amount brought into income.
Restaurants and Cash Businesses
Purchases imply sales. A restaurant buying a given volume of food and drink is expected to have sold a corresponding volume, and the relationship between the two is testable without any third party involved.
Alongside that: tips and how they are handled, staff paid in cash, wastage written off without records, and meals claimed without the 50% limitation applied.
Transport and Logistics
Vehicle costs are the whole file. Without logs showing distance and purpose, a claim is unsupported regardless of how genuine the expense was.
Note also that a corporation does not prorate vehicle costs the way a sole proprietor does. The company claims the cost and reports a benefit where there is personal use, and applying the wrong method is common.
E-Commerce and Digital
Payment processors and marketplaces report independently, so gross sales are visible even where a business records only net payouts.
- Record sales at gross with processing fees as an expense
- Reconcile processor and marketplace reports to recorded revenue monthly
- Establish where customers are for sales tax purposes
- Track inventory properly, since cost of goods sold depends on it
- Support any home office arrangement rather than assuming one
Childcare and Similar Services
Childcare services are largely exempt for sales tax purposes, which means the usual issue is not failing to charge tax but claiming credits that are not available on exempt activity.
Payroll is the larger exposure in this sector: staff hours, casual and relief workers, and whether everyone paid is properly on the payroll system.
Sector matters less than people expect. The mechanism is the same everywhere: something reported elsewhere does not match what you filed. Figures changed for privacy.
Pro Tip: Please check whether your supplies are exempt before claiming input tax credits. Exempt activity does not carry recovery.
Lowering Your Risk and Working With Gondaliya CPA
Lowering Your Risk and Working With Us
The Prevention
Run the Checks Yourself
Everything the CRA matches, you can match first. Do it before filing rather than after.
| When | What to Check |
|---|---|
| Monthly | Bank and card accounts reconciled; unidentified deposits labelled |
| Quarterly | Revenue against sales tax filings; payroll register against remittances |
| Mid-year | Margin against prior periods; explanations recorded for any swing |
| Before slips | Wage expense against slips to be filed; contractors reviewed for classification |
| Before the return | All reconciliations complete; shareholder loan reviewed and supported |
| Annually | Related-party agreements refreshed; asset register updated |
A difference you find and document is not a red flag. It is an explained variance sitting in your working papers with the evidence attached.
Fixing a Backlog
Late filings and disorganised records raise risk on their own, and catching up lowers it. The order matters.
- Assemble the source documents for every open period
- Reconcile the bank accounts before preparing anything
- Rebuild the ledger so the periods actually tie
- Prepare and file the returns, oldest first
- Deal with the balance owing and any relief available
Filing quickly with unreconciled numbers to appear compliant is a poor trade. It produces returns that will not withstand a review and often creates a second problem.
Where past filings were wrong, the Voluntary Disclosures Program may reduce penalties, provided you come forward before the CRA raises the issue. Once contact has been made on the matter, that option generally closes.
Who Prepares It Matters
| Approach | Where Risk Sits |
|---|---|
| Doing it yourself | Technical errors and missed reconciliations, made in good faith |
| An unregulated preparer | Variable standards, and no professional body behind the work |
| A licensed CPA firm | Reconciliations run as standard, with representation if a review follows |
The point is not that self-preparation is reckless. It is that the reconciliations described above are exactly what tends to get skipped when the person preparing the return is also running the business.
The errors that follow are consistent enough to list, and we have set them out in our review of the bookkeeping mistakes that raise CRA audit risk. Almost none of them involve any intent to underreport. They are omissions of process rather than judgement, which is what makes them straightforward to fix once someone is looking.
What We Do
We support incorporated businesses on a flat annual fee covering bookkeeping with monthly reconciliation, the cross-checks between revenue, sales tax, payroll and slips, expense documentation review, shareholder loan monitoring, worker classification review, sector-specific exposure, financial statements and the corporate return.
Where a letter has already arrived, we act as your representative and manage the file through to conclusion. Our step-by-step guide to the CRA audit process sets out what that involves.
Pricing is quoted before any work begins, including HST, with a one-business-day response.
What It Depends On
- The condition of the current records
- How many periods are outstanding, if any
- Transaction volume and number of accounts
- Whether payroll and sales tax are involved
- Sector complexity, including mixed taxable and exempt supplies
Getting Started
Bring your last filed corporate return, your most recent sales tax return, and a recent bank reconciliation. Those three let us run the main cross-checks and tell you where your file actually stands.
Contact Gondaliya CPA at info@gondaliyacpa.ca, call 647-212-9559, or send us a message.
Three documents and twenty minutes tells us how a file looks to the CRA. Usually the answer is fine, and the owner had been worrying about the wrong thing. Figures changed for privacy.
Pro Tip: Please run the CRA’s own cross-checks before filing. An explained variance in your working papers is not a red flag.
FAQs on CRA Audit Triggers and Selection
Frequently Asked Questions
FAQ
How does the CRA actually pick businesses to audit?+
Through four routes: information matching where your return disagrees with data filed by others, risk assessment against sector patterns, sector or issue projects, and genuinely random selection.
Is there a scoring model with percentage weights?+
No published one. The CRA uses risk assessment but does not disclose weights, and articles presenting exact percentages have invented the methodology.
What information does the CRA already hold about me?+
Slips others issued to you, contract payment reporting, investment and partnership income, property transfer data, customs import records, foreign account information, and records obtained from third parties.
Which numbers are expected to reconcile?+
Revenue to sales reported on GST/HST returns, wage expense to slips filed, remittances to the payroll register, subcontractor expense to contract payment slips, and import credits to customs documents.
When are T5018 contract payment slips due?+
Six months after the end of the reporting period you chose. The last day of February is the T4 and T4A deadline, and the two are frequently confused.
Do repeated losses trigger an audit?+
Not by themselves. What draws attention is a pattern of losses with no explanation in a business that continues trading. Record the explanation rather than only holding it in your head.
Are round-number expenses a problem?+
They read as estimated rather than recorded. Real costs rarely arrive at exactly $5,000, and a ledger full of round figures invites the first question.
Is every bank deposit treated as revenue?+
Not if you identify it. Loans, capital contributions, transfers between your own accounts and refunds are all deposits, but unlabelled they look like unreported income.
Why does the shareholder loan matter so much?+
It collects whatever nobody could code, and amounts not repaid within the period the Act allows can be included in your personal income. It is both a signal and a real exposure.
Can a GST/HST audit happen on its own?+
Yes. Sales tax and payroll examinations are separate programmes with their own selection criteria, and either can arrive without any income tax audit.
What makes a GST/HST refund claim risky?+
Size relative to your trading history. A genuine refund business such as an exporter should expect review at some point and keep the supporting documentation assembled.
Can I claim credits if my supplies are exempt?+
Generally no. Exempt supplies carry no recovery on your costs. Where you make both taxable and exempt supplies, credits must be apportioned on a documented basis.
What is the biggest payroll risk?+
Worker classification. A contractor who is in substance an employee means the CRA can assess deductions that should have been withheld, and directors are personally exposed on unremitted amounts.
Does a written contract settle contractor status?+
No. The test looks at control, tools, chance of profit and risk of loss, and integration. A contract stating independent contractor does not settle it if the relationship says otherwise.
Why is real estate under more scrutiny?+
Property transactions are visible through registry data, and the sector has seen sustained focus on capital against business income treatment, housing rebates and assignment sales.
Can I lower my audit risk to zero?+
No. Random selection means a well-run business can still be picked. What you can control is whether your numbers agree with the data already held about you.
Sixteen questions and one underneath most of them: does your return agree with what somebody else already reported. That is where selection begins. Figures changed for privacy.
The Risk Reduction Checklist
The Risk Reduction Checklist
Quick Reference
The Cross-Checks
- Reconcile revenue on the corporate return to sales reported for GST/HST.
- Reconcile wage expense to the total on slips filed.
- Reconcile payroll remittances to the payroll register.
- Reconcile subcontractor expense to contract payment slips issued.
- Reconcile import credits to the customs accounting documents.
- Compare total deposits to recorded revenue, identifying the difference.
- Record the explanation for any variance in the working papers.
The Signals You Control
- Label loans, transfers and refunds when the deposit arrives.
- Keep a vehicle log wherever vehicle costs are claimed.
- Apply the 50% limitation to meals and entertainment.
- Record the business purpose on travel and entertainment.
- Avoid round-number entries; post what was actually spent.
- Document reasonableness on related-party fees and rent.
- Keep personal spending out of the business accounts entirely.
- Review the shareholder loan quarterly and support each entry.
- Explain any recurring loss in the file, not just in your head.
- File on time across income tax, sales tax and payroll.
The Sector and Structural Items
- Confirm whether your supplies are taxable, zero-rated or exempt.
- Apportion credits on a documented basis where supplies are mixed.
- Test every long-term contractor against the classification factors.
- Remit source deductions on schedule; directors are personally liable.
- File contract payment slips six months after your period end.
- File T4 and T4A slips by the last day of February.
- Record sales at gross where processors report gross independently.
- Support capital against income treatment on property dispositions.
- Confirm rebate and self-supply positions before claiming.
- Keep six years of records, longer for capital property.
- Come forward before contact if you know a past filing was wrong.
- Reconcile monthly, since almost every issue is visible that month.
For a review of how your file looks before the CRA runs its own, contact Gondaliya CPA at info@gondaliyacpa.ca, call 647-212-9559, or book a free consultation.
Twenty-nine points and one underneath them: make your numbers agree with everyone else\u2019s. That is most of audit risk management in a sentence. Figures changed for privacy.
Businesses We Serve
Industry Expertise
Which signal dominates differs by the business. Here are ten and the usual exposure.
| Business Type | The Characteristic Exposure |
|---|---|
| Medical practices | Exempt supplies and credits claimed anyway |
| Dental practices | Mixed taxable and exempt, needing apportionment |
| Construction and trades | Contract payment reporting and classification |
| Real estate and development | Capital against income, and rebate conditions |
| Restaurants and bars | Purchases implying sales, and cash wages |
| Transport and logistics | Vehicle logs, and corporate proration errors |
| E-commerce sellers | Processor reporting against recorded revenue |
| Childcare providers | Exempt activity and payroll completeness |
| Importers | Credits claimed off the wrong document |
| Any owner-managed corporation | The shareholder loan account |
- Medical practices: Exempt supplies carry no recovery.
- Dental practices: Cosmetic and care are treated differently.
- Construction and trades: Your slips let them work backwards.
- Real estate and development: Registry data makes it visible.
- Restaurants and bars: What you bought implies what you sold.
- Transport and logistics: No log means no claim.
- E-commerce sellers: Gross is reported whether you record it or not.
- Childcare providers: The risk is credits, not uncharged tax.
- Importers: The customs document is the support.
- Any owner-managed corporation: It collects what nobody could code.
The sector changes which mismatch is likeliest. It does not change the method, which is run the cross-checks yourself, document the variances, then file. Figures changed for privacy.
Professional Guidance and Quick Reference
Guidance
Professional Guidance: How Gondaliya CPA Lowers Your Audit Risk
Small businesses get selected in a predictable set of ways: revenue on the corporate return that does not agree with sales reported on GST/HST filings, wage expense that does not tie to the slips actually filed, subcontractor payments reported through contract slips that the recipient never reflected, bank deposits from loans and transfers that were never labelled and therefore look like unreported income, input tax credits claimed on activity that is exempt and carries no recovery, contractors who are in substance employees, vehicle claims with no log behind them, and a shareholder loan account collecting whatever nobody could code. Gondaliya CPA reduces that exposure on a fixed annual fee.
We handle what decides the outcome: running the same cross-checks the CRA runs, before filing rather than after, reconciling revenue to sales tax and wages to slips, identifying every deposit that is not revenue, confirming whether your supplies are taxable or exempt and apportioning credits where mixed, testing worker classification, reviewing the shareholder loan quarterly and documenting the explanation for any variance in the working papers.
Our team starts with your last corporate return, your most recent sales tax return and a bank reconciliation. Those three run the main checks and tell you where your file actually stands. Whatever your sector, you get clear advice and a fixed price before we start.
Quick Answers
- Selection: Data matching, not instinct
- Biggest gap: Revenue against sales tax filings
- Deposits: Label what is not revenue
- Losses: Fine, if explained in the file
- Exempt supplies: No credit recovery
- Classification: The relationship, not the contract
- T5018: Six months after period end
- T4 and T4A: Last day of February
- Scoring models: Not published; invented
- Random selection: Real, so stay ready
Who This Is For
- For: Incorporated Canadian small businesses wanting to understand how selection works and reduce their exposure before a letter arrives.
- Not For: Matters already under enforcement or involving allegations requiring legal counsel, and any expectation that risk can be reduced to zero, since random selection is real.
People Also Ask
Should I avoid claiming a legitimate loss?+
No. Claim what is correct and document why the loss arose. The problem is an unexplained pattern, not the loss itself.
Does a corporation prorate vehicle costs?+
No. A corporation claims the cost and reports a taxable benefit where there is personal use. Prorating is the sole proprietor method.
What if I already know something was filed wrong?+
Act before contact. The Voluntary Disclosures Program may reduce penalties, but it generally requires the disclosure to be voluntary.
Glossary of Key Terms
- Information matching: Comparing your return to data filed by others.
- Risk assessment: Comparing your figures against sector patterns.
- Random selection: Files chosen without any risk indicator.
- T4 and T4A: Slips for employment income and fees for services.
- T5018: Contract payment reporting in construction.
- Taxable supply: A sale carrying tax, with credits recoverable.
- Zero-rated supply: Taxed at nil, with credits still recoverable.
- Exempt supply: No tax charged and no credits recoverable.
- Apportionment: Splitting credits where supplies are mixed.
- Worker classification: Whether someone is an employee or contractor.
- Source deductions: Amounts withheld and held in trust for the CRA.
- Director liability: Personal exposure for unremitted trust amounts.
- Shareholder loan: Company funds used personally, taxable if not repaid.
- Self-supply: Sales tax rules where new housing is rented rather than sold.
- Capital against income: Whether a gain is a capital gain or business profit.
- Voluntary Disclosures Program: Correcting filings before CRA contact.
CRA Audit Risk Check
This quick self-check indicates where your operation most likely has room. Please answer the six questions below.
CRA Audit Risk Check
Six quick questions on your filings. No fee shown.
Points to raise with us:
This is a general prompt, not tax or legal advice or a quote. Your position depends on your full facts. For a real review, please book a free consultation.
Want a checklist to work from? You can download our free CRA audit red flags checklist before your consultation.
Reconcile revenue to your GST/HST filings and wages to the slips you filed. Label every deposit that is not revenue when it arrives. Confirm whether your supplies are taxable or exempt before claiming credits. Test contractor classification against the real relationship. Keep vehicle logs. Review the shareholder loan quarterly. Document the explanation for any variance. Please keep six years of records.
2026 Update — what is current: This article reflects rules current to 2026. The six-year retention period, the end-of-February deadline for T4 and T4A slips, the six-month deadline for contract payment slips after the chosen reporting period ends, the 50% limitation on meals and entertainment, and the personal liability of directors for unremitted source deductions are unchanged. Please note that the CRA does not publish its audit selection weightings, so any table presenting exact percentage weights and a total risk score is describing an invented model rather than a disclosed one; that exempt supplies carry no input tax credit recovery, which reverses the usual advice for sectors such as childcare and most medical services; that dental practices commonly make both taxable and exempt supplies and must apportion credits on a documented basis; that a corporation does not prorate vehicle costs by business use but claims the cost and reports a taxable benefit; and that the Voluntary Disclosures Program generally requires the disclosure to be voluntary, so it closes once the CRA has made contact on the matter.
CRA Audit Triggers Canada: How Gondaliya CPA Reduces Your Exposure
Start with three documents
Gondaliya CPA runs the same cross-checks the CRA runs before you file rather than after, reconciling revenue to sales tax filings and wages to slips, identifying every deposit that is not revenue, confirming whether your supplies are taxable or exempt and apportioning credits where mixed, testing worker classification against the real relationship, reviewing the shareholder loan quarterly and documenting the explanation for every variance, on a flat annual fee including HST with a one-business-day response. Please book a free consultation.
Next Steps
Please book a free consultation with Gondaliya CPA and bring your last filed corporate return, your most recent sales tax return, and a recent bank reconciliation. Those three let us run the main cross-checks, show how your file looks to the CRA, and identify what remains to claim on the equipment, and where the documentation is thin. You will get a flat annual fee including HST before any work begins. If our content helps, please add gondaliyacpa.ca as a preferred source on Google.
Published: · Last updated:
Editorial policy: We research against CRA and CPA Ontario sources, fact-check the figures, and Sharad Gondaliya, CPA, reviews the content, which we update as the rules change.
Disclaimer: This article is educational information only and is not tax, legal, or financial advice. Figures marked illustrative are examples rather than quotes or guarantees. It reflects CRA rules current to 2026, including the $30,000 GST/HST threshold, the Class 8 rate, Class 13 leasehold treatment, the half-year rule, and the six-year retention requirement. Rates, limits and expensing rules change and outcomes depend on your specific facts. Please consult a CPA Ontario member before acting.
Sharad Gondaliya is a CPA Canada & CPA USA with 15 Years+ experience of Accounting, Tax, Payroll of Corporate Small Businesses as Tax Accountant. He is a CPA Ontario member (61040184) and holds US CPA licences in Washington and Montana and is well known among corporate small businesses for tax planning, efficient tax solutions, and affordable CPA services. Sharad is the Principal (Director) of Gondaliya CPA – Affordable CPA Firm in Canada. Licenses: CPA Ontario: 61040184 | CPA USA (MT): PAC-CPAP-LIC-033176 | CPA USA (WA): 57629 | CPA Firm License: 61330051 View Full Author Bio