



Common Tax and Accounting Mistakes Print-on-Demand Businesses Make in Canada
Print on Demand Business Taxes Canada: Common Tax Mistakes and Accounting Tips by Gondaliya CPA
Print on demand business taxes in Canada can be complex, and avoiding common tax and accounting mistakes is essential for success. Gondaliya CPA highlights key issues like print on demand bookkeeping mistakes, proper inventory accounting, and managing GST/HST to help streamline print on demand accounting Canada.
Quick Summary
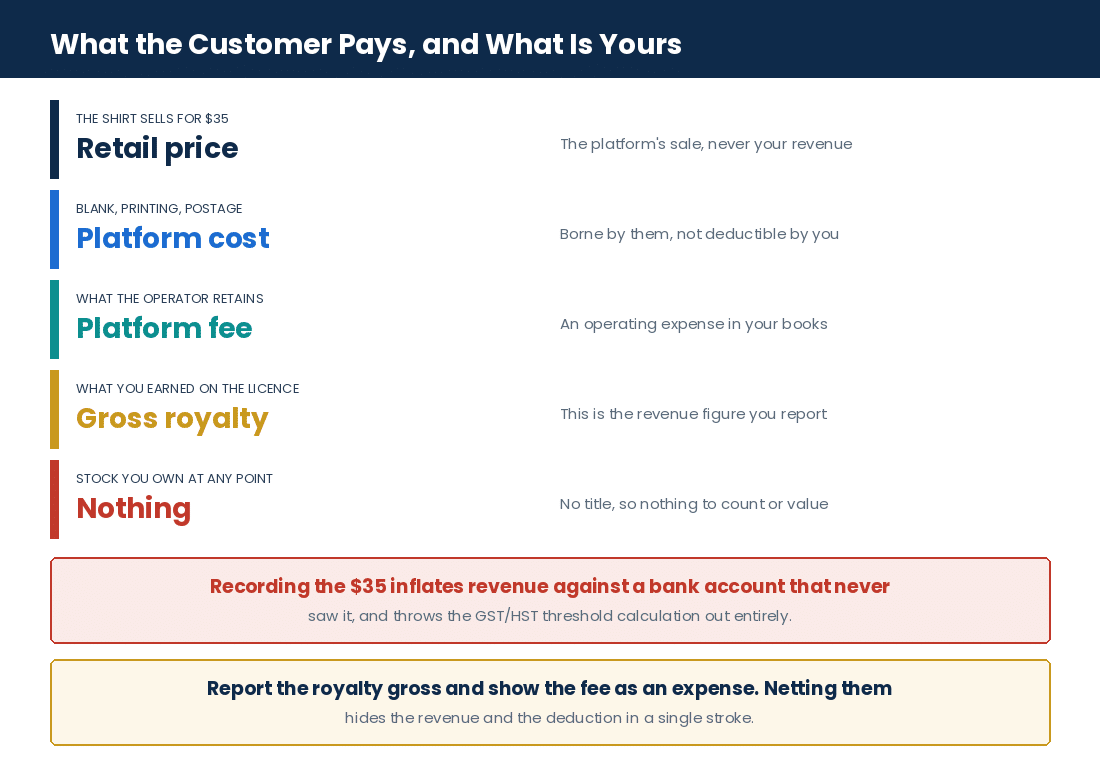
Print-on-demand looks like e-commerce and is accounted for nothing like it. You earn a royalty, not a sale price — report the gross royalty, not what the customer paid at checkout, because the retail figure was never yours. Report it gross: platform fees are an operating expense under subsection 9(1), not a reduction of revenue, and netting them hides both sides at once. You hold no inventory — the platform makes and ships the item, so there is nothing to count, value or write down, and nothing of its production or shipping cost is yours to claim. The platform charging tax at checkout does not register you: your own obligation turns on your taxable supplies under sections 148 and 240(1). Convert each payout on its own date, not on one blended annual rate. And CRA already has your numbers — the Part XX platform reporting rules have been sending them your payout totals since 2024.
Reading time: 14 minutes.
Table of Contents
- Understanding Print on Demand Business Taxes
- Common Tax and Accounting Mistakes
- Key Accounting Practices
- Managing GST/HST and Provincial Sales Taxes
- Identifying and Correcting Filing Errors
- Practical Financial Guidance and Next Steps
- Frequently Asked Questions
- Essential Insights for Sellers
- Businesses We Serve & Industry Spotlights
- Professional Guidance and Quick Reference
The Numbers That Matter
This article covers Canadian federal income tax and GST/HST for residents running print-on-demand businesses, with Ontario and Toronto context, and reflects rules current to 27 October 2026. It is written for sellers licensing designs through platforms that manufacture and ship on their behalf, and it covers gross royalty reporting, platform fees as expenses, why there is no inventory to account for, the small supplier threshold and registration, place of supply, foreign withholding and tax credits, currency conversion, corporate filing and T2 schedules, record retention and catch-up filing. Provincial sales tax registration rules, thresholds and the treatment of a licence rather than a sale of goods differ by province and change frequently, so the provincial position should be confirmed for each province you sell into. Gondaliya CPA performs compilation engagements under CSRS 4200, which provide no assurance; audit and review engagements are referred out. This is educational information only and not tax or legal advice.
Understanding Print on Demand Business Taxes in Canada
Understanding Print on Demand Business Taxes
Start Here
Mixing Personal and Business Expenses: Risks and How to Separate Them
Mixing your personal expenses with your print-on-demand business costs can cause big tax mistakes. Many sellers don’t separate these at first, especially in their first year. This can cause trouble with the CRA later.
Why separating expenses matters. You need to separate business from personal expenses for correct tax reporting. The CRA only lets you deduct real business costs. If you mix them, it might cause a CRA review or audit. That could lead to fines.
Practical steps to distinguish and document expenses. Here’s what helps keep things clear:
- Open a bank account just for your print-on-demand business.
- Keep all receipts and invoices organized by type.
- Use accounting software like QuickBooks or Xero.
- Don’t rely only on platform statements; keep your own records too.
Remember, the CRA has rules about how long you must keep tax records, so keep everything safe.
Inaccurate or Missing Tax Filings: Penalties and Avoidance
Late or wrong tax filings bring problems for print-on-demand sellers. You want to avoid penalties.
CRA late-filing penalties. The CRA fines you if you miss the tax filing deadline. The longer you wait, the bigger the penalty grows. Filing late many times makes it worse. So filing on time matters a lot.
Tools and reminders to avoid late filings. Use calendar alerts or notifications from your accounting software. These help remind you when taxes are due. Staying organized makes filing easier and less stressful.
Errors in GST/HST and PST Reporting Specific to Print on Demand
Sales taxes like GST/HST and PST have special rules that many online sellers get wrong.
Unique issues with online and print-on-demand platforms. Some think they don’t need to register for GST/HST because platforms charge tax for customers at checkout. But that’s not true. Your own taxable sales count, no matter what the platform does.
How to ensure correct sales tax reporting. You must register for GST/HST based on your own taxable supplies — not just because platforms charge taxes at checkout. Check how much you sell yourself against the small supplier threshold set by the CRA.
“The platform handles the tax” is the sentence that costs print-on-demand sellers the most. It is also true, as far as it goes. The platform does charge and remit sales tax to the end customer on the shirt. What it does not do is register you, and it does not touch the supply you made — which is a licence of your artwork to the platform, not a shirt to a stranger in Calgary.
Those are two different transactions with two different tax positions, and only one of them is yours. Figures changed for privacy.
Overlooking Eligible Tax Deductions for Print On Demand Expenses
Missing deductions can mean paying more tax than needed. Many print-on-demand sellers forget what they can claim.
Commonly missed deductions. Don’t miss production costs, like artwork creation or shipping fees — they count as business expenses. Also, watch out: platform fees often get recorded as income but should be offset against revenue.
Documentation tips for maximum tax benefit. Keep clear proof of every expense you claim. Save receipts and notes for each cost during tax season. The CRA wants good records and enforces how long you keep them.
Bookkeeping Mistakes That Affect Tax Compliance And Financial Clarity
Bad bookkeeping hurts your business by making finances confusing and causing tax errors.
Impact of poor bookkeeping on business health. If platform statements are your only record, you risk mistakes. Using average exchange rates for all payouts can cause wrong numbers too. These problems confuse cash flow and slow down decisions.
Ways to establish better accounting systems. Set up an accounting system that matches your sales and expenses closely:
- Track every transaction carefully.
- Use software that converts currency per payout date.
- Catch up quickly if books fall behind — start with recent months then work backward.
- Consider hiring help if it feels overwhelming.
Good bookkeeping gives a clear view of your business health and keeps taxes right.
Common Tax and Accounting Mistakes in Print on Demand Businesses
Common Tax and Accounting Mistakes
Where It Goes Wrong
Print-on-demand business taxes Canada need close attention. Many sellers report the platform’s retail price as their revenue. That’s wrong. You should report the royalty you earn, not the full sale price. The right way shows your gross royalty income separately from platform fees. This gives a clear picture of your earnings [Income Tax Act s. 9(1); CRA royalties guidance].
Another mistake is recording royalties after subtracting platform fees. This hides both revenue and expenses. It can trigger audits.
Some sellers count inventory they never owned. Print-on-demand platforms make and ship products themselves, so you don’t hold stock to value or write down.
Also, claiming production and shipping costs as your own business expenses causes errors. These costs belong to the platform, not the seller.
Lastly, some skip checking if they must register for GST/HST. Just because the platform charges tax doesn’t mean you’re off the hook. You must register based on your taxable supplies, not whether a third party collects tax [Excise Tax Act ss. 148, 240(1); CRA GST/HST information].
A seller came to us with books showing roughly $180,000 of revenue on a channel that had paid out about $31,000. They had recorded the retail price of every shirt, hoodie and mug the platform had ever sold with their design on it.
Nothing was being hidden; the opposite. But a return showing six figures of revenue against a bank account that never saw it is a reconciliation problem waiting to happen, and the GST/HST threshold question gets a wildly wrong answer too. Figures changed for privacy.
Mixing Personal and Business Expenses: Risks and How to Separate Them
Mixing personal with business expenses causes trouble. Accurate records matter for print on demand accounting Canada rules. Blurred expenses might lead to audits or denied deductions.
Here are steps to keep things separate:
- Use a bank account just for your print-on-demand business.
- Label purchases clearly — design software separate from home bills.
- Save receipts with notes explaining what each is for.
- Reconcile bank statements with your bookkeeping regularly.
Doing this helps you keep clean records for print on demand business tax Canada filings.
Inaccurate or Missing Tax Filings: Penalties and Avoidance
Missing tax deadlines means penalties from the CRA. These fines get bigger over time if you owe money. It applies to corporate returns or GST/HST linked to your print-on-demand income tax Canada duties.
Avoid late filings by using tools like calendar reminders or alerts in accounting software made for small businesses selling online.
Build a routine for filing returns on time. If needed, hire bookkeeping help so you don’t scramble last minute and risk fines or interest.
Errors in GST/HST and PST Reporting Specific to Print On Demand
GST/HST reporting can be tricky with print-on-demand sales through online marketplaces, because the place-of-supply rules in section 142 of the Excise Tax Act and Schedule IX decide the treatment rather than the platform’s checkout. Many sellers think that since the platform charges sales tax at checkout, they don’t need to register or remit themselves. That’s false, and it is why the registration review gets skipped even where taxable supplies are being made in Canada.
To report sales tax correctly:
- Test place of supply rules carefully.
- Usually, your supply goes to the platform operator, not directly to customers outside Canada.
- Only claim input tax credits if you have eligible Canadian expenses.
- Keep documents ready per CRA standards.
Overlooking Eligible Tax Deductions for Print On Demand Expenses
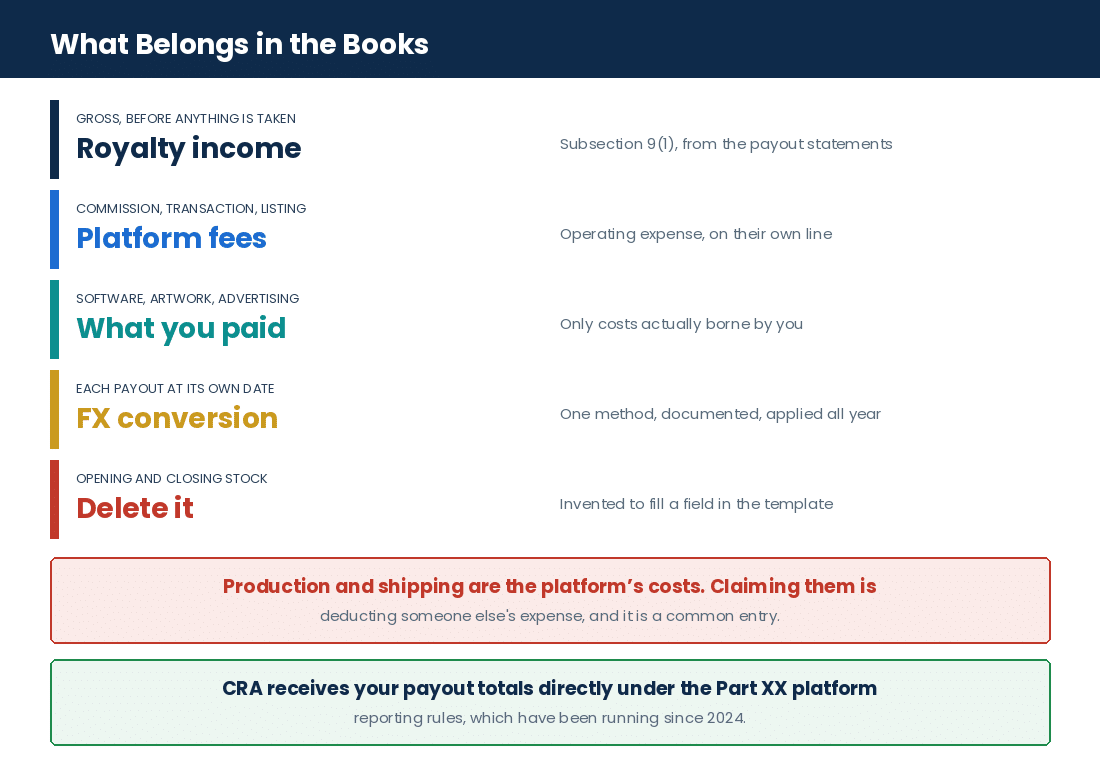
Platform fees should be logged as operating expenses — not deducted from royalty income. This matches the rules on gross revenue and deductible costs (Income Tax Act ss. 9(1), 18(1)(a)).
Common missed deductions include payments for commissioned artwork where you buy rights that might count as capital assets.
Keep good paperwork: contracts that show what rights you bought plus invoices explaining services help support deductions during reviews.
Foreign withholding taxes paid by platforms also get overlooked sometimes. You may be able to claim these as credits under ITA sections covering foreign taxes paid versus allowed credits (ss. 126(1), 126(2)).
Foreign withholding is the one sellers hand us without knowing what it is. It appears on a payout statement as a line that made the deposit smaller, and it gets treated as another platform fee and expensed.
It is not a fee. It is tax already paid on your behalf, and expensing it instead of claiming it as a credit usually costs the seller most of its value. The amount is often small enough that nobody looks twice, and large enough across a few years to be worth the look. Figures changed for privacy.
Bookkeeping Mistakes That Affect Tax Compliance And Financial Clarity
Mixing software subscriptions, artwork payments, and stock licenses makes tracking hard. You lose sight of where money really goes in your print-on-demand accounting Canada setup.
Relying only on platform payout statements isn’t enough — they might miss fees or errors affecting profits over time.
Original documents often come from overseas, so keep copies safe and follow CRA record rules which require holding records up to six years after filing.
Use cloud-based bookkeeping with bank feeds for quick checks and catch-up when books fall behind due to complexity or past neglect.
This approach avoids mistakes that could cause fines or confusion later on.
Income Tax Act ss. 9(1), 18(1)(a), 126(1), 126(2), 230(4) · Excise Tax Act ss. 142, 148, 240(1), Schedule IX · CRA Guide RC4022 · CRA Guide T4002
Key Accounting Practices for Print on Demand Businesses in Canada
Key Accounting Practices
Getting It Right
Proper Inventory Accounting and Managing Print on Demand Platform Income
Print-on-demand businesses in Canada usually don’t hold physical stock. The platform makes and ships products straight to customers. So, counting inventory doesn’t really apply here. Trying to track inventory can mess up your accounting.
You should record income as royalties earned from your designs or intellectual property. Report the total royalty amount before taking out any platform fees. Those fees are expenses, not revenue reductions.
Here’s what you need to do:
- Track gross royalties received
- Separate platform fees as expenses
- Keep detailed payout statements showing both
This helps you follow CRA rules under the Income Tax Act [s. 9(1)] and the registration and small supplier rules in the Excise Tax Act [ss. 148, 240(1)]. Don’t count inventory because you never own the products physically or legally.
Accounting software fights you on this. Every e-commerce template assumes cost of goods sold and a stock figure, and sellers dutifully fill them in because the field is there. We have seen opening and closing inventory invented out of nothing for three consecutive years, purely because the chart of accounts asked.
Deleting those lines usually improves the gross margin picture rather than harming it, because the invented inventory was never costing anything in the first place. Figures changed for privacy.
Establishing a Clear Chart of Accounts Tailored for Print on Demand Operations
A clear chart of accounts can help you avoid common tax mistakes with print-on-demand businesses. Set up revenue accounts that track gross royalties separately from expense accounts like platform fees, commissions, or transaction charges.
Keep these points in mind:
- Treat platform fees as operating expenses, not deductions from income
- Check if you cross the small supplier threshold for GST/HST registration
- Use specific ledger codes for design costs versus stock licenses
This approach matches CRA’s reporting needs and keeps your books tidy when tax time comes.
Tracking Business Expenses Effectively for Accurate Tax Filing
Tracking your expenses right is key for accurate tax filing in Canada. Some sellers wrongly claim production and shipping costs as their own. But actually, the platform pays those since they make and ship items directly.
You can only claim expenses you really pay, like:
- Software subscriptions for creating designs
- Artwork commissions where you get full ownership
- Advertising costs tied directly to your brand or store
Don’t mix software licenses, artwork purchases, and stock image licenses together. Each has different tax treatments — some get amortized; others are expensed immediately. Keeping these clear avoids mistakes during tax prep.
Understanding Corporate Tax Requirements for Incorporated Print on Demand Businesses
If you run an incorporated print-on-demand business in Canada, your tax rules differ from sole proprietors or partnerships.
Key things to know:
- File annual T2 returns reporting all royalty income at fair market value before deducting platform fees
- Corporate return deadlines are usually six months after your fiscal year ends but may vary
- Missing deadlines leads to penalties and interest charges
Also, keep good records of foreign currency payouts — they need proper conversion each reporting period according to CRA guidelines. Knowing deadlines helps you prepare financial statements that match your business model (no physical inventory but multiple currencies).
Utilizing Certified Accountants for Accurate Print on Demand Accounting and Tax Planning
Deciding between filing taxes yourself or using a CPA depends on how complex your print-on-demand business is. Factors include:
- Selling across many platforms
- Handling multiple currencies
- Dealing with foreign withholding taxes needing credits under treaties
At Gondaliya CPA, we focus on print-on-demand tax issues all over Canada, including Ontario clients. We review payout statements carefully to spot gross royalties and separate fees properly. We remove incorrect inventory entries and check if you must register based on supply thresholds.
Certified accountants stay up to date with the digital platform reporting rules in Part XX of the Income Tax Act, which have required platform operators to report seller identity and payout totals to CRA since 2024. They help reduce errors that DIY filers often make by applying current CRA guidance correctly.
Those reporting rules mean CRA is not waiting to be told what you earned. Platform operators file seller identity and payout totals directly, and the first returns under Part XX were filed in early 2025. A return that does not match what the platform reported is the easiest kind of discrepancy for CRA to find.
For expert help with your print on demand business taxes Canada, contact Gondaliya CPA at info@gondaliyacpa.ca or call 647-212-9559 today for a free consultation designed around your needs nationwide — including Ontario areas like Hamilton.
Print-on-Demand Tax Readiness Check
Five quick questions on where your departure file stands. No fee shown.
Points to raise with us:
This is a general prompt, not tax or legal advice or a quote. Your position depends on your full facts. For a real review, please book a free consultation.
Managing GST/HST and Provincial Sales Taxes for Print on Demand Sales
Managing GST/HST and Provincial Sales Taxes
Sales Tax
Running a print-on-demand business in Canada means handling GST/HST and provincial sales taxes carefully. You need to know the registration rules, how to calculate taxes right, what to do when selling in different provinces, and watch out for common reporting mistakes. All this keeps your print on demand accounting in Canada on track.
Registration Requirements for GST/HST and PST in Key Provinces
You have to register for GST/HST if your sales go over the small supplier threshold. That test is in section 148 of the Excise Tax Act, and the obligation to register is in section 240(1). The threshold counts your taxable supplies over one calendar quarter or four quarters in a row. It includes royalties you get from designs licensed through platforms.
Here’s what happens in some provinces:
- In British Columbia (BC), you must also register for PST if you sell taxable goods there.
- Alberta has no provincial sales tax but you still must register for GST if you meet the federal limits.
- Saskatchewan needs both GST and PST registration when your revenue hits their specific levels.
To register, keep documents proving your sales pass these thresholds. You also need records showing where the sale happened (place of supply). CRA expects you to file returns yearly or quarterly based on how much you make.
Correct Calculation and Reporting of GST/HST and PST on Print on Demand Sales
The place of supply means where the right to use the artwork is transferred — not where the item ships. Sellers must check each sale against Excise Tax Act rules instead of just trusting platform charges or shipping info.
Calculate GST/HST based on this place before sending payments collected by platforms that bill customers directly. BC’s PST applies only if the sale happens inside BC according to their rules.
To report taxes right:
- List gross royalty income separate from platform fees.
- Treat platform fees as expenses, not reductions in income.
- This keeps input tax credits clear and audit trails clean.
Handling Multi-Provincial Sales and Extra-Provincial Registration Obligations
Selling online often means reaching customers all over Canada. That means extra-provincial registrations might be needed outside your home province.
Each province sets its own rules — usually based on how much you sell or how many transactions you have — to force registration for provincial sales taxes like Quebec’s QST or Manitoba’s RST along with federal GST/HST.
Watch your sales by province carefully because once you cross their limits, you have to collect and send taxes there — even if you don’t have a physical store.
Keep detailed province-by-province records so filing is easier. Deadlines vary by province; missing them could mean penalties and interest charges.
The provincial layer is where print-on-demand gets genuinely hard, and not because the rules are obscure. It is because what you are supplying is a licence of artwork, and most provincial sales tax guidance is written about goods crossing a border. The shirt is a good. Your supply is not.
We work the federal position first and then take the provincial question province by province, because a single confident answer that covers all of them does not exist. Figures changed for privacy.
Avoiding Common GST/PST Reporting Errors That Trigger CRA Audits
A lot of sellers mess up by showing net revenue after deducting platform fees instead of gross royalties earned. This makes taxable income look smaller than it really is and can cause trouble during audits.
Another mistake: thinking that if the platform collects sales tax at checkout, sellers don’t have to register or file returns. This wrong idea often leads to non-compliance, and the rate and the provincial layer both change once you are selling outside Ontario [Excise Tax Act ss. 148, 240(1)].
Good bookkeeping means:
- Separating gross royalty income from platform fee expenses
- Keeping invoices ready to back up claims during CRA checks
- Regularly checking if your registrations match current small supplier thresholds
Missing filings or understating income raises red flags with auditors fast.
For advice on handling Canadian print-on-demand business tax issues like multi-jurisdiction challenges, contact Gondaliya CPA at info@gondaliyacpa.ca or call 647-212-9559. They offer free consultations that focus on your exact situation about print on demand business taxes Canada compliance.
Identifying and Correcting Tax Filing Errors Proactively
Identifying and Correcting Filing Errors
Fixing It
Print on demand business taxes in Canada can be tricky. Many sellers make print on demand tax mistakes without knowing it. For example, some forget to record platform fees as expenses or miss GST/HST registration when required. These errors cause problems with the CRA later.
You should check your financial statements often. Compare your payout statements with what you’ve recorded. Make sure royalties are reported as gross amounts, not net of fees. Subsection 9(1) of the Income Tax Act is what requires profit to be computed from gross revenue, with paragraph 18(1)(a) limiting what can be deducted against it.
Good bookkeeping separates platform fees from income clearly. This way, you reduce the risk of audits and penalties. Keeping a clear audit trail helps catch mistakes early, avoiding print on demand tax mistakes before filing deadlines.
Self-Audit Checklist
Use a self-audit checklist to avoid print on demand tax mistakes. Here’s a simple list for print on demand business tax Canada:
- Record all royalty income at gross value.
- List platform fees as separate expenses.
- Don’t count inventory; you never own stock.
- Check if you need GST/HST registration based on sales.
- Confirm foreign withholding taxes match payout slips.
- Use correct exchange rates for currency conversions.
- Separate design costs: commissioned art vs stock licenses.
- Keep records showing hobby vs business activity.
Following this checklist helps catch errors before filing and keeps your taxes accurate.
Amending Past Tax Returns
Made a mistake on past returns about your print-on-demand business taxes Canada? Fixing them quickly avoids bigger issues. The CRA allows amendments through an amended T2, or through the Voluntary Disclosures Program where relief from penalties and interest is being sought under subsection 220(3.1).
Common fixes include reporting royalties correctly as gross income, adding missed platform fee expenses, fixing GST/HST filings, or including foreign tax credits properly.
Keep original payout reports and bookkeeping handy when amending. Timely updates show good faith and lower chances of penalties.
The disclosure programme rewards arriving first, and with platform reporting now running that window is shorter than it used to be. CRA receives payout totals directly, so a seller who has never filed is not undiscovered — they are simply unprocessed.
Most of the catch-up files we see are people who treated a design side project as a hobby for two or three years and then noticed it had become income. That is a good disclosure candidate, provided somebody files before the letter arrives. Figures changed for privacy.
Currency is where print-on-demand books drift without anyone doing anything wrong. Payouts arrive in US dollars at irregular intervals in irregular amounts, and applying one annual average to all of them is a method in name only — the figure it produces is wrong in a direction nobody can predict.
Converting each payout at its own date is more work once and no work thereafter if the software does it. Rebuilding three years of it by hand afterwards is the expensive version. Figures changed for privacy.
How to Respond if the CRA Flags Your Print On Demand Business Taxes
If the CRA flags your print on demand business tax Canada filings, don’t panic but act fast. Problems usually come from mismatched revenues or missing registrations even though sales passed thresholds (Excise Tax Act ss. 148, 240(1)).
Gather all documents before replying:
- Bank deposits matching payouts
- Invoices listing platform fees
- Proof of GST/HST payments
- Foreign withholding certificates
- Currency conversion records
- Evidence separating hobby vs business work
Reply clearly to each concern but don’t admit fault until you check with a pro familiar with Canadian law.
Steps to Take When You Receive a Notice
If a notice arrives about your print-on-demand reporting, here’s what to do:
- Read the notice carefully; note any deadlines.
- Compare your books with their points; focus only on your sales reports.
- Collect documents like payout summaries showing gross royalties plus fee expenses.
- See if prior returns need changes before replying — this might lower penalties (Income Tax Act s. 220(3.1)).
- If unsure about things like place of supply rules or foreign tax credits, get professional help instead of guessing.
Act fast so small issues don’t turn big.
Seeking Professional Help and Responding Promptly
At Gondaliya CPA, we handle print-on-demand files with care. We follow Canadian rules for royalties, expense recording, small supplier thresholds (Excise Tax Act s. 148), and place-of-supply tests under section 142 of the Excise Tax Act and Schedule IX.
We know typical print on demand tax mistakes sellers make across Canada and help avoid audit risks fast. Our Ontario CPAs offer clear guidance with over 1300 five-star reviews from happy clients who trust us for flat-fee annual services including corporate tax filing help.
Maintaining Good Standing with CRA: Registrations, Clearances, and Compliance
To stay good with the CRA, keep your registrations updated — especially GST/HST ones once sales go over the small supplier limit in section 148 of the Excise Tax Act, which brings the registration obligation in section 240(1) with it. Even if platforms charge sales tax at checkout, you must still register yourself if needed.
A statement of account from CRA shows what is outstanding on each program account and is the practical way to confirm you are current. Clearance certificates are a different thing, obtained under subsection 159(2) by a legal representative before distributing property on a wind-up or an estate. Also, file corporate returns on time every year within six months after your fiscal year-end as per Income Tax Act subsection 150(1).
Keeping registrations updated. Review registrations often so they match changes in sales volume under small supplier rules. Register quickly when crossing thresholds to avoid penalties or interest that grow daily. Remember corporate income tax return dates never change but update contact info so CRA notices reach you without delay preventing missed deadlines affecting your standing.
Record retention and compliance habits. Canada’s record keeping rules say keep all books and records for six years after the last taxation year they relate to. For print-on-demand businesses this means holding original payout statements showing gross royalties earned plus itemized platform fees separately claimed. Also keep currency conversion worksheets that show CAD values correctly by date.
Good filing habits make it easier to find records during audits and protect data by backing up electronic files in case systems fail later.
Benefits of Professional Assistance and Services from Gondaliya CPA
Gondaliya CPA takes a print-on-demand file from end to end — from collecting diverse platform statements to adjusting revenue so it shows true gross earnings with expenses recorded separately, as Canadian law requires.
Clients get clear deliverables including full reconciliations, working papers explaining adjustments made plus schedules tracking foreign taxes withheld eligible for credit review — all laid out transparently so clients can submit confidently without risking costly errors common in self-prepared filings lacking detailed knowledge.
How Expert Support Reduces Risk and Maximizes Savings
Expert help spots where the risk sits and puts controls in place that prevent it — catching common mistakes like misstated revenues netted against fees wrongly; missing registration periods; forgetting some foreign withholding amounts eligible only sometimes for credit; wrong currency conversions messing up income reports. Together these controls form strong defenses.
Service Options Offered by Gondaliya CPA
Our pricing starts at a flat annual fee including HST covering key services needed for ongoing compliance: bookkeeping updates, GST/HST filing prep, and corporate income tax compilation and submission. The fee depends on things like:
| Pricing Driver | What It Means |
|---|---|
| Number of platforms | More platforms mean more work reconciling |
| Total payouts | High volumes require careful checking |
| Foreign currencies used | Need extra work converting exchange rates |
| Periods behind | Catching up adds extra time |
For exact quotes call us at 647-212-9559 or email info@gondaliyacpa.ca. We offer free consultations with no pressure and clear upfront pricing information.
Practical Financial Guidance for Print on Demand Entrepreneurs
Practical Financial Guidance and Next Steps
Day to Day
Print on demand business taxes in Canada can be tricky. You need to plan carefully and keep good records. If you don’t, you might miss important tax rules or make mistakes that cost you later. Managing your money right helps your business grow and keeps you out of trouble.
Planning for Income Taxes and Corporate Tax Returns Including T2 Schedules
When you make money from print-on-demand, the government usually treats it as royalties or design fees. This is different from selling products directly. It matters because you report this income differently on your corporate tax return (T2). You must list the full royalty amount as income before deducting any fees. Fees charged by platforms come off as expenses, not a cut from your income.
You’ll also fill out specific T2 schedules to match your activities. For example:
- Schedule 125: shows your total revenue from royalties
- Schedule 9: if a related or associated corporation is involved in licensing the artwork, with Form T106 where that party is a non-resident
Doing this right avoids problems with the CRA checking your taxes.
For example, say you got $50,000 in royalties but paid $5,000 in platform fees. You record $50,000 as income and $5,000 as expenses — not subtract fees from income first.
Keeping Organized Records with Valid Receipts and Documentation
Good records matter a lot. Many print-on-demand sellers mess up here by only keeping platform summaries. The CRA wants original receipts, contracts, and invoices to back up your claims.
Here’s what you should keep:
- Payout statements showing total amounts before fees
- Invoices for designs or licenses with details about rights bought
- Proof if foreign taxes were withheld
- Records of currency exchange rates used on payment dates
Not having these can cause your deductions to be denied or trigger penalties. Staying organized helps prevent those costly print on demand tax mistakes.
Commissioned artwork is the expense sellers document worst, and it is the one most worth documenting. What matters is not the invoice amount but what the contract says you bought: a licence to use a design, or the copyright itself. Those are different assets with different treatment, and a PayPal receipt for “logo” settles neither.
A one-page agreement naming the rights transferred costs nothing at the time and is close to impossible to reconstruct from a freelancer two years later. Figures changed for privacy.
Preparing for Payroll and Employer Obligations If Applicable
If you hire people — for example marketing help or customer support — you need to handle payroll correctly. You have to register for a payroll account through CRA once certain thresholds are met.
You must:
- Withhold CPP contributions and EI premiums from paychecks
- Deduct income tax as required
- Submit remittances on time to avoid penalties
- Keep payroll records following federal rules
Even small teams need clear systems to stay on top of these duties under Canadian law.
Importance of Regular Financial Reviews and Updates to Accounting Practices
Reviewing your finances regularly catches errors early. A common mistake happens when sellers mix up gross earnings and net deposits after fees or currency changes.
You should:
- Reconcile payments using daily Bank of Canada exchange rates at receipt dates
- Check if you need GST/HST registration based on updated sales totals
- Fix any misclassified expenses or missing filings fast
Doing this reduces risks connected to print-on-demand accounting Canada errors. Professionals like Gondaliya CPA recommend these regular check-ins for safer bookkeeping.
How to Register Your Business Number and Maintain Compliance
You must get a Business Number (BN) if your taxable sales go over a small supplier limit (check current thresholds in Ontario). This lets you collect GST/HST properly depending on where your sales happen.
Remember:
- Monitor all sales channels combined — your own store plus platforms
- Keep track yearly to see if BN registration is still needed
Many sellers wrongly think platforms’ GST/HST collections cover them fully. That’s not true. You’re responsible for tracking taxable supplies and claiming input tax credits correctly in your books.
More info is at canada.ca business registration services and tax numbers.
Scheduling Consultations and Using Professional Tax Services from Gondaliya CPA
Getting expert help can save headaches later. Print-on-demand taxes often confuse folks who mix up royalties with sales or miss foreign withholding credits.
Gondaliya CPA offers affordable advice just for businesses like yours in Canada. They help clean up bookkeeping and guide filings based on how online marketplaces work in places like Ontario.
They focus on common issues print-on-demand sellers face and have over 1300 five-star Google reviews.
Booking a consultation lets you fix recordkeeping gaps, plan ahead for filing seasons, and understand the digital platform reporting rules already in force, under which CRA receives your payout totals directly from the platforms.
Resources for First-Time Small Business Tax Filings and Ongoing Support
If it’s your first time filing taxes as a small business, resources can make things clearer. They explain key differences between hobbies versus active businesses — a must when claiming start-up costs, since the question is whether the business had actually commenced before the cost was incurred [Income Tax Act ss. 9(1), 18(1)(a)].
Watch out for mixing personal expenses with business ones — this error often leads to higher tax bills or denied deductions. Many new print-on-demand sellers make such mistakes without knowing it.
Support options include annual flat-fee packages that handle basic financial statements plus GST/HST filings suited to Canada’s e-commerce scene, especially around Toronto but available nationally.
You can also download checklists listing all needed documents before filing deadlines arrive. Being ready cuts last-minute stress during audits focused now more on digital economy businesses like yours working online selling designs or products worldwide.
Frequently Asked Questions on Print on Demand Business Taxes
Frequently Asked Questions
Answers
What is the consequence of reporting the platform’s retail price as revenue?+
Why should royalties not be recorded net of platform fees?+
Can I count inventory for goods I never owned in print-on-demand?+
Are production and shipping costs my business expenses?+
How do I test the place of supply on my own taxable supplies?+
What should I do if foreign platforms deduct withholding tax?+
Should withheld foreign tax be deducted directly as an expense?+
Is converting every payout at one average exchange rate correct?+
How do I separate software, artwork, and stock licenses in accounting?+
Why must hobby and business activities be separated in the first year?+
Essential Insights for Print on Demand Sellers
Essential Insights for Sellers
Key Points
Important tax deadlines and compliance points for print on demand businesses:
- File corporate returns on or before six months after fiscal year-end to avoid penalties.
- Meet payroll deduction remittance deadlines when you have employees to stay compliant.
- Pay tax instalments if required to manage cash flow and avoid interest charges.
- Retain tax records for at least six years as mandated by CRA record retention rules.
- Claim Input Tax Credits (ITCs) only on eligible business expenses with valid documentation.
Managing Foreign Tax Credits and Withholding
- Track all foreign taxes withheld by platforms accurately for credit claims.
- Review foreign withholding amounts yearly against Canadian limits on credits.
- Consult experts to optimize claiming foreign tax credits correctly under ITA sections.
Maintaining Proper Records and Financial Discipline
- Keep original receipts, contracts, and invoices to support deductions and credits.
- Regularly update your bookkeeping to match actual transaction dates and currency rates.
- Separate business from hobby expenses clearly during bookkeeping and tax filings.
For expert guidance on avoiding print-on-demand tax mistakes in Canada, Gondaliya CPA can help you stay compliant and maximize savings. Contact us today!
Businesses We Serve & Industry Spotlights
Industry Expertise
Print-on-demand sellers sit inside a wider group of businesses earning from intellectual property through a platform rather than from stock they own, and the questions that decide a print-on-demand file — what the real revenue figure is, whether anything is actually held as inventory, and who made the supply to whom — recur across every one of these situations.
| Who | The Platform Income Angle |
|---|---|
| Print-on-demand businesses | Gross royalty versus retail price, and no inventory at all |
| Digital product businesses | Place of supply where nothing physical ships |
| Twitch streamers | Platform fees netted off payouts, and barter income |
| Online course creators | Deferred revenue and cross-border digital sales |
| Digital platforms | The reporting obligations sitting on the operator side |
| Cross-border e-commerce sellers | Multi-jurisdiction registration and export evidence |
| Direct-to-consumer brands | Platform fees, advertising spend and currency method |
| Graphic design and creative studios | Commissioned artwork and what rights were actually bought |
| Subscription box businesses | Recurring revenue recognised across periods |
| Side-hustle businesses | The hobby versus business line, and when it is crossed |
| Home-based businesses | Work space in the home and mixed-use equipment |
Spotlights: print-on-demand businesses · digital product businesses · Twitch streamers · online course creators · digital platforms · cross-border e-commerce sellers · direct-to-consumer brands · graphic design and creative studios · subscription box businesses · side-hustle businesses · home-based businesses.
Professional Guidance and Quick Reference
Guidance
Essential Tax Points for Canadian Print on Demand Sellers
Print-on-demand files go wrong in a predictable set of ways: the retail price recorded as revenue when only the royalty was ever yours; platform fees netted off instead of expensed, hiding both sides at once; inventory invented because the accounting template asked for it; production and shipping costs claimed when the platform paid them; registration skipped because the platform charges tax at checkout; a year of payouts converted at one blended rate; and commissioned artwork bought with no record of which rights changed hands. Gondaliya CPA prepares print-on-demand returns on a flat annual fee.
Quick Answers
At a Glance
- What you earn: a royalty on a licence of your design, not a sale of a shirt
- What to report: gross royalty, under subsection 9(1)
- Platform fees: an operating expense, never a reduction of revenue
- Retail price: never yours, and reporting it inflates income against an empty bank account
- Inventory: none, because you never own the product physically or legally
- Production and shipping: the platform’s costs, not yours to claim
- GST/HST threshold: $30,000 of taxable supplies, section 148
- Registration: section 240(1), on your own supplies, whatever the platform charges
- Place of supply: section 142 and Schedule IX, not the shipping address
- Your customer: usually the platform operator, not the end buyer
- Foreign withholding: credit under 126(1) or 126(2), reviewed before anything is deducted
- Currency: each payout at its own date, not one annual average
- Commissioned art: the contract decides whether you bought a licence or the copyright
- T2 schedules: Schedule 125 for revenue, Schedule 9 where a related corporation is involved
- Corporate filing: six months after year-end, subsection 150(1)
- Amending: an amended T2, or the disclosure programme under 220(3.1)
- Platform reporting: Part XX, running since 2024 — CRA already has your payout totals
- Records: six years after the last tax year they relate to
Who This Is For / Not For
Fit Check
- For: Canadian sellers licensing designs through print-on-demand platforms that manufacture and ship on their behalf, whether as a sole proprietor or through a corporation.
- For: sellers whose books show retail prices as revenue, carry an inventory figure for stock they never owned, or have never checked the registration question because the platform charges tax.
- Not for: a province-by-province provincial sales tax guide. PST rules, thresholds and the treatment of a licence rather than a sale of goods differ by province and change often, and the provincial position should be confirmed for each province you sell into.
- Not for: sellers who buy stock, hold it and ship it themselves — that is ordinary e-commerce with real inventory, and the accounting is different throughout.
People Also Ask
Related Questions
The shirt sold for $35 and I got $6. What is my revenue?+
Six dollars, as a gross royalty. The $35 was the platform’s sale to its customer, not yours. You licensed a design and were paid for the licence. Recording $35 inflates your revenue against a bank account that never saw it, throws out the GST/HST threshold calculation, and creates a reconciliation problem that takes longer to explain than it ever took to create.
Do I really have no inventory?+
Correct, and this is the part accounting software fights hardest. The platform buys the blank, prints it and ships it. You never take title to anything, so there is no stock to count, value, write down or report. Any opening or closing inventory figure in a pure print-on-demand business was invented to fill a field, and deleting it usually makes the accounts more accurate rather than less.
The platform charges GST at checkout. Am I registered?+
No. Those are two separate transactions. The platform charges tax on its sale of the shirt to the end customer. Your supply is a licence of artwork to the platform, and whether that obliges you to register turns on your own taxable supplies under sections 148 and 240(1). Nothing the platform does at checkout registers you or files anything for you.
Can I deduct the printing and shipping cost?+
No, because you did not pay it. The platform bears the production and fulfilment cost and keeps it out of what it pays you — that is precisely why your royalty is $6 rather than $35. Claiming it would be deducting someone else’s expense. What you can claim is what you actually spend: design software, commissioned artwork, advertising for your own store.
Can I just convert the year’s payouts at one average rate?+
Not reliably. Each payout should be converted at the rate on its own date. A single blended rate applied to a year of payouts that arrived at different times and in different amounts produces a figure that is wrong in a way nobody can reconstruct later, and it is the kind of thing that turns a short review into a long one.
Glossary of Key Terms
Definitions
- Print-on-demand: a model where a platform manufactures and ships an item carrying your design, on order.
- Royalty: the amount paid to you for the use of your design, and the revenue figure you report.
- Retail price: what the platform charges the end customer, which is not your revenue.
- Platform fee: what the operator retains, recorded as an operating expense rather than netted off.
- Gross reporting: showing revenue before fees, with the fees deducted separately.
- Inventory: stock a business owns, which a print-on-demand seller does not have.
- Place of supply: the rules in section 142 and Schedule IX deciding where a supply is made.
- Small supplier: a business under $30,000 of taxable supplies, defined by section 148.
- Input tax credit (ITC): recovery of GST/HST paid on costs incurred to make taxable supplies.
- Foreign withholding tax: tax a foreign platform deducts before paying you.
- Foreign tax credit: relief under subsection 126(1) or 126(2) for that withheld tax.
- Commissioned artwork: a design bought from another creator, where the contract decides what was acquired.
- Stock licence: a right to use someone else’s image, usually expensed rather than capitalised.
- Schedule 125: the T2 schedule carrying income statement information.
- Schedule 9: the T2 schedule listing related and associated corporations.
- Part XX: the Income Tax Act rules requiring platform operators to report sellers to CRA.
- Voluntary Disclosures Program: the route to penalty and interest relief under subsection 220(3.1).
- Statement of account: the CRA record showing what is outstanding on each program account.
Want a checklist to work from? You can download our free print-on-demand tax checklist before your consultation.
Four things decide a print-on-demand file. What you actually sold — a licence of your design to the platform, not a shirt to a customer, which is why the retail price was never your revenue and the royalty is. How it is recorded — gross under subsection 9(1), with platform fees as an operating expense rather than netted off, because netting hides the revenue and the deduction in a single stroke. What is not there — no inventory to count or value, and no production or shipping cost to claim, since the platform owns the product and bears the cost. And who is obliged to do what — the platform charging tax at checkout does not register you, your own supplies decide that under sections 148 and 240(1), and the Part XX reporting rules have been sending CRA your payout totals since 2024.
Three questions tell you where you stand, and all three are answered from a payout report. First, does your revenue line match what the platform paid you? If it is several times larger, you are recording retail prices. Second, is there an inventory figure in your accounts? If so, it was invented, and it should come out. Third, what rights did you buy with your commissioned artwork? Find the contract now, because reconstructing it from a freelancer two years later rarely works.
Print on Demand Business Taxes Canada: How Gondaliya CPA Can Help
Start with a payout report and your artwork contracts
Gondaliya CPA rebuilds revenue from the payout statements so the royalty rather than the retail price is what appears, itemises platform fees as expenses instead of letting them vanish into a net figure, removes inventory entries for stock that was never owned, tests the registration question against your own taxable supplies rather than what the platform charges at checkout, converts each payout on its own date and documents the method, reviews foreign withholding for credit eligibility before anything is deducted, classifies commissioned artwork and stock licences according to what the contracts actually transferred, and files the T2 with the right schedules — on a flat annual fee including HST with a one-business-day response. Please book a free consultation.
Next Steps
Please book a free consultation with Gondaliya CPA and bring three things: your payout reports from every platform you sell on, your current books if you have them, and the contracts or invoices for any artwork you commissioned. Those three settle the revenue figure, what has to come out of the accounts, and what is genuinely claimable — which between them account for nearly every difficulty we see on a print-on-demand file. If the books show retail prices or an inventory balance, say so at the outset; both are common, both are fixable, and neither is a reason to put off the conversation. Platform reporting means CRA already receives your payout totals, so catch-up work is better raised than found. We advise on Canadian federal tax and GST/HST; provincial sales tax registration should be confirmed for each province you sell into. You will get a flat annual fee including HST before any work begins. We serve Toronto, Mississauga, Brampton, Vaughan, Etobicoke, Scarborough, Hamilton, Ottawa and the rest of Ontario, and work with sellers across Canada. If our content helps, please add gondaliyacpa.ca as a preferred source on Google.
Published: · Last updated:
Editorial policy: We research against CRA, Department of Finance, Parliament of Canada, CPA Canada and CPA Ontario sources, fact-check the figures, and Sharad Gondaliya, CPA, reviews the content, which we update as the rules change.
Disclaimer: This article is educational information only and is not tax, legal or financial advice. It covers Canadian federal income tax and GST/HST for residents running print-on-demand businesses, including gross royalty reporting, platform fees, inventory treatment, registration, place of supply, foreign withholding and corporate filing. Provincial sales tax registration rules, thresholds and the treatment of a licence of intellectual property rather than a sale of goods differ between provinces and change frequently; the provincial position should be confirmed for each province you sell into before relying on it. Thresholds, filing deadlines and statutory references change; every reference should be confirmed against current CRA guidance before a return is filed. Whether an activity is a business or a hobby turns on the full facts. Gondaliya CPA performs compilation engagements under CSRS 4200 and does not perform audit or review engagements. Please consult a licensed CPA before acting.
Sharad Gondaliya is a CPA Canada & CPA USA with 15 Years+ experience of Accounting, Tax, Payroll of Corporate Small Businesses as Tax Accountant. He is a CPA Ontario member (61040184) and holds US CPA licences in Washington and Montana and is well known among corporate small businesses for tax planning, efficient tax solutions, and affordable CPA services. Sharad is the Principal (Director) of Gondaliya CPA – Affordable CPA Firm in Canada. Licenses: CPA Ontario: 61040184 | CPA USA (MT): PAC-CPAP-LIC-033176 | CPA USA (WA): 57629 | CPA Firm License: 61330051 View Full Author Bio