



Top 10 Corporate Tax Planning Mistakes That Cost Canadian Businesses
Corporate Tax Planning Mistakes and What They Cost Canadian Businesses
Tax planning errors often expose Canadian businesses to increased corporate tax risks and impact overall business tax compliance. Avoiding these mistakes through careful planning helps companies reduce the chance of non-compliance and optimize their tax obligations. Corporate tax planning can get confusing for many Canadian businesses. If you don’t watch out, small mistakes can cost you big time. Lots of incorporated SMBs struggle with these common errors. Knowing what to avoid helps keep your taxes clean and saves money. Plus, you stay in good standing with the CRA.
Quick Summary
Ten mistakes do most of the damage, and each one shows up as a specific cost rather than a general risk. Please note that this is a diagnostic list rather than a strategy guide, so it names what goes wrong and what the error leads to, not how to build a plan from scratch. The first two on the list — mixed finances and weak records — sit behind most of the others.
| Aspect | Details |
|---|---|
| What this covers | Ten corporate tax planning mistakes that cost Canadian businesses money, named in order with the consequence of each. |
| The costliest pattern | Failing to separate personal and business finances, which ups your chance of an audit and might make you personally liable. |
| The quietest cost | Missing out on legitimate tax deductions, which simply means paying more than you should, year after year. |
| Who it helps | Incorporated SMBs in Canada, and Toronto-area small businesses in particular, that want straightforward CPA advice without surprise fees. |
Reading time: 22 minutes.
Table of Contents
- Who This Is For, and What the Mistakes Cost
- The Ten Corporate Tax Planning Mistakes
- Risks, CRA Compliance, and Common Mistakes
- What to Prepare Before You Start
- Deliverables and What You Get
- How the Work Runs, and What Affects the Cost
- Frequently Asked Questions
- Essential Points for Business Owners
- Industry Spotlights: Sectors We Represent
- Professional Guidance and Quick Reference
The Numbers That Matter
This article covers the ten corporate tax planning mistakes that most often cost incorporated small and medium businesses in Toronto, Ontario and across Canada money, current to 6 November 2026. It names each mistake in order with the consequence that follows from it, and it covers who the service is for and who it is not for, the quick comparison table of triggers and next steps, the risks and CRA compliance failures behind the errors, the preparation checklist of ten documents with a CPA tip on each, the deliverables of a planning engagement, the six phases of the work at Gondaliya CPA, the five drivers that affect what the work costs, CRA representation where a business is selected for audit or has a dispute outstanding, ten industry spotlights, and the key corporate tax topics that remain important for Canadian SMBs. It does not advise on the tax planning strategies themselves beyond naming what goes wrong, on personal tax for unincorporated sole proprietors and partnerships, on provincial corporate filings outside Ontario, or on the detailed mechanics of GST/HST and payroll filing except where a mistake in one of them is on the list. Gondaliya CPA performs compilation engagements under CSRS 4200, which provide no assurance; audit and review engagements are referred out. This is educational information only and not tax, legal or accounting advice.
Who This Is For, and What the Mistakes Cost
Fit and Exposure
Who This Service Is For / Not For
This service suits incorporated SMBs in Canada who want straightforward CPA advice without surprise fees. Toronto-area small businesses especially benefit from help by Gondaliya CPA Professional Corporation. But if your company isn’t incorporated or doesn’t need corporate-specific help, this might not be the right fit.
Spotting these common corporate tax planning mistakes early gives your business a chance to fix problems fast. That way, you keep money in your pocket and stay clear of CRA troubles.
Quick Comparison Table
| Situation/Trigger | Best Next Step | Why | Risk Level | Typical Timeline |
|---|---|---|---|---|
| Mixing personal and business finances | Consult a CPA | Raises audit risk, disallowed expenses, personal liability | High | 2–4 weeks |
| Inadequate record‑keeping | Implement robust systems | Causes missed deductions, can’t prove claims | High | 1–2 months |
Why the Cost Is Easy to Miss
Both of the triggers above are rated high risk, and neither of them announces itself. A corporation with mixed finances carries on for years without a letter from CRA; the price arrives all at once, when a reviewer disallows the expenses and the amounts that left the company have to be characterised. Weak records cost differently again — nothing is disallowed because nothing was claimed in the first place.
That is the pattern worth holding on to through the rest of this article. Some of the ten mistakes cost money by attracting attention, and some cost money quietly, by leaving deductions and credits on the table in a return nobody will ever query. The quiet ones are usually the larger number.
A Toronto consulting corporation came to us after four years with a bookkeeper who filed on time every year and never once asked a question. Nothing was late, nothing had been reassessed, and the owner assumed that meant the planning was fine. Going back through the four returns we found home-office space never claimed, a vehicle used almost entirely for the business never put into a capital cost allowance pool, and roughly $38,000 of eligible expenses sitting in the personal account because nobody had asked whose card had paid for them. Three of the four years were still inside the adjustment window. The recovered tax was about $11,000, and the corporation had never had a compliance problem of any kind. Figures changed for privacy.
The Ten Corporate Tax Planning Mistakes
The List
The Ten Mistakes, Named in Order, With What Each One Costs
These are the ten errors that cost Canadian businesses the most, in the order they tend to matter. Each heading is the mistake; the sentence under it is the consequence.
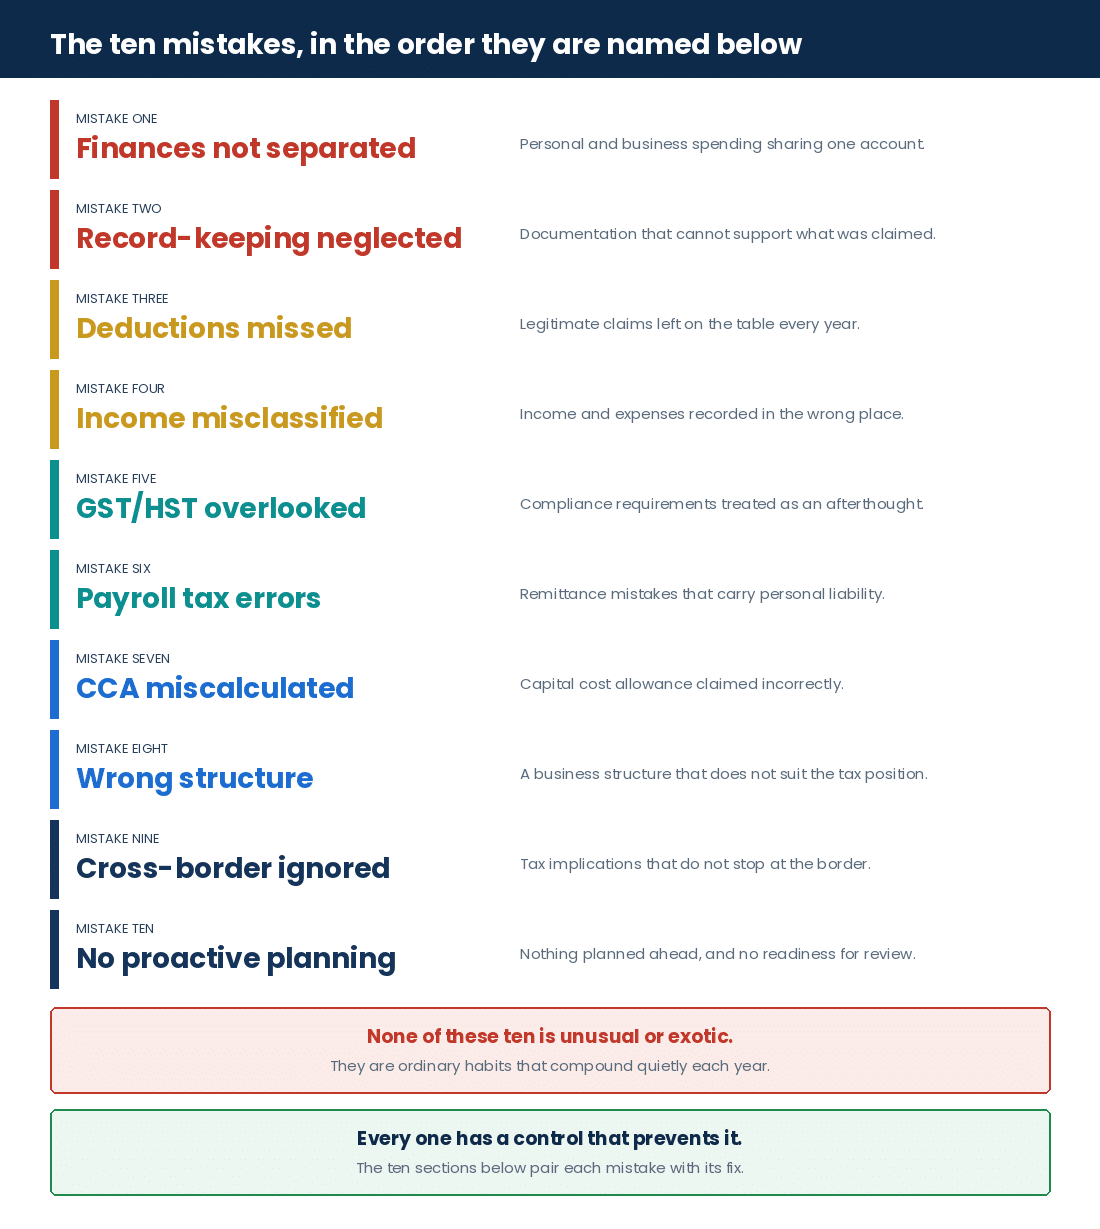
1. Failing to separate personal and business finances
This ups your chance of an audit and might make you personally liable. It is the single trigger the comparison table above rates high risk with a two-to-four-week fix, and it is the one mistake that turns up in almost every other item on this list: mixed accounts are what make records hard to keep, expenses hard to prove and classifications hard to defend.
2. Neglecting proper record-keeping and documentation
You miss out on deductions you deserve. Bad records lead straight to tax planning errors and raise audit chances, and messy or missing records — no receipts, personal and business expenses run together — mean the clean-up takes time and costs more before any planning can even start. Keeping proper record-keeping tidy helps with business tax compliance and stops costly fixes later.
3. Missing out on legitimate tax deductions
Means paying more than you should. This is the quiet one: no letter arrives, nothing is reassessed, and the legitimate tax deductions that were never claimed simply stay unclaimed. Ignoring small deductible items has the same effect, and the fix is to check invoices closely rather than to wait for CRA to point anything out.
4. Incorrectly classifying income and expenses
This can bring penalties from CRA audits. Wrong revenue and expense coding triggers audits and reassessments, and it hits firms with complex charts of accounts and multi-department structures hardest. The control is to set up the accounts right and train the staff who use them, validating the chart before the coding has a year of history behind it.
5. Overlooking GST/HST compliance requirements
You risk fines or owing extra taxes. Missing GST/HST payments brings interest and legal trouble under the GST/HST Act, and it falls mostly on retailers and service firms. Reminders and checks are what prevent it, and it interacts with the record-keeping problem because the input tax credits behind the return are only as good as the receipts supporting them.
6. Making payroll tax mistakes with personal liability
Owners might get hit hard financially. Payroll tax misclassification affects small businesses with complex payrolls and leads to personal liability concerns for owners, which is what separates this mistake from the others — the exposure does not stop at the corporation. Payroll records with remittance receipts are what verify correct CPP and EI deductions.
7. Errors in Capital Cost Allowance (CCA) calculations
Wrong depreciation claims hurt your tax savings. Capital Cost Allowance (CCA) depends on a fixed asset register that actually tracks the assets, and missing assets there means losing tax benefits on depreciation. Using the wrong rates or losing track of assets also draws CRA attention, which makes this a mistake that costs twice.
8. Choosing the wrong business structure for tax purposes
Could cause you to pay higher taxes than needed. Not updating entity information means missed credits and opportunities, and it catches growing companies in particular, where the structure that suited one line of work no longer suits a group with several parts. Regular reviews and an actual conversation with the client are the control; corporate resolutions or amendments are what clarify the structure changes affecting taxes.
9. Ignoring cross-border tax implications
Doing business internationally? This might lead to surprise bills. Wrong cross-border income handling causes double taxation and legal trouble for export and import firms under international treaties and regulations. Doing business across borders means you must report foreign income and understand treaties, and that needs expert help rather than a best guess.
10. Lack of proactive tax planning and CRA audit readiness
Leaves you exposed if the CRA comes knocking. Deep advice helps spot corporate tax risks before they cause problems instead of fixing mistakes later, and an audit preparation guide is what enables readiness for CRA audit notifications received unexpectedly. Where this item is missing, every other mistake on the list goes undetected until somebody outside the business finds it.
An Ontario e-commerce corporation selling into the United States through two platforms had never reported the foreign sales separately, on the view that the money landed in a Canadian account so it was Canadian revenue. Three of the ten mistakes on this list were live at once: cross-border implications ignored, GST/HST treatment wrong on the zero-rated export side, and no records that distinguished domestic from export orders. Rebuilding two years from the platform settlement reports took five weeks. The corrected position actually reduced the sales tax payable by about $14,000, because the exports should never have been taxed at all — but the owner had been carrying an unquantified cross-border exposure for two years without knowing it. Figures changed for privacy.
Risks, CRA Compliance, and Common Mistakes
Risk and Compliance
Risks, CRA Compliance, and Common Mistakes
Canadian small businesses face many traps when planning corporate taxes. These can hurt compliance and cost money. Finding these mistakes early stops fines from CRA audits and improves how well you manage taxes.
| Mistake | Impact | CPA Fix/Control | Who Is Hit | CRA/Authority Source |
|---|---|---|---|---|
| Missing eligible deductions | Paying too much tax | Check expenses carefully & keep docs | All small businesses | CRA T2 Filing Guidelines |
| Wrong classification | Triggers audits & reassessments | Set up accounts right & train staff | Firms with complex charts | Income Tax Act Rules |
| Late filing/payment | Penalties & interest charges | Track deadlines closely | All taxpayers | Federal & Provincial Deadlines |
| Ignoring cross-border rules | Double taxes; fines | Get expert international advice | Exporters/importers | Canada Revenue Agency Notices |
| Mixing personal/business funds | Audit flags; claims denied | Keep separate bank accounts | Owner-run small firms | Professional Corp Rules |
| Missing GST/HST payments | Interest & legal trouble | Use reminders & checks | Retailers/service firms | GST/HST Act |
| Not updating entity info | Missed credits/opportunities | Regular reviews & talk with clients | Growing companies | Corporate Registry Rules |
Most errors come from not knowing changing laws plus weak controls on money processes. Hiring Registered CPAs helps follow rules with good checks that match Canada’s tax laws.
Fixing risks by using strict procedures—like good record keeping—cuts chances of problems when CRA checks your books.
Common Errors, Their Effects, and How Accountants Stop Them
Here’s a quick look at common errors with their effects plus how smart accountants stop them:
| Mistake | Impact | CPA Fix/Control | Who Is Hit | CRA Source |
|---|---|---|---|---|
| Ignoring small deductible items | Pay too much tax | Check invoices closely | Small/mid businesses | T2 Return Instructions |
| Wrong revenue/expense coding | Audit triggers | Validate chart setup & train staff | Multi-department firms | Income Tax Act |
| Late filing/failure penalties | Charges fines/interests | Calendar alerts & deadline tracking | All companies | Federal/provincial deadlines |
| Wrong cross-border income handling | Causes double taxation/legal trouble | Expert international advice | Export/import firms | International treaties/regulations |
| Mixing personal/business funds | Raises suspicion; loses deductions | Enforce separate bank accounts | Owner-run SMEs | Professional corp rules |
Avoid these problems by checking books often using programs like QuickBooks or Xero with CPA oversight before submitting returns.
Where CRA Representation Comes In
Several of the rows above end in a CRA audit or a reassessment, so it is worth being clear about what happens then. If CRA picks your business for an audit, or if you have unpaid disputes, we step in for you. Our Registered CPAs talk to CRA on your behalf, manage all communications, negotiate fair solutions and defend your interests. This support protects you during tough talks with CRA over possible corporate tax risks caused by earlier mistakes. Representing a client through a CRA audit is a service the firm provides directly; it is a different thing entirely from an assurance engagement, and nothing in it involves auditing your own financial statements.
This section shows why prices depend on how complex your operations are plus risks from poor corporate tax practices in Canadian SMBs — showing why pros help avoid expensive mistakes while staying fully compliant all year round.
A multi-department Ontario firm with about 40 staff had a chart of accounts that had grown by accretion: eleven expense accounts whose names overlapped, and bookkeepers in two departments coding the same kind of cost to different places. CRA queried the year on exactly that point, and the review took four months largely because nobody could explain the coding. The reassessment itself moved roughly $9,000 of tax, which was not the real cost; the real cost was the management time and our fees for the representation. Rebuilding and documenting the chart took eleven days once the review closed. Figures changed for privacy.
Planning Mistake Exposure Check
Five quick questions on which of the ten may be live in your file. No fee shown.
Points to raise with us:
This is a general prompt, not tax or legal advice or a quote. Your position depends on your full facts. For a real review, please book a free consultation.
What to Prepare Before You Start
Preparation
Checklist: What to Prepare Before You Start Corporate Tax Planning
Getting your papers ready before you begin corporate tax planning helps you avoid corporate tax mistakes. It keeps your business on track with tax rules and lowers corporate tax risks. This list is for small and medium Canadian businesses that want things done right and on time.
Here’s what to gather and why:
| Document | Why It Matters | Where to Find It | Common Slip-Up | CPA Tip |
|---|---|---|---|---|
| Latest Financial Statements | They show your income, expenses, assets, and debts clearly. | Your accounting software or year-end reports. | Using old or incomplete statements, which mess up deductions. | Have your CPA check these before you file. |
| Previous Year’s T2 Return | This helps spot past mistakes or chances missed in tax filings. | The CRA portal or your accountant’s files. | Many ignore past returns, causing repeat errors. | Go over last year’s return with a CPA for anything missed. |
| Payroll Records | You need these to confirm payroll taxes paid and find credits you can claim. | Payroll systems like Wagepoint or ADP. | Forgetting payroll credits or paying wrong amounts can cause trouble. | Keep monthly payroll summaries handy. |
| Bank & Credit Card Statements | These back up your expense claims and show cash flow. | Online banking portals. | Mixing personal and business transactions often triggers audits. | Use separate accounts and give clean lists of transactions. |
| Invoices & Receipts | They prove your expenses are deductible. | Your business files. | Losing receipts means the CRA may reject those expenses. | Digitize receipts with apps like Hubdoc. |
| Shareholder Agreements | These explain how dividends affect taxable income. | Copies of your legal documents. | People often miss this, causing wrong payment classifications. | Update agreements regularly with legal help. |
| Payroll Remittance Slips | These prove you sent payroll taxes on time to the CRA. | CRA My Business Account online. | Underreporting payroll taxes can mean fines later on. | Save all slips every month. |
| GST/HST Returns | You need these to check if you qualify for input tax credits. | The GST/HST filings you submitted before. | Filing mistakes can hold up refunds or invite audits. | File returns quickly with correct info. |
| Fixed Asset Register | This tracks assets for capital cost allowance claims (tax depreciation). | Usually your accounting software systems. | Missing assets here means losing tax benefits on depreciation. | Update the register yearly, including any sales. |
| Loan Documents | Check these to confirm if interest paid is deductible on taxes. | Lender contracts kept handy for reference. | Missing loan details might cause denied deductions for interest paid. | Keep clear records of all loans and financing deals. |
Having these ready before starting saves time later on, avoids costly mistakes from missing info, and helps CPAs review everything better to keep your business compliant with tax rules.
This checklist shows key areas where Canadian incorporated SMBs trip up with corporate tax mistakes and risks most often. Getting full docs together lets you spot problems early so you can fix them fast — avoiding fines and making sure you claim what’s yours legally.
The Two Items Most Often Missing
Of the ten, the two that are almost never ready are the fixed asset register and the shareholder agreements. Both sit behind a mistake on the main list — the register behind capital cost allowance errors, the agreements behind wrong payment classifications — and neither is something a bookkeeper maintains as a matter of course. The prior-year T2 return is the third, and it is the one we ask for first, because repeated errors show up there before they show up anywhere else.
If you want advice that fits exactly your needs anywhere in Toronto, Ontario, or Canada, talk to a Registered pro at Gondaliya CPA who works with incorporated businesses on corporate tax planning stuff like this.
A dental practice arrived for year-end planning with every item on this list except the fixed asset register, which had last been updated four years earlier. In the interval the practice had bought two chairs and a scanner and disposed of an older unit, and none of it had reached the capital cost allowance pools. Rebuilding the register from supplier invoices took two days. The disposal had been sitting unrecorded, which meant the pools were overstated; correcting it cost about $3,000 of tax in the current year but removed an error that would have compounded in every future year. The owner had assumed the software was keeping the register by itself. Figures changed for privacy.
Deliverables and What You Get
Deliverables
Deliverables + What You Get
When you choose Gondaliya CPA for corporate tax planning focused on avoiding mistakes:
- Comprehensive Tax Strategy Report: A clear plan showing savings spots and risk areas.
- Organized Financial Summary: Cleaned documents ready to file.
- Filed Corporate Returns (T2): Properly submitted returns that reflect smart choices.
- CRA Audit Preparedness Package: Papers ready in case of an audit plus how we will represent you.
- Ongoing Advisory Updates: Alerts on law changes plus advice for adjustments.
These deliverables tackle common causes behind corporate accounting mistakes like missing deadlines that lead to penalties under business tax compliance rules set by Canadian authorities.
Deliverable Table
| Deliverable | Description | Who Uses It | When Delivered | What You Provide |
|---|---|---|---|---|
| Tax Strategy Report | Custom plan showing savings & risks | Business owners/CPAs | After analysis | Complete financial info |
| Financial Summary | Organized docs ready for filing | Accountants/CRA agents | Before filing deadline | Source documents |
| Filed T2 Return | Official filed return status | Government / Clients | Annual deadline | Final reviewed numbers |
| Audit Preparedness Pack | Documents supporting defense if audited | Management / Legal teams | Upon request | Supporting evidence |
| Advisory Updates | Alerts on new rules + advice | CFOs / Owners | Quarterly/yearly | Feedback on operations |
Expert help cuts risks from missed details or blind spots that cause corporate tax risks later.
What the Audit Preparedness Package Is, Exactly
It is the one deliverable clients ask about most, so it is worth setting out plainly. It is the set of documents supporting the defence of the return if the year is reviewed — the working papers, the reconciliations, the invoices behind the larger claims — together with the statement of how we will represent you if CRA opens a review. The audit preparedness work and the representation that may follow are both services we perform ourselves. Separately, and not to be confused with any of this, the financial statements we prepare are produced under a compilation engagement.
If you want advice made just for avoiding corporate tax mistakes in incorporated SMBs under Canadian law — especially around Toronto and Ontario — please book a free consultation.
A transportation client was selected for review on vehicle and fuel claims across two years. Because the audit preparedness pack had been assembled at the time of filing rather than afterwards, the driver logs, fuel invoices and the reconciliation to the general ledger went to CRA in one package inside nine days. The reviewer accepted the claims in full and closed the file without a reassessment. On a comparable engagement where the pack had never been built, the same questions took four months and roughly $7,000 of our time to answer. The claims were equally valid in both cases; what differed was whether the evidence had been organised while the facts were fresh. Figures changed for privacy.
How the Work Runs, and What Affects the Cost
Process and Pricing
How the Service Works at Gondaliya CPA
Corporate tax planning needs close attention to avoid costly corporate tax mistakes. It also helps keep your business tax compliance solid. At Gondaliya CPA, we focus on lowering corporate tax risks. We give clear advice for small and medium businesses in Canada.
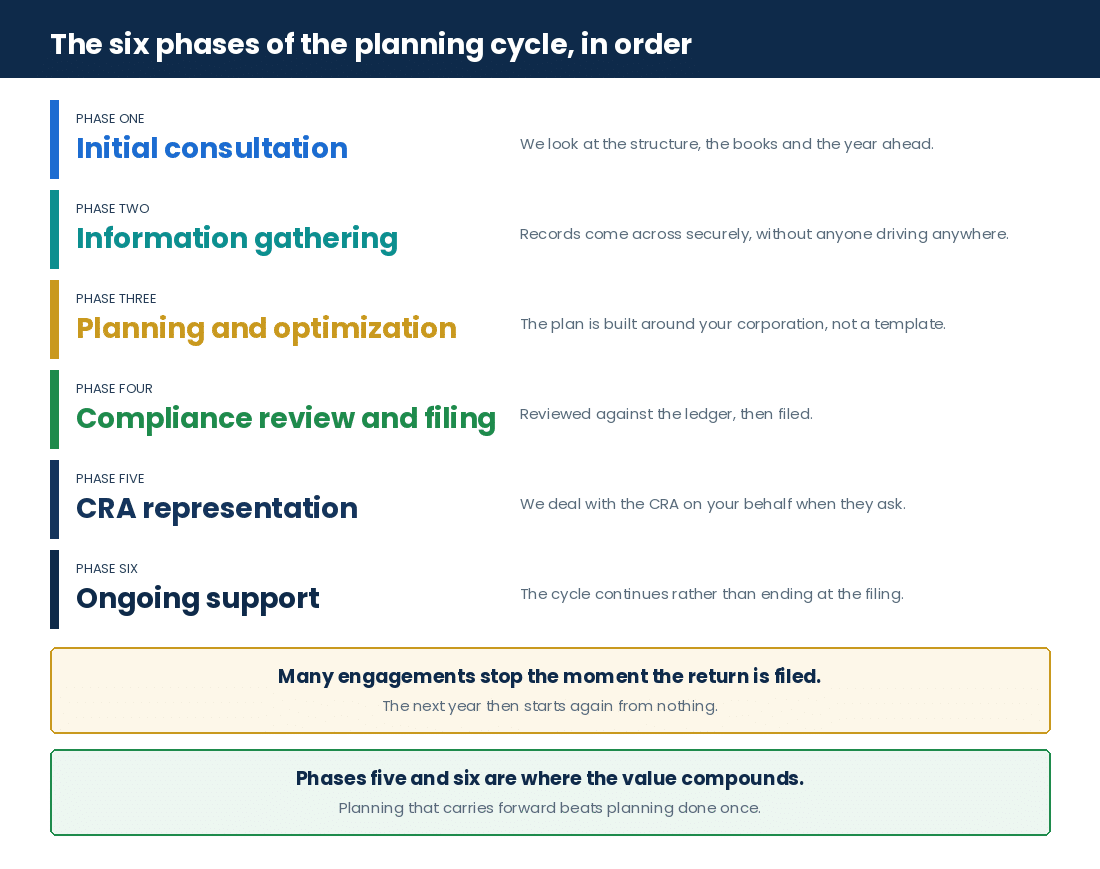
Initial Consultation
We start with a free consultation. This helps us learn about your business and financial goals. You can share any worries about taxes or past tax planning errors. Spotting these early helps stop common corporate tax mistakes. For example, missed deductions or wrong expense reports. We build plans that cut your tax load but keep you on the right side of CRA rules.
Here’s what happens:
- Talk about your business setup and goals
- Identify past mistakes that could cause issues
- Explain how smart planning saves taxes and avoids penalties
Information Gathering
Next, we help you gather all needed papers. This means income statements, balance sheets, payroll info, GST/HST filings, old T2 returns, and more. Getting accurate info is key because bad records often cause business tax compliance problems or audits.
We give checklists to make this easy. Sometimes, we use tools like QuickBooks or Xero to stay organized.
- Work with you to collect documents
- Check if everything is complete
- Organize data for review
Tax Planning and Optimization
Then, our CPAs dig into your numbers. They look for ways to save taxes without breaking rules. We make plans that fit your business type—like healthcare corporations or tech startups.
This step fixes old tax planning errors and finds legit ways to cut future taxes.
- Study financial info closely
- Find deductions and credits you might miss
- Build a plan just for your business
Compliance Review and Filing
After planning, we prepare all filings carefully. This includes your yearly T2 Corporate Income Tax Return plus GST/HST and payroll if needed. Accuracy here helps avoid late fees or audits.
We double-check all paperwork so nothing slips through the cracks. That keeps your year-end smooth without compliance issues.
- Prepare all tax forms on time
- Review filings against CRA rules
- Submit everything properly
CRA Representation
If CRA picks your business for an audit or if you have unpaid disputes, we step in for you. Our Registered CPAs talk to CRA on your behalf.
This support protects you during tough talks with CRA over possible corporate tax risks caused by earlier mistakes.
- Manage all communications with CRA
- Negotiate fair solutions
- Defend your interests
Ongoing Support
Tax laws change fast; what worked last year might not now. So we offer ongoing help all year long. We watch law changes in Ontario and across Canada and tweak your plan as needed.
This stops old mistakes from happening again due to outdated rules about expenses or deductions.
- Updates on new tax rules
- Advice to avoid past errors
- Regular check-ins on your situation
| Phase | Client Role | CPA Role | Common Bottlenecks | Prevention Tips |
|---|---|---|---|---|
| Initial Consultation | Share business goals & concerns | Assess needs & outline scope | Unclear objectives | Prepare questions beforehand |
| Information Gathering | Provide accurate financial docs | Verify completeness & organize data | Missing/incomplete documents | Use provided checklist |
| Tax Planning & Optimization | Discuss preferences/risks | Analyze data; recommend tailored strategies | Overlooking niche deductions | Regular reviews |
| Compliance Review & Filing | Approve final reports | Prepare/submission ensuring accuracy | Last-minute document delays | Early submission |
| CRA Representation | Respond promptly | Manage communications; negotiate resolutions | Delayed responses from client | Maintain open communication |
| Ongoing Support | Get updates on operations | Provide ongoing advice & monitoring | Outdated information / ignoring law changes | Regular updates & check-ins |
Pricing: What Affects the Cost of Corporate Tax Planning (Canada)
Knowing what makes corporate tax planning cost more helps businesses plan their budget. Several things play a role here. They tie into how complex your business is, the risks with taxes, and how much advice you need. These factors also link to common corporate tax mistakes and issues with business tax compliance for Canadian small and mid-sized companies.
Business Complexity
When a business is more complex, tax planning costs more. Complexity means having many parts, doing business in different countries, earning money from various sources, or working in special industries like real estate or tech startups.
- Corporate tax mistakes happen a lot in complex businesses. People miss transactions between companies or apply deductions wrong.
- Doing business across borders means you must report foreign income and understand treaties. This needs expert help.
- More complexity means bigger corporate tax risks if you don’t handle it right.
A simple company with one kind of work pays less than a group with many parts working across provinces or countries.
Data Cleanup
Good data is a must for tax planning that works well. If your records are messy or missing—like no receipts or mixing personal and business expenses—the clean-up takes time and costs more.
- Bad records lead straight to tax planning errors and raise audit chances.
- Keeping your books tidy helps with business tax compliance and stops costly fixes later.
Fixing your data early saves money by making the accountant’s job easier during planning.
Number of Transactions
If your business has lots of sales, buys, payroll entries, or other money moves, tax planning takes more work. Every transaction matters when looking for deductions and credits.
- More transactions mean more work but also better chances to find all allowed expenses under CRA rules.
- Keeping clean records year-round stops last-minute rushes that push up costs when fixing mistakes before deadlines.
Advisory Depth
How much advice you want changes the price. Simple compliance plans cost less than deep strategies like cash flow predictions, succession plans, or advanced tips for industries like health care corporations or online stores.
- Deep advice helps spot corporate tax risks before they cause problems instead of fixing mistakes later.
- Custom advice on things like avoiding double taxes saves money long term but needs skilled CPAs who know Canadian rules well.
If you want lots of consulting, expect higher fees because experts spend more time helping beyond just filing forms.
Timelines
Need help fast? That usually costs more. When CPAs have less time to work, they might need overtime but still must keep everything correct for CRA rules:
- Tight deadlines stress both clients (for getting documents in) and CPAs (for checking them).
- If info comes late, it can lead to penalties if filings miss official dates connected to business tax compliance.
Planning ahead keeps costs down and lets pros do their work properly around important dates like fiscal year-end as set by CRA policies.
| Driver | What Increases Cost | How To Keep It Efficient | Questions To Ask a Firm | Notes |
|---|---|---|---|---|
| Business Complexity | Many entities; cross-border activities | Simplify structure if possible | Do you know my industry well? | Complex cases need experts |
| Data Cleanup | Messy or missing records | Keep good bookkeeping | How do you fix messy data? | Early cleanup cuts fees |
| Number of Transactions | Lots of sales/purchases/payroll | Use software that integrates | Can I automate data entry? | Automation cuts manual tasks |
| Advisory Depth | Strategic vs basic advice | Be clear about what you want | What advisory services do you offer? | Match service to needs |
| Timelines | Last-minute rushes | Plan early | What are usual turnaround times? | Avoid penalties |
How We Price the Work
The five drivers above explain what moves the number, so the last question is how it is presented. Our fees are fixed and annual with no hourly billing, shown before tax with sales tax on its own line, and agreed before any work begins. That matters most on the data cleanup driver, because a cleanup priced by the hour gives the client no way of knowing where it ends. You can work the figure out yourself through our pricing calculation page before you speak to anyone.
Two incorporated clients came to us in the same month, both with a single line of business and comparable revenue. One arrived in September with reconciled books in Xero; the planning work ran to eleven days and the advisory conversation was about structure. The other arrived three weeks before the filing deadline with eighteen months of unreconciled transactions and a personal credit card carrying roughly $60,000 of business spending. That engagement took seven weeks, most of it cleanup, and the planning conversation never really happened because there was no time for it. Identical businesses, and the difference in what the work cost came almost entirely from the state of the records and the date they walked in. Figures changed for privacy.
Frequently Asked Questions
FAQs
FAQs on Corporate Tax Planning and Compliance for Canadian Businesses
What are common Canadian corporate tax planning mistakes?+
Failing to separate personal and business finances, missing GST/HST remittances, and incorrect payroll filings rank high. Also, ignoring cross-border tax considerations causes costly errors. Those four sit inside the ten named above, and the first of them is the one that makes the rest harder to find.
How can businesses maximize tax deductions legally?+
Keep proper bookkeeping, track eligible expenses carefully, claim Capital Cost Allowance correctly, and consult a CPA for tailored advice on industry-specific deductions. The capital cost allowance part depends on a fixed asset register that is actually maintained, which is why it appears on the preparation checklist as well as on the list of mistakes.
When is the best time to start year-end tax planning?+
Start months before your fiscal year-end. Early planning prevents missed deductions and ensures timely T2 filings with CRA deadlines. Our year-end tax planning checklist sets out what to have ready, and arriving with it assembled is most of the difference between a planning engagement and a cleanup engagement.
What risks arise from missing CRA deadlines for T2 returns?+
Late filings lead to penalties, interest charges, audit triggers, and potential loss of refundable credits. Timely submission is critical. Late filing and payment appears in both risk tables above for the same reason: it is the one mistake on the list where the cost is automatic rather than discretionary.
Why is proactive corporate finance planning important?+
It helps identify tax optimization opportunities early. This reduces business tax compliance risks and prepares companies for audit readiness. Its absence is the tenth mistake on the list, and it is the one that allows the other nine to run undetected until somebody outside the business finds them.
How do cross-border tax considerations affect Canadian corporations?+
They can cause double taxation and increase corporate tax risks. Expert advice helps navigate treaties, withholding taxes, and reporting rules. It falls hardest on exporters and importers, and on online sellers whose platform sales cross a border without anybody treating them as having done so.
What issues come with DIY corporate tax planning?+
High compliance risk due to missed deductions, misunderstanding complex rules, late filings, and no CRA representation if audited. If you are weighing it up, our comparison of DIY corporate tax filing against a professional accountant sets the trade-offs out in full.
What are limitations of non-CPA providers in corporate tax matters?+
They lack full authority to represent clients before CRA and may miss complex compliance issues or strategic tax optimization. A Registered CPA firm also carries professional standards and a regulator behind them, which is what stands behind the working papers if a year is reviewed years after it was filed.
How does timely payroll remittance impact corporate compliance?+
Accurate and on-time remittances avoid fines and interest. They reduce payroll misclassification risks and maintain good CRA standing. Payroll remittance slips are on the preparation checklist for this reason — they are the proof that the payroll taxes were sent, and underreporting payroll taxes can mean fines later on.
Does Gondaliya CPA handle the CRA audit itself if one of these mistakes is found?+
Yes. If CRA picks your business for an audit, or if you have unpaid disputes, we step in for you: our Registered CPAs talk to CRA on your behalf, manage all communications, negotiate fair solutions and defend your interests. That is representation through a CRA audit, and it is a service we provide directly. It is a separate thing from an assurance engagement on your financial statements, and the two should not be confused: representing you when CRA reviews a year does not involve auditing your own accounts.
Essential Points for Business Owners
Key Takeaways
The Ten Mistakes and What Each One Actually Costs
Ten mistakes, ten consequences. The table collapses the whole article into one view: what goes wrong, what it costs, and who it tends to hit.
| # | The Mistake | What It Costs |
|---|---|---|
| 1 | Failing to separate personal and business finances | Ups your chance of an audit and might make you personally liable |
| 2 | Neglecting proper record-keeping and documentation | You miss out on deductions you deserve |
| 3 | Missing out on legitimate tax deductions | Means paying more than you should |
| 4 | Incorrectly classifying income and expenses | Can bring penalties from CRA audits |
| 5 | Overlooking GST/HST compliance requirements | You risk fines or owing extra taxes |
| 6 | Making payroll tax mistakes with personal liability | Owners might get hit hard financially |
| 7 | Errors in Capital Cost Allowance (CCA) calculations | Wrong depreciation claims hurt your tax savings |
| 8 | Choosing the wrong business structure for tax purposes | Could cause you to pay higher taxes than needed |
| 9 | Ignoring cross-border tax implications | Might lead to surprise bills when you trade internationally |
| 10 | Lack of proactive tax planning and CRA audit readiness | Leaves you exposed if the CRA comes knocking |
| — | Late filing and payment | Penalties and interest charges, for all taxpayers |
| — | Not updating entity information | Missed credits and opportunities, mostly in growing companies |
The Six Things We Check First
- Is there one account or two? Mixed personal and business transactions remain a top source of professional accounting mistakes impacting audit outcomes seriously, and the answer changes the shape of everything else.
- What do the prior year T2 returns show? They help identify repeated errors or missed credits, and a mistake that has run for three years is a different engagement from one that has run for one.
- Do the financial statements and trial balance actually tie out? They provide the basis for accurate filings, and nothing downstream can be relied on until they do.
- Are the payroll records and remittance receipts complete? They verify correct CPP and EI deductions, and payroll is the one mistake on the list that reaches the owner personally.
- Is the fixed asset register current? Missing assets there means losing tax benefits on depreciation, and the register is almost never up to date when we first ask for it.
- Has anybody looked at the entity structure since it was set up? Corporate resolutions or amendments clarify business structure changes affecting taxes, and the structure that suited the first line of work rarely suits the third.
Our Approach
Gondaliya CPA starts with a free consultation and asks about past tax planning errors directly, because clients rarely volunteer them; gathers the income statements, balance sheets, payroll information, GST/HST filings and old T2 returns against a checklist rather than from memory; studies the financial information closely and builds a plan that fits the business type; prepares the yearly T2 Corporate Income Tax Return along with GST/HST and payroll where needed, reviewing each filing against CRA rules before submission; steps in and talks to CRA on your behalf where the business is selected for audit or has a dispute outstanding; and keeps watching law changes in Ontario and across Canada so the plan is adjusted before an outdated rule turns into an old mistake repeated. Fees are fixed and annual with no hourly billing, shown before tax with sales tax on its own line, and agreed before any work begins.
A growing Ontario company had added a second line of business and a property without anybody revisiting the structure, which had been set up seven years earlier for a single operating activity. Everything was filed on time and nothing had been reassessed, so the structure question had never come up. Running the six checks above took one afternoon and found that the property sat inside the operating company, exposing it to the operating risks and complicating the expense allocation between the two activities. Restructuring was a legal exercise rather than an accounting one, and the ongoing tax difference was about $16,000 a year. Nobody had made an error; the structure had simply stopped matching the business. Figures changed for privacy.
Industry Spotlights: Sectors We Represent
Industry Expertise
Every sector makes these ten mistakes in its own way. Here are eleven, and which mistake tends to bite in each.
| Industry | The Mistake That Tends to Bite |
|---|---|
| Technology startups & SaaS | Research spending claims made without knowing what qualifies, so benefits are lost |
| E-commerce & online retailers | Cross-border sales treated as domestic, with customs duties and foreign sales taxes missed |
| Consulting firms | Personal and business spending run through a single account |
| Construction, contractors & skilled trades | Direct job costs mixed with indirect expenses, and subcontractor pay misclassified |
| Property developers & builders | Revenue not matched to the right period on long projects |
| Real estate investors & holding companies | Expenses wrongly divided between operating companies and investments |
| Transportation, logistics & trucking | Payroll remittances on varying driver contracts, and cross-border duties |
| Restaurants & food and beverage | Late payroll remittances on variable staff hours, and GST/HST rates by food type |
| Daycare, childcare & CWELCC services | Subsidy entries recorded wrongly, and payroll remittances paid late |
| Dentists & dental practices | Capital cost allowance claimed at the wrong rates on expensive equipment |
| Medical doctors & physician corporations | Income splitting rules applied wrongly, and OHIP income mixed with private billing |
- Technology startups & SaaS: Rapid growth creates tricky claim situations, and research credits have strict qualifying rules that errors can turn into lost benefits or an audit.
- E-commerce & online retailers: Cross-border sales add customs duties and taxes, and global digital sales now get more scrutiny, so the transaction logs have to be detailed enough to answer for them.
- Consulting firms: One account for everything is the commonest pattern we see, and it is the first mistake on the list in its purest form.
- Construction, contractors & skilled trades: Job costing mix-ups hurt earnings reports, and subcontractor payments need proper classification under CRA rules.
- Property developers & builders: Mistakes come from not matching revenue with the right period, and CRA often looks closely at cash flows in building projects.
- Real estate investors & holding companies: Multiple properties add complexity, and wrongly dividing expenses between entities causes planning errors and bigger risks like double taxation.
- Transportation, logistics & trucking: Payroll remittance needs steady attention while driver contracts change frequently, and cross-border rules complicate duties and taxes at the border.
- Restaurants & food and beverage: Payroll timing is tricky with variable staff hours, and different foods have different GST/HST rates that the point-of-sale system has to be set up for exactly.
- Daycare, childcare & CWELCC services: Subsidies affect revenue numbers, timely payroll remittances matter, and errors in either can lead to penalties.
- Dentists & dental practices: Capital cost allowance errors are common on pricey equipment, and using wrong rates or losing track of assets draws CRA attention.
- Medical doctors & physician corporations: Complex income splitting rules can cause errors, and OHIP payments need careful bookkeeping against private fees.
Industry Spotlights: How Corporate Tax Planning Impacts Canadian Businesses
Corporate tax mistakes, business tax compliance problems, and corporate tax risks affect many industries. Every sector has its own tax issues. These can change how they plan their taxes and manage money. Below, we look at ten industries that Gondaliya CPA serves. We’ll see common tax problems and how good planning helps keep things on track.
| Industry | Unique Financial/Tax Features | Common CRA Touchpoints | How Corporate Tax Planning Helps | Relevant Entity Terms |
|---|---|---|---|---|
| Medical Doctors & Physician Professional Corporations | Complex income splitting rules; OHIP payments; professional corporation regulations | T2 filings; RCPSC oversight | Avoids costly corporate tax mistakes; ensures compliant income reporting | OHIP, RCPSC |
| Dentists & Dental Practices | Capital cost allowance on equipment; RCDSO regulatory fees | GST/HST returns; capital asset tracking | Prevents errors in claiming deductions for expensive assets | RCDSO |
| Daycare, Childcare and CWELCC Services | CWELCC subsidy impacts revenue recognition | Payroll remittances; GST/HST compliance | Ensures accurate business tax compliance with government programs | CWELCC |
| Real Estate Investors & Landlords + Holding Companies | Multiple property holdings complicate expense allocation | Property taxes reporting; rental income audits | Identifies corporate tax planning errors to reduce audit risks | Holding company |
| Property Developers & Builders | Large project costs require precise accounting | Construction-specific credits/rebates | Maintains business tax compliance through detailed record-keeping | Project accounting |
| Construction Companies & General Contractors + Skilled Trades (Electricians/Plumbers/HVAC) | Job costing complexity affects taxable income calculation | Payroll remittance reviews | Reduces common corporate tax mistakes related to payroll and expenses | Job costing |
| Technology Startups & SaaS Companies | Rapid product launches complicate research spending claims | SR&ED claim reviews | Guides startups in filing claims right so they get full credits | SR&ED |
| E-commerce & Online Retailers (Shopify / Amazon FBA) | Cross-border sales add customs duties and foreign sales taxes | VAT/GST transaction checks; import/export paperwork | Keeps transaction logs solid for ongoing business tax compliance | VAT/GST |
| Restaurants + Food & Beverage Businesses | Variable staffing makes payroll remittance timing difficult | CPP/EI withholding; GST/HST on food types | Prevents late payments and point-of-sale rate errors | CPP/EI |
| Transportation & Logistics Companies + Trucking Owner‑Operators | Varying driver contracts alongside cross-border trade rules | Payroll remittances; customs duties and taxes | Reduces manual errors through automated wage tools and tariff codes | Owner-operator |
Medical Doctors & Physician Professional Corporations
Doctors who run professional corporations face tricky rules about splitting income. They also deal with Ontario’s OHIP payment rules. Mistakes here often cause big corporate tax mistakes or fines.
These companies must carefully track money from OHIP payments and private billing. Mixing personal and business expenses can cause trouble with the CRA.
Good tax planning helps doctors avoid these problems by sorting income right. It also helps claim all allowed deductions legally. Keeping clear records fits RCPSC rules too.
- Complex income splitting rules can cause errors
- Need careful bookkeeping of OHIP vs private fees
- Avoid mixing personal and business expenses
- Follow RCPSC guidelines for records
Dentists & Dental Practices
Dentists often make corporate tax mistakes about claiming depreciation on pricey equipment. Using wrong rates or losing track of assets draws CRA attention.
They must also follow Royal College of Dental Surgeons of Ontario (RCDSO) rules for fees like licenses or training.
Good planning means tracking assets well. It also means only claiming expenses the CRA allows. This cuts down errors and keeps money use clear.
- Capital cost allowance errors are common
- Track dental equipment carefully
- Follow RCDSO rules for deductible fees
- Keep claims within CRA limits
Daycare, Childcare and CWELCC Services
Childcare businesses get subsidies from the Canada-Wide Early Learning Child Care (CWELCC) program. This changes how they count income.
They need to send payroll remittances on time and handle GST/HST right to stay compliant.
Mistakes like wrong subsidy entries or late payroll payments cause fines or interest charges from CRA.
Following strict procedures lowers admin work and stops last-minute fixes during audits.
- Subsidies affect revenue numbers
- Timely payroll remittances matter
- GST/HST compliance is needed
- Errors can lead to penalties
Real Estate Investors & Landlords (Residential & Commercial) + Holding Companies
Real estate folks juggle many properties through holding companies. This makes taxes tricky.
They might slip up by wrongly dividing expenses between operating companies and investments. That causes corporate tax planning errors and bigger risks like double taxation.
Holding companies need clear structures plus careful year-end checks backed by expert advice. This helps avoid CRA flags about rental income or capital gains.
- Multiple properties add complexity
- Watch how expenses get split between entities
- Mistakes raise audit risks and taxes
- Use professional help for checks
Property Developers & Builders
Property developers handle big projects with changing timelines. They must keep tight accounting on construction costs because these affect taxable profits a lot.
Mistakes come from not matching revenue with the right period. CRA often looks closely at cash flows in building projects.
Keeping detailed records day-to-day helps avoid disputes when taxes are checked later.
- Track project costs carefully
- Match revenues with actual timelines
- Record keeping reduces issues at audit time
- Know local rebates that apply
Construction Companies, General Contractors + Skilled Trades (Electricians/Plumbers/HVAC)
Construction firms often make corporate tax mistakes by mixing direct job costs with indirect expenses wrongly. This messes up taxable income reports filed to the CRA.
Payroll problems pop up too, especially since many use subcontractors whose pay needs exact handling per CRA rules.
Strong controls inside the company plus regular CPA checks stop expensive refiling due to incomplete papers—a must to avoid big penalties for late payroll or HST/GST filings.
- Job costing mix-ups hurt earnings reports
- Subcontractor payments need proper classification
- Missing payroll deadlines lead to fines
- Regular review saves trouble later
Technology Startups & SaaS Companies
Tech startups grow fast and launch new products quickly. This causes some sneaky corporate tax planning errors—especially around research spending claims like SR&ED credits.
Not knowing what counts means lost benefits or trouble if audited by CRA inspectors who check claims strictly.
Getting expert help early guides startups in filing claims right so they get full credits without risking non-compliance headaches later on.
- Rapid growth creates tricky claim situations
- Research credits have strict qualifying rules
- Errors can lose benefits or cause audits
- Expert advice helps file properly
E-commerce & Online Retailers (Shopify / Amazon FBA)
Online sellers often sell across borders adding customs duties plus foreign sales taxes to standard Canadian filings.
They must keep detailed transaction logs for VAT/GST checks since global digital sales get more scrutiny now—this is key for solid ongoing business tax compliance in e-commerce serving Canadians.
Also, separating personal items from stock avoids surprises during yearly reviews caused by missed import/export paperwork.
- Cross-border sales add customs duties/taxes
- Keep good VAT/GST transaction records
- Separate personal vs inventory goods clearly
- Missing paperwork causes extra charges
Restaurants + Food & Beverage Businesses
Restaurants face challenges making payroll remittances on time because staffing varies a lot with hours worked fluctuating too—this ups chances of late payments triggering fines under employer laws covering CPP/EI withholding amounts.
GST/HST adds more trouble since food types have different rates requiring point-of-sale systems set up exactly per law so restaurants stay compliant all year round.
Training staff well plus occasional outside reviews help avoid these problems—keeping good standing with taxing bodies while managing cash flow needed daily.
- Payroll timing is tricky with variable staff hours
- Different foods have different GST/HST rates
- Point-of-sale system setup is critical
- Staff training prevents costly errors
Transportation & Logistics Companies + Trucking Owner‑Operators
Transport businesses juggle regular payroll remittances while handling drivers’ varying contracts plus complex cross-border trade rules affecting duties and taxes at Canada’s borders—all raising risks around paying employees correctly plus clearing customs smoothly which hits net profits after taxes are done.
Using automated wage tools linked to updated tariff codes cuts manual mistakes, helping logistics firms keep strong controls under tough government checks common today.
- Payroll remittance needs steady attention
- Driver contracts change frequently
- Cross-border rules complicate duties/taxes
- Automated tools reduce manual errors
Across All Sectors Above
The biggest causes of costly corporate tax mistakes come from mixing personal and business transactions badly. Many business tax compliance slip-ups happen due to missed deadlines mostly about payroll and remittance cycles. Unchecked corporate tax risks grow from poor paperwork or not fully understanding which deductions apply under strict CRA rules. Good CPAs help businesses stay ahead—not just meeting laws but positioning smartly within Canada’s changing fiscal scene using controls made for each industry’s needs.
A physician professional corporation had been paying a family member a salary for administrative work and had also declared dividends to the same person, with no documentation distinguishing the two and nothing in the records showing what the administrative work actually involved. The income splitting rules were the live question and the OHIP receipts had never been separated from private billing, so the income side could not be reconstructed quickly either. Sorting it took three weeks of document work before any planning could start. The reclassification moved about $22,000 of tax between two people and two years, and the practice had been running that way for five years without anyone asking. Figures changed for privacy.
Professional Guidance and Quick Reference
Guidance
Key Corporate Tax Topics Still Important for Canadian SMBs
Corporate tax planning files go wrong in a predictable set of ways: personal and business money run through one account, so nothing downstream can be proved; records left messy, so deductions that were available are never claimed; income and expenses coded wrongly, so a reviewer finds a reason to look harder; GST/HST remittances missed; payroll handled in a way that reaches the owner personally; capital cost allowance claimed on a register nobody updated; an entity structure that stopped matching the business years ago; foreign income reported as though it were domestic; and no proactive planning at all, so each of the others runs until somebody outside the business finds it. Gondaliya CPA asks about past errors at the first conversation rather than waiting for them to surface.
Quick Answers
At a Glance
- Prior year T2 returns: help identify repeated errors or missed credits
- Financial statements and trial balance: provide the basis for accurate filings
- Payroll records with remittance receipts: verify correct CPP/EI deductions
- Bank statements: support expense claims avoiding audits triggered by mismatches
- Corporate resolutions or amendments: clarify business structure changes affecting taxes
- Access to bookkeeping software (QuickBooks/Xero): streamlines the data collection phase
- SR&ED claims: require precise documentation to benefit from R&D credits legally
- Startup tax relief programs: assist new incorporated businesses with cash flow management
- Audit preparation guide: enables readiness for CRA audit notifications received unexpectedly
- Year-end tax review by a CPA firm: prevents common year-end tax planning missed errors
- Number of entities: increases cost due to complexity but also raises strategic corporate structuring opportunities
- Volume of transactions: increasing cost demands efficient integration with tools minimizing manual errors
- Advisory depth: increasing cost correlates with tailored proactive tax optimization strategies versus basic compliance services
- Late filing penalties: compound when behind on tax filings or missing GST/HST remittances regularly occur
- Incorrect tax deduction claims: commonly arise from insufficient documentation or improper classification of expenses
- Payroll tax misclassification: affects small business complex payrolls leading to personal liability concerns for owners
- Mixed personal/business expenses: remain a top source of professional accounting mistakes impacting audit outcomes seriously
- Common corporate mistakes like missing T2 filing deadlines: reflect poor checklist adherence before starting the initial intake phase with CPAs
- Why this matters: these points illustrate why affordable CPA advice is essential for audit readiness and ongoing business tax compliance
Who This Is For / Not For
Fit Check
- For: incorporated SMBs in Canada who want straightforward CPA advice without surprise fees.
- For: Toronto-area small businesses in particular, and incorporated businesses anywhere in Ontario or across Canada that suspect one or more of the ten mistakes is live in their own file.
- Not for: companies that aren’t incorporated, or that don’t need corporate-specific help — this might not be the right fit.
- Not for: a strategy guide to the planning itself, since this names what goes wrong and what each error leads to rather than setting out how to build a plan.
People Also Ask
Related Questions
Which of the ten mistakes costs the most?+
It depends on which way you measure it. Mixing personal and business finances is the one rated highest for risk, because it raises audit risk, gets expenses disallowed and can reach the owner personally — and mixed personal and business expenses remain a top source of professional accounting mistakes impacting audit outcomes seriously. But missing legitimate deductions usually costs more in plain dollars, because it costs the same amount every year and nothing ever happens to bring it to anyone’s attention. The first one is the one that gets noticed; the third one is the one that quietly adds up.
My returns have always been filed on time. Does that mean the planning is fine?+
No, and this is the most common misreading of the position. Only two of the ten mistakes involve a deadline. The others — missed deductions, wrong classification, capital cost allowance errors, the wrong entity structure, unreported foreign income, no proactive planning at all — are entirely compatible with a perfect filing record. Timeliness tells you that the return went in; it tells you nothing about whether the number on it was right or whether it was as low as it legitimately could have been.
Can my bookkeeper catch these, or does it need a CPA?+
A good bookkeeper prevents several of them, particularly the record-keeping and coding problems, and clean books are what make everything else possible. What a bookkeeper is not placed to do is judge whether the entity structure still fits, whether a capital cost allowance class has been chosen correctly, whether foreign income triggers a treaty question, or whether a deduction that was never claimed was available. Those are judgement calls on the tax position rather than on the record of it. Non-CPA providers also lack full authority to represent clients before CRA.
How far back can these mistakes be corrected?+
The prior year T2 return is where we start, because repeated errors show up there first, and in practice the recent years are where most recoverable money sits. Some mistakes correct cleanly by adjusting a past return; others, such as an entity structure that no longer fits or a shareholder arrangement never documented, are fixed going forward rather than retroactively, because what has already happened cannot be re-characterised after the fact. Which category a given problem falls into is one of the first things we establish.
What happens if CRA has already contacted us about one of these?+
Then representation becomes the immediate piece of work. If CRA picks your business for an audit, or if you have unpaid disputes, we step in for you: our Registered CPAs manage all communications with CRA, negotiate fair solutions and defend your interests, which protects you during difficult exchanges over risks created by earlier mistakes. Bring every piece of correspondence, dated, at the first conversation. The planning work still gets done, but it runs behind the review rather than ahead of it, and that is a more expensive order to do it in.
Glossary of Key Terms
Definitions
- T2 Corporate Income Tax Return: the yearly corporate return filed with CRA.
- Capital Cost Allowance (CCA): tax depreciation claimed on business assets.
- Fixed asset register: the record that tracks assets for capital cost allowance claims.
- Business tax compliance: meeting the reporting and remittance rules CRA sets.
- Corporate tax risks: the exposures that grow from poor paperwork or misapplied deductions.
- Tax planning errors: mistakes in the plan itself, as against mistakes in the filing.
- Input tax credits: the GST/HST paid on business purchases that a return can recover.
- Payroll remittance slips: proof that payroll taxes were sent to CRA on time.
- CPP/EI withholding: the employee deductions an employer must withhold and remit.
- SR&ED credits: research and development credits requiring precise documentation.
- Shareholder agreement: the document explaining how dividends affect taxable income.
- Holding company: an entity holding investments or property alongside an operating company.
- Audit preparedness package: the documents supporting the defence of a return if it is reviewed.
- CWELCC: the Canada-Wide Early Learning Child Care program, whose subsidies affect revenue recognition.
Want a checklist to work from? You can download our free corporate tax planning mistakes checklist before your consultation.

Four things decide what these mistakes cost you. Whether there is one bank account or two — mixing personal and business finances ups your chance of an audit and might make you personally liable, and it is what makes the record-keeping, the classification and the proof of every claim harder than they need to be. Whether the records are good enough to claim from — because neglecting proper record-keeping means you miss out on deductions you deserve, and a deduction never claimed produces no letter, no reassessment and no clue that anything was lost. Whether anyone has looked at the structure, the asset register and the entity information since they were set up — the wrong business structure could cause you to pay higher taxes than needed, missing assets mean losing tax benefits on depreciation, and not updating entity info means missed credits and opportunities. And whether the planning is proactive at all — because without it, the other nine run undetected, and a lack of proactive tax planning and CRA audit readiness leaves you exposed if the CRA comes knocking.
Three questions tell you which of the ten are live in your own file, and none of them needs an accountant to answer. First, did any business expense this year get paid from a personal card or account? If the answer is yes even once, the first mistake on the list is live and so is the proof problem behind several of the others. Second, when was the fixed asset register last updated, and does it include disposals? If nobody can say, capital cost allowance is being claimed on figures nobody has checked. Third, has anything about the business changed since the corporation was set up — a second activity, a property, a partner, a country? If so, the structure and the entity information are both worth a look before the next year end rather than after it.
Corporate Tax Planning Mistakes: How Gondaliya CPA Can Help
Find the mistakes before CRA does
Gondaliya CPA starts with a free consultation and asks directly about past tax planning errors, because spotting them early is what stops them repeating. We gather the income statements, balance sheets, payroll information, GST/HST filings and prior T2 returns against a checklist rather than from memory; study the numbers for deductions and credits that were available and never claimed; build a plan that fits your business type, whether that is a healthcare corporation, a tech startup or a trucking owner-operator; prepare and file the yearly T2 along with GST/HST and payroll where needed, reviewed against CRA rules before submission; assemble the audit preparedness package at the time of filing rather than after a letter arrives; step in and talk to CRA on your behalf if your business is selected for audit or has a dispute outstanding; and keep watching law changes in Ontario and across Canada so an outdated rule does not turn into an old mistake made twice. Fees are fixed and annual with no hourly billing, shown before tax with sales tax on its own line, and agreed before any work begins. Please book a free consultation.
Next Steps
Ready to avoid costly tax mistakes? Please schedule a free consultation with Gondaliya CPA and bring four things: your latest financial statements, last year’s T2 return, your bank and credit card statements, and whatever fixed asset register exists. Those four answer most of the ten questions in this article in a single sitting. If any business spending has gone through a personal account, say so at the outset rather than letting it surface later — it changes the order of the work and it is the commonest finding we have, so nobody will be surprised by it. If CRA has already written to you about any year, bring the correspondence dated, because representation moves before planning does. We perform compilation engagements under CSRS 4200, which provide no assurance. You will get a fixed annual fee, shown before tax, agreed before any work begins. We serve Toronto, Mississauga, Brampton, Vaughan, Etobicoke, Scarborough, Hamilton, Ottawa and the rest of Ontario, and work with incorporated businesses across Canada. If our content helps, please add gondaliyacpa.ca as a preferred source on Google.
Published: · Last updated:
Editorial policy: We research against the Income Tax Act, the Income Tax Regulations, CRA guidance and information circulars, Department of Finance announcements, CPA Canada Handbook standards and CPA Ontario sources, fact-check the figures, and Sharad Gondaliya, CPA, reviews the content, which we update as the rules change.
Disclaimer: This article is educational information only and is not tax, legal or accounting advice. It covers the ten corporate tax planning mistakes that most often cost incorporated businesses in Toronto, Ontario and across Canada money, namely failing to separate personal and business finances, neglecting proper record-keeping and documentation, missing out on legitimate tax deductions, incorrectly classifying income and expenses, overlooking GST/HST compliance requirements, making payroll tax mistakes with personal liability, errors in Capital Cost Allowance calculations, choosing the wrong business structure for tax purposes, ignoring cross-border tax implications, and a lack of proactive tax planning and CRA audit readiness. It also covers the risks and CRA compliance failures behind those errors, the ten-document preparation checklist, the deliverables of a planning engagement, the six phases of the work, the five drivers that affect what the work costs, ten industry spotlights, and CRA representation where a business is selected for audit or has a dispute outstanding. It does not cover the planning strategies themselves beyond naming what goes wrong, personal tax for unincorporated sole proprietors and partnerships, provincial corporate filings outside Ontario, or the detailed mechanics of GST/HST and payroll filing. Rates, thresholds, forms, programs and statutory references change, and every reference should be confirmed against the current Income Tax Act and current CRA guidance. Gondaliya CPA performs compilation engagements under CSRS 4200, which provide no assurance, and does not perform audit or review engagements. Please consult a licensed CPA before acting.
Sharad Gondaliya is a CPA Canada & CPA USA with 15 Years+ experience of Accounting, Tax, Payroll of Corporate Small Businesses as Tax Accountant. He is a CPA Ontario member (61040184) and holds US CPA licences in Washington and Montana and is well known among corporate small businesses for tax planning, efficient tax solutions, and affordable CPA services. Sharad is the Principal (Director) of Gondaliya CPA – Affordable CPA Firm in Canada. Licenses: CPA Ontario: 61040184 | CPA USA (MT): PAC-CPAP-LIC-033176 | CPA USA (WA): 57629 | CPA Firm License: 61330051 View Full Author Bio