



How to Maximize Tax Refunds and Reduce Corporate Taxes Through Proper Year-End Filing
Corporate Tax Refund Canada: T2 Filing Optimization and Year-End Tax Savings Guide by Gondaliya CPA
Corporate tax refund Canada can be maximized through proper T2 filing optimization and strategic year-end tax savings. Understanding the T2 return process helps minimize corporate tax burden and ensures accurate corporate tax returns Canada.
The distinction that runs through this whole subject is between reducing tax and recovering tax. Both are worth having, but they work through completely different mechanisms, and corporate year-end accounting and filings should address each on its own terms.
Quick Summary
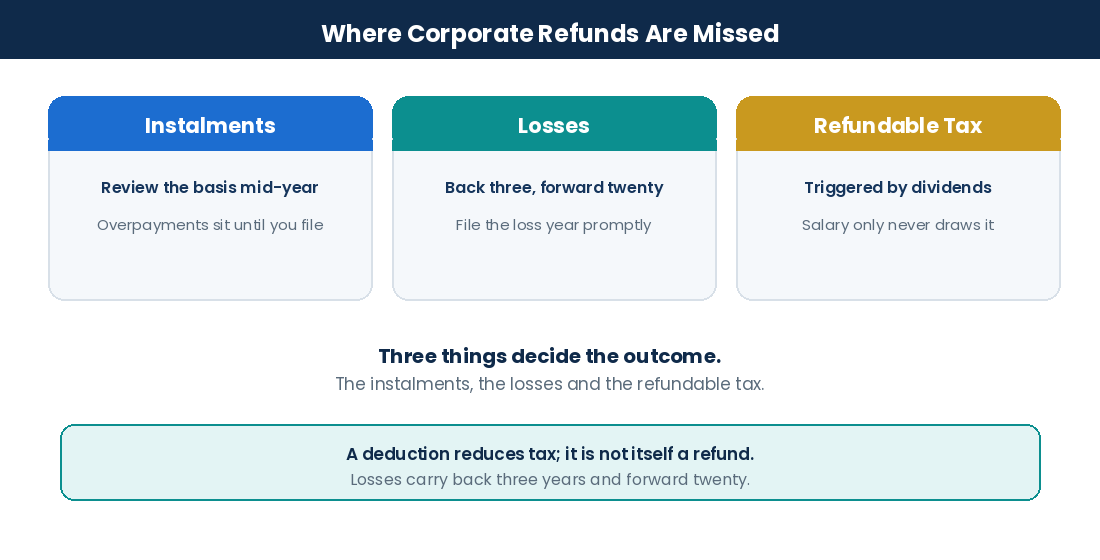
There are four ways a corporation receives money back: overpaid instalments, carrying a loss back to a profitable year, the dividend refund from refundable tax accounts, and refundable credits. Deductions reduce what you owe; they are not a refund mechanism.
Reading time: 52 minutes.
Table of Contents
- Four Ways Money Comes Back
- Instalments and Overpayments
- Losses: Back or Forward
- Refundable Tax and the Dividend Refund
- What Deductions Actually Do
- Filing It Correctly and Working With Us
- Frequently Asked Questions
- The Refund and Reduction Checklist
- Businesses We Serve
- Professional Guidance and Quick Reference
The Numbers That Matter
This article covers Canada, with Ontario and Toronto context, and reflects rules current to 2026. It is written for incorporated Canadian-controlled private corporations. Figures marked illustrative are examples, not quotes, and any masked engagement notes end with “Figures changed for privacy.” This is educational information only and not tax or legal advice. Refund outcomes depend entirely on your own tax accounts, instalment history and loss position, so no article can predict what a particular corporation will receive.
Four Ways Money Comes Back
Four Ways Money Comes Back
The Framing
Reduction Is Not Recovery
Most writing about corporate tax refunds is really about deductions. A deduction lowers taxable income, which lowers the tax you owe. That is valuable, but if you have not already paid the money, there is nothing to send back.
A refund means the CRA returns cash. For a corporation there are four mechanisms, and they are quite different from one another.
| Mechanism | Where the Money Comes From |
|---|---|
| Instalment overpayment | You paid more during the year than the return shows owing |
| Loss carryback | A current loss applied to a profitable earlier year, refunding tax paid then |
| Dividend refund | Refundable tax on investment income, returned when taxable dividends are paid |
| Refundable credits | Credits paid out even where no tax is owing, principally research credits for a CCPC |
Guidance on maximising corporate refunds routinely covers the first and fourth while omitting the second and third entirely. Those two are where most of the recoverable money in an owner-managed corporation actually sits.
Why the Distinction Matters Practically
- Finding an extra deduction in a loss year produces no refund unless you carry the loss back
- A corporation with investment income may be sitting on a refundable balance nobody has drawn
- Overpaid instalments come back automatically, but only once the return is filed
- Refundable credits require a claim, and the claim has its own deadline
- Three of the four are decisions made on the return, so they stay open after year end
That last point is worth holding onto. Most planning closes at your fiscal year end. Refund mechanisms largely do not, which makes them unusually useful when you are already looking backwards.
A Note on Terminology
An assessment is the CRA’s determination of your tax. A reassessment revisits it later. An amended return is your own correction of a return already filed. A refund is cash returned; a credit may or may not be refundable.
Those distinctions matter because the deadlines attached to each are different, and using the wrong route can mean a valid claim arrives too late to be accepted.
Owners ask how to increase the refund and mean how to reduce the tax. They are different questions with different answers, and one of them stays open after year end. Figures changed for privacy.
Risk Warning: A deduction reduces tax owing; it does not generate a refund by itself. Please check the loss carryback and dividend refund positions separately.
Instalments and Overpayments
Instalments and Overpayments
The First Route
How Instalments Actually Work
Corporate instalments are generally monthly. Quarterly instalments are available only to an eligible CCPC meeting conditions, including a clean compliance history and taxable income within the business limit.
Guidance stating that corporate instalments are usually quarterly is not describing the default. Most corporations pay monthly.
| Basis | How It Is Calculated |
|---|---|
| Prior year | Based on the tax payable for the immediately preceding year |
| Current year estimate | Based on what you expect to owe this year |
| Combined method | First payments on the earlier year, the rest on the preceding year |
The choice matters. A corporation having a materially worse year than the last one should not be paying instalments based on a strong prior year, because that is precisely how an overpayment builds up and sits with the CRA until the return is filed.
Where Overpayments Come From
- Instalments set on a prior year that turned out to be much stronger
- A one-time gain in the prior year inflating the instalment base
- Deductions found during preparation that were not anticipated
- Capital cost allowance claimed at a level the estimate did not assume
- A loss carried back reducing tax already paid and covered by instalments
The remedy is not complicated. Review the instalment basis mid-year rather than paying the notice amount by default, and file promptly once the year ends so an overpayment is not sitting idle.
The Balance Owing Date
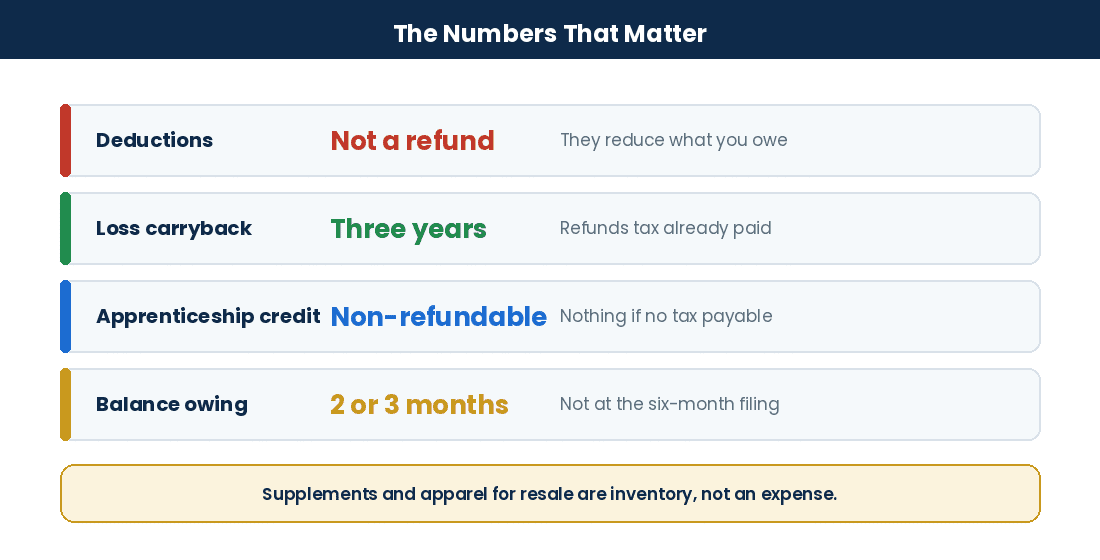
This is the deadline most commonly misunderstood. The balance is due two months after year end, or three months for an eligible CCPC. That is separate from the six-month filing deadline.
A corporation that files on the last day of the sixth month, perfectly on time, can still owe interest on a balance that was due four months earlier. Diarise the two dates separately.
A corporation with a 31 December year end and eligible CCPC status must pay its balance by 31 March and file by 30 June. A business that treats June as its only deadline accrues three months of interest without ever filing late. Figures changed for privacy.
Interest Runs Both Ways
The CRA charges interest on amounts owing and pays interest on overpayments, though not at the same rate and not from the same starting point. Refund interest generally begins later than arrears interest would.
The practical consequence is that an overpayment left with the CRA is not a good place to keep working capital. Recovering it promptly is worth more than the interest it earns.
Filing Speed Matters Here
Where you expect a refund, filing early releases the cash. Where you expect a balance, filing early does not accelerate the payment date, since the balance is due at its own deadline regardless.
So the sensible pattern is: work out roughly where you sit as soon as the year closes, and prioritise filing where a refund is expected.
Better still, form that view before the year closes, while the decisions that shape it are still open. Our guide to corporate tax planning for small and medium businesses sets out what can still be changed at each stage.
Instalments paid on a strong prior year during a weak current year is the most common source of trapped cash. Nothing was wrong; it was simply never reviewed. Figures changed for privacy.
Key Stat: Corporate instalments are generally monthly, not quarterly. Please review the basis mid-year rather than paying the notice amount by default.
Losses: Back or Forward
Losses: Back or Forward
The Real Refund Lever
The Mechanism
A non-capital loss can generally be carried back three years or forward twenty. Carrying it back reduces the taxable income of a prior year, and the CRA refunds tax already paid for that year.
This is the single largest refund mechanism available to most owner-managed corporations, and it is the one absent from most articles about maximising corporate refunds.
| Loss Type | Carry Back | Carry Forward |
|---|---|---|
| Non-capital loss, from business operations | Three years | Twenty years |
| Net capital loss | Three years | Indefinitely, against capital gains only |
Note the restriction on capital losses. They can only shelter capital gains, so a corporation with a large capital loss and no gains has an asset it cannot presently use.
Back or Forward: The Actual Decision
Carrying back produces cash now. Carrying forward produces a deduction later. Neither is automatically better.
- Carry back where the prior year was taxed at a meaningful rate and the cash is useful now
- Carry forward where future years are expected to be taxed higher, so the deduction is worth more
- Consider that the prior year may have been sheltered by the small business rate already
- Consider the passive income and taxable capital grinds, which can change the applicable rate
- You can split a loss, carrying part back and part forward
The splitting point is underused. There is no requirement to send the whole loss in one direction, and the optimal split depends on the rates in each of the years involved.
How It Is Claimed
A carryback is requested on the schedule accompanying the return for the loss year, rather than by amending the earlier return. That is a mechanical detail with practical consequences: the request is made once, with the loss year filing, and it identifies which prior years the loss is being applied to and in what amounts.
Please note that a request made properly with the return is processed as a normal part of the assessment. Attempting the same thing by writing to ask for an adjustment to the earlier year is a slower route.
Timing
The loss must be determined before it can be carried anywhere, which means the loss year return has to be prepared. A corporation delaying the filing of a loss year is delaying its own refund.
Where a business has just had a difficult year following profitable ones, that return should be prioritised rather than left because “there is no tax to pay.” There may well be a refund to collect.
What Can Restrict a Loss
- An acquisition of control can restrict the use of losses that arose before it
- Losses from a business that has ceased can face restrictions on future use
- The loss has to be genuinely computed, not simply the accounting result
- Capital losses cannot shelter business income
The acquisition of control point matters where a corporation is being bought or restructured. Losses that looked like an asset in the deal can be substantially restricted afterwards, which is a question to ask before the transaction rather than after.
A loss year return left unfiled because there was no tax to pay is money sitting on the table. The carryback refunds tax paid in the good years. Figures changed for privacy.
Key Stat: A non-capital loss carries back three years and forward twenty, and it can be split between the two. Please model the split rather than defaulting.
Refundable Tax and the Dividend Refund
Refundable Tax and the Dividend Refund
The Overlooked One
Why Investment Income Is Taxed Twice Over
Investment income earned inside a corporation is taxed at a high corporate rate, materially higher than the rate on active business income. Owners often see that rate and conclude the corporation is a bad place to hold investments.
A portion of that tax is refundable. It is not a penalty; it is a prepayment. The corporation gets it back when it pays taxable dividends to shareholders, which is the mechanism that makes the overall system approximately neutral.
This is called the dividend refund, and it is tracked in notional accounts alongside the corporation’s other balances.
How It Works in Practice
| Step | What Happens |
|---|---|
| The corporation earns investment income | Tax is paid at the high rate, part of it refundable |
| The refundable portion accumulates | Tracked in a notional balance, not a bank account |
| The corporation pays a taxable dividend | A refund is triggered, based on the dividend paid |
| The shareholder reports the dividend | Personal tax applies, with the dividend tax credit |
| No dividend is ever paid | The balance simply sits there, unrecovered |
The last row is the problem. A corporation that has earned investment income for years and paid its owner by salary only may have accumulated a meaningful refundable balance that nobody has drawn.
Note also that the accounts are split between amounts arising from eligible and non-eligible dividends received and from other investment income, and the type of dividend paid affects which balance is recovered. Getting the designation right matters.
What to Check
- Whether the corporation has any refundable balance at all
- Whether it has been correctly tracked across prior returns
- Whether a dividend this year would trigger a recovery
- Which balance a given dividend would draw from
- How the resulting personal tax compares to the refund recovered
The last point keeps this honest. Paying a dividend purely to trigger a corporate refund creates personal tax, so the exercise is only worthwhile where the shareholder wanted funds anyway or where the combined arithmetic works.
The Capital Dividend Account
Separately, the non-taxable portion of capital gains and certain life insurance proceeds accumulate in an account that can be paid to shareholders tax-free, with an election filed.
This is not a refund from the CRA, but it is money leaving the corporation without tax, which for the shareholder amounts to the same thing. It is the item owners are least likely to know they have.
A corporation that has realised capital gains at any point may have a balance available. It is worth checking rather than assuming there is nothing there, and the election has to be filed before or at the time the dividend becomes payable.
Refundable balances sitting unrecovered because the owner takes salary only is common. The corporation paid the tax; nobody triggered the refund. Figures changed for privacy.
Pro Tip: Please check both the refundable tax balance and the capital dividend account before deciding how the owner is paid this year.
What Deductions Actually Do
What Deductions Actually Do
The Reduction Side
Refundable Against Non-Refundable Credits
Credits are frequently discussed as though they all produce cash. Most do not.
| Credit | Position |
|---|---|
| SR&ED investment tax credit for a qualifying CCPC | Refundable on qualifying expenditures, at an enhanced rate |
| SR&ED for other corporations | Generally non-refundable, reducing tax owing |
| Apprenticeship job creation tax credit | Non-refundable, despite frequent claims otherwise |
| Most other investment tax credits | Generally non-refundable, with carryover provisions |
| Unused non-refundable credits | Often carried back three years or forward |
The apprenticeship credit is worth correcting specifically. It is a non-refundable credit against tax payable, calculated on eligible apprentice wages up to a maximum per apprentice. Guidance describing it as providing refundable amounts is wrong, and a corporation with no tax payable receives nothing from it in that year.
On SR&ED timing, please note the CRA publishes service standards measured in months rather than weeks. Claims quoting a four to six week turnaround are not describing the published standard.
Deductions Worth Reviewing
- Capital cost allowance, including the incentive reinstated by Bill C-15
- Accrued costs incurred but not yet invoiced at year end
- Bonuses declared before year end and paid within the allowed period
- Bad debts written off with the collection record behind them
- Obsolete or damaged inventory written down with evidence
- Professional and financing fees
- Charitable donations, subject to the limits
Two corrections belong here because they appear constantly in corporate guidance written from a sole proprietor template.
First, a corporation does not prorate vehicle costs by business use. It claims them in full and reports a taxable benefit where there is personal use. Second, the individual home office deduction rules are not how a corporation handles an owner working from home; that is addressed through a documented arrangement, not by claiming a share of household costs on the T2.
Protecting the Rate
The largest single reduction available is the small business deduction, giving a reduced federal rate of 9% on active business income up to the federal business limit of $500,000. Three things erode it.
- Association, where corporations share one limit between them
- The passive income grind, reducing the limit by $5 per $1 of investment income above $50,000
- The taxable capital grind, reducing it where the balance sheet across the group is large
The passive grind uses the prior year’s investment income to reduce the current year’s limit, which gives a year of warning if anyone is tracking it.
Where the corporation is genuinely doing development work, refundable research credits sit alongside these reductions rather than competing with them, and our overview of SR&ED tax credits covers what qualifies and what the documentation has to show.
Family Remuneration and Split Income
This needs stating carefully, because corporate guidance regularly presents income splitting as a straightforward saving and it has not been for some years.
Paying a spouse or adult child a salary is legitimate where they genuinely work in the business and the amount is reasonable for the work done. Keep the record of duties, hours and how the rate was set.
Dividends to family members are a different matter. The tax on split income rules apply the top marginal rate to split income unless a specific exclusion is met, and whether an exclusion applies depends on actual involvement in the business, age, and the nature of the business. Guidance saying income splitting simply shifts income to lower-taxed family members is describing a position that no longer holds generally.
Please have this reviewed on your own facts rather than assumed, since the consequence of getting it wrong is tax at the highest rate.
Income splitting described as a simple saving is the most dated advice still circulating. The split income rules changed the answer, and the exclusions are fact-specific. Figures changed for privacy.
Risk Warning: The apprenticeship job creation credit is non-refundable. Please do not plan cash flow around receiving it where no tax is payable.
Filing It Correctly and Working With Gondaliya CPA
Filing It Correctly and Working With Us
The Return
The Schedules, Correctly Named
| Schedule | What It Actually Is |
|---|---|
| Schedule 1 | Reconciliation of net income for tax purposes |
| Schedule 100 | Balance sheet information |
| Schedule 125 | Income statement information |
| Schedule 141 | Notes checklist, on who prepared the statements |
| Schedule 8 | Capital cost allowance |
| Schedule 50 | Shareholder information |
| Schedule 4 | Continuity of losses and loss application |
| Schedule 3 | Dividends received and paid, and the dividend refund |
Three of these are commonly mislabelled in corporate tax guidance. Schedule 125 is the income statement, not the balance sheet. Schedule 100 is the balance sheet. And Schedule 141 is the notes checklist recording who prepared the financial statements and on what basis, not a summary of dispositions.
The Schedule 141 point matters more than it sounds. It is where the level of assurance is declared, and it should match the engagement actually performed.
What the Financial Statements Are Prepared Under
Private Canadian corporations generally report under Accounting Standards for Private Enterprises. The term “Canadian GAAP” as a current standard for private companies is dated; ASPE replaced it.
Most owner-managed corporations receive a compilation engagement under CSRS 4200, which produces financial statements from information you provide and gives no assurance. It replaced the former Notice to Reader. A compilation is not a review and confirms nothing, which is worth knowing before describing it to a lender.
The trial balance maps to GIFI codes populating the financial schedules, which is why a clean trial balance makes the whole return straightforward. Where the books need correcting first, that work comes before the return rather than during it, and our page on bank reconciliation covers the starting point.
Deadlines
| Obligation | Deadline | If Missed |
|---|---|---|
| T2 corporate return | Six months after fiscal year end | 5% of unpaid tax plus 1% per complete month, to twelve |
| Balance owing | Two months, or three for an eligible CCPC | Interest from the due date |
| Instalments | Monthly, or quarterly if eligible | Instalment interest |
| T4, T4A and T5 slips | Last day of February | Penalty by slip count |
A repeated late-filing penalty can apply at a higher rate where the CRA has demanded a return and a late-filing penalty was assessed in one of the three preceding years, so the exposure grows with a pattern rather than a single lapse.
Correcting Past Returns
- Amend where a deduction or credit was missed, within the reassessment period
- Request a loss carryback on the loss year return rather than by amending the earlier year
- Object within 90 days where you disagree with an assessment
- Ask for taxpayer relief where penalties arose from circumstances beyond your control
- Use voluntary disclosure where something was reported incorrectly and carries a penalty
Where a past filing was wrong in a way that could attract a penalty, the Voluntary Disclosures Program may help, provided you come forward before the CRA raises the issue. Our CRA audit guide covers what a review involves.
What We Do
We support incorporated businesses on a flat annual fee covering bookkeeping through the year, the pre-year-end review while decisions are still open, reconciliation and cleanup, compilation financial statements under CSRS 4200, capital cost allowance with the reinstated incentive, instalment basis review, loss carryback and carryforward modelling, refundable tax and capital dividend account review, owner remuneration, the corporate return and support if the CRA follows up.
Pricing is quoted before any work begins, including HST, with a one-business-day response and evening and weekend availability. Our engagements carry a 30-day money-back arrangement and a 60-day fee-matching arrangement.
Getting Started
Bring three things: your last two filed corporate returns, a current trial balance, and your instalment history for the year. Those show us whether a refund is sitting unclaimed, whether the instalment basis is right, and what remains to fix.
Contact Gondaliya CPA at info@gondaliyacpa.ca, call 647-212-9559, or send us a message.
The last two returns and the instalment history answer the refund question quickly. Everything recoverable shows up in those three documents. Figures changed for privacy.
Risk Warning: Schedule 125 is the income statement and Schedule 141 is the notes checklist. Please do not rely on guidance that labels them otherwise.
FAQs on Corporate Refunds and T2 Filing
Frequently Asked Questions
FAQ
Does a deduction give me a refund?+
No. A deduction reduces taxable income and therefore tax owing. A refund requires that tax has already been paid, or that a credit is refundable. They are different mechanisms.
What are the actual ways a corporation gets money back?+
Four: overpaid instalments, carrying a loss back to a profitable year, the dividend refund from refundable tax accounts, and refundable credits such as SR&ED for a qualifying CCPC.
Are corporate instalments monthly or quarterly?+
Generally monthly. Quarterly is available only to an eligible CCPC meeting conditions including a clean compliance history. Guidance saying instalments are usually quarterly is not describing the default.
When is my balance owing due?+
Two months after year end, or three for an eligible CCPC. That is separate from the six-month filing deadline, so a corporation filing on time can still owe interest.
How far back can I carry a loss?+
A non-capital loss carries back three years and forward twenty. A net capital loss carries back three years and forward indefinitely, but only against capital gains.
Should I carry a loss back or forward?+
Carrying back refunds tax already paid, which is cash now. Carrying forward is worth more if future years will be taxed higher. You can split the loss between the two.
How is a loss carryback claimed?+
On the schedule filed with the loss year return, identifying which prior years the loss applies to and in what amounts, rather than by amending the earlier return.
Should I file a loss year return if no tax is owing?+
Yes, and promptly. The loss cannot be carried back until it is determined, so delaying the filing delays a refund of tax paid in the profitable years.
What is the dividend refund?+
Investment income in a corporation is taxed at a high rate, part of which is refundable. The corporation recovers it when taxable dividends are paid, which is what makes the system approximately neutral.
Could my corporation have an unclaimed refundable balance?+
Possibly, if it has earned investment income and the owner has been paid by salary only. The balance accumulates and simply sits there until a taxable dividend triggers the recovery.
What is the capital dividend account?+
A notional account holding the non-taxable portion of capital gains and certain insurance proceeds, payable to shareholders tax-free with an election filed. It is the item owners are least likely to know they have.
Is the apprenticeship job creation credit refundable?+
No. It is non-refundable, applied against tax payable and calculated on eligible apprentice wages up to a maximum per apprentice. A corporation with no tax payable receives nothing from it that year.
How quickly are SR&ED claims processed?+
The CRA publishes service standards measured in months rather than weeks. Guidance quoting a four to six week turnaround is not describing the published standard.
Can I split income with family members?+
Paying a salary for genuine work at a reasonable amount is legitimate. Dividends raise split income rules that apply the top rate unless an exclusion is met, so the old general approach no longer holds.
Does my corporation prorate vehicle costs by business use?+
No. That is the sole proprietor method. A corporation claims the costs in full and reports a taxable benefit for personal use by a driver.
Which schedule is the income statement?+
Schedule 125. Schedule 100 is the balance sheet and Schedule 141 is the notes checklist recording who prepared the financial statements. These are frequently mislabelled.
Sixteen questions and one underneath most of them: is this reducing tax or recovering it. Two different answers, two different deadlines. Figures changed for privacy.
The Refund and Reduction Checklist
The Refund and Reduction Checklist
Quick Reference
Recovering Money
- Review the instalment basis mid-year, not just the notice amount.
- Remember instalments are generally monthly, not quarterly.
- File promptly where a refund is expected.
- File a loss year return even where no tax is owing.
- Model carrying the loss back three years against forward twenty.
- Consider splitting a loss between back and forward.
- Claim the carryback on the loss year return, not by amending.
- Check whether a refundable tax balance has accumulated.
- Check which balance a given dividend would recover.
- Check the capital dividend account before paying an ordinary dividend.
- Confirm which credits are actually refundable before relying on them.
Reducing Tax
- Protect the small business limit against all three reductions.
- Confirm association before assuming a second limit exists.
- Watch the passive income grind from the prior year’s investment income.
- Watch the taxable capital grind if the balance sheet is large.
- Apply the reinstated investment incentive to assets acquired after 2024.
- Treat the capital cost allowance claim as discretionary.
- Accrue costs incurred but not invoiced at year end.
- Declare bonuses before year end and pay within the allowed period.
- Write off bad debts and obsolete stock with evidence.
- Claim vehicle costs in full and report a benefit rather than prorating.
Filing and Correcting
- Diarise the balance date separately from the filing date.
- Confirm the level of assurance declared on the notes checklist.
- Use the correct schedule for each purpose.
- Have family remuneration reviewed against the split income rules.
- Amend within the reassessment period where something was missed.
- Object within 90 days if you disagree with an assessment.
- Request taxpayer relief where circumstances were beyond your control.
- Consider voluntary disclosure before the CRA makes contact.
- Keep six years of records supporting every position taken.
For a review of what your corporation may be able to recover, contact Gondaliya CPA at info@gondaliyacpa.ca, call 647-212-9559, or book a free consultation.
Thirty points across two columns, and the columns matter. One list recovers money already paid; the other reduces what you will pay. Figures changed for privacy.
Businesses We Serve
Industry Expertise
Which route matters most differs by the corporation. Here are ten and the usual one.
| Situation | Where the Recovery Sits |
|---|---|
| A loss year after profitable ones | The three-year loss carryback |
| Instalments set on a strong prior year | Overpayment released on filing |
| Investment income held in the company | The dividend refund balance |
| Owner paid by salary only for years | Refundable tax never triggered |
| Past capital gains realised | The capital dividend account |
| Genuine development work | Refundable research credits for a CCPC |
| Equipment bought since 2024 | The reinstated investment incentive |
| Investment income above the threshold | The grind on next year’s business limit |
| Two or more corporations | One shared limit, not one each |
| A return filed with something missed | Amendment within the reassessment period |
- A loss year after profitable ones: File it, do not park it.
- Instalments set on a strong prior year: Review the basis.
- Investment income held in the company: It is a prepayment.
- Owner paid by salary only for years: Nobody drew it down.
- Past capital gains realised: That portion comes out tax-free.
- Genuine development work: Refundable, but claim it properly.
- Equipment bought since 2024: The first-year claim changed.
- Investment income above the threshold: A year of warning.
- Two or more corporations: Confirm before assuming.
- A return filed with something missed: Usually still fixable.
The situation changes which route applies. It does not change the question, which is whether you are trying to reduce tax you will pay or recover tax you already paid. Figures changed for privacy.
Professional Guidance and Quick Reference
Guidance
Professional Guidance: How Gondaliya CPA Handles Your Corporate Return
Corporations lose money in a predictable set of ways: treating deductions as though they generate refunds when they only reduce tax owing, leaving a loss year return unfiled because no tax is payable and therefore never carrying the loss back to refund tax paid in profitable years, paying instalments on a strong prior year through a weak current one, accumulating refundable tax on investment income that no dividend ever triggers, never checking the capital dividend account, planning cash flow around credits that turn out to be non-refundable, and treating the six-month filing deadline as though the balance were also due then. Gondaliya CPA prepares corporate returns on a fixed annual fee.
We handle what decides the outcome: reviewing the instalment basis during the year rather than paying the notice amount, filing loss years promptly and modelling the carryback against the carryforward including a split, checking refundable tax balances and the capital dividend account before owner remuneration is set, confirming which credits are actually refundable, protecting the small business limit against association and both grinds, and applying the reinstated investment incentive.
Our team starts with your last two filed returns, a current trial balance and your instalment history. Those three show whether anything recoverable is sitting unclaimed. Whatever your sector, you get clear advice and a fixed price before we start.
Quick Answers
- Deductions: Reduce tax, do not refund it
- Four routes: Instalments, losses, dividends, credits
- Loss carryback: Three years
- Loss carryforward: Twenty years
- Instalments: Monthly unless eligible for quarterly
- Balance owing: Two or three months after year end
- Dividend refund: Triggered by paying taxable dividends
- Capital dividend account: Comes out tax-free
- Apprenticeship credit: Non-refundable
- Schedule 125: Income statement, not balance sheet
Who This Is For
- For: Incorporated Canadian-controlled private corporations preparing a corporate return, reviewing a filed one, or planning ahead of a fiscal year end.
- Not For: A prediction of what any particular corporation will receive, since refund outcomes depend entirely on your own tax accounts, instalment history and loss position.
People Also Ask
What does a compilation engagement provide?+
No assurance. A compilation under CSRS 4200 produces statements from information you provide and replaced the former Notice to Reader. It is not a review and confirms nothing.
Do private companies still use Canadian GAAP?+
That terminology is dated. Private Canadian corporations generally report under Accounting Standards for Private Enterprises.
What happens if I file late repeatedly?+
A higher penalty can apply where the CRA has demanded a return and a late-filing penalty was assessed in one of the three preceding years, so the exposure grows with a pattern.
Glossary of Key Terms
- T2: The corporation income tax return.
- CCPC: A Canadian-controlled private corporation.
- Instalment: A payment made during the year against expected tax.
- Non-capital loss: A business loss carried back three or forward twenty years.
- Net capital loss: Carried back three years, forward indefinitely, against gains only.
- Dividend refund: Recovery of refundable tax when taxable dividends are paid.
- Capital dividend account: A balance payable to shareholders tax-free.
- Refundable credit: A credit paid out even where no tax is owing.
- Non-refundable credit: A credit applied only against tax payable.
- Business limit: The income eligible for the small business rate.
- Passive income grind: Reduction of the limit above investment income of 50,000 dollars.
- Taxable capital grind: Reduction of the limit where the balance sheet is large.
- Split income: Amounts taxed at the top rate unless an exclusion applies.
- GIFI: The coding system mapping your accounts onto the return.
- ASPE: Accounting Standards for Private Enterprises.
- Compilation engagement: Statements prepared under CSRS 4200 with no assurance.
Corporate Refund Check
This quick self-check indicates where your operation most likely has room. Please answer the six questions below.
Corporate Refund Check
Six quick questions on your corporation. No fee shown.
Points to raise with us:
This is a general prompt, not tax or legal advice or a quote. Your position depends on your full facts. For a real review, please book a free consultation.
Want a checklist to work from? You can download our free corporate refund and reduction checklist before your consultation.
Understand that deductions reduce tax while only four mechanisms refund it. Review the instalment basis mid-year. File loss years promptly and model the carryback. Check the refundable tax balance and the capital dividend account. Confirm which credits are refundable. Pay the balance two or three months after year end. Please keep six years of records.
2026 Update — what is current: This article reflects rules current to 2026. The federal small business limit of $500,000 at a 9% federal rate, the $50,000 passive income threshold with the limit reduced by $5 per $1 above it, the three-year carryback and twenty-year carryforward for non-capital losses, the six-month T2 filing deadline, the 5% plus 1% per month late-filing penalty, the 90-day objection period, the end-of-February slip deadline and the six-year retention requirement are unchanged. Bill C-15 received Royal Assent on 26 March 2026, reinstating the accelerated investment incentive for most depreciable property acquired after 2024 and available for use before 2030. Please note that a deduction reduces tax owing rather than generating a refund, and that the four mechanisms producing an actual refund are instalment overpayment, loss carryback, the dividend refund from refundable tax accounts and refundable credits; that corporate instalments are generally monthly, with quarterly available only to an eligible CCPC; that the balance owing is due two or three months after year end rather than at the six-month filing deadline; that the apprenticeship job creation tax credit is non-refundable; that split income rules apply the top marginal rate unless an exclusion is met, so income splitting is no longer the straightforward saving older guidance describes; that Schedule 100 is the balance sheet, Schedule 125 the income statement and Schedule 141 the notes checklist; and that private corporations report under ASPE rather than the dated Canadian GAAP terminology, with a CSRS 4200 compilation engagement providing no assurance.
Corporate Tax Refund Canada: How Gondaliya CPA Supports Incorporated Businesses
Start with the last two returns
Gondaliya CPA reviews the instalment basis during the year rather than paying the notice amount, files loss years promptly and models the carryback against the carryforward including a split between them, checks refundable tax balances and the capital dividend account before owner remuneration is set, confirms which credits are actually refundable, protects the small business limit against association and both grinds and applies the reinstated investment incentive, on a flat annual fee including HST with a one-business-day response. Please book a free consultation.
Next Steps
Please book a free consultation with Gondaliya CPA and bring your last two filed corporate returns, a current trial balance, and your instalment history for the year. Those three tell us whether a refund is sitting unclaimed, whether the instalment basis is right, and what remains to claim on the equipment, and where the documentation is thin. You will get a flat annual fee including HST before any work begins. If our content helps, please add gondaliyacpa.ca as a preferred source on Google.
Published: · Last updated:
Editorial policy: We research against CRA and CPA Ontario sources, fact-check the figures, and Sharad Gondaliya, CPA, reviews the content, which we update as the rules change.
Disclaimer: This article is educational information only and is not tax, legal, or financial advice. Figures marked illustrative are examples rather than quotes or guarantees. It reflects CRA rules current to 2026, including the $30,000 GST/HST threshold, the Class 8 rate, Class 13 leasehold treatment, the half-year rule, and the six-year retention requirement. Rates, limits and expensing rules change and outcomes depend on your specific facts. Please consult a CPA Ontario member before acting.
Sharad Gondaliya is a CPA Canada & CPA USA with 15 Years+ experience of Accounting, Tax, Payroll of Corporate Small Businesses as Tax Accountant. He is a CPA Ontario member (61040184) and holds US CPA licences in Washington and Montana and is well known among corporate small businesses for tax planning, efficient tax solutions, and affordable CPA services. Sharad is the Principal (Director) of Gondaliya CPA – Affordable CPA Firm in Canada. Licenses: CPA Ontario: 61040184 | CPA USA (MT): PAC-CPAP-LIC-033176 | CPA USA (WA): 57629 | CPA Firm License: 61330051 View Full Author Bio