



Tax Accountant for Market Research Firms in Ontario and Across Canada
We carry your project work in progress across the year-end instead of recognizing a whole fee the day you invoice it, build the documentation trail behind every respondent incentive and gift-card payout so the deduction survives a review, settle the employee-versus-contractor question on your field interviewers on CRA guide RC4110, file the T4A slips your fieldwork subcontractors generate, establish and document the export zero-rating on your foreign client work so the input tax credits on panel, platform and fieldwork are claimed in full, and put your survey platform licences in Class 12 and your focus-group suite in Class 13. Whether you run a quantitative agency, a qualitative practice, a focus-group facility, or a brand tracking business, we handle the project, incentive and export accounting, and plan the salary, dividends and eventual sale of your company — with AFFORDABLE flat fees.
AFFORDABLE Market Research Firm Tax Accountant
A research agency spends its money before it collects any. You buy the sample, pay the incentives, pay the interviewers and book the facility, and then deliver a report and wait sixty days to be paid. That timing is what makes project work in progress the defining accounting question in this trade: a study that starts in October and reports in February has costs in one fiscal year and a fee in the next, and recognizing the whole fee on the invoice date misstates both. The second distinctive issue is respondent incentives. Paying individuals in cash or gift cards is entirely ordinary in research and entirely reasonable as a deduction, but it is also exactly the kind of expense CRA asks to see supported, and a payout with no trail behind it is a deduction at risk. Add the export question on foreign client work, where zero-rating is often available but not automatic when the fieldwork is conducted among Canadian respondents. At Gondaliya CPA, we specialize in project, incentive and export accounting for research firms, providing AFFORDABLE flat-fee support that keeps you CRA-compliant and stops you paying more tax than you owe.
As an insights and research accountant, we work with quantitative agencies, qualitative practices, focus-group facilities, and brand tracking businesses across Ontario, with year-round support rather than a once-a-year scramble. We tell you plainly what you can deduct, what you cannot, and where the real margin sits on each project you run.
Let us handle the numbers so you can focus on the fieldwork and the clients who actually pay you.
Our Official Partners
Accounting That Understands How a Research Agency Actually Works
Running a research firm comes with financial questions a conventional consultancy never faces. Your projects straddle year-ends, you pay individual respondents in cash and gift cards, your fieldwork runs through subcontracted interviewers, and a tracker client can be a third of your revenue on a contract that renews annually. At Gondaliya CPA, we understand that reality and provide practical, trade-focused solutions across the GTA and all of Ontario.
Stay Compliant and Minimize Your Research Firm Tax
For a research agency, staying onside with CRA and paying the least legal tax are the same job. We keep every filing on schedule while claiming every incentive, panel and fieldwork dollar the T2 allows, so nothing is missed and nothing invites a reassessment.
Accounting & Tax Experts for Market Research Firms
- AFFORDABLE + Registered CPA Firm
- Business and Corporate Tax Expert
- Small & Medium Business Expert
- Accounting, bookkeeping, and tax filing
- CPA (Chartered Professional Accountant)
- 1300+ 5-star Google reviews
- 30-Day Money-Back Guarantee
- 60-Day Fees Matching Policy
Why Choose Our Accounting Services for Market Research Firms?
Tax Planning — Project & Facility Expertise
We know the trade: survey platform licences in Class 12 at 100%, workstations in Class 50 at 55%, focus-group furniture and recording gear in Class 8, the viewing suite in Class 13. We protect the $500,000 Small Business Deduction.
Consulting — Project WIP & Incentive Bookkeeping
Our bookkeeping carries work in progress by study, loads incentives, panel and fieldwork against the project that consumed them, and builds the documentation trail behind every payout as it happens.
CRA Representation — Incentive & Contractor Audit
When CRA questions your incentive expense or your interviewers’ status, we prepare the response and pursue relief on Form RC4288 where a prior error caused the penalties.
Bookkeeping — Cash Flow, Trackers & Sale
We build a cash-flow plan that survives paying fieldwork up front against clients who pay on delivery, and get you ready to sell. We model the profit level where incorporating pays off.
Google Reviews
Market Research Clients
Market Research Firm Tax and Accounting Services in Ontario
Corporate Tax Filing (T2) for Market Research Firms
Professional T2 preparation with Schedule 8 CCA on your platform licences, workstations and focus-group facility, project work in progress carried properly, and CRA compliance on every line.
Bookkeeping & Accounting for Market Research Firms
Project, incentive and fieldwork bookkeeping with financial statements, clean records, and per-study margin reporting built for a research agency.
Payroll Services for Market Research Firms
Research staff payroll with PD7A remittances, T4s filed by the last day of February, T4A slips on fieldwork subcontractors, and Employer Health Tax tracking.
GST/HST Filing for Market Research Firms
AFFORDABLE HST filing with the export position properly reviewed and documented, place of supply applied to Canadian clients, and full input tax credits recovered.
Tax Planning for Market Research Firms
Smart tax planning to protect the Small Business Deduction, time your platform and facility investment, and plan salary, dividends and the sale of your agency.
Corporate Catch-Up Filing for Market Research Firms
File overdue T2 and HST years, rebuild missing project, incentive and fieldwork records, and get back into CRA compliance with accurate catch-up support.
CRA Audit Resolution for Market Research Firms
Expert support for incentive-expense, contractor-classification and export-documentation audits, handled with confidence from the first letter.
CPA Financial Statements (Notice to Reader) for Market Research Firms
CPA-compiled financial statements that banks accept for a fieldwork float and that enterprise procurement accepts during vendor onboarding.
Incorporation Services for Market Research Firms
Full incorporation including NUANS, articles, share structure, and the section 85 rollover of your client relationships and panel into the company.
Catch-Up Bookkeeping Services for Market Research Firms
Months or years of project costs, incentive payouts and interviewer payments reconstructed and reconciled, so your work in progress and export split are finally accurate.
US Corporation & LLC Tax Filing for Market Research Firms
Cross-border filing for agencies with US clients or multi-country projects, covering 1120/1120-F returns, treaty positions and FBAR reporting.
Voluntary Disclosure Program for Market Research Firms
Come forward on unreported foreign-client income, unfiled T4A slips or mis-rated HST before CRA calls, cancelling penalties through a Voluntary Disclosures Program application.
Accounting & Tax Services Tailored for Market Research Firms
Real, practitioner-level CPA expertise for quantitative agencies, qualitative practices, focus-group facilities, and brand tracking businesses across Ontario — built for how a research firm actually runs.
- We prepare your T2 with GIFI on Schedule 100 and Schedule 125, separating project fees, tracker retainers, facility rental and data processing revenue onto their correct lines so CRA’s automated matching does not misread the file.
- We claim capital cost allowance on Schedule 8 with survey platform and analysis software in Class 12 at 100%, workstations and servers in Class 50 at 55%, focus-group furniture and recording equipment in Class 8 at 20%.
- We capitalize your focus-group suite build-out, including viewing rooms and one-way glass, to Class 13 over the lease term rather than expensing it, so a $70,000 facility fit-out is deducted across the years it serves.
- We carry project work in progress on studies still in field at year-end, so a tracker that fields in November and reports in February has its costs and its fee land in the periods they actually belong to.
- We record client deposits taken before fieldwork begins as a liability rather than revenue, because money held against a study you have not yet delivered is not income no matter when it hit the bank account.
- We cost each study against the sample, incentives, interviewer hours and facility time it consumed inside QuickBooks Online or Xero, and on one agency this showed a low-incidence tracker losing money on every wave.
- We build the documentation trail behind incentive payouts as they happen, recording the study, the date, the amount and the method, because reconstructing a year of gift-card distributions after a query arrives is close to impossible.
- We track panel and sample purchases by project so your cost per complete is visible against what you quoted, which is the number that decides whether a fixed-fee study was ever priced correctly.
- We carry work in progress study by study rather than estimating it once at year-end, so your monthly numbers mean something and a project overrunning its budget shows up while you can still act on it.
- We capture every panel, facility and platform invoice through Dext and reconcile monthly, keeping the six years of records section 230 requires and ensuring no input tax credit is lost to a missing bill.
- We set up research staff payroll in Wagepoint, withholding income tax, CPP and EI and remitting on the PD7A by the 15th of the following month, because CRA’s late-remittance penalty on source deductions climbs to 10% as the lateness grows.
- We settle the employee-versus-contractor question on your field interviewers using CRA guide RC4110, because an interviewer working assigned shifts from your call room on your script looks like an employee whatever the agreement says.
- We file T4A slips on the fieldwork subcontractors, moderators and data processors you pay, because a substantial subcontractor line on your T2 with no slips behind it is a mismatch CRA can find from its own records.
- We file your T4 slips and T4 Summary by the last day of February and reconcile them to the PD7A remittances actually made, so a firm that scales staff for a big wave is never penalized for a mismatch.
- We monitor total Ontario payroll against the $1,000,000 Employer Health Tax exemption, so a growing agency registers and remits in the right year instead of being assessed for it later with interest.
- Research supplied to a non-resident client who is not registered for GST/HST is generally zero-rated as an export of services, so we establish the position with the contract and residency evidence rather than defaulting to 13%.
- Zero-rated is not exempt, and the difference is worth real money: because the supply stays taxable at 0%, your input tax credits on panel purchase, platform licences, facility costs and fieldwork remain fully claimable.
- We review the carve-out that decides the harder cases, because a study run for an American client among Canadian respondents is not automatically zero-rated and the analysis has to be done rather than assumed.
- For Canadian clients we apply the place-of-supply rules so the rate follows the client’s address, because billing every domestic invoice at 13% from an Ontario office over-collects and invites an adjustment.
- We reconcile the HST on your returns to the revenue on your T2 every filing period, because CRA’s matching program compares the two and a company whose figures disagree by even $5,000 is among the fastest files pulled for audit.
- We set the salary-versus-dividend mix for the owners, paying enough T4 salary to build RRSP room while the balance flows as dividends, so combined tax stays near the 12.2% Ontario small-business rate instead of the 53.53% top personal rate.
- We keep your active income under the $500,000 Small Business Deduction limit using section 125, and watch the associated-corporation and passive-income rules that grind the limit toward the higher general corporate rate as surplus builds.
- We time your platform licence renewals, workstation refresh and facility investment against your fiscal year-end so the Class 12 and Class 50 rates give the largest first-year deduction against a strong project year.
- We use the work in progress position deliberately rather than accidentally, because whether a large study straddling the year-end lands in this year or next has a real effect on the tax your corporation pays.
- We plan at least two years ahead so your shares qualify for the $1.25M Lifetime Capital Gains Exemption under section 110.6, purifying the company of non-active assets so selling your agency defers tax CRA would otherwise collect.
- We reconstruct project fees, tracker retainers and facility income from bank deposits, issued invoices and project records across your unfiled years, rebuilding the six years of records section 230 requires.
- Late filing costs 5% of the balance owing plus 1% per month up to twelve months, so we file your oldest unfiled T2 first to stop the penalty compounding and limit the arrears interest CRA charges your corporation.
- We rebuild the incentive and fieldwork records for each unfiled year, because these are the largest deductions on a research return and the ones least likely to survive without contemporaneous support.
- We rebuild the zero-rated and domestic split for every unfiled GST34 period, because that figure drives each return and no catch-up filing is defensible without establishing it client by client.
- We file a Voluntary Disclosures Program application on Form RC199 before CRA contacts you, because a disclosure accepted under the general program cancels penalties in full and gives roughly 50% interest relief on the older years.
- When CRA questions your respondent incentive expense, we answer with the study-by-study payout records, the project documentation and the field reports, because cash and gift-card payments to individuals draw scrutiny by their nature.
- When CRA challenges the status of your field interviewers, we defend the position with the control, equipment, profit and risk analysis CRA guide RC4110 sets out, because a reclassification brings back CPP, EI and penalties across every year.
- When CRA asks for the evidence behind a zero-rated project, we produce the residency documentation, the scope of work and the analysis of where the research was actually conducted and for whom.
- We answer work in progress and revenue-recognition queries with the project cost records, because a study straddling the year-end is exactly the kind of timing question a reviewer will test on a research file.
- We file the Notice of Objection within 90 days of a reassessment and pursue taxpayer relief on Form RC4288, cancelling penalties and interest that can top $15,000 where a prior accountant’s error caused them, protecting your right to the Tax Court.
- We prepare the CSRS 4200 compilation engagement financial statements a bank requires across two fiscal years before approving the operating line that funds incentives and fieldwork paid long before the client settles.
- Your compiled statement of financial position presents project work in progress, client deposits, aged receivables, accrued fieldwork costs and facility assets at net book value, giving a lender the picture a bare T2 cannot.
- Enterprise procurement screens financial capacity during vendor onboarding, and an agency bidding for a multi-year tracker without compiled statements can be set aside before anyone reads the methodology it spent weeks writing.
- We build the statement of operations with project fees, tracker retainers, incentives and fieldwork costs classified consistently across two years and tied to the T2 filed with CRA, so the bank and the client both accept it.
- We deliver the compiled statements within 30 days of receiving your records and the year’s T2 figures, because a bid deadline or a conditional credit offer collapses when the file is not produced in time.
- We incorporate your business under the Ontario Business Corporations Act, giving you limited liability and roughly the 12.2% Ontario small-business rate, against the 53.53% top personal rate an unincorporated consultant pays.
- We complete the section 85 rollover on Form T2057, transferring your client relationships, panel, equipment and goodwill into the corporation at elected amounts, deferring the gain a straight sale would trigger.
- We open the corporation’s CRA Business Number, HST and payroll accounts within the first 30 days, and register for HST where project billings already put you past the $30,000 threshold, so no credits are lost.
- We set up the chart of accounts with project costing, the incentive documentation routine and the zero-rated split built in from the first study, so the records accumulate as you work rather than being reconstructed later.
- We structure the share classes and set the first fiscal year-end up to 53 weeks after incorporation, choosing a date that does not fall in the middle of your heaviest fielding season, which simplifies the work in progress position every year.
- We rebuild months or years of neglected books from bank deposits, issued invoices, panel invoices and interviewer payments, so an agency that let its records slide through a busy year gets a clean ledger.
- We reconstruct the incentive payouts across the backlog and attach each to the study it belonged to, because an unexplained block of cash and gift-card spending is the deduction most likely to be challenged.
- We rebuild project work in progress period by period so the caught-up statements show costs and fees in the right years rather than whichever year the invoice happened to be raised in.
- We rebuild the subcontractor ledger so the T4A slips that were never filed can be prepared, closing an exposure CRA finds simply by comparing your fieldwork expense to its own slip records.
- We rebuild the Class 12, Class 50, Class 8 and Class 13 asset schedules and reconcile payroll across the caught-up months, so an accurate T2 can be filed without guessing at a lost year.
- When a large share of your clients are American, we determine whether that US-source revenue creates a filing obligation and prepare Form 1120-F, applying the Canada-US treaty so the same income is not taxed twice.
- We claim treaty protection against a US permanent establishment where moderators or researchers travel to run groups or present findings on site, filing the treaty-based return positions that keep that travel from triggering US tax.
- On multi-country projects we handle the foreign fieldwork supplier payments and the reporting that follows, so a study fielded across three countries does not create exposure nobody looked at until year-end.
- We file Form T1135 where your foreign property, including balances held with overseas panel and platform suppliers, passes the $100,000 threshold, avoiding a penalty regime CRA treats as non-negotiable.
- We reconcile the US and Canadian returns so foreign tax credits actually land, ensuring any US tax withheld on your project income offsets Canadian tax on the same income rather than being written off as a cost.
- We bring your company forward on foreign-client project income that never reached a return, because a Voluntary Disclosures Program application accepted under the general program cancels the gross-negligence penalty that can reach 50% of the tax.
- We disclose a missed registration where project billings pushed you past the $30,000 threshold years ago, correcting the record on your terms and opening the door to credits rather than waiting for CRA to find the gap.
- We correct unfiled T4A slips on your fieldwork subcontractors and moderators through the same disclosure, sparing your company the per-slip penalties CRA would otherwise stack once it matches your expense line.
- We file your VDP submission on Form RC199 with a full income reconstruction from invoices and project records, so an agency that under-reported over several years is not left facing an arbitrary CRA assessment.
- We confirm your disclosure is genuinely voluntary before CRA contacts you — the single condition that makes it valid — and secure the roughly 50% interest relief on the older years, turning a prosecution risk into a managed correction.
Research Firm Project & Incentive Check
Six quick questions on your project work in progress, your incentive documentation, your interviewer status, your subcontractor slips, your export HST position and whether it is time to incorporate. No fee shown.
1. Do you carry project work in progress across the year-end?
2. Do you document every respondent incentive payout by study?
3. Have your field interviewers been reviewed on CRA guide RC4110?
4. Do you file T4A slips for fieldwork subcontractors and moderators?
5. Do you hold documentation supporting your export HST position?
6. Is your research firm incorporated?
Free CPA Consultation for Market Research Firms
Case Studies: Market Research Firm Accounting & Tax
Toronto Quantitative Agency — Work in Progress
The problem: A Toronto quantitative agency recognized every project fee on the date it invoiced, which for a firm running trackers meant the sample, incentives and interviewer costs for a November wave sat in one fiscal year while the fee for that same wave landed in the next. Two consecutive years looked wildly different from each other for no operational reason, the owner could not tell whether the business was growing, and the corporation paid tax in the wrong years on profit it had not actually earned when it was reported.
What we did: We set up project work in progress study by study in Xero, carried the cost of studies still in field across the year-end, moved client deposits to a liability until delivery, and rebuilt the prior year comparatives so the trend a reader sees matches what the agency actually did.
The result:
- Costs and fees now land in the same period
- Client deposits carried as a liability until delivery
- Year-over-year trend finally readable
Mississauga Qualitative Practice — Incentives and Interviewers
The problem: A Mississauga qualitative practice was paying respondents in cash and gift cards at every group and recording the whole lot as a single monthly expense line with no study attached and no payout records behind it. It was also engaging a regular pool of recruiters and moderators as contractors with no T4A slips filed. Both are ordinary industry practice done badly: the incentive spending was a genuine cost with nothing to prove it, and the subcontractor line on the T2 had no slips behind it at all.
What we did: We built an incentive payout routine capturing study, date, amount and method at the point of payment, reconstructed the prior periods as far as the records allowed, ran the CRA guide RC4110 analysis across the fieldwork pool, and filed the outstanding T4A slips.
The result:
- Incentive deduction now supported study by study
- Prior-year T4A slips filed, per-slip penalties avoided
- Moderator and recruiter status settled under RC4110
Ottawa Brand Tracking Firm — The Foreign Client Question
The problem: An Ottawa brand tracking firm did most of its work for American clients and had been charging 13% HST on all of it, on the previous accountant’s view that because the fieldwork happened in Canada the supply was domestic. That is not the test, and the firm had been quoting against US competitors at a 13% disadvantage for years. But the correct answer was not blanket zero-rating either, because a meaningful share of the work was research conducted among Canadian respondents, which engages a carve-out most agencies have never heard of.
What we did: We analysed each client contract against the export rules, established and documented zero-rating on the work that qualified, kept the residency evidence on file, and confirmed that input tax credits on panel, platform and fieldwork remained fully claimable throughout.
The result:
- Qualifying US projects moved to zero-rated
- Input tax credits preserved in full, refund position confirmed
- Residency documentation now kept as work is quoted
Our clear, efficient process ensures every step is transparent, building trust and long-term client relationships.
Kickoff (Document Request)
Collect prior T2 returns, client contracts with residency details, project cost records, incentive payout logs, panel and facility invoices, interviewer and moderator agreements, payroll records, and bank statements.
First 30 Days (Cleanup & Setup)
Set up QuickBooks Online or Xero with project tracking, build the work in progress schedule, establish the incentive documentation routine, set the zero-rated split, and run the RC4110 review on fieldwork.
Monthly Close
Project cost and WIP review, incentive payout reconciliation, per-study margin reporting, GST34 with the export split, and receivables ageing against client terms.
Quarterly Planning Review
Salary and dividend mix, export and place-of-supply review, work in progress position ahead of year-end, and platform and facility investment timing.
Year-End Close & T2 Filing
Trial balance, financial statements with project work in progress, client deposits and accrued fieldwork costs, T4A slips, T2 with GIFI, and CRA preparation.
Get Your Research Firm Taxes Done Right Today
Affordable Pricing for Market Research Firms
We believe in clear, upfront pricing so you know exactly what to expect. All fees include HST.
- Tax Preparation (Corporation) — From $400
- Tax Return Filing (Corporation) — From $400
- Tax Compliance Audit — FREE CRA audit support for our clients
- Tax Strategy — FREE for our clients
- Accounting Base Plan — From $100 per month
- Bookkeeping Management — Free for our Accounting clients
- Financial Reporting — Free for our Accounting clients
- Business Formation — Flat $35
- Incorporation Process — Flat $35
- Entity Setup Assistance — Flat $35
- Full-Service Payroll — From $125 per month
Payment is by Interac e-Transfer to info@gondaliyacpa.ca only. Security question: Not Applicable, as auto-deposit is enabled.
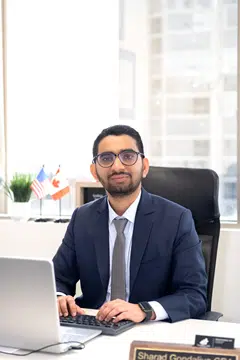
Meet Your Lead Market Research Accountant
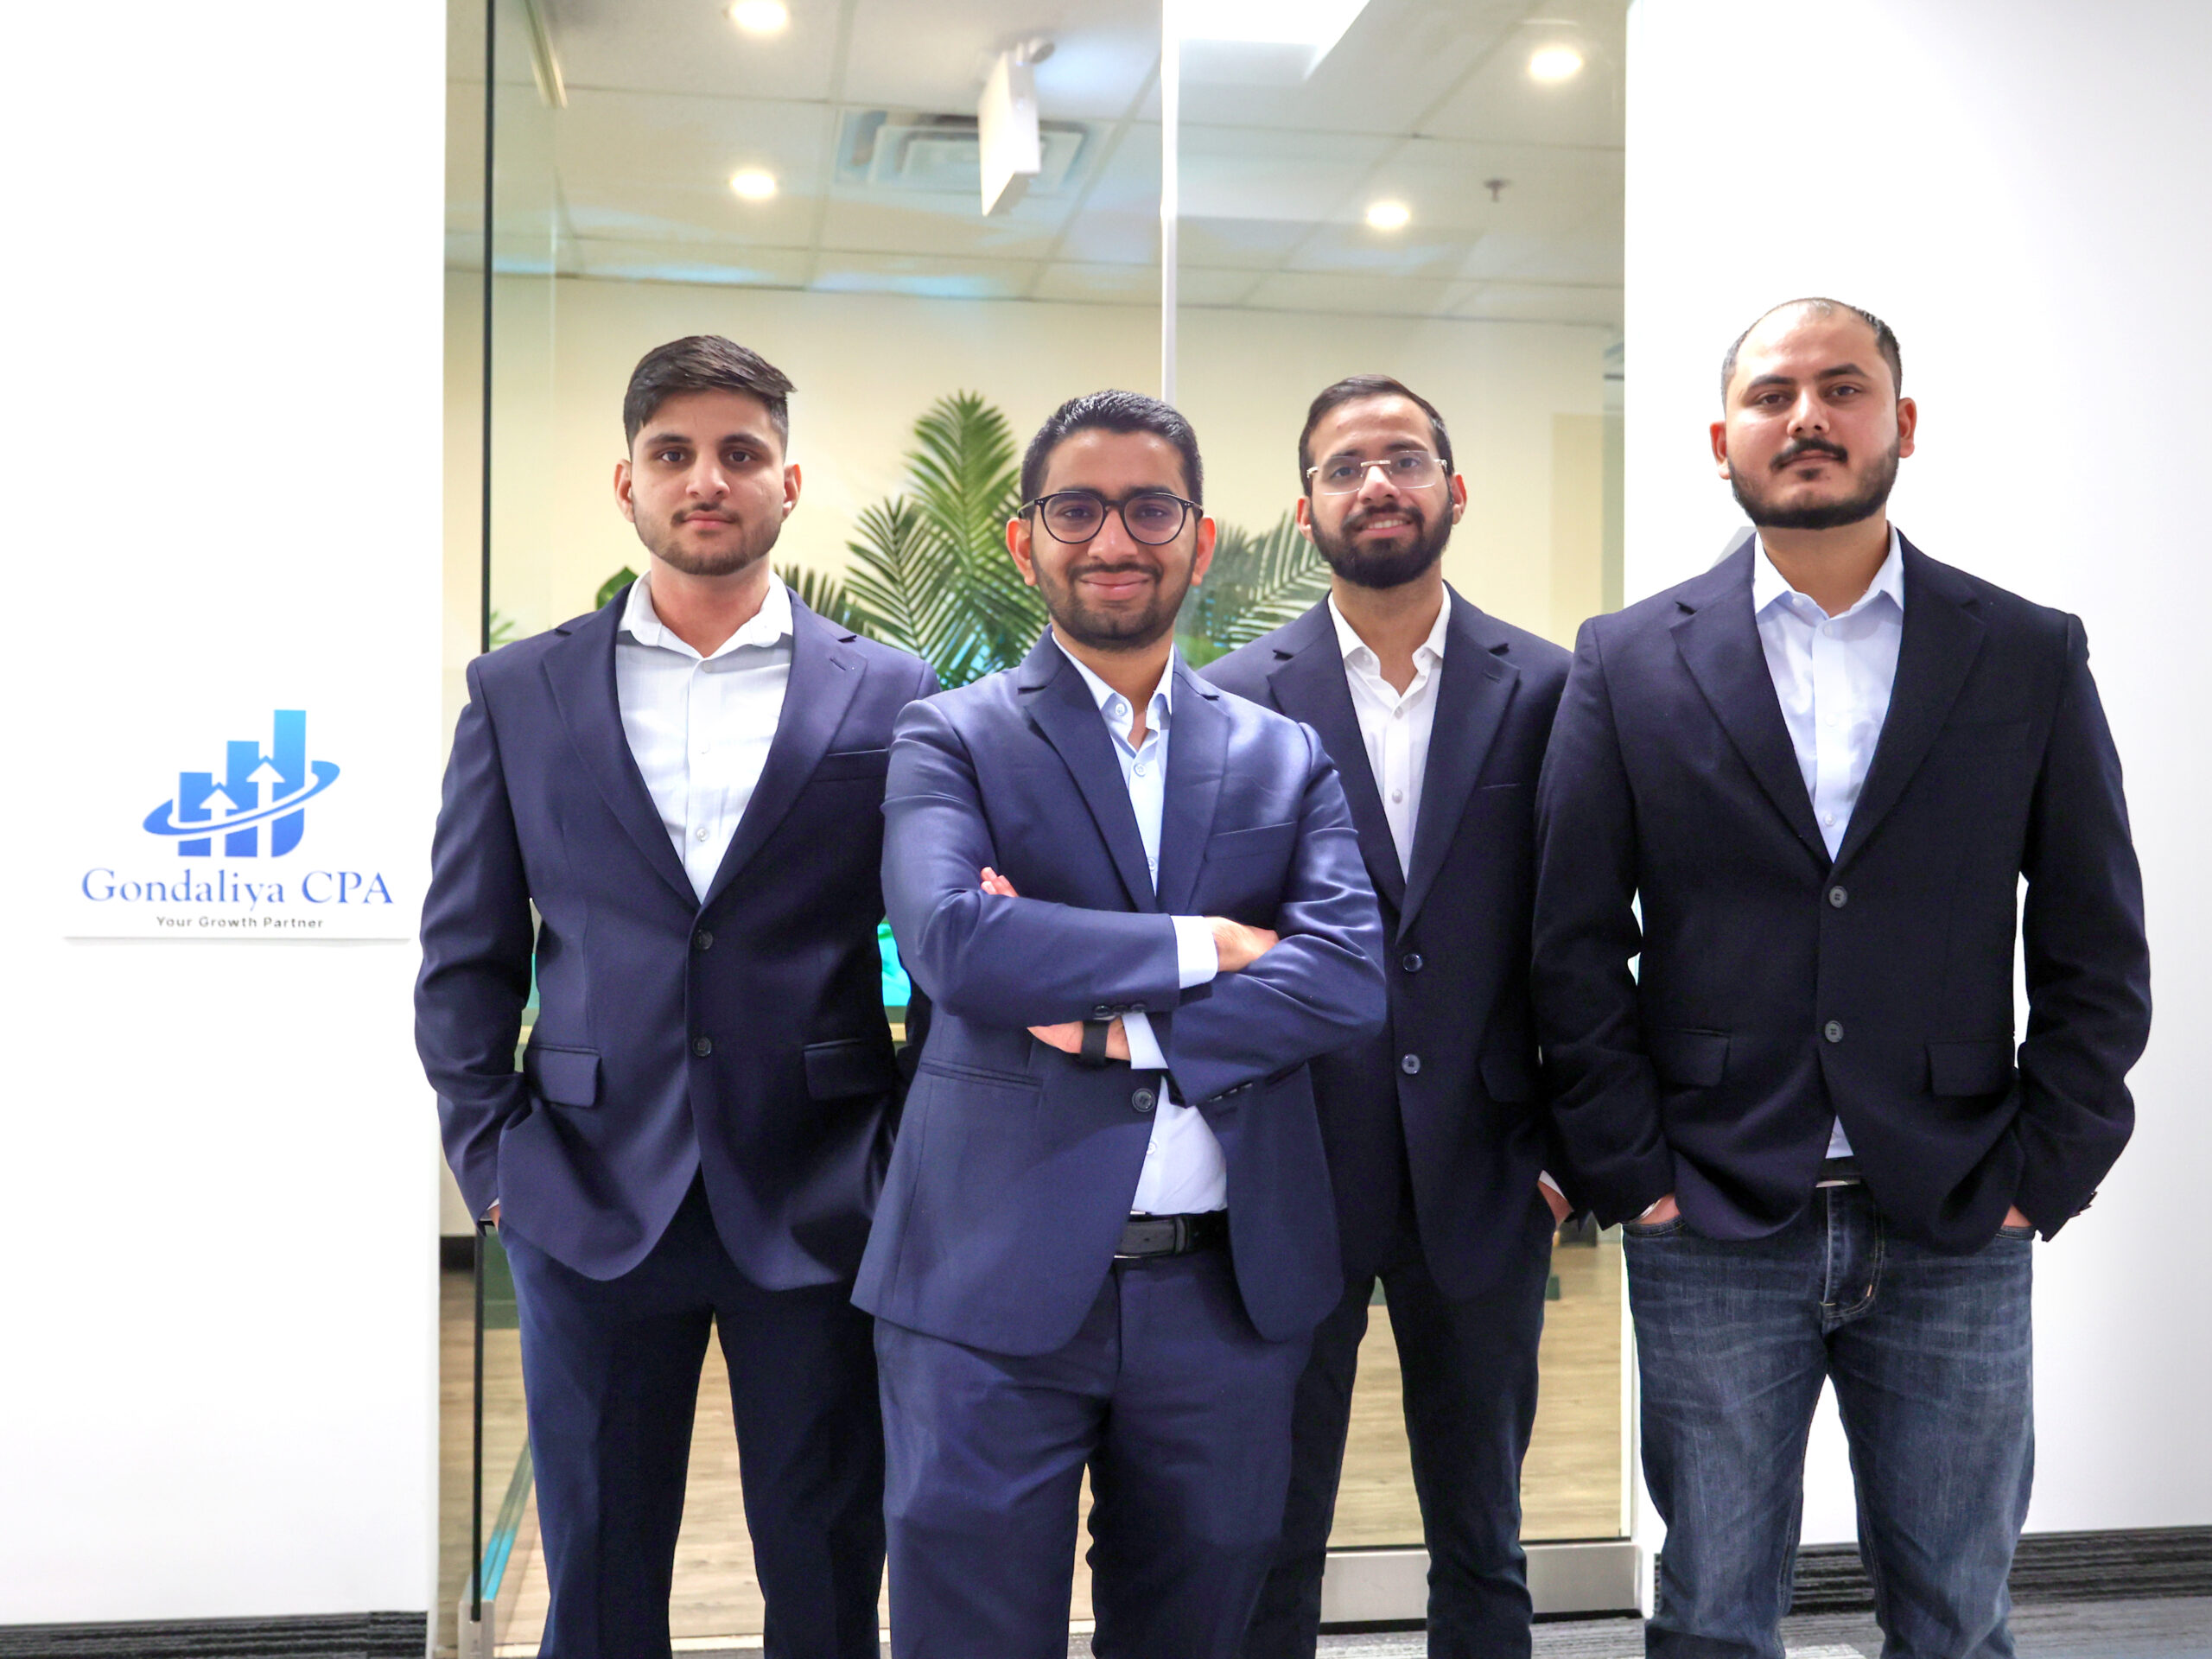
Meet your lead market research accountant. As your project-business and corporate tax adviser, you deal with the same two people every year.
What Our Clients Say
1300+ five-star reviews from research, insights and professional services owners across Ontario and Canada.
Serving Market Research Firms Across Ontario
Our CPA team provides specialized accounting and tax solutions for research and insights agencies throughout Ontario. We understand how project work in progress, respondent incentives, fieldwork subcontractors and export HST actually flow through a research firm, what CRA looks at on a project-based file, and how to keep every deduction supported.
Toronto (ON)
55 Queen St E Ste 1205, Toronto, ON M5C 1R6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Mississauga (ON)
2100 Camilla Rd #716, Mississauga, ON L5A 2J8
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Brampton (ON)
4 Starhill Crescent, Brampton, ON L6R 2P9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Scarborough (ON)
24 Clementine Square, Scarborough, ON M1G 2V7, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Vaughan (ON)
19 Cabinet Crescent, Woodbridge, ON L4L 6H9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Oshawa (ON)
210 Durham St, Oshawa, ON L1J 5R3, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Ottawa (ON)
2090 Neepawa Ave a314, Ottawa, ON K2A 3L6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Etobicoke (ON)
60 Stevenson Rd #1601, Etobicoke, ON M9V 2B4, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Hamilton (ON)
70 Starling Dr, Hamilton, ON L9A 0C5, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Guelph (ON)
1155 Gordon St, Guelph, ON N1L 1S8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Windsor (ON)
4387 Guppy Ct, Windsor, ON N9G 2N8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
North York (ON)
150 Graydon Hall Dr #912, North York, ON M3A 3B2, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Market Research Firm Accounting & Tax FAQs
Related Industries We Serve
Accountant for Call Centres
- Telephone fieldwork and agent payroll
- Class 46 network gear and floor build-out
- Export HST reviewed and documented
Accountant for BPO Companies
- Offshore delivery and transfer pricing
- Multi-year contracts and transition costs
- Corporate tax planning and statements
Accountant for Translation Services
- Zero-rated exports and input tax credits
- Freelance linguist subcontractor reporting
- Multi-currency bookkeeping and incorporation
Accountant for Incorporated Businesses
- T2 corporate returns and GIFI
- Salary, dividend and SBD planning
- Compilation statements and incorporation
Market Research Accounting & Tax Done Right.
T2 filing, project work in progress carried across the year-end so costs and fees land together, respondent incentives documented study by study so the deduction holds, field interviewers reviewed on CRA guide RC4110 with T4A slips filed on your fieldwork pool, the export HST position analysed and documented rather than assumed, and survey platform licences in Class 12 with the focus-group suite in Class 13 under one roof. AFFORDABLE flat fees, no hourly billing. Licensed CPA Ontario. 1300+ five-star reviews. 30-Day Money-Back Guarantee.