



Tax Accountant for Currency Exchange Businesses in Ontario and Across Canada
A bureau earns its revenue on the spread between the rate it buys at and the rate it sells at, never on the volume that crosses the counter, and that one distinction decides whether your statements are true. Under ETA section 123(1) the exchange is a financial service and therefore an exempt supply, which means nothing is charged on it and the HST behind the counter, on rent, security and armoured transport, generally stays with you. The $30,000 small-supplier threshold is measured against your taxable fee income alone. We determine and document the character of any separate wire or service fee, revalue the banknotes in your vault at year end, split realised from unrealised movement, and build the daily till and rate-sheet records that prove a cash business’s income. T2, teller payroll, incorporation and the $1.25M Lifetime Capital Gains Exemption under one roof. Flat-fee, no hourly billing, CPA Ontario, 1300+ five-star.
AFFORDABLE Currency Exchange Tax Accountant
A currency exchange business looks enormous on paper and is usually a modest operation underneath. Twenty million dollars crosses the counter in a year and the owner says the business does twenty million, but the revenue is the spread and the spread might be a few hundred thousand. Every financial statement, every bank conversation and every CRA question goes wrong from that one confusion. Underneath it sit three problems a general bookkeeper will not have met. Exchanging one currency for another is a financial service under ETA section 123(1), which makes the exchange an exempt supply: no HST is charged on it, and as an exempt supplier you generally cannot recover the tax you pay on rent, security and armoured transport as input tax credits. The banknotes in your vault are an asset that must be revalued at year end, with realised and unrealised movement kept apart and the rate documented. And the whole operation runs on cash, which makes the ledger not merely an accounting record but the evidence that the income you reported is the income you earned.
As currency exchange accountants we work with storefront bureaus, airport and border counters, multi-branch operators and single-window shops across Ontario, with year-round support rather than a once-a-year scramble. We split exempt exchange revenue from any separately charged fee income, restrict input tax credits properly, and tell you plainly what you can deduct and where the margin really sits once the cost of holding currency is counted.
Leave the numbers with us and give the counter your attention.
Our Official Partners
Accounting That Understands How a Currency Exchange Actually Works
A bureau carries four problems at once that an ordinary shop never has to think about. The headline number everyone quotes is turnover, while the revenue is the spread retained on each trade. The exchange itself is exempt, so you cannot recover the tax on your inputs. The currency in your vault is an asset whose value moves while you hold it. And because the business runs on cash, your records are not just bookkeeping but proof. Gondaliya CPA knows where a bureau’s money actually comes from, and we bring that to the counter for operators across the GTA and the rest of Ontario.
Stay Compliant and Minimize Your Currency Exchange Tax
In a bureau, the work that keeps CRA satisfied and the work that keeps your tax bill low turn out to be the same work. Deadlines are met, and the exchange revenue, any separate fee, the vault position and the payroll are each classified as the rules actually require, which is what keeps a reassessment off the table.
Accounting & Tax Experts for Currency Exchange Businesses
- AFFORDABLE + Fully Registered CPA Firm
- Business and Corporate Tax Expert
- Small & Medium Business Expert
- Accounting, bookkeeping, and tax filing
- Certified CPA
- 1300+ 5-star Google reviews
- 30-Day Money-Back Guarantee
- 60-Day Fees Matching Policy
Why Choose Our Accounting Services for Currency Exchange Businesses?
Tax Planning — Spread & Structure
We hold active income inside the $500,000 Small Business Deduction limit, weigh salary against dividends for the year you are actually in, elect the section 85 rollover when you incorporate, and keep the $1.25M Lifetime Capital Gains Exemption available for the day you sell.
Consulting — Spread Revenue & Vault Accounting
Our bookkeeping records the spread as revenue and keeps turnover out of the income statement, carries currency on hand as an asset, revalues it at year end, splits realised from unrealised movement and restricts input tax credits correctly.
CRA Representation — HST & Cash-Business Audit
Queries about restricted credits, the year-end revaluation, or deposits that look large beside declared income all get the same treatment: a written response, the daily record set produced in support, and Form RC4288 relief where a prior error caused the penalties.
Bookkeeping — Teller Payroll & Growth
We run T4 teller payroll, handle source deductions and WSIB, issue ROEs on separation, and get you ready to open a second counter. We work out the profit level at which a corporation starts to pay for itself, then carry out the change when you reach it.
Google Reviews
Currency Exchange Clients
Currency Exchange Tax and Accounting Services in Ontario
Corporate Tax Filing (T2) for Currency Exchange Businesses
Professional T2 preparation reporting spread revenue on Schedule 125, the vault position on Schedule 100, and Schedule 8 capital cost allowance on every line.
Bookkeeping & Accounting for Currency Exchange Businesses
Daily till and vault bookkeeping that records the spread as revenue, keeps turnover out of the income statement, and reports monthly.
Payroll Services for Currency Exchange Businesses
T4 teller payroll with PD7A source deductions, WSIB from the first hire, ROEs and Ontario Employer Health Tax handled correctly.
GST/HST Filing for Currency Exchange Businesses
AFFORDABLE handling of the exempt exchange under ETA section 123(1), with restricted input tax credits and every separate fee determined and documented.
Tax Planning for Currency Exchange Businesses
Keeping the Small Business Deduction intact, balancing salary against dividends, timing the section 85 election and readying the bureau for sale.
Corporate Catch-Up Filing for Currency Exchange Businesses
Overdue T2 and payroll years filed, missing till and rate-sheet paper rebuilt, and your bureau brought back to current with CRA.
CRA Audit Resolution for Currency Exchange Businesses
Expert support on exempt-supply HST, restricted input tax credits, unreported-income and arbitrary-assessment files, with RC4288 relief handled confidently.
CPA Financial Statements (Notice to Reader) for Currency Exchange Businesses
CPA-compiled financial statements banks and landlords accept, presenting spread revenue and the year-end vault position clearly and consistently.
Incorporation Services for Currency Exchange Businesses
NUANS search, articles, share classes, and a Form T2057 election that moves fixtures, the safe and goodwill into the new company.
Catch-Up Bookkeeping Services for Currency Exchange Businesses
Months or years of till, vault and rate-sheet paper turned back into clean books, with monthly reporting running again.
US Corporation & LLC Tax Filing for Currency Exchange Businesses
Forms 1120, 1120-F and 5472 prepared beside your Canadian returns where a US entity or branch sits in the structure.
Voluntary Disclosure Program for Currency Exchange Businesses
Disclose spread income that never reached a return, on Form RC199 under the CRA Voluntary Disclosures Program, while relief is still open.
Accounting & Tax Services Tailored for Currency Exchange Businesses
Real, practitioner-level CPA expertise for storefront currency exchange bureaus, airport and border counters, multi-branch operators and single-window shops across Ontario — built for how a bureau actually earns.
- We prepare your T2 with GIFI and report the spread you actually earned on Schedule 125 rather than the gross value of currency exchanged, because a return built on turnover misstates every figure CRA compares against your industry.
- We tie the Schedule 100 balance sheet to the banknotes counted in your vault at year end, so currency on hand is carried as an asset at a documented rate instead of a plug figure nobody can support.
- We claim capital cost allowance on Schedule 8 with your safe, counters and security fixtures in CCA Class 8 at 20% and computers in Class 50, and one bureau recovered $4,300 of depreciation its prior preparer never claimed.
- Holding active income inside the $500,000 limit keeps the first half-million of exchange profit near the 12.2% Ontario combined small-business rate, and we check the associated-corporation rules before CRA reduces that limit on you.
- The return goes in inside the six-month window and the balance is paid when it falls due, which is how a bureau clearing $180,000 of spread profit avoids the arrears interest CRA adds to anything settled late.
- We build your chart of accounts in QuickBooks Online or Xero so the spread retained on each transaction posts to revenue while the gross value exchanged stays a statistic, correcting one bureau’s $340,000 overstatement of income.
- We post every window to the daily close so the ledger reflects what each till actually took in, and one operator found $2,700 of nightly shortages that had been absorbed into a single monthly journal entry.
- Because a currency exchange business is registered with FINTRAC and carries record-keeping obligations of its own, we keep the daily ledger complete and current as the year runs rather than rebuilding it from loose paper once the year has already closed.
- We carry the banknotes in your vault as an asset by denomination and currency, revalue them at year end, and record that movement apart from trading spread so your statements show where the profit genuinely came from.
- We capture rent, security monitoring, armoured transport and insurance through Dext and attach each receipt to its transaction, so an $11,000 expense pool is fully documented rather than lost when CRA asks for support.
- We run pay through Wagepoint, issue T4 slips to your tellers and pay source deductions on the PD7A by the deadline, because the penalty on a late payment is graduated and reaches 10% of the amount owing.
- We register your bureau with WSIB from the first hire, because coverage is required from the day you take on staff, and an operator who waits until an audit pays the premiums and the interest anyway.
- Slips and the T4 Summary go in by the last day of February, tied back to what was actually paid on the PD7A through the year, so nothing in CRA’s matching ever points at your payroll.
- We watch the Ontario Employer Health Tax so you pay only on payroll above the $1,000,000 exemption, and one operator running three branches recovered $2,400 of EHT a prior bookkeeper had paid on exempt payroll.
- Who is an employee and who is genuinely in business alone is settled against the CRA factors of control and integration, because getting a counter worker wrong puts both halves of CPP and EI, plus penalties, on the bureau.
- We confirm that exchanging currency is a financial service under ETA section 123(1), so the exchange itself is an exempt supply carrying no HST, and we stop the costly error of adding 13% to it.
- The exemption blocks recovery, so the tax riding on your rent, security monitoring and armoured transport stays where it is; we restrict those credits instead of leaving an over-claim on the return for CRA to unwind with interest.
- The $30,000 small-supplier threshold is measured against your taxable fee income alone; exempt exchange revenue never enters that calculation, so a bureau turning over millions is not dragged into registration by volume it never earned.
- Where you charge a separate wire or service fee, we determine and document the character of that fee rather than assume it, because the answer drives whether you register, what you charge, and which credits you may claim.
- Where any fee is taxable you become a mixed supplier, so we apportion input tax credits between exempt and taxable use on a fair and reasonable basis, document the method, and apply it consistently each period.
- Owners take enough T4 salary to keep RRSP room accumulating and the rest as dividends, a split that holds combined tax close to 12.2% on what stays in the company instead of the 53.53% top personal rate.
- On incorporation we elect under section 85, filing Form T2057 so fixtures, the safe and goodwill cross at chosen amounts; one owner kept $19,000 of tax deferred that an outright sale of the same assets would have crystallised.
- We plan at least two years ahead so your shares can qualify for the $1.25M Lifetime Capital Gains Exemption, purifying the corporation of passive investments so a future sale of the bureau is sheltered rather than fully taxed.
- We time the purchase of counters, safes and counting equipment before your fiscal year-end so the Class 8 and Class 50 declining-balance rates deliver the largest first-year deduction against a profitable year of spread income.
- Because the tax on rent, security and armoured transport is not recoverable to you, we build the full HST-inclusive cost into the margin work, so a bureau pricing off a recoverable-tax assumption is not quietly losing money.
- We reconstruct the spread earned in each unfiled year from daily rate sheets, till records and bank deposits, so CRA cannot assess your bureau arbitrarily under ITA 152(7) on an estimate built from deposits alone.
- The late-filing penalty runs at 5% of the balance owing with a further 1% for each month outstanding, to a maximum of twelve, so the oldest year goes in first to halt it, which spared one client $6,800.
- We restate any year where gross volume was booked as revenue, because a return filed on turnover reports income the bureau never earned, and one correction reduced restated taxable income by $27,000 across three years.
- Every year you had tellers on the payroll gets its missing T4 slips and its PD7A reconciliation, filed together with the catch-up returns, so per-slip and late-payment penalties are not added on top of the late T2.
- The undepreciated capital cost pools are reconstructed year by year, so capital cost allowance never claimed on Class 8 fixtures and Class 50 computers is picked up while the reassessment period still permits it.
- Asked to justify your input tax credits, we point to ETA section 123(1), show the exchange is a financial service and therefore exempt, and demonstrate the credits were restricted on that footing before any reassessment issues.
- Where CRA argues your reported income is too low for your deposits, we produce the daily till, vault and rate-sheet records that tie the spread to the volume, because ITA 230 books are the answer to that question.
- A weak ledger invites an arbitrary assessment under ITA 152(7), where CRA sets the income itself and you carry the burden of displacing it, so we rebuild the record set before responding rather than afterwards.
- We answer an HST query letter inside its 30-day deadline with the exempt-versus-taxable split and the credit apportionment in one package, because support that arrives late cannot restore a position already disallowed.
- A reassessment is objected to on Form T400A inside the 90-day window, and where the penalties trace back to a prior accountant we apply for taxpayer relief on Form RC4288; one bureau had $8,600 of penalties cancelled.
- We prepare CSRS 4200 compilation engagement financial statements, the Notice to Reader a bank wants across two fiscal years before it approves the operating line a bureau needs to keep working capital on the counter.
- Your compiled statement of financial position presents currency on hand as an asset at a documented year-end rate, so a lender sees a real balance sheet rather than a cash figure that drifts with the market.
- We build the statement of operations on spread revenue rather than turnover, because a bank reading twenty million dollars of volume as sales misjudges the business entirely and prices or declines the facility on a false premise.
- Every compilation carries a CSRS 4200 communication stating that neither an audit nor a review was carried out, together with the basis of accounting and owner withdrawals, and a bank or landlord will not read a file lacking it.
- Compiled statements leave our office inside 30 days of your records and T2 figures arriving, because a conditional offer that lapses takes the financing with it; that timing once held a $75,000 operating line open.
- Incorporation under the Ontario Business Corporations Act puts limited liability around the bureau and brings the rate on active income to roughly 12.2% combined, so profit you do not draw is no longer taxed at 53.53%.
- A Form T2057 election carries the safe, the counters, the fixtures and the goodwill into the new corporation at chosen amounts, which is what stops a taxable gain arising merely because those assets changed hands.
- We open the corporation’s CRA Business Number and payroll account and close the proprietorship accounts inside the first thirty days, so the same teller payroll is never reported twice under two different numbers.
- The share register is built with voting and non-voting classes from the outset, which is what later allows dividends to reach family shareholders and lets more than one $1.25M Lifetime Capital Gains Exemption apply on a sale.
- We model the break-even first, because incorporation adds annual T2 and filing cost, and an owner earning $70,000 of spread and drawing all of it usually gains nothing until there is real surplus to leave behind.
- We rebuild months or years of missing books from daily rate sheets, till tapes and bank deposits, posting the spread to the period it was actually earned rather than the month the cash reached the account.
- We separate exempt exchange revenue from any separately charged fee income across the rebuilt period, so the catch-up books report each stream the way the corporate and HST returns will need to see it.
- We reconstruct the vault position at each year end by denomination and currency, so the revaluation rests on a count and a documented rate instead of a figure reverse-engineered to make the books balance.
- Where an owner has left three years unrecorded, we typically surface $12,000 or more of deductible rent, security, armoured transport and licensing costs never claimed, cutting the corporate tax owing on the catch-up returns.
- Three years of catch-up is normally finished 45 days after your records reach us, and you are handed reconciled monthly figures, so the following daily close lands in the books the week it actually happens.
- Where your bureau operates a US branch or subsidiary serving cross-border customers, we determine whether that income is effectively connected to a US trade or business and file Form 1120-F where an obligation exists.
- Where a US C-corporation or single-member LLC sits in your structure, we file Form 1120 together with Form 5472, the information return required of any foreign-owned US entity, so the $25,000 penalty for leaving it out never arises.
- We apply the Canada-US tax treaty to test whether your bureau has a US permanent establishment, so an owner whose only American contact is an occasional counter is not taxed twice on the same dollar of spread.
- We coordinate FBAR and Form T1135 foreign-property reporting where the corporation holds a US bank account and the reporting threshold is met, because a foreign deposit counts even when it earns nothing at all.
- US tax already paid is credited against your Canadian T2 through the foreign tax credit, and for operators with a real presence on both sides of the border that routinely keeps $10,000 or more a year from being taxed twice.
- Spread income that never made it onto a return is brought forward on Form RC199 under the CRA Voluntary Disclosures Program, putting years of missing revenue back on record ahead of any audit or deposit-matching letter.
- Three conditions are tested before anything is lodged: the disclosure has to be voluntary, it has to be complete, and it has to be at least a year overdue. Once CRA has made contact the door has closed.
- Because the exchange itself is an exempt supply, a disclosure usually corrects unreported income tax alone; where you also charged a fee determined to be taxable, we address the GST/HST that genuinely should have been collected.
- We quantify what was left off past T1 or T2 returns from till records, rate sheets and bank deposits, so the disclosed figures withstand the reviewer scrutiny that always follows a cash-business disclosure.
- A successful application relieves gross-negligence penalties that can reach 50% of the tax owing and reduces arrears interest, once saving an owner who had under-reported $90,000 of spread income more than $23,000.
Currency Exchange Spread & HST Check
Six quick questions on spread revenue, the exempt exchange, your input tax credits, the year-end vault revaluation, separately charged fees and whether it is time to incorporate. No fee shown.
1. Are you recording the spread as revenue rather than the gross value of currency exchanged?
2. Are you correctly NOT charging HST on the exchange itself?
3. Are you treating the HST on rent, security and armoured transport as non-recoverable?
4. Is the currency in your vault counted and revalued at a documented rate each year end?
5. Have you determined and documented the character of any separate wire or service fee?
6. Is your currency exchange business incorporated yet?
Free CPA Consultation for Currency Exchange Businesses
Case Studies: Currency Exchange Accounting & Tax
Waterloo Currency Exchange — Twenty Million in Turnover Booked as Revenue
The problem: A Waterloo currency exchange had been booking the gross value of every transaction as sales, so its income statement showed revenue in the millions against an almost identical cost of sales. The bank had already repriced its operating line off those statements, the owner believed the business was far larger than it was, and the T2 filed on that basis reported figures that matched nothing CRA would expect from a bureau of its size.
What we did: We restated three years onto spread revenue, posting only the margin retained on each trade to the income statement and leaving turnover as a volume statistic. We rebuilt the comparative figures, refiled the affected T2 returns, and gave the bank a corrected set of statements with a plain explanation of what had changed and why.
The result:
- $27,000 of restated taxable income corrected across three years
- Statements finally show the spread the bureau actually earns
- Operating line repriced on figures the bank can rely on
Burlington Exchange Bureau — Credits Claimed Against Exempt Revenue
The problem: A Burlington exchange bureau had been claiming input tax credits on rent, security monitoring and armoured transport as though its counter revenue were taxable. Exchanging currency falls inside the financial service definition at ETA section 123(1); that makes the exchange an exempt supply, which carries no HST and leaves the tax on the inputs behind it stranded. Every filing period added to an over-claim that a single CRA review would have reversed with interest.
What we did: We quantified the credits taken in error, corrected the exempt-supply position, and determined and documented the character of the separate wire fee the bureau also charged. We then adjusted the affected returns and set up an apportionment method for the taxable stream, written down and applied the same way each period.
The result:
- $16,800 of input tax credits reversed before CRA assessed them
- Fee character determined and documented, not assumed
- Exempt-supply position clean and supportable going forward
Whitby Currency Exchange — Building the Daily Till, Vault and Rate-Sheet Record Set
The problem: A Whitby currency exchange ran two counters on a shoebox of paper. There was no daily till close, no vault count between year ends, and the rates applied each day were never written down. Deposits were large, declared income was modest, and nothing connected the two. On that record set a CRA question about unreported income would have been answered with an arbitrary assessment under section 152(7) rather than with evidence.
What we did: We built the record set from scratch: a daily close for each window, a vault count by denomination and currency, and a dated rate sheet retained every day. We tied the three together into a monthly reconciliation that proves the spread against the volume, and trained the counter staff to run it without us.
The result:
- Daily till, vault and rate-sheet records now complete
- Reported income provable against deposits every month
- Section 230 books maintained by staff, not rebuilt yearly
Our clear, efficient process ensures every step is transparent, building trust and long-term client relationships.
Kickoff (Document Request)
Collect prior T2 returns, daily till and rate-sheet records, year-end vault counts, payroll and T4 records, lease and security contracts, and bank statements.
First 30 Days (Cleanup & Setup)
QuickBooks Online or Xero configured, the income statement rebuilt on spread rather than throughput, your exempt-supply position confirmed, and till, vault and fee tracking switched on.
Monthly Close
Monthly reconciliations, daily till and rate-sheet matching, vault counts, payroll and PD7A source deductions, and exempt-versus-taxable revenue tracking.
Quarterly Planning Review
Salary and dividend mix, spread margin review, input-tax-credit apportionment, fee-character documentation, and the incorporation break-even.
Year-End Close & T2 Filing
Trial balance, vault revaluation with realised and unrealised movement split, financial statements on spread revenue, T2 with GIFI, payroll slips, and CRA preparation.
Get Your Currency Exchange Taxes Done Right Today
Affordable Pricing for Currency Exchange Businesses
We believe in clear, upfront pricing so you know exactly what to expect. All fees include HST.
- Tax Preparation (Corporation) — From $400
- Tax Return Filing (Corporation) — From $400
- Tax Compliance Audit — FREE CRA audit support for our clients
- Tax Strategy — FREE for our clients
- Accounting Base Plan — From $100 per month
- Bookkeeping Management — Free for our Accounting clients
- Financial Reporting — Free for our Accounting clients
- Business Formation — Flat $35
- Incorporation Process — Flat $35
- Entity Setup Assistance — Flat $35
- Full-Service Payroll — From $125 per month
Payment is by Interac e-Transfer to info@gondaliyacpa.ca only. Security question: Not Applicable, as auto-deposit is enabled.
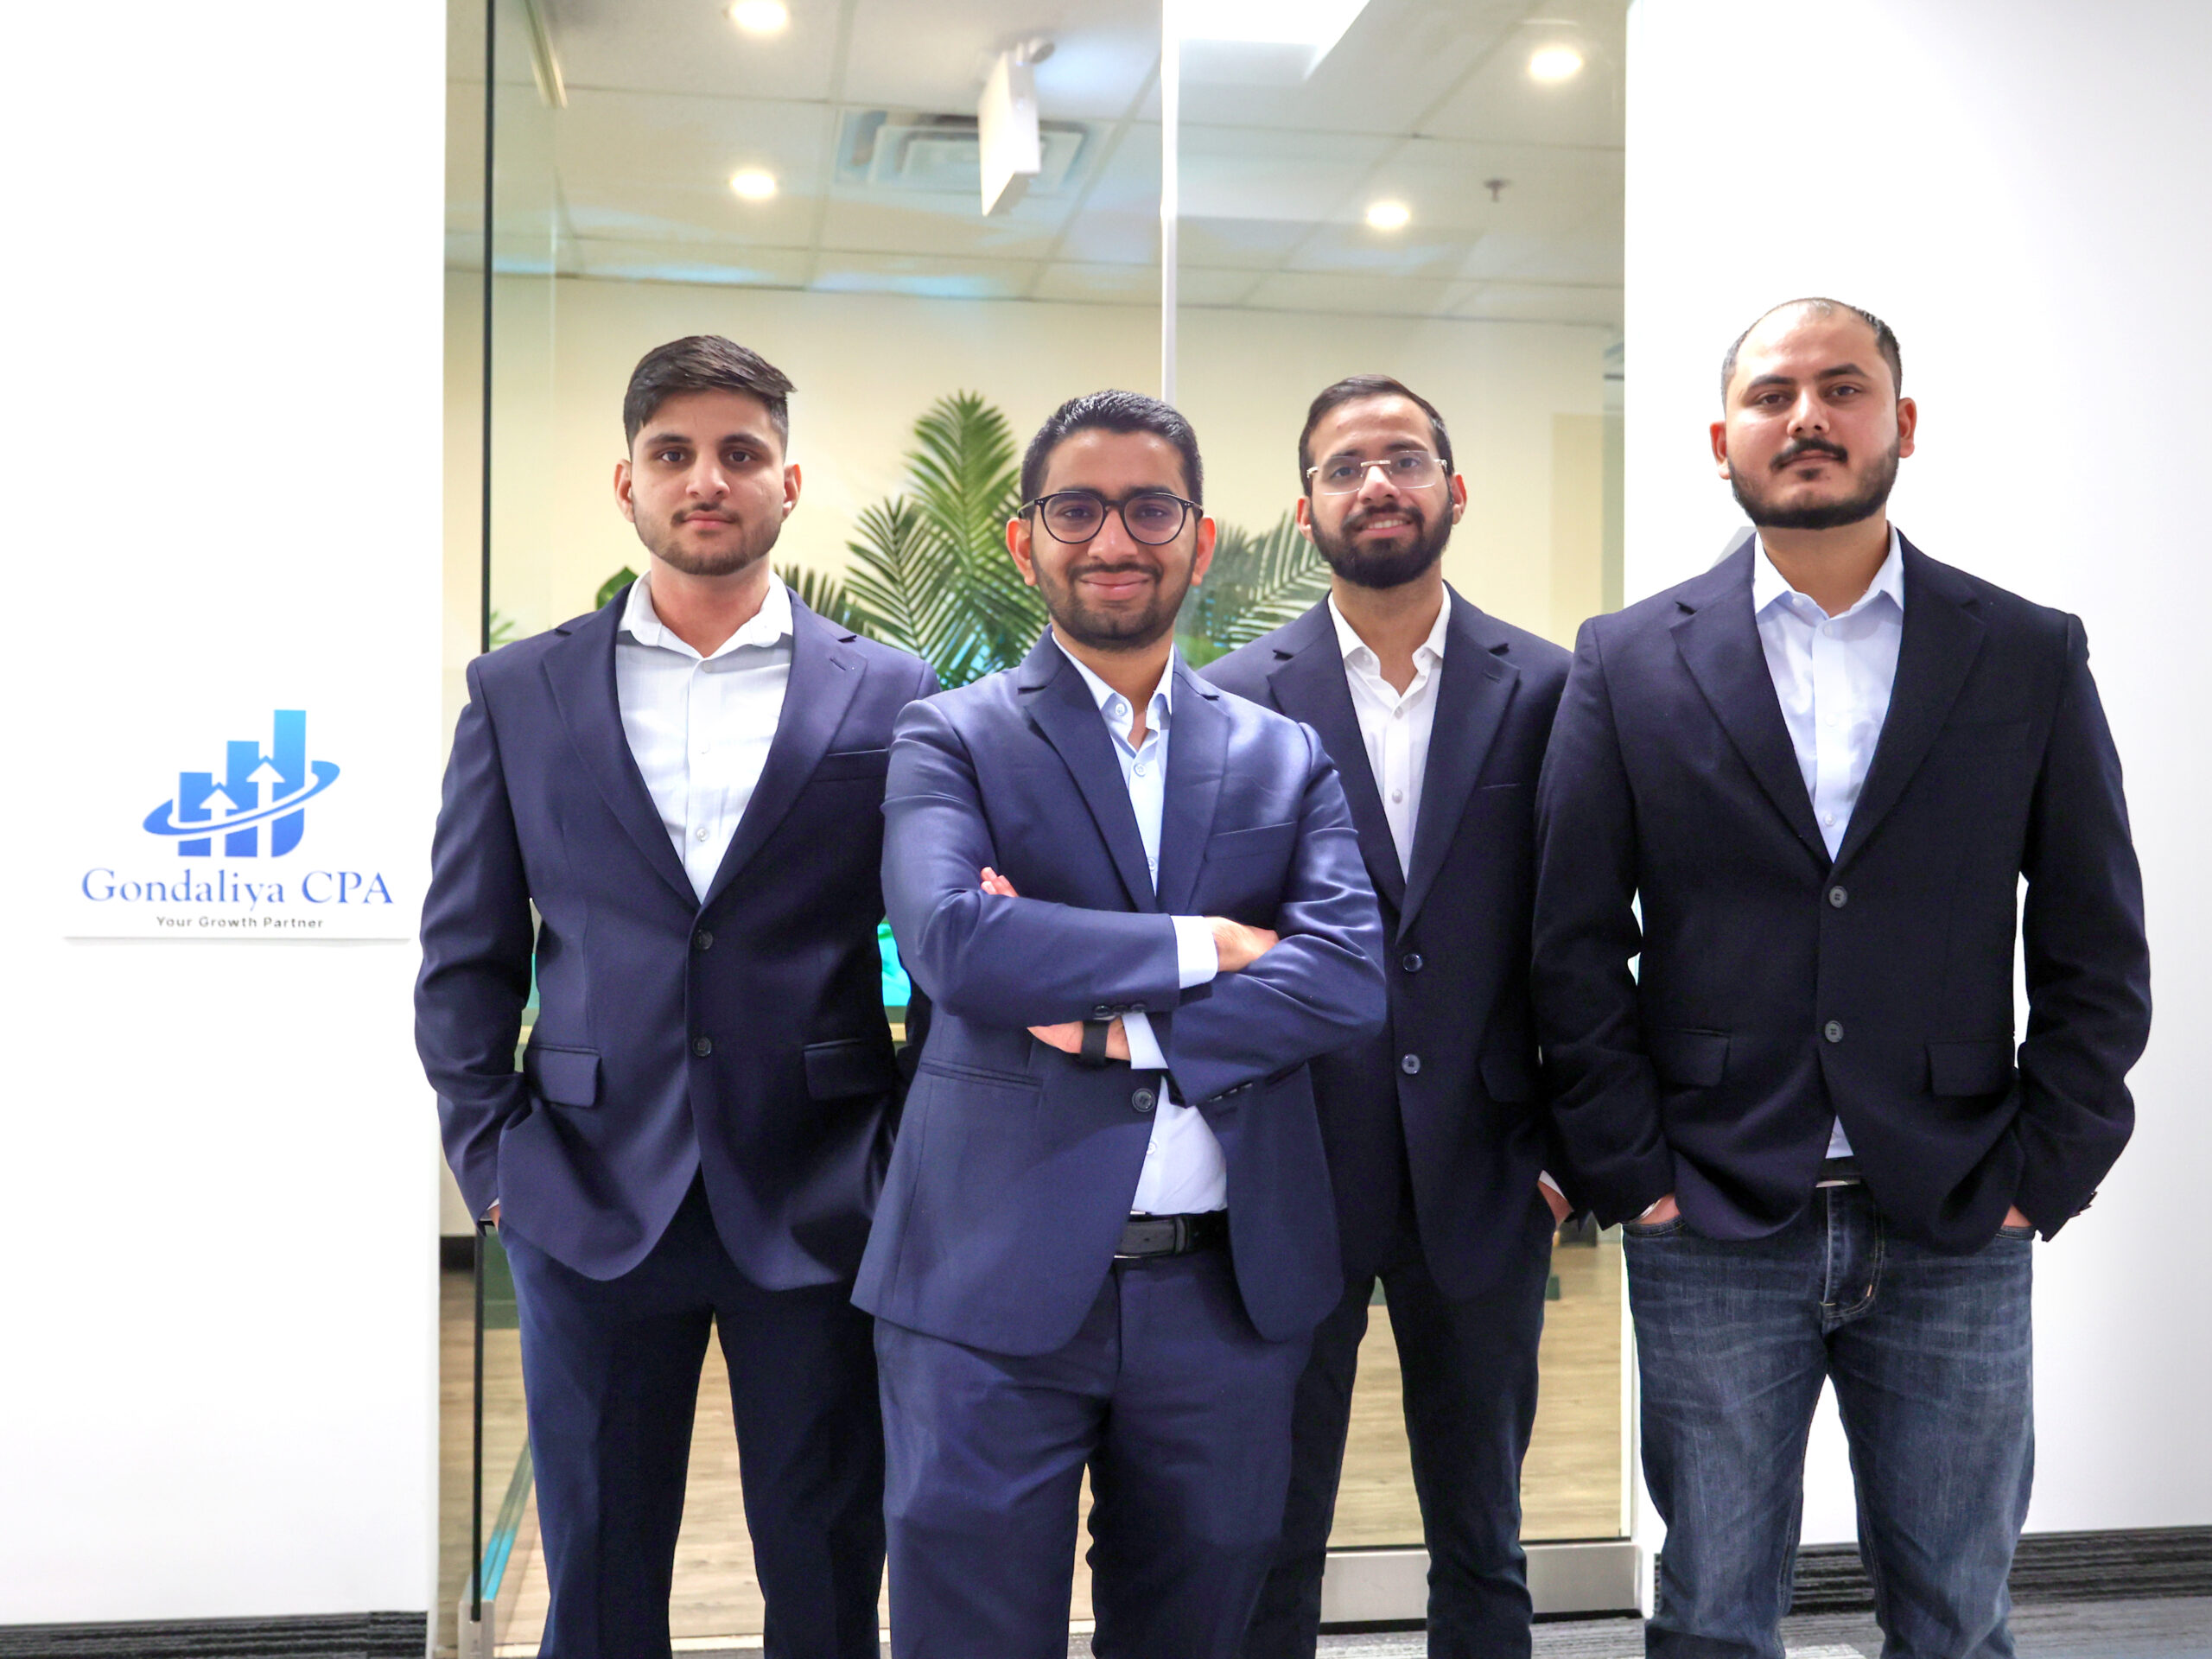
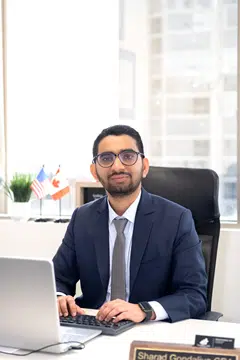
Meet Your Lead Currency Exchange Accountant
Meet your lead currency exchange accountant. As your spread and corporate tax adviser, you deal with the same two people every year.
What Our Clients Say
1300+ five-star reviews from currency exchange and small-business owners across Ontario and Canada.
Serving Currency Exchange Businesses Across Ontario
We act for currency exchange operators the length of Ontario, from single-window storefronts to multi-branch groups. We understand how spread revenue, the exempt exchange, restricted input tax credits, the year-end vault revaluation and teller payroll actually flow through a bureau, what CRA looks at on a cash-intensive file, and where the real margin sits once the cost of holding currency is counted.
Toronto (ON)
55 Queen St E Ste 1205, Toronto, ON M5C 1R6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Mississauga (ON)
5373 Bullrush Dr, Mississauga, ON, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Brampton (ON)
4 Starhill Crescent, Brampton, ON L6R 2P9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Scarborough (ON)
24 Clementine Square, Scarborough, ON M1G 2V7, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Vaughan (ON)
19 Cabinet Crescent, Woodbridge, ON L4L 6H9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Oshawa (ON)
210 Durham St, Oshawa, ON L1J 5R3, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Ottawa (ON)
2090 Neepawa Ave a314, Ottawa, ON K2A 3L6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Etobicoke (ON)
60 Stevenson Rd #1601, Etobicoke, ON M9V 2B4, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Hamilton (ON)
70 Starling Dr, Hamilton, ON L9A 0C5, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Guelph (ON)
1155 Gordon St, Guelph, ON N1L 1S8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Windsor (ON)
4387 Guppy Ct, Windsor, ON N9G 2N8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
North York (ON)
150 Graydon Hall Dr #912, North York, ON M3A 3B2, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Currency Exchange Accounting & Tax FAQs
Related Industries We Serve
Accountant for Money Service Businesses
- Exempt and taxable revenue split
- Corporate tax filing and financial statements
- Bookkeeping and cash records
Accountant for Private Lenders
- Exempt financial services and HST
- Corporate tax planning and T5 reporting
- Bookkeeping and loan ledgers
Accounting for Small Businesses
- Corporate tax planning for small businesses
- Business tax filing and financial statements
- Payroll and bookkeeping services
Accountant for Incorporated Businesses
- T2 corporate returns and GIFI
- Salary, dividend and SBD planning
- Compilation statements and incorporation
Currency Exchange Accounting & Tax Done Right.
T2 filing, spread revenue rather than turnover, the exempt exchange under ETA section 123(1) and restricted input tax credits, year-end currency revaluation with realised and unrealised movement split, daily till and rate-sheet records, T4 teller payroll, incorporation and the $1.25M capital gains exemption under one roof. AFFORDABLE flat fees, no hourly billing. Licensed CPA Ontario. 1300+ five-star reviews. 30-Day Money-Back Guarantee.