



Tax Accountant for Fulfillment Centres in Ontario and Across Canada
Nothing on your racking belongs to you. A fulfillment centre accepts delivery of a client’s units, keeps them safe and releases them on instruction, which is a bailment for reward rather than a purchase, so title stays with the client and the units never join your own stock. Subsection 10(1) of the Income Tax Act values the inventory you do own at the lower of cost and fair market value, and what you own is cartons, void fill, tape, labels and pallets. We bill your two real supplies apart: storage, which runs with time on occupied space, and pick and pack, which runs with activity on each order worked, both taxable at 13% under the Excise Tax Act. Damage to goods in your custody is a claim against you rather than a write-down, and paragraph 18(1)(e) refuses a general provision for what might be claimed later. Racking, conveyors and packing benches go to Class 8 at 20% and scanners and servers to Class 50 at 55%. Peak crews are withheld and remitted on the PD7A, and the receiving and cycle-count record is built for the six years section 230 expects. AFFORDABLE fixed fees, quoted before we start.
AFFORDABLE Fulfillment Centre Tax Accountant
Walk the floor of a fulfillment centre and almost every dollar of value in sight is somebody else’s. The units arrived on a client’s purchase order, they leave on a client’s sales order, and in between you count them, keep them dry and answer for them. That relationship has a name. Goods are delivered into your custody for reward, to be dealt with on the depositor’s instructions and then returned or forwarded onward, and the one event that never occurs is a sale to you. It is a bailment, and everything awkward about the accounting follows from it. Stock you never acquired cannot be valued, so the client’s units fall outside the computation subsection 10(1) of the Income Tax Act asks for. The part nobody tells operators is what falls inside it: your inventory line is cartons, void fill, tape, labels, stretch wrap, pallets and shipping supplies, bought by you and owned by you. You also sell two things rather than one, space and work, earned on different clocks. And when a skid is crushed or a count comes up short there is no asset of yours to write down, because the asset was never yours; what exists is a claim against the custodian. At Gondaliya CPA we build the ledger around custody instead of ownership, so the numbers on your return describe the business you are actually running.
Our fulfillment clients run third-party warehouses holding retail and online stock, pick-and-pack floors shipping direct to consumers, bulk storage and transload sites, returns-processing operations and kitting and assembly providers across Ontario. We stay on the file through the whole year instead of appearing once each spring, and we tell you what your own inventory is worth, which of your two revenue streams is carrying the building, and where holding somebody else’s property has quietly become a tax exposure nobody priced.
Let us carry the ledger and the filings while your attention stays on the floor and the dock.
Our Official Partners
Accounting That Understands How a Fulfillment Centre Actually Works
A fulfillment centre has a balance sheet that looks almost bare beside the value of the goods in the building, revenue that arrives on two unrelated triggers, a wage bill that trebles for eight weeks and then stops, and a risk measured in other people’s property. Those four facts are what we build the ledger and the tax position on, for warehouse operators right across Ontario.
Stay Compliant and Minimize Your Fulfillment Centre Tax
Two things have to happen at once in a building this busy: every return goes in on the day it is due, and every deduction the operation has genuinely earned is actually inside it. We run the T2, the HST periods and the source-deduction cycle to the calendar, and we chase the capital cost allowance, the input tax credits and the packaging, consumable and freight costs that quietly go unclaimed where nobody has time to file.
Accounting & Tax Experts for Fulfillment Centres
- AFFORDABLE + Registered CPA Firm
- Business and Corporate Tax Expert
- Small & Medium Business Expert
- Accounting, bookkeeping, and tax filing
- CPA (Chartered Professional Accountant)
- 1450+ 5-star Google reviews
- 30-Day Money-Back Guarantee
- 60-Day Fees Matching Policy
Why Choose Our Accounting Services for Fulfillment Centres?
Tax Planning — Custody, Capital and the Limit
Client goods stay off your inventory, capital spending is timed against the Class 8, Class 10, Class 50 and Class 12 rates, and active income is held under the small business limit.
Consulting — Which Stream Pays for the Building
Our bookkeeping posts space against occupied positions and work against orders completed, so you can finally see which of the two carries the rent and which one you are giving away.
CRA Representation — Records, Claims and Counts
When CRA asks whose goods those are, or why a provision was deducted, we assemble the agreements, the receiving records and the counts and answer the letter ourselves.
Bookkeeping — Cash Across a Peak
We model the cash hole between paying a peak crew and being paid for what it shipped, build the statements an equipment lender wants, and set the exit structure early.
Google Reviews
Fulfillment Centre Clients
Fulfillment Centre Tax and Accounting Services in Ontario
Corporate Tax Filing (T2) for Fulfillment Centres
T2 preparation with client-owned goods kept out of your subsection 10(1) inventory, your own packaging stock valued, racking in Class 8, scanners in Class 50, and recapture settled on every disposal.
Bookkeeping & Accounting for Fulfillment Centres
Books that post space by occupied position and work by order completed, with a custody record for client-owned goods running beside the ledger instead of inside it.
Payroll Services for Fulfillment Centres
Payroll for a permanent core and a seasonal surge: source deductions on the PD7A, the February slips reconciled, T4A where the engagement calls for it, WSIB registered and employer health tax watched.
GST/HST Filing for Fulfillment Centres
AFFORDABLE HST filing with 13% charged on storage and on pick and pack as two supplies, money taken before occupancy held to the period it is earned, and tax recovered on equipment and packaging.
Tax Planning for Fulfillment Centres
Where in the year the capital spend lands, how the owners draw, keeping active income under the small business limit, and getting ready for the sale you will want one day.
Corporate Catch-Up Filing for Fulfillment Centres
Late T2 and HST periods brought in, the capital pools and your own packaging stock reconstructed year by year, and the corporation put back onside with CRA.
CRA Audit Resolution for Fulfillment Centres
Support on why a full building reports little inventory, on damage and shortage provisions, and on records adequacy, carried from the first letter through to resolution.
CPA Financial Statements (Notice to Reader) for Fulfillment Centres
CPA-compiled statements equipment and facility lenders accept, with client-owned goods disclosed and unearned storage presented for what it is.
Incorporation Services for Fulfillment Centres
The company built from scratch, name search through articles and share classes, with racking, equipment and goodwill rolled in on Form T2057 under section 85.
Catch-Up Bookkeeping Services for Fulfillment Centres
Years of storage and handling billing, equipment invoices, receiving documents and packaging purchases reconstructed and reconciled until the asset and inventory schedules are finally right.
US Corporation & LLC Tax Filing for Fulfillment Centres
Filing on both sides where an owner, a shareholder or an affiliated warehousing company sits in the United States, with withholding and T1135 reporting handled in the same pass.
Voluntary Disclosure Program for Fulfillment Centres
Come forward on HST missed on storage or handling, prepaid space never deferred, unreported recapture or client goods carried as your own, and let a Voluntary Disclosures Program submission take the penalties off.
Accounting & Tax Services Tailored for Fulfillment Centres
Practitioner-level CPA work for third-party warehouses, pick-and-pack fulfillment floors, bulk storage and transload sites and returns-processing operations across Ontario — built for a business whose largest number in the building is a number it does not own.
- Storage revenue, pick-and-pack revenue, inbound receiving charges, kitting and returns handling each get a line of their own on Schedule 100 and Schedule 125, rather than reaching CRA as a single undivided fee total.
- Client units held under a bailment are not your property, so they stay outside the inventory that subsection 10(1) of the Income Tax Act values at the lower of cost and fair market value.
- What does belong in that computation is the packaging you bought: cartons, void fill, tape, labels, stretch wrap and pallets, counted and valued at your year end exactly like the stock of any other business.
- Capital cost allowance on Schedule 8 puts racking, shelving, conveyors and packing benches in Class 8 at 20%, a yard vehicle in Class 10 at 30%, and scanners, servers and workstations in Class 50 at 55%.
- A forklift can fall either way, so we state which and why: treated as a vehicle in your operation it sits in Class 10 at 30%, treated as fixed warehouse equipment it belongs in Class 8 at 20%.
- Storage accrues with time and handling accrues with activity, so the two post to separate accounts against separate drivers: occupied pallet positions counted by the day, and orders, lines and units counted by the shift.
- Client-owned goods are tracked in a custody record that runs alongside the ledger rather than inside it, because what you are measuring there is a duty of care, not an asset belonging to the corporation.
- Where a client buys a block of space before occupying it, the money arrives ahead of the service: paragraph 12(1)(a) of the Income Tax Act pulls it into income, and the paragraph 20(1)(m) reserve pushes recognition back to the period the space is used.
- We split the cost side the way the revenue side splits, with facility rent, racking and utilities behind the storage line and labour, packaging, consumables and courier charges behind the handling line.
- Equipment purchases, packaging buys, utility accounts and freight bills come in through Dext and get reconciled monthly, so every deduction is backed by paper and no recoverable tax quietly stays unclaimed.
- A peak brings crews in for eight or ten weeks, and the obligations follow the engagement: where a worker is your employee, income tax, CPP and EI come off every single run and go to CRA against the PD7A.
- Where a worker is genuinely independent the T4A reports the payment, and where the worker is yours the T4 does, so we file whichever slip the arrangement actually in front of us produces.
- Remitting late is penalised on a sliding scale that reaches 10% at the top, so the November payroll that has trebled in size is precisely the one you least want to be late with.
- The February deadline for the T4 slips and the T4 Summary is the last day of the month, and we agree them to what was genuinely remitted on the PD7A so any gap shows up in January, not in a CRA letter.
- WSIB coverage attaches from the first hire, and Ontario employer health tax begins once annual payroll passes $1,000,000, so we watch the running total and tell you in advance which year you cross it.
- Storage and pick and pack are two taxable supplies made in Ontario rather than one, and each carries 13% HST under the Excise Tax Act whether your client is a brand, a retailer or another operator.
- We set the tax point on each stream against its own trigger, because a monthly charge for space held and a per-order charge for work done are invoiced on different events and reconcile to different records.
- Once four consecutive calendar quarters of taxable supplies add up to more than $30,000, registering stops being optional, so we keep that rolling total in front of you right through a busy season.
- A deposit becomes consideration under subsection 168(9) of the Excise Tax Act only at the moment it is set against what is owed, whereas money paid up front for a named service is consideration on payment under subsection 168(1).
- Input tax credits come back on racking, conveyors, scanners, lift equipment, packaging, facility rent, utilities and the third-party courier charges you incur, which in a year holding a fit-out is a substantial refund.
- Where in the fiscal year you buy matters, because 20% on Class 8 racking and 55% on a Class 50 scanner fleet reward two quite different purchase dates, and we plan the spend around that.
- Strip out racking, retire a conveyor line or trade a lift truck above what the class still carries, and subsection 13(1) of the Income Tax Act recaptures the excess, so disposals get planned rather than discovered afterwards.
- Roughly 11.2% (from July 1, 2026) combined is what Ontario asks on the first $500,000 that section 125 covers, and the measure is active business income, so the value of goods crossing your dock never eats into that limit.
- We set how the owners take money out, weighing T4 salary that builds registered savings room against dividends, so the real cost of moving profit into your hands is decided ahead of the filing rather than after it.
- Selling the shares one day may bring the $1.275M lifetime capital gains exemption under section 110.6 into play, but only for a company tidied up well in advance, so we start testing the conditions years out.
- We rebuild storage and handling revenue separately across your unfiled years from bank deposits, the warehouse system exports and the invoices that were actually issued, so each return rests on a reconstructed record.
- Packaging and consumable stock is valued at every missed year end, because a catch-up return showing no inventory whatsoever in a building full of cartons and pallets will not survive a first look.
- Filing the earliest outstanding year ahead of the later ones slows the compounding of late-filing penalties and arrears interest, and that ordering on its own changes what the final bill comes to.
- Equipment written off outright in a missing year is moved into its proper class and the pools rebuilt forward, because racking taken as an expense on purchase flatters one year and shortchanges each one that follows it.
- For properly overdue years, Form RC199 opens a Voluntary Disclosures Program file ahead of any contact from CRA, so long as the submission is unprompted, complete and more than twelve months late.
- When CRA asks why a building holding millions of dollars of goods reports almost no inventory, we produce the storage agreements, the receiving records and the custody register that show whose property it actually is.
- A blanket accrual for damage and shortage claims yet to come is not an allowable deduction, since paragraph 18(1)(e) of the Income Tax Act shuts out reserves and contingencies that no other provision has opened.
- A specific amount that has genuinely been determined and become payable on a settled claim stands on entirely different ground, and we document which side of that line every item on the file sits.
- Subsection 152(7) lets CRA assess on a basis other than the return where the records behind it do not hold up, and the onus of displacing that assessment then sits squarely with the taxpayer.
- Where a reassessment is simply wrong we file the objection, and where penalties and interest piled up because a previous adviser got something wrong we apply for taxpayer relief on Form RC4288.
- We prepare compilation engagement financial statements across two fiscal years under CSRS 4200, which is what a lender wants in front of it before advancing on racking, a conveyor line or a facility fit-out.
- The statement of financial position shows your own inventory for what it is, packaging and consumables, with the client-owned goods in the building disclosed in a note instead of inflating the asset side.
- Space sold but not yet occupied sits on its own line, well away from fees earned, so that a reader can tell paid-for space from space a client has genuinely used.
- Each pool shows separately at net book value, racking on one line and conveyors, lift equipment, scanners and vehicles on their own, because no lender prices a sortation line and a yard truck alike.
- We commit to a delivery date when your records come in, because a fit-out decision taken before a peak cannot wait on an accountant who will not put a day in writing.
- Incorporating in Ontario brings the operation inside section 125, where roughly 11.2% combined applies to the first $500,000 of active business income and an unincorporated owner can be looking at 53.53%.
- Form T2057 carries the section 85 election, so racking, lift equipment, scanners, vehicles and goodwill move across at elected amounts and the transfer itself does not crystallise the gain a sale would.
- Every opening capital pool, from Class 8 racking through Class 10, Class 50, Class 12 and Class 13, comes off the invoices behind that transfer, so the first Schedule 8 rests on paper rather than recollection.
- HST, payroll and WSIB are all registered before the first skid comes through the door, so the company can charge, withhold and remit from day one rather than retroactively.
- The chart of accounts separates storage revenue, handling revenue, unearned storage, packaging inventory and the custody register from the very first entry, so the records accumulate correctly instead of needing an expensive cleanup.
- We rebuild months or years of ledger from bank records, warehouse system exports, equipment invoices and timesheets, so an operation that ran two peaks without bookkeeping ends up able to file from its own books.
- Storage and handling are separated retrospectively wherever the billing allows it, because a single blended fee line tells you nothing about which half of the business is paying for the building you occupy.
- The custody position is reconstructed from receiving documents and cycle counts, so client-owned goods are evidenced as somebody else’s property instead of being left looking like unrecorded stock of yours.
- The asset schedule is rebuilt item by item and split into its proper classes, because a neglected file nearly always turns up as a single undifferentiated pool with racking and computers thrown in together.
- Input tax credits buried in unentered equipment purchases, packaging buys, utility accounts and courier invoices are recovered, and the payroll postings are reconciled to the PD7A and to the slips already filed.
- An American citizen or resident among the owners pulls the company into two tax systems at once, so we run the Canadian and the United States filings side by side instead of one after the other.
- A dividend reaching a shareholder who is not resident in Canada carries Part XIII tax, at the rate in the Act or the reduced treaty rate, and the NR4 slip and summary have to follow it out.
- An owner holding specified foreign property above the reporting threshold needs Form T1135, and that regime punishes the silence rather than the tax, so the filing goes in whether or not anything is owing.
- Where the group runs an American warehousing or selling company alongside the Ontario building, we reconcile the two sets of books and keep the charges between them documented and consistent from year to year.
- We align the two filings so foreign tax is actually credited rather than paid twice, which is the single most common cross-border error we take over on a fulfillment file.
- We bring an operation forward where HST was never charged on storage, on handling, or on both, an error that compounds quietly across years in a building issuing invoices every single week of the year.
- We disclose blocks of space collected in advance and taken straight to revenue, because the income belongs in the period the space was used and restating it changes the result of every open year.
- We disclose recapture nobody reported when racking was stripped out or a lift truck went out the door, since a disposal that was never written down does not quietly disappear on its own.
- We disclose client-owned goods carried as the corporation’s own inventory, an error that overstates the asset side and distorts the income reported for every single year it was allowed to run.
- Acceptance turns on three things at once: the disclosure is unprompted, it is complete, and the year is more than twelve months overdue, so we verify all of that before Form RC199 goes anywhere near CRA.
Fulfillment Centre Custody & Billing Check
Six questions on whose stock sits on your own return, whether space and work are billed as two supplies, where money taken in advance is held, how your HST is charged and whether incorporating is overdue. No fee shown.
1. Are client-owned goods kept out of the inventory on your own return?
2. Are storage and pick and pack billed and posted as two separate supplies?
3. Is space paid for in advance held back until the client occupies it?
4. Is 13% HST charged on the storage fee and on the handling fee alike?
5. Do your receiving records and cycle counts tie to the client agreements?
6. Is your fulfillment centre incorporated?
Free CPA Consultation for Fulfillment Centres
Case Studies: Fulfillment Centre Accounting & Tax
Bolton Fulfillment Centre — The Stock That Was Never Theirs
The problem: A three-client Bolton operator closed every year with the entire contents of the building sitting on its own inventory line. Receiving had been posted as a purchase and shipping as a sale, so a warehouse that had never bought a single unit was reporting closing stock in the hundreds of thousands and income to match. Nothing in the paperwork supported it. The goods came in under storage and fulfillment agreements, were counted in and counted out, and title stayed with the brands the whole way through.
What we did: We read the agreements, established that the goods were held in custody under a bailment rather than acquired, moved them to a custody register kept outside the ledger, and rebuilt the subsection 10(1) inventory from what the corporation genuinely owned — cartons, void fill, stretch wrap and pallets. The affected years were then restated.
The result:
- Client-owned units taken off the corporation’s own inventory
- Closing stock rebuilt from packaging and consumables alone
- Overstated income corrected across the affected years
Caledon Fulfillment Operator — One Invoice, Two Businesses
The problem: A Caledon centre billed each client a single blended monthly amount covering space, labour and materials together. Nothing in the ledger pulled the two apart, so when a large account doubled its stored volume and halved its order count, the operator could not say whether it had gained work or lost it. Space is earned with time and work is earned with activity, and with both inside one figure neither stream could be measured against its own costs, repriced, or explained to a lender.
What we did: We rebuilt the rate card around the two supplies, posting occupied pallet positions by the day and orders, lines and units by the shift, with facility costs behind one and labour and packaging behind the other. HST at 13% continues to apply to each, now against records that reconcile to their own triggers.
The result:
- Space and work billed and posted as separate supplies
- Margin per client visible on both streams for the first time
- Each HST figure now ties to its own underlying record
Grimsby Fulfillment Centre — A Reserve That Was Not Deductible
The problem: A Grimsby operator had been accruing a standing provision each year for the damage and shortage claims its clients might bring, and deducting it. The reasoning was understandable — goods get crushed and counts come up short — but the deduction was not available. Paragraph 18(1)(e) of the Income Tax Act closes the door on reserves and contingent amounts that no other provision opens, and nothing opened this one. A review letter had already arrived.
What we did: We reversed the general provision, then worked through the claims file item by item to identify the amounts that had actually been determined and become payable, which stand on quite different ground. We also rewrote the loss allocation in the client agreements, so who bears a shortage is settled in writing before it happens rather than argued afterwards.
The result:
- General damage provision reversed before the review closed
- Determined and payable claims identified and treated separately
- Loss allocation written into the client agreements
Our clear, efficient process ensures every step is transparent, building trust and long-term client relationships.
Documents We Ask For
Prior T2 returns and notices of assessment, the client storage and fulfillment agreements, your rate card, warehouse system exports, receiving and cycle-count records, racking and equipment invoices, payroll records, the facility lease and bank statements.
First Month: Cleanup and Setup
QuickBooks Online or Xero mapped to storage and handling as two separate streams, a custody register stood up outside the ledger, every capital pool from Class 8 through Class 13 rebuilt off the original invoices, and your own inventory counted for the first time.
The Monthly Cycle
Occupied positions and orders completed both posted, space sold in advance held back, the HST return prepared with input tax credits claimed on equipment and packaging, and payroll reconciled to the PD7A.
Planning Each Quarter
Owner compensation, when in the year the racking and equipment spend ought to land, the doubtful-account position on slow payers, the open claims file, and cash across the gap between a peak and its receipts.
Closing the Year
Trial balance, packaging and consumable inventory valued, unearned storage settled, any recapture or terminal loss on disposals resolved, statements issued, and the T2 and its GIFI lodged.
Get Your Fulfillment Centre Taxes Done Right Today
Affordable Pricing for Fulfillment Centres
We believe in clear, upfront pricing so you know exactly what to expect. All fees include HST.
- Tax Preparation (Corporation) — From $400
- Tax Return Filing (Corporation) — From $400
- Tax Compliance Audit — FREE CRA audit support for our clients
- Tax Strategy — FREE for our clients
- Accounting Base Plan — From $100 per month
- Bookkeeping Management — Free for our Accounting clients
- Financial Reporting — Free for our Accounting clients
- Business Formation — Flat $35
- Incorporation Process — Flat $35
- Entity Setup Assistance — Flat $35
- Full-Service Payroll — From $125 per month
Payment is by Interac e-Transfer to info@gondaliyacpa.ca only. Security question: Not Applicable, as auto-deposit is enabled.
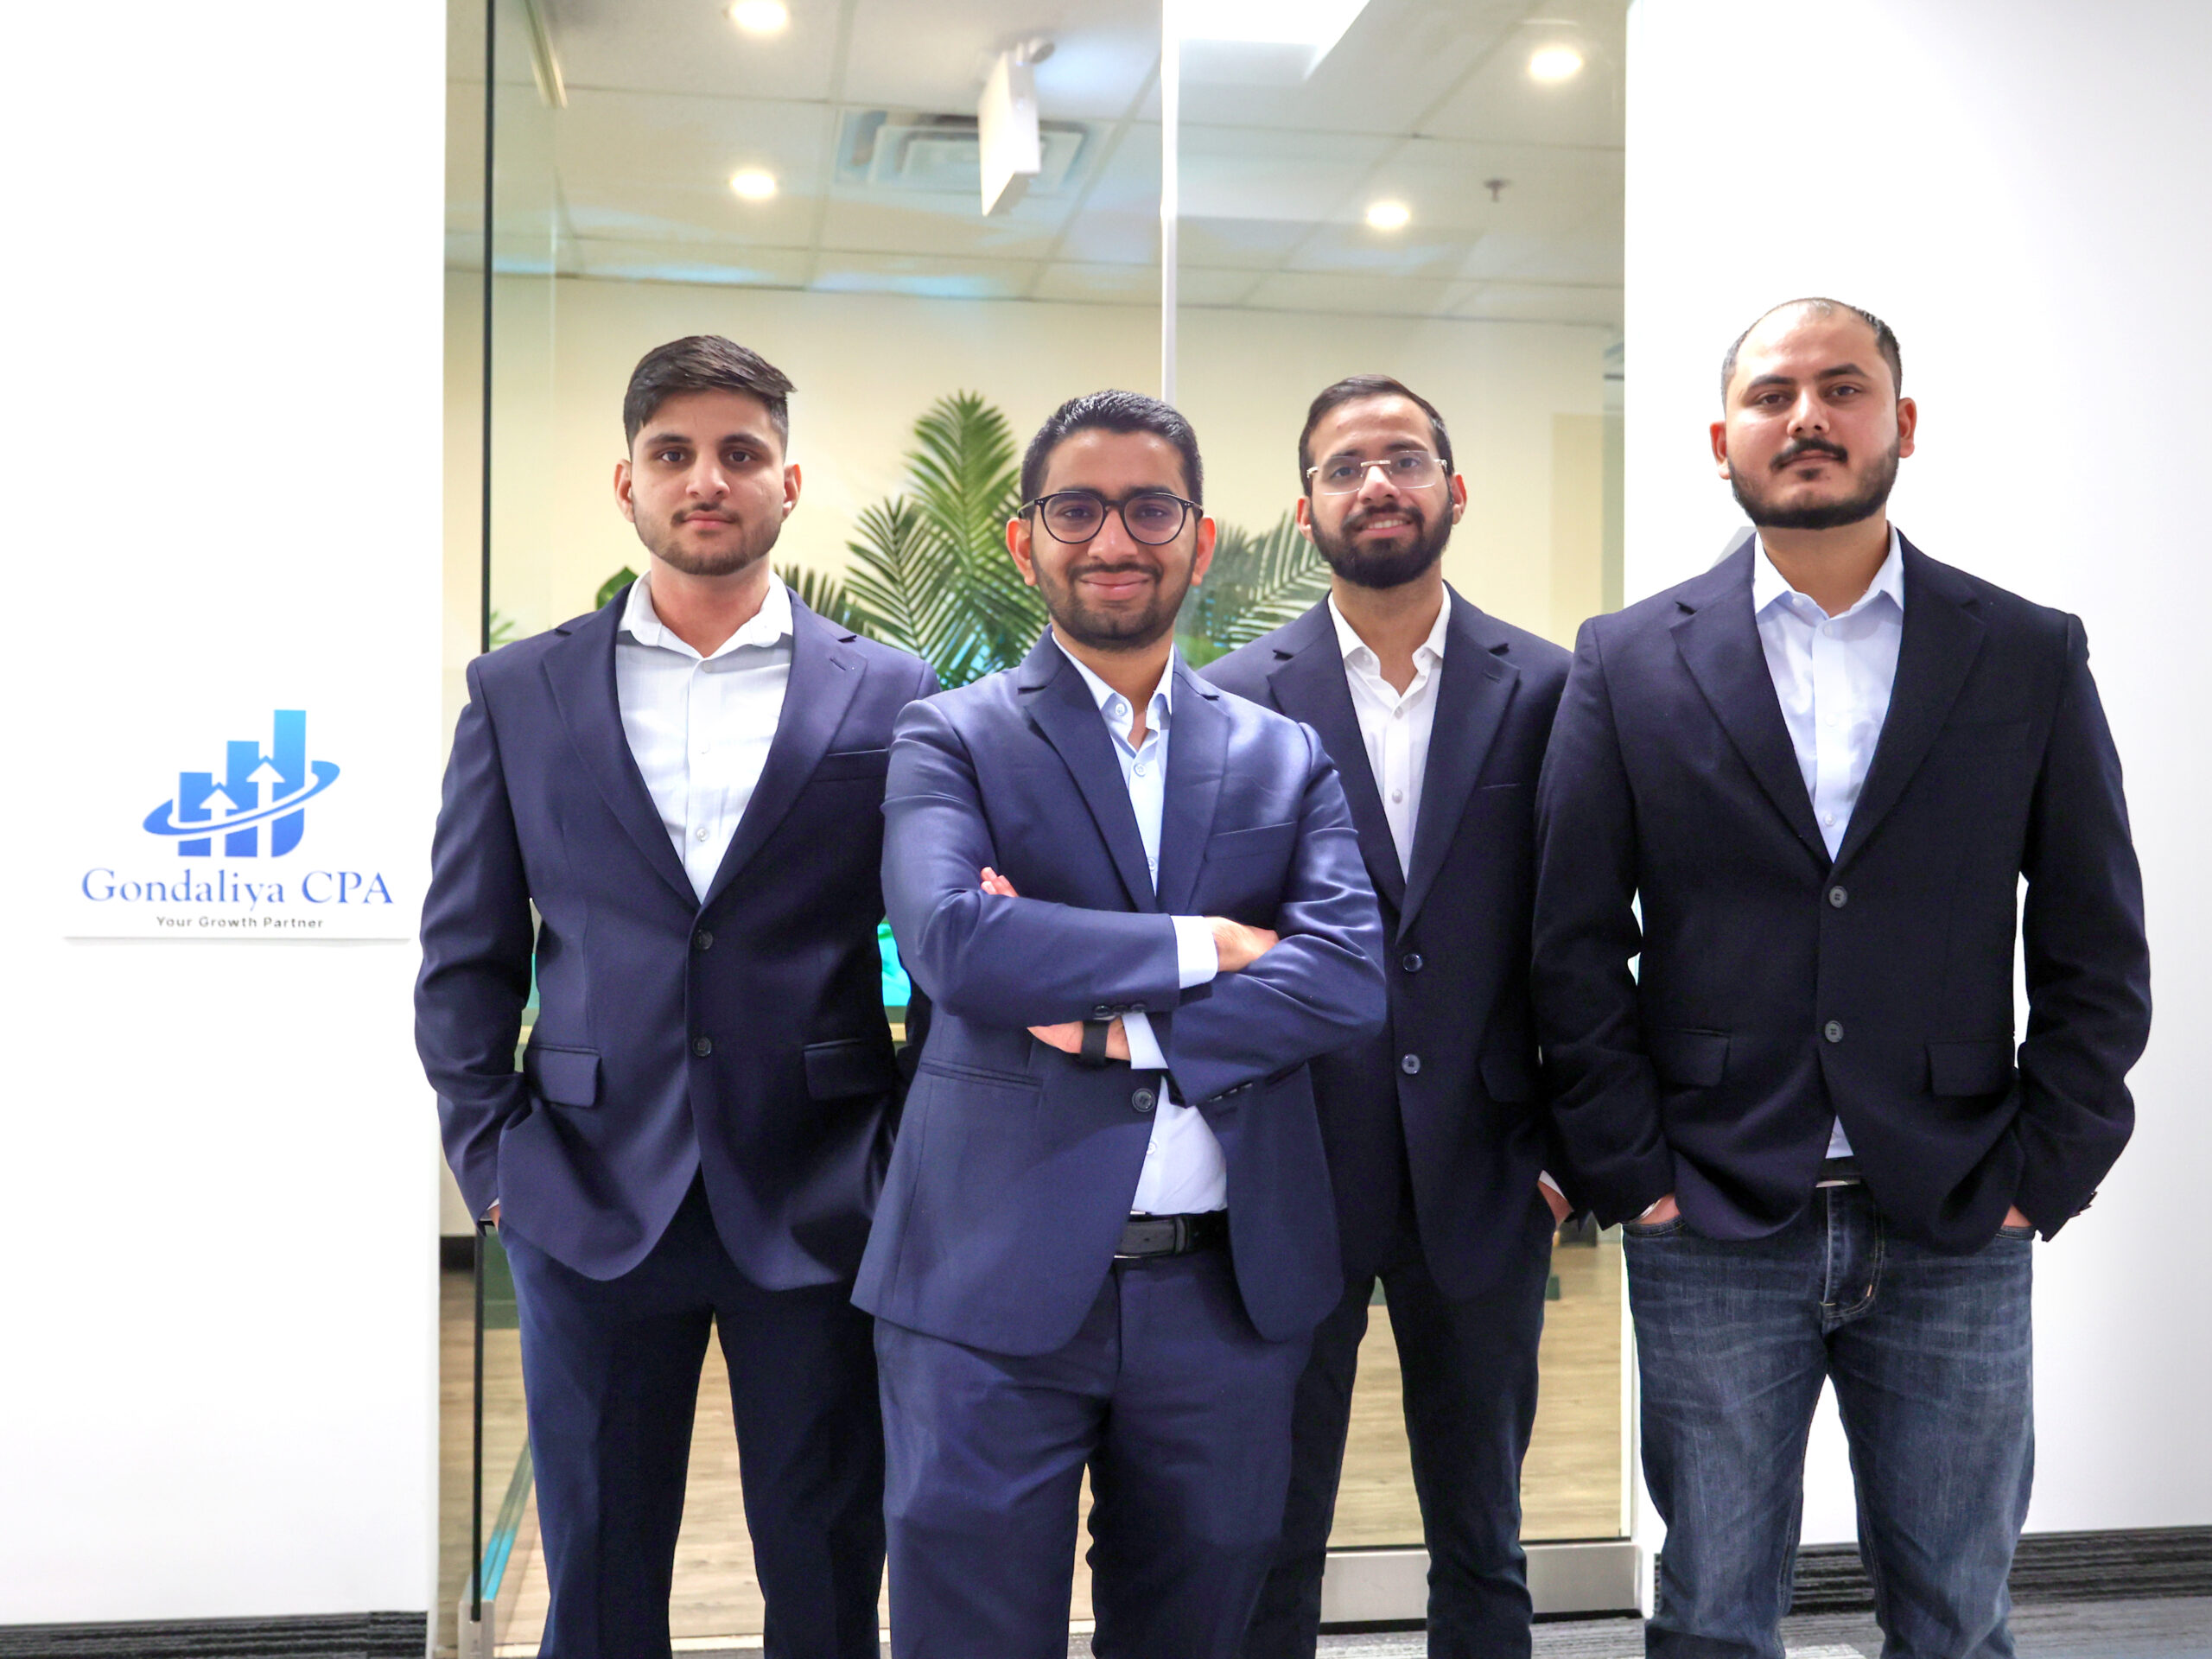
Meet Your Lead Fulfillment Centre Accountant
Two people hold your file and they do not rotate. The same CPA who signs off and the same accounting specialist count your own stock, build the T2 and sit across from you at every planning review.


What Our Clients Say
Owners of warehouses and fulfillment floors are among the people behind more than 1450 five-star Google reviews of this practice.
Serving Fulfillment Centres Across Ontario
Our CPA practice supports fulfillment centres, third-party warehouses and pick-and-pack operations throughout Ontario. We know why the goods stacked in your building are not your inventory, why space and work are two supplies, and why a shortage on somebody else’s stock is a claim against the custodian rather than a write-down.
Toronto (ON)
55 Queen St E Ste 1205, Toronto, ON M5C 1R6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Mississauga (ON)
2100 Camilla Rd #716, Mississauga, ON L5A 2J8
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Brampton (ON)
4 Starhill Crescent, Brampton, ON L6R 2P9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Scarborough (ON)
24 Clementine Square, Scarborough, ON M1G 2V7, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Vaughan (ON)
19 Cabinet Crescent, Woodbridge, ON L4L 6H9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Oshawa (ON)
210 Durham St, Oshawa, ON L1J 5R3, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Ottawa (ON)
2090 Neepawa Ave a314, Ottawa, ON K2A 3L6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Etobicoke (ON)
60 Stevenson Rd #1601, Etobicoke, ON M9V 2B4, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Hamilton (ON)
70 Starling Dr, Hamilton, ON L9A 0C5, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Guelph (ON)
1155 Gordon St, Guelph, ON N1L 1S8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Windsor (ON)
4387 Guppy Ct, Windsor, ON N9G 2N8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
North York (ON)
150 Graydon Hall Dr #912, North York, ON M3A 3B2, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Fulfillment Centre Accounting & Tax FAQs
Related Industries We Serve
Delivery Businesses
- Route revenue and vehicle capital pools
- Source deductions and WSIB registration
- T2 with quarterly planning reviews
Last-Mile Delivery
- Per-stop and per-parcel revenue coding
- Driver pay reconciled to the PD7A
- Overdue years filed and CRA letters answered
Courier Companies
- Worker status reviewed and documented
- HST on freight and accessorial charges
- Compiled statements a lender will read
Wholesale E-Commerce Sellers
- Goods you own valued for the T2
- Channel revenue separated by stream
- Rollovers elected on Form T2057
Fulfillment Centre Accounting & Tax Done Right.
T2 filing with the goods in your building treated for what they are — held in custody under a bailment, never acquired, and therefore outside the inventory subsection 10(1) values at the lower of cost and fair market value — while the cartons, void fill, tape, labels and pallets you do own are counted and valued properly. Storage and pick and pack billed and posted as two supplies on two triggers, both at 13%, with space sold in advance held back until it is occupied. Damage and shortage treated as claims rather than write-downs, because paragraph 18(1)(e) refuses a general provision for what has not yet been determined. Racking, conveyors and packing benches in Class 8 at 20%, scanners and servers in Class 50 at 55%, small tools and warehouse software in Class 12, a yard vehicle in Class 10 at 30%, and subsection 13(1) recapture whenever an asset leaves. Peak payroll withheld and remitted on the PD7A, WSIB from the first hire, and a receiving and count record built for the six years section 230 expects. AFFORDABLE fixed fees quoted up front. Registered CPA firm in Ontario. 1450+ five-star reviews. 30-Day Money-Back Guarantee.