



Tax Accountant for Truck Dispatch Businesses in Ontario and Across Canada
You find the freight, somebody else owns it, and somebody else hauls it. The money that moves through the lane is not yours — your income is the dispatch fee, and the two get confused on almost every set of books we inherit. We pull them apart. The fee carries 13% under the Excise Tax Act on every lane, including the ones where the carriage itself was relieved. It is income once your right to be paid it arises, which paragraph 12(1)(b) of the Income Tax Act fixes well before a carrier settlement lands. And the capital cost allowance schedule is built around the short list a dispatch office genuinely owns: Class 50 workstations, Class 8 furniture, Class 12 software. Flat AFFORDABLE fees, never hourly.
AFFORDABLE Truck Dispatch Tax Accountant
A dispatch business is one of the few operations in freight that owns nothing on the road. No equipment, no cargo, nothing of its own anywhere on the road. What you sell is the work of finding a lane, negotiating a rate and keeping a carrier moving, and what you are paid is a fee — very often a percentage of whatever that carrier collects on the load. The percentage is where the trouble starts. Because your fee is calculated off a number that belongs to someone else, that larger number has a habit of climbing into your revenue line, and once it does, the books describe a business several times the size of the one you actually run. Every ratio a lender calculates moves, your registration dates look wrong, and nothing in the file explains why. Separating the fee from the freight it was measured against is the first thing we do on a dispatch file, and it is the thing almost nobody arrives having done.
The second problem is quieter and more expensive. Dispatchers who arrange cross-border and international lanes see relief applied to the carriage itself and assume the same treatment reaches the fee for arranging it. It does not. Arranging a movement and performing it are two different supplies made to two different people, and each is tested on its own terms. We work with single-desk dispatchers billing a handful of carriers, dispatch offices running twenty or thirty units across Ontario lanes, and operations that handle cross-border freight for carriers based well outside the province.
Let us take the fee ledger and the filings so you can stay on the phone covering loads.
Our Official Partners
Accounting That Understands How a Truck Dispatch Business Actually Works
Almost every other business in freight owns something — equipment, cargo, a warehouse, a yard. A dispatch business owns a desk, a phone and a relationship, and is paid a fee measured against money that passes through other people’s hands entirely. That single fact decides your revenue line, your registration date, your HST treatment and the moment your income is earned. At Gondaliya CPA we build the file around the fee, not around the freight the fee was calculated from.
Stay Compliant and Minimize Your Truck Dispatch Tax
On this file the compliance work and the planning work turn out to be the same work, because both rest on one answer. What did you supply, and who did you supply it to? Settle that, and your returns, your registration dates and your deductions stop being arguments.
Accounting & Tax Experts for Truck Dispatch Businesses
- AFFORDABLE + Registered CPA Firm
- Business and Corporate Tax Expert
- Small & Medium Business Expert
- Accounting, bookkeeping, and tax filing
- CPA (Chartered Professional Accountant)
- 1300+ 5-star Google reviews
- 30-Day Money-Back Guarantee
- 60-Day Fees Matching Policy
Why Choose Our Accounting Services for Truck Dispatch Businesses?
Tax Planning — Fee Timing & Rate
We settle the point at which a per-load fee becomes receivable, plan around the small business limit so your fee income is taxed at the lower corporate rate, and time owner draws against it.
Consulting — What You Actually Supply
We read your dispatch agreements, establish what is being supplied and to whom, and set the HST and revenue treatment that follows — including whether section 177 is in play at all.
CRA Representation — Fees & HST
When CRA questions your revenue figure, an unbilled HST position on cross-border lanes or a reversed fee, we assemble the confirmations and settlements and answer it from the record.
Bookkeeping — Fees Against Settlements
We build the reconciliation that shows fees earned by load beside fees actually paid by each carrier, so you can see which relationships are funding the business and which are not.
Google Reviews
Truck Dispatch Clients
Truck Dispatch Tax and Accounting Services in Ontario
Corporate Tax Filing (T2) for Truck Dispatch Businesses
T2 preparation on a revenue line that carries your fees and nothing else, with fee timing settled on the right to be paid and capital cost allowance claimed properly on Schedule 8.
Bookkeeping & Accounting for Truck Dispatch Businesses
A fee ledger built load by load and carrier by carrier, reconciled every month against the settlements that actually paid, so earned and collected never get confused.
Payroll Services for Truck Dispatch Businesses
Payroll for your dispatch staff, WSIB registered before the first hire, remittances agreed to the PD7A, and the February slip filings handled without a scramble.
GST/HST Filing for Truck Dispatch Businesses
AFFORDABLE HST filing with 13% charged on the dispatch fee, cross-border lanes handled correctly, and registration timing checked against the $30,000 threshold.
Tax Planning for Truck Dispatch Businesses
When a per-load fee is earned, how reversals land, how owners take money out of fee income, and the share structure a future sale will depend on.
Corporate Catch-Up Filing for Truck Dispatch Businesses
Overdue T2 and HST years rebuilt from confirmations and settlement statements, with the fee stripped back out of any year that reported gross lane value.
CRA Audit Resolution for Truck Dispatch Businesses
Support on revenue figures, unbilled HST on arranged freight and reversed fee adjustments, handled from the first CRA letter through to the final answer.
CPA Financial Statements (Notice to Reader) for Truck Dispatch Businesses
Compiled statements a lender will read without needing an explanation, showing fee revenue, carrier concentration and the receivable position behind it.
Incorporation Services for Truck Dispatch Businesses
Incorporation set up so the corporation opens with a chart of accounts that can only hold fee income, plus the tax and payroll accounts it needs immediately.
Catch-Up Bookkeeping Services for Truck Dispatch Businesses
Years of fee invoices, carrier settlements and reversed loads reconstructed and reconciled, so the revenue figure on every open year is finally defensible.
US Corporation & LLC Tax Filing for Truck Dispatch Businesses
Cross-border work where your carriers are American or a shareholder lives outside Canada, including withholding obligations and the owners’ foreign property reporting.
Voluntary Disclosure Program for Truck Dispatch Businesses
Come forward on fee income never reported, HST never charged on arranged freight, or a revenue line built on lane value, and have penalties cancelled.
Accounting & Tax Services Tailored for Truck Dispatch Businesses
Practitioner depth for single-desk dispatchers, dispatch offices covering twenty or thirty units, and operations arranging cross-border lanes for carriers based outside Ontario. Everything on this file starts from one question: what did you supply, and to whom.
- The T2 goes in with GIFI on Schedules 100 and 125, and on the revenue line there are dispatch fees and nothing else, because lane value in that position misstates the business everywhere downstream.
- The freight the carrier bills and collects is the carrier’s revenue, not yours. Where you are paid a percentage of it, the percentage is your income and the remainder never passed through your business at all.
- Under paragraph 12(1)(b) of the Income Tax Act a fee is brought into income when it becomes receivable, so a per-load fee is earned once the load is covered and your right to be paid has arisen.
- Schedule 8 carries the short list a dispatch office actually owns: workstations, monitors and servers at 55% in Class 50, furniture at 20% in Class 8, and purchased software at 100% in Class 12.
- The small business limit under section 125 is measured on active business income rather than on revenue, so the gross value of the lanes you cover passes through the carrier’s books without consuming any part of yours.
- The fee ledger is built load by load and carrier by carrier, so you can see what each relationship earned you in a period rather than one undifferentiated monthly deposit figure.
- Beside it sits the reconciliation that matters most here: fees you earned against fees a carrier actually settled, with the gap aged and attributed to the carrier it belongs to.
- A fee that is reversed after you took it into income is adjusted in the period the reversal arises, with the reason recorded, so the correction can be traced back to the specific movement.
- Records adequate to determine your tax must be kept for six years under section 230 of the Income Tax Act, and on this file that means the rate confirmations and the settlement statements above everything else.
- We run the monthly close in QuickBooks Online or Xero with Dext capturing the paperwork, and we post against confirmations rather than against bank lines, which is where the fee detail actually lives.
- Payroll for the desk runs through us end to end: tax, CPP and EI withheld, remittances matched to the PD7A and sent before the due date, because the penalty for missing one is graduated and climbs to 10%.
- WSIB coverage goes in place from the first person you hire, and we register it before the hire rather than after a claim has already made the question urgent.
- Both the T4 slips and the T4 Summary are due by the final day of February, and we agree them against the remittances already sent so the two records cannot disagree when CRA compares them.
- Where you pay a self-employed dispatcher for services rather than employing them, the fees are reported on a T4A in box 048, and we set that up at the point the arrangement starts.
- Ontario Employer Health Tax becomes payable once annual payroll clears the $1,000,000 exemption, and a dispatch office that grows from three desks to a dozen can reach that line faster than expected.
- Arranging a load is a service you supply to the carrier, and supplied in Ontario it is a taxable supply carrying 13% under the Excise Tax Act, with input tax credits claimed on your own operating costs.
- That stays true on the lanes where the carriage itself was relieved. The treatment of the movement belongs to the movement; relief for the arranging service would have to be found in a provision covering that service.
- The $30,000 registration threshold is measured over four consecutive calendar quarters, and a dispatcher earning a percentage of linehaul clears it on far fewer loads than the number most people picture.
- Where the arrangement means you genuinely act as agent in making the carrier’s supply, section 177 of the Excise Tax Act decides who is treated as making it and who accounts for the tax.
- Every return is reconciled to the fee ledger before it is filed, because a return that cannot be tied back to the records behind it is the fastest route to a CRA question.
- A flat monthly fee, a percentage of linehaul and a fixed amount per covered load are earned at three different moments, and the planning has to follow the moment the right to payment arises.
- A sum put aside now against loads that might fall over later is a contingent amount, and paragraph 18(1)(e) of the Income Tax Act refuses it as a deduction until the event actually happens.
- Retained fee income carries a combined Ontario rate of about 12.2% up to the $500,000 business limit under section 125, and we test the associated corporation rules whenever a second company is involved.
- Owner compensation is planned against that rate rather than drawn on instinct, and we model salary against dividend each year instead of repeating whatever last year’s bookkeeper happened to do.
- The lifetime capital gains exemption under section 110.6 shelters up to $1.25M of gain on a qualifying share sale, and it needs the share structure to be right years before you look for a buyer.
- We rebuild the unfiled years from the confirmations and the carrier settlements, establishing load by load what the fee actually was, because that single figure changes the taxable income of every year involved.
- Where an earlier year reported gross lane value as revenue, we strip it back to fee income and restate, which usually shrinks the reported business dramatically without altering a dollar of real profit.
- A late corporate return attracts a penalty set against the unpaid balance plus a further monthly charge for each month it stays outstanding, capped at twelve months, so the order you file the backlog in matters.
- Every missing year needs its own capital cost allowance calculation, so the pools get rebuilt forward from the earliest open year with each asset sitting in the class that actually fits it.
- Unbilled HST on fees for arranging cross-border freight is quantified in the same exercise, since it is the exposure that most often sits unnoticed behind a dispatch backlog.
- When CRA asks why your revenue is so small beside the freight value moving through your lanes, we produce the dispatch agreements, the confirmations and the settlements that show what you were actually paid.
- The Income Tax Act lets CRA assess on its own basis under subsection 152(7) without being bound by what it was handed, which is why the file behind your figure matters more than the figure.
- On an HST review of arranged freight we set out the supply you made, the person you made it to and the basis on which tax was or was not charged.
- Where reversed and cancelled fees are questioned, we show each adjustment against the movement it relates to and the period it was taken in, which is usually what closes the point.
- Relief from penalties and interest is sought on Form RC4288 where the cause was a genuine error or a circumstance beyond your control, and we assemble the supporting narrative with you.
- We produce compilation engagement statements for your lender under the relevant CPA Canada compilation standard, covering the comparative years a credit decision on a service business of this size normally reaches back over.
- Revenue on the face of the statements is fee income, which means a reader sees the business as it is instead of guessing which part of a blended figure belonged to carriers.
- Carrier concentration is disclosed, because a dispatch business earning most of its fees from two or three carriers carries a risk a lender should be told about rather than discover later.
- Receivables are aged against each carrier’s real settlement behaviour, so the schedule reflects who pays in two weeks and who pays in two months instead of one averaged assumption.
- Complete records in, statements out inside 30 days, which on this file is usually the difference between an operating facility being approved in a quarter and being deferred to the next one.
- Incorporating separates you personally from the obligations the business takes on, and it taxes retained fee income at the small business rate instead of at a personal rate that tops out above fifty per cent.
- Where an existing unincorporated dispatch operation is moving in, the election under section 85 on Form T2057 transfers goodwill and equipment at agreed amounts rather than at full market value.
- Opening capital cost allowance balances are set from that transfer, with computer equipment, office furniture and software each landing in their own class rather than in one undifferentiated pool.
- We open the corporation’s tax, HST and payroll accounts as part of the setup, so the first fee it invoices is billed, collected and reported by the entity that actually earned it.
- The chart of accounts is built so that only fee income can reach the revenue line, which is far cheaper than the reconstruction we are usually asked for three or four years later.
- Neglected books get rebuilt from the bank record, the fee invoices and the carrier settlements together, because no single one of those three sources tells you what was earned in a period.
- Every movement in the backlog is tied to the fee it generated, which stops a settlement deposit being read as revenue when part of it was a reimbursement or a correction.
- Reversed and cancelled loads are matched back to the fee originally taken, so the caught-up ledger shows the adjustment rather than a revenue figure nobody can explain two years later.
- Equipment bought over several years usually sits in one undifferentiated account, and we take it apart so computers, furniture and software each land where they belong before any claim is calculated.
- Input tax credits sitting unclaimed in software subscriptions, phone and internet, professional fees and office rent are recovered across the open periods as part of the same catch-up work.
- Dispatching for carriers whose base is in the United States raises two questions we settle before your first invoice: where the service is treated as supplied, and which system taxes the fee.
- Part XIII tax at 25% applies to a dividend leaving Canada for a non-resident shareholder unless a treaty cuts the rate, and the NR4 reporting behind it is part of the same obligation.
- Form T1135 is required from the owners once the cost of their specified foreign property exceeds $100,000, and the penalty for filing it late applies regardless of whether any tax was payable.
- Where a shareholder is a United States citizen or holds a green card, American reporting obligations reach into a Canadian corporation, and we prepare both returns as one piece of work.
- Foreign tax credits only work where both returns are reconciled against each other, and we prepare them as one exercise so the same income is not taxed twice in two countries.
- Where fee income was never reported, or a revenue line was built on gross lane value, the correction reaches every open year at once and a disclosure is a better route than a reassessment.
- Form RC199 goes in as the taxpayer agreement, backed by a reconstruction built off the confirmations, the carrier statements and the bank, so every corrected year rests on documents instead of estimates.
- The application only stands if you reach CRA before CRA reaches you. That single condition is the difference between a correction you control and a file somebody else has already opened.
- HST never charged on fees for arranging international movements is the single most common item we bring forward on this file, and it is correctable in the same submission.
- A dispatcher who had reported lane value for three years came forward on that basis and had the penalties cancelled, with relief granted on the interest that had accumulated meanwhile.
Truck Dispatch Fee & HST Check
Six quick checks: what sits on your revenue line, whether the fee carries tax, when you book it, how carrier settlements reconcile, how reversals are treated, and whether a corporation makes sense. No fee shown.
1. Does your reported revenue hold your dispatch fees and nothing else?
2. Is 13% charged on your dispatch fee on cross-border lanes as well?
3. Is a per-load fee recorded when the load is covered, not when it settles?
4. Do you reconcile fees earned against fees each carrier actually paid?
5. Are reversed or cancelled fees adjusted in the period they arise?
6. Is your truck dispatch business incorporated?
Free CPA Consultation for Truck Dispatch Businesses
Case Studies: Truck Dispatch Accounting & Tax
Stouffville Dispatch Office — The Fee That Was Never Taxed
The problem: A Stouffville dispatcher covered almost entirely cross-border lanes and invoiced its carriers without charging tax on any of it. The reasoning was understandable and wrong: the carriage was relieved, so the fee for arranging the carriage was treated as relieved too. Several years of fee invoices had gone out that way, and no return had ever shown tax collected on a dispatch fee.
What we did: We separated the two supplies on paper — the carriage the carrier performed for the shipper, and the arranging service the dispatcher supplied to the carrier — quantified the unbilled tax across the open periods, and brought the position forward.
The result:
- Fee treated as its own supply from that quarter onward
- Open periods corrected before any CRA contact
- Invoice template rebuilt so tax cannot be omitted again
Bowmanville Dispatcher — A Business Five Times Its Real Size
The problem: A Bowmanville dispatch business recorded the full linehaul value of every load it covered as revenue, then showed the carriers’ share as a cost of sales. The statements presented a company with substantial turnover and a margin of a few per cent. Its bank read it exactly that way, declined an operating line on the margin, and nobody could explain why the cash in the business bore no relation to the revenue figure.
What we did: We restated revenue to the dispatch fees the business had actually earned, removed the carriers’ freight from both the top and the cost line, and reconciled every period to the settlement statements behind it.
The result:
- Revenue restated to fee income only, with no change to profit
- Margin presented at the level the business genuinely runs at
- Operating line reassessed on statements the lender could read
Alliston Dispatcher — Earned on Settlement, Reserved Against Nothing
The problem: An Alliston dispatcher recorded each fee only when the carrier’s settlement arrived, sometimes two months after the load was covered, which pushed income across a year-end with no basis for doing so. Separately, a lump provision had been set aside each year against loads that might be cancelled in the next one, deducted in full, with nothing identifying a single specific load behind it.
What we did: We moved recognition to the point the fee became receivable, reversed the general provision, and replaced it with period-by-period adjustments recorded against the specific movements that were actually cancelled or clawed back.
The result:
- Fee recognition moved back to the year of the work
- Contingent provision removed from the deduction schedule
- Reversals now traceable to the load that caused them
A sequence with no hidden steps in it. At any point you can see which documents sit with us, which piece of work is open, and what lands next.
Kickoff (Document Request)
Prior T2 returns, your dispatch agreements with each carrier, the fee basis on every one, rate confirmations, carrier settlement statements, your fee invoices, payroll records, equipment purchases and bank statements.
First 30 Days (Cleanup & Setup)
Strip any carrier freight out of the revenue line, establish what you supply and to whom, settle the HST position on cross-border lanes, and rebuild the Class 50, Class 8 and Class 12 schedules.
Monthly Close
Fees posted from confirmations as loads are covered, settlements matched against them, reversals recorded in period, HST filed and tied to the fee ledger, payroll and PD7A agreed.
Quarterly Planning Review
Fee timing against the right to payment, carrier concentration and receivable exposure, the small business limit, owner draws, and whether the registration threshold has been passed.
Year-End Close & T2 Filing
Trial balance, statements showing fee revenue with the carrier reconciliation behind it, reversals settled, doubtful amounts and write-offs kept apart, and the T2 with GIFI filed.
Get Your Truck Dispatch Taxes Done Right Today
Affordable Pricing for Truck Dispatch Businesses
We believe in clear, upfront pricing so you know exactly what to expect. All fees include HST.
- Tax Preparation (Corporation) — From $400
- Tax Return Filing (Corporation) — From $400
- Tax Compliance Audit — FREE CRA audit support for our clients
- Tax Strategy — FREE for our clients
- Accounting Base Plan — From $100 per month
- Bookkeeping Management — Free for our Accounting clients
- Financial Reporting — Free for our Accounting clients
- Business Formation — Flat $35
- Incorporation Process — Flat $35
- Entity Setup Assistance — Flat $35
- Full-Service Payroll — From $125 per month
Payment is by Interac e-Transfer to info@gondaliyacpa.ca only. Security question: Not Applicable, as auto-deposit is enabled.
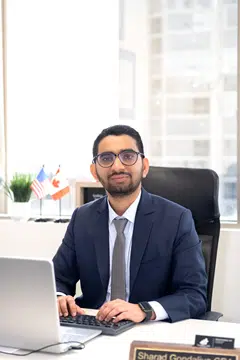
Meet Your Lead Truck Dispatch Accountant
Two people handle this file and they do not change. Whoever reads your dispatch agreements in January is the person who signs off your return in the autumn.
What Our Clients Say
Over 1300 five-star reviews, left by people running transportation, logistics and freight service businesses across Ontario and the rest of Canada.
Serving Truck Dispatch Businesses Across Ontario
Our CPA team works with truck dispatch businesses and dispatch offices throughout Ontario. We know why your revenue line should be far smaller than the freight you move, what has to sit behind the fee figure you reported, and what CRA asks for when it opens a dispatch file.
Toronto (ON)
55 Queen St E Ste 1205, Toronto, ON M5C 1R6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Mississauga (ON)
2100 Camilla Rd #716, Mississauga, ON L5A 2J8
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Brampton (ON)
4 Starhill Crescent, Brampton, ON L6R 2P9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Scarborough (ON)
24 Clementine Square, Scarborough, ON M1G 2V7, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Vaughan (ON)
19 Cabinet Crescent, Woodbridge, ON L4L 6H9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Oshawa (ON)
210 Durham St, Oshawa, ON L1J 5R3, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Ottawa (ON)
2090 Neepawa Ave a314, Ottawa, ON K2A 3L6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Etobicoke (ON)
60 Stevenson Rd #1601, Etobicoke, ON M9V 2B4, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Hamilton (ON)
70 Starling Dr, Hamilton, ON L9A 0C5, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Guelph (ON)
1155 Gordon St, Guelph, ON N1L 1S8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Windsor (ON)
4387 Guppy Ct, Windsor, ON N9G 2N8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
North York (ON)
150 Graydon Hall Dr #912, North York, ON M3A 3B2, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Truck Dispatch Accounting & Tax FAQs
Related Industries We Serve
Accountant for Freight Brokers
- Brokerage revenue reporting and margin
- Carrier payable and claims exposure
- Corporate tax filing and T2 preparation
Accountant for Specialized Haulers
- Permit and escort cost treatment
- Driver payroll and source deductions
- Equipment capital cost allowance pools
Accountant for Fleet Owners
- Equipment financing and CCA planning
- Payroll, WSIB and remittance compliance
- Year-end statements and T2 filing
Accountant for Courier Companies
- Delivery revenue and route costing
- Vehicle and equipment CCA claims
- HST filing and input tax credit recovery
Truck Dispatch Accounting & Tax Done Right.
T2 filing on a revenue line that holds your dispatch fees and nothing a carrier collected, fees brought into income when they become receivable under paragraph 12(1)(b) of the Income Tax Act, 13% charged on the fee under the Excise Tax Act on every lane including the ones where the freight itself was relieved, section 177 considered where the arrangement genuinely makes you an agent in the carrier’s supply, fees earned reconciled against fees settled, reversals recorded in period with no contingent provision claimed against paragraph 18(1)(e), and workstations in Class 50 at 55% with office furniture in Class 8 at 20% and software in Class 12. AFFORDABLE flat fees, no hourly billing. Licensed CPA Ontario. 1300+ five-star reviews. 30-Day Money-Back Guarantee.