



Tax Accountant for Dormant Corporations in Ontario and Across Canada
The business stopped. Nobody closed the company. The reasonable assumption is that with no activity there is nothing to file, and it is wrong in three directions at once. ITA subsection 150(1) requires a T2 for every tax year, within six months of year end, whether or not the corporation carried on business and whether or not tax is payable. The familiar 5% plus 1% per month penalty computes to nil on a nil balance, which is exactly why the years pile up — but ITA subsection 162(7) still reaches a corporation that does not file, at the greater of $100 and $25 a day to a maximum of 100 days, and a demand under subsection 150(2) changes the position again. Then Ontario: since 2021 the Annual Return is filed through the Ontario Business Registry and no longer travels with the T2, and a corporation in default under the Business Corporations Act can be dissolved for it. We bring the years current, close the accounts properly, and tell you plainly whether to keep the shell or end it — at an AFFORDABLE flat fee agreed before the work starts.
AFFORDABLE Dormant Corporation Tax Accountant
Almost nobody sets out to have a dormant corporation. The business wound down, or the contract ended, or the second company turned out not to be needed, and closing it properly was going to be next month’s job. Then the returns stopped, because filing a return for a company with no revenue felt like paperwork for its own sake. Several years later the file is a short stack of unfiled years, an open HST account quietly accruing filing obligations, an Ontario annual return nobody knew had moved, and in some cases a company that has already been dissolved for default without the owner being told.
The owners we act for are not avoiding anything. An owner who closed a practice in 2021 and has had nothing to report since. A couple whose second numbered company holds one rental unit and has never filed. A group with three inactive subsidiaries somebody wants cleaned up before a sale. An estate dealing with a company the deceased had not touched in nine years. A founder restarting a corporation that has been idle for four, and hoping the losses in it are still there. What they share is the belief that inactivity is the same as no obligation, and the discovery that it is not.
None of this is hard to fix. It is simply overdue, and the cost of fixing it goes up quietly while it waits.
Two lines we draw plainly. We give no legal advice on dissolution or revival — the articles and the registry filings that effect either are legal work, and we prepare the tax returns around them and coordinate with your counsel. And we will not tell you on a web page whether to dissolve the company or keep it dormant, because that depends on your loss pool, what the corporation still holds and what you intend to do next. If the business is winding down now rather than long since stopped, see businesses winding down; if it is being sold, see business sellers.
Our Official Partners
Accounting for a Company That Is Doing Nothing
Four things catch owners of inactive corporations, and all four are the result of the same reasonable assumption. None of them is expensive to deal with early, and all of them get worse while nobody looks.
Get the Years Current and the Accounts Closed Properly
The work on a dormant file is almost entirely administrative, which is why it is so often left. It is also why it is cheap to do properly and awkward to do late, particularly once a demand has arrived.
Accounting & Tax Experts for Dormant Corporations
- AFFORDABLE + Registered CPA Firm
- Business and Corporate Tax Expert
- Small & Medium Business Expert
- Accounting, bookkeeping, and tax filing
- CPA (Chartered Professional Accountant)
- 1300+ 5-star Google reviews
- 30-Day Money-Back Guarantee
- 60-Day Fees Matching Policy
Why Choose Our Accounting Services for Dormant Corporations?
Catch-Up Filing — All the Years
Every overdue T2 filed, not just the recent ones, with relief requested on Form RC4288 where the facts support it and the Voluntary Disclosures Program used before the CRA makes contact.
Accounts — Closed, Not Abandoned
The HST and payroll accounts filed up to date and then actually cancelled, so the obligations stop instead of accruing quietly against a company nobody is watching.
Registry — Default Checked
Your Ontario annual return position checked and the corporation’s registry status confirmed, because a company dissolved for default is a problem you want to find before your bank does.
Decision — Dissolve or Keep
The loss pool, the assets still held and your plans weighed against the annual cost of keeping the shell alive, so the choice is made once and deliberately.
Google Reviews
Dormant Corporation Files
Dormant Corporation Tax and Accounting Services in Ontario
Nil T2 Corporate Filing
The return ITA subsection 150(1) requires for every year, with the GIFI schedules a nil year still needs, filed on time from now on.
Catch-Up on Unfiled Years
Every overdue year brought current, in order, including the years an owner assumed did not need filing because there was no income.
Penalty and Demand Response
Where a demand under subsection 150(2) or a penalty under subsection 162(7) has arrived, the filings and the response handled together.
Voluntary Disclosure
Form RC199 before the CRA makes contact where there is exposure rather than simply delay, with relief requested on Form RC4288.
Closing the HST Account
Outstanding nil returns filed and the registration actually cancelled, with the consequences for property still held worked out first.
Closing the Payroll Account
Final T4 slips for any year remuneration was paid, remittances reconciled, and the RP account closed rather than left open.
Registry Status Check
Your Ontario Annual Return position and whether the corporation is in default or has already been dissolved for it.
Loss Pool Review
Non-capital losses over twenty years and net capital losses indefinitely, and what a change of control would do to them.
Dissolve or Keep Dormant
The annual cost of the shell weighed against the losses, the assets and your plans, with the final-year work mapped either way.
Shareholder and Intercompany Balances
The loan balances still sitting in the shell identified and dealt with before they become the reason a dissolution is not simple.
Statements and Records
Compilation engagement statements where a bank, a buyer or an estate needs them, and the record retention a dissolution requires.
CRA Representation
Arbitrary assessments, director liability under ITA section 227.1 and ETA section 323, and objections filed within 90 days.
Accounting & Tax Services Tailored for Dormant Corporations
Real, practitioner-level CPA expertise for owners of inactive corporations: every overdue year filed, the accounts closed rather than abandoned, the registry position checked, and the keep-or-dissolve decision made once.
- ITA subsection 150(1) requires every corporation resident in Canada to file a return of income for each tax year, within six months of the end of that year, whether or not it carried on a business.
- There is no exemption for inactivity, and no threshold below which the obligation stops. A corporation with a bank account holding two hundred dollars has the same filing duty as one with staff.
- A nil year is still a return with schedules: the GIFI information has to be there, the balance sheet still has to balance, and the year end has to match what the registry and the CRA both hold.
- We also set the filing cycle properly so the next year does not drift. Most dormant files became dormant files because one missed deadline turned into a habit nobody revisited.
- And we keep the six years of records ITA section 230 requires, including the two years after a dissolution during which the records of a dissolved corporation still have to be retained.
- This is the work most dormant files actually need: a run of years, often four to nine, filed in order so that the balances carry forward correctly and the loss pool is established where there is one.
- We start by confirming what the CRA actually holds on the account, because an owner’s memory of which years were filed and the account’s own record of it are frequently two different documents.
- Then we work out the real first dormant year from when the business actually stopped, since the final trading year usually has figures in it and is the one most likely to be wrong.
- Where a year has been assessed arbitrarily because nothing was filed, the filed return replaces that assessment, which is normally the fastest way to remove a figure the owner does not recognise.
- We file them all rather than the recent ones only, because a gap in the middle of a run is what generates the next letter, and the cost of the whole set is far closer to the cost of one than owners expect.
- The reason dormant years pile up is a real feature of the rules. The late filing penalty under ITA subsection 162(1) is 5% of the unpaid tax plus 1% per month, and on a nil balance it is nil.
- So owners conclude, not unreasonably, that there is no consequence. But ITA subsection 162(7) imposes, where no other penalty applies, the greater of $100 and $25 for each day of default, to a maximum of 100 days.
- A demand to file served under subsection 150(2) changes the position again, and it is usually the point at which an owner discovers the file exists, several years after it stopped being simple.
- We do not state what any of that would be in your case. We name the provisions, file the returns, and work the numbers out on the actual account rather than on a web page.
- Where relief is available we ask for it on Form RC4288 on the facts, which is a different and better conversation than asking for it after a collections letter has already arrived.
- There is an important difference between a delay and an exposure. Years of nil returns are a delay. Unreported rent from the unit the shell still owns is an exposure, and it is treated differently.
- The Voluntary Disclosures Program on Form RC199 is available before the CRA contacts you, and the whole value of it is in that sequence: disclose first, then file, rather than respond to a letter.
- So we ask the uncomfortable question early. Was there any income in these years at all? Rent, interest, a single consulting invoice, a gain on a property sale nobody mentioned?
- Where the answer is yes, we deal with it through the right channel and request relief from penalties and interest on Form RC4288 where the facts support it.
- Where the answer is genuinely no, we say so plainly and simply file the outstanding years, because a run of nil returns does not need a disclosure programme designed for something else entirely.
- This one has caught more owners than any other change in recent years. The Ontario Annual Return used to travel with the corporate tax return. Since 2021 it does not.
- It is filed through the Ontario Business Registry as a separate filing, which means a corporation whose accountant files only the T2 can be in default of its registry obligations without anybody noticing.
- The consequence is not cosmetic. Under the Ontario Business Corporations Act a corporation in default of its filing obligations may be dissolved by the Director for that default.
- We check your registry position as part of the file, because an owner who finds out their company was dissolved three years ago usually finds out from a bank, a buyer or a lawyer rather than from us.
- A dissolved Ontario corporation may apply to be revived, and property not distributed may have forfeited to the Crown in the meantime, so the sooner that is established the better.
- A GST/HST registrant must file a return for every reporting period, including periods with no activity, until the registration is cancelled. Stopping filing is not the same as closing the account.
- That is why a dormant corporation can accumulate a run of missing returns on an account its owner regarded as finished years earlier, and why the first letter is often about HST rather than income tax.
- A person who has ceased commercial activity generally must request cancellation of the registration rather than simply stop filing, so we file whatever is outstanding and then close the account deliberately.
- Cancellation also has consequences where the corporation still holds property, so we work that through before the account is closed rather than discovering it in the period afterwards.
- Then the payroll account, on the same principle: final T4 slips for any year remuneration was paid, remittances reconciled, and the account closed rather than left open indefinitely.
- This is the part of a dormant file that is genuinely personal rather than corporate, and it is the reason we ask about outstanding remittances before anything else on the engagement.
- ITA section 227.1 makes directors jointly and severally liable for amounts the corporation failed to deduct, withhold or remit, and ETA section 323 does the same for net tax under the sales tax rules.
- In each case an assessment of a director cannot be made more than two years after the person last ceased to be a director, which is the only real limitation in the picture.
- Which means keeping a dormant corporation alive, with yourself in office, is also keeping that two-year clock from starting. Owners are rarely told this and it is often decisive.
- We identify any unremitted source deduction or net tax balance in the shell first, because that is the exposure that does not go away simply because the company stopped trading.
- Sometimes the shell is worth keeping, and the reason is the losses. Non-capital losses carry forward twenty years and net capital losses carry forward indefinitely, which is a real asset.
- We establish the pool from the filed returns rather than from an estimate, which is the first argument for filing the overdue years even where nothing was owing in any of them.
- Then the risk: where control of the corporation is acquired, ITA subsection 249(4) deems a tax year to end, and subsection 111(5) restricts the non-capital losses to income from the same or a similar business.
- So a plan that involves bringing somebody else into the shell, or selling it, needs that restriction modelled first, because the losses are exactly what the buyer thinks they are paying nothing for.
- A dormant corporation can also still be associated with your active one, which means sharing the $500,000 business limit, and that is a live cost of keeping it rather than closing it.
- A corporation that holds something is not dormant in the way its owner usually means. A rental unit, a portfolio, a vehicle, even a bank account earning interest: each produces something to report.
- So we inventory it properly: the bank balance, any property and its cost base, any shareholder loan, any intercompany balance, and anything that was transferred out without being recorded.
- Shareholder loan balances are the most common complication, because they have to be dealt with before a dissolution rather than discovered during one, and they have their own rules.
- Intercompany balances inside a group of companies are the second most common complication, and cleaning up three inactive subsidiaries usually means unwinding those balances first, in the right order.
- Where there is property still held we flag the GST/HST consequence of cancelling the registration before anybody cancels it, because that sequence is an easy one to get the wrong way round.
- This is the decision the whole file exists to support, and we will not make it for you on a web page because it turns on things we need to see.
- Keeping it costs the annual filings, the registry return, the risk of default, the association effect on your active company’s business limit, and the directors’ clock that does not start.
- Closing it costs the final-year work, dealing with whatever the corporation still holds, and giving up the loss pool and the name, which may or may not matter to you.
- So we price both sides on your actual numbers and tell you which we would do, which is a different thing from telling you what the rules are and leaving you to choose.
- If dissolution is the answer, the articles and the registry filings are legal work and we coordinate with your counsel; we prepare and file the final returns and the record retention that follows.
- Sometimes the point is the opposite of closing: the owner wants the company back. A dissolved Ontario corporation may apply to be revived, and a dormant one can simply be restarted.
- A revival brings the missing years with it, so the filings that were not done while the company was dissolved still have to be dealt with, and we deal with them as part of the same exercise.
- Restarting a dormant corporation is a good moment to fix the things that were never right: the year end, the share structure, the accounts that are open and the ones that are not.
- We check whether the losses sitting in the shell will actually be available against the new activity, because the same or similar business test is not a formality where the plan is a different business.
- And we re-open the programme accounts the new activity needs rather than assuming the old ones still work, which is the most common administrative snag on a restart.
- When a demand to file or an arbitrary assessment arrives for a company nobody has thought about in years, we answer it with the filed returns rather than with correspondence about intentions.
- When a director is assessed personally under ITA section 227.1 or ETA section 323, we deal with the amounts and the dates, including when the person actually ceased to hold office.
- When an estate is dealing with a corporation the deceased had not touched, we reconstruct the position from the records that exist and file what is required before the estate can be closed.
- When the loss pool is examined on a restart or a sale, we produce the returns that established it and the analysis of the same or similar business test done at the time.
- We file the Notice of Objection within 90 days of a reassessment, and request relief on Form RC4288 where the history supports it, which on a dormant file it frequently does.
Dormant Corporation Check
Six quick questions on your filings, your accounts and your registry status. No email required, and the result tells you what to deal with first.
1. Are there tax years since the business stopped for which no T2 was filed?
2. Is the corporation’s GST/HST account closed, rather than just unused?
3. Has the Ontario Annual Return been filed since 2021?
4. Does the corporation still hold property, a bank balance or a shareholder loan?
5. Were all payroll and HST amounts remitted before the business stopped?
6. Have you decided whether to dissolve the corporation or keep it dormant?
Free CPA Consultation for Dormant Corporations
Case Studies: Dormant Corporations
Toronto Consultant — Six Years of Nil Returns and a Demand
The problem: A consultant had closed her practice and taken a salaried job. The corporation had no income from that point, so nothing was filed, on the reasonable view that a return showing zeros served no purpose. Six years later a demand to file arrived for several of those years, along with an arbitrary assessment for one of them showing a figure she did not recognise.
What we did: We confirmed what the CRA actually held on the account rather than relying on recollection, established the real first dormant year from when the practice stopped, and filed every outstanding year in order so the balances carried forward correctly. The filed return replaced the arbitrary assessment. We requested relief on Form RC4288 on the facts, and set the filing cycle so the next year would not drift again.
The result:
- Every outstanding year filed, not only the ones demanded
- Arbitrary assessment displaced by the actual return
- Relief requested on the history rather than after a collections letter
Mississauga Numbered Company — Dissolved Without the Owner Knowing
The problem: A couple held one rental unit in a numbered Ontario company. Their previous accountant had filed the T2s and nothing else. When they went to refinance, the lender’s search came back showing the corporation had been dissolved for default some time earlier, which meant the registered owner of the property no longer existed as a corporation.
What we did: We established the registry position and explained how the Ontario Annual Return had moved to the Ontario Business Registry in 2021 and stopped travelling with the corporate tax return, which is how the default happened unnoticed. We set out what revival involves and what forfeiture to the Crown can mean for undistributed property, referred the revival filings to counsel, and prepared the returns for the intervening years.
The result:
- Registry default identified and explained, not guessed at
- Revival handled by counsel with the tax filings prepared alongside
- Annual return now tracked separately from the T2
Ottawa Group — Three Subsidiaries Nobody Had Closed
The problem: An owner-managed group had three inactive subsidiaries left from earlier ventures. All three were still registered for GST/HST with unfiled nil returns, two had shareholder and intercompany balances outstanding, and the group’s active company was sharing the small business deduction limit with companies doing nothing at all.
What we did: We inventoried each business number and its programme accounts, filed the outstanding corporate and sales tax returns, and unwound the intercompany and shareholder balances in the right order before anything was dissolved. We identified the loss pools worth keeping and the shells worth ending, priced each side, and worked with counsel on the dissolutions.
The result:
- All three accounts filed up to date and then closed, not abandoned
- Intercompany balances unwound before dissolution, not during
- Business limit no longer shared with inactive companies
Our clear, efficient process ensures every step is transparent, with no surprises and no hourly billing.
Kickoff (Document Request)
Collect the business number with every programme account, the last filed returns, the year end, the province of incorporation, the date trading stopped and anything the CRA has sent.
First 30 Days (The Position)
Confirm what the CRA holds, what the registry holds, which years are outstanding, and whether any remittance balance or director exposure is sitting in the shell.
Catch-Up Filing
Every overdue T2 filed in order with its schedules, outstanding HST and payroll returns filed, relief requested on Form RC4288 and Form RC199 used where there is exposure.
Accounts and Balances
HST and payroll accounts closed rather than abandoned, shareholder and intercompany balances dealt with, and the loss pool established from the filed returns.
Keep or Dissolve
Both routes priced on your numbers, and either the annual cycle set so it never drifts again, or the final returns prepared alongside your counsel’s dissolution filings.
Get Your Inactive Corporation Back in Good Standing
Affordable Pricing for Dormant Corporations
We believe in clear, upfront pricing so you know exactly what to expect. All fees include HST.
- Tax Preparation (Corporation) — From $400
- Tax Return Filing (Corporation) — From $400
- Tax Compliance Audit — FREE CRA audit support for our clients
- Tax Strategy — FREE for our clients
- Accounting Base Plan — From $100 per month
- Bookkeeping Management — Free for our Accounting clients
- Financial Reporting — Free for our Accounting clients
- Business Formation — Flat $35
- Incorporation Process — Flat $35
- Entity Setup Assistance — Flat $35
- Full-Service Payroll — From $125 per month
Payment is by Interac e-Transfer to info@gondaliyacpa.ca only. Security question: Not Applicable, as auto-deposit is enabled.
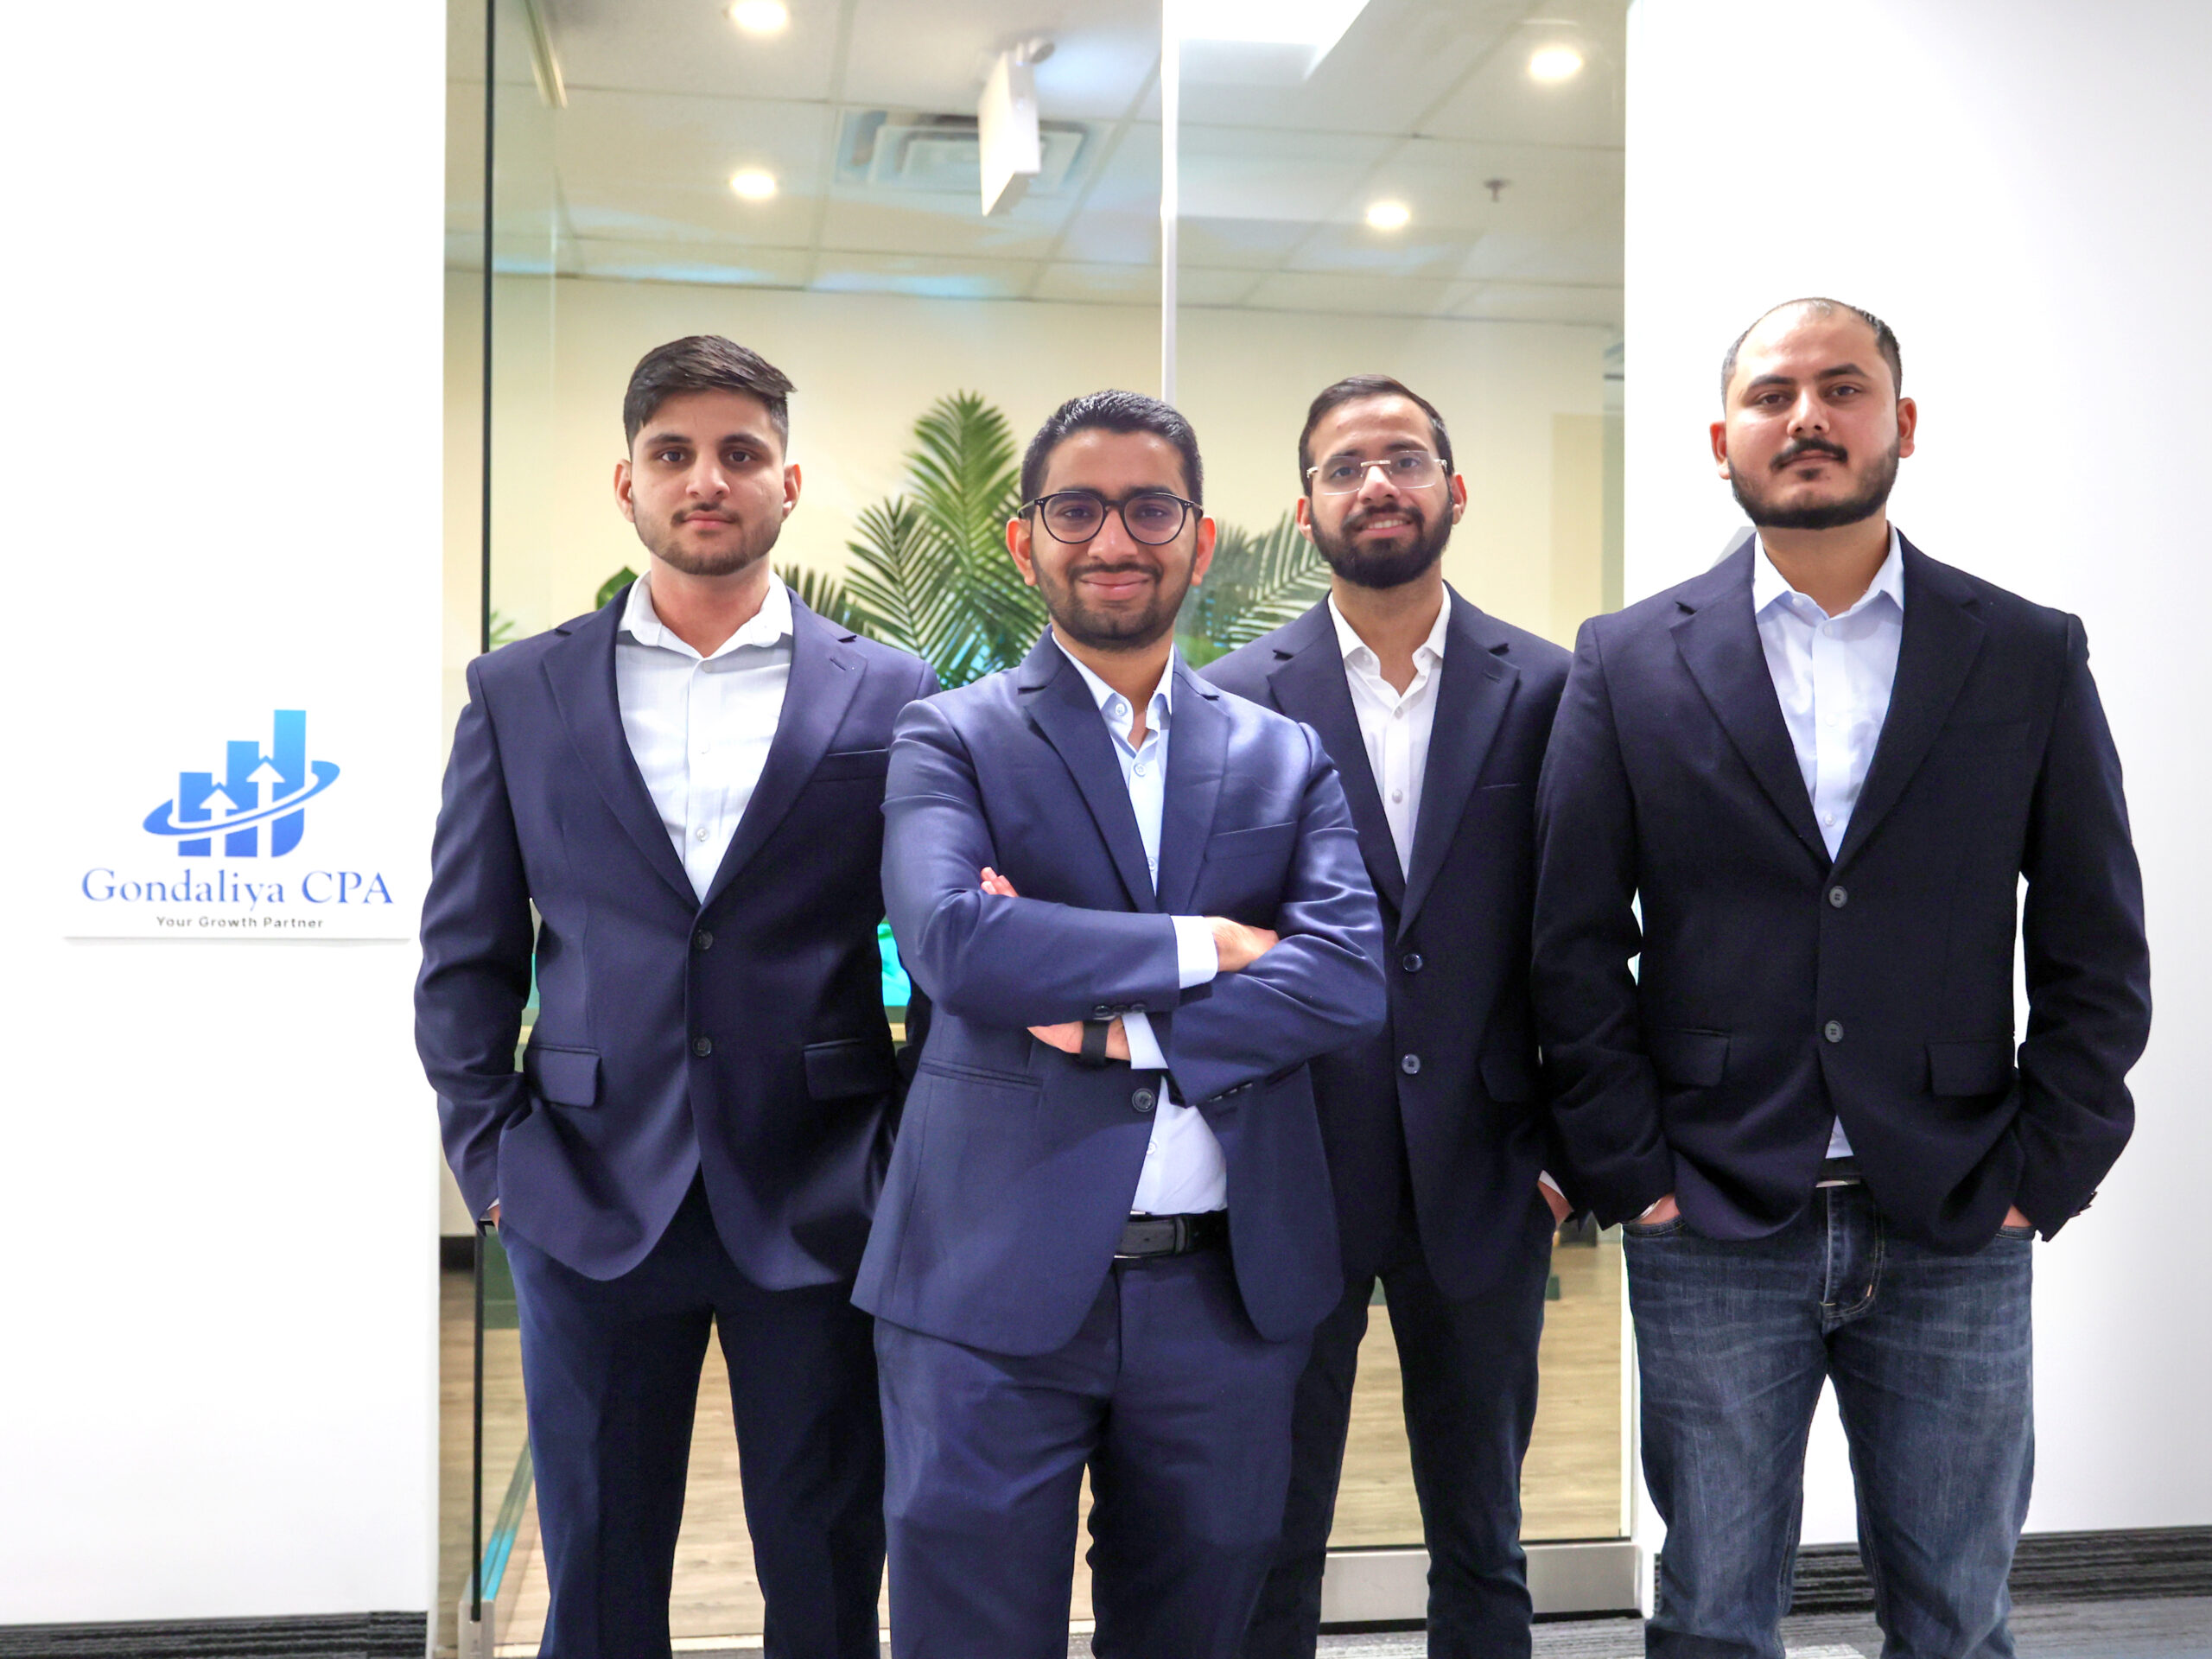
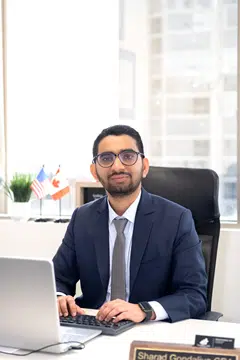
Meet Your Lead Accountant
Meet your lead accountant. As your business and professional needs grow, your dedicated CPA stays the same person.
What Our Clients Say
1300+ five-star reviews from owner-managers, incorporated businesses and holders of inactive corporations across Ontario.
Serving Dormant Corporations Across Ontario
Our CPA team provides specialized accounting and tax solutions for dormant corporations across Ontario, from a single numbered company with four unfiled years to an owner-managed group with three inactive subsidiaries to clean up before a sale. The work is the same wherever you are: establish the position, file what is outstanding, close what should be closed.
Toronto (ON)
55 Queen St E Ste 1205, Toronto, ON M5C 1R6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Mississauga (ON)
2100 Camilla Rd #716, Mississauga, ON L5A 2J8
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Brampton (ON)
4 Starhill Crescent, Brampton, ON L6R 2P9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Scarborough (ON)
24 Clementine Square, Scarborough, ON M1G 2V7, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Vaughan (ON)
19 Cabinet Crescent, Woodbridge, ON L4L 6H9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Oshawa (ON)
210 Durham St, Oshawa, ON L1J 5R3, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Ottawa (ON)
2090 Neepawa Ave a314, Ottawa, ON K2A 3L6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Etobicoke (ON)
60 Stevenson Rd #1601, Etobicoke, ON M9V 2B4, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Hamilton (ON)
70 Starling Dr, Hamilton, ON L9A 0C5, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Guelph (ON)
1155 Gordon St, Guelph, ON N1L 1S8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Windsor (ON)
4387 Guppy Ct, Windsor, ON N9G 2N8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
North York (ON)
150 Graydon Hall Dr #912, North York, ON M3A 3B2, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Dormant Corporation Accounting & Tax FAQs
Related Industries We Serve
Accountant for Businesses Winding Down
- Closing a business now
- Final returns and dissolution
- A decision, not a shell left behind
Accountant for Business Sellers
- Selling rather than shelving
- Qualifying shares and the exemption
- A purchaser at the table
Investment Holding & Investment Companies
- A corporation that is active
- Passive income and refundable tax
- Holding rather than idle
Small Business Accountant
- The operating company
- Trading normally
- Ongoing rather than overdue
Dormant Corporation Filing Done Right.
Built for the owner who closed the business and never closed the company: every year ITA subsection 150(1) requires filed, including the overdue ones, with the schedules a nil year still needs; the ITA subsection 162(7) exposure explained rather than discovered, along with what a demand under subsection 150(2) changes; the Ontario Annual Return position checked since it stopped travelling with the T2 in 2021, including whether the corporation has already been dissolved for default; the HST and payroll accounts filed up to date and then actually closed; shareholder and intercompany balances dealt with before a dissolution rather than during one; the loss pool established from the filed returns and the subsection 111(5) restriction modelled; and the keep-or-dissolve decision priced on your own numbers. No legal advice on dissolution, no guessed penalty figures, and an AFFORDABLE flat fee agreed before the work starts.