



Tax Accountant for Insurance Agents in Ontario and Across Canada
Your income is your own production, and the number on the commission statement is not the number you keep. First-year commission on a life policy is advanced at issue against a policy that has not yet persisted, and where it lapses inside the window your agent contract sets, the advance comes back out of the next statement. That gap is the whole accounting problem of a producing agent, and we build your file around it: gross commission rather than the net deposit, renewal and trailing revenue separated from first-year production, and the chargeback treated correctly against the contingent-liability limit in ITA paragraph 18(1)(e). Arranging for insurance is within the financial service definition in ETA subsection 123(1), and where a supply is exempt there are no input tax credits on the rent, the CRM, the leads or the marketing behind it — so we get that characterization looked at properly instead of assumed. A purchased book goes to Class 14.1 at 5%, not into an expense account. Whether you are a career agent building a first book or a producer whose renewals now outweigh new sales, we handle the commission, the clawback and the book — with AFFORDABLE flat fees.
AFFORDABLE Insurance Agent Tax Accountant
An insurance agent gets two things wrong before anything else, and both of them come from the shape of a commission. The first is that a growth year looks better on paper than it is. First-year commission is advanced at issue, before the policy has proved it will stay on the books, and where a policy lapses, is cancelled or is replaced inside the chargeback window your agent contract sets, the insurer or the managing general agency takes the advance back out of a later statement. An agent who wrote a record year and banked a record deposit can be carrying a clawback obligation against most of it. The accounting treatment of that exposure is the central judgment on a producing agent’s file, and it is not simply a matter of booking a provision: an amount in respect of a contingent liability is denied by ITA paragraph 18(1)(e), so what is deductible and when has to be worked through on your own contract rather than assumed. The second thing is sales tax, and it runs the opposite way to what most agents expect. Arranging for insurance falls within the financial service definition in ETA subsection 123(1), and the exemption for financial services sits in Part VII of Schedule V, so the classification of your own commission is reviewed against what is actually supplied rather than assumed from the job title. The consequence that follows either way is the one worth planning around: where a supply is exempt there are no input tax credits on what you bought to make it. At Gondaliya CPA, we specialize in commission accounting, chargeback treatment and the exempt-supply position for producing agents, providing AFFORDABLE flat-fee support that keeps you CRA-compliant and stops you paying more tax than you owe.
As an insurance agents accountant, we work with career and captive life agents, living benefits and group benefits producers, dual-licensed advisors and agents buying or selling a book of business across Ontario, with year-round support rather than a once-a-year scramble. We tell you what your first-year production is actually worth after the clawback exposure, what your renewal and trailing revenue is worth on its own, and where your home office, your vehicle and your lead spend genuinely sit.
Let us handle the numbers so you can focus on the appointments and the book.
Our Official Partners
Accounting That Understands How an Insurance Agent Actually Earns
An agent is not a firm with a payroll and a premium trust account. You are paid for your own production, most of it advanced before the policy has persisted, some of it arriving for years afterwards on business you wrote long ago. The revenue is two different animals wearing the same name, and the sales tax position on it can deny you the credits on everything you spend. At Gondaliya CPA, we understand that reality and provide practical, industry-focused solutions across Ontario.
Stay Compliant and Minimize Your Insurance Agent Tax
For a producing agent, staying onside with CRA and your regulator and paying the least legal tax are the same job. We keep every filing on schedule while claiming every lead, licensing, office and vehicle dollar the return allows, so nothing is missed and nothing invites a reassessment.
Accounting & Tax Experts for Insurance Agents
- AFFORDABLE + Registered CPA Firm
- Business and Corporate Tax Expert
- Small & Medium Business Expert
- Accounting, bookkeeping, and tax filing
- CPA (Chartered Professional Accountant)
- 1300+ 5-star Google reviews
- 30-Day Money-Back Guarantee
- 60-Day Fees Matching Policy
Why Choose Our Accounting Services for Insurance Agents?
Tax Planning — Commission Timing & Pools
We plan around when first-year commission is income and when a chargeback is deductible, put a purchased book in Class 14.1 at 5%, and protect the $500,000 Small Business Deduction.
Consulting — Production & Persistency
Our bookkeeping separates first-year from renewal and trailing revenue, tracks lead cost against policies issued, and shows what your book is worth on recurring income rather than on a peak year.
CRA Representation — Credits & Claims
When CRA challenges an input tax credit claim, a home office, a vehicle log or the commission reported against your T4A, we prepare the response and pursue relief on Form RC4288 where a prior error caused the penalties.
Bookkeeping — Cash Flow & Exit
We build the cash flow that survives a clawback quarter, produce the statements a book acquisition lender reads, and model the eventual sale of your book years before you need it.
Google Reviews
Insurance Agent Clients
Insurance Agent Tax and Accounting Services in Ontario
Corporate Tax Filing (T2) for Insurance Agents
Professional T2 preparation with first-year and renewal commission separated, the chargeback position tested against ITA paragraph 18(1)(e), and a purchased book in Class 14.1.
Bookkeeping & Accounting for Insurance Agents
Books built from the gross commission statement rather than the net deposit, with administration fees, advances and chargebacks each carried on their own line.
Payroll Services for Insurance Agents
Assistant and staff payments handled properly, with PD7A remittances, T4 and T4A slips filed on time and classification tested against CRA guide RC4110.
GST/HST Filing for Insurance Agents
AFFORDABLE HST work with the ETA subsection 123(1) position reviewed first, registration questioned rather than assumed, and inputs allocated where revenue is mixed.
Tax Planning for Insurance Agents
Smart planning on commission timing against your year-end, the vehicle and home office claims, the Small Business Deduction, and the structure you will eventually sell from.
Corporate Catch-Up Filing for Insurance Agents
File overdue T2 and personal years, rebuild the commission and capital pools you never had, and get back into CRA compliance with accurate catch-up support.
CRA Audit Resolution for Insurance Agents
Expert support on input tax credit denials, vehicle and home office reviews and commission-to-slip mismatches, handled with confidence from the first letter.
CPA Financial Statements (Notice to Reader) for Insurance Agents
CPA-compiled statements a book acquisition lender accepts, showing renewal and trailing revenue separately from first-year production.
Incorporation Services for Insurance Agents
Full incorporation including NUANS, articles and share structure, with the personal services business test worked through before anything is filed.
Catch-Up Bookkeeping Services for Insurance Agents
Months or years of commission statements, chargebacks, lead invoices and mileage reconstructed and reconciled, so your income figure is finally accurate.
US Corporation & LLC Tax Filing for Insurance Agents
Cross-border filing where you, a shareholder or a client sits outside Canada, covering withholding, NR4 reporting and T1135 obligations.
Voluntary Disclosure Program for Insurance Agents
Come forward on unreported commission, credits claimed before the revenue was ever characterized, or unfiled slips before CRA calls, cancelling penalties through a Voluntary Disclosures Program application.
Accounting & Tax Services Tailored for Insurance Agents
Real, practitioner-level CPA expertise for career and captive life agents, living benefits and group benefits producers, dual-licensed advisors and agents buying or selling a book across Ontario — built for a practice whose revenue is personal production.
- We prepare your T2 with GIFI on Schedule 100 and Schedule 125, putting first-year commission, renewal and service commission, trailing commission, group benefits revenue and any separately charged planning fee on their own lines rather than in one total.
- We reconcile the gross commission reported on the return to the T4A your insurer or managing general agency filed, because a return built on the net deposit understates your revenue and hides every administration fee and chargeback behind it.
- We test any year-end chargeback accrual against the contingent-liability limit in ITA paragraph 18(1)(e), so the amount claimed on the return is the amount that survives a review rather than an accounting provision nobody examined.
- We bring commission that is legally an amount receivable into income under ITA paragraph 12(1)(b) whether or not the statement has settled, and we document the cut-off so the position holds from one year to the next.
- We claim capital cost allowance on Schedule 8 with your laptop and tablet in Class 50 at 55%, office furniture and locked client-file storage in Class 8 at 20%, software in Class 12, and a purchased book in Class 14.1 at 5%.
- We build your books from the gross commission statement rather than the amount that landed in the bank, splitting managing general agency administration and technology fees, advances, adjustments and chargebacks onto accounts you can actually read each month.
- We separate first-year production from renewal, service and trailing commission in every period, because one of them is a spike that funds this year and the other is recurring income that funds your eventual exit.
- We track the clawback exposure sitting behind your first-year advances as a live figure rather than a year-end surprise, so a record quarter is never mistaken for cash you are safely entitled to keep.
- We cost your lead buying and marketing spend against the policies it actually produced in QuickBooks Online or Xero, which is the only honest way to see whether a lead source is paying for itself.
- We capture licensing, software, errors and omissions, office and vehicle invoices through Dext and reconcile monthly, keeping the six years of records ITA section 230 requires so nothing has to be rebuilt from memory later.
- We test your assistant, your case manager and anyone doing your administration against the CRA guide RC4110 factors, because a large subcontract line with no analysis behind it is the first thing a payroll auditor opens.
- We file T4A slips on the people who are genuinely contractors, so the administration, marketing and paraplanning payments you deducted are reported the way CRA expects instead of sitting in an unsupported total.
- We set up payroll and withhold income tax, CPP and EI, remitting on the PD7A by the 15th of the following month, because CRA’s late-remittance penalty on source deductions reaches 10%.
- We file your T4 slips and T4 Summary by the last day of February, reconcile them to the PD7A remittances actually made, and watch Ontario payroll against the $1,000,000 Employer Health Tax exemption.
- Where you pay a non-resident for services performed in Canada, we address Regulation 105 withholding and the T4A-NR reporting that follows, instead of paying the invoice as though the border made no difference.
- Arranging for insurance falls within the financial service definition in ETA subsection 123(1), and the exemption in Part VII of Schedule V is where that leads, so the starting question is what you are actually supplying.
- We do not assert that your commission is or is not an exempt financial service: the classification is reviewed against what is actually supplied under each contract, documented in writing, and revisited when your revenue mix changes.
- The consequence that matters commercially, and the one we can state without qualification, is this: where a supply is exempt there are no input tax credits on the rent, the CRM, the leads, the marketing or the professional fees behind it.
- Where you also earn clearly taxable revenue, such as a separately charged planning fee, the practice is mixed and we allocate inputs under ETA section 141.01 on a fair and reasonable method applied consistently all year.
- We review whether you should be registered at all before anything is filed, because exempt revenue does not count toward the $30,000 small supplier threshold in ETA section 148 and a needless registration creates needless returns.
- We plan around the timing gap that defines this trade: commission advanced and taxed in one year against a chargeback that may only become deductible in another, which is how a good year and a bad cash position arrive together.
- We work through the personal services business test in ITA subsection 125(7) before any structure is built, because a corporation caught by it loses the small business deduction and almost every deduction other than salary.
- Where a corporation is permitted and appropriate, we set the salary and dividend mix so combined tax sits near the 11.2% (from July 1, 2026) Ontario small-business rate on the first $500,000 of active income rather than 53.53% personally.
- We time vehicle and equipment purchases against your fiscal year-end, weighing the Class 50 rate at 55% against Class 8 at 20% and the Income Tax Regulation 7307 limit that decides Class 10 or Class 10.1.
- We plan at least two years ahead so shares can qualify for the $1.275M Lifetime Capital Gains Exemption under ITA 110.6, purifying retained cash that would otherwise fail the active-business asset test on a sale.
- We reconstruct gross commission, administration fees, advances and chargebacks from your commission statements, T4A slips and bank deposits across every unfiled year, rebuilding the six years of records ITA section 230 requires.
- Late filing costs 5% of the balance owing plus 1% per month up to twelve months, so we file your oldest unfiled return first to stop the penalty compounding and limit the arrears interest CRA charges.
- We rebuild the chargeback history year by year, because a catch-up filing that ignored clawbacks entirely reports income the agent never kept and leaves a deduction sitting unclaimed in whichever year it was actually incurred.
- We rebuild the capital pools across the missing years, moving a purchased book out of expenses into Class 14.1 at 5% and computers out of Class 8 into Class 50 at 55% where they belong.
- We file a Voluntary Disclosures Program application on Form RC199 before CRA contacts you, because a disclosure accepted under the general program cancels penalties in full and gives roughly 50% interest relief on the older years.
- When CRA denies input tax credits on an agent whose commission revenue has been characterized as exempt, we produce that characterization file and, where the practice is genuinely mixed, the ETA section 141.01 allocation that supports whatever was properly claimed.
- When CRA compares your reported commission to the T4A your insurer or managing general agency filed, we produce the gross-to-net reconciliation showing administration fees and chargebacks as the deductions they are.
- When CRA reviews your vehicle and home office claims, we produce the logbook, the square-footage allocation and the ITA subsection 18(12) analysis, because client-facing driving is genuinely deductible and undocumented driving is not.
- When CRA opens a full audit, we manage the file and answer the revenue, credit and expense queries inside the deadlines, so a one-year review does not expand across the prior years CRA is able to reopen.
- We file the Notice of Objection within 90 days of a reassessment and pursue taxpayer relief on Form RC4288, cancelling penalties and interest that can top $15,000 where a prior accountant’s error caused them, protecting your appeal rights.
- We prepare the CSRS 4200 compilation engagement financial statements a lender requires across two fiscal years for a book of business acquisition loan, or for a mortgage underwriter who needs assessed commission income.
- Your compiled statement of operations shows renewal and trailing commission separately from first-year production, because a lender advancing against recurring revenue needs to see which part of your income actually recurs.
- We state the chargeback exposure behind your first-year advances honestly rather than presenting a peak production year as though every dollar of it were settled and safely earned.
- We carry a purchased book of business on the statement of financial position as the Class 14.1 asset it is, so the lender can see what was bought instead of finding it inside general expenses.
- We deliver the compiled statements within 30 days of receiving your commission statements and the year’s tax figures, because a book acquisition that is already under offer does not wait for a slow accountant.
- Before anything else, we tell you plainly that whether an insurance agent may direct commissions into a corporation is a question for your provincial regulator and for the insurer or managing general agency that holds your contract.
- We model the tax outcome both ways on your own numbers, so the decision is made on evidence rather than on what another agent at a branch meeting said worked for them last year.
- We work through the personal services business test in ITA subsection 125(7) honestly, because a single-carrier career agent contract is exactly the profile CRA looks at and the consequences of being caught are severe.
- Where incorporation is permitted and appropriate, we handle NUANS, articles and share structure under the Ontario Business Corporations Act and open the CRA Business Number and payroll accounts within the first 30 days.
- We complete the section 85 rollover on Form T2057 where existing assets or an owned book move into the corporation, deferring the gain a straight sale would trigger and setting the opening capital cost allowance schedules correctly.
- We rebuild months or years of neglected books from commission statements, bank deposits, lead invoices, licensing receipts and mileage records, so an agent who has never kept books finally has a ledger that ties out.
- We unwind net deposits into gross commission, administration and technology fees, advances and chargebacks across the whole backlog, which is the single correction that changes both your revenue figure and most of your expense lines.
- We reconstruct the chargeback history from the statements so the clawbacks are claimed in the years they were actually incurred rather than lost entirely because nobody separated them from the deposit.
- We rebuild the equipment, vehicle and book of business schedules from purchase documents and split them across Class 50, Class 8, Class 12, Class 10 or 10.1 and Class 14.1 as the facts require.
- We reconstruct the home office and vehicle support for each caught-up year, so the claims can be made on documentation that exists rather than on a percentage somebody guessed at after the fact.
- Where you hold a licence or a carrier contract outside Canada, or write business for clients who have moved, we map which country has the right to tax that income before anything is reported on either return.
- Where a non-resident owns shares in your corporation, we handle the Part XIII withholding on dividends paid out of Canada and the NR4 reporting that follows, so nothing is missed at 25% or at the treaty rate.
- We file Form T1135 where foreign property costs more than $100,000, avoiding a penalty regime CRA applies whether or not any tax was actually owing on the holding in that particular year.
- Where a United States citizen is a shareholder or a spouse in the picture, we coordinate the Canadian and American returns, because those reporting obligations reach into a Canadian corporation in ways most families discover far too late.
- We translate any foreign-currency commission or fee at the rate on the transaction date rather than at a year-end average picked for convenience, which is what keeps the reported figure defensible under review.
- We bring you forward on commission income that was never reported, or reported net of what the managing general agency withheld, before CRA matches your return against the T4A slips it already holds on file.
- We disclose input tax credits claimed in prior periods against revenue that should have been characterized first, correcting the net tax before a reviewer finds the same gap and assesses penalties and interest on top.
- We correct a chargeback provision that was deducted in the teeth of ITA paragraph 18(1)(e), and at the same time claim the clawbacks that were genuinely incurred and never deducted at all.
- We file your submission on Form RC199 with a full reconstruction from commission statements, bank records and lead and expense invoices, so an agent who outgrew their bookkeeping is not left facing an arbitrary assessment.
- We confirm your disclosure is genuinely voluntary before CRA contacts you — the single condition that makes it valid — and secure the roughly 50% interest relief on the older years, turning a real risk into a managed correction.
Insurance Agent Tax & Commission Check
Six quick questions on your gross commission reporting, your chargeback treatment, your sales tax position, your book of business, your home office and vehicle support, and whether it is time to look at a structure. No fee shown.
1. Are your books built from the gross commission statement rather than the net deposit?
2. Is your chargeback exposure tracked and its tax treatment reviewed each year?
3. Has your ETA subsection 123(1) position been reviewed before any credits were claimed?
4. Is a purchased book of business carried in Class 14.1 rather than expensed?
5. Do you keep a logbook and a square-footage allocation for the vehicle and home office?
6. Has your business structure been reviewed against the personal services business test?
Free CPA Consultation for Insurance Agents
Case Studies: Insurance Agent Accounting & Tax
Toronto Career Life Agent — The Record Year That Was Not There
The problem: A Toronto career agent had the best production year of his life and a tax bill to match. Every first-year commission advance had been taken into income on the day it hit the statement, and nothing in the file distinguished an advance on a policy issued in December from renewal income on business written five years earlier. When lapses came through the following spring, the clawbacks were withheld from later statements and simply disappeared into a smaller net deposit, so neither the exposure nor the eventual deduction was ever visible on any line.
What we did: We rebuilt the year from the gross commission statements, separated first-year advances from renewal and trailing revenue, quantified the clawback exposure sitting behind the advances, and tested the proposed year-end accrual against the contingent-liability limit in ITA paragraph 18(1)(e) so that what was claimed was what would survive.
The result:
- $186,000 of first-year advances separated from recurring revenue
- $41,300 of chargebacks claimed in the years actually incurred
- Clawback exposure now reported monthly, not discovered in spring
Mississauga Living Benefits Producer — Credits Claimed Before Anyone Asked What Was Supplied
The problem: A Mississauga producer earning almost entirely commission income had been registered for HST by a prior accountant and had claimed input tax credits in full on office rent, the CRM subscription, lead purchases, marketing and the vehicle for three years. Nobody had ever asked what was actually being supplied, or whether arranging for insurance fell within the financial service definition in ETA subsection 123(1). There was no characterization file, no allocation method and nothing to put in front of a reviewer.
What we did: We reviewed what was actually supplied under each carrier contract and documented the analysis, identified the small amount of separately charged planning work that stood on different footing, built a fair and reasonable allocation under ETA section 141.01 for the mixed portion, and corrected the prior returns voluntarily before any CRA contact.
The result:
- Revenue characterized on the facts and documented in writing
- $27,800 of net tax corrected voluntarily, penalties cancelled
- Allocation method now applied every filing period
Ottawa Agent Buying a Book — The Purchase Price That Went to Expenses
The problem: An Ottawa agent bought a retiring colleague’s book of business and paid for it over a transition period tied to client retention. The prior accountant put the whole purchase price through as a marketing and consulting expense in the year the first instalment was paid. The deduction was denied on review, the agent faced a reassessment, and the statements he took to his lender for the acquisition loan showed no asset at all against the debt he had taken on.
What we did: We capitalized the purchase price to Class 14.1 at 5% across the instalments, restated the affected years, prepared CSRS 4200 compilation statements showing the book as an asset and the renewal and trailing revenue it generated on its own line, and refiled with the correct capital cost allowance claimed.
The result:
- Book of business capitalized to Class 14.1 at 5%
- Reassessment resolved and the deduction put on a defensible footing
- Lender statements now show the asset against the acquisition loan
Our clear, efficient process ensures every step is transparent, building trust and long-term client relationships.
Kickoff (Document Request)
Collect prior returns, your agent contract with the insurer or managing general agency, gross commission statements, T4A slips, lead and marketing invoices, licensing and errors and omissions receipts, mileage records and bank statements.
First 30 Days (Cleanup & Setup)
Set up QuickBooks Online or Xero with Dext, rebuild the books from gross commission, review the ETA subsection 123(1) position, split first-year from renewal revenue, and rebuild the Class 50, 8, 12, 10.1 and 14.1 schedules.
Monthly Close
Gross-to-net commission reconciliation, chargeback exposure updated, lead cost against policies issued, renewal and trailing revenue tracked separately, mileage and home office support filed, and any payroll remittance reconciled.
Quarterly Planning Review
Salary and dividend mix where a corporation exists, commission timing against the year-end, vehicle and equipment purchases, the personal services business question revisited, and cash flow tested against a clawback quarter.
Year-End Close & T2 Filing
Trial balance, financial statements with renewal and trailing revenue shown separately and the book of business carried as an asset, the chargeback position settled, T2 with GIFI or T2125, and CRA preparation.
Get Your Insurance Agent Taxes Done Right Today
Affordable Pricing for Insurance Agents
We believe in clear, upfront pricing so you know exactly what to expect. All fees include HST.
- Tax Preparation (Corporation) — From $400
- Tax Return Filing (Corporation) — From $400
- Tax Compliance Audit — FREE CRA audit support for our clients
- Tax Strategy — FREE for our clients
- Accounting Base Plan — From $100 per month
- Bookkeeping Management — Free for our Accounting clients
- Financial Reporting — Free for our Accounting clients
- Business Formation — Flat $35
- Incorporation Process — Flat $35
- Entity Setup Assistance — Flat $35
- Full-Service Payroll — From $125 per month
Payment is by Interac e-Transfer to info@gondaliyacpa.ca only. Security question: Not Applicable, as auto-deposit is enabled.
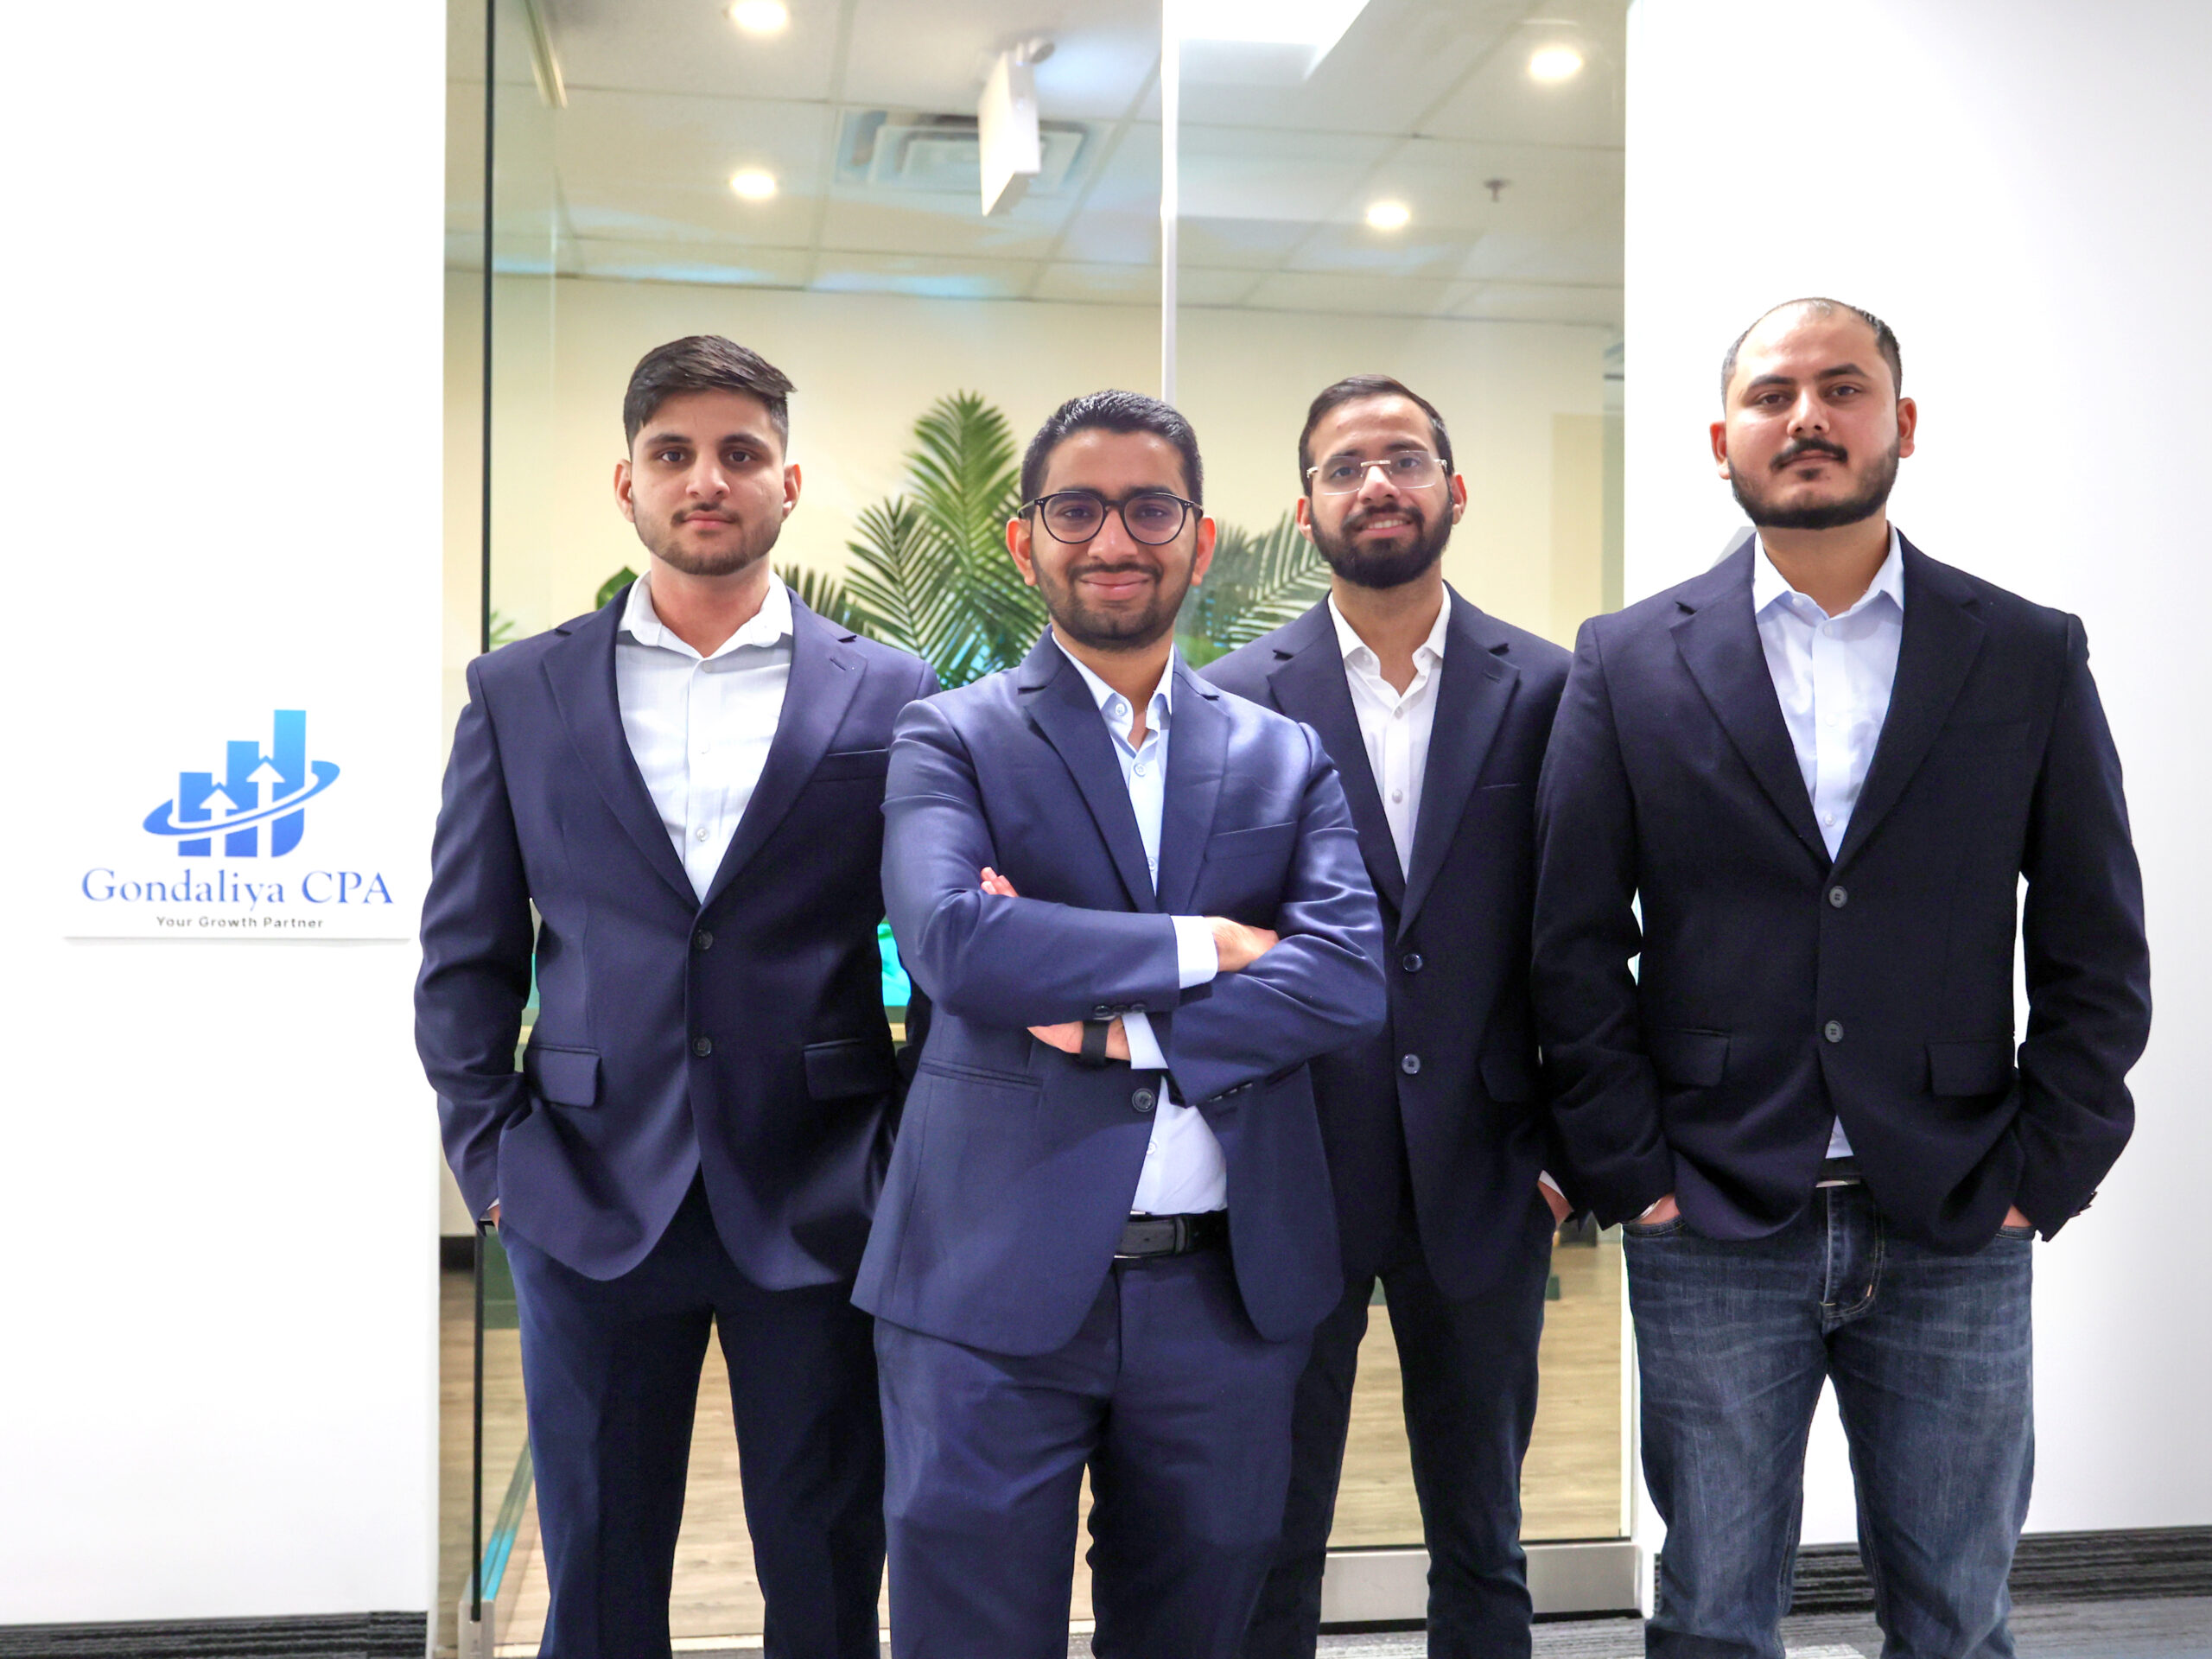
Meet Your Lead Insurance Agent Accountant
Meet your lead insurance agent accountant. As your commission and corporate tax adviser, you deal with the same two people every year.


What Our Clients Say
1300+ five-star reviews from insurance agents, advisors and commission earners across Ontario and Canada.
Serving Insurance Agents Across Ontario
Our CPA team provides specialized accounting and tax solutions for insurance agents, advisors and commission earners throughout Ontario. We understand why a first-year advance is not the same thing as renewal income, why a chargeback has to be tracked long before it appears, why the sales tax characterization decides whether your costs carry recoverable tax, and what CRA looks at first when it opens a commission earner’s file.
Toronto (ON)
55 Queen St E Ste 1205, Toronto, ON M5C 1R6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Mississauga (ON)
2100 Camilla Rd #716, Mississauga, ON L5A 2J8
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Brampton (ON)
4 Starhill Crescent, Brampton, ON L6R 2P9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Scarborough (ON)
24 Clementine Square, Scarborough, ON M1G 2V7, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Vaughan (ON)
19 Cabinet Crescent, Woodbridge, ON L4L 6H9, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Oshawa (ON)
210 Durham St, Oshawa, ON L1J 5R3, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Ottawa (ON)
2090 Neepawa Ave a314, Ottawa, ON K2A 3L6, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Etobicoke (ON)
60 Stevenson Rd #1601, Etobicoke, ON M9V 2B4, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Hamilton (ON)
70 Starling Dr, Hamilton, ON L9A 0C5, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Guelph (ON)
1155 Gordon St, Guelph, ON N1L 1S8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Windsor (ON)
4387 Guppy Ct, Windsor, ON N9G 2N8, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
North York (ON)
150 Graydon Hall Dr #912, North York, ON M3A 3B2, Canada
+1 (647) 212-9559
9:00 AM – 8:30 PM (Mon – Sun)
Insurance Agent Accounting & Tax FAQs
Related Industries We Serve
Accountant for Insurance Brokers
- Brokerage and producer accounting
- Premium trust and contingent commission
- Corporate tax filing and statements
Accountant for Mutual Fund Representatives
- Exempt financial service review
- Trailing commission and book of business
- Corporate tax planning and bookkeeping
Accountant for Portfolio Managers
- Management fee revenue recognition
- Registered firm compliance costs
- Corporate tax filing and statements
Accountant for Notaries
- Regulated practice deductions
- Professional liability and dues
- Corporate tax planning and advisory
Insurance Agent Accounting & Tax Done Right.
Books built from the gross commission statement rather than the net deposit, first-year production separated from renewal and trailing revenue, the chargeback exposure tracked as it accumulates and its treatment tested against the contingent-liability limit in ITA paragraph 18(1)(e), the ETA subsection 123(1) characterization reviewed before a single input tax credit is claimed, inputs allocated under ETA section 141.01 where the revenue is mixed, a purchased book capitalized to Class 14.1 at 5% instead of expensed, and the home office and vehicle claims documented before CRA asks. AFFORDABLE flat fees, no hourly billing. Licensed CPA Ontario. 1300+ five-star reviews. 30-Day Money-Back Guarantee.