



Catch-Up Bookkeeping Costs in Canada: Pricing, Factors and What Is Included
What Catch-Up Bookkeeping Costs in Canada
The catch-up bookkeeping cost a Canadian business faces depends on the volume of overdue bookkeeping, the number of historical periods still open, and the condition of the records that have to be cleaned up. Catch-up bookkeeping means fixing your business’s financial records when they are behind. It helps businesses follow tax rules and get clear information about their own money. This service matters when you have missed regular updates in your books, and it is the step that has to happen before a catch-up corporate tax filing can be prepared at all. Gondaliya CPA sets out the inputs that drive a bookkeeping service estimate so you can see where the cost to update business books actually comes from.
Quick Summary
Catch-up bookkeeping is priced from scope, not from a rate card, because two businesses the same number of months behind can be an order of magnitude apart in effort. Please note that we cannot responsibly put a figure on a cleanup before the open periods, the account list, the transaction volume and the record condition have been looked at, which is what the free initial consultation is for. Our own fees are fixed and annual with no hourly billing, shown before tax with sales tax on its own line, and a cleanup is scoped work agreed and fixed before it begins.
| Aspect | Details |
|---|---|
| What drives the price | Open periods, accounts to reconcile, transaction volume and record condition, in that order. |
| Backlog versus cleanup | A backlog is unentered transactions; a cleanup is errors inside records that already exist. |
| What is not in a cleanup | Late returns, payroll remittances, amendments and CRA audit work are each scoped separately. |
| How we charge | Fixed and annual with no hourly billing, shown before tax with sales tax on its own line. |
Reading time: 17 minutes.
Table of Contents
- What Catch-Up Bookkeeping Is, and What It Is Not
- Signs Your Books Have Fallen Behind
- What Actually Drives the Price
- How the Market Prices It, and How We Price It
- What Is Included, What Is Excluded, and How the Work Runs
- The Cost of Waiting and How to Keep the Bill Down
- Frequently Asked Questions
- Essential Points for Business Owners
- Industry Spotlights: Sectors We Represent
- Professional Guidance and Quick Reference
The Numbers That Matter
This article covers what catch-up bookkeeping costs in Canada and why, current to 18 November 2026. It covers the difference between a backlog and a cleanup, the signs that books have fallen behind, the four scope inputs that drive a quote, GST/HST reporting periods and payroll remittance frequency as volume drivers, the pricing models a business will meet in the market and how our own fees work, what a cleanup includes and excludes, the workflow from intake to controller review, written change control, the CRA penalty and interest exposure that sits alongside professional fees, record retention under section 230, and how to reduce the cost of a cleanup without cutting scope. It does not quote a fee for any engagement without reviewing the file, advise on any particular business’s filing position, or set out provincial sales tax regimes outside GST/HST. Gondaliya CPA performs compilation engagements under CSRS 4200, which provide no assurance; audit and review engagements are referred out. We do represent clients through CRA audits, which is a separate service and not an assurance engagement. We do not prepare SR&ED claims; those are referred out. This is educational information only and not tax, legal or accounting advice. Talk to a Registered pro in Canada or Ontario about your case.
What Catch-Up Bookkeeping Is, and What It Is Not
The Work
Catch-Up Bookkeeping in Canada: Backlog, Cleanup and Why the Difference Changes the Price
Catch-up bookkeeping looks at old transactions and checks accounts carefully. It produces records that let an owner understand the money that has actually moved through the business. Unlike regular bookkeeping, which keeps track every day, catch-up focuses on rebuilding periods that were never recorded or on fixing past mistakes and missing information.
Key Differences: Backlog vs Cleanup
People often mix up backlog and cleanup, but they are different pieces of work and they cost differently.
- Backlog means you have lots of unentered transactions. It is a measure of how far behind your records are, and it is priced mostly on volume.
- Cleanup fixes errors inside records that already exist. It also means organising messy data or correcting wrong entries, and it is priced mostly on how wrong the existing data is.
Knowing this difference helps you work out what kind of help your business actually needs. A file can be both at once: eleven months unentered and the four months before that entered badly. That combination is the commonest one we see, and it is why a quote has to look at the file rather than at the calendar.
Factors Influencing Costs
The price for catch-up bookkeeping changes a lot depending on these things:
- How many transactions have to be reviewed.
- How many bank, credit card or loan accounts need work.
- How messy or how clear your source documents are.
- Whether you also owe filings, such as returns that must be brought up to date.
Because of these, the catch-up bookkeeping cost a Canadian business faces varies a lot from one file to the next. Firms price the work after looking at those details, which is why a number quoted before anyone has seen the file is a guess wearing a quote’s clothing.
Fixing overdue financial records keeps you compliant and shows a clearer picture of your money. That clarity matters if you want to grow the business and avoid charges from the Canada Revenue Agency, which are separate from anything a bookkeeper or accountant charges you.
A trades company came to us nineteen months behind and convinced the job was small because the bank feed had pulled everything in automatically. It had. What it had not done was code any of it, so roughly $52,000 of shareholder draws sat in revenue, the owner’s truck loan showed as an expense every month rather than as principal and interest, and three years of what he believed was profit was partly his own money going round in a circle. The backlog was two weeks of entry. The cleanup underneath it took five. He had been quoting new work off a gross margin that did not exist. Figures changed for privacy.
Definitions Table
| Term | Definition |
|---|---|
| Open period | A month or quarter with no recorded transactions, or with transactions recorded but never reconciled to a statement. |
| Record condition | How complete and how organised the source documents are when the catch-up starts, from clean digital files to loose paper with gaps. |
Signs Your Books Have Fallen Behind
Warning Signs
Seven Signs a Canadian Business Needs Catch-Up Bookkeeping
Sometimes businesses fall behind on their bookkeeping, and that creates a backlog which needs catch-up work. Spotting the signs early helps control the cost. It also avoids a surprise cleanup bill, because the scope is smaller when you deal with it sooner.
Common Indicators of Backlogged Books
- Missing financial statements. If you do not have recent profit and loss statements, balance sheets or cash flow reports, your books probably need catch-up work. Those statements are what you make decisions from and what a return is built on.
- Unreconciled bank accounts. When bank accounts have not been matched for months or even years, the records are incomplete. That raises the workload and the price, because more of the time goes into finding and fixing errors rather than entering data.
- Overdue tax filings. Late corporate tax returns, GST/HST returns, payroll slips or other filings show you need cleanup work beyond ordinary bookkeeping.
- Inconsistent transaction records. If invoices do not match payments in your books, the transaction tracking is off, and reconciling it is detailed work.
- Accumulated paperwork without organisation. If receipts, bills and files pile up with no order, the mess compounds. Sorting takes longer, so the cleanup costs more.
- Frequent CRA notices. Repeated notices about late filings or missing information show gaps in your books. Fixing it calls for professional help, and the fee for that sits apart from any CRA penalty.
- Difficulty producing reports on demand. If you cannot quickly produce an updated financial report without rebuilding the data first, your bookkeeping is overdue.
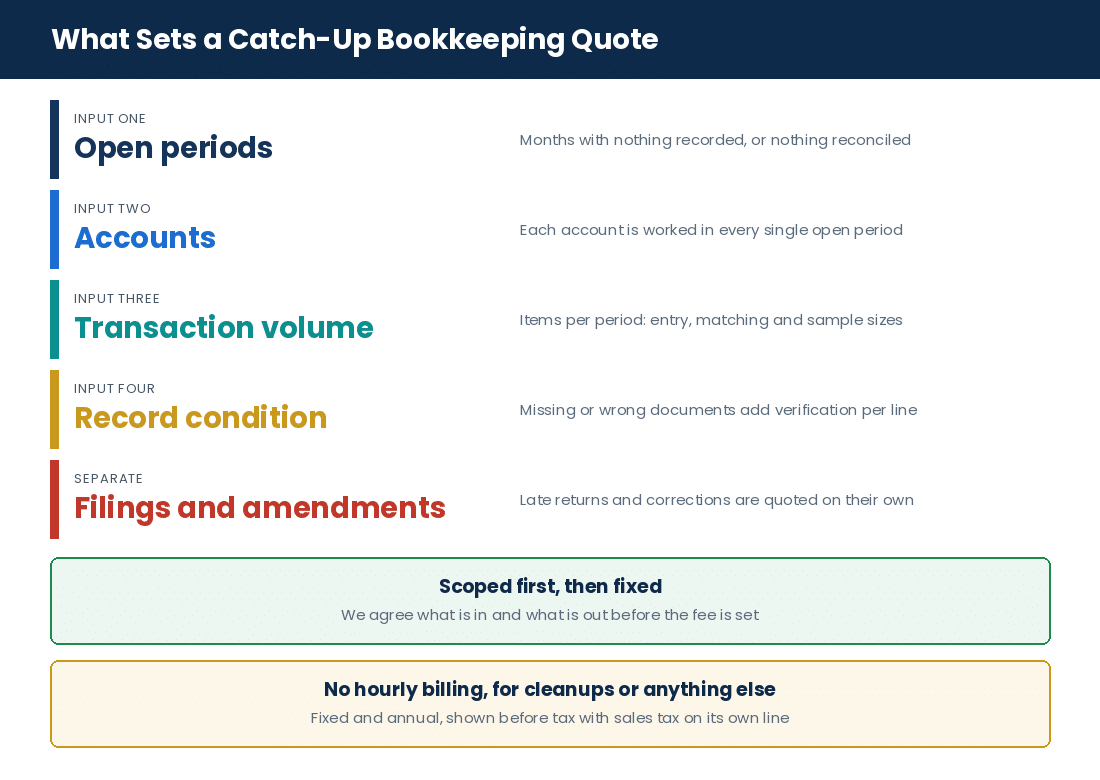
Why Early Recognition Matters for Pricing
Knowing these signs helps you work out how much work is needed before you go asking for quotes, and every one of those details affects the final price. For example:
- More open periods mean more work.
- Extra bank accounts mean more reconciliation.
- Poor record condition adds hours verifying transactions.
- Multiple late filings add complexity.
Knowing this stops the surprises when you review estimates. You get a fee breakdown that matches the real work, rather than an hourly rate multiplied by a guess and presented as a total.
The Canada Revenue Agency requires businesses to keep proper books and records supporting all reported amounts, under section 230 of the Income Tax Act. Failing to do so carries consequences that are separate from professional fees.
An e-commerce seller called us the week a CRA demand letter arrived, having assumed for two years that because the platform showed sales and the bank showed deposits, the books existed somewhere in between. They did not. Platform settlements are net of fees, refunds and chargebacks, so every deposit was a summary of four things, and gross taxable sales had never been recorded anywhere. Once the settlements were unpicked, roughly $23,000 of HST had been collected and never remitted. The bookkeeping cleanup was the small half of that problem. Figures changed for privacy.
Scenario Decision Table
| Scenario | What Can Go Wrong | CRA Touchpoint | What a CPA Adds | What To Prepare First |
|---|---|---|---|---|
| Twelve months of unentered transactions | Volume underestimated from the bank balance alone | Section 230 books and records | Counts periods and accounts before quoting | Full bank and card statements |
| Entries made but never reconciled | Duplicates and missing items found late | Reported amounts not supported | Reconciles every account every period | Statements and the existing ledger file |
| GST/HST returns behind | Collected tax never remitted | GST/HST reporting period obligations | Separates the bookkeeping from the filing | Sales records and the reporting period assigned |
| Payroll remittances missed | Penalty rising with the number of days late | Subsection 227(9) failure to remit | Rebuilds the remittance history and quantifies exposure | Pay runs, remittance confirmations, the business number |
| Errors found in a return already filed | Amendment treated as part of the cleanup | Adjustment to a filed return | Quotes the amendment as its own scope | Copies of the returns as filed |
What Actually Drives the Price
Scope Inputs
Open Periods, Accounts, Volume and Condition: the Four Inputs Behind a Quote
Catch-up bookkeeping pricing depends on a few main things that shape the job’s size and difficulty. Knowing them explains why a cleanup can be very different in price from one business to another even when both owners say the same sentence: we are about a year behind.
Open Periods and Accounts Set the Base
The first step in costing a catch-up is counting open periods. These are the months or quarters with no recorded transactions. Then you list every account that has to be worked: bank, credit card, loan, merchant, and anything else money moves through. Each open period needs a full review and reconciliation for every account that was live during it.
More open periods mean more work, because each one needs separate handling and each one has its own cut-off. Many accounts add effort in the other direction, because every account has to be checked carefully for accuracy in every period.
That count is the base of any quote. Without knowing how many periods are behind and which accounts need work, nobody can give you a reliable price, and nobody should pretend otherwise.
Transaction Volume Moves a Quote
Once the open periods and the accounts are known, transaction volume changes the price. Businesses with many transactions in each period need more data entry, more sorting, more checking against statements and more error correction.
Two companies might both be six months behind. If one runs 50 transactions a month and the other runs well over 1,000, the second cleanup costs more, because keeping records that support the reported amounts takes proportionally more hours of work. Higher volumes also change method: where checking every item is not practical, the work moves to testing samples, and larger populations need larger samples.
Filing Frequency Is a Volume Driver Most Owners Miss
How often you are required to file sets how many cut-offs sit inside the same backlog, and that is a real cost driver rather than a technicality. For GST/HST, the reporting period is assigned on annual taxable supplies: $1,500,000 or less is assigned annual, more than $1,500,000 and up to $6,000,000 is assigned quarterly, and more than $6,000,000 is assigned monthly. Charities and most listed financial institutions are assigned annual. A business assigned annual or quarterly may elect a more frequent period, and the period does not change by itself when supplies cross a threshold, so a company that grew three years ago may still be sitting on the period it was given then. A GST/HST registration on a monthly period that is two years behind is twenty-four cut-offs to rebuild; the same two years on an annual period is two.
Payroll works the same way, and it is usually worse. Remittance frequency is set by the employer’s average monthly withholding amount, so a monthly or accelerated remitter has far more deadlines sitting behind them than a quarterly one does. Quarterly remitting is available to existing small employers with an average monthly withholding amount under $3,000 and a perfect compliance record; a regular remitter is under $25,000; threshold 1 accelerated runs from $25,000 to $99,999.99; and threshold 2 accelerated applies at $100,000 or more, which brings remittances several times a month. That is why a payroll backlog is the most expensive kind of backlog per month of delay.
Two clients arrived the same month, both fourteen months behind, both with one corporation and one fiscal year to rebuild. The first was a consultancy with roughly forty transactions a month and clean digital invoices filed by date. The second was a restaurant group with three locations, four bank accounts, two merchant processors, a payroll on an accelerated remittance schedule and somewhere over a thousand transactions a month. Same number of months, same deadline, and the second file took more than six times the work. While reconciling it we also found about $7,800 of supplier payments that had been made twice. The months were identical; nothing else was. Figures changed for privacy.
Record Condition Changes Pricing Significantly
Record condition means how neat and complete your documents are when the catch-up starts. Good digital files with clear invoices and matched bank statements cut cleanup time a lot. Messy paper files or missing documents take much longer.
Poor record condition means extra steps:
- Finding lost receipts, or reconstructing them from supplier records.
- Fixing incomplete ledgers where an entry exists but the detail behind it does not.
- Chasing differences between the bank statements and the books, item by item.
Those steps go beyond the reconciliation work included in an ordinary catch-up, so fees go up when records need serious repair. This is also the one input the client can change before the work starts, which is the subject of the last section of this article.
What If Something Already Filed Must Be Amended?
If old filings such as GST/HST returns or corporate tax returns contain mistakes that surface during the catch-up, they may need correcting. That rework is not part of a catch-up bookkeeping scope. A corporate return is corrected by filing an amended return or requesting an adjustment to the return as assessed; a GST/HST return is corrected by requesting an adjustment to the return previously filed. Either route is a filing exercise with its own judgement calls, not a bookkeeping entry.
Correcting filings needs knowledge of the correction mechanism rather than just the ability to update books. It can also attract penalties or interest charged by the CRA, separately from any professional fee.
If amendment work is not planned for explicitly, the total cost of a project can be badly misjudged. That is why a cleanup quote should carry amendments as their own line, and why ours does.
| Scope Input | What It Measures | Effect on the Quote |
|---|---|---|
| Open periods | Months or quarters with nothing recorded or nothing reconciled | Sets the base workload; effort rises with each period |
| Accounts to reconcile | Bank, credit card, loan and merchant accounts live in those periods | Multiplies the base, because each account is worked every period |
| Transaction volume | Items per period across all accounts | Drives entry, matching and sample sizes |
| Record condition | Completeness and organisation of source documents | Adds verification steps where documents are missing or wrong |
| Filing frequency | GST/HST reporting period and payroll remitter type | Sets how many cut-offs sit inside the same elapsed time |
| Amendments identified | Errors inside returns already filed | A separate scope, quoted on its own |
So these inputs show why catch-up bookkeeping cannot be priced from a flat rate card. They have to be fitted to the business in front of you before anyone offers a final price for backlog work in Canada.
Catch-Up Bookkeeping Scope Check
Five questions that decide how big your cleanup actually is.
Points to raise with us:
This is a general prompt, not tax or legal advice or a quote. Your position depends on your full facts. For a real review, please book a free consultation.
How the Market Prices It, and How We Price It
Pricing
Pricing Models You Will Meet, and the One We Use
Before the models, it is worth being plain about the four things that move the cost of any catch-up, because they are what every model is really measuring.
Length of Overdue Period and Transaction Volume
The longer the books are behind, the more work it takes. More months mean more bank statements, more invoices and more receipts to work through. If there were a lot of transactions in those months, that adds time on top again.
State of Source Documents and Account Complexity
Neat, organised paperwork makes a catch-up cheaper. Messy or missing documents make it harder. Equally, a business with several bank accounts, credit cards, loans, a payroll and sales tax filings takes more steps to put right than one with a single account.
Missed CRA Filings and Payroll Remittances
If filings or payroll remittances have been missed, the work grows. Each missed obligation needs its own attention, and the type and number of them add to both effort and urgency.
Scope, Deliverables and Deadline Pressure
Price depends on what you actually need at the end, such as reconciled ledgers ready for reporting. Tight deadlines can push prices higher, because staff have to be moved onto the file. But fast bookkeeping does not speed up CRA processing and it does not reduce a penalty that has already accrued.
The Three Pricing Models in the Canadian Market
Shop around for a cleanup and you will be offered one of three arrangements. All three exist, and it is worth knowing how each behaves before you compare two quotes side by side.
| Pricing Model | What It Covers | Limitations |
|---|---|---|
| Flat fee | A set price based on backlog details such as open periods and account count | Needs accurate information up front, so the scoping step has to be real |
| Hourly | Charges for the hours actually worked | Total cost is unknown without a clear scope, and the estimate is not a quote |
| Hybrid | A base fee plus hourly charges if something unexpected appears | Harder to budget, because the variable part has no ceiling unless one is written in |
The trap in the hourly model is not the rate. It is that an hourly rate multiplied by an estimated number of hours is not a fee, and it is routinely presented as one. Complexity is what moves the hours, and complexity is exactly what nobody has measured at the point the estimate is given. When you compare quotes, make the scopes match first; otherwise you are comparing two different jobs and calling it a price difference.
A client brought us a cleanup already half-finished elsewhere, abandoned because the running total had gone past what she had budgeted for the whole project. The arrangement had been hourly against an estimated scope. Nobody had counted her accounts at the start, and she had three bank accounts and a merchant processor rather than the single account she had mentioned on the phone, with roughly $310,000 of deposits running through the ones nobody had been told about. The hours were honest. The estimate had simply been built on a file nobody had looked at. Figures changed for privacy.
How Gondaliya CPA Charges for This Work
We do not bill by the hour, for cleanups or for anything else. Our fees are fixed and annual with no hourly billing, shown before tax with sales tax on its own line. A catch-up is scoped work: we look at the open periods, the account list, the transaction volume and the record condition, we agree what is in and what is out, and the fee for it is fixed before the work begins. If the scope changes, that is a written change order and a new agreed number, not a meter that has been running quietly in the background.
Which is also why there is no price on this page. We will not publish a figure, a range, or a starting-from number for a cleanup, because any of those would be invented until somebody has looked at your file. The initial consultation is free, and it exists precisely so that the scope can be established before anyone talks about money. That is not evasion; it is the honest answer to the question. The cost of your catch-up is the four inputs in the previous section, applied to your business.
A flat annual arrangement and a cleanup are two different things, and it is worth not confusing them. The flat annual fee covers ongoing work at a steady, predictable cost. A cleanup is a one-off project, scoped and fixed before it starts, sized by the backlog in front of us. Many clients end up with both: the cleanup to get current, then the annual arrangement so it never happens again.
A contractor spent eleven weeks getting three quotes for the same backlog and did nothing while he compared them. By the time he chose, the corporate return had gone from late to very late, the GST/HST position had been assessed on an estimate, and the penalties and interest sitting on the file came to roughly $41,000. The gap between the cheapest quote and the dearest was a fraction of that. We have never seen a cleanup where the difference between two sensible quotes cost more than the delay in choosing between them, and we have seen the opposite many times. Figures changed for privacy.
What Is Included, What Is Excluded, and How the Work Runs
Scope
What a Catch-Up Bookkeeping Project Includes and Excludes in Canada
Knowing what is included is how you avoid surprises when you read a quote. Knowing what is excluded is how you avoid the bigger surprise later.
Common Inclusions
- Reconciling the bank, card and loan accounts listed in the scope.
- Checking and sorting transactions by period, with proper cut-offs.
- Getting the records into a state from which a compilation engagement can be performed.
- Identifying missed filings and telling you about them, without preparing or submitting them.
- Making the adjusting entries needed inside the records themselves.
That third point is worth reading twice, because it is widely misdescribed. Catch-up bookkeeping is not a compilation engagement and it does not produce a compilation engagement report. CSRS 4200 governs compilation engagements, which are a separate professional service producing compiled financial information with a compilation engagement report attached to it. Bookkeeping output is not required to meet CSRS 4200 and does not carry that report. What a cleanup does is get the underlying records to the point where a bookkeeping file can support one. If you want the financial statements as well, that is a second engagement, quoted separately, and the standard it is performed under is issued by the Auditing and Assurance Standards Board.
Common Exclusions That Affect the Final Fee
- Filing late corporate (T2), personal (T1) or GST/HST returns.
- Submitting payroll remittances or preparing slips.
- Correcting errors inside returns that have already been filed.
- Rebuilding missing source documents from scratch.
- Representing the client during a CRA audit or dispute.
Two of those need a word of explanation, because an exclusion from a bookkeeping scope is not the same thing as a service we do not offer. We file T2 corporate returns, personal returns and GST/HST returns, and we do represent clients through CRA audits and disputes. Both are services we provide directly. They are excluded from a catch-up bookkeeping scope because they are different work with different risks, and putting them inside one number is how a client ends up unable to tell what they paid for. SR&ED claim preparation is the one piece we do not do at all; those are referred out.
Penalties and interest under the Income Tax Act or the Excise Tax Act arise separately once amounts are late, and they are never mixed into a bookkeeping fee.
A client assumed the cleanup quote covered fixing two GST/HST returns she already knew were wrong, because fixing them felt like part of the same problem. It is not, and we had quoted it as its own line, which she had read as optional. The reason it is separate is that it is genuinely different work: once the books were rebuilt, the adjustment requests recovered roughly $16,500 of input tax credits she had never claimed, which took judgement about what was supportable rather than data entry. Had it been buried inside the bookkeeping fee, neither of us could have shown what that money cost to recover. Figures changed for privacy.
Workflow: From Intake to Controller Review
Here is how we move from intake to final review when quoting and running catch-up work.
- Intake and quick assessment. We gather how many periods need catching up, the number of bank and loan accounts involved, estimated transaction counts per month, and any filings owed. This is the free consultation, and it is deliberately the step that happens before any number is discussed.
- Scoring complexity and estimating effort. Each factor is scored against set criteria, which builds a scope sheet listing every part of the workload. Open periods set the base effort; the number of accounts widens the task.
- Open periods and accounts set the base. More open periods add time vertically, because each month needs working. More accounts add tasks horizontally, because each account must be reviewed in every period.
- Transaction volume moves the quote. Higher volumes increase the sample sizes tested where full checks are not practical. Even with identical periods and accounts, more transactions mean more labour.
- Record condition adjusts the estimate. Messy or incomplete records mean extra verification that raises cost compared with tidy books, where the workflow runs straight through.
- Amendments are scoped as rework. If returns already filed turn out to contain errors, correcting them is a discrete piece of work with its own scope and its own fee.
- Controller or accountant review. A controller reviews the completed work before sign-off, to confirm quality and readiness for whatever comes next, including a compilation engagement where one has been asked for.
- Written change control. Any departure from the agreed scope is documented in writing as a change order, with the revised fee agreed before the extra work is done. That is what keeps a fixed fee fixed and keeps both sides out of a billing argument at the end.
The Cost of Waiting and How to Keep the Bill Down
Risk and Control
Risks of Delaying a Catch-Up, and Practical Ways to Reduce What It Costs
Waiting too long to catch up on bookkeeping costs Canadian businesses more than they expect. The longer you wait, the messier the records get, which raises the cleanup cost directly, because more time goes into fixing mistakes and finding missing information.
The larger cost is usually elsewhere. If you delay, the CRA can charge penalties and interest on late filings and unpaid amounts, and those charges are entirely separate from bookkeeping fees. Missing deadlines leads to failure-to-file and failure-to-remit penalties, plus interest that starts running the day after the amount was due.
The Penalties, Correctly Separated
Three different penalties get mixed together constantly, including by people quoting them at business owners. They are not the same provision and they do not apply to the same failure.
| Provision | What Triggers It | How It Is Calculated | Source |
|---|---|---|---|
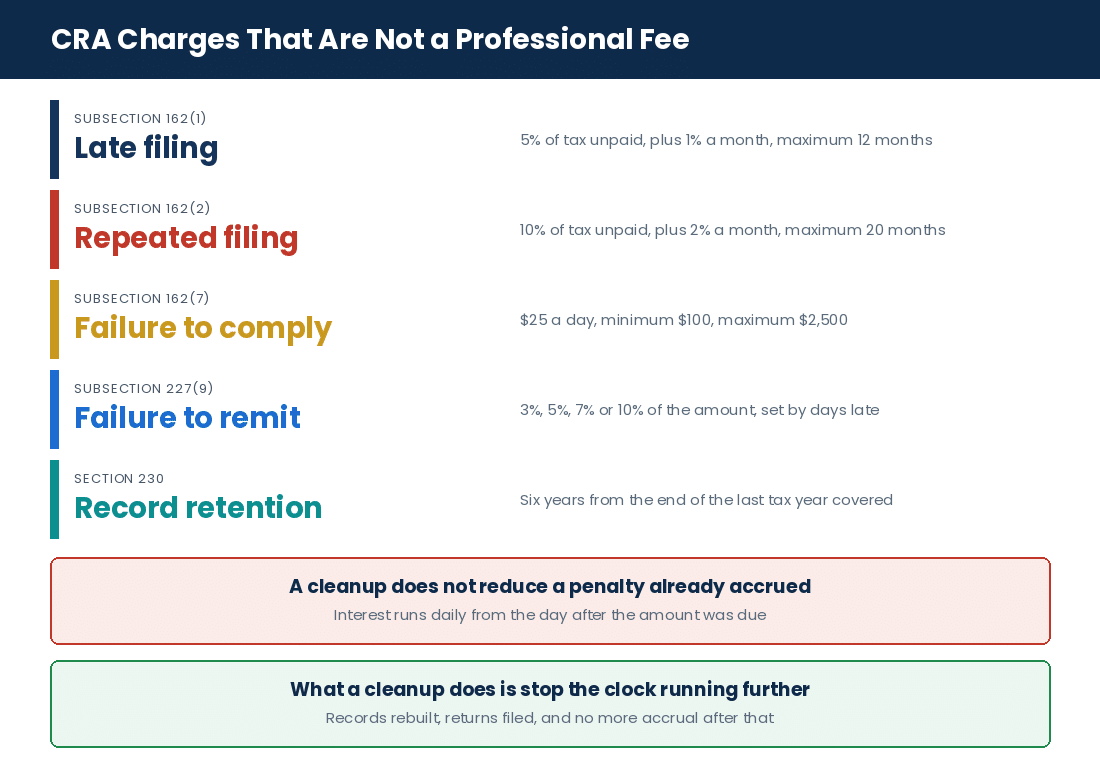
| Subsection 162(1), late filing a return of income | Filing a T2 or T1 after the due date with tax unpaid | 5% of the tax unpaid on the due date, plus 1% of that unpaid tax for each complete month the return is late, to a maximum of 12 months | Income Tax Act |
| Subsection 162(2), repeated late filing | A demand to file was issued under subsection 150(2) and a 162(1) penalty was assessed in any of the three preceding taxation years | 10% of the tax unpaid on the due date, plus 2% of that unpaid tax for each complete month the return is late, to a maximum of 20 months | Income Tax Act |
| Subsection 162(7), failure to comply | Failing an information return or another duty or obligation where no other penalty is specified | $25 per day the failure continues, with a minimum of $100 and a maximum of $2,500 | Income Tax Act |
| Subsection 227(9), failure to remit | Payroll amounts deducted or withheld but not remitted when due | 3% if one to three days late, 5% if four or five days, 7% if six or seven days, and 10% if more than seven days late or if nothing is remitted at all | Income Tax Act |
| Subsection 227(8), failure to deduct | Not deducting or withholding at all | 10% of the amount that should have been withheld, rising to 20% where the failure was knowing or amounted to gross negligence | Income Tax Act |
Two further points on the payroll side, because they are where the numbers escalate. A second or subsequent failure-to-remit assessment in the same calendar year attracts 20% where the failure was made knowingly or in circumstances amounting to gross negligence. And interest runs daily on amounts outstanding, on top of every penalty above, so a payroll backlog compounds on two axes at once. The equivalent interest provision for GST/HST is section 280 of the Excise Tax Act, which is an interest provision and not a records one. Late filing penalties for corporations are worth understanding before you decide how long you can leave a backlog sitting.
How Long You Have to Keep the Records
Books and records must be kept for six years from the end of the last taxation year to which the records relate, under section 230 of the Income Tax Act and the retention regulations made under it. That is the rule, and it is not six years from the date of filing, which is the version that circulates. A corporation that has been dissolved keeps its records for two years after the day of dissolution. The GST/HST side carries its own obligation under section 286 of the Excise Tax Act, on broadly the same six-year basis.
A small employer kept paying net wages on time while the source deductions quietly went unremitted, on the theory that payroll was handled as long as staff were paid. Eleven remittance periods went by. Because the remittances were more than seven days late rather than a few days late, the penalty landed at the top of the scale rather than the bottom, and the assessment came to roughly $4,200 before interest. Nothing about the bookkeeping was difficult; the records were tidy. The cost was entirely in the delay, and no amount of cleanup afterwards reduced it by a dollar. Figures changed for privacy.
Paying a bookkeeper does not lower a CRA penalty or the interest on it. Those charges stand alone and they are not negotiable through better record-keeping after the fact.
Benefits of Staying Current
Keeping books up to date saves money on catch-up fees, because when you do the work regularly there is no large cleanup to pay for. Fewer periods and fewer transactions pile up, so the work stays small.
An annual arrangement also lets you budget, instead of meeting a one-off cleanup bill at the moment your backlog has grown to its largest. And tidy books reduce the chance of a wrong filing, which lowers the risk of a reassessment or a review that needs professional help to answer. Current records also make the whole filing season shorter and less expensive.
DIY, a Bookkeeper, or an Accountant
Who does the catch-up matters for cost and for quality:
- DIY. Looks cheap and can backfire. Mistakes or missing documents mean more work later, usually paid for by somebody else at a higher rate than it would have cost to do right.
- Bookkeeper. Good at tracking transactions, which is most of the volume in a backlog. A bookkeeper does not perform compilation engagements or file the corporate return, so if you need financial statements or filings at the end, those come from elsewhere.
- Accountant (CPA). Scopes the whole job, prices it against open periods and tasks, and keeps the bookkeeping separate from the filings rather than blending them into a single opaque number.
Consider the flat annual arrangement against cleanup pricing as well. The annual fee covers routine upkeep at a steady cost; the cleanup price moves with the size of the backlog and the work it needs. Ask for a detailed scope before you choose anyone, and treat an hourly rate quoted without a scope as what it is, which is not a quote.
Reducing the Cost Without Cutting Corners
- Gather bank statements, receipts and invoices before the work starts, so nobody is waiting on you mid-job.
- Break a very large backlog into phases where that is practical, so each phase stays a manageable size.
- Know exactly which returns are behind, so you are not paying to find out.
- Check filings already made, so amendments are identified at scoping rather than discovered halfway through.
- Tell us quickly about anything that changes during the job, so it goes through change control instead of surfacing at the end.
- Move to an annual arrangement once the cleanup is done, so the backlog never rebuilds.
| Scope Input Changed | Effect on Pricing |
|---|---|
| Additional open periods | Increases the base workload proportionally |
| More accounts reconciled | Raises reconciliation and transaction sampling effort |
| Added filings behind | Expands the obligation-related tasks outside the bookkeeping scope |
| Poorer record condition | Requires extra verification steps per transaction |
| New amendments identified | Adds a discrete rework scope, quoted separately |
Talk these points through before the work starts, so the agreed fee matches the actual effort rather than anybody’s guess about it.
Frequently Asked Questions
FAQs
FAQs on Catch-Up Bookkeeping Cost and Services in Canada
What affects the catch-up bookkeeping cost in Canada?+
How many periods you need to catch up on, how many accounts must be reconciled, and how many transactions ran through each period. The condition of the records and any filings or amendments needed affect it as well. Each one adds work, and each one moves the price.
Why can I not get a fixed price before my backlog has been looked at?+
Because the scope is the price. Until somebody knows how many periods are behind, which accounts need work, how many transactions sit in them and what obligations are outstanding, any number is a guess that will move later. Our fee is fixed before the work starts, which is exactly why the scoping step has to come first. The initial consultation is free.
What is the CRA retention period for books and records?+
Six years from the end of the last taxation year to which the records relate, under section 230 of the Income Tax Act and the regulations made under it. It is not six years from the date you filed. A dissolved corporation keeps its records for two years after the day of dissolution.
How are late filing penalties calculated by the CRA?+
Under subsection 162(1), filing a return of income late carries 5% of the tax unpaid on the due date, plus 1% of that unpaid tax for each complete month the return is late, to a maximum of 12 months. Where the CRA has issued a demand to file under subsection 150(2) and a 162(1) penalty was assessed in any of the three preceding taxation years, subsection 162(2) applies instead at 10% plus 2% per month, to a maximum of 20 months.
What is the penalty for failing to comply with a filing obligation?+
That is subsection 162(7), a separate provision from the late filing penalty above. It is $25 per day the failure continues, with a minimum of $100 and a maximum of $2,500. It applies where no other penalty is specified for the particular failure.
What happens if payroll amounts are not remitted on time?+
Under subsection 227(9) the penalty is 3% if the amount is one to three days late, 5% if four or five days, 7% if six or seven days, and 10% if more than seven days late or if nothing is remitted. A second or subsequent failure in the same calendar year attracts 20% where it was knowing or amounted to gross negligence. Failing to deduct at all is 10%, rising to 20% in the same circumstances. Interest runs daily on top.
Do professional fees cover CRA penalties or interest?+
No. Professional fees cover the accounting work agreed in the engagement. Penalties and interest are statutory charges owed to the CRA and sit entirely outside any bookkeeping or filing fee.
Does catch-up bookkeeping have to meet the CSRS 4200 standard?+
No. CSRS 4200 governs compilation engagements, which are a separate professional service that produces compiled financial information with a compilation engagement report attached. Bookkeeping output is not required to meet that standard and does not carry that report. What a catch-up does is get the records into a state from which a compilation engagement can be performed, if you want one, as a second engagement.
How does GST/HST reporting frequency affect what a cleanup costs?+
Reporting periods are assigned on annual taxable supplies: $1,500,000 or less is annual, more than $1,500,000 up to $6,000,000 is quarterly, and more than $6,000,000 is monthly, with charities and most listed financial institutions assigned annual. More filing periods inside the same backlog means more cut-offs to reconcile, so two years behind on a monthly period is a much larger job than two years behind on an annual one.
Can one quote cover rebuilding books, filing returns and handling a dispute?+
It should not. Those are different pieces of work with different risks, and we scope and price them separately so you can see what each one costs. We do all three, including catch-up corporate tax filing and representing clients through CRA audits. Rolling them into a single number is how clients lose track of what they paid for.
This set covers what drives catch-up bookkeeping cost in Canada, what the statutory charges alongside it actually are, and where the boundary of a bookkeeping scope sits.
Essential Points for Business Owners
Key Takeaways
Key Points on Catch-Up Bookkeeping Pricing and Good Practice
The scoping conversation happens once. Everything in the table below is what that conversation is trying to establish, and what happens afterwards if it was done properly.
| Point | What It Means in Practice |
|---|---|
| Scope sheets | A written scope sheet defines the workload before any fee is agreed, rather than after. |
| Baseline workload | Open periods and account counts set the initial effort, before anything else is counted. |
| Sampling effort | Transaction volume adjusts how much is tested where checking every item is impractical. |
| Separate scopes | Bookkeeping, filings and amendments are scoped separately so each cost is visible. |
| Amendments | Errors inside returns already filed trigger a separate scope discussion, never a silent extra. |
| Change control | A written change order manages scope movement during the job and keeps a fixed fee fixed. |
| Fee structure | Our fees are fixed and annual with no hourly billing, shown before tax with sales tax on its own line. |
| Cleanup versus annual | A cleanup is one-off scoped work; the annual arrangement is ongoing upkeep at a steady cost. |
| Document preparation | Statements, receipts and invoices gathered before the start shorten the job and lower the cost. |
| Filing frequency | GST/HST reporting period and payroll remitter type decide how many cut-offs sit in a backlog. |
| Penalties are separate | CRA penalties and interest are statutory and never form part of a professional fee. |
| Record retention | Six years from the end of the last taxation year to which the records relate. |
| Compilation boundary | A cleanup prepares records; a compilation engagement is a separate service with its own report. |
| Audit representation | CRA audit representation is a service we provide, scoped and quoted on its own. |
| Free consultation | The initial consultation costs nothing and exists so scope is established before money is. |
The Six Things We Check First
- How many periods are actually open? Not how many months since you stopped looking, but how many have nothing recorded or nothing reconciled.
- How many accounts were live in those periods? Every bank, card, loan and merchant account, including the ones that have been forgotten about.
- Roughly how many transactions a month? This is the single number that most often turns out to be ten times what the owner estimated.
- What condition are the source documents in? Clean digital files and a box of loose paper are different jobs at the same number of months.
- What is your GST/HST reporting period and your payroll remitter type? They decide how many deadlines are sitting behind you.
- Is anything already filed likely to be wrong? Amendments are a separate scope, and we would rather find them now than halfway through.
Our Approach
Gondaliya CPA starts with a free consultation that counts the open periods, lists the accounts, estimates the transaction volume and looks at the state of the paperwork, before any figure is discussed. We write that into a scope sheet, agree what is in and what is out, and fix the fee for the cleanup before the work begins. We reconcile every listed account in every open period, apply proper cut-offs, make the adjusting entries the records need, and put the file through a controller review before sign-off. Where returns are behind we quote the filing work separately, where something already filed is wrong we quote the amendment separately, and where a compilation engagement is wanted at the end that is its own engagement again. We represent clients through CRA audits directly, which is a service we provide and not an assurance engagement. Scope changes go through written change control. Our ongoing fees are fixed and annual with no hourly billing, shown before tax with sales tax on its own line, and agreed before any work begins.
Industry Spotlights: Sectors We Represent
Industry Expertise
Every sector builds a backlog in its own way, and the shape of the backlog is what sets the cleanup price. Here are eleven, and what makes each one expensive.
| Industry | What Makes the Backlog Expensive |
|---|---|
| Technology startups & SaaS | Subscription billing and processor settlements that never match the bank line |
| E-commerce & online retailers | Several storefronts and processors, each needing its own reconciliation every period |
| Consulting firms | Few transactions, but expense classification that decides the tax outcome |
| Construction, contractors & skilled trades | Holdbacks, progress billings and payroll deadlines arriving together |
| Property developers & builders | Project costs that must land in the right period or the margin is wrong |
| Real estate investors & holding companies | One account trail per property, plus intercompany movements between entities |
| Transportation, logistics & trucking | Fuel cards and per-trip settlements generating volume in every period |
| Restaurants & food and beverage | Daily cash, tips and multiple processors, the highest volume per dollar of revenue |
| Daycare, childcare & CWELCC services | Funding reporting that runs on its own calendar alongside the books |
| Dentists & dental practices | Practice software that does not reconcile itself to the bank account |
| Medical doctors & physician corporations | Practice income, remuneration decisions and a payroll that cannot wait |
- Technology startups & SaaS: A platform settlement is net of fees, refunds and chargebacks, so one deposit hides four numbers and gross sales are never in the bank feed.
- E-commerce & online retailers: Multiple storefronts, processors and currencies mean several reconciliations per period rather than one.
- Consulting firms: Low transaction volume but high expense-coding judgement, so cleanups here are short on entry and long on classification.
- Construction, contractors & skilled trades: Progress billings, holdbacks and a payroll that is often on an accelerated remittance schedule stack deadlines quickly.
- Property developers & builders: Project costs spread across periods, so a cut-off error in one month misstates the margin on a whole site.
- Real estate investors & holding companies: Each property has its own account trail, and intercompany transfers between entities are where backlogs get tangled.
- Transportation, logistics & trucking: Fuel cards, per-trip settlements and owner-operator payments produce high volume in every single period.
- Restaurants & food and beverage: Daily cash, tips, several merchant processors and food supplier statements make this the highest volume per dollar of revenue.
- Daycare, childcare & CWELCC services: Funding and subsidy reporting runs on its own calendar, so a bookkeeping backlog becomes a reporting backlog too.
- Dentists & dental practices: Practice management software rarely reconciles itself to the bank, and the gap between the two is the cleanup.
- Medical doctors & physician corporations: Professional corporation bookkeeping mixes practice income, remuneration decisions and a payroll that cannot be left behind.
An online retailer and a consultancy came to us the same month, both eighteen months behind, and the quotes were nowhere near each other. The consultancy had around forty invoices and a handful of expenses a month, filed properly. The retailer had two storefronts, three processors and a bank feed showing net settlements, so every deposit had to be unpicked into gross sales, platform fees, refunds and chargebacks before a single figure was reliable. Roughly $88,000 of gross sales had never appeared anywhere in the records, because only the net had ever reached the bank. Same months behind, entirely different piece of work. Figures changed for privacy.
Professional Guidance and Quick Reference
Guidance
Where Catch-Up Bookkeeping Projects Go Wrong, and What to Fix First
Catch-up files go wrong in a predictable set of ways: an hourly estimate accepted as a total and then exceeded, because nobody counted the accounts first; a backlog quoted off the number of months while the transaction volume inside them is ten times what the owner thought; a cleanup priced as if the three GST/HST returns behind it were included, when returns were never in the bookkeeping scope; an amendment discovered halfway through and treated as a dispute rather than a scope change; payroll left until last because staff were being paid, while the remittance penalty climbed with every week; and a business that paid for the cleanup and then went straight back to recording nothing, so the same bill arrived again two years later. Gondaliya CPA scopes the file before putting a number on it, and fixes that number in writing.
Quick Answers
At a Glance
- What sets the base: the number of open periods multiplied by the accounts live in them
- What moves it most: transaction volume per period
- What is hardest to predict: record condition
- Backlog: transactions never entered
- Cleanup: transactions entered wrongly
- Our fee structure: fixed and annual with no hourly billing, shown before tax with sales tax on its own line
- A cleanup with us: scoped work, agreed and fixed before it begins
- Initial consultation: free
- Price published on this page: none, and deliberately so
- Market models you will meet: flat fee, hourly, hybrid
- Hourly rate times estimated hours: an estimate, not a quote
- Included as standard: reconciliation of listed accounts, period sorting, adjusting entries
- Not included: late returns, payroll remittances and slips, amendments, document reconstruction
- Audit representation: outside a bookkeeping scope, and a service we provide separately
- SR&ED claims: referred out
- Compilation engagement: a separate engagement under CSRS 4200, with its own report
- Bookkeeping output: not required to meet CSRS 4200 and carries no such report
- GST/HST assigned annual: annual taxable supplies of $1,500,000 or less
- GST/HST assigned quarterly: more than $1,500,000 up to $6,000,000
- GST/HST assigned monthly: more than $6,000,000
- Reporting period changes: not automatic when supplies cross a threshold
- Quarterly payroll remitter: average monthly withholding under $3,000, with a perfect compliance record
- Regular payroll remitter: average monthly withholding under $25,000
- Threshold 1 accelerated: $25,000 to $99,999.99
- Threshold 2 accelerated: $100,000 or more
- Late filing, subsection 162(1): 5% plus 1% per month, maximum 12 months
- Repeated late filing, subsection 162(2): 10% plus 2% per month, maximum 20 months
- Failure to comply, subsection 162(7): $25 per day, minimum $100, maximum $2,500
- Failure to remit, subsection 227(9): 3%, 5%, 7% or 10% by days late
- Record retention: six years from the end of the last taxation year to which the records relate
Who This Is For / Not For
Fit Check
- Ideal candidates: Canadian businesses several months or several years behind who want the scope established before the fee.
- Ideal candidates: owners who also have returns behind and want the bookkeeping and the filings priced separately rather than blended.
- Not suitable for: anyone who wants a figure quoted over the phone without the file being looked at, because we will not give one.
- Not for: a view on your own filing position without reviewing your facts, which is what the free consultation is for.
People Also Ask
Related Questions
How do I compare catch-up quotes from different providers fairly?+
Make every quote list the same things: the number of open periods, the accounts to be reconciled, the transactions to be worked or sampled, the obligations outstanding, the record condition assumed, any amendments identified, and whether filing returns is inside or outside the price. Two quotes that differ on any of those are quotes for two different jobs. Most apparent price gaps in this market are scope gaps, and the cheapest-looking quote is usually the one that assumed the least work.
Is hourly billing normal for catch-up bookkeeping in Canada?+
You will certainly meet it, along with flat fees and hybrids, so it is fair to call it common in the market. We do not use it. Our fees are fixed and annual with no hourly billing, shown before tax with sales tax on its own line, and a cleanup is scoped and fixed before it starts. The practical reason is the one this whole article is about: an hourly rate multiplied by an estimate is not a total, and the client carries all of the risk that the estimate was wrong.
Will a fast cleanup reduce the penalties I already owe?+
No. Penalties and interest accrue by statute from the date an amount was due, and no amount of bookkeeping afterwards unwinds them. What a cleanup does is stop the clock on the obligations that are still running and let the returns be filed, which prevents further accrual. It will not reduce what has already been assessed. If there are grounds for relief, that is a separate application and a separate conversation.
Can I do the catch-up myself and bring you only the finished books?+
You can, and some clients do it well. Be honest with yourself about which half you are taking on, though: entering transactions is the volume, but reconciling every account in every period and getting the cut-offs right is the part that decides whether the numbers are usable. If the reconciliations have not been done, we will be redoing the work rather than reviewing it, and that costs more than if we had started from the statements.
What should I bring to the free consultation?+
The number of months you believe are open, a list of every bank, credit card, loan and merchant account the business has used in that time, a rough monthly transaction count, whichever statements you can lay hands on, your GST/HST reporting period and payroll remitter type, and copies of any returns already filed for the periods in question. With those we can scope the job properly. Without them, anything we said about cost would be a guess.
Glossary of Key Terms
Definitions
- Catch-up bookkeeping: bringing financial records up to date where periods are behind, by entering and reconciling what was missed.
- Backlog: transactions that were never entered, measured by period and by volume.
- Cleanup: correcting errors inside records that already exist, including misclassified and duplicated entries.
- Open period: a month or quarter with nothing recorded, or with entries never reconciled to a statement.
- Record condition: how complete and organised the source documents are when the work starts.
- Reconciliation: matching the ledger for an account to the statement for that account, period by period.
- Scope sheet: the written list of periods, accounts, volumes and obligations a fee is agreed against.
- Change order: a written variation to an agreed scope, with the revised fee agreed before the extra work is done.
- Compilation engagement: a separate service under CSRS 4200 producing compiled financial information with a compilation engagement report.
- Amendment: correcting a return already filed, by amended return or by a request to adjust it.
- Reporting period: the GST/HST filing frequency assigned on annual taxable supplies, which does not change by itself.
- Average monthly withholding amount: the figure that sets how often an employer must remit payroll source deductions.
- Failure to remit: the subsection 227(9) penalty on payroll amounts withheld but not remitted when due.
- Books and records: the records a business must keep under section 230 of the Income Tax Act to support reported amounts.
Want a checklist to work from? You can download our free catch-up bookkeeping scope checklist before your consultation.
Four things decide what your catch-up costs, and none of them is on a price list. How many periods are genuinely open — not months since you stopped looking, but months with nothing recorded or nothing reconciled, because that count is the base of every quote. How many accounts were live inside them — each bank, card, loan and merchant account is worked in every period, so accounts multiply the base rather than adding to it. How many transactions sit in each period — two businesses fourteen months behind can be six times apart on this one number alone, and it is the figure owners most often underestimate. And what condition the paperwork is in — clean digital files run straight through, while missing documents and wrong entries add verification to every line. Our fees are fixed and annual with no hourly billing, shown before tax with sales tax on its own line, a cleanup is scoped and fixed before it begins, and the initial consultation that establishes all four inputs is free.
Three things settle a cleanup quote before anybody discusses money. First, how many periods and how many accounts? Count them properly, including the account the business opened for one project and forgot about, because that single omission is the commonest reason an estimate is exceeded. Second, what is behind besides the bookkeeping? Corporate returns, GST/HST returns, payroll remittances and slips are each separate work, and whether they are inside or outside the price is the difference between two quotes that look the same. Third, could anything already filed be wrong? Amendments are a discrete scope, they are far cheaper to identify at the start than to discover halfway through, and they are where delay turns into penalties and interest that no bookkeeper can reduce.
Catch-Up Bookkeeping Costs: How Gondaliya CPA Can Help
Let us scope it first, then fix the fee
Gondaliya CPA counts your open periods, lists every account live inside them, estimates transaction volume, looks at the condition of your documents and checks your GST/HST reporting period and payroll remitter type, all before a number is put on anything. We write it into a scope sheet, agree what is in and what is out, and fix the fee for the cleanup before the work begins. We reconcile every listed account in every open period, apply proper cut-offs, make the adjusting entries the records need, and run a controller review before sign-off. Late returns, amendments to returns already filed, a compilation engagement where you want financial statements, and representation through a CRA audit are each quoted separately so you can see what each one costs. Scope changes go through written change control. Our ongoing accounting fees are fixed and annual with no hourly billing, shown before tax with sales tax on its own line, and agreed before any work begins. The initial consultation is free. Please book one.
Next Steps
Have more questions or need personalised guidance? Schedule a free consultation with our expert CPAs today and get the backlog scoped properly before anybody talks about a fee. Bring three things when you do: the number of months you believe are open, a list of every bank, credit card, loan and merchant account the business has used across that time, and a rough monthly transaction count. Add your GST/HST reporting period, your payroll remitter type and copies of anything already filed for those periods, and the scope sheet can be written in one sitting. If payroll remittances are among what is behind, say so first, because that is the exposure that grows fastest while you decide. We serve Toronto, Mississauga, Brampton, Vaughan, Etobicoke, Scarborough, Hamilton, Ottawa and the rest of Ontario, and we take on catch-up bookkeeping for clients across Canada. If our content helps, please add gondaliyacpa.ca as a preferred source on Google.
Published: · Last updated:
Editorial policy: We research against the Income Tax Act and the Income Tax Regulations, the Excise Tax Act, CRA guidance and information circulars, CPA Canada Handbook standards including those issued by the Auditing and Assurance Standards Board, and CPA Ontario sources, fact-check the figures, and Sharad Gondaliya, CPA, reviews the content, which we update as the rules change.
Disclaimer: This article is educational information only and is not tax, legal or accounting advice. It covers what catch-up bookkeeping costs in Canada and why, including the difference between a backlog and a cleanup, the signs that records have fallen behind, the scope inputs behind a quote, GST/HST reporting periods and payroll remittance frequency as volume drivers, the pricing models found in the market, what a cleanup includes and excludes, the workflow from intake to controller review, written change control, the CRA penalty and interest exposure that runs alongside professional fees, and record retention obligations. It does not quote a fee for any engagement without a review of the file, advise on any particular business’s filing position, or address provincial sales tax regimes outside GST/HST. Statutory rates, thresholds, penalties and forms change without notice and should be confirmed against the governing legislation and current CRA guidance at the time you act. Gondaliya CPA performs compilation engagements under CSRS 4200, which provide no assurance, and does not perform audit or review engagements; we do represent clients through CRA audits, which is a separate service. We do not prepare SR&ED claims. Please consult a licensed CPA before acting.
Sharad Gondaliya is a CPA Canada & CPA USA with 15 Years+ experience of Accounting, Tax, Payroll of Corporate Small Businesses as Tax Accountant. He is a CPA Ontario member (61040184) and holds US CPA licences in Washington and Montana and is well known among corporate small businesses for tax planning, efficient tax solutions, and affordable CPA services. Sharad is the Principal (Director) of Gondaliya CPA – Affordable CPA Firm in Canada. Licenses: CPA Ontario: 61040184 | CPA USA (MT): PAC-CPAP-LIC-033176 | CPA USA (WA): 57629 | CPA Firm License: 61330051 View Full Author Bio