



CRA Audit Checklist for Small Businesses in Canada: Documents You Must Prepare
CRA Audit Checklist Canada: Essential Tax Audit Documents and Business Audit Preparation Checklist by Gondaliya CPA
CRA audit checklist Canada is a key tool for tax audit readiness, helping businesses gather all necessary tax audit documents Canada and meet CRA records requirements. Gondaliya CPA provides a clear business audit preparation checklist that covers documentation standards and year-end audit preparation steps.
Most audit guidance lists documents. The harder question is which ones actually decide the outcome, and the answer is narrower than the list suggests. Getting CRA audit preparation right means knowing where a claim stands or falls.
Quick Summary
An audit turns on four things: whether your books reconcile to your bank, whether every claimed expense has a document tying it to the business, whether payroll and sales tax were reported consistently, and whether you can produce it all within the deadline you are given.
Reading time: 51 minutes.
Table of Contents
The Numbers That Matter
This article covers Canada, with Ontario and Toronto context, and reflects rules current to 2026. It is written for incorporated Canadian small businesses facing an income tax, GST/HST or payroll examination. Figures marked illustrative are examples, not quotes, and any masked engagement notes end with “Figures changed for privacy.” This is educational information only and not tax or legal advice. Timelines and reassessment periods vary with the type of taxpayer, the tax involved and the circumstances, so please have your own position confirmed. Where an audit involves allegations of misrepresentation or moves toward enforcement, legal counsel should be involved.
What an Audit Actually Is
What an Audit Actually Is
The Framing
The Distinction Most People Miss
An audit does not ask whether your tax was correct in the abstract. It asks whether the amounts on your return are supported by records you can produce.
A perfectly legitimate expense with no invoice behind it can be disallowed. A deduction you were fully entitled to becomes a reassessment because the paperwork went missing. That is the whole game, and it is decided long before the auditor calls.
Review Against Audit
| Type | What It Involves | Typical Scope |
|---|---|---|
| Processing or matching review | An automated check against third-party information | One or two figures |
| Desk review | A written request for support on specific items | Named claims or credits |
| Office audit | Records examined at a CRA office | Broader, still targeted |
| Field audit | An auditor attends your premises | Books and records generally |
| GST/HST examination | Focused on collected tax and input tax credits | Sales tax accounts |
| Payroll examination | Remittances, classification and benefits | Employer accounts |
The scale matters because the response differs. A request for one receipt is answered with one receipt. A field audit is a different exercise entirely, and treating it casually is how a narrow enquiry becomes a broad one. Our comparison of a CRA audit and a CRA review sets out the difference in detail.
What Actually Triggers One
- Ratios out of line with your sector, particularly gross margin and expense-to-revenue
- A sharp year-over-year change with no visible explanation
- Sales tax filings that do not reconcile to reported revenue
- Third-party information that does not match your return
- Repeated late filing or a history of amendments
- A cash-intensive business with thin documentation
- Losses claimed year after year against other income
- Random selection, which is genuinely a factor
Notice how many of these are visible from the return alone. Most audits begin with something the CRA could see without asking you anything.
Indirect Verification
Where records are inadequate, the CRA is not obliged to give up. It can estimate income by other means: comparing your lifestyle and assets against declared income, applying industry markups to purchases, or analysing bank deposits.
The burden then effectively sits with you to displace their estimate. That is a far worse position than answering questions from a clean set of books, and it is the real cost of poor record keeping.
Clients assume the argument will be about tax law. It almost never is. It is about whether a document exists, and that was decided years earlier. Figures changed for privacy.
Risk Warning: A legitimate expense with no supporting document can still be disallowed. Please treat the record as part of the deduction.
The Records You Must Keep
The Records You Must Keep
The Obligation
The Legal Requirement
Every person carrying on business in Canada must keep books and records at their place of business or another designated place, in a form that allows the tax payable to be determined.
Two things follow that people miss. Records must be kept in Canada unless permission has been obtained to keep them elsewhere, which matters for businesses using offshore bookkeeping or foreign cloud arrangements. And “adequate” is judged by whether the tax can be determined from them, not by whether you found them useful.
How Long
| Record | Retention |
|---|---|
| General books and records | Six years from the end of the last tax year they relate to |
| Records for a late-filed return | Six years from the date the return was filed |
| Capital property records | Until six years after the year the property is disposed of |
| Corporate minute book and share records | Generally retained permanently |
| Records relevant to an objection or appeal | Until the matter and any appeal period is resolved |
| Where the CRA has issued a written demand | For the period specified |
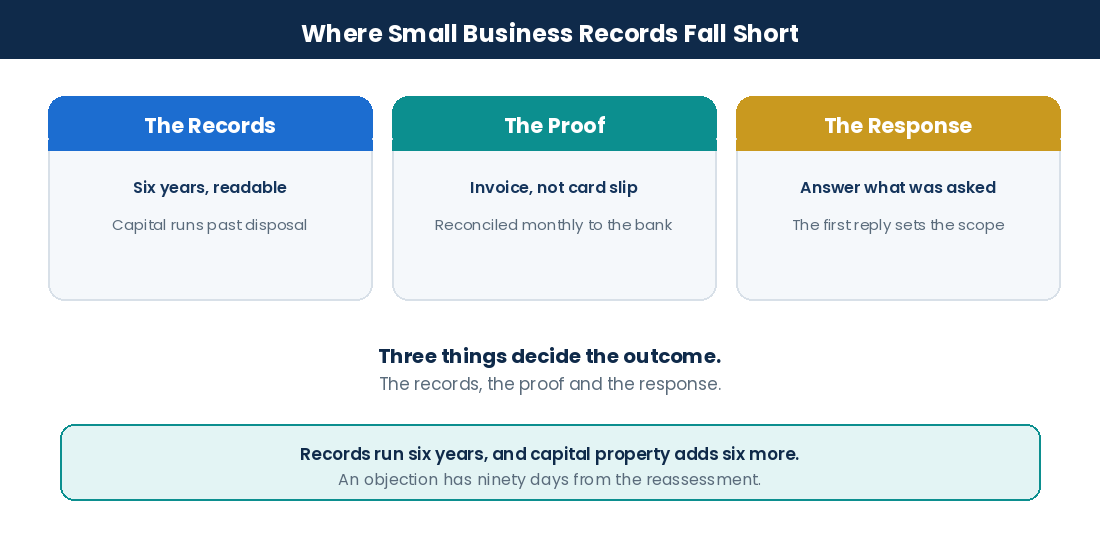
The capital property line is the one commonly stated wrongly. It is not “keep until you sell”. It is keep until six years after the end of the year of disposition, because the gain or loss is calculated from the original cost. A property held for twenty years needs its purchase documents for twenty-six.
The dissolution point is worth noting too. Winding up a corporation does not end the retention obligation, and records must generally be kept for a period after dissolution.
Electronic Records
Electronic records are acceptable, and for most businesses they are now the norm. The conditions are what matter.
- Records must be kept in an electronically readable format
- They must be retrievable and readable throughout the retention period
- Scanned images must be legible and reproduce the original faithfully
- The system must maintain integrity, so records cannot be altered without trace
- Where records are kept only in encrypted or proprietary form, they must still be accessible
- Software and the ability to read the records must survive as long as the records do
That last point catches businesses that change accounting systems. Data exported to a format nobody can open is not a retained record, and a migration is exactly when six years of history quietly becomes unreadable.
Where scanned images meet the standards, paper originals generally need not be kept. Where they do not, the originals still matter.
What You Still Keep on Paper
Some documents are worth holding in original form regardless:
- The corporate minute book, resolutions and share certificates
- Signed agreements where the original signature carries weight
- Government certificates, licences and permits
- Anything you might need to produce as evidence in a dispute
Store these apart from working files, protected against fire and water, and know where they are. A minute book nobody can locate is a problem in an audit and a larger one in a sale.
Foreign and Offshore Records
Where records relating to your Canadian business are held outside Canada, or where transactions run through foreign accounts and entities, the obligation still applies and the CRA can require access.
Businesses using overseas bookkeeping services should confirm the arrangement meets the requirement rather than assuming that cloud access is equivalent to keeping records in Canada.
An accounting system migration is where six years of history goes missing. The data was exported; nothing left can read it. That is a record retention failure. Figures changed for privacy.
Key Stat: Capital property records run until six years after the year of disposition, not six years from purchase. Please keep acquisition documents for the whole holding period.
The Document Checklist by Category
The Document Checklist by Category
The Checklist
Financial Statements and the Return
- Balance sheet, income statement and, where prepared, the cash flow statement
- The notes to the statements and the engagement report
- The corporate return as filed, with all schedules
- The trial balance and its mapping to the return
- Adjusting journal entries with the reasoning behind each
- Prior-year statements for comparison
Adjusting entries deserve attention. A journal moving a material amount with a one-line description is exactly what an auditor asks about first, and “the accountant did it” is not an answer.
Bookkeeping and the General Ledger
- General ledger for each period under review
- Sales, purchase, cash receipts and cash disbursements journals
- Sales invoices issued, in sequence
- Purchase invoices received
- Inventory listings and count sheets where stock is held
- Accounts receivable and payable ageing
Invoice sequence matters more than people expect. Gaps in a numbered sales sequence invite the question of what was in the gap, and a plausible explanation given at the time is far easier than one reconstructed later.
Bank and Reconciliation
Bank reconciliation is the single most useful thing in an audit file, because it links the records to something the CRA can verify independently.
| Document | What It Establishes |
|---|---|
| Monthly bank statements, all accounts | Actual cash movement |
| Monthly reconciliation to the ledger | That the books agree with the bank |
| Outstanding item listings | Timing differences at each period end |
| Credit card statements, business cards | Card expenditure by account |
| Merchant processor statements | Gross sales against net deposits |
| Loan and financing statements | Principal, interest and the split between them |
Include every account through which business money moved, including a personal account used occasionally. Selective disclosure of accounts is the fastest route from a routine audit to a serious one.
Expense Support
An expense needs a document showing what was bought, from whom, when and for how much, and a link to the business purpose.
- Supplier invoices, not just credit card slips
- Vehicle logs where vehicle costs are claimed
- Meal and entertainment receipts noting the business purpose and who attended
- Travel itineraries connecting the trip to the business
- Contracts and engagement letters behind professional and service fees
- Home office calculations with the basis documented
- Asset purchase invoices with commissioning dates
A credit card statement proves money left the account. It does not prove what was bought or that it related to the business. Both are needed.
Payroll and Sales Tax
- Payroll registers by pay period
- T4 and T4A slips and summaries as filed
- Remittance records reconciled to the payroll register
- Employment contracts and contractor agreements
- Taxable benefit calculations, including vehicles
- GST/HST returns as filed, with the working papers behind them
- Input tax credit support, including customs documents on imports
- Provincial sales tax registrations and returns where applicable
Payroll and sales tax examinations often begin as a reconciliation exercise. Where revenue on the corporate return does not tie to sales reported on GST/HST returns, or wage expense does not tie to slips filed, that difference is the opening question.
Corporate and Legal
- The articles of incorporation and any amendments
- The minute book with directors’ and shareholders’ resolutions
- Share register and any transfers
- Shareholder loan account with supporting entries
- Related-party agreements, including rent and management fees
- Leases, financing agreements and major contracts
Resolutions matter where a transaction needs a corporate decision behind it: declaring a dividend, approving a bonus, setting related-party terms. A payment with no resolution and no agreement is harder to characterise the way you intended.
The shareholder loan account is where an audit usually goes next. It collects everything nobody knew how to code, and each entry needs an explanation. Figures changed for privacy.
Key Stat: A credit card statement shows money left the account. Please keep the supplier invoice showing what it bought.
The Audit Process, Step by Step
The Audit Process, Step by Step
The Process
First Contact
An audit generally opens with a letter, sometimes preceded by a call. It identifies the auditor, the periods and taxes under review, and what is required initially.
Read what is actually being asked. A request about one expense category is not an invitation to send three years of everything, and volunteering material outside the scope enlarges the audit without helping you.
- Note the deadline and diarise it the day the letter arrives
- Confirm receipt and establish a single point of contact
- Authorise your representative before responding, not afterwards
- Ask for an extension if the deadline is unrealistic; asking early is normal
- Keep a log of every request, response and conversation
Getting Your Representative in Place
Authorising a CPA to deal with the CRA on your behalf is administrative, and it should be done at the start.
The practical benefit is not secrecy. It is that questions get answered by someone who understands what is being asked and what the answer commits you to. An owner explaining their own books under pressure frequently says something imprecise that then has to be corrected.
The Fieldwork
In a field audit the auditor attends your premises. They have statutory powers to inspect records and to require information and documents.
| Do | Do Not |
|---|---|
| Provide a working space away from staff | Give unsupervised run of the office |
| Respond to requests in writing where practical | Answer complex questions off the cuff |
| Log every document handed over | Hand over originals without copies |
| Route questions through your representative | Let staff answer directly without briefing |
| Meet deadlines or ask for more time in advance | Miss a deadline silently |
| Correct an error you find yourself, promptly | Hope an error will not be noticed |
The last row matters. Finding your own error and raising it is materially better than having it found. It bears directly on whether a penalty for gross negligence is considered.
The Proposal Letter
Before reassessing, the auditor usually issues a proposal setting out the adjustments they intend to make and the reasoning. You are given a period to respond, commonly around thirty days.
This is the most valuable point in the whole process and it is routinely wasted. The auditor has not yet issued anything binding. Providing a missing document or correcting a misunderstanding here avoids an assessment you would otherwise have to formally object to.
A proposal disallows roughly $46,000 of subcontractor costs on the basis that the invoices lacked detail. Responding within the window with the contracts, the payment trail and the corresponding work records reduced the proposed adjustment substantially before any reassessment issued. The same evidence produced after assessment would have required a formal objection. Figures changed for privacy.
The Outcome
- No change: The audit closes with the returns as filed
- Adjustment in your favour: Less common, but it happens
- Adjustment against you: Additional tax, with interest from the original due date
- Adjustment with penalties: Where the conduct warrants it
- Referral: Where the auditor identifies indicators warranting different treatment
Interest runs from the original balance-due date, not from the reassessment, which is why a multi-year audit can produce an interest figure that surprises people more than the tax does.
The proposal letter window is the most under-used opportunity in the process. Nothing is fixed yet, and a document produced then avoids an objection later. Figures changed for privacy.
Risk Warning: Interest runs from the original due date, not from the reassessment. Please do not assume a long audit is a free delay.

Your Rights, and What Happens After
Your Rights, and What Happens After
The Protections
What You Are Entitled To
The Taxpayer Bill of Rights sets out commitments the CRA makes to taxpayers. The ones that matter practically during an audit:
- To be treated professionally, courteously and fairly
- To have the law applied consistently
- To be represented by a person of your choice
- To complete, accurate, clear and timely information
- To privacy and confidentiality
- To have the costs of compliance taken into account
- To lodge a service complaint and be given an explanation of findings
- To expect the CRA to be accountable
These are commitments rather than a code you litigate directly, but they are the basis of a service complaint where an audit is being conducted unreasonably, and that route exists separately from disputing the tax itself.
What You Owe in Return
You are required to keep adequate books and records, to provide reasonable access and assistance, and to respond to requirements for information. Obstruction has its own consequences and never improves an outcome.
Being cooperative and being expansive are different. Answer what is asked, accurately and on time. That is cooperation. Producing material nobody requested is not.
Objecting to a Reassessment
If you disagree with a reassessment, a notice of objection must generally be filed within 90 days of the date on the notice. For a corporation this is a firm deadline, and missing it means applying for an extension rather than objecting as of right.
| Stage | What Happens |
|---|---|
| Notice of objection | An appeals officer independent of the auditor reviews it |
| Appeals review | Further submissions and evidence can be made |
| Decision | The reassessment is confirmed, varied or vacated |
| Tax Court | Available where the objection does not resolve it |
For a large corporation, collection can proceed on part of the amount even while an objection is outstanding. For most small corporations, collection action is generally held during the objection process, but confirm the position rather than assuming.
Penalties
| Situation | Consequence |
|---|---|
| Failure to keep adequate books and records | Penalty, and the CRA may compel compliance |
| Failure to comply with a requirement or compliance order | Escalating consequences including court proceedings |
| Late filing | 5% plus 1% per complete month, to twelve |
| Repeated late filing within three years | Higher rates apply |
| False statement made knowingly or in circumstances amounting to gross negligence | A penalty of 50% of the understated tax, subject to a minimum |
| Failure to remit source deductions | Penalty plus personal director liability |
The gross negligence penalty is the serious one and the threshold is conduct, not error. A genuine mistake is not gross negligence. Indifference to whether a return was accurate can be.
Taxpayer Relief and Voluntary Disclosure
Two different remedies get confused.
Taxpayer relief asks the CRA to cancel or waive penalties and interest where circumstances beyond your control, CRA delay, or financial hardship contributed. It does not change the tax owing, and there is a limitation on how far back a request can reach.
The Voluntary Disclosures Program is for correcting your own filings before the CRA raises the issue. The conditions are strict: the disclosure must be voluntary, complete, involve a penalty or the potential for one, include information that is overdue, and be accompanied by payment of the estimated tax.
The word voluntary is decisive. Once an audit letter has arrived on the matter, that door is generally closed. If you know something is wrong, the time to act is before the contact, not after.
Clients ask about voluntary disclosure the week an audit letter lands. That is the week it stops being available. The conversation needed to happen earlier. Figures changed for privacy.
Risk Warning: A notice of objection is generally due within 90 days of the notice. Please diarise it the day the reassessment arrives.
Staying Ready and Working With Gondaliya CPA
Staying Ready and Working With Us
The Preparation
Readiness Is a Habit, Not a Project
Businesses that come through audits well are not the ones with the best filing cabinets. They are the ones whose books were reconciled monthly, so nothing had to be reconstructed.
| Frequency | What Gets Done |
|---|---|
| Monthly | Bank and card reconciliation, receipt capture, payroll remittance check |
| Quarterly | Sales tax reconciled to revenue, shareholder loan reviewed, margin compared to prior periods |
| Mid-year | Draft statements, catch errors while the year can still absorb them |
| Year end | Inventory count, accruals, adjusting entries documented, asset register updated |
| Annually | Minute book updated, related-party agreements refreshed, retention reviewed |
The mid-year review is the item most often skipped and the one that pays. An error found in June is a correction. The same error found the following April is an amendment, and found by an auditor two years later it is a reassessment.
Our guide to corporate year-end accounting and T2 filings sets out the year-end sequence in full.
Building a Document System That Survives a Review
- Group by category first, then chronologically within each
- Name files consistently so a document can be found by description
- Capture receipts at the point of spending rather than at year end
- Keep the working papers behind every return with the return itself
- Store the minute book and originals separately and securely
- Back up, and test that the backup actually restores
- Preserve the ability to read old records through any system change
The test is simple: could you produce every document supporting a randomly chosen expense from two years ago, within a week, without asking anyone? If not, the system is not ready.
What We Do on an Audit File
We act as your representative and manage the file end to end: reviewing the scope of the request, assembling and reviewing the documentation before anything goes out, responding within the deadlines, answering the auditor’s questions, dealing with the proposal letter while it can still be influenced, and objecting where a reassessment is wrong.
Where the books need work before they can be produced, we do that first. Sending incomplete records to an auditor to buy time makes the audit longer and worse.
Pricing is quoted before any work begins, including HST, with a one-business-day response and evening and weekend availability while an audit is live.
What It Depends On
| Factor | Why It Matters |
|---|---|
| Scope of the audit | One credit against several years of books |
| Condition of the records | Clean books need assembling; poor books need rebuilding |
| Number of periods | Each year adds reconciliation and review |
| Taxes involved | Income tax, sales tax and payroll each carry their own work |
| Whether penalties are proposed | Penalty exposure changes what the response has to establish |
Getting Started
If a letter has arrived, send it to us before responding. If one has not, bring your last filed return, a recent set of bank reconciliations and your shareholder loan account. Those three show us how a review would go before one starts.
Contact Gondaliya CPA at info@gondaliyacpa.ca, call 647-212-9559, or send us a message.
The businesses that come through an audit cleanly reconciled monthly. Nothing was reconstructed, so nothing was missing. That is the whole difference. Figures changed for privacy.
Pro Tip: Please send an audit letter to your CPA before replying. The first response sets the scope for everything that follows.
FAQs on CRA Audits and Records
Frequently Asked Questions
FAQ
How long must I keep my business records?+
Generally six years from the end of the last tax year they relate to. For a late-filed return, six years from the filing date. Records relating to capital property run until six years after the year of disposition.
Is it really six years from purchase for capital assets?+
No, and this is commonly stated wrongly. Keep acquisition records until six years after the end of the year you dispose of the property, because the gain is calculated from the original cost.
Are electronic records acceptable?+
Yes, provided they are in an electronically readable format, retrievable and legible throughout the retention period, and the system maintains integrity so records cannot be altered without trace.
Do I still need paper originals?+
Where scanned images meet the standards, generally not. Keep originals of the minute book, signed agreements where the signature carries weight, and government certificates.
Can I keep records outside Canada?+
Records must generally be kept in Canada unless permission has been obtained. Businesses using offshore bookkeeping should confirm the arrangement meets the requirement.
What is the difference between a review and an audit?+
A review is usually a targeted request about specific items. An audit examines the books more broadly, and a field audit means an auditor attends your premises. The response required differs considerably.
What triggers a CRA audit?+
Ratios out of line with the sector, unexplained year-over-year swings, sales tax that does not reconcile to reported revenue, third-party information mismatches, repeated late filing, and random selection.
What happens if my records are inadequate?+
The CRA can estimate income by indirect means, including deposit analysis, industry markups or a comparison of assets against declared income. Displacing their estimate is much harder than answering from clean books.
Is a credit card statement enough to support an expense?+
No. It shows money left the account but not what was bought or that it related to the business. Keep the supplier invoice as well.
What is a proposal letter and why does it matter?+
It sets out the adjustments the auditor intends to make, with a period to respond. Nothing is binding yet, so producing a missing document at this stage avoids a reassessment you would otherwise have to object to.
How long do I have to object to a reassessment?+
Generally 90 days from the date on the notice. Missing that means applying for an extension rather than objecting as of right, so diarise it the day it arrives.
Does interest run from the audit or the original year?+
From the original balance-due date. A long audit is not a free delay, which is why interest on a multi-year reassessment often surprises people more than the tax.
What is the gross negligence penalty?+
A penalty of 50% of the understated tax where a false statement was made knowingly or in circumstances amounting to gross negligence. The threshold is conduct, not an honest error.
Can I use the Voluntary Disclosures Program after an audit starts?+
Generally no. The disclosure must be voluntary, and once the CRA has contacted you about the matter that door usually closes. If you know something is wrong, act before the contact.
What is the difference between taxpayer relief and voluntary disclosure?+
Relief asks the CRA to cancel penalties and interest for reasons such as circumstances beyond your control. Voluntary disclosure corrects your own filings before the CRA raises the issue. They are different remedies.
Do I have to let the auditor speak to my staff?+
You are required to provide reasonable access and assistance. In practice it is better to route questions through your representative so answers are accurate and considered.
Sixteen questions and one underneath most of them: can you produce the document. Everything else in an audit follows from that answer. Figures changed for privacy.
The Audit Readiness Checklist
The Audit Readiness Checklist
Quick Reference
Records and Retention
- Keep books and records for six years from the end of the last tax year they relate to.
- Keep capital property records until six years after the year of disposition.
- Keep records in Canada unless permission has been obtained otherwise.
- Confirm electronic records stay readable through any system change.
- Ensure the system prevents alteration without a trace.
- Hold minute books, signed agreements and certificates in original form.
- Retain records relevant to an objection until the matter is closed.
- Remember retention obligations survive a corporate dissolution.
Documentation
- Reconcile every bank and card account monthly.
- Include every account through which business money moved.
- Keep supplier invoices, not just card statements.
- Maintain vehicle logs where vehicle costs are claimed.
- Note the business purpose on meal and entertainment receipts.
- Keep contracts behind professional and service fees.
- Document the basis for any home office or mixed-use apportionment.
- Explain every adjusting journal entry in the working papers.
- Keep sales invoices in sequence and explain any gaps.
- Reconcile revenue on the return to sales reported for GST/HST.
- Reconcile wage expense to slips filed and remittances made.
- Review the shareholder loan account and support each entry.
If an Audit Starts
- Send the letter to your CPA before responding.
- Authorise your representative at the outset.
- Diarise the deadline and ask early if more time is needed.
- Answer what is asked; do not volunteer material outside the scope.
- Log every document provided and every conversation held.
- Route questions through your representative rather than answering off the cuff.
- Raise any error you find yourself, promptly.
- Use the proposal letter window; nothing is binding yet.
- File a notice of objection within 90 days if you disagree.
- Consider voluntary disclosure only before contact, never after.
For help preparing for or responding to a CRA audit, contact Gondaliya CPA at info@gondaliyacpa.ca, call 647-212-9559, or book a free consultation.
Thirty points and one underneath them: reconcile monthly. Almost every audit problem we see is something that would have been caught in the month it happened. Figures changed for privacy.
Businesses We Serve
Industry Expertise
Which issue dominates differs by the business. Here are ten and the usual focus.
| Business Type | Where Auditors Concentrate |
|---|---|
| Medical and dental practices | Billing records against reported revenue |
| Construction and trades | Subcontractor payments and contract reporting |
| Restaurants and cash businesses | Deposits against sales, and supplier purchases |
| Transportation and logistics | Vehicle logs and fuel records |
| Retail and e-commerce | Platform and processor reports against revenue |
| Daycare and care services | Payroll hours and remittances |
| Real estate and development | Capital against income treatment on dispositions |
| Professional services | Work in progress and shareholder remuneration |
| Importers and distributors | Landed cost and input tax credit documentation |
| Any owner-managed corporation | The shareholder loan account |
- Medical and dental practices: Billing data is independently verifiable.
- Construction and trades: Subcontractor reporting is checked against slips.
- Restaurants and cash businesses: Purchases imply sales; the two must agree.
- Transportation and logistics: No log means no vehicle claim.
- Retail and e-commerce: Processors report gross independently.
- Daycare and care services: Hours worked against remittances made.
- Real estate and development: Intention at acquisition drives the treatment.
- Professional services: Unbilled work and how the owner was paid.
- Importers and distributors: Credits need the customs document.
- Any owner-managed corporation: It collects whatever nobody could code.
The business changes where auditors look first. It does not change the method, which is reconcile to the bank, document every claim, then answer only what was asked. Figures changed for privacy.
Professional Guidance and Quick Reference
Guidance
Professional Guidance: How Gondaliya CPA Handles Your Audit File
Small businesses lose CRA audits in a predictable set of ways: claiming legitimate expenses with no supplier invoice behind them so a real cost gets disallowed on documentation alone, books that were never reconciled to the bank so nothing can be tied to anything verifiable, capital property records discarded six years after purchase rather than six years after sale, an accounting system migration that left six years of history unreadable, a shareholder loan account collecting every entry nobody knew how to code, revenue on the corporate return that does not agree to sales reported for GST/HST, and responding to the first letter with far more than was asked. Gondaliya CPA represents small businesses through CRA audits on a fixed fee.
We handle what decides the outcome: reviewing the scope of what has actually been requested, assembling and reviewing documentation before anything is sent, reconciling the books where they need work first, responding within the deadlines, managing questions so answers are accurate and considered, using the proposal letter window while nothing is binding yet, and objecting within the 90 days where a reassessment is wrong.
Our team starts with the letter itself, or if none has arrived, your last filed return with recent bank reconciliations and the shareholder loan account. Those show how a review would go before one starts. Whatever your sector, you get clear advice and a fixed price before we start.
Quick Answers
- The real test: Can you produce the document
- Retention: Six years, generally
- Capital property: Six years after disposition
- Electronic records: Readable and unalterable
- Card statement: Not enough on its own
- Proposal letter: Nothing is binding yet
- Objection: 90 days from the notice
- Interest: Runs from the original due date
- Voluntary disclosure: Before contact only
- First response: Sets the scope for everything
Who This Is For
- For: Incorporated Canadian small businesses preparing for or responding to an income tax, GST/HST or payroll examination.
- Not For: Matters that have moved toward enforcement or involve allegations requiring legal counsel, and foreign tax authorities, which require advice in that jurisdiction.
People Also Ask
Should I send everything the auditor might want?+
No. Answer what is asked, accurately and on time. Volunteering material outside the scope enlarges the audit without helping you.
What if I find an error myself during the audit?+
Raise it promptly. Finding your own error and disclosing it is materially better than having it found, and it bears on whether penalties are considered.
Does the CRA hold collection while I object?+
For most small corporations collection action is generally held during an objection, though the position differs for large corporations. Please confirm rather than assuming.
Glossary of Key Terms
- Review: A targeted request for support on specific items.
- Field audit: An examination conducted at your premises.
- Books and records: The documentation from which tax can be determined.
- Retention period: How long records must be kept before disposal.
- Electronically readable: Retrievable and legible for the whole period.
- Indirect verification: Estimating income where records are inadequate.
- Bank reconciliation: Agreeing the ledger to the bank statement.
- Proposal letter: The auditor’s intended adjustments, before assessment.
- Reassessment: A revised assessment issued after an audit.
- Notice of objection: The formal dispute, generally within 90 days.
- Appeals officer: A reviewer independent of the auditor.
- Gross negligence penalty: 50% of understated tax, based on conduct.
- Taxpayer relief: A request to cancel penalties and interest.
- Voluntary Disclosures Program: Correcting filings before CRA contact.
- Shareholder loan: Company funds used personally, taxable if not repaid.
- Taxpayer Bill of Rights: The service commitments the CRA makes.
CRA Audit Readiness Check
This quick self-check indicates where your operation most likely has room. Please answer the six questions below.
CRA Audit Readiness Check
Six quick questions on your records. No fee shown.
Points to raise with us:
This is a general prompt, not tax or legal advice or a quote. Your position depends on your full facts. For a real review, please book a free consultation.
Want a checklist to work from? You can download our free CRA audit readiness checklist before your consultation.
Reconcile every bank and card account monthly. Keep a supplier invoice behind every claimed expense. Maintain vehicle logs where vehicle costs are claimed. Reconcile revenue to your GST/HST filings and wages to slips filed. Review the shareholder loan account. Keep capital property records until six years after disposition. Send any audit letter to your CPA before replying. Please keep six years of records.
2026 Update — what is current: This article reflects rules current to 2026. The six-year general retention period, the requirement to keep records in Canada absent permission otherwise, the acceptance of electronic records meeting the readability and integrity standards, the 90-day period to file a notice of objection, the 5% plus 1% per month late-filing penalty and the 50% gross negligence penalty are unchanged. Please note that records relating to capital property must be kept until six years after the end of the year of disposition rather than six years from acquisition, since the gain is computed from original cost; that retention obligations survive a corporate dissolution for a period; that taxpayer relief and the Voluntary Disclosures Program are different remedies, relief addressing penalties and interest where circumstances warrant while the disclosure programme requires the correction to be voluntary and therefore generally unavailable once the CRA has made contact on the matter; and that interest on a reassessment runs from the original balance-due date rather than from the date of the reassessment.
CRA Audit Support Canada: How Gondaliya CPA Represents Small Businesses
Start with the letter
Gondaliya CPA reviews the scope of what has actually been requested, assembles and reviews the documentation before anything is sent, reconciles the books first where they need work, responds within the deadlines, manages questions so answers are accurate and considered, uses the proposal letter window while nothing is binding yet and files a notice of objection within the 90 days where a reassessment is wrong, at a fixed price quoted before we start including HST with a one-business-day response. Please book a free consultation.
Next Steps
Please book a free consultation with Gondaliya CPA and bring any audit letter received, your last filed corporate return, and a recent set of bank reconciliations. Those three tell us immediately what is actually being asked, how the records stand, and what remains to claim on the equipment, and where the documentation is thin. You will get a flat annual fee including HST before any work begins. If our content helps, please add gondaliyacpa.ca as a preferred source on Google.
Published: · Last updated:
Editorial policy: We research against CRA and CPA Ontario sources, fact-check the figures, and Sharad Gondaliya, CPA, reviews the content, which we update as the rules change.
Disclaimer: This article is educational information only and is not tax, legal, or financial advice. Figures marked illustrative are examples rather than quotes or guarantees. It reflects CRA rules current to 2026, including the $30,000 GST/HST threshold, the Class 8 rate, Class 13 leasehold treatment, the half-year rule, and the six-year retention requirement. Rates, limits and expensing rules change and outcomes depend on your specific facts. Please consult a CPA Ontario member before acting.
Sharad Gondaliya is a CPA Canada & CPA USA with 15 Years+ experience of Accounting, Tax, Payroll of Corporate Small Businesses as Tax Accountant. He is a CPA Ontario member (61040184) and holds US CPA licences in Washington and Montana and is well known among corporate small businesses for tax planning, efficient tax solutions, and affordable CPA services. Sharad is the Principal (Director) of Gondaliya CPA – Affordable CPA Firm in Canada. Licenses: CPA Ontario: 61040184 | CPA USA (MT): PAC-CPAP-LIC-033176 | CPA USA (WA): 57629 | CPA Firm License: 61330051 View Full Author Bio