



How Effective Corporate Tax Planning Can Maximize Your Business Profits in Canada
Corporate Tax Planning Strategies to Save Taxes and Boost Business Profits
Corporate tax planning by Gondaliya CPA focuses on smart strategies to save taxes and boost business profits through effective corporate investment strategies and money retention techniques. These business tax strategies help companies optimize tax obligations while maximizing overall returns. Corporate tax planning strategies by Gondaliya CPA help save taxes and boost business profits. These strategies focus on corporate tax planning, maximizing corporate profits, and tax optimization, for incorporated small and medium businesses across Canada.
Quick Summary
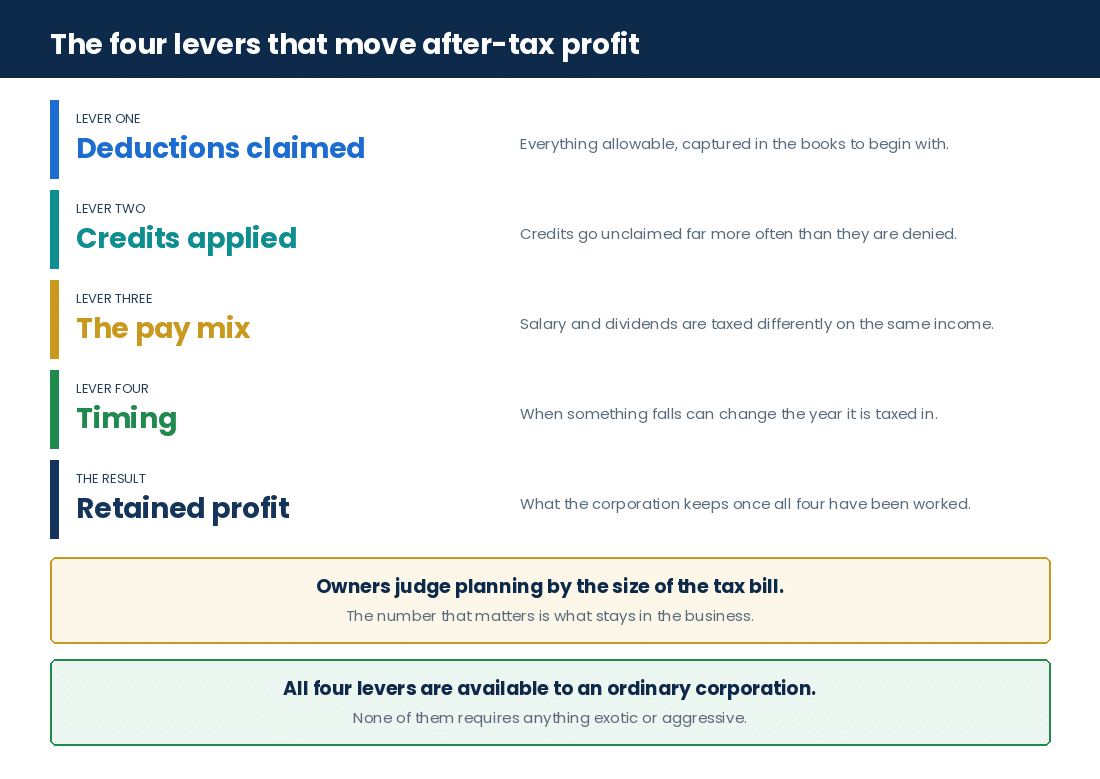
Planning is worth whatever it adds to retained profit, which is why this post follows the money rather than listing tactics. Please note that nothing here involves hiding income or bending a rule, because the levers that move after-tax profit are all ordinary ones and all of them are claimed openly on the return. Four of them do most of the work.
| Aspect | Details |
|---|---|
| What planning is worth | It cuts down how much tax you owe and keeps more profits in your business, which is the only measure that counts. |
| Where the money comes from | Deductions you were entitled to, credits you qualified for, and the timing of when income and expenses land. |
| What you personally keep | Follows from the salary and dividend mix, because the company’s tax and your own tax move in opposite directions. |
| What it costs you to skip | Tax paid that never had to be paid, plus penalties and interest when a filing or a remittance is late. |
Reading time: 21 minutes.
Table of Contents
- What Corporate Tax Planning Keeps for You
- Deductions and Credits: The Two Direct Levers
- Salary, Dividends and What the Company Holds
- Filing T2 Returns and When Planning Pays
- Your Options and How the Work Runs
- The Planning Year: Cost, Risk and Preparation
- Frequently Asked Questions
- Essential Points for Business Owners
- Industry Spotlights: Sectors We Represent
- Professional Guidance and Quick Reference
The Numbers That Matter
This article covers corporate tax planning aimed at after-tax profit for incorporated small and medium businesses in Toronto, Ontario and across Canada, current to 6 November 2026. It covers what corporate tax planning is and what it typically includes and excludes, identifying eligible tax deductions, Canadian corporate tax credits including SR&ED, structuring salary against dividends, corporate investment strategy and passive income thresholds, filing T2 returns, the decision triggers that mean it is time to plan, the choice between DIY, a Registered CPA firm and a non-CPA provider, how the engagement runs from intake to follow-up support, the documents to prepare, the deliverables you receive, the drivers behind what it costs, the risks and common mistakes, and how the work differs by industry. It does not cover personal income tax planning, which sits outside the corporate scope, the filing obligations of sole proprietors and unincorporated businesses, or any guarantee of a particular saving in a particular year. Gondaliya CPA performs compilation engagements under CSRS 4200, which provide no assurance; audit and review engagements are referred out. This is educational information only and not tax, legal or accounting advice.
What Corporate Tax Planning Keeps for You
The Profit Side
Corporate Tax Planning to Maximize Profits in Canada
If you want to keep more of your money, corporate tax planning is key. It involves smart business tax strategies that help you maximize corporate profits while staying legal. Working with experts makes this easier.
Summary
- Corporate tax planning cuts down how much tax you owe and keeps more profits in your business.
- Tax optimization means making smart choices about where and how to spend or invest money.
- Business tax strategies use Canadian tax breaks and balance paying yourself salary versus dividends.
- Good planning keeps you on the right side of CRA rules and ready if they audit you.
- CPAs add value by improving accuracy, lowering risks, and helping build wealth over time.
- Small and medium incorporated businesses see the biggest benefits from these plans.
- You need to check and update your plan often because tax laws and business needs change.
Quick Comparison Table: Choosing Your Corporate Tax Planning Approach
| Situation/Trigger | Best Next Step | Why | Risk Level | Typical Timeline | Source/Note |
|---|---|---|---|---|---|
| New incorporated SMB with simple finances | DIY with professional review | Low cost, easy to handle | Medium | 1–2 months | CRA compliance basics |
| Growing SMB facing higher tax bills | Engage Registered CPA firm | Experts reduce audit risk | Low | 2–4 months | CPA Ontario standards |
| Complex multi-entity structure | Engage a CPA firm for consulting | Ensures compliance & optimization | Low | 3–6 months | CRA multi-entity rules |
| Limited budget but need guidance | Affordable CPA services | Clear costs, flat fees | — | — | — |
This table shows options based on your situation, risk level, cost, and timeline. For small businesses just starting out, a do-it-yourself approach with a pro review can work fine. When your business grows or structures get complex, Registered CPAs offer more support.
What Is Corporate Tax Planning?
Corporate tax planning helps Canadian small and medium businesses handle taxes smartly. It looks at your business money to find ways to pay less tax. You spot chances to cut taxable income, use credits, and time income or expenses well. The aim is to pay the least tax you can, all while following CRA rules.
Good corporate tax planning ties your business moves—like paying salaries, giving dividends, investing, and managing costs—to Canada’s tax laws. It’s not just about filing forms at year-end. It’s a plan that helps your business keep more money after taxes.
You use business tax strategies every day. For example:
- Claim smart deductions
- Use credits like SR&ED
- Choose how to split pay between salary and dividends
This way, you pay less tax without CRA trouble or audits. Your company keeps more profit this way.
An Ontario distribution company came to us after three profitable years in which nobody had looked at the tax position until the return was already being prepared. The books were tidy and the filings were on time, so on paper nothing was wrong. What we found was roughly $41,000 of equipment bought in the last week of a year that had been capitalised with no capital cost allowance claimed at all, a vehicle used three quarters for business with none of it deducted, and two years of professional fees sitting in a shareholder account instead of in expenses. Correcting the current year and amending the two before it moved about $23,000 of tax back into the company. Nothing aggressive was claimed; the deductions had simply never been taken. Figures changed for privacy.
Scope Overview Table: What Corporate Tax Planning Typically Covers (and What It Doesn’t)
| Topic/Task | Included? | Why it matters | Notes |
|---|---|---|---|
| Identifying eligible deductions | Yes | Cuts down taxable income | Needs good bookkeeping |
| Utilizing corporate tax credits | Yes | Lowers taxes owed directly | Includes SR&ED claims |
| Structuring salary vs dividends | Yes | Balances personal & corporate tax | Affects CPP payments |
| Corporate investment strategy | Yes | Helps grow profits after tax | Fits long-term plans |
| Filing T2 returns | Varies | Keeps you legal | Part of wider services |
| Personal income tax planning | No | Not part of corporate focus | – |
Deductions and Credits: The Two Direct Levers
Where the Money Is
Identifying Eligible Tax Deductions
Tax optimization means knowing what expenses your company can subtract from income. Typical deductions include:
- Rent and utilities
- Salaries for employees (not shareholder-employees)
- Office supplies
- Professional fees (like CPA help in Toronto)
- Advertising costs in Ontario markets
- Vehicle costs for business use only
- Capital Cost Allowance on assets
Keep receipts clear about business vs personal use. If not, CRA may reject claims. Update your books regularly so you don’t scramble at year-end.
Finding these deductions cuts taxes now and frees cash for other needs. This is key in solid business tax strategies designed for Canadian SMBs.
A Toronto consulting corporation was claiming almost nothing beyond software subscriptions, because the owner had been told that claiming too much draws attention. Rent on the home office, the portion of the vehicle actually used for client work, the accounting fees, the phone and the advertising spend were all legitimate and all missing. We rebuilt two years of the expense side from bank and card statements, documented the business-use percentages properly, and the deductible total rose by roughly $58,000 across the two years. There was no change in what the business did or spent, only in what was claimed and supported. Figures changed for privacy.
Utilizing Canadian Corporate Tax Credits (e.g., SR&ED)
Canadian companies get help through various tax credits aimed at growth and innovation. The big one is the SR&ED program. It gives back money for research done in Canada.
To claim it, you need clear records showing the work fits CRA rules. You must calculate expenses tied directly to research carefully. Other credits might apply depending on what industry or province you’re in (like Ontario).
Using these credits lowers the taxes you owe more than just normal deductions would. Plus, they support projects that keep your business competitive—whether tech startups or construction firms.
A software company in the Toronto area had been running what was plainly experimental development for two years and had never filed an SR&ED claim, because the owner assumed the programme was for laboratories. Two developers had been resolving a performance problem by trial and elimination, with the attempts recorded in commit history and sprint notes. That contemporaneous record was enough. The eligible expenditure came to roughly $190,000 and the refundable credit to about $64,000, which went straight back into payroll. The work had already happened; the only new thing was the documentation that proved it. Figures changed for privacy.
Salary, Dividends and What the Company Holds
The Pay Mix
Structuring Salary vs Dividends
Choosing how much to pay as salary versus dividends affects both your company’s taxes and what you pay personally as a shareholder.
Salary lowers the company’s taxable income because it counts as an expense. But it means you must also handle payroll taxes like CPP contributions which add some cost but build future benefits like pensions.
Dividends don’t reduce company profits subject to tax but give shareholders cash that’s taxed differently—often lower personally thanks to dividend rules and credits in Canada.
The right mix depends on things like:
- Wanting RRSP contribution room from salary earned
- Needing steady monthly income
- Reducing overall combined personal + corporate taxes
A good balance matches short-term cash needs with long-term wealth plans. CPAs who know local CRA rules help find the best setup for SMBs, including those working with Gondaliya CPA in Toronto.
Two shareholders in a Mississauga trades corporation had taken everything as dividends for four years because it was simpler and the cheques were larger. The corporate tax was unchanged by that choice, and personally the dividend credit made it look efficient, but neither of them had built any RRSP room and neither had contributed to CPP since incorporating. We modelled a mix on about $240,000 of combined draw and landed on roughly $140,000 of salary with the balance in dividends. Combined personal and corporate tax moved by only a few hundred dollars; what changed was roughly $25,000 of new RRSP room a year and two CPP records that had stopped. The pay mix is as much about what you keep in twenty years as this year. Figures changed for privacy.
Corporate Investment Strategy
Investments inside a corporation affect how much profit stays after tax over time. A solid investment strategy considers:
- Types of assets held (stocks vs fixed assets)
- How Canada taxes capital gains and passive income
- Limits on small-business deduction when passive incomes go too high
Tax optimization means picking investments that fit your risk goals but avoid extra taxes caused by crossing thresholds set by the CRA each year.
Putting money into things like new equipment may qualify for faster depreciation write-offs too. This helps with cash flow now without hurting future profits.
Expert advice makes sure all this is done within the law while keeping more profit in your company’s pocket.
Profit Retention Check
Five quick questions on how much of your profit you are keeping. No fee shown.
Points to raise with us:
This is a general prompt, not tax or legal advice or a quote. Your position depends on your full facts. For a real review, please book a free consultation.
Filing T2 Returns and When Planning Pays
Compliance
Filing T2 Returns
Every corporation must file a T2 Corporation Income Tax Return yearly, even if no taxes are due or refunds expected.
Late filings risk penalties plus interest charges if the CRA finds missing info during reviews of businesses, including those in Toronto or Ontario served by firms like Gondaliya CPA specializing in SMBs.
T2 returns sum up all financial details: earnings here or abroad, claimed deductions, plus applied credits—both refundable and non-refundable—to show full transparency to authorities enforcing fair taxation across Canada.
While software can help fill T2 forms, mistakes happen easily without expert help. Complex cases with cross-border dealings need professionals who know how to avoid costly errors and possible audits.
A Scarborough corporation filed its own T2 for three years using consumer software and the returns were accepted without comment, which the owner read as confirmation that they were right. They were not. The small business deduction had been claimed on income that included about $70,000 of rent from a property the company owned, the capital cost allowance pools had been restarted from scratch each year instead of carried forward, and a non-capital loss from the first year had never been applied against the third. Acceptance is not agreement; CRA assesses as filed and reviews later. Reassessment and amendment left the company roughly $16,000 better off, and the three years of tidy-up cost more than planning would have. Figures changed for privacy.
When You Need Corporate Tax Planning in Canada
Knowing when to start corporate tax planning can save you money later and avoid surprises from missed deadlines or overlooked chances under Canadian CRA rules—including Ontario-specific payroll schedules many local businesses face.
Signs it’s time include:
- Restructuring incorporation to better suit ownership and reduce taxes
- Year-end coming up needing last-minute review for max write-offs
- Big changes in revenue causing tax bracket shifts requiring updates
- Retirement planning balancing payouts with pension contribution limits
Local firms like Gondaliya CPA offer advice tuned for companies around Toronto and Ontario aiming to follow rules without losing out on savings.
Common Decision Triggers Table: When You Need Corporate Tax Planning
| Scenario | Potential Issue | Relevant Compliance Point | How a CPA Helps |
|---|---|---|---|
| Incorporation restructuring | Possible misclassification causing lost benefits | Adjusted articles + updated registrations needed | Designs optimal entity setup minimizing redundant taxes |
| Year-end close nearing | Missed last-minute deductions/credits | Deadline-driven reporting + accrual adjustments | Timely recommendations capturing max savings |
| Revenue fluctuations | Unexpected bracket changes raising liabilities | Accurate forecasting + quarterly reviews | Proactive adjustment preventing surprises |
| Retirement benefit planning | Complex payout options impacting corp/personal split | Coordinated succession plan incorporating CPP/OAS effects | Tailored advice preserving wealth integrity |
Your Options and How the Work Runs
Who Does It
Your Options: DIY vs Registered CPA vs Non-CPA Provider
Picking who handles your corporate tax planning depends on a few things. Think about your business’s size and how complicated it is. Also, consider how much risk you’re okay with and what your budget looks like. Corporate tax planning takes some know-how about Canadian tax rules and CRA compliance. You want to save on taxes while keeping everything legal.
If you run a small or medium business in Canada, making smart business tax strategies can help you keep more money in your company. You have three main choices:
- Do it yourself (DIY)
- Hire a Registered CPA firm like Gondaliya CPA, which knows all about tax optimization
- Use non-CPA providers who might be cheaper but offer less detailed help
Each choice has its good points and risks. They affect how much tax you pay and how well you use corporate tax credits. Knowing these can help you pick the best fit for your business goals.
Comparison Table: DIY vs Registered CPA Firm vs Non-CPA Provider
| Factor | DIY | Registered CPA Firm | Non-CPA Provider | Best For | Key Risk |
|---|---|---|---|---|---|
| Expertise | Limited; self-study | High; regulated professionals | Varies; often limited | Simple returns; low budgets | Mistakes causing audits |
| Compliance & CRA Readiness | High risk; knowledge gaps | Full compliance guaranteed | Moderate compliance support | Straightforward needs | Fines from missing rules |
| Tax Optimization | Low potential savings | High potential savings | Medium savings | SMBs wanting to maximize profits | Missed deductions/credits |
| Audit Support | No | Yes | No | Businesses needing audit help | No representation |
| Cost | Low | Higher but fixed pricing | Lower than CPAs | Tight budgets accepting risk | Surprise fees or hidden costs |
| Accountability | None | Professional standards enforced | Yes but no regulation | Small businesses testing options | Liability worries |
You have to balance cost against the value of expert advice for Canadian SMBs dealing with CRA rules.
How the Service Works at Gondaliya CPA
At Gondaliya CPA, we focus on corporate tax planning with affordable pricing tailored to your business. We ensure everything stays within CRA rules to prevent issues down the line.
Here’s what happens:
- First, we talk with you to understand your finances and find where you can improve.
- Then, we gather documents like bookkeeping, payroll info (QuickBooks or Xero), last year’s filings, and contracts that might affect taxes.
- Next, we analyze your info carefully. We work with many types of businesses—from doctors’ professional corporations under OHIP rules to startups wanting SR&ED credits.
- We find every legit deduction and credit you can claim.
- Then, we share clear advice with tables showing how changes will help you.
- We make easy action plans so you can follow steps without headaches.
- While preparing T2 returns, we keep communication open so nothing surprises you.
- After filing, we track any law changes that might affect future taxes.
- If CRA asks questions or audits you, we represent you—so you don’t face them alone.
This process saves money now and keeps your business ready for what’s next in Ontario or Toronto.
Process Timeline Table: Typical Engagement Timeline (Intake → Delivery → Follow-Up)
| Phase | Typical Duration | Client Actions | CPA Actions | Outputs | Common Delays & Prevention |
|---|---|---|---|---|---|
| Intake | 1–3 weeks* | Provide docs + answer questions | Collect/analyze data + prepare plan | Customized Corporate Tax Plan report | Late docs – send reminders early |
| Delivery | 2–4 weeks* | Review drafts + approve feedback | Finalize filings + submit T2 return | T2 Filing confirmation letter | Poor communication – schedule regular check-ins |
| Follow-Up | Ongoing | Respond promptly if contacted by CRA | Monitor updates + represent client | Ongoing advisory/support calls | Client unavailability – set expectations upfront |
* Timelines vary by case complexity
We follow this clear plan so clients get good results without stress. Our advice comes from real experience in many industries.
Tools & Workflow Transparency
We work smoothly with popular accounting tools like QuickBooks and Xero. We also use payroll tools such as Wagepoint when needed. This helps avoid errors from manual entry that could raise audit risks.
Clients get clear views of their data flow throughout the process — no surprises or confusion here.
A Vaughan corporation had been using a non-CPA preparer at about a third of our fee, which looked like the sensible choice until CRA opened a review of two years of expenses. The preparer had no representation rights the owner could rely on and no professional insurance behind the work, and the file came to us mid-review with no working papers at all. We rebuilt the support, represented the company through the review and got the great majority of the claims accepted, but roughly $9,000 of poorly documented expenses were denied and the engagement cost more than six years of the fee difference. Cheap preparation is only cheap while nobody asks a question. Figures changed for privacy.
How the Corporate Tax Planning Process Works at Gondaliya CPA
Corporate tax planning is a clear process that helps you lower taxes and boost profits. At Gondaliya CPA, we take you through easy steps. We start with learning about your business. Then, we build a plan that fits your needs. We check everything for accuracy and keep supporting you as things change. This works well for small and medium businesses all over Canada.
Intake & Assessment
First, we collect basic info about your business. We talk about your goals and current tax situation. This helps us find ways to plan your corporate taxes better and come up with smart business tax strategies.
Here’s what happens:
- Discuss your business goals.
- Look at past tax filings.
- Spot quick chances to save money or avoid risks.
This step gives us a good base to work from for the rest of the process.
Data Collection
Gathering all data matters a lot for tax optimization. We ask for financial papers like bookkeeping files, payroll reports, GST/HST records, bank statements, invoices, and receipts.
We will:
- Check if records are complete.
- Find deductions or credits you can use.
- Make sure all documents meet CRA rules.
Getting this info right means fewer problems later on.
Strategy Development
After reviewing your data, we make custom business tax strategies. These plans aim to reduce taxable income legally while following Canadian laws. Some examples:
- Organize income streams smartly.
- Choose when to spend money within the year.
- Use credits like SR&ED to save taxes.
Our main focus is helping you keep more profits by paying less tax without breaking any rules.
Review & Quality Assurance (QA)
Before we finish anything, we check all numbers and ideas carefully:
- Double-check math against CRA rules.
- Confirm deductions are valid.
- Make sure plans fit your financial aims.
This step helps prevent errors that might cause audits or fines. It also makes sure our advice stays solid and reliable under Ontario CPA standards.
Delivery
After review:
We send you final documents such as completed T2 returns (corporate income tax filing) plus detailed strategy reports with backup schedules. Also:
- Help with GST/HST remittance management
- Oversee payroll remittances if needed
- Suggest how to improve bookkeeping controls for next year’s ease
Delivery means you get everything ready for filing along with clear strategy notes.
Follow-Up Support
Tax laws change often. So, after delivery, support keeps things on track throughout the year. We help by:
- Watching law changes affecting your taxes
- Recommending updates when your business changes
- Representing you during CRA reviews or audits if needed
This ongoing help keeps your taxes optimized over time as new chances show up.
The Planning Year: Cost, Risk and Preparation
Practicalities
Typical Engagement Timeline: Corporate Tax Planning Process
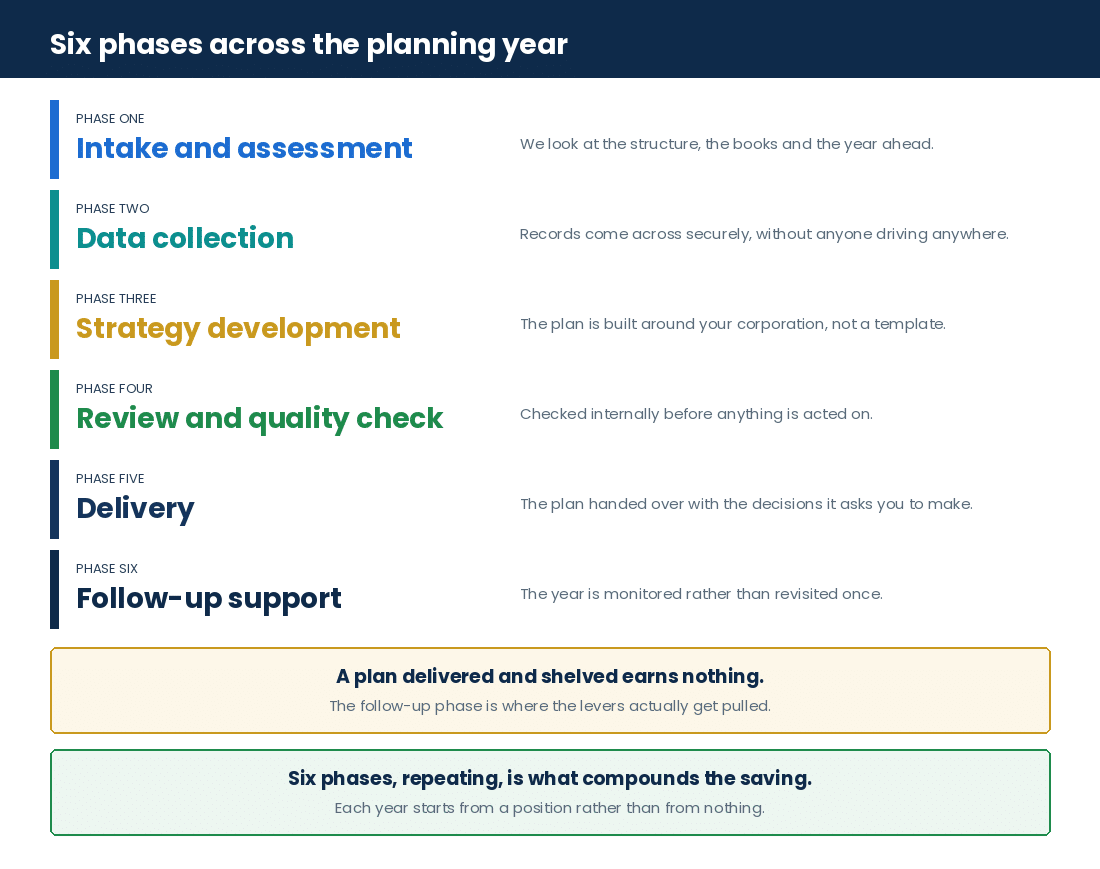
| Phase | Typical Duration | Client Actions | CPA Actions | Outputs | Common Delays + Prevention |
|---|---|---|---|---|---|
| Intake & Assessment | 1–2 weeks | Give basic info and docs | Meet; study needs | Needs analysis report | Late docs; remind client early |
| Data Collection | 2–4 weeks | Send all financial records | Check records | Confirm document checklist | Missing papers; send reminders |
| Strategy Development | 3–5 weeks | Approve suggested plans | Build custom business/corporate strategies | Draft strategy plan | Scope creep; set clear goals upfront |
| Review & QA | 1 week | Answer queries fast | Do quality checks | Final plan/report | — |
| Delivery | 1 week | Receive final docs/reports | Prepare/finalize T2 return + summaries | Filed returns + notes | — |
| Follow-Up Support | Ongoing | Maintain contact | Monitor law updates/CRA issues | Ongoing advice/support | — |
What We Need From You: Checklist Preview
To keep things moving smoothly for good business tax strategies and smart investments, please provide these items on time:
- Financial statements (income statement/balance sheet)
- Detailed general ledger exports
- Bank reconciliations up-to-date
- Payroll summaries/payroll remittance details
- Copies of last years’ filed T2 returns
- Papers backing big transactions/investments
- Records of buying/selling capital assets
- Info on shareholder loans/dividends given
Sending these early helps avoid slowdowns later when we check data accuracy.
Deliverables You Receive from Corporate Tax Planning
When you use our corporate tax planning service, here’s what you get: clear results covering both compliance and strategy insights.
Deliverable Table: Key Outputs from Corporate Tax Planning Services
| Deliverable | What It Is | Who Uses It | When Delivered | Notes |
|---|---|---|---|---|
| T2 Corporate Income Tax Return Filing | The official federal/provincial form sent yearly | Business owners / CRA | End of fiscal year deadline | Accurate client docs needed |
| GST/HST Remittance Management | Help preparing/submitting correct amounts | Finance teams / CRA | Deadlines depend on revenue | Timely transaction data required |
| Payroll Remittance Oversight | Support managing payroll source deductions | HR/payroll teams / CRA | Regular pay period deadlines | Correct employee pay records needed |
| Bookkeeping Controls Review | Report suggesting ways to improve bookkeeping | Accounting/business owners | At engagement end | Current books help results |
These deliverables define what’s finished — legal filings combined with practical tips aimed at keeping profits up by using good record practices.
Following this process timeline and sharing what’s needed makes sure Canadian small and medium incorporated businesses get the most from expert corporate tax planning that fits their growth goals.
Pricing: Factors Affecting Cost of Corporate Tax Planning in Canada
Figuring out what affects the cost of corporate tax planning helps small and medium businesses in Canada keep more of their profits. Your business size, how complex it is, and the kind of advice you need all change the price. Good corporate tax planning means finding ways to lower taxes while following CRA rules.
A few things drive the price up. These include how big and complicated your business is, any cleanup work needed from past filings, having many income sources, how deep the advisory service goes, linking your financial systems, and last-minute rushes.
Knowing these factors early lets you set clear expectations with firms like Gondaliya CPA. They focus on affordable help for incorporated SMBs in Ontario and across Canada.
Pricing Drivers Table
| Driver | What Raises Cost | How to Keep Costs Down | Questions to Ask | Notes |
|---|---|---|---|---|
| Business Size & Complexity | More staff or transactions increase work | Keep records tidy; merge entities if possible | How do you manage multi-entity setups? | Bigger businesses need deeper reviews |
| Cleanup Required | Messy books or missing files slow things down | Do bookkeeping regularly; send records fast | Can you help clean up before planning? | Cleanup takes time but improves accuracy |
| Number of Income Streams | Many revenue sources need special handling | Try to simplify sales channels | Can you handle complex income types? | Different incomes make deductions tricky |
| Advisory Depth | Advice beyond basic filing takes more time | Focus on urgent issues first | What ongoing support do you offer? | Detailed plans cost more but can save money |
| Integration Needs | Linking accounting/payroll/GST systems needs setup | Use updated software that works together | Which platforms do you connect with? | Integration cuts errors but costs upfront |
| Timeline Pressure | Deadlines that are close mean higher fees | Plan early; avoid last-minute jobs | Can you do rush work without extra fees? | Rush jobs might skip some checks |
Two Ontario corporations of almost identical size came to us in the same month. One sent a reconciled general ledger, payroll summaries and the prior T2 within a week, and the planning work ran to the published fixed fee with the whole saving left in the company. The other had eighteen months of unreconciled bank activity and no payroll summaries, so the cleanup had to happen before any planning could, and the engagement took three times as long. The planning identified a similar amount in both — around $18,000 of tax in each case — but one owner kept all of it and the other spent a meaningful part of it getting the records into a state where the planning was possible. Tidy books are not an accounting virtue; they are part of the return. Figures changed for privacy.
Risks, CRA Compliance, and Common Mistakes in Corporate Tax Planning
Corporate tax planning can get tricky if you’re not careful. Missed deadlines mean penalties that cut into your cash. Wrong deductions or mixing up income types can cause audits or re-filing. Not using available credits like SR&ED means losing out on money.
Other common errors include late filings of forms like T2 returns or not balancing salary and dividends right. This mix-up can hike taxes or hurt CPP contributions.
A Registered CPA helps by keeping up with tax rules, checking everything before filing, and warning you about deadlines or chances to save through smart strategies.
Risk & Compliance Table
| Risk Area | Consequence | Prevention Method | Who It Affects | Notes |
|---|---|---|---|---|
| Missed Filing Deadlines | Penalties and interest reduce cash flow | Set reminders; communicate proactively | SMBs with tight budgets | Check CRA due dates yearly |
| Incorrect Deduction Claims | Audits and extra tax bills | Review documents carefully | Businesses filing T2 returns | Keep full receipts |
| Misclassification of Income Types | Wrong taxable income reported | Follow CRA categories clearly | Firms with many income streams | Use CPAs who know your industry |
| Ignoring Available Credits | Lost refunds or tax reductions | Regularly check credit eligibility | Startups and R&D companies | Verify credit rules often |
| Improper Salary-Dividend Mix | Higher overall taxes | Customize pay strategy yearly | Sole proprietors turned corporations | Adjust as rates change |
Common Mistakes Prevention Table
- Wrong Expense Classification: Claiming wrong expenses makes taxes higher. Teach what counts as an expense. Use standard categories.
- Late Filing/Penalties: Missing deadlines causes fines. Set calendar alerts. File early.
- Missing Tax Credits: Forgetting credits wastes money. Check credits regularly. Track spending for claims like SR&ED.
- Poor Record Keeping: No proof leads to audits. Keep good docs all the time. Use digital tools like Hubdoc or Xero.
Checklist: What to Prepare Before Starting Corporate Tax Planning
Getting ready before starting helps things go faster and smoother later. Collecting clear financial papers and proof makes it easier for advisors from day one.
Here’s a list for Canadian SMBs including T2 returns, GST/HST filings, and payroll details — stuff firms like Gondaliya CPA often use when planning your taxes.
Preparation Checklist Table
| Item | Description | Source | Notes |
|---|---|---|---|
| Financial Statements (Income Statement/Balance Sheet) | Shows how company is doing | Get from your accountant | Avoid old reports; Use latest year-end versions |
| General Ledger Detail | Details every transaction | Export from software (QuickBooks/Xero) | Reconcile monthly; Send electronic copies |
| T2 Corporate Tax Return Draft/Previous Year Returns | Past tax filings | Find digital/paper copies | Check if complete; Share early |
| GST/HST Filings Records | Shows reported sales/taxes | Get from GST portal/accountant | Match bank records; Include adjustment notes |
| Payroll Remittance Summaries | Shows employee deductions paid | Pull reports from payroll provider (Wagepoint/ADP) | Confirm timely payments; List all employees/contracts |
This guide helps Canadian incorporated SMB owners see what affects corporate tax planning costs and avoid common mistakes. Following this info aims to maximize after-tax profits while sticking to Canadian tax laws. Contact experts focused on small-business taxes in Canada for advice based on your unique needs.
Common Mistakes in Corporate Tax Planning and How to Prevent Them
Corporate tax planning takes focus and good money habits. Lots of small and medium businesses in Canada mess up on simple stuff. These mistakes cost money or cause trouble with the CRA. Catching them early keeps profits safe and your business running smoothly.
| Common Mistake | Why It Matters | Prevention Strategy |
|---|---|---|
| Failing to Keep Receipts | No receipts means you miss deductions and pay more tax. | Keep all receipts organized; try using apps to save them digitally. |
| Mixing Personal & Business Funds | Mixing funds makes bookkeeping tough and risks audits or lost deductions. | Always use separate bank accounts; track expenses carefully. |
| Overlooking Year-End Actions | Missing deadlines cuts down your chances for tax savings. | Plan year-end checks early; talk to a CPA for help on timing. |
| Ignoring Provincial Differences | Different provinces have different rates and rules that affect taxes. | Keep updated on the tax rules where your business is located. |
These slip-ups lead to paying more tax or trouble with CRA audits. Getting help from a pro makes sure you follow rules while saving money on taxes.
Checklist: What You Need Before Starting Corporate Tax Planning
Getting ready before you start corporate tax planning saves time and hassle. Having the right papers helps your CPA spot every way to save taxes.
Gathering all info first cuts delays and makes your plan fit your business better.
Preparation Checklist Table
| Item | Purpose | Where to Find | Notes |
|---|---|---|---|
| Prior Year T2 Returns | Check last year’s filings for accuracy | From your previous CPA or bookkeeper | Double check before submitting |
| Current Financial Statements (Balance Sheet & Income Statement) | See how your business is doing now | Accounting software or bookkeeper | Needed for planning |
| Payroll Summaries | Confirm payroll deductions are correct | Payroll provider or software | Includes CPP/EI contributions |
| Investment Details | Get cost info for capital gains/losses | Investment statements or brokerage reports | Include dividends received |
| Expense Receipts | Back up deductible expenses | Physical/digital copies | Sort by type |
| Corporate Structure Documents (Incorporation papers, shareholder agreements) | Know how your company is set up | Legal files or registries | Important if owners changed recently |
Finishing this list before meeting a CPA saves time and helps make smart plans that grow profits using business tax strategies.
Frequently Asked Questions
FAQs
FAQs on Corporate Tax Planning and Related Topics
What role do Registered CPAs play in corporate tax planning?+
Registered CPAs ensure compliance with CRA rules. They create customized tax strategies. They also provide audit representation and reduce audit risk.
How can professional CPA involvement improve tax optimization?+
CPAs use proactive tax optimization strategies. They track changes in tax laws. Their advice maximizes deductions and credits.
Why is audit readiness important for Canadian businesses?+
Audit readiness helps avoid penalties and fines. It ensures proper documentation and risk management. CPAs guide you through CRA audit protocols smoothly, and we represent clients through a CRA audit from the first letter to the outcome.
What are the benefits of integrating accounting software like QuickBooks or Xero?+
Integration improves bookkeeping efficiency. It reduces data entry errors. Software access allows better financial statements and payroll record keeping.
How does salary versus dividend planning affect retirement benefits?+
Salary builds CPP pension contributions. Dividends do not. A balanced salary-dividend mix supports better retirement tax planning.
What documents are needed for efficient corporate tax filing (T2)?+
Key documents include financial statements, payroll remittance details, shareholder agreements, and business incorporation papers.
How do multi-entity tax strategies help businesses?+
They optimize taxes across entities through consolidation or restructuring. This reduces overall compliance risk and penalty exposure.
How much does planning actually add to retained profit?+
It depends entirely on what was being left on the table, and the honest answer in advance is that nobody knows until the books have been read. What can be said is where it comes from: deductions that were available and never claimed, credits the company qualified for and never filed for, a pay mix set by habit rather than by arithmetic, and spending or income that landed in the wrong year by a few weeks. On a company with reasonable records the first review is usually the largest, because it picks up everything that accumulated before anyone looked.
Is it better to keep profit in the company or take it out?+
Profit left in an eligible corporation is taxed at the lower corporate rate, so more of it survives to be invested, which is the whole argument for retaining it. The argument against is that it has not finished being taxed — it is taxed again when it comes out as a dividend, and once enough of it sits in passive investments it begins to affect the small business deduction itself. So the question is not which is better in general but how much you actually need personally this year, and what the money will be doing if it stays.
My tax bill is already small. Is there anything left to plan?+
Often yes, and for two reasons. A small bill in a profitable year usually means something has been claimed in a way that cannot be repeated, or a loss is being used up faster than it needs to be, and both are worth knowing before the next year. A small bill in a thin year is the moment to look at timing instead, because expenses and income moved across a year end are worth most when the rates either side of it differ. The planning question is never only this year’s number.
Essential Points for Business Owners
Key Takeaways
Key Insights: Essential Aspects of Corporate Tax Planning
These are the points that decide how much of the planning actually reaches retained profit.
| Aspect | The Essential Point |
|---|---|
| Pricing model | Flat-fee pricing models ensure cost transparency and fixed annual pricing for SMBs. |
| Tools | Hubdoc, Rotessa, ADP, and Wagepoint enhance payroll remittance management and digital receipt management. |
| Cross-border work | Cross-border transactions require expertise in US CPA licensing, US tax compliance, and US-Canada tax treaties. |
| Dividends | Shareholder dividends must consider dividend tax credit eligibility to optimize combined personal and corporate taxes. |
| Succession | Succession and retirement planning align with pension contributions such as RRSPs and IPPs for long-term wealth preservation. |
| Year-round work | Year-round tax optimization includes timely year-end closing, installment payments, and proactive advisory updates. |
| Compliance | Regulatory compliance spans CRA corporate deadlines, documentation requirements, expense rules, and audit procedures. |
| Bookkeeping controls | Bookkeeping controls review identifies process improvements that support accurate GST/HST filings and payroll filings compliance. |
| Consultation | Consultation services include free consultations with professionals like Sharad Gondaliya or Vandana Goel offering expert guidance. |
| Accountability | Professional accountability ensures fiduciary responsibility while excluding personal income tax planning from corporate services. |
Additional Bullet Points: Enhancing Corporate Tax Planning Success
- Cost-effective tax planning depends on business size, advisory depth, timeline pressure, and integration needs.
- Audit risk mitigation involves risk control strategies to reduce penalty risk linked to compliance gaps or missed deadlines.
- Use cloud document management for electronic filing to improve efficiency and maintain audit trails for CRA inquiries or appeals.
- Business financial health improves via cash flow forecasting, capital expenditures tracking, and investment income reporting accuracy.
- Payroll accuracy requires employee records management with integrated payroll systems syncing wage data seamlessly for filings.
- Industry-specific compliance adjusts to Ontario tax specifics including provincial rules impacting medical doctors or dentists under RCPSC/RCDSO regulations.
- Succession plans involve shareholder agreements updating to reflect ownership changes supporting smooth business restructuring or entity consolidation efforts.
The Six Things We Check First
- What is the actual after-tax profit, by year? Not revenue and not accounting profit. The number the owner keeps is the only baseline worth measuring against.
- Which deductions were available and not claimed? Vehicle, home office, capital cost allowance and professional fees are the four that go missing most often.
- Has any credit been left unfiled? SR&ED first, then the provincial and industry credits that attach to what the company already does.
- Is the salary and dividend mix a decision or a habit? Most of the time it was set once and never revisited, and RRSP room and CPP have been quietly accruing or not.
- How much passive income is inside the corporation? It is the thing most likely to be eroding the small business deduction without anyone noticing.
- Is anything late? A filing or remittance behind by a month turns planning into cleanup, and penalties and interest come straight off retained profit.
Our Approach
Gondaliya CPA starts from the after-tax number rather than the return, so the work is measured against what the company and its owners actually keep; reads the general ledger and the prior returns before advising, because the missing deductions are usually already in the records; files the credits the company qualifies for, SR&ED included, with the documentation built as the work happens rather than afterwards; models the salary and dividend mix each year against both the corporate rate and the shareholders’ own position, including RRSP room and CPP; watches the passive income sitting inside the corporation against the small business deduction thresholds; keeps the filings and remittances current so penalties and interest never come out of the saving; represents clients through CRA audits and reviews; and revisits the plan as the rules and the business change. Fees are fixed and annual with no hourly billing, shown before tax with sales tax on its own line, and agreed before any work begins.
Industry Spotlights: Sectors We Represent
Industry Expertise
Profit is kept differently in every sector. Here are eleven, and where the after-tax money is won or lost in each.
| Industry | Where the After-Tax Profit Moves |
|---|---|
| Technology startups & SaaS | SR&ED credits, and development costs that are capitalised when they could be claimed |
| E-commerce & online retailers | Platform fees and shipping costs claimed in full, and GST/HST collected correctly by province |
| Consulting firms | Home office, vehicle and the pay mix, because there is little else on the expense side |
| Construction, contractors & skilled trades | Equipment capital cost allowance, and subcontractor payments kept apart from payroll |
| Property developers & builders | Which year construction costs land in against which year the sale closes |
| Real estate investors & holding companies | Passive rental income against the small business deduction, and the holding company structure |
| Transportation, logistics & trucking | Fuel, vehicle and per-diem claims that are only as good as the logs behind them |
| Restaurants & food and beverage | Inventory valuation at the year end, and the limits on meal and entertainment claims |
| Daycare, childcare & CWELCC services | How subsidy and funding receipts are brought into taxable income |
| Dentists & dental practices | Equipment depreciation pools, and whether the practice income is in the right entity |
| Medical doctors & physician corporations | OHIP billing cycles against the year end, and the salary and dividend split |
- Technology startups & SaaS: An SR&ED claim is usually the single largest item on the file, and sales taxes have to be managed across every province the product sells into.
- E-commerce & online retailers: Payments arrive from several platforms and have to be combined before anything is provable, and GST/HST has to be collected correctly by province.
- Consulting firms: With few costs to claim, almost all of the retained profit comes from the pay mix and from the home office and vehicle percentages being documented properly.
- Construction, contractors & skilled trades: Subcontractor payments are kept apart from employee payroll, and vehicles and machinery are deducted properly rather than conservatively.
- Property developers & builders: Construction costs are tracked against sales timing, and SR&ED credits are claimed where the build work actually qualifies.
- Real estate investors & holding companies: Rental income is separated from its costs carefully, and holding companies are used for protecting assets and delaying taxes.
- Transportation, logistics & trucking: Fuel and other expenses are tracked closely, and provincial licence fees and taxes are followed so nothing is claimed that cannot be supported.
- Restaurants & food and beverage: Inventory controls how much profit the year reports, and meal and travel expense deductions are claimed within their limits.
- Daycare, childcare & CWELCC services: Government subsidies affect taxable income and have to be reconciled, and childcare-related corporate credits are claimed properly.
- Dentists & dental practices: Equipment depreciation is watched under RCDSO rules, and the incorporation is set up right to balance personal and practice income.
- Medical doctors & physician corporations: OHIP billing cycles sit alongside the salary and dividend choice, and RCPSC rules decide which expenses count.
Industry Spotlights: How Corporate Tax Planning Applies Across Businesses We Serve
Corporate tax planning changes depending on the industry because every business handles money differently and follows different rules. Gondaliya CPA Professional Corporation works with many types of businesses, each with its own needs.
Knowing these differences helps apply smart tax moves without breaking CRA rules:
- Medical Doctors & Physician Professional Corporations – Handle OHIP billing cycles plus salary vs dividend choices – Follow RCPSC rules about which expenses count
- Dentists & Dental Practices – Watch equipment depreciation under RCDSO rules – Set up incorporation right to balance personal and practice income
- Daycare, Childcare, CWELCC Services – Deal with how government subsidies affect taxable income – Claim childcare-related corporate credits properly
- Real Estate Investors & Landlords + Holding Companies – Separate rental income from costs carefully – Use holding companies for protecting assets and delaying taxes
- Property Developers & Builders – Track construction costs versus sales timing – Use SR&ED credits if eligible
- Construction Companies & Skilled Trades (Electricians/Plumbers/HVAC) – Keep subcontractor payments apart from employee payroll – Deduct vehicles and machinery use well
- Technology Startups & SaaS Companies – Use R&D incentives like SR&ED credits – Manage sales taxes across provinces
- E-commerce & Online Retailers (Shopify / Amazon FBA) – Combine payments from different platforms – Collect GST/HST correctly by province
- Restaurants + Food & Beverage Businesses – Control how inventory affects profit – Claim meal and travel expense deductions
- Transportation & Logistics + Trucking Owner Operators – Track fuel and other expenses closely – Follow provincial license fees/taxes
Industry Spotlight Summary Table
| Industry | Unique Financial Patterns | Key CRA Touchpoints | Role of Corporate Tax Planning | Entity Terms Used |
|---|---|---|---|---|
| Medical Doctors | Salary/dividend split; OHIP billing cycles | RCPSC oversight; physician professional corporation rules | Optimize compensation strategy; manage billings/payroll balance | OHIP / RCPSC |
| Dentists | Equipment depreciation focus | RCDSO standards | Incorporation structuring advice | RCDSO |
| Childcare Services | Subsidy impacts | Government funding reconciliation | Maximize childcare-related credits | CWELCC |
| Real Estate Investors | Rental income tracking | Property transfer/depreciation rules | Asset protection via holding company setups | Holding Company |
| Property Developers | Construction cost accounting | Capital gains reporting | Timing of revenue recognition | N/A |
| Construction Firms | Subcontractor vs employee classification | Payroll remittance accuracy | Vehicle/equipment deduction optimization | N/A |
| Tech Startups | Research incentives | Multi-provincial GST/HST filings | SR&ED claim maximization | N/A |
| E-commerce Retailers | Payment platform integration | Cross-border sales/GST complexities | Sales channel reconciliation | N/A |
| Restaurants | Inventory control | Meal/travel expense documentation | Expense categorization | N/A |
| Transportation | Fuel/logistics cost tracking | Licensing fee adherence | Cost allocation between owner/operator roles | N/A |
Each sector works differently, so the best corporate tax strategies change too. These custom fits help lower taxes while keeping things legit with the CRA.
A physician professional corporation in Toronto had its OHIP receipts arriving unevenly and a year end two weeks after the heaviest billing month, so every year the corporation reported a profit spike it had not really earned and paid tax at the top of its range on it. Nothing was wrong with the bookkeeping. Moving the year end, which took one filing, flattened the reported profit across the two years either side of the change and deferred roughly $31,000 of tax into a year where it was taxed at the small business rate instead. The practice earned exactly the same money; the calendar was the only thing that changed. Figures changed for privacy.
Professional Guidance and Quick Reference
Guidance
Essential Points for Canadian Incorporated Businesses
Profit is lost to tax in a predictable set of ways: deductions the company was entitled to and never claimed, so the taxable income was overstated from the start; credits such as SR&ED left unfiled because nobody thought the work qualified; a salary and dividend mix set once at incorporation and never recalculated, which quietly costs RRSP room and CPP as well as tax; passive investment income accumulating inside the corporation until it starts eroding the small business deduction; spending and income landing on the wrong side of a year end by a few weeks; and a late filing or remittance that turns a planning engagement into a cleanup with penalties and interest attached. Gondaliya CPA reads the ledger and the prior returns before advising, and measures the result against after-tax profit.
Quick Answers
At a Glance
- What planning does: cuts how much tax you owe and keeps more profit in the business
- What it is measured against: after-tax profit, not revenue
- Who benefits most: small and medium incorporated businesses
- Who it is not for: sole proprietors and unincorporated businesses
- Lever one: eligible deductions, which cut taxable income
- Lever two: corporate tax credits, which cut the tax directly
- Lever three: the salary and dividend mix
- Lever four: the timing of income and expenses
- Common deductions: rent, utilities, salaries, office supplies, professional fees, advertising
- Also deductible: business-use vehicle costs and capital cost allowance on assets
- The big credit: SR&ED, for research done in Canada
- What a credit needs: clear records showing the work fits CRA rules
- Salary: deductible to the company, builds CPP and RRSP room
- Dividends: not deductible, but often taxed more lightly in your hands
- Investments inside the company: watch the passive income limit on the small business deduction
- Equipment: may qualify for faster depreciation write-offs
- T2 return: required every year, even with no tax due and no refund expected
- Late filing: penalties plus interest charges
- Not in scope: personal income tax planning
- Triggers to plan: restructuring, year end approaching, revenue swings, retirement
- Your three options: DIY, a Registered CPA firm, or a non-CPA provider
- Audit support: a Registered CPA firm represents you; a non-CPA provider does not
- Engagement intake: one to three weeks, depending on how fast documents arrive
- Delivery: two to four weeks, ending in the filed T2
- Follow-up: ongoing, tracking law changes and CRA correspondence
- Software we work with: QuickBooks, Xero, Wagepoint, Hubdoc, Rotessa, ADP
- What raises the fee: size, cleanup, income streams, advisory depth, integrations, rush work
- Deliverables: T2 filing, GST/HST remittances, payroll oversight, bookkeeping controls review
- Fees: fixed and annual with no hourly billing, shown before tax with sales tax on its own line
- Review cycle: check and update the plan often, because the rules and the business change
Who This Is For / Not For
Fit Check
- For: incorporated small and medium businesses across Canada looking for smart corporate tax planning.
- For: business owners wanting to maximize after-tax profits with careful planning.
- For: companies needing expert advice on staying compliant with CRA rules.
- Not for: sole proprietors or unincorporated businesses.
- Not for: personal income tax planning, which sits outside the corporate scope and is dealt with separately.
Disclaimer: The info here is for education only. It’s not legal or financial advice. Always talk to a Registered pro in Canada or Ontario.
People Also Ask
Related Questions
How soon does the money actually show up?+
In two different places at two different speeds. Deductions and credits that belong to a year the company has not yet filed show up as a smaller balance owing on that return, so within the current cycle. A refundable credit such as SR&ED arrives as cash, usually some months after filing. Changes to the pay mix take effect from the moment payroll or dividends change, and timing decisions pay off only at the year end they were aimed at — which is why the planning has to happen before the date, not after.
The year has already closed. Is it too late to do anything?+
Partly. Anything that depended on a date — buying equipment before the year end, declaring a bonus, moving an expense across the line — is finished for that year. What is still open is everything that was simply never claimed: deductions, capital cost allowance, losses carried forward or back, and credits. Returns can be amended, and prior years are commonly reopened to pick up what was missed. So a closed year usually still has money in it, just less than it would have had in November.
Does paying less tax make my company look worse to a lender?+
It can, and it is worth saying so plainly. A lender reads reported profit, and aggressive deduction of every available cost lowers exactly the number a mortgage or credit application is assessed on. That is a genuine trade-off rather than a reason to overpay tax: what it means is that the planning has to know what the company is going to need. Where a financing application is coming, we say so before the return is filed and we prepare financial statements under a compilation engagement that lenders can work from.
My spouse owns shares. Does that change what we keep?+
It can, but far less freely than it once did, and share ownership alone is not enough. Dividends paid to a family member who is not genuinely involved in the business are tested, and where the test is failed the amount is taxed at the top rate rather than at the recipient’s own. What still works is ordinary and documented: real work for real pay, and ownership structures set up for commercial reasons that happen to be efficient. This is a question to ask before the dividend is declared.
What happens to all the retained profit when I eventually sell?+
It becomes part of what the sale is negotiated over, and the form of the sale decides how it is taxed. Selling shares and selling assets out of the company produce very different results for the seller, and a company carrying a lot of retained cash and passive investments can be harder to sell in share form for exactly that reason. None of that is an argument against retaining profit; it is an argument for knowing several years ahead what the exit is likely to look like, because the structure that suits it is not built in the final month.
Glossary of Key Terms
Definitions
- Corporate tax planning: arranging a corporation’s affairs to pay the least tax the rules allow.
- Tax optimization: making smart choices about where and how to spend or invest money.
- After-tax profit: what is left in the company once tax has been paid.
- Eligible deduction: an expense the company may subtract from its income.
- Capital Cost Allowance: the deduction for the depreciation of business assets.
- Corporate tax credit: an amount that reduces tax owing directly rather than reducing income.
- SR&ED: the Canadian credit programme for research and experimental development.
- Salary: remuneration that is deductible to the company and builds CPP and RRSP room.
- Dividend: a distribution to shareholders, not deductible to the company.
- Dividend tax credit: the credit that stops dividend income being taxed twice over.
- Passive income: investment income earned inside the corporation rather than from trading.
- Small business deduction: the lower corporate rate for eligible active business income.
- T2: the corporation income tax return filed with CRA every year.
- Compilation engagement: financial statements prepared under CSRS 4200, which provide no assurance.
Want a checklist to work from? You can download our free corporate profit planning checklist before your consultation.
Four things decide how much of your profit you actually keep. Whether the deductions you were entitled to were claimed — rent, utilities, salaries, office supplies, professional fees, advertising, business-use vehicle costs and capital cost allowance on assets are ordinary claims, and the commonest reason they are missing is that nobody went looking for them. Whether the credits were filed — SR&ED gives money back for research done in Canada and reduces tax more than a deduction of the same size would, and it needs records showing the work fits CRA rules rather than a special kind of business. Whether the salary and dividend mix is still the right one — salary lowers the company’s taxable income and builds CPP and RRSP room, dividends do neither but are often taxed more lightly in your hands, and the balance should be recalculated each year rather than inherited from incorporation. And whether anything is sitting in the wrong year — timing income and expenses well is one of the four levers, and it is the one that stops being available the moment the year end passes.
Three questions tell you whether there is money to find, and none of them needs a tax calculation. First, what did the company actually keep after tax in each of the last three years? If nobody can answer that quickly, the planning has never been measured against anything. Second, when was the salary and dividend split last recalculated? If the answer is at incorporation, it is almost certainly wrong now. Third, is your bookkeeping current to this month? Planning runs on records, and a deduction you cannot document is a deduction you cannot claim.
Corporate Tax Planning for Maximum Profit: How Gondaliya CPA Can Help
Keep more of what the business earns
Gondaliya CPA begins with your after-tax profit rather than your return, reads the general ledger and the prior filings before advising, and then works through the levers in order: every eligible deduction identified and documented, the credits the company qualifies for filed with SR&ED among them, the salary and dividend mix modelled against both the corporate rate and your own position including RRSP room and CPP, the passive income inside the corporation watched against the small business deduction, and the timing of income and expenses planned before the year end rather than explained after it. We prepare and file the T2 return, manage GST/HST and payroll remittances, review your bookkeeping controls, track the law changes that affect you, and represent you through CRA reviews and audits. Fees are fixed and annual with no hourly billing, shown before tax with sales tax on its own line, and agreed before any work begins. Please book a free consultation.
Next Steps
These FAQs and insights highlight key corporate tax planning strategies for Canadian small to medium businesses with expert CPA guidance. Please schedule your free consultation now to maximize profits and minimize taxes. Bring three things with you: your most recent financial statements, your last filed T2 return, and a note of how much you and any other shareholders took out of the company last year and in what form. With those we can usually tell you in the first conversation whether the deductions and credits have been claimed, whether the pay mix is doing what you think it is doing, and whether anything is sitting in the wrong year. Contact experts focused on small-business taxes in Canada for advice based on your unique needs. If your records are not current, say so at the outset rather than tidying them first — cleanup is part of the work, and knowing about it changes the order we do things in rather than the price you were quoted. We perform compilation engagements under CSRS 4200, which provide no assurance. You will get a fixed annual fee, shown before tax, agreed before any work begins. We serve Toronto, Mississauga, Brampton, Vaughan, Etobicoke, Scarborough, Hamilton, Ottawa and the rest of Ontario, and work with incorporated businesses across Canada. If our content helps, please add gondaliyacpa.ca as a preferred source on Google.
Published: · Last updated:
Editorial policy: We research against the Income Tax Act, the Income Tax Regulations, CRA guidance and information circulars, Department of Finance announcements, CPA Canada Handbook standards and CPA Ontario sources, fact-check the figures, and Sharad Gondaliya, CPA, reviews the content, which we update as the rules change.
Disclaimer: This article is educational information only and is not tax, legal or accounting advice. It covers corporate tax planning aimed at after-tax profit for incorporated small and medium businesses in Toronto, Ontario and across Canada, including what corporate tax planning is and what it typically includes and excludes, identifying eligible tax deductions, Canadian corporate tax credits including SR&ED, structuring salary against dividends, corporate investment strategy and passive income thresholds, filing T2 returns, the triggers that mean it is time to plan, the choice between DIY, a Registered CPA firm and a non-CPA provider, how the engagement runs from intake to follow-up support, the documents to prepare, the deliverables, the drivers behind cost, the risks and common mistakes, and how the work differs by industry. It does not cover personal income tax planning, the filing obligations of sole proprietors and unincorporated businesses, or any guarantee of a particular saving in a particular year. Rates, thresholds, forms and statutory references change, and every reference should be confirmed against the current Income Tax Act and current CRA guidance. Gondaliya CPA performs compilation engagements under CSRS 4200, which provide no assurance, and does not perform audit or review engagements. Please consult a licensed CPA before acting.
Sharad Gondaliya is a CPA Canada & CPA USA with 15 Years+ experience of Accounting, Tax, Payroll of Corporate Small Businesses as Tax Accountant. He is a CPA Ontario member (61040184) and holds US CPA licences in Washington and Montana and is well known among corporate small businesses for tax planning, efficient tax solutions, and affordable CPA services. Sharad is the Principal (Director) of Gondaliya CPA – Affordable CPA Firm in Canada. Licenses: CPA Ontario: 61040184 | CPA USA (MT): PAC-CPAP-LIC-033176 | CPA USA (WA): 57629 | CPA Firm License: 61330051 View Full Author Bio